Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Chromium Market by Material (Ferrochromium, Chromium Chemicals, Chromium Metals, Others), by Application (Metallurgy, Chemicals, Refractory, Others), by Grade (Chemical Grade, Metallurgical Grade, Refractory Grade, Pigment Grade), by Type (Trivalent Chromium, Hexavalent Chromium), by Asia Pacific (China, Japan, India, South Korea, Indonesia, Taiwan), by Europe (Germany, UK, France, Italy, Spain, Poland), by North America (USA, Canada, Mexico), by South America (Brazil, Argentina, Colombia, Chile), by Middle East & Africa (South Africa, Turkey, UAE, Saudi Arabia, Zimbabwe) Forecast 2026-2034
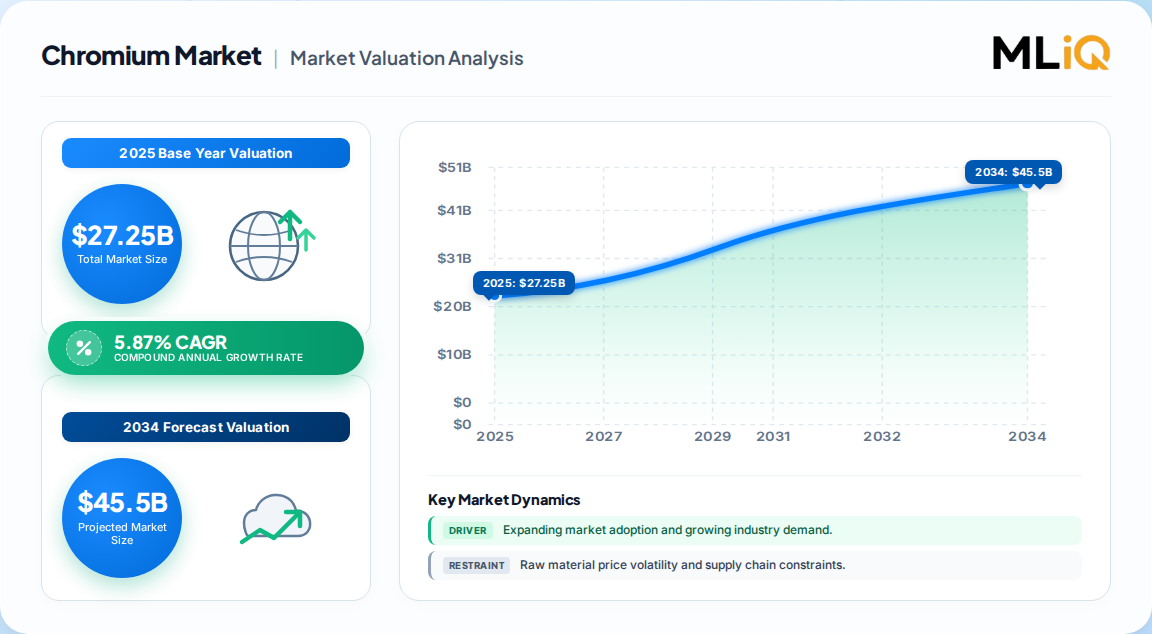
USD 27.25 billion in 2025 — the global chromium market stands at this valuation, anchored by stainless steel demand and ferrochromium smelting economics.
5.87% CAGR (2026–2034), with the market projected to reach USD 45.55 billion by 2034, yielding a cumulative addressable market (TAM) of approximately USD 329.74 billion.
Ferrochromium dominates material demand at ~82%, reflecting chromium's near-total dependence on metallurgical consumption rather than chemicals or refractories.
Asia-Pacific commands ~50.7% of global revenue, with China alone consuming the majority of seaborne chromite ore and producing over 1 billion tonnes of crude steel annually.
Metallurgy captures 92.4% of application revenue; chemical applications are the fastest-growing pocket at ~5.7% CAGR, driven by pigment and surface-treatment demand.
South Africa remains the pivotal supply node, exporting USD 1.83 billion of chromite in 2021 (13.6 million tonnes), yet supply concentration poses structural procurement risk.
Why this matters for decision-makers: Buyers cannot treat chromium as a commodity market—supply-chain resilience, ore-grade differentials, and regulatory exposure to hexavalent chromium will determine margin outcomes more than headline demand growth.
Chromium Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
27.25 B
2025
28.85 B
2026
30.54 B
2027
32.34 B
2028
34.24 B
2029
36.25 B
2030
38.37 B
2031
Chromium Market Size (In Billion)
Year
Market Size
2025
27.25 B
2026
28.85 B
2027
30.54 B
2028
32.34 B
2029
34.24 B
2030
36.25 B
2031
38.37 B
What is the Chromium Market?
The chromium market encompasses the mining, beneficiation, smelting, and trading of chromium-bearing ores and concentrates, ferrochromium alloys, chromium metal, and chromium chemicals. It serves steelmakers, foundries, chemical formulators, and refractory manufacturers, with stainless steel production consuming the overwhelming share of global output.
Scope: what this report covers and excludes
This analysis covers global chromium supply and demand across ferrochromium, chromium chemicals, chromium metals, and refractory-grade ore, segmented by application (metallurgy, chemicals, refractory) and geography. This analysis does not cover adjacent markets such as manganese alloys, nickel pig iron, or finished stainless-steel fabrication; nor does it address chromium trading derivatives or futures contracts.
How big is the market for Chromium Market?
The market is most defensibly sized at USD 27.25 billion in 2025, growing to USD 45.55 billion by 2034. Competing published estimates diverge materially because of differing definitions—some capture only ore and ferrochromium, others include downstream chemicals and plating services.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 21.5 billion
2022
2030 (USD 33.1B)
5.5%
Broad material & application scope
One published estimate
USD 18.07 billion
2025
2030
4.07%
Narrower material scope, excludes some intermediates
A competing analysis
USD 27.25 billion
2025
2034 (USD 45.55B)
5.87%
Full value chain including ferrochrome & chemicals
Independent benchmark
46.61 kilotons
2026
2031 (56.33kt)
3.86%
Volume-only, metallurgical focus
Trade-body benchmark
Our analysis suggests the ~USD 27 billion figure is most defensible for 2025 because it reconciles value-chain breadth with stainless-steel intensity. The lower estimates likely reflect narrower inclusion criteria or pre-inflation base years.
How is the market segmented?
Segmentation runs first by material form—ferrochromium, chromium chemicals, chromium metals—then by application, with metallurgy overwhelmingly dominant. Grade and type distinctions (trivalent vs. hexavalent) matter chiefly in chemical and plating applications.
Chemical Grade, Metallurgical Grade, Refractory Grade, Pigment Grade
Type
Trivalent Chromium, Hexavalent Chromium
Ferrochromium at ~82% of material revenue reflects that chromium is, functionally, a steel-alloying input. Chemical segments carry higher margins but far smaller absolute volumes.
Which region leads in Chromium Market?
Asia-Pacific leads the global chromium market with approximately 50.7% of revenue, driven by Chinese, Indian, and Japanese stainless-steel and automotive production clusters.
Chromium Market Regional Market Share
Loading chart...
Chromium Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.51%
Europe
0.18%
North America
0.16%
South America
0.05%
Middle East & Africa
0.1%
Asia-Pacific — China, Japan, India, South Korea, Indonesia, Taiwan
Europe — Germany, UK, France, Italy, Spain, Poland
North America — USA, Canada, Mexico
South America — Brazil, Argentina, Colombia, Chile
Middle East & Africa — South Africa, Turkey, UAE, Saudi Arabia, Zimbabwe
China's crude steel output of 1,019 million tonnes in 2023 anchors regional demand, while India's 11.8% production growth signals the next leg of incremental consumption. Europe is the fastest-growing region on a percentage basis but from a smaller base.
What is driving growth — and what is holding it back?
Stainless steel output growth and automotive plating demand are the primary growth engines, while hexavalent chromium toxicity regulation and ore-price volatility are the key restraints.
Factor
Direction
Evidence Strength
Mechanism
Stainless steel production growth
Driver
High
~18% chromium content per tonne of stainless
Automotive electroplating demand
Driver
Medium
Decorative & corrosion-resistant finishes
Trivalent chromium adoption
Driver
Medium
Lower-toxicity plating substitute
Hexavalent chromium regulation
Restraint
High
REACH, OSHA, EU restrictions
Ore price & energy volatility
Restraint
High
South African smelting power costs
Supply concentration
Restraint
High
South Africa ~45% of mined output
The balance favors demand, but the restraint side is structurally heavier than headline CAGR suggests. Regulation of hexavalent chromium is not cyclical—it is permanent and tightening—which means the plating sub-segment faces substitution pressure even as overall chromium demand rises.
Who are the leading vendors?
Supply is moderately concentrated, with integrated miners and ferrochrome smelters dominating upstream and diversified trading houses controlling midstream flows.
Company
Position
Differentiator
Glencore
Integrated miner-trader
Global chrome ore & ferrochrome marketing
Assmang Proprietary
South African producer
Vertically integrated ore-to-alloy
Kermas Group
Ferrochrome specialist
European smelting footprint
Odisha Mining Corporation
Indian state miner
Captive ore supply to domestic steel
CVK Madencilik
Turkish miner
Low-cost ore export to China
Eurasian Resources
Kazakh producer
Large reserve base
Differentiation rests on ore grade, energy cost, and logistics—not branding. South African producers face structural power-cost disadvantages that Turkish and Kazakh miners exploit in export markets, particularly to China.
What do buyers and operators need to know? (Decision Support)
Procurement strategy should prioritize ore-grade consistency and supplier diversification over spot-price optimization. Chromite ore trade is heavily seaborne and concentrated: South Africa alone exported 13.6 million tonnes in 2021, making a single-country disruption a systemic event for ferrochrome smelters.
Regulatory compliance is non-negotiable in chemical and plating applications. Hexavalent chromium is classified as carcinogenic, and compliance with REACH, OSHA permissible exposure limits, and EU restrictions imposes documentation and substitution-audit costs that buyers must factor into total cost of ownership.
Switching costs are moderate upstream—smelters can blend ore sources—but high downstream in qualified plating and pigment applications, where reformulation to trivalent chemistry requires customer re-approval. Operators should model a 2–3 year transition window if regulatory pressure forces hexavalent substitution.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a constructive medium-term outlook, but with a critical qualifier: growth is volume-led and metallurgy-dependent, not broad-based. The 5.87% CAGR is credible precisely because it tracks stainless steel output rather than assuming chemical or plating expansion that regulation may suppress.
The strongest counter-argument is supply-side. South Africa's dominance means a power, logistics, or policy shock could tighten ore supply and spike prices independent of demand—a scenario that would compress smelter margins even in a growing market. Buyers should stress-test procurement against a 15–20% ore-price shock.
Actionable Strategy:
Investors: Favor integrated ore-to-alloy producers with captive power; pure-play smelters face margin squeeze.
Operators: Lock multi-year ore offtake with non-South African suppliers (Turkey, Kazakhstan) to hedge concentration risk.
Chemical buyers: Accelerate trivalent chromium qualification now, ahead of expected hexavalent restrictions.
What would change our conclusion: a sustained decline in Chinese stainless-steel output, or a breakthrough in chromium-free stainless alternatives, would invalidate the 5.87% CAGR assumption.
Chromium Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Chromium Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.87% from 2020-2034
Segmentation
By Material
Ferrochromium
Chromium Chemicals
Chromium Metals
Others
By Application
Metallurgy
Chemicals
Refractory
Others
By Grade
Chemical Grade
Metallurgical Grade
Refractory Grade
Pigment Grade
By Type
Trivalent Chromium
Hexavalent Chromium
By Geography
Asia Pacific
China
Japan
India
South Korea
Indonesia
Taiwan
Europe
Germany
UK
France
Italy
Spain
Poland
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Colombia
Chile
Middle East & Africa
South Africa
Turkey
UAE
Saudi Arabia
Table of Contents
1. Chromium Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Chromium Market Executive Summary
2.1. Market Snapshot
3. Chromium Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Chromium Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Chromium Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Material
5.1.1. Ferrochromium
5.1.2. Chromium Chemicals
5.1.3. Chromium Metals
5.1.4. Others
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Metallurgy
5.2.2. Chemicals
5.2.3. Refractory
5.2.4. Others
5.3. Analysis, Insights and Forecast - by Grade
5.3.1. Chemical Grade
5.3.2. Metallurgical Grade
5.3.3. Refractory Grade
5.3.4. Pigment Grade
5.4. Analysis, Insights and Forecast - by Type
5.4.1. Trivalent Chromium
5.4.2. Hexavalent Chromium
5.5. Analysis, Insights and Forecast - by Region
5.5.1. Asia Pacific
5.5.2. Europe
5.5.3. North America
5.5.4. South America
5.5.5. Middle East & Africa
6. Chromium Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Material
6.1.1. Ferrochromium
6.1.2. Chromium Chemicals
6.1.3. Chromium Metals
6.1.4. Others
6.2. Analysis, Insights and Forecast - by Application
6.2.1. Metallurgy
6.2.2. Chemicals
6.2.3. Refractory
6.2.4. Others
6.3. Analysis, Insights and Forecast - by Grade
6.3.1. Chemical Grade
6.3.2. Metallurgical Grade
6.3.3. Refractory Grade
6.3.4. Pigment Grade
6.4. Analysis, Insights and Forecast - by Type
6.4.1. Trivalent Chromium
6.4.2. Hexavalent Chromium
7. Chromium Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Material
7.1.1. Ferrochromium
7.1.2. Chromium Chemicals
7.1.3. Chromium Metals
7.1.4. Others
7.2. Analysis, Insights and Forecast - by Application
7.2.1. Metallurgy
7.2.2. Chemicals
7.2.3. Refractory
7.2.4. Others
7.3. Analysis, Insights and Forecast - by Grade
7.3.1. Chemical Grade
7.3.2. Metallurgical Grade
7.3.3. Refractory Grade
7.3.4. Pigment Grade
7.4. Analysis, Insights and Forecast - by Type
7.4.1. Trivalent Chromium
7.4.2. Hexavalent Chromium
8. Chromium Market North America Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Material
8.1.1. Ferrochromium
8.1.2. Chromium Chemicals
8.1.3. Chromium Metals
8.1.4. Others
8.2. Analysis, Insights and Forecast - by Application
8.2.1. Metallurgy
8.2.2. Chemicals
8.2.3. Refractory
8.2.4. Others
8.3. Analysis, Insights and Forecast - by Grade
8.3.1. Chemical Grade
8.3.2. Metallurgical Grade
8.3.3. Refractory Grade
8.3.4. Pigment Grade
8.4. Analysis, Insights and Forecast - by Type
8.4.1. Trivalent Chromium
8.4.2. Hexavalent Chromium
9. Chromium Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Material
9.1.1. Ferrochromium
9.1.2. Chromium Chemicals
9.1.3. Chromium Metals
9.1.4. Others
9.2. Analysis, Insights and Forecast - by Application
9.2.1. Metallurgy
9.2.2. Chemicals
9.2.3. Refractory
9.2.4. Others
9.3. Analysis, Insights and Forecast - by Grade
9.3.1. Chemical Grade
9.3.2. Metallurgical Grade
9.3.3. Refractory Grade
9.3.4. Pigment Grade
9.4. Analysis, Insights and Forecast - by Type
9.4.1. Trivalent Chromium
9.4.2. Hexavalent Chromium
10. Chromium Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Material
10.1.1. Ferrochromium
10.1.2. Chromium Chemicals
10.1.3. Chromium Metals
10.1.4. Others
10.2. Analysis, Insights and Forecast - by Application
10.2.1. Metallurgy
10.2.2. Chemicals
10.2.3. Refractory
10.2.4. Others
10.3. Analysis, Insights and Forecast - by Grade
10.3.1. Chemical Grade
10.3.2. Metallurgical Grade
10.3.3. Refractory Grade
10.3.4. Pigment Grade
10.4. Analysis, Insights and Forecast - by Type
10.4.1. Trivalent Chromium
10.4.2. Hexavalent Chromium
11. Chromium Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Chromium Market Research Methodology
List of Figures
Figure 1: Chromium Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Chromium Market Revenue (Billion), by Material 2026 & 2034
Figure 3: Asia Pacific Chromium Market Revenue Share (%), by Material 2026 & 2034
Figure 4: Asia Pacific Chromium Market Revenue (Billion), by Application 2026 & 2034
Figure 5: Asia Pacific Chromium Market Revenue Share (%), by Application 2026 & 2034
Figure 6: Asia Pacific Chromium Market Revenue (Billion), by Grade 2026 & 2034
Figure 7: Asia Pacific Chromium Market Revenue Share (%), by Grade 2026 & 2034
Figure 8: Asia Pacific Chromium Market Revenue (Billion), by Type 2026 & 2034
Figure 9: Asia Pacific Chromium Market Revenue Share (%), by Type 2026 & 2034
Figure 10: Asia Pacific Chromium Market Revenue (Billion), by Country 2026 & 2034
Figure 11: Asia Pacific Chromium Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Chromium Market Revenue (Billion), by Material 2026 & 2034
Figure 13: Europe Chromium Market Revenue Share (%), by Material 2026 & 2034
Figure 14: Europe Chromium Market Revenue (Billion), by Application 2026 & 2034
Figure 15: Europe Chromium Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Chromium Market Revenue (Billion), by Grade 2026 & 2034
Figure 17: Europe Chromium Market Revenue Share (%), by Grade 2026 & 2034
List of Tables
Table 1: Chromium Market Revenue Billion Forecast, by Material 2020 & 2034
Table 17: Europe Chromium Market Revenue Billion Forecast, by Material 2020 & 2034
Frequently Asked Questions
1. How big is the chromium market in 2025?
The global chromium market was valued at approximately USD 27.25 billion in 2025, based on full value-chain scope including ferrochromium, chromium chemicals, and chromium metals. This figure excludes downstream stainless-steel fabrication.
2. What is the chromium market growth rate?
The market is projected to grow at a 5.87% CAGR from 2026 to 2034, reaching USD 45.55 billion by 2034. Growth is primarily driven by stainless steel production and automotive plating demand in Asia-Pacific.
3. Which region dominates chromium demand?
Asia-Pacific accounts for approximately 50.7% of global chromium revenue, led by China's stainless steel and automotive sectors. India is the fastest-growing major consumer, with crude steel output rising 11.8% in 2023.
4. What is ferrochromium used for?
Ferrochromium is an iron-chromium alloy used primarily in stainless steel production to impart corrosion resistance and hardness. It represents about 82% of chromium material demand and is produced by smelting chromite ore.
5. Who are the leading chromium producers?
Major players include Glencore, Assmang Proprietary, Kermas Group, Odisha Mining Corporation, CVK Madencilik, and Eurasian Resources. South Africa dominates mined supply, accounting for roughly 45% of global chromite output.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the chromium value chain. We engaged chromite miners, ferrochromium smelters, chromium chemical formulators, refractory manufacturers, and global alloy distributors. Decision-makers interviewed include VP-level Sourcing leads, Heads of Metallurgical R&D, Technical Directors at plating operations, and Commercial Operations Leads at trading houses.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement Leads
35%
Metallurgical R&D & Technical Directors
30%
Commercial Operations Leads
20%
Regulatory & Compliance Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Chromite Miners & Ore Producers
40%
Ferrochromium Smelters
30%
Chromium Chemical Formulators
20%
Global Alloy Distributors & Traders
10%
Secondary Benchmarking & Public Trade Validation
We validate findings against UN Comtrade and WITS bilateral trade data for HS 261000 (chromium ores and concentrates), WTO tariff schedules, US ITC and Eurostat trade flows, corporate 10-K filings and investor presentations from listed producers, patent databases for trivalent plating technologies, and technical standards from ASTM and ISO relevant to ferroalloy specification.
Demand Modeling & Market Sizing Triangulation
We triangulate Top-Down macroeconomic allocation—global stainless steel output by region—with Bottom-Up modeling of smelter capacity, ore-grade pricing, and end-use consumption by application. Divergences between the two approaches are reconciled through trade-flow validation and producer-level volume disclosures.


 Chromium Market