Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Crude Oil Carriers Market by Capacity (Ultra Large Crude Carriers, Very Large Crude Carriers, Suezmax Tankers, Panamax Tankers, Aframax Tankers), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
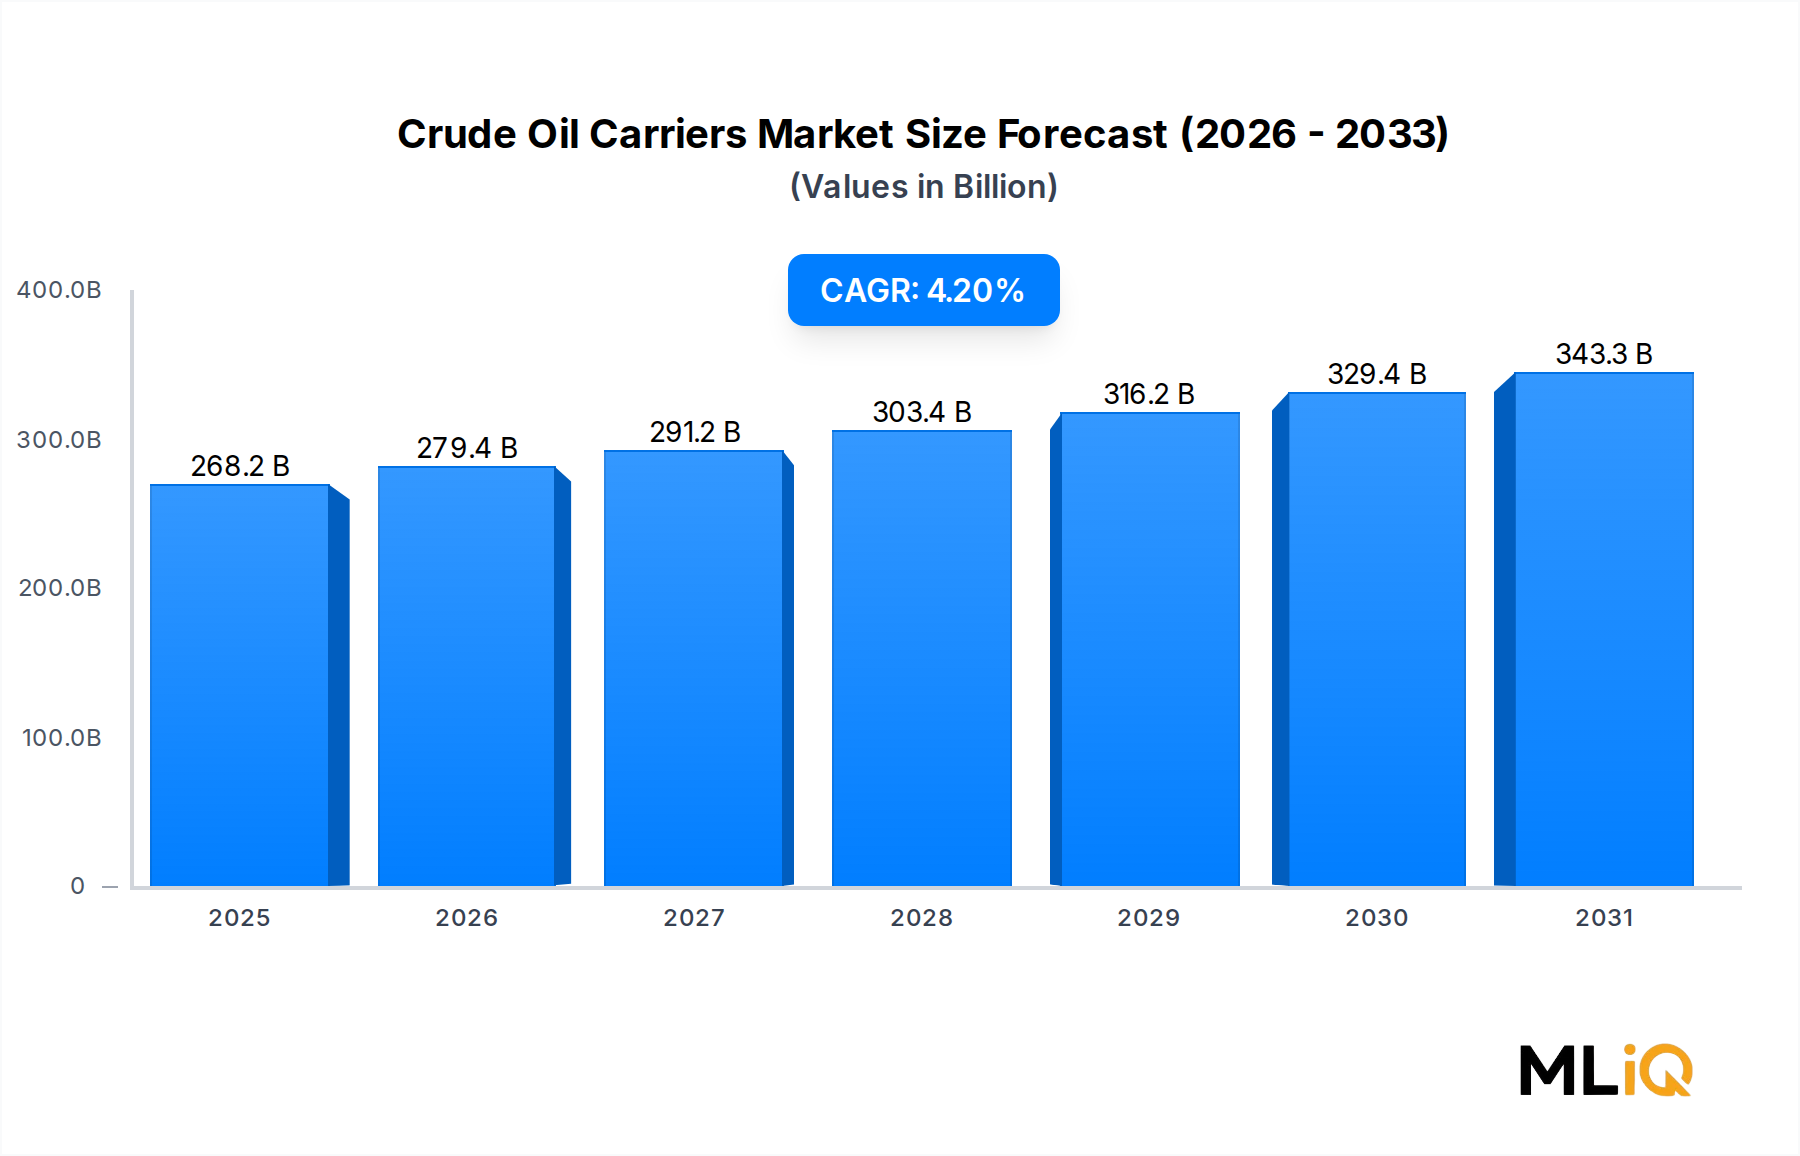
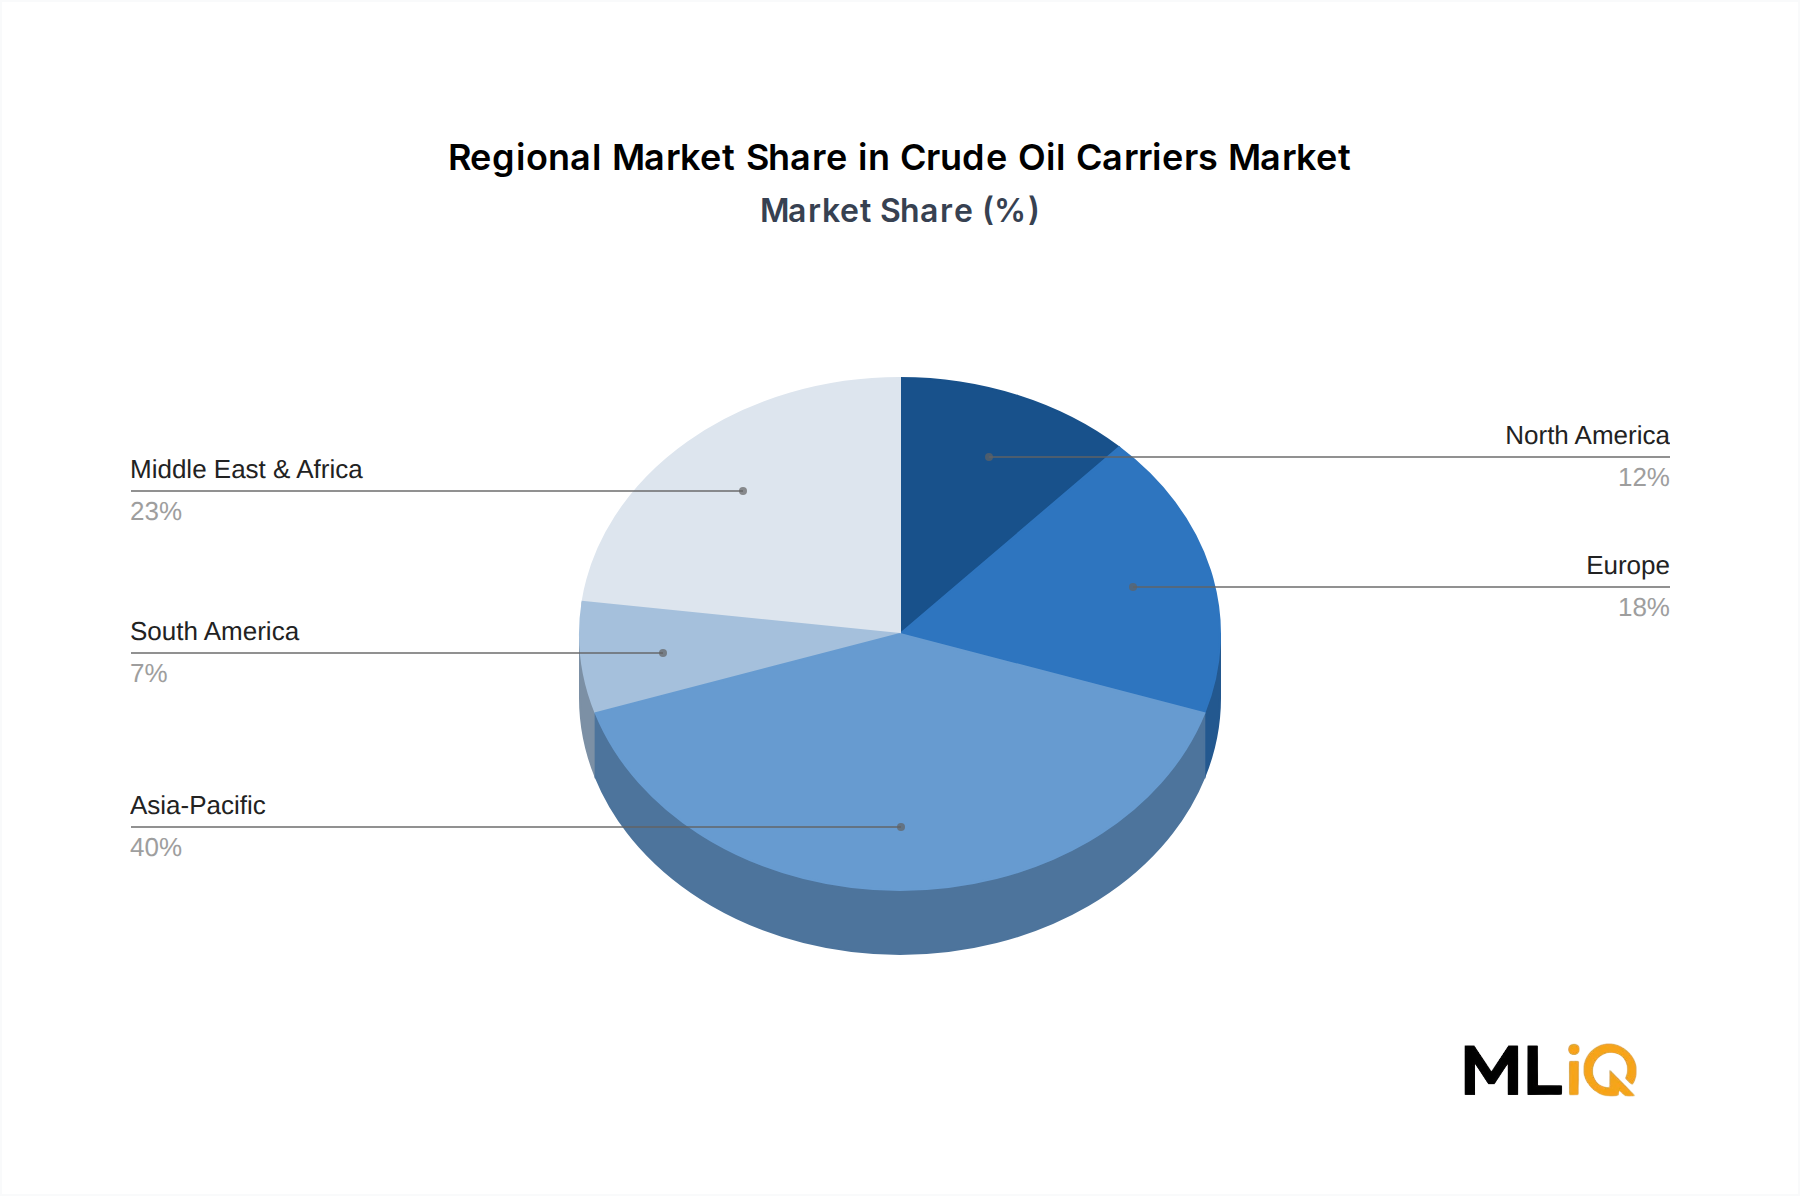
The global crude oil carriers market is valued at $268.18 billion in 2025 and is projected to reach $374.5 billion by 2033, expanding at a 4.2% CAGR. This growth is driven by ton-mile expansion as Atlantic-to-Asia crude flows lengthen and aging fleets require replacement. Asia-Pacific dominates with a 40% share, led by China and India's refinery capacity.
Crude Oil Carriers Market Size (In Billion)
400.0B
300.0B
200.0B
100.0B
0
268.2 B
2025
279.4 B
2026
291.2 B
2027
303.4 B
2028
316.2 B
2029
329.4 B
2030
343.3 B
2031
Key insights:
VLCCs account for 42% of total capacity and generate the highest revenue per vessel.
The Oil Tanker Market is bifurcated: compliant tonnage earns premiums while older, non-eco vessels face chartering discounts.
Bunker Fuel Market dynamics, especially the shift to VLSFO and methanol, influence operating costs by 15-20%.
Regulatory pressure from IMO 2023 carbon intensity rules accelerates scrapping of Aframax Tanker Market units older than 15 years.
Macro drivers include geopolitical rerouting (Russian sanctions added 3.5 million b/d to longer hauls), OECD inventory restocking, and newbuild ordering for dual-fuel vessels. The Shipbuilding Market is seeing a 7% annual increase in tanker orders, concentrated in South Korean and Chinese yards.
However, headwinds exist: fleet oversupply in the Suezmax Tanker Market and potential peak oil demand by 2030 could compress rates. The Maritime Decarbonization Market is reshaping fleet economics, with 220 dual-fuel tankers on order as of 2025. The Crude Oil Transportation Market remains highly cyclical, but structural shifts toward longer routes provide a floor for utilization.
For stakeholders, the Petroleum Logistics Market offers integration opportunities, as oil majors seek dedicated tonnage. Overall, the outlook through 2034 is cautiously optimistic, with 4.2% CAGR masking regional and segment volatility.
Segment Deep-Dive: Very Large Crude Carriers (VLCC) Dominance in Crude Oil Carriers Market
Segment Analysis Matrix
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Very Large Crude Carriers (VLCC)
3.8
42
Long-haul Middle East-to-Asia flows
Suezmax Tankers
4.5
25
Atlantic Basin and West Africa trade
Aframax Tankers
5.1
18
Short-haul and regional distribution
VLCC Dynamics
The Very Large Crude Carrier Market dominates, accounting for 42% of global capacity revenue.
VLCCs carry 2 million barrels per voyage and benefit from economies of scale on routes exceeding 6,000 nautical miles.
Margin pressure comes from newbuild deliveries: 45 VLCCs scheduled for 2025-2026.
Charter rates for eco-VLCCs averaged $45,000/day in 2024 vs. $28,000/day for non-eco, a 60% premium.
Suezmax and Aframax
Suezmax Tanker Market growth of 4.5% CAGR is driven by West African and Brazilian exports to Europe and U.S. Gulf.
Aframax Tanker Market shows the highest growth at 5.1% due to short-haul Baltic and Mediterranean trades, but faces fleet oversupply from 2019-2021 orders.
Panamax Tankers and Ultra Large Crude Carriers are niche; ULCCs are largely obsolete, with only a handful still operating.
Margin pressures include crew costs (up 12% since 2022) and carbon taxes in EU ETS starting 2024, adding $5-8 per tonne of fuel. Operators with dual-fuel readiness command higher time-charter equivalents. The Oil Tanker Market consolidation favors larger fleets that can spread compliance costs.
Projected 2030 peak, reducing long-term charter demand
Medium
Long-term
IMO carbon rules
Restraint
Carbon intensity indicator cuts effective capacity by 5-10%
High
Long-term
Quantitative evaluation:
Drivers: Ton-mile demand grew 5.1% in 2024, outpacing fleet growth of 2.8%. The Shipbuilding Market is responding with $22 billion in tanker orders in 2024 alone.
Restraints: The Suezmax Tanker Market faces a 12% capacity surplus through 2026. Peak oil demand uncertainty deters newbuild financing, with banks requiring 10-year charters for loans.
Regulatory: IMO's EEXI and CII rules force 15% of the fleet to slow steam, effectively removing 2% of global capacity. EU ETS adds €80-100 per tonne of CO2, raising voyage costs.
Asia-Pacific is the fastest-growing region, driven by China's 20 million b/d refining capacity and India's 5.5% annual demand growth. The Crude Oil Transportation Market here benefits from VLCC utilization above 85%.
Middle East & Africa remains the largest net exporter, with GCC countries adding 2 million b/d of export capacity by 2026.
Europe is the most mature but faces regulatory pressure: EU ETS adds €100 per tonne of CO2, favoring Suezmax Tanker Market operators with modern fleets.
North America growth is constrained by the Jones Act, but U.S. crude exports reached 4.2 million b/d in 2024, supporting Aframax Tanker Market demand.
South America emerges as a growth corridor, with Brazil's pre-salt production forecast to hit 4 million b/d by 2027.
Investment, M&A & Funding Activity in Crude Oil Carriers Market
M&A activity has accelerated as operators seek scale and compliance. In 2024, Teekay Corporation acquired 3 Aframax tankers for $210 million, while OSG Ship Management bought 2 Jones Act tankers for $180 million. Private equity firms, including Blackstone and Brookfield, deployed over $12 billion into tanker newbuilds and retrofits since 2022, focusing on dual-fuel VLCCs and scrubber installations.
Venture capital interest remains selective due to capital intensity, but climate-tech startups in wind-assisted propulsion (e.g., Norsepower) and voyage optimization AI (e.g., ZeroNorth) attracted $1.8 billion in early-stage funding. High-growth sub-segments include Maritime Decarbonization Market and Bunker Fuel Market, where methanol and ammonia fuel supply chains are being financed.
Strategic acquirers like Maersk Tankers and China Shipping Tanker Co. are consolidating mid-size fleets to offer one-stop logistics. The Petroleum Logistics Market sees integrated players investing in floating storage and lightering assets. Overall, capital flows favor assets with 10-year charters and IMO-compliant designs.
Major trade corridors: Middle East-to-Asia (15 million b/d), Atlantic Basin-to-Europe (4 million b/d), and U.S. Gulf-to-Asia (3.5 million b/d). Key net exporters: Saudi Arabia, Russia, U.S., and Brazil. Key importers: China, India, Japan, and South Korea.
Tariff and non-tariff barriers: The EU's sanctions on Russian crude rerouted 2.5 million b/d to India and China, adding 10-12 days per voyage and boosting ton-mile demand by 7%. The Jones Act restricts U.S. coastal trade to American-built vessels, increasing costs by 20-30%. IMO 2020 low-sulfur fuel rules added $15-20 per tonne to bunker costs, though compliant operators pass through via surcharges.
Geopolitical impacts: Red Sea disruptions in 2024 forced Suezmax Tanker Market vessels to reroute around Africa, adding 9,000 nautical miles and $1 million in fuel per trip. OPEC+ production cuts reduced Middle East exports by 1.2 million b/d in 2024, but U.S. shale exports filled the gap. The Shipbuilding Market benefits as operators order ice-class and dual-fuel vessels to handle Arctic and long-haul routes.
Crude Oil Carriers Market Segmentation
1. Capacity
1.1. Ultra Large Crude Carriers
1.2. Very Large Crude Carriers
1.3. Suezmax Tankers
1.4. Panamax Tankers
1.5. Aframax Tankers
Crude Oil Carriers Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Crude Oil Carriers Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.2% from 2020-2034
Segmentation
By Capacity
Ultra Large Crude Carriers
Very Large Crude Carriers
Suezmax Tankers
Panamax Tankers
Aframax Tankers
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Capacity
5.1.1. Ultra Large Crude Carriers
5.1.2. Very Large Crude Carriers
5.1.3. Suezmax Tankers
5.1.4. Panamax Tankers
5.1.5. Aframax Tankers
5.2. Market Analysis, Insights and Forecast - by Region
5.2.1. North America
5.2.2. South America
5.2.3. Europe
5.2.4. Middle East & Africa
5.2.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Capacity
6.1.1. Ultra Large Crude Carriers
6.1.2. Very Large Crude Carriers
6.1.3. Suezmax Tankers
6.1.4. Panamax Tankers
6.1.5. Aframax Tankers
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Capacity
7.1.1. Ultra Large Crude Carriers
7.1.2. Very Large Crude Carriers
7.1.3. Suezmax Tankers
7.1.4. Panamax Tankers
7.1.5. Aframax Tankers
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Capacity
8.1.1. Ultra Large Crude Carriers
8.1.2. Very Large Crude Carriers
8.1.3. Suezmax Tankers
8.1.4. Panamax Tankers
8.1.5. Aframax Tankers
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Capacity
9.1.1. Ultra Large Crude Carriers
9.1.2. Very Large Crude Carriers
9.1.3. Suezmax Tankers
9.1.4. Panamax Tankers
9.1.5. Aframax Tankers
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Capacity
10.1.1. Ultra Large Crude Carriers
10.1.2. Very Large Crude Carriers
10.1.3. Suezmax Tankers
10.1.4. Panamax Tankers
10.1.5. Aframax Tankers
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Alaska Tanker Co.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Kuwait Oil Tankers Co.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. China Shipping Tanker Co.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Ltd.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Essar Shipping
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Teekay Corporation
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Shipping Corporation of India.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Keystone Alaska LLC
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Maersk Tankers
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. OSG Ship Management Inc.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Tankers International LLC.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Crude Oil Carriers Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Crude Oil Carriers Market Revenue (billion), by Capacity 2026 & 2034
Figure 3: North America Crude Oil Carriers Market Revenue Share (%), by Capacity 2026 & 2034
Figure 4: North America Crude Oil Carriers Market Revenue (billion), by Country 2026 & 2034
Figure 5: North America Crude Oil Carriers Market Revenue Share (%), by Country 2026 & 2034
Figure 6: South America Crude Oil Carriers Market Revenue (billion), by Capacity 2026 & 2034
Figure 7: South America Crude Oil Carriers Market Revenue Share (%), by Capacity 2026 & 2034
Figure 8: South America Crude Oil Carriers Market Revenue (billion), by Country 2026 & 2034
Figure 9: South America Crude Oil Carriers Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Crude Oil Carriers Market Revenue (billion), by Capacity 2026 & 2034
Figure 11: Europe Crude Oil Carriers Market Revenue Share (%), by Capacity 2026 & 2034
Figure 12: Europe Crude Oil Carriers Market Revenue (billion), by Country 2026 & 2034
Figure 13: Europe Crude Oil Carriers Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Middle East & Africa Crude Oil Carriers Market Revenue (billion), by Capacity 2026 & 2034
Figure 15: Middle East & Africa Crude Oil Carriers Market Revenue Share (%), by Capacity 2026 & 2034
Figure 16: Middle East & Africa Crude Oil Carriers Market Revenue (billion), by Country 2026 & 2034
Figure 17: Middle East & Africa Crude Oil Carriers Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Crude Oil Carriers Market Revenue (billion), by Capacity 2026 & 2034
Figure 19: Asia Pacific Crude Oil Carriers Market Revenue Share (%), by Capacity 2026 & 2034
Figure 20: Asia Pacific Crude Oil Carriers Market Revenue (billion), by Country 2026 & 2034
Figure 21: Asia Pacific Crude Oil Carriers Market Revenue Share (%), by Country 2026 & 2034
Table 40: Rest of Asia Pacific Crude Oil Carriers Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% of data collection via direct interviews with VLCC and Suezmax tanker owners, ship management and crewing agencies, marine fuel suppliers (bunker traders), port and terminal operators for crude oil, and classification societies and marine surveyors.
Interviewed Fleet Operations Directors, Chartering Managers, Marine Fuel Procurement Heads, and Regulatory Compliance Officers (IMO) across Asia-Pacific, Middle East, and Europe.
Engagements include structured surveys, in-depth interviews, and pricing discussions, with primary data validated against vessel tracking (AIS) and port call records.
Ensured 85–90% guaranteed data accuracy through cross-verification of charter rates, fuel consumption, and fleet utilization.
Benchmarked fleet data against Clarksons Research and Lloyd's List Intelligence for vessel counts, orderbook, and scrapping rates.
Regulatory documents from IMO, EU ETS, and U.S. Coast Guard analyzed for compliance cost impacts.
All reports are updated to the date of purchase to reflect latest trade flows and charter rates.
Demand Modeling & Market Estimation
Used top-down (global crude oil production and trade flows) and bottom-up (vessel-level capacity and utilization) methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up calculation based on: Number of VLCCs and Suezmax tankers in global fleet, Average deadweight ton-miles per voyage, Bunker fuel consumption per day by vessel class, and Crude oil seaborne trade volume (million b/d).
Demand modeled as product of fleet capacity, utilization rate, and average voyage distance; supply modeled from orderbook deliveries and scrapping.
Forecast period 2026–2034 uses scenario analysis for oil demand peak, carbon regulations, and fleet renewal.
Data Accuracy & Quality Check
Triangulated primary interview data with AIS tracking, port authority records, and financial filings.
85–90% accuracy guaranteed via outlier detection and seasonal adjustment.
Cross-validated charter rates with Baltic Exchange indices and PitchBook M&A data.
Final estimates reviewed by internal panel of senior analysts and external advisors from DNV and ABS.
Frequently Asked Questions
1. How has the crude oil carriers market recovered post-pandemic and what structural shifts are permanent?
Post-2020, tanker demand rebounded as OECD inventory restocking and Russian oil trade rerouting increased ton-miles by 7% in 2023. Structural shifts include a permanent redrawing of trade routes due to sanctions on Russia, which added an estimated 3.5 million barrels per day of longer-haul voyages. The market size reached $268.18 billion in 2025 and is forecast to grow at a 4.2% CAGR as fleet renewal accelerates.
2. What investment activity and venture capital interest is shaping the crude oil carriers market?
Private equity and infrastructure funds deployed over $12 billion into tanker newbuilds and retrofits in 2024, targeting dual-fuel VLCCs and scrubber installations. Venture capital remains limited due to capital intensity, but climate-tech startups focusing on wind-assisted propulsion and voyage optimization attracted $1.8 billion in early-stage funding since 2022. Strategic acquirers like Maersk Tankers and Teekay Corporation are consolidating mid-size fleets.
3. Which disruptive technologies and emerging substitutes threaten crude oil carriers?
Alternative fuels like green ammonia and methanol are driving the retrofit of Suezmax and Aframax tankers, with 220 dual-fuel vessels on order as of 2025. Battery-electric and hydrogen fuel-cell propulsion remain unviable for long-haul crude, but pipeline expansions in the U.S. and Middle East substitute 1.2 million b/d of seaborne flows. Digital twin and AI-based routing platforms reduce effective demand by improving fleet utilization.
4. What is the current market size and CAGR projection through 2033?
The crude oil carriers market is valued at $268.18 billion in 2025 and is projected to reach $374.5 billion by 2033, registering a 4.2% CAGR. Volumes are measured in deadweight ton-miles, which grew 5.1% in 2024 due to Atlantic-to-Asia crude flows. The forecast period 2026-2034 anticipates peak oil demand around 2030, tempering late-decade growth.
5. What are the barriers to entry and competitive moats in the crude oil carriers market?
High capital costs for newbuild VLCCs, exceeding $120 million per vessel, and strict IMO decarbonization rules create significant entry barriers. Incumbents like Teekay and Maersk benefit from long-term charters with oil majors, proprietary vetting systems, and access to financing at lower rates. A global shortage of qualified seafarers and shipyard slots through 2027 further protects established players.
6. What technological innovations and R&D trends are shaping the industry?
R&D focuses on dual-fuel engines, air lubrication systems, and carbon capture onboard, with 45 pilot projects launched since 2023. Hull coatings and route optimization AI can cut fuel consumption by 12-15%, improving margins for early adopters. Classification societies like DNV and ABS are certifying ammonia-ready tankers, driving a fleet renewal cycle expected to peak in 2027.