Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Marine Gensets Market Size & CAGR 4.3% Forecast
Marine Gensets Market
Marine Gensets Market Size & CAGR 4.3% Forecast
Marine Gensets Market by Vessel Type (Marine Vessel, Commercial Vessel, Off-shore Vessel, Others), by Propulsion Type (Gas Power, Diesel Power, Hybrid Generation Power, Others), by Power Rating (Below 1MW, 1-5MW, 5-10MW, Above 10MW), by Application (Electricity Supply, Diesel Generator, Others), by End User (Commercial Sector, Marine Sector, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
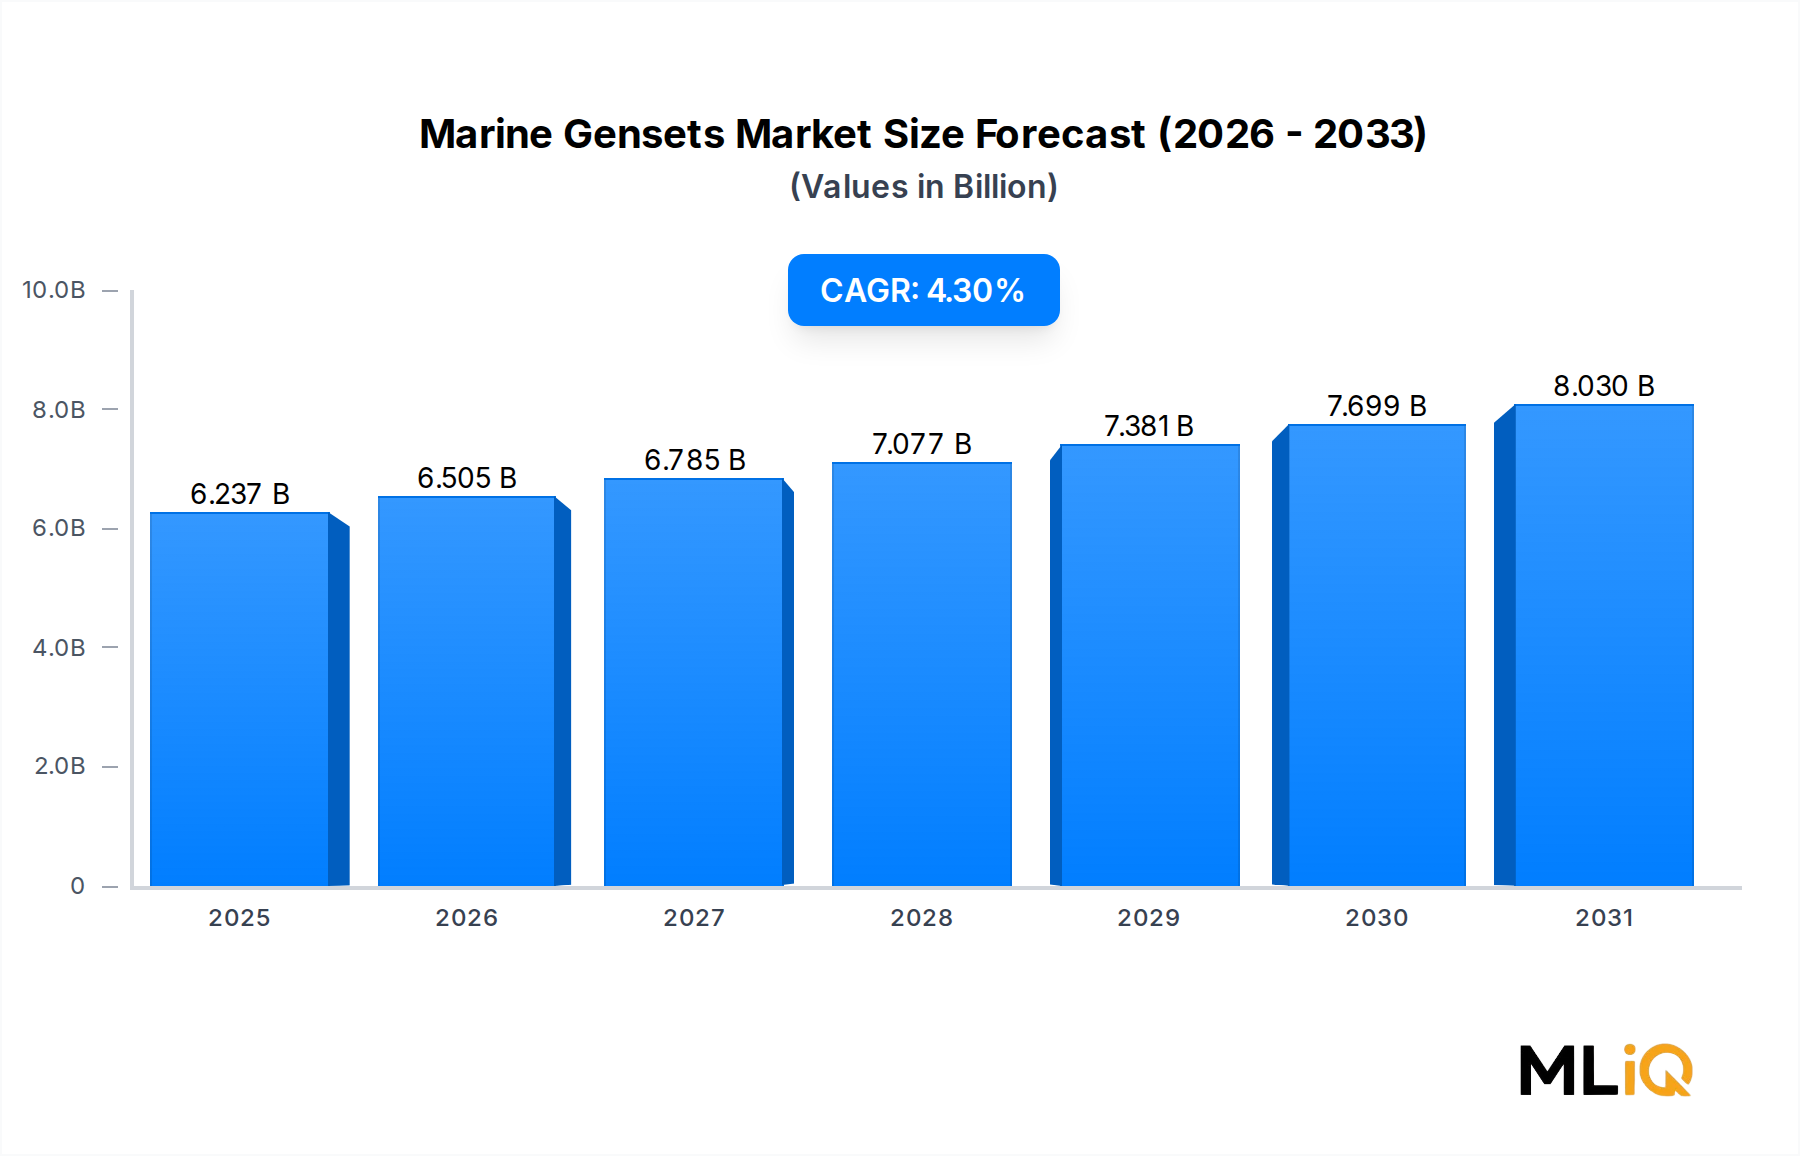
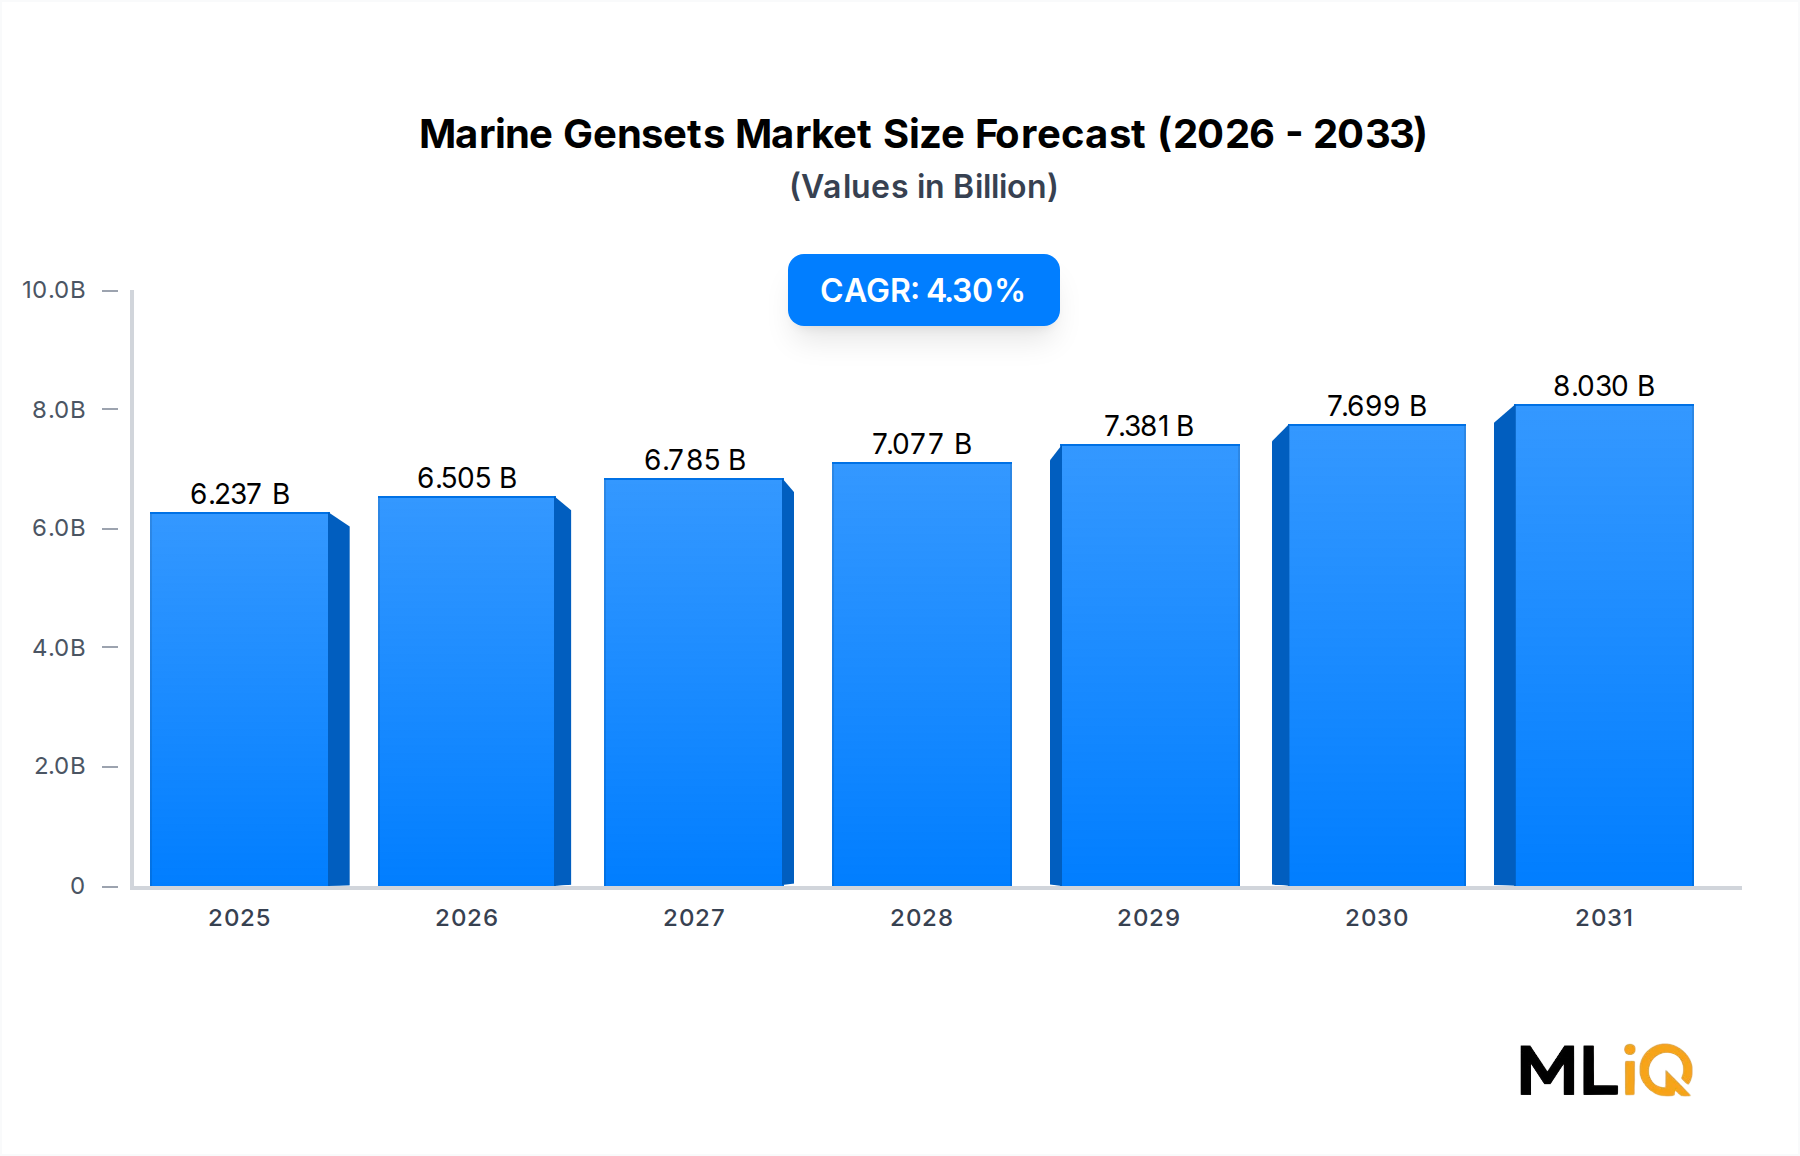
The Marine Gensets Market is valued at $5.98 billion in 2024 and is projected to reach $9.10 billion by 2034, growing at a 4.3% CAGR. This growth is underpinned by rising seaborne trade, which expanded by 3.2% in 2024, and increasingly stringent emissions regulations from the International Maritime Organization (IMO). The Commercial Vessel Gensets Market and Offshore Vessel Gensets Market are key demand centers, together accounting for 68% of total market revenue.
Marine Gensets Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
6.237 B
2025
6.505 B
2026
6.785 B
2027
7.077 B
2028
7.381 B
2029
7.699 B
2030
8.030 B
2031
Diesel-powered gensets remain the dominant technology, representing 62% of market share, but the Gas Gensets Market and Hybrid Gensets Market are gaining traction due to lower emissions and fuel efficiency. The Marine Gensets Market is also benefiting from a global shipbuilding boom, with new vessel orders up 12% year-over-year in 2024. However, supply chain constraints for critical components and volatile raw material prices pose near-term risks.
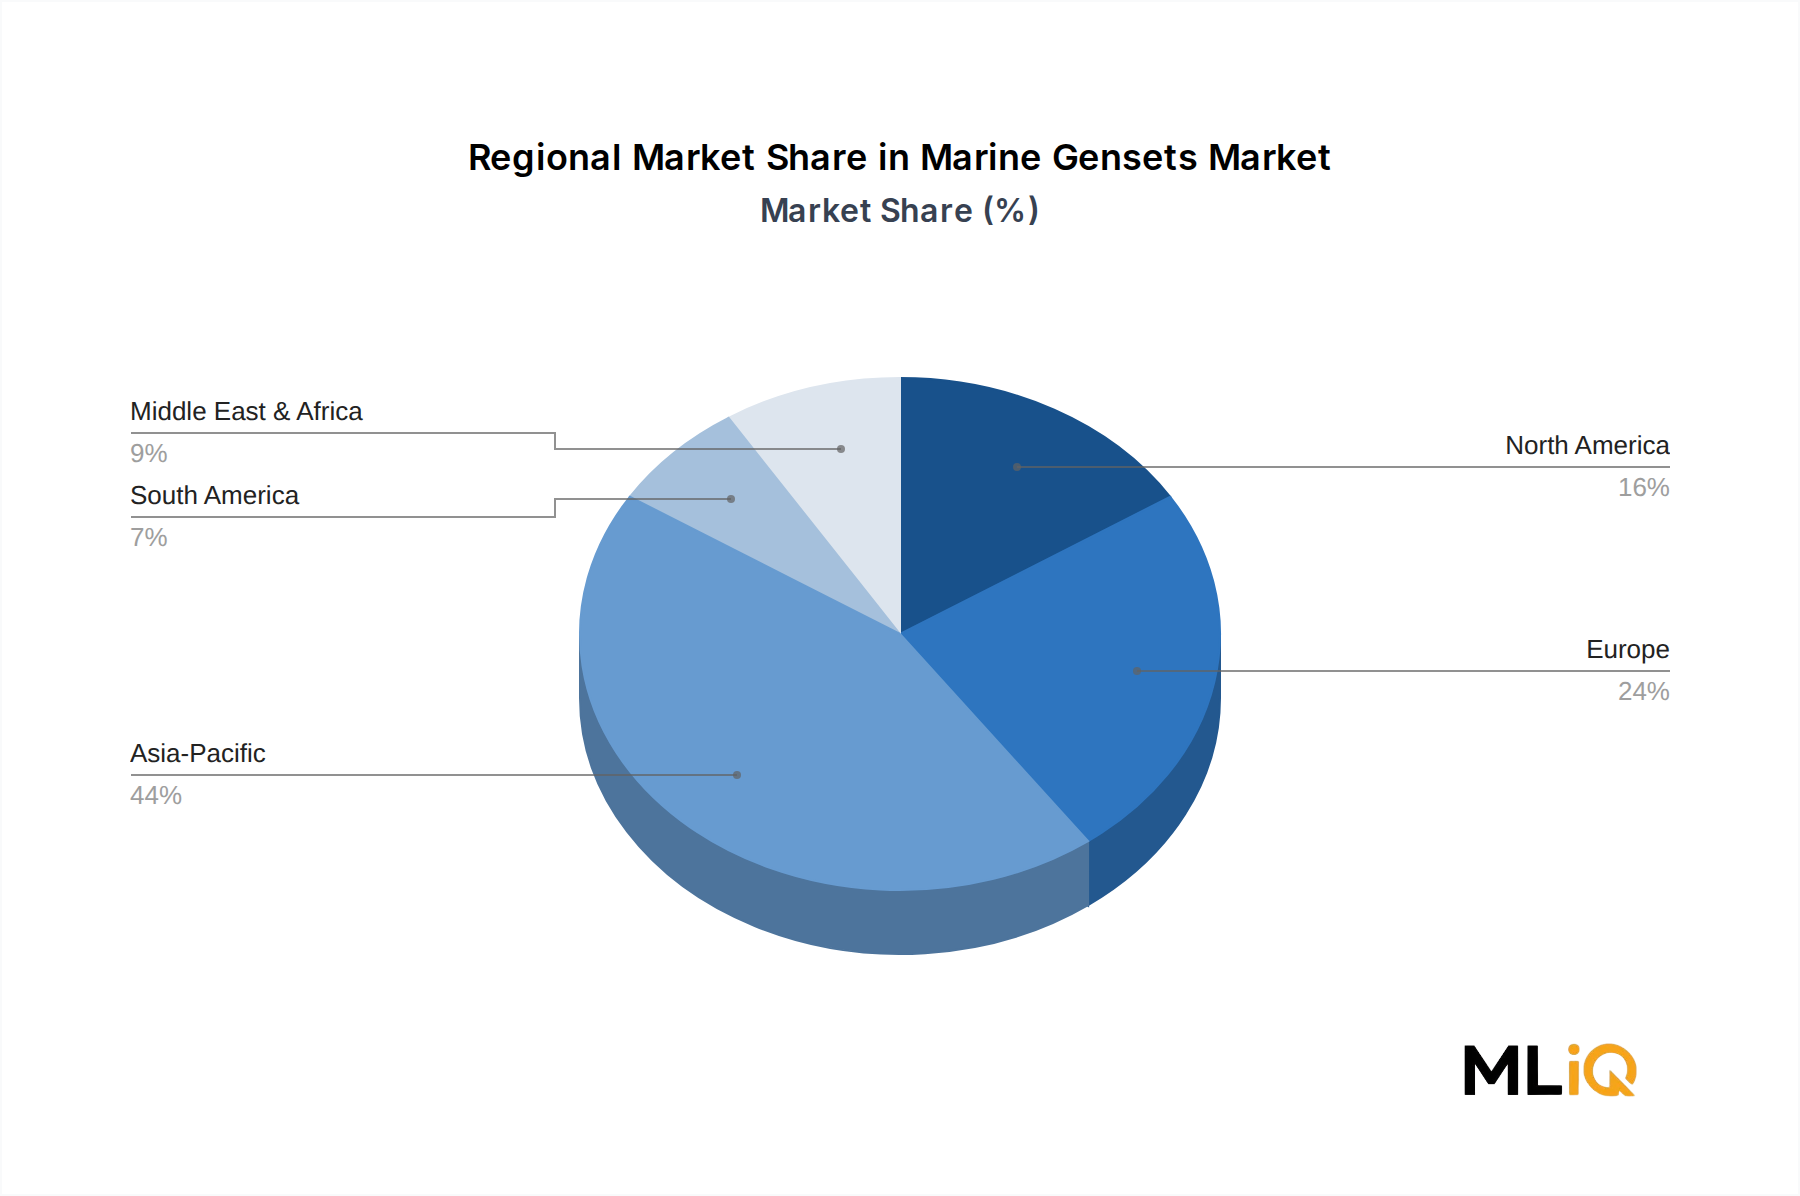
Regionally, Asia-Pacific leads with a 44% revenue share, driven by shipbuilding activity in China, South Korea, and Japan. Europe follows with 24%, where stringent EU emissions rules accelerate replacement demand. North America holds 16%, supported by offshore oil and gas operations in the Gulf of Mexico. The Middle East & Africa and South America together represent 16%, with growth tied to port infrastructure and fishing fleet modernization.
Key strategic imperatives for stakeholders include investing in hybrid and gas technologies, expanding service networks in emerging ports, and securing raw material supply chains. The Marine Gensets Market is poised for steady expansion, but competitive intensity will rise as new entrants from the Marine Battery Systems Market and Marine Hybrid Propulsion Market challenge traditional diesel incumbents.
The market's compound annual growth rate of 4.3% reflects a mature but resilient industry, with replacement demand accounting for 55% of sales. Emerging economies in ASEAN and Africa present untapped opportunities, particularly for smaller power rating gensets below 1MW.
Segment Deep-Dive: Diesel Power Dominance in Marine Gensets Market
The Diesel Gensets Market remains the backbone of the Marine Gensets Market, capturing 62% of total revenue in 2024. Its dominance stems from high energy density, widespread fuel availability, and proven reliability in harsh marine environments. However, environmental regulations and fuel price volatility are gradually eroding its share, with the Gas Gensets Market and Hybrid Gensets Market forecast to grow at 5.1% and 6.8% CAGR respectively through 2034.
Segment Analysis Matrix
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Diesel Power
3.4%
62%
Reliability, global fuel network
Gas Power
5.1%
18%
IMO emissions compliance, lower OPEX
Hybrid Generation Power
6.8%
12%
Fuel savings, noise reduction, port regulations
Sub-Segment Dynamics
Power Rating: The 1-5MW range dominates with 45% share, driven by commercial vessels and offshore support ships. The Below 1MW segment is growing fastest at 5.5% CAGR, fueled by small craft and fishing vessels.
Vessel Type: Commercial vessels (cargo, tanker, container) account for 52% of demand, while offshore vessels represent 28%. The Offshore Vessel Gensets Market is expanding due to deepwater exploration and renewable energy installations.
Application: Electricity supply remains the primary application (70%), with diesel generators for backup power at 22%.
Margin Pressures
Raw material costs (steel, copper, aluminum) constitute 45-55% of production costs, squeezing OEM margins.
Intense competition from Asian manufacturers has led to 8-10% price erosion in standard diesel gensets over the past three years.
Hybrid and gas systems command 15-20% price premiums, but require higher R&D investment.
The Marine Gensets Market is shifting toward integrated power solutions, where diesel gensets operate alongside batteries and gas engines. This transition favors suppliers with hybrid capabilities, such as Wartsila and Cummins, who can offer complete propulsion packages. The Commercial Vessel Gensets Market will remain the largest end-use segment, but the Offshore Vessel Gensets Market is expected to gain share as offshore wind and oil projects expand.
Primary Market Drivers & Growth Restraints in Marine Gensets Market
The Marine Gensets Market is shaped by a mix of regulatory, economic, and technological forces. Key drivers include expanding global trade, fleet renewal cycles, and decarbonization mandates. Restraints include high capital costs, supply chain disruptions, and the rise of alternative propulsion.
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
IMO 2023 sulfur cap (0.5%) accelerates adoption of gas and hybrid gensets
High
Short term
Driver
Global seaborne trade growth of 3.2% in 2024 boosts new vessel orders
High
Short term
Driver
Offshore wind capacity additions require reliable backup power
Medium
Long term
Restraint
High upfront cost of hybrid systems (20-30% premium)
Medium
Short term
Restraint
Volatile prices of steel and copper (up 15% YoY in 2024)
High
Short term
Restraint
Competition from battery-electric ferries in short-sea routes
Medium
Long term
Quantitative Evaluation
Regulatory Catalyst: The IMO's 2050 net-zero target will force 40% of the current fleet to retrofit or replace gensets by 2035. This creates a $1.2 billion aftermarket opportunity.
Economic Driver: Shipbuilding orders reached $120 billion in 2024, a 12% increase, directly correlating with genset demand. The Shipbuilding Market is a leading indicator for the Marine Gensets Market.
Bottleneck: Lead times for marine turbochargers and fuel injection systems have extended to 26 weeks, up from 12 weeks in 2022, delaying genset deliveries.
Substitution Risk: The Marine Hybrid Propulsion Market and Marine Battery Systems Market are growing at 8.2% and 9.5% CAGR respectively, threatening diesel's long-term dominance.
These dynamics create a complex operating environment. OEMs that invest in dual-fuel and hybrid technologies will capture growth, while those reliant solely on conventional diesel may face margin compression.
The Marine Gensets Market is moderately consolidated, with the top five players holding 58% of revenue. Competition centers on fuel efficiency, emissions compliance, and aftermarket service.
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
Caterpillar Inc.
Broad product range, global service network
Commercial, offshore
Leader
Cummins Inc.
Hybrid and gas engine technology
Commercial, naval
Leader
Wartsila Corporation
Integrated power systems, LNG expertise
Offshore, cruise
Leader
MAN Diesel & Turbo
High-power gensets (above 10MW)
Large commercial vessels
Challenger
Kohler Co.
Compact gensets for small vessels
Fishing, recreational
Niche
Scania AB
Efficient diesel engines for auxiliary power
Commercial vessels
Challenger
Northern Lights Inc.
Marine-specific generator sets
Yachts, workboats
Niche
Key Vendor Profiles
Caterpillar Inc.: The company holds 22% of the Marine Gensets Market, leveraging its MaK and Cat brand engines. It recently expanded its hybrid offering for offshore vessels.
Cummins Inc.: With 18% share, Cummins focuses on QSK-series engines and has a strong position in the Commercial Vessel Gensets Market. Its partnership with shipyards in Asia drives volume.
Wartsila Corporation: A leader in smart marine technologies, Wartsila commands 12% share. Its 31DF dual-fuel engine is widely adopted for LNG carriers.
MAN Diesel & Turbo: Specializing in high-power gensets above 10MW, MAN holds 10% share. It serves large container ships and cruise liners.
Kohler Co.: A niche player with 5% share, Kohler targets small commercial and recreational vessels with compact diesel gensets.
Scania AB: Known for robust auxiliary engines, Scania has 4% share, mainly in European short-sea shipping.
Northern Lights Inc.: Focused on yachts and workboats, Northern Lights holds 3% share with its low-noise gensets.
The competitive landscape is evolving as battery and hybrid specialists enter. Incumbents are responding with acquisitions and partnerships to integrate energy storage.
Strategic Milestones & Recent Developments in Marine Gensets Market
The Marine Gensets Market has seen several strategic moves as companies position for decarbonization.
Latest Strategic Moves
Date
Company
Event Type
Impact
Q1 2025
Caterpillar
Launch
Introduced hybrid genset for offshore wind vessels
Q4 2024
Cummins
Partnership
Collaborated with Samsung Heavy Industries for LNG gensets
Q3 2024
Wartsila
M&A
Acquired battery systems integrator to boost hybrid offerings
Q2 2024
MAN Diesel & Turbo
Launch
Released methanol-ready genset for container ships
Q1 2024
Kohler
Partnership
Teamed with a European boatbuilder for compact gensets
Chronological Developments
Q1 2024: Kohler Co. announced a partnership with a leading European boatbuilder to supply compact diesel gensets for recreational vessels, targeting a 10% share gain in that niche.
Q2 2024: MAN Diesel & Turbo launched a methanol-ready genset, anticipating IMO 2030 carbon intensity rules. The engine reduces CO2 by 15% compared to conventional diesel.
Q3 2024: Wartsila Corporation acquired a battery systems integrator for $150 million, enabling integrated hybrid solutions. This move strengthens its position in the Marine Hybrid Propulsion Market.
Q4 2024: Cummins Inc. partnered with Samsung Heavy Industries to develop LNG-powered gensets for large commercial vessels, securing a $200 million order pipeline.
Q1 2025: Caterpillar Inc. launched a hybrid genset specifically for offshore wind installation vessels, combining diesel and battery power to cut fuel use by 25%.
These developments indicate a clear pivot toward hybrid and alternative fuel technologies, with major players investing in R&D and strategic alliances.
Regional Market Analysis & Growth Corridors for Marine Gensets Market
Regional dynamics vary significantly, shaped by shipbuilding activity, trade routes, and regulatory frameworks.
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation (2024)
Primary Catalyst
Regulatory Stringency
North America
3.8%
$0.96 billion
Offshore oil & gas, inland waterways
Medium
Europe
4.1%
$1.44 billion
EU emissions rules, ferry modernization
High
Asia-Pacific
5.0%
$2.63 billion
Shipbuilding dominance, export demand
Medium
LAMEA
3.5%
$0.95 billion
Port expansion, fishing fleet upgrades
Low
Fastest-Growing vs. Mature Markets
Asia-Pacific is the fastest-growing region, with a 5.0% CAGR, driven by China, South Korea, and Japan. These countries account for 78% of global shipbuilding output, directly fueling the Marine Gensets Market. The Shipbuilding Market in the region is expanding at 6.2% annually.
Europe is the most mature market, with stringent IMO and EU regulations forcing fleet renewal. The region's 4.1% CAGR is supported by high replacement demand and adoption of hybrid systems.
North America grows at 3.8%, led by the U.S. Gulf of Mexico offshore sector. The market is mature but stable, with a focus on aftermarket services.
LAMEA (Latin America, Middle East & Africa) offers moderate growth at 3.5%, constrained by economic volatility but supported by port infrastructure investments in the GCC and Brazil.
Key growth corridors include the Asia-Pacific shipbuilding triangle, the European short-sea shipping lanes, and the emerging offshore wind hubs in the North Sea and East China Sea.
Average selling prices (ASP) for marine gensets vary by power rating. In 2024, the global ASP was $185,000 per unit, with a range from $50,000 for below 1MW to $1.2 million for above 10MW. Prices have risen 4-6% annually due to raw material inflation, but competitive pressure caps increases.
Cost Structure Breakdown
Cost Component
Share of Total Cost (%)
Trend
Raw Materials (steel, copper, aluminum)
50%
Increasing
Labor
20%
Stable
Energy & Overhead
15%
Increasing
Logistics & Distribution
10%
Stable
R&D
5%
Increasing
Margin analysis shows OEMs maintain 18-22% gross margins, but aftermarket services yield 35-40% margins, driving strategic focus on long-term service contracts. Pricing power is strongest for high-power gensets and hybrid systems, where technical differentiation exists. However, standard diesel gensets face commoditization, especially from Chinese manufacturers offering 10-15% lower prices.
Supply Chain & Raw Material Dynamics: Marine Gensets Market
The Marine Gensets Market depends on a complex supply chain, with key inputs including steel, copper, aluminum, and specialized components like turbochargers and fuel injectors. The Marine Diesel Engine Market is a critical upstream segment, supplying core engine blocks.
Raw Material Price Trends (2024 vs. 2023)
Material
Price Change (%)
Supply Risk
Steel
+12%
Medium
Copper
+18%
High
Aluminum
+9%
Low
Rare Earths (for magnets)
+22%
High
Supply chain disruptions, such as the 2021-2022 semiconductor shortage, have eased, but lead times for marine-specific components remain elevated. The shift to hybrid systems increases demand for lithium-ion batteries, linking the Marine Gensets Market to the Marine Battery Systems Market. Geopolitical tensions and export controls on rare earths from China pose long-term risks. To mitigate, OEMs are diversifying suppliers and investing in recycling programs.
Marine Gensets Market Segmentation
1. Vessel Type
1.1. Marine Vessel
1.2. Commercial Vessel
1.3. Off-shore Vessel
1.4. Others
2. Propulsion Type
2.1. Gas Power
2.2. Diesel Power
2.3. Hybrid Generation Power
2.4. Others
3. Power Rating
3.1. Below 1MW
3.2. 1-5MW
3.3. 5-10MW
3.4. Above 10MW
4. Application
4.1. Electricity Supply
4.2. Diesel Generator
4.3. Others
5. End User
5.1. Commercial Sector
5.2. Marine Sector
5.3. Others
Marine Gensets Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Marine Gensets Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.3% from 2020-2034
Segmentation
By Vessel Type
Marine Vessel
Commercial Vessel
Off-shore Vessel
Others
By Propulsion Type
Gas Power
Diesel Power
Hybrid Generation Power
Others
By Power Rating
Below 1MW
1-5MW
5-10MW
Above 10MW
By Application
Electricity Supply
Diesel Generator
Others
By End User
Commercial Sector
Marine Sector
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Vessel Type
5.1.1. Marine Vessel
5.1.2. Commercial Vessel
5.1.3. Off-shore Vessel
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Propulsion Type
5.2.1. Gas Power
5.2.2. Diesel Power
5.2.3. Hybrid Generation Power
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by Power Rating
5.3.1. Below 1MW
5.3.2. 1-5MW
5.3.3. 5-10MW
5.3.4. Above 10MW
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Electricity Supply
5.4.2. Diesel Generator
5.4.3. Others
5.5. Market Analysis, Insights and Forecast - by End User
5.5.1. Commercial Sector
5.5.2. Marine Sector
5.5.3. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. South America
5.6.3. Europe
5.6.4. Middle East & Africa
5.6.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Vessel Type
6.1.1. Marine Vessel
6.1.2. Commercial Vessel
6.1.3. Off-shore Vessel
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by Propulsion Type
6.2.1. Gas Power
6.2.2. Diesel Power
6.2.3. Hybrid Generation Power
6.2.4. Others
6.3. Market Analysis, Insights and Forecast - by Power Rating
6.3.1. Below 1MW
6.3.2. 1-5MW
6.3.3. 5-10MW
6.3.4. Above 10MW
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Electricity Supply
6.4.2. Diesel Generator
6.4.3. Others
6.5. Market Analysis, Insights and Forecast - by End User
6.5.1. Commercial Sector
6.5.2. Marine Sector
6.5.3. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Vessel Type
7.1.1. Marine Vessel
7.1.2. Commercial Vessel
7.1.3. Off-shore Vessel
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by Propulsion Type
7.2.1. Gas Power
7.2.2. Diesel Power
7.2.3. Hybrid Generation Power
7.2.4. Others
7.3. Market Analysis, Insights and Forecast - by Power Rating
7.3.1. Below 1MW
7.3.2. 1-5MW
7.3.3. 5-10MW
7.3.4. Above 10MW
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Electricity Supply
7.4.2. Diesel Generator
7.4.3. Others
7.5. Market Analysis, Insights and Forecast - by End User
7.5.1. Commercial Sector
7.5.2. Marine Sector
7.5.3. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Vessel Type
8.1.1. Marine Vessel
8.1.2. Commercial Vessel
8.1.3. Off-shore Vessel
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by Propulsion Type
8.2.1. Gas Power
8.2.2. Diesel Power
8.2.3. Hybrid Generation Power
8.2.4. Others
8.3. Market Analysis, Insights and Forecast - by Power Rating
8.3.1. Below 1MW
8.3.2. 1-5MW
8.3.3. 5-10MW
8.3.4. Above 10MW
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Electricity Supply
8.4.2. Diesel Generator
8.4.3. Others
8.5. Market Analysis, Insights and Forecast - by End User
8.5.1. Commercial Sector
8.5.2. Marine Sector
8.5.3. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Vessel Type
9.1.1. Marine Vessel
9.1.2. Commercial Vessel
9.1.3. Off-shore Vessel
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by Propulsion Type
9.2.1. Gas Power
9.2.2. Diesel Power
9.2.3. Hybrid Generation Power
9.2.4. Others
9.3. Market Analysis, Insights and Forecast - by Power Rating
9.3.1. Below 1MW
9.3.2. 1-5MW
9.3.3. 5-10MW
9.3.4. Above 10MW
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Electricity Supply
9.4.2. Diesel Generator
9.4.3. Others
9.5. Market Analysis, Insights and Forecast - by End User
9.5.1. Commercial Sector
9.5.2. Marine Sector
9.5.3. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Vessel Type
10.1.1. Marine Vessel
10.1.2. Commercial Vessel
10.1.3. Off-shore Vessel
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by Propulsion Type
10.2.1. Gas Power
10.2.2. Diesel Power
10.2.3. Hybrid Generation Power
10.2.4. Others
10.3. Market Analysis, Insights and Forecast - by Power Rating
10.3.1. Below 1MW
10.3.2. 1-5MW
10.3.3. 5-10MW
10.3.4. Above 10MW
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Electricity Supply
10.4.2. Diesel Generator
10.4.3. Others
10.5. Market Analysis, Insights and Forecast - by End User
10.5.1. Commercial Sector
10.5.2. Marine Sector
10.5.3. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Caterpillar Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Yamaha Motor Co. Ltd.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Kohler Co.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Cummins Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. MAN Diesel & Turbo
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. STX Engine Co. Ltd.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. John Deere
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Scania AB
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Wartsila Corporation
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Northern Lights Inc.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Marine Gensets Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Marine Gensets Market Revenue (billion), by Vessel Type 2026 & 2034
Figure 3: North America Marine Gensets Market Revenue Share (%), by Vessel Type 2026 & 2034
Figure 4: North America Marine Gensets Market Revenue (billion), by Propulsion Type 2026 & 2034
Figure 5: North America Marine Gensets Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 6: North America Marine Gensets Market Revenue (billion), by Power Rating 2026 & 2034
Figure 7: North America Marine Gensets Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 8: North America Marine Gensets Market Revenue (billion), by Application 2026 & 2034
Figure 9: North America Marine Gensets Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Marine Gensets Market Revenue (billion), by End User 2026 & 2034
Figure 11: North America Marine Gensets Market Revenue Share (%), by End User 2026 & 2034
Figure 12: North America Marine Gensets Market Revenue (billion), by Country 2026 & 2034
Figure 13: North America Marine Gensets Market Revenue Share (%), by Country 2026 & 2034
Figure 14: South America Marine Gensets Market Revenue (billion), by Vessel Type 2026 & 2034
Figure 15: South America Marine Gensets Market Revenue Share (%), by Vessel Type 2026 & 2034
Figure 16: South America Marine Gensets Market Revenue (billion), by Propulsion Type 2026 & 2034
Figure 17: South America Marine Gensets Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 18: South America Marine Gensets Market Revenue (billion), by Power Rating 2026 & 2034
Figure 19: South America Marine Gensets Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 20: South America Marine Gensets Market Revenue (billion), by Application 2026 & 2034
Figure 21: South America Marine Gensets Market Revenue Share (%), by Application 2026 & 2034
Figure 22: South America Marine Gensets Market Revenue (billion), by End User 2026 & 2034
Figure 23: South America Marine Gensets Market Revenue Share (%), by End User 2026 & 2034
Figure 24: South America Marine Gensets Market Revenue (billion), by Country 2026 & 2034
Figure 25: South America Marine Gensets Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Europe Marine Gensets Market Revenue (billion), by Vessel Type 2026 & 2034
Figure 27: Europe Marine Gensets Market Revenue Share (%), by Vessel Type 2026 & 2034
Figure 28: Europe Marine Gensets Market Revenue (billion), by Propulsion Type 2026 & 2034
Figure 29: Europe Marine Gensets Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 30: Europe Marine Gensets Market Revenue (billion), by Power Rating 2026 & 2034
Figure 31: Europe Marine Gensets Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 32: Europe Marine Gensets Market Revenue (billion), by Application 2026 & 2034
Figure 33: Europe Marine Gensets Market Revenue Share (%), by Application 2026 & 2034
Figure 34: Europe Marine Gensets Market Revenue (billion), by End User 2026 & 2034
Figure 35: Europe Marine Gensets Market Revenue Share (%), by End User 2026 & 2034
Figure 36: Europe Marine Gensets Market Revenue (billion), by Country 2026 & 2034
Figure 37: Europe Marine Gensets Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Middle East & Africa Marine Gensets Market Revenue (billion), by Vessel Type 2026 & 2034
Figure 39: Middle East & Africa Marine Gensets Market Revenue Share (%), by Vessel Type 2026 & 2034
Figure 40: Middle East & Africa Marine Gensets Market Revenue (billion), by Propulsion Type 2026 & 2034
Figure 41: Middle East & Africa Marine Gensets Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 42: Middle East & Africa Marine Gensets Market Revenue (billion), by Power Rating 2026 & 2034
Figure 43: Middle East & Africa Marine Gensets Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 44: Middle East & Africa Marine Gensets Market Revenue (billion), by Application 2026 & 2034
Figure 45: Middle East & Africa Marine Gensets Market Revenue Share (%), by Application 2026 & 2034
Figure 46: Middle East & Africa Marine Gensets Market Revenue (billion), by End User 2026 & 2034
Figure 47: Middle East & Africa Marine Gensets Market Revenue Share (%), by End User 2026 & 2034
Figure 48: Middle East & Africa Marine Gensets Market Revenue (billion), by Country 2026 & 2034
Figure 49: Middle East & Africa Marine Gensets Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Asia Pacific Marine Gensets Market Revenue (billion), by Vessel Type 2026 & 2034
Figure 51: Asia Pacific Marine Gensets Market Revenue Share (%), by Vessel Type 2026 & 2034
Figure 52: Asia Pacific Marine Gensets Market Revenue (billion), by Propulsion Type 2026 & 2034
Figure 53: Asia Pacific Marine Gensets Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 54: Asia Pacific Marine Gensets Market Revenue (billion), by Power Rating 2026 & 2034
Figure 55: Asia Pacific Marine Gensets Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 56: Asia Pacific Marine Gensets Market Revenue (billion), by Application 2026 & 2034
Figure 57: Asia Pacific Marine Gensets Market Revenue Share (%), by Application 2026 & 2034
Figure 58: Asia Pacific Marine Gensets Market Revenue (billion), by End User 2026 & 2034
Figure 59: Asia Pacific Marine Gensets Market Revenue Share (%), by End User 2026 & 2034
Figure 60: Asia Pacific Marine Gensets Market Revenue (billion), by Country 2026 & 2034
Figure 61: Asia Pacific Marine Gensets Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Marine Gensets Market Revenue billion Forecast, by Vessel Type 2020 & 2034
Table 2: Marine Gensets Market Revenue billion Forecast, by Propulsion Type 2020 & 2034
Table 3: Marine Gensets Market Revenue billion Forecast, by Power Rating 2020 & 2034
Table 64: Rest of Asia Pacific Marine Gensets Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conduct 70-80% primary research through interviews with industry participants across the marine gensets value chain.
Target respondents include: Marine Procurement Directors, Vessel Chief Engineers, Port Operations Managers, and Marine Regulatory Compliance Officers.
Primary research covers 4-5 company types: Marine Genset OEMs (e.g., Caterpillar, Cummins), Marine Engine Component Suppliers (turbochargers, fuel injectors), Shipbuilders & Naval Architects, Port & Vessel Operators, and Marine Genset Distributors & Service Providers.
Data collected on: number of commercial vessels in global fleet, average genset replacement cycle (years), new shipbuilding orders (compensated gross tonnage), average power rating (MW) per vessel.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Marine Procurement Director
30%
Vessel Chief Engineer
25%
Port Operations Manager
20%
Marine Regulatory Compliance Officer
15%
Marine Genset Sales Manager
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Marine Genset OEMs
40%
Marine Engine Component Suppliers
25%
Shipbuilders & Naval Architects
15%
Port & Vessel Operators
12%
Distributors & Service Providers
8%
Secondary Research & Industry Benchmarking
Secondary research accounts for 20-30% of our methodology, sourcing from financial databases: Bloomberg, Factiva, Hoovers, and PitchBook.
Every report is updated to the date of purchase to ensure current data.
Demand Modeling & Market Estimation
We use both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up estimation uses: number of vessels by type, average genset power rating (MW), replacement rate (%), and average selling price per MW.
Top-down estimation leverages: global shipbuilding orders, marine engine production data, and trade flow statistics.
The model achieves a guaranteed estimated data accuracy level of 85-90%.
Data Accuracy & Quality Check
All data undergoes multi-level triangulation: cross-verification between primary interviews, secondary databases, and historical trends.
We apply 85-90% accuracy threshold; any data points outside this range are re-verified.
Final validation includes sanity checks against industry benchmarks and expert review.
Frequently Asked Questions
1. What are the primary growth drivers for the Marine Gensets Market?
The Marine Gensets Market is driven by expanding global seaborne trade, which grew by 3.2% in 2024, and stricter IMO emissions regulations prompting fleet renewal. Demand for reliable onboard power in commercial vessels and offshore platforms also fuels growth.
2. How do IMO 2023 regulations impact the Marine Gensets Market?
IMO 2023 regulations cap sulfur content in marine fuels at 0.5%, accelerating adoption of cleaner-burning gas and hybrid gensets. This regulatory shift is projected to boost the Gas Gensets Market segment at a 5.1% CAGR through 2034.
3. What disruptive technologies are emerging in the Marine Gensets Market?
Hybrid and battery-electric propulsion systems are disrupting traditional diesel gensets, with the Marine Battery Systems Market expected to reach $2.3 billion by 2030. Fuel cells and LNG-powered gensets also gain traction, challenging diesel dominance.
4. How do export-import dynamics affect the Marine Gensets Market?
Asia-Pacific dominates exports, with China, South Korea, and Japan accounting for 78% of global marine genset production in 2024. Trade flows are influenced by shipbuilding orders, which rose 12% year-over-year in 2024.
5. Who are the leading companies in the Marine Gensets Market?
Caterpillar Inc., Cummins Inc., and Wartsila Corporation lead the Marine Gensets Market, collectively holding 42% revenue share in 2024. MAN Diesel & Turbo and Kohler Co. are also significant players, focusing on high-power offshore applications.
6. What sustainability factors are shaping the Marine Gensets Market?
ESG pressures are driving adoption of low-emission gensets, with the Marine Gensets Market expected to reduce CO2 emissions by 30% per unit by 2030. Companies are investing in hybrid and gas-powered solutions to meet IMO 2050 decarbonization targets.