Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Medium Voltage Transformer Market to 2033: 6.97% CAGR
Medium Voltage Transformer Market
Medium Voltage Transformer Market to 2033: 6.97% CAGR
Medium Voltage Transformer Market by Product Type (Liquid-Filled Transformer, Dry-Type Transformer), by Mounting (Pad-Mounted Transformer, Pole-Mounted Transformer), by Application (Residential, Commercial, Industrial), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
Key Insights & Executive Summary: Medium Voltage Transformer Market
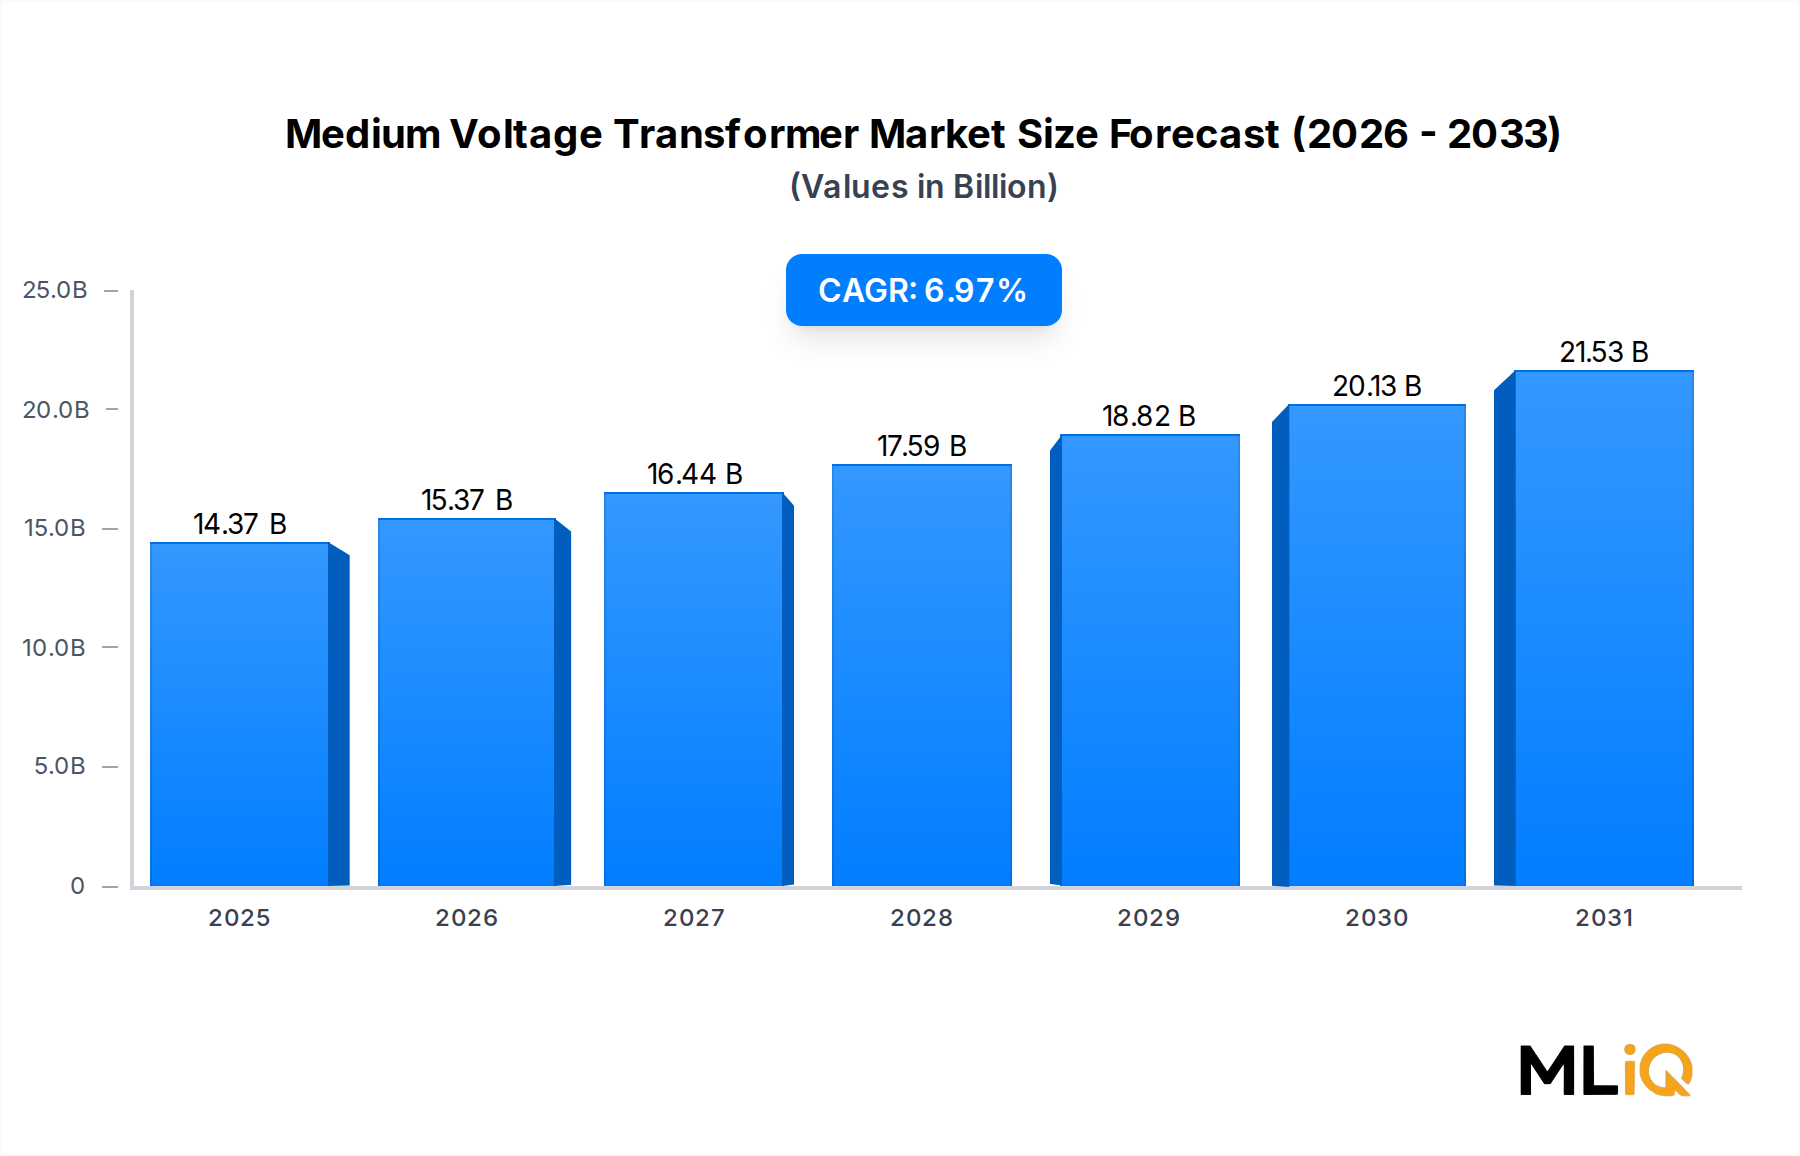
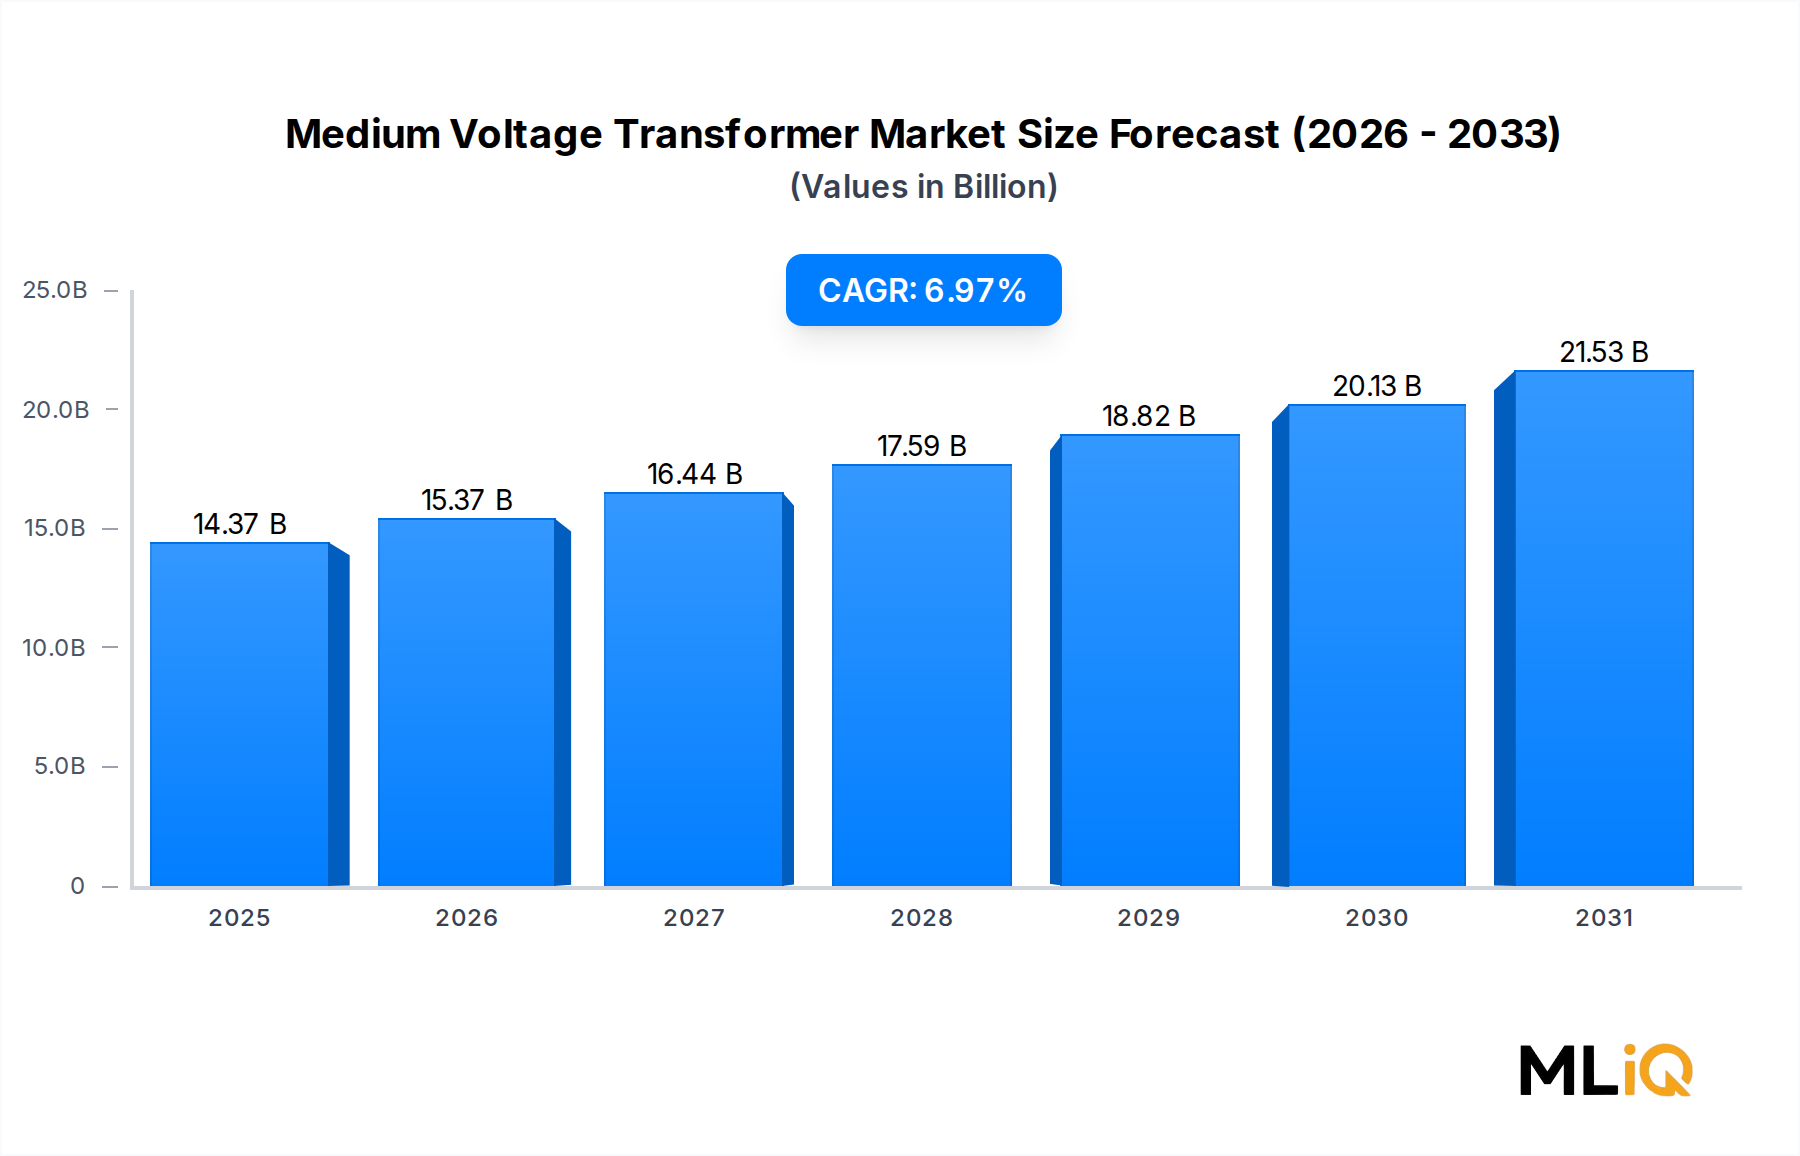
The Medium Voltage Transformer Market is projected to expand from $14.37 billion in 2025 to $24.6 billion by 2033, representing a 6.97% CAGR. Growth is tied to grid modernization, renewable energy interconnection, and rising electricity demand from data centers and electric vehicles. The broader Power Transformer Market provides upstream scale and technology spillovers, especially in high-voltage insulation and core materials. Smart grid investments are increasing demand for intelligent monitoring and voltage regulation, which supports the Smart Grid Transformer Market.
Medium Voltage Transformer Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
14.37 B
2025
15.37 B
2026
16.44 B
2027
17.59 B
2028
18.82 B
2029
20.13 B
2030
21.53 B
2031
Key demand catalysts include:
Global electricity consumption is expected to rise 2.5–3.0% annually through 2030, requiring distribution capacity upgrades.
Renewable energy additions reached 510 GW in 2023, with solar and wind farms needing step-up and step-down medium voltage transformers.
Data center power demand could grow 160% by 2030, driving pad-mounted and dry-type transformer installations.
The Renewable Energy Transformer Market benefits from utility-scale solar and offshore wind projects, particularly in Asia-Pacific and Europe.
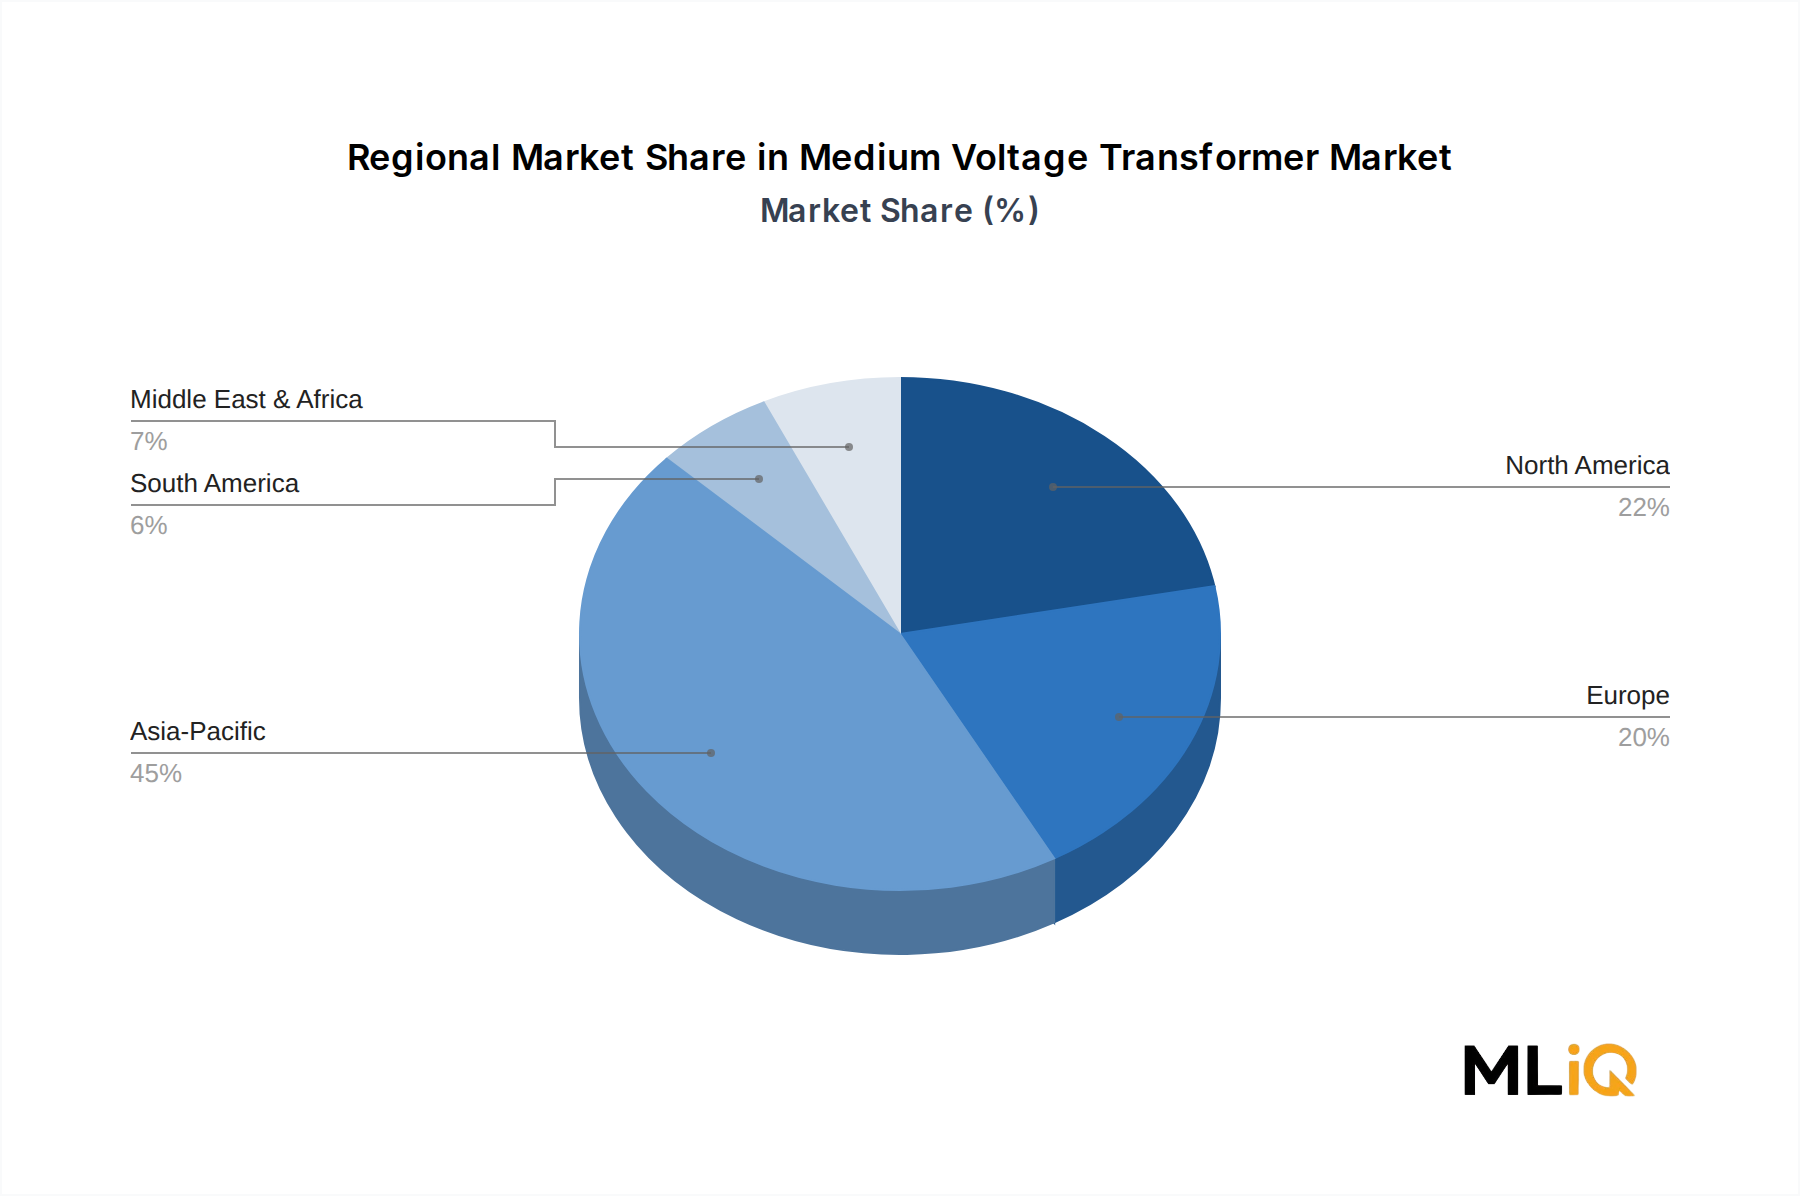
Regionally, Asia-Pacific holds the largest revenue share at 45%, followed by North America at 22% and Europe at 20%. Supply chain pressure from electrical steel and copper remains a risk, but vendor backlogs and capacity expansions indicate a multi-year replacement and new-build cycle. The forecast assumes no major regulatory reversal on grid decarbonization and stable raw material availability.
Segment Deep-Dive: Liquid-Filled Transformer Dominance in Medium Voltage Transformer Market
Product Type Dynamics
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Liquid-Filled Transformer
6.5%
58%
Utility distribution and renewable step-up applications
Dry-Type Transformer
7.8%
30%
Indoor commercial, data center, and metro rail use
Pad-Mounted Transformer
7.1%
42% of mounting segment
Underground distribution and urban grid hardening
The Liquid-Filled Transformer Market remains the largest product category, accounting for 58% of medium voltage transformer revenue in 2025. These units dominate utility distribution networks because of high efficiency, overload tolerance, and lower upfront cost per kVA. Growth is steady at 6.5% CAGR, supported by replacement demand in North America and capacity additions in Asia-Pacific.
Dry-Type and Pad-Mounted Growth
The Dry-Type Transformer Market is growing faster at 7.8% CAGR, driven by fire safety requirements in commercial buildings, data centers, and hospitals. Dry-type units avoid oil containment and are preferred for indoor installations. The Pad-Mounted Transformer Market captures 42% of mounting segment revenue, as utilities shift toward underground distribution and compact urban substations. Pole-mounted units remain cost-effective in rural electrification but face slower growth.
Margin Pressures
Copper and grain-oriented electrical steel represent 50–60% of bill-of-materials cost.
The Electrical Steel Market has seen price swings of 20–35% since 2021, compressing OEM margins.
Liquid-filled transformers face environmental regulations on mineral oil, pushing ester-fluid alternatives at 10–15% price premiums.
Dry-type transformers require more copper per kVA, making them sensitive to copper price spikes.
Manufacturers are responding with automated winding, amorphous cores, and localized assembly to reduce landed costs. The segment mix is shifting slowly toward dry-type and pad-mounted designs, but liquid-filled units will retain majority share through 2033 because of utility procurement inertia and lower total cost of ownership for high-load applications.
Primary Market Drivers & Growth Restraints in Medium Voltage Transformer Market
Factor Type
Description
Impact Level
Timeline
Driver
Grid modernization and replacement of aging distribution assets
High
Long term
Driver
Renewable energy interconnection and inverter-based resources
High
Long term
Driver
Data center, EV charging, and industrial electrification demand
High
Short term
Driver
Government efficiency standards and smart grid funding
Medium
Medium term
Restraint
Electrical steel and copper price volatility
High
Short term
Restraint
Long permitting and utility approval cycles
Medium
Long term
Restraint
Shortage of skilled transformer winders and test technicians
Medium
Short term
Grid modernization is the strongest driver. Utilities in the United States and Europe are replacing transformers installed in the 1970s and 1980s, and the average age of distribution transformers in the U.S. exceeds 35 years. The Industrial Transformer Market benefits from manufacturing reshoring, electric arc furnace expansions, and semiconductor fab construction. The Commercial Transformer Market is supported by data centers, hospitals, and office retrofits that require dry-type and pad-mounted units.
Restraints are mostly cost and lead-time related. Grain-oriented electrical steel supply is concentrated among Nippon Steel, JFE Steel, and thyssenkrupp, and capacity additions take 2–3 years. Transformer lead times peaked at 80 weeks in 2024, delaying project completion. Regulatory compliance adds 5–10% to unit costs but also creates replacement demand. Overall, driver impact outweighs restraints, supporting the 6.97% CAGR.
Competitive Ecosystem & Key Vendor Profiles: Medium Voltage Transformer Market
Company Name
Core Strength
Target Audience
Market Position
Hitachi ABB Power Grids
High-voltage and medium-voltage integration
Utilities, EPCs
Leader
Siemens
Digital grid solutions and global service
Utilities, industrial
Leader
Schneider Electric
EcoStruxure grid software and dry-type transformers
Commercial, data centers
Leader
Eaton
Pad-mounted and distribution transformers
Utilities, industrial
Challenger
SGB-SMIT
Custom liquid-filled transformers
Utilities, renewables
Challenger
CHINT Group
Cost-competitive liquid-filled units
Asia-Pacific utilities
Challenger
Mitsubishi Electric
High-efficiency dry-type and gas-insulated
Industrial, rail
Niche
GE Vernova
Grid automation and transformer retrofits
Utilities
Challenger
Hammond Power Solutions
Dry-type transformers for commercial use
Commercial, industrial
Niche
Olsun Electrics Corporation
Custom magnetic components
Industrial OEMs
Niche
Hitachi ABB Power Grids: Leverages ABB grid automation and Hitachi digital platforms to sell integrated substation packages. The company holds a leading position in Europe and North America.
Siemens: Offers transformers with digital monitoring and has a strong service network. It targets utilities and large industrial customers with total lifecycle contracts.
Schneider Electric: Focuses on commercial and data center segments with dry-type transformers and energy management software. It has expanded medium voltage offerings through partnerships.
Eaton: Strong in pad-mounted transformers for North American utilities. It benefits from grid resilience spending and EV charging infrastructure.
SGB-SMIT: Specializes in custom liquid-filled transformers for renewable energy and utility projects. It has manufacturing in Europe, the U.S., and Asia.
CHINT Group: Competes on price and local manufacturing in China and emerging Asia. It is expanding into Africa and the Middle East.
Mitsubishi Electric: Provides high-efficiency dry-type and gas-insulated transformers for rail and industrial applications. It focuses on Japan and Southeast Asia.
GE Vernova: Combines transformer manufacturing with grid software and automation. It targets utility modernization programs.
Hammond Power Solutions: Supplies dry-type transformers to commercial and industrial buildings, with a strong North American distribution network.
Olsun Electrics Corporation: Builds custom transformers and reactors for industrial OEMs and specialty applications.
Strategic Milestones & Recent Developments in Medium Voltage Transformer Market
Date
Company
Event Type
Impact
2023
Hitachi Energy
Capacity expansion
Announced $1.5 billion investment in transformer manufacturing across Europe and Asia
2024
Siemens
Product launch
Released digital twin-enabled medium voltage transformers for grid operators
2024
Schneider Electric
Partnership
Collaborated with data center operators on dry-type transformer deployments
2024
Eaton
Capacity expansion
Added pad-mounted transformer lines in North America to cut lead times
2025
CHINT Group
Market expansion
Opened distribution transformer assembly in the Middle East
2025
SGB-SMIT
M&A
Acquired a European winding component supplier to secure core materials
2023: Hitachi Energy committed $1.5 billion to expand transformer production, responding to utility backlogs and renewable interconnection delays.
2024: Siemens launched digital twin-enabled medium voltage transformers, integrating temperature and partial discharge sensors for predictive maintenance.
2024: Schneider Electric partnered with data center operators to deploy dry-type transformers that meet indoor fire safety codes and reduce cooling loads.
2024: Eaton expanded pad-mounted transformer capacity in North America, targeting 30% shorter lead times by 2026.
2025: CHINT Group opened a transformer assembly plant in the Middle East to serve GCC grid and solar projects.
2025: SGB-SMIT acquired a European winding component supplier, verticalizing production of cores and windings.
Regional Market Analysis & Growth Corridors for Medium Voltage Transformer Market
Region
Projected CAGR (%)
Base Year Valuation (2025)
Primary Catalyst
Regulatory Stringency
Asia-Pacific
7.8%
$6.47 billion
Grid expansion, renewables, industrial demand
Medium to High
North America
6.2%
$3.16 billion
Aging grid replacement, data centers, EV charging
High
Europe
6.0%
$2.87 billion
Renewable integration, efficiency standards
High
Middle East & Africa
6.5%
$1.01 billion
Solar farms, desalination, urban growth
Medium
South America
5.8%
$0.86 billion
Hydropower upgrades, mining electrification
Medium
Asia-Pacific is the fastest-growing region, with 7.8% CAGR, driven by China's $150 billion annual grid investment and India's distribution upgrade program. The region also hosts the largest manufacturing base for liquid-filled and dry-type transformers, giving it cost advantages. North America remains the most mature market, with replacement demand for transformers older than 35 years and strong data center construction. Europe follows with strict Ecodesign efficiency rules that favor high-efficiency dry-type and amorphous core units.
Fastest-Growing vs. Mature Markets
Fastest-growing: Asia-Pacific and Middle East & Africa. GCC solar projects and ASEAN industrial parks are adding medium voltage capacity at double the global average.
Most mature: North America and Europe. Growth depends on replacement cycles and grid hardening rather than new electrification.
South America: Brazil and Argentina show moderate growth from hydropower modernization and mining electrification, but currency volatility limits investment.
Regulatory hotspots: The EU and U.S. have the most stringent efficiency and environmental rules, raising compliance costs but creating premium opportunities.
Technology Innovation & R&D Trajectory in Medium Voltage Transformer Market
Three emerging technologies are reshaping medium voltage transformer design:
Amorphous core transformers: Reduce no-load losses by 60–70% compared with conventional silicon steel cores. Adoption is accelerating in India and Europe, where efficiency standards penalize high-loss units. Commercial scale is expected by 2026–2027.
High-temperature superconducting (HTS) transformers: Offer compact footprints and high overload capacity for urban substations. Prototypes are under test in Japan and Germany, but cost remains 5–10x conventional units. Commercial adoption is unlikely before 2030.
Digital monitoring and IoT sensors: Enable condition-based maintenance and dynamic loading. Siemens, Hitachi ABB Power Grids, and Schneider Electric are embedding sensors in dry-type and liquid-filled units. This reinforces incumbent business models by adding service revenue.
Patent filings for transformer monitoring and core materials grew 12% annually from 2020 to 2024. R&D investment among top vendors ranges from 2.5% to 3.5% of transformer revenue. The Dry-Type Transformer Market is the primary beneficiary of digital monitoring because sensors can be integrated without oil-immersion constraints. However, solid-state transformers remain a long-term substitute rather than a near-term threat.
Customer Segmentation & Buying Behavior in Medium Voltage Transformer Market
The end-user base splits into four main segments:
Utilities: Purchase 60% of medium voltage transformers, prioritizing reliability, efficiency, and compliance with IEEE and IEC standards. Procurement is often through multi-year framework agreements.
Industrial: Represent 22% of demand. The Industrial Transformer Market is driven by manufacturing plants, mining, and oil and gas. Buyers focus on total cost of ownership, overload capacity, and service response time.
Commercial: Account for 12% of demand. The Commercial Transformer Market includes data centers, hospitals, universities, and office towers. These buyers prefer dry-type transformers for indoor safety and low maintenance.
Residential: Make up 6% of demand, mainly through pad-mounted and pole-mounted distribution transformers purchased by utilities for neighborhood networks.
Decision criteria have shifted toward lead time and lifecycle cost. In 2024, 45% of utility buyers ranked delivery speed above initial price, up from 30% in 2020. Price elasticity is low for utility and industrial buyers because transformers are critical components, but high for commercial projects with alternative designs. Procurement channels include direct OEM sales, EPC contractors, electrical distributors, and digital marketplaces. Digital purchasing now accounts for 15–20% of commercial dry-type transformer orders, as buyers use online configurators and request e-quotes.
Medium Voltage Transformer Market Segmentation
1. Product Type
1.1. Liquid-Filled Transformer
1.2. Dry-Type Transformer
2. Mounting
2.1. Pad-Mounted Transformer
2.2. Pole-Mounted Transformer
3. Application
3.1. Residential
3.2. Commercial
3.3. Industrial
Medium Voltage Transformer Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Medium Voltage Transformer Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.97% from 2020-2034
Segmentation
By Product Type
Liquid-Filled Transformer
Dry-Type Transformer
By Mounting
Pad-Mounted Transformer
Pole-Mounted Transformer
By Application
Residential
Commercial
Industrial
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Liquid-Filled Transformer
5.1.2. Dry-Type Transformer
5.2. Market Analysis, Insights and Forecast - by Mounting
5.2.1. Pad-Mounted Transformer
5.2.2. Pole-Mounted Transformer
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Residential
5.3.2. Commercial
5.3.3. Industrial
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Liquid-Filled Transformer
6.1.2. Dry-Type Transformer
6.2. Market Analysis, Insights and Forecast - by Mounting
6.2.1. Pad-Mounted Transformer
6.2.2. Pole-Mounted Transformer
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Residential
6.3.2. Commercial
6.3.3. Industrial
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Liquid-Filled Transformer
7.1.2. Dry-Type Transformer
7.2. Market Analysis, Insights and Forecast - by Mounting
7.2.1. Pad-Mounted Transformer
7.2.2. Pole-Mounted Transformer
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Residential
7.3.2. Commercial
7.3.3. Industrial
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Liquid-Filled Transformer
8.1.2. Dry-Type Transformer
8.2. Market Analysis, Insights and Forecast - by Mounting
8.2.1. Pad-Mounted Transformer
8.2.2. Pole-Mounted Transformer
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Residential
8.3.2. Commercial
8.3.3. Industrial
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Liquid-Filled Transformer
9.1.2. Dry-Type Transformer
9.2. Market Analysis, Insights and Forecast - by Mounting
9.2.1. Pad-Mounted Transformer
9.2.2. Pole-Mounted Transformer
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Residential
9.3.2. Commercial
9.3.3. Industrial
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Liquid-Filled Transformer
10.1.2. Dry-Type Transformer
10.2. Market Analysis, Insights and Forecast - by Mounting
10.2.1. Pad-Mounted Transformer
10.2.2. Pole-Mounted Transformer
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Residential
10.3.2. Commercial
10.3.3. Industrial
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Chint
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. GE
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Efacec
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. TWB
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Hammond Power Solutions
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Jefferson Electric Transformers
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Mitsubishi Electric
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Siemens
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. MGM Transformer Company
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Weg. Eaton
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Olsun Electrics Corporation
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Crompton Greaves
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Hubbell
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Hitachi ABB Power Grids
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Schneider
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. SGB-SMIT
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Alce
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Medium Voltage Transformer Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Medium Voltage Transformer Market Revenue (billion), by Product Type 2026 & 2034
Figure 3: North America Medium Voltage Transformer Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Medium Voltage Transformer Market Revenue (billion), by Mounting 2026 & 2034
Figure 5: North America Medium Voltage Transformer Market Revenue Share (%), by Mounting 2026 & 2034
Figure 6: North America Medium Voltage Transformer Market Revenue (billion), by Application 2026 & 2034
Figure 7: North America Medium Voltage Transformer Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Medium Voltage Transformer Market Revenue (billion), by Country 2026 & 2034
Figure 9: North America Medium Voltage Transformer Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Medium Voltage Transformer Market Revenue (billion), by Product Type 2026 & 2034
Figure 11: South America Medium Voltage Transformer Market Revenue Share (%), by Product Type 2026 & 2034
Figure 12: South America Medium Voltage Transformer Market Revenue (billion), by Mounting 2026 & 2034
Figure 13: South America Medium Voltage Transformer Market Revenue Share (%), by Mounting 2026 & 2034
Figure 14: South America Medium Voltage Transformer Market Revenue (billion), by Application 2026 & 2034
Figure 15: South America Medium Voltage Transformer Market Revenue Share (%), by Application 2026 & 2034
Figure 16: South America Medium Voltage Transformer Market Revenue (billion), by Country 2026 & 2034
Figure 17: South America Medium Voltage Transformer Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Medium Voltage Transformer Market Revenue (billion), by Product Type 2026 & 2034
Figure 19: Europe Medium Voltage Transformer Market Revenue Share (%), by Product Type 2026 & 2034
Figure 20: Europe Medium Voltage Transformer Market Revenue (billion), by Mounting 2026 & 2034
Figure 21: Europe Medium Voltage Transformer Market Revenue Share (%), by Mounting 2026 & 2034
Figure 22: Europe Medium Voltage Transformer Market Revenue (billion), by Application 2026 & 2034
Figure 23: Europe Medium Voltage Transformer Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Europe Medium Voltage Transformer Market Revenue (billion), by Country 2026 & 2034
Figure 25: Europe Medium Voltage Transformer Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Medium Voltage Transformer Market Revenue (billion), by Product Type 2026 & 2034
Figure 27: Middle East & Africa Medium Voltage Transformer Market Revenue Share (%), by Product Type 2026 & 2034
Figure 28: Middle East & Africa Medium Voltage Transformer Market Revenue (billion), by Mounting 2026 & 2034
Figure 29: Middle East & Africa Medium Voltage Transformer Market Revenue Share (%), by Mounting 2026 & 2034
Figure 30: Middle East & Africa Medium Voltage Transformer Market Revenue (billion), by Application 2026 & 2034
Figure 31: Middle East & Africa Medium Voltage Transformer Market Revenue Share (%), by Application 2026 & 2034
Figure 32: Middle East & Africa Medium Voltage Transformer Market Revenue (billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Medium Voltage Transformer Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Medium Voltage Transformer Market Revenue (billion), by Product Type 2026 & 2034
Figure 35: Asia Pacific Medium Voltage Transformer Market Revenue Share (%), by Product Type 2026 & 2034
Figure 36: Asia Pacific Medium Voltage Transformer Market Revenue (billion), by Mounting 2026 & 2034
Figure 37: Asia Pacific Medium Voltage Transformer Market Revenue Share (%), by Mounting 2026 & 2034
Figure 38: Asia Pacific Medium Voltage Transformer Market Revenue (billion), by Application 2026 & 2034
Figure 39: Asia Pacific Medium Voltage Transformer Market Revenue Share (%), by Application 2026 & 2034
Figure 40: Asia Pacific Medium Voltage Transformer Market Revenue (billion), by Country 2026 & 2034
Figure 41: Asia Pacific Medium Voltage Transformer Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Medium Voltage Transformer Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 2: Medium Voltage Transformer Market Revenue billion Forecast, by Mounting 2020 & 2034
Table 3: Medium Voltage Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 4: Medium Voltage Transformer Market Revenue billion Forecast, by Region 2020 & 2034
Table 5: North America Medium Voltage Transformer Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 6: North America Medium Voltage Transformer Market Revenue billion Forecast, by Mounting 2020 & 2034
Table 7: North America Medium Voltage Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 8: North America Medium Voltage Transformer Market Revenue billion Forecast, by Country 2020 & 2034
Table 9: United States Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 10: Canada Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: South America Medium Voltage Transformer Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 13: South America Medium Voltage Transformer Market Revenue billion Forecast, by Mounting 2020 & 2034
Table 14: South America Medium Voltage Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 15: South America Medium Voltage Transformer Market Revenue billion Forecast, by Country 2020 & 2034
Table 16: Brazil Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: Argentina Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Rest of South America Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 19: Europe Medium Voltage Transformer Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 20: Europe Medium Voltage Transformer Market Revenue billion Forecast, by Mounting 2020 & 2034
Table 21: Europe Medium Voltage Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 22: Europe Medium Voltage Transformer Market Revenue billion Forecast, by Country 2020 & 2034
Table 23: United Kingdom Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Germany Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 25: France Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 26: Italy Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Spain Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Russia Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: Benelux Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: Nordics Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Europe Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Medium Voltage Transformer Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 33: Middle East & Africa Medium Voltage Transformer Market Revenue billion Forecast, by Mounting 2020 & 2034
Table 34: Middle East & Africa Medium Voltage Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 35: Middle East & Africa Medium Voltage Transformer Market Revenue billion Forecast, by Country 2020 & 2034
Table 36: Turkey Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: Israel Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: GCC Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: North Africa Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: South Africa Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 41: Rest of Middle East & Africa Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: Asia Pacific Medium Voltage Transformer Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 43: Asia Pacific Medium Voltage Transformer Market Revenue billion Forecast, by Mounting 2020 & 2034
Table 44: Asia Pacific Medium Voltage Transformer Market Revenue billion Forecast, by Application 2020 & 2034
Table 45: Asia Pacific Medium Voltage Transformer Market Revenue billion Forecast, by Country 2020 & 2034
Table 46: China Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 47: India Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 48: Japan Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 49: South Korea Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 50: ASEAN Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 51: Oceania Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Medium Voltage Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of total effort, while secondary research contributes 20–30%. We interview medium voltage transformer OEMs, component suppliers, utility asset managers, and EPC contractors across North America, Europe, Asia-Pacific, and LAMEA.
Target company types include liquid-filled and dry-type transformer OEMs for utility distribution networks; grain-oriented electrical steel and copper winding suppliers; transformer core lamination and tank fabrication specialists; pad-mounted and pole-mounted enclosure fabricators; and utility EPC firms and grid integration contractors.
We conduct structured interviews with Utility Asset Management Directors, Substation Engineering Managers, Power Distribution Procurement Leads, and Regulatory Compliance Officers for Grid Infrastructure. These stakeholders provide unit-level pricing, lead times, and procurement criteria.
We explicitly exclude market research websites from citation to avoid circular sourcing. All references are primary regulatory documents, utility integrated resource plans, technical standards, and company annual reports.
Benchmarking covers medium voltage transformer price per kVA, efficiency classes, lead times, and regional capacity additions. Every report is updated to the date of purchase, incorporating the latest quarterly utility filings and trade data.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously. The top-down model uses global electricity distribution capex and transformer replacement rates. The bottom-up model aggregates utility-level procurement and industrial project pipelines.
Quantitative metrics in the bottom-up calculation include annual MW of new distribution capacity added; number of pad-mounted transformer units installed per utility territory; average age of installed distribution transformers (years); copper and grain-oriented electrical steel price indices; and utility capex per capita by region.
Segment splits by product type, mounting, and application are validated against OEM order books and import-export records. Multi-level data triangulation reconciles discrepancies between utility capex, vendor revenue, and component shipment data.
The model produces a base-year valuation of $14.37 billion for 2025 and a forecast valuation of $24.6 billion by 2033 at a 6.97% CAGR.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%. All primary interview transcripts are coded and cross-checked against at least two independent secondary sources.
Data triangulation uses multi-level validation: utility procurement data, OEM shipment data, and component supplier order data are compared at regional and global levels. Outliers beyond ±5% are re-interviewed or excluded.
Quality checks include sanity testing of CAGR against historical transformer demand, price elasticity checks, and regulatory impact assessment. Final estimates are reviewed by a senior analyst panel before publication.
Frequently Asked Questions
1. How are technological innovations and R&D trends shaping the medium voltage transformer industry?
Manufacturers are investing in amorphous core materials, high-temperature superconducting windings, and integrated IoT sensors to cut no-load losses by 15–30% versus conventional silicon steel cores. Hitachi ABB Power Grids and Siemens have filed patents on digital twin and condition-monitoring systems for substation transformers. R&D spending among top vendors reached an estimated 2.5–3.5% of transformer segment revenue in 2024.
2. Which region is the fastest-growing for medium voltage transformers, and where are emerging opportunities?
Asia-Pacific is the fastest-growing region, projected at 7.8% CAGR through 2033, driven by China's $150 billion annual grid capex and India's distribution upgrade program. Middle East & Africa follows with 6.5% CAGR as GCC countries integrate solar farms and build data centers. Emerging opportunities include ASEAN industrial parks and South American renewable corridors.
3. What raw material sourcing and supply chain issues affect medium voltage transformer production?
Grain-oriented electrical steel and copper windings account for 50–60% of material costs, and supply remains concentrated among a few global mills. Price volatility in the Electrical Steel Market and copper markets pushed transformer lead times to 60–80 weeks in 2023–2024. Vendors are dual-sourcing cores and expanding local winding capacity to reduce logistics risk.
4. Who are the leading companies in the medium voltage transformer market, and how concentrated is the competitive landscape?
Hitachi ABB Power Grids, Siemens, Schneider Electric, Eaton, and SGB-SMIT lead the global market, with the top five holding an estimated 35–40% revenue share. CHINT Group and Mitsubishi Electric are strong challengers in Asia-Pacific. The market remains fragmented among regional OEMs, with niche players competing on dry-type and pad-mounted designs.
5. What disruptive technologies or substitutes could affect medium voltage transformer demand?
Solid-state transformers and power electronics-based voltage regulators may replace some conventional units in data centers and EV charging hubs after 2028–2030. Distributed energy resources and microgrid controllers can reduce reliance on traditional pad-mounted transformers in new commercial campuses. However, cost and reliability gaps keep liquid-filled and dry-type transformers dominant through the forecast.
6. How does the regulatory environment influence the medium voltage transformer market?
Efficiency standards such as DOE 2016 in the U.S. and EU Ecodesign Lot 2 require lower no-load losses, pushing demand for amorphous core and high-efficiency dry-type units. FERC and European regulators also mandate grid resilience reporting that accelerates replacement cycles. Compliance costs add 5–10% to unit prices but support premium segments.