Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Industrial Controller Transformer Market: 6.6% CAGR to 2033
Industrial Controller Transformer Market
Industrial Controller Transformer Market: 6.6% CAGR to 2033
Industrial Controller Transformer Market by Phase Type (Single Phase, Three Phase), by Power Rating (25-500 VA, 500-1, 000 VA, 1, 000-1, 500 VA, Above 1, 500 VA), by Industry Vertical (Power Generation, Oil Gas, Chemical, Metal Mining (Iron, Steel, Aluminum), by Others (Paper Pulp, Cement, Glass, Water Wastewater Industries), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
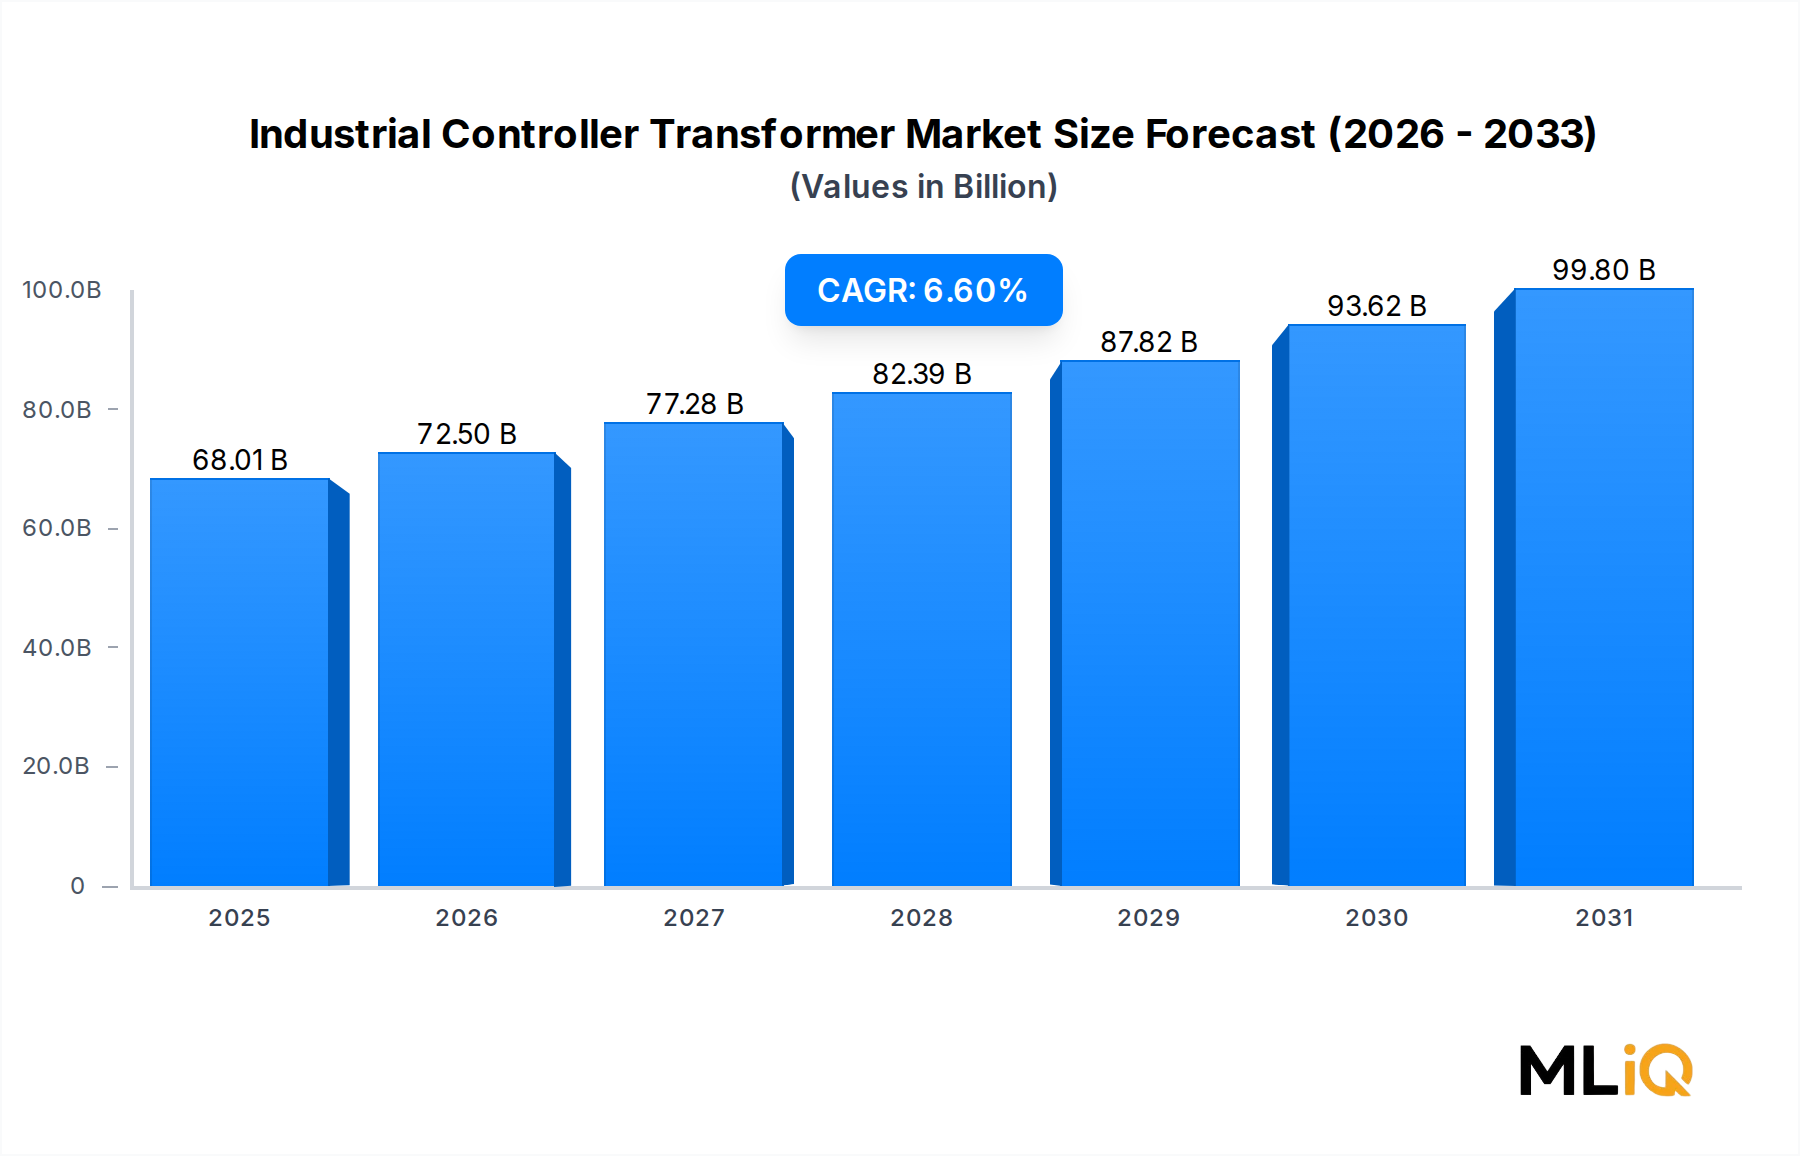
The Industrial Controller Transformer Market closed 2024 at USD 63.8 billion and is projected to reach USD 113.4 billion by 2033, a 6.6% CAGR that runs roughly 2.4 percentage points above global GDP growth. Approximately USD 14.2 billion of that base sits in the Industrial Control Transformer Market — the low-voltage class that steps line voltage down to 120 V, 24 V, or 12 V for PLC racks, contactors, relays, and instrumentation loops.
Industrial Controller Transformer Market Size (In Billion)
100.0B
80.0B
60.0B
40.0B
20.0B
0
68.01 B
2025
72.50 B
2026
77.28 B
2027
82.39 B
2028
87.82 B
2029
93.62 B
2030
99.80 B
2031
Three structural forces define the trajectory:
Fleet replacement: The North American installed base averages 38 years of service against a 25–30 year design life; the European average is 41 years.
Regulatory tightening: IEC 61558-2-2, UL 5085-1/2, and IEEE C57.12.01 now govern impedance, temperature rise, and no-load loss on most new specifications.
Process electrification: Industrial heat pump and electric furnace retrofits added an estimated 4.1 GW of new low-voltage control demand in 2024.
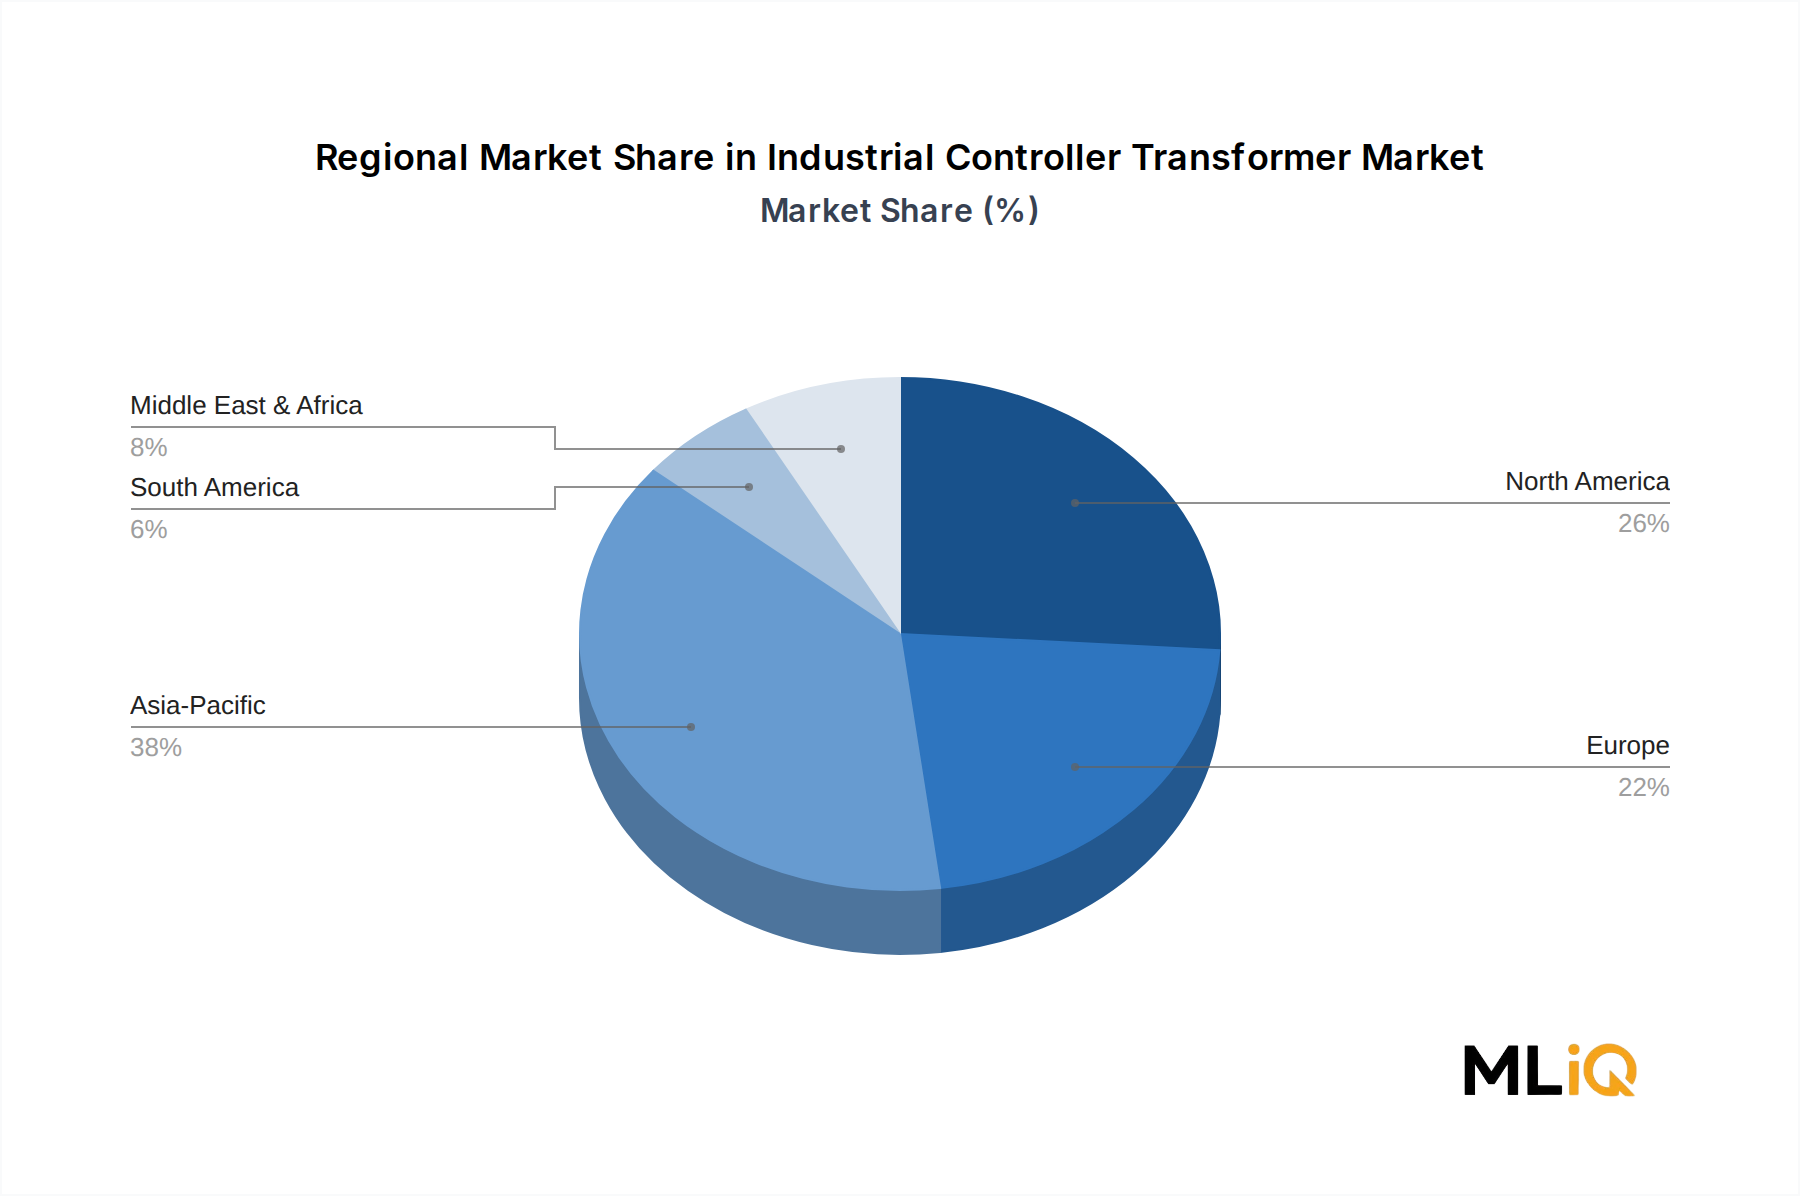
Geography is decisive. Asia-Pacific holds 38.1% of revenue, led by China at USD 12.6 billion and India at USD 4.9 billion. North America holds 26.1%, Europe 22.4%, and LAMEA 13.4%. The Industrial Transformer Market overall remains moderately concentrated: the top ten vendors capture an estimated 46% of global revenue, with a long tail of regional panel builders serving local projects.
Margin structure splits by product class. Standard dry-type control units run 22–28% gross margin, while cast-resin, K-rated, and low-loss variants sustain 31–36%.
Strategic takeaway: growth is not volume-led. Unit shipments advance at roughly 3.9% annually; the balance of the 6.6% CAGR comes from mix shift toward three-phase, higher-VA, and low-loss designs. Vendors that win specification at the panel-design stage capture a 12–15 year replacement annuity.
Segment Deep-Dive: Three Phase Segment Dominance in Industrial Controller Transformer Market
Segment Analysis Matrix
Segment
Revenue Share (%)
CAGR 2025–2033 (%)
Key Demand Driver
Three Phase (Phase Type)
64.5
7.1
Motor control centers, multi-axis drives, metals and mining
The Three Phase Transformer Market accounted for USD 41.2 billion of 2024 revenue, and its 7.1% CAGR sits 1.5 points above the single-phase class. Demand originates where three-phase motors, VFD banks, and multi-axis servo systems concentrate: metals rolling lines, cement kilns, refining process units, and water treatment pumping stations.
Metals and mining consumes an estimated 21% of three-phase control transformer output, driven by mill drives rated 250–5,000 hp.
Power generation retrofit and balance-of-plant work absorbs another 17%, concentrated in switchgear and auxiliary control cabinets.
Three-phase units carry 2.3× the average selling price of single-phase equivalents, which is why the value share gap (64.5% vs. 35.5%) exceeds the unit share gap (41% vs. 59%).
Single Phase: Stable, Instrumentation-Led
The Single Phase Transformer Market remains the volume backbone at roughly 14.6 million units shipped annually. Growth is slower at 5.6% because the dominant applications — panel instrumentation, control relays, and safety interlock circuits — are mature and highly standardized. Pricing is competitive: encapsulated 100 VA units trade in a narrow USD 28–46 band, and regional assemblers compress margins below 18%.
Sub-Segment Dynamics and Margin Pressure
The Above 1,500 VA tier is the fastest-growing power-rating band at 7.4% CAGR, reflecting larger MCC lineups and higher control-circuit burdens from networked drives. The 25–500 VA tier grows at only 4.9%, pressured by integrated switch-mode power supplies displacing small magnetic transformers in new panel designs.
Copper and GOES input volatility compresses gross margin by 150–250 basis points in any quarter where metal indices move more than 8%.
Custom windings and agency certifications raise switching costs; once a unit is qualified into a Power Generation Transformer Market panel design, replacement cycles run 12–15 years.
The three-phase segment is where differentiation is sustainable: low-loss cores, K-factor ratings, and integrated thermal telemetry defend price.
Aging installed fleet (38-year North America average) forces replacement
High
Short term
Driver
IEC 61558-2-2 and UL 5085 efficiency enforcement
High
Short term
Driver
Process electrification and heat pump retrofits (4.1 GW added 2024)
High
Long term
Driver
Industrial reshoring and nearshore plant construction
Medium
Long term
Restraint
Copper and GOES price volatility
High
Short term
Restraint
Switch-mode power supply substitution in low-VA panel designs
Medium
Long term
Restraint
Skilled winding labor shortage in North America and Europe
Medium
Short term
Catalysts, Quantified
The dominant driver is replacement economics. With the European fleet averaging 41 years and North American units at 38 years, an estimated 2.8 million control transformers globally are operating beyond design life. Utilities and heavy process operators budgeted USD 9.3 billion in 2024 for low-voltage control replacement alone.
Regulation compounds the effect. IEC 61558-2-2 and UL 5085-1/2 require documented temperature rise and impedance, effectively disqualifying uncertified imports from price-led panel builds. The Oil and Gas Transformer Market adds a second regulatory layer: ATEX and IECEx zone classification forces encapsulated or cast-resin construction in upstream and midstream installations.
Grid-side investment is the third catalyst. Smart Grid Transformer Market spending, including distribution automation and edge monitoring, rose to USD 21.7 billion in 2024 and pulls control-power demand into new substation and feeder automation cabinets.
Bottlenecks, Quantified
Restraints are cost- and capacity-driven rather than demand-driven.
Metal input volatility: a 10% move in GOES prices shifts unit cost by 2.8–3.4%.
Substitution: integrated switch-mode supplies now compete for 25–500 VA duty, capping that band at 4.9% CAGR.
Labor: trained coil winders are scarce; vacancy rates in North American transformer assembly run near 11%.
Net effect: volume growth of 3.9% is paired with mix-driven value growth of 6.6%.
EcoStruxure panel ecosystem and specification pull
Panel builders, utilities
Leader
ABB
Broad transformer portfolio and global service
Utilities, heavy industry
Leader
Eaton
Electrical distribution bundle and channel reach
Contractors, industrials
Leader
Hubbell
K-rated and harmonic-mitigating designs
Data-adjacent industrial loads
Challenger
Rockwell Automation
Control architecture certification pull-through
OEM machine builders
Leader
GE
Utility and balance-of-plant channel
Power generation, grid
Challenger
Hammond Power Solutions
Dry-type specialization and lead time
Panel builders, OEMs
Challenger
Emerson
Process control integration and instrumentation
Oil, gas, chemical
Challenger
Boardman Transformers
Custom and low-volume windings
Regional panel shops
Niche
Siemens: integrates control transformers into broader automation and digital-twin selection tools, which shortens specification cycles and defends price in process industries.
Schneider Electric: leverages EcoStruxure panel design standards to pull transformer demand through integrator channels, with strong presence in Europe and India.
ABB: holds the deepest installed base in utility and heavy-industry balance-of-plant applications, supported by a global service network.
Eaton: bundles control transformers with switchgear, breakers, and enclosures, giving it channel leverage across North American contractors.
Hubbell: differentiates on K-rated and harmonic-tolerant units as non-linear loads from VFDs stress legacy windings.
Rockwell Automation: certification alignment with its control platforms makes its specified transformers effectively pre-qualified for OEM machine builders.
GE: maintains utility and power generation relationships that create pull-through demand for auxiliary and control-power units.
Hammond Power Solutions: pure-play dry-type focus with competitive lead times of 14–18 weeks and strong panel-builder loyalty.
Emerson: ties transformer specification to process control and instrumentation packages in oil, gas, and chemical plants.
Boardman Transformers: custom and low-volume windings serve niche industrial and legacy replacement needs.
Top ten share is estimated at 46%; the remainder fragments across hundreds of regional assemblers.
Strategic Milestones & Recent Developments in Industrial Controller Transformer Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2024 Q1
ABB
Launch
Low-loss dry-type control line targeting reduced no-load losses
2024 Q2
Schneider Electric
Partnership
Integrator specification program for panel design standardization
2024 Q3
Hammond Power Solutions
Capacity Expansion
Added dry-type winding capacity in North America
2024 Q4
Siemens
Portfolio Integration
Control transformer SKUs embedded in digital selection tooling
2025 Q1
Eaton
M&A
Acquired regional assembly assets to shorten lead times
2025 Q2
Hubbell
Launch
K-rated, harmonic-mitigating units for non-linear industrial loads
2024 Q1 — ABB: shifted its dry-type lineup toward lower no-load loss cores, aligning with IEC 61558-2-2 efficiency thresholds and defending premium pricing in Europe.
2024 Q2 — Schneider Electric: formalized a specification partnership with panel integrators, moving transformer selection earlier in the design cycle to capture multi-year replacement annuity.
2024 Q3 — Hammond Power Solutions: added North American winding capacity to cut lead times toward 14–18 weeks, reversing the 26–34 week backlog peak seen in 2022.
2024 Q4 — Siemens: embedded control transformer selection into digital engineering tooling, reducing specification effort for OEM machine builders.
2025 Q1 — Eaton: acquired regional assembly and panel assets, targeting nearshore production as buyers demand domestic options.
2025 Q2 — Hubbell: launched harmonic-mitigating designs as VFD penetration in industrial panels continues to rise.
Consolidation remains modest; the strategic theme is capacity localization rather than scale acquisition.
Retrofit efficiency mandates and industrial heat electrification
High
Middle East & Africa
8.4
5.1
Desalination, refining, metals expansion in GCC
Medium
South America
6.9
3.5
Pulp, steel, and mining projects in Brazil and Chile
Medium
Fastest-Growing Corridors
Middle East and Africa leads at 8.4% CAGR, anchored in GCC desalination and refining capex plus North African industrial zones.
India is the standout single market at 8.9% CAGR, supported by PLI-linked electronics and auto component plants adding motor control centers.
ASEAN follows at 7.8%, driven by semiconductor and battery plant construction in Vietnam, Malaysia, and Thailand.
Most Mature Markets
Western Europe grows at 5.4%, with demand almost entirely replacement-led. Germany and France together hold 52% of regional revenue.
North America grows at 5.9%; the United States alone accounts for USD 12.8 billion of the regional base, with Canada at USD 2.4 billion and Mexico at USD 1.4 billion.
Mature markets compete on efficiency and documentation depth, not price. Certification and arc-flash coordination studies are standard deliverables.
Strategic implication: volume growth is concentrated in Asia-Pacific and MEA, while margin growth concentrates in North America and Europe where specification control and low-loss premiums are enforceable.
Supply Chain & Raw Material Dynamics: Industrial Controller Transformer Market
Input Cost Structure and Price Direction
Input
Share of BOM (%)
2024 Price Direction
Supply Risk
Grain-oriented electrical steel (GOES)
28–34
Stable to slightly down
Medium to High
Copper winding wire
22–27
Up
Medium
Insulation and varnish systems
9–12
Stable
Low
Enclosures and mounting hardware
12–16
Stable
Low
Core lamination and assembly labor
15–20
Up
Medium
Upstream Dependencies
The Electrical Steel Market is the critical upstream link. High-permeability GOES supply has consolidated among a small group of producers — Nippon Steel, POSCO, Thyssenkrupp, and JFE — and structural shortages flare when utility-scale transformer demand spikes. The Transformer Core Materials Market, covering laminations, amorphous ribbon, and wound cores, adds a second dependency layer; amorphous core supply remains concentrated among a handful of qualified mills and carries a 25–40% price premium over conventional GOES.
Sourcing Risk and Historical Disruption
The 2021–2023 period demonstrated the fragility of the chain. GOES index prices climbed from roughly USD 1,150 per metric ton in early 2022 to above USD 1,480 by mid-2023 before easing to about USD 1,390. Copper averaged USD 9,100 per metric ton across 2024. Lead times for cast-resin control transformers peaked at 26–34 weeks against a pre-2020 norm of 10–14 weeks.
Dual sourcing of cores and laminations is now standard practice among the top ten vendors.
Buffer inventory of 90–120 days on critical windings was adopted by several large industrials during 2022–2023.
Vertical integration into winding and lamination is rising in India and Southeast Asia to reduce import dependency.
Asia-Pacific supplies an estimated 61% of globally traded control transformers by unit volume. China remains the largest single exporter, though its share of North American imports fell from roughly 44% in 2018 to about 29% by 2024 as duties and dual-sourcing reshaped flows.
Tariff and Non-Tariff Barriers
United States: Section 301 tariffs on Chinese electrical equipment raised landed cost by 10–25%, accelerating shifts to Mexico and Vietnam assembly.
European Union: low-voltage directive compliance and CE documentation act as effective non-tariff barriers for uncertified imports.
India: phased manufacturing programs and BIS certification requirements pushed local content in control transformers above 70% for utility-linked projects.
Middle East: GCC technical regulations and Saudi content thresholds influence award decisions on refinery and desalination packages.
Net effect: tariffs have redirected trade rather than reduced it. Nearshoring added an estimated USD 1.1 billion of North American assembly value between 2019 and 2024, while Chinese exporters shifted volume toward ASEAN, Africa, and Latin America.
Table 58: Rest of Asia Pacific Industrial Controller Transformer Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Research split: 70–80% primary research, 20–30% secondary research, weighted toward primary for segment-level and regional granularity.
Primary interviews conducted with company types across the control-power value chain: dry-type control transformer OEMs (25 VA–1,500 VA), cast-resin and encapsulated transformer manufacturers, grain-oriented electrical steel and core lamination suppliers, industrial EPC and electrical panel integrators, and OEM machine builders embedding control transformers into equipment.
Stakeholder interview panel: Transformer Product Line Managers, Electrical Design & Standards Engineers (IEC 61558 / UL 5085 compliance), Plant Maintenance & Reliability Managers, and Industrial Procurement Directors for electrical equipment.
Geographic interview distribution: Asia-Pacific 34%, North America 24%, Europe 22%, Middle East & Africa 11%, South America 9%.
Interviews target specification behavior, qualification timelines, pricing bands, and replacement-cycle assumptions rather than top-line revenue opinions alone.
No market research aggregator websites are used as source inputs.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously and reconciled through multi-level data triangulation.
Bottom-up quantitative anchors: installed base of motor control centers per industrial site by region; annual replacement rate of control transformers against an average 12–15 year service life; number of industrial panel builds per year by country; and average VA rating per control transformer shipped.
Top-down anchors: regional industrial capex envelopes, utility distribution automation spend, and electrical equipment import/export values.
Segment splits (Phase Type, Power Rating, Industry Vertical) are cross-checked against vendor shipment disclosures and channel inventory data.
Price and margin modeling incorporates GOES and copper index series from 2019 to 2025 to separate volume growth from mix and price effects.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90% for all published figures and forecasts.
Multi-level triangulation: primary interview ranges are tested against secondary shipment data, trade statistics, and vendor financial disclosures before a figure is published.
Outlier screening removes responses deviating more than two standard deviations from segment medians.
Every report is updated to the date of purchase, with revision logs maintained for segment shares, regional splits, and input-cost assumptions.
Forecast ranges are published where primary respondent dispersion exceeds 15%, rather than presenting false point precision.
Frequently Asked Questions
1. How are raw material supply chains affecting industrial controller transformer pricing?
Grain-oriented electrical steel (GOES) represents 28–34% of a dry-type control transformer bill of materials, and its index price moved from roughly $1,150 per metric ton in early 2022 to above $1,480 per metric ton by mid-2023 before settling near $1,390. Copper winding wire adds another 22–27% of cost, with LME cash prices averaging $9,100 per metric ton across 2024. Vendors with multi-year GOES contracts through Nippon Steel and POSCO have held gross margins 4–6 points above spot buyers.
2. What are the primary growth drivers pushing demand for control transformers in heavy industry?
Replacement of transformers commissioned between 1975 and 1995 is the single largest demand pool, with the North American installed fleet averaging 38 years of age against a 25–30 year design life. Electrification of process heat added an estimated 4.1 GW of new low-voltage control load in 2024 alone. Enforcement of IEC 61558-2-2 and UL 5085 efficiency and impedance rules forces specification upgrades rather than like-for-like swaps.
3. Which technological innovations are shaping transformer design and R&D priorities?
Manufacturers are shifting toward amorphous-metal cores and cast-resin encapsulation to cut no-load losses by 30–45% versus conventional laminated steel units. Integrated thermal sensing and Modbus or IO-Link telemetry now ship on roughly 12% of three-phase control units, enabling predictive maintenance. K-rated and harmonic-mitigating designs are expanding because non-linear loads from VFDs and rectifiers push winding temperature rise beyond Class F limits in legacy units.
4. Why are barriers to entry low for basic units but high at the premium end?
Basic single-phase encapsulated transformers can be assembled with commodity cores and standard bobbins, so regional panel shops enter at low capital cost and compete on price. The premium end requires UL 5085 and IEC 61558 certification, partial-discharge test benches, and multi-year qualification with firms such as Siemens, ABB, and Rockwell Automation. Field-failure liability, 10-year warranty expectations, and utility-grade documentation create a moat for the top ten vendors, who hold an estimated 46% of global revenue.
5. Which region is growing fastest and where are the emerging opportunities?
Asia-Pacific is the largest region at 38.1% of revenue, but the Middle East and Africa corridor is expanding fastest at 8.4% CAGR on the back of GCC desalination, refining, and metals projects. India is the standout single market, growing at 8.9% CAGR as PLI-linked electronics and auto component plants add motor control centers. South America follows at 6.9%, concentrated in Brazilian pulp, steel, and mining expansions.
6. How did the post-pandemic period reshape the transformer supply structure?
Lead times for cast-resin control transformers stretched to 26–34 weeks in 2022 from a pre-2020 norm of 10–14 weeks, prompting several large industrials to dual-source and hold 90–120 days of buffer stock. That restocking cycle unwound through 2024, pulling lead times back to 14–18 weeks. The durable structural shift is regionalization: North American and European buyers now require a domestic or nearshore assembly option for critical panel builds.