Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Well Casing and Cementing Market: 6.1% CAGR to 2033
Well Casing and Cementing Market
Well Casing and Cementing Market: 6.1% CAGR to 2033
Well Casing and Cementing Market by Operation Type (Remedial Cementing, Primary Cementing, Others), by Application (Onshore, Offshore), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
Key Insights & Executive Summary: Well Casing and Cementing Market
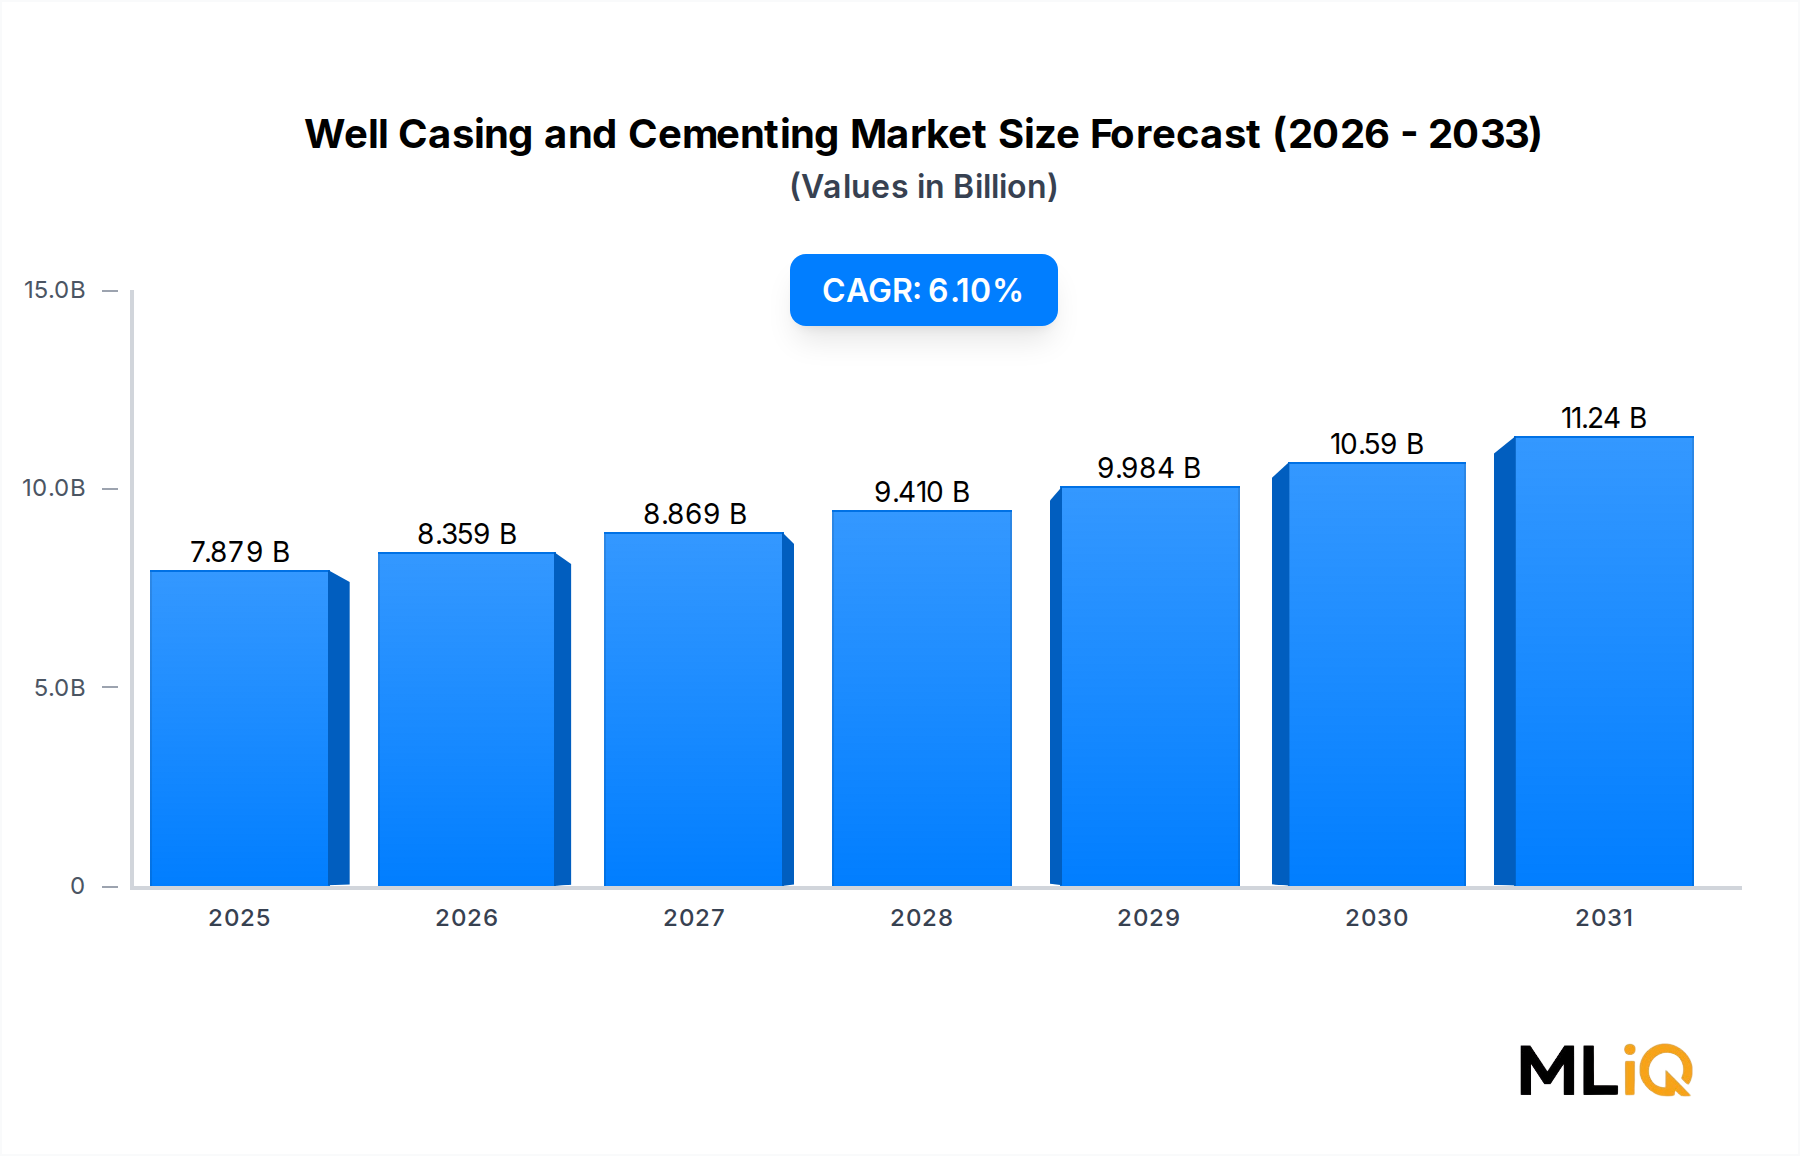
Well Casing and Cementing Market Size (In Billion)
15.0B
10.0B
5.0B
0
7.879 B
2025
8.359 B
2026
8.869 B
2027
9.410 B
2028
9.984 B
2029
10.59 B
2030
11.24 B
2031
Market at a Glance
The Well Casing and Cementing Market was valued at $7,425.75 million in 2024 and is forecast to reach $12,655.6 million by 2033, equivalent to a 6.1% CAGR. Spending is structurally non-discretionary: casing and cement form the primary barrier envelope of every well, so budgets are committed once a well is sanctioned.
Within the wider Global Oilfield Services Market, this segment is one of the most defensive categories. Operators can defer seismic acquisition or hydraulic fracturing, but they cannot defer barrier placement without breaching permit conditions.
Three forces dominate the forecast:
Deepwater and HPHT development. Deepwater wells consume 3-5x the casing tonnage and 2-3x the cement slurry volume of comparable onshore wells.
Well-integrity regulation. Rules from the Bureau of Safety and Environmental Enforcement (BSEE), NORSOK and ISO 16530 raise minimum barrier verification and zonal isolation requirements.
Plugging and abandonment backlog. Thousands of idle and orphaned wells in North America and Europe convert into remedial cementing demand.
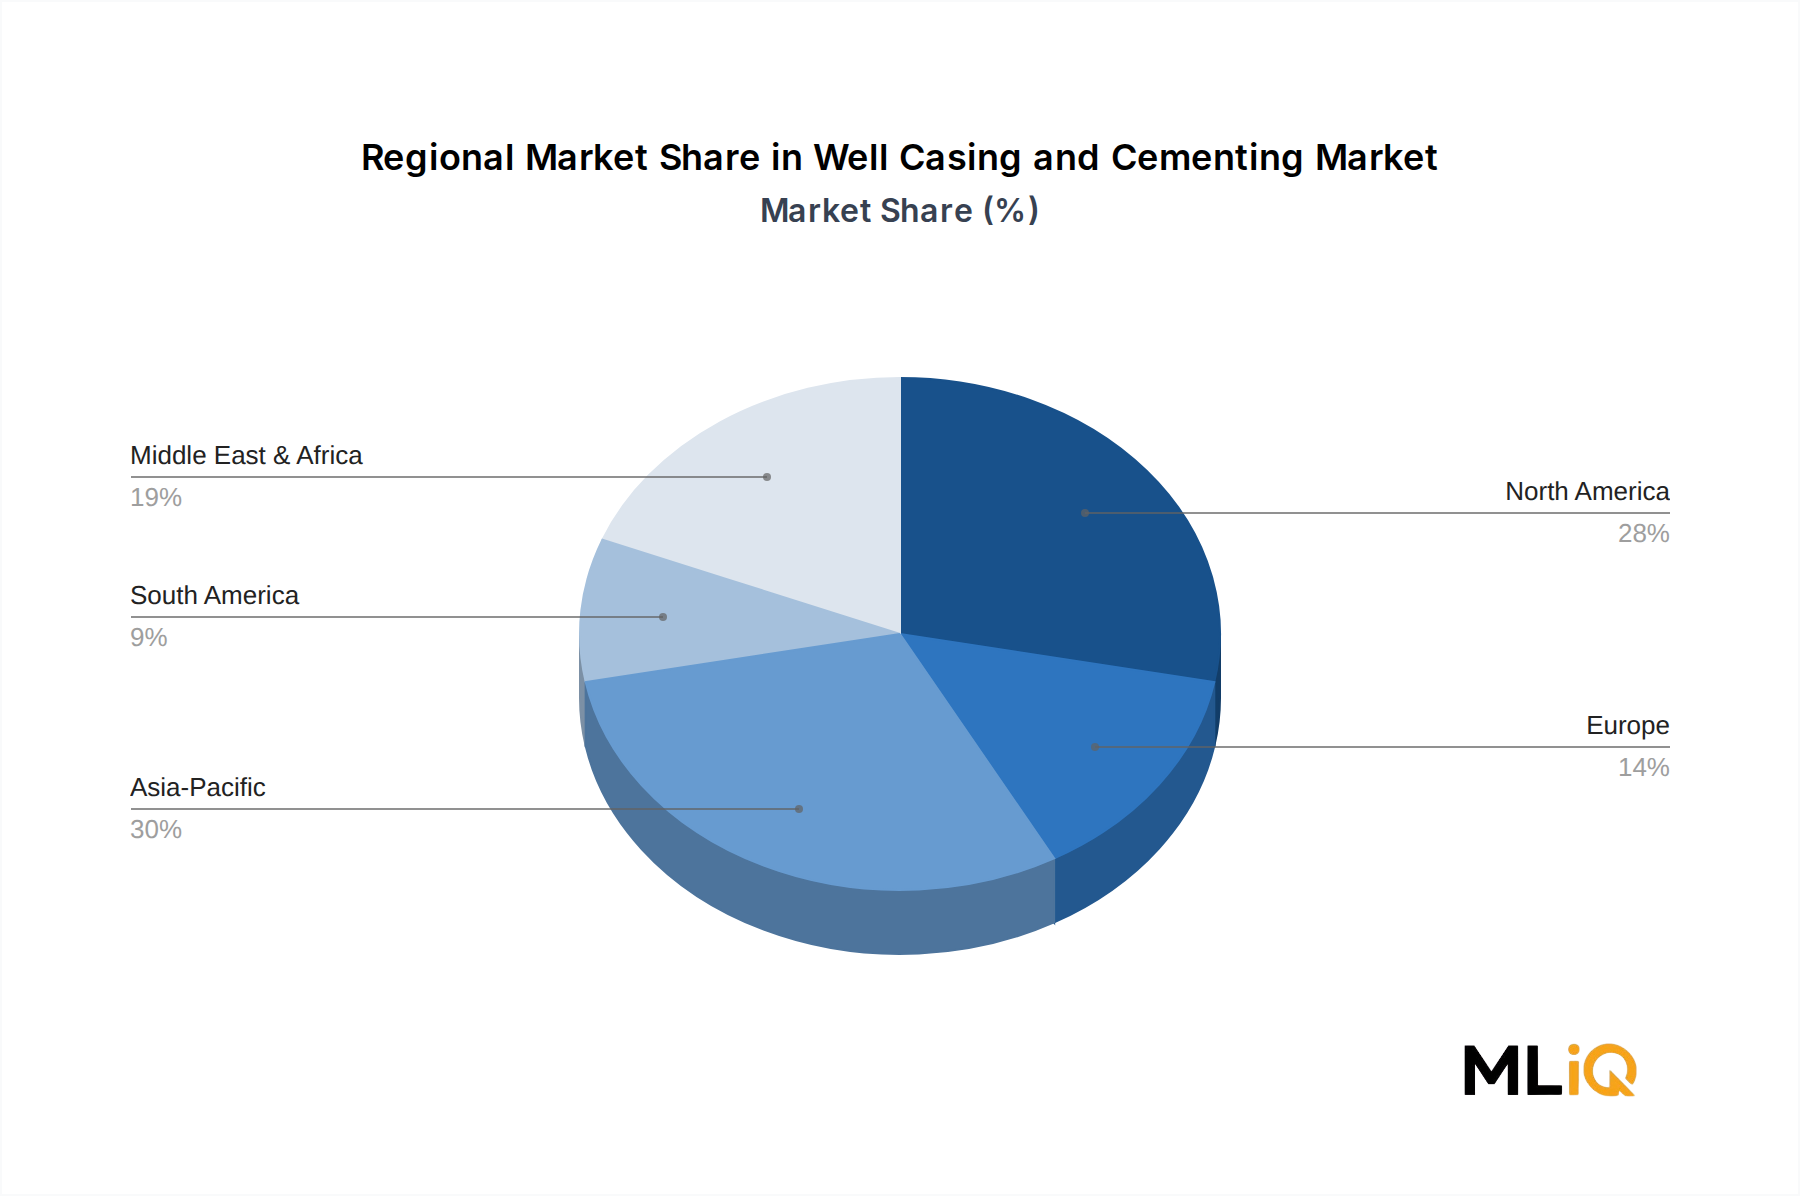
Demand Concentration
Region
2024 Share
Growth Profile
Asia-Pacific
~30%
Fastest growing, NOC-led
North America
~28%
Largest absolute spend, most cyclical
Middle East & Africa
~19%
Low-cost gas capacity expansion
Europe
~14%
Mature, integrity-driven
South America
~9%
Pre-salt and unconventional
Segment mix is stable. Primary cementing holds roughly 62% of revenue, remedial work about 24%, and specialty liner and surface systems the remainder. Offshore is expected to rise from ~34% to ~39% of total spend by 2033 as Brazil, Guyana, West Africa and the Eastern Mediterranean add deepwater capacity.
Bottom line: the market compounds at roughly 1.5x global upstream capital spending growth, with Asia-Pacific supplying volume growth and North America supplying the highest service intensity per well.
Segment Deep-Dive: Primary Cementing Dominance in Well Casing and Cementing Market
Segment Analysis Matrix
Segment
Projected CAGR (%)
Market Share (%)
Key Demand Driver
Primary Cementing
6.4
~62
New wellbore construction and mandated zonal isolation
Remedial Cementing
5.6
~24
Well-integrity repair, squeeze jobs, plugging and abandonment
Others (liner hangers, surface and specialty systems)
5.1
~14
Liner tie-backs and deepwater completion architecture
Primary Cementing: The Revenue Core
The Primary Cementing Services Market is the anchor of the category, generating an estimated $4.6 billion in 2024.
Revenue share of ~62% in 2024, easing to ~60% by 2033 as remedial work accelerates.
Service intensity rises with total depth, mud weight window and HPHT classification.
Job economics are driven by slurry design complexity rather than cement volume alone.
Remedial Cementing: The Stability Anchor
The Remedial Cementing Services Market is smaller but far less cyclical, because repair and abandonment work is driven by regulation rather than commodity price.
Forecast growth of 5.6% CAGR, with offshore abandonment carrying the highest revenue per job.
North Sea and Gulf of Mexico decommissioning programs support multi-year service backlogs.
Squeeze cementing for water and gas shut-off is a recurring revenue line in mature fields.
Casing and Tubulars
The Oil Well Casing Market sits upstream of the service spend. Casing typically represents 40-55% of combined casing and cementing cost per well, depending on depth and steel grade.
Grade mix shifts toward L80, P110 and corrosion-resistant alloys in sour service and HPHT wells.
Premium connections and torque monitoring add value per joint in deepwater.
Margin Pressure Points
API Class G cement and additive inputs are the largest variable cost line.
Certified cementing crew scarcity raises service cost per job.
Bundled integrated contracts compress standalone cementing margins by an estimated 200-400 basis points versus discrete tendering.
Primary Market Drivers & Growth Restraints in Well Casing and Cementing Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Rig count recovery and NOC development drilling programs
High
Short term
Driver
Well-integrity and zonal isolation rules (BSEE, NORSOK, ISO 16530)
High
Long term
Driver
Deepwater and HPHT project sanctions in Brazil, Guyana and West Africa
High
Medium term
Driver
Orphan well funding and idle well closure mandates
Medium
Long term
Driver
Geothermal and CCUS wells adopting oilfield casing and cementing practice
Medium
Long term
Restraint
Upstream capital discipline and shale cyclicality
High
Short term
Restraint
API Class G cement and additive price volatility
Medium
Short term
Restraint
Shortage of certified cementing crews and equipment
Medium
Medium term
Restraint
CO2 intensity scrutiny of Portland-based well cement
Low
Long term
Drilling activity remains the largest demand lever. Each additional onshore rig in a shale basin adds roughly 15-25 wells per year, each consuming a casing string and a primary cementing job. Offshore, a single deepwater development can absorb 50-150 casing strings, with cement volumes several times higher per interval.
Regulation is the more durable lever. ISO 16530 and parallel national rules require documented barrier verification across the well life cycle, converting well-integrity work from discretionary maintenance into a compliance obligation. The Oilfield Cementing Equipment Market benefits directly, because verification-grade evidence requires instrumented cementing units and downhole data acquisition.
Capital discipline caps near-term upside. When shale operators hold maintenance-level programs, service pricing flattens and cementing margins compress. Additive and cement price volatility transmits straight to project economics because slurry materials account for 30-45% of cementing job cost, while crew availability constrains how quickly contractors can respond to a demand spike.
Competitive Ecosystem & Key Vendor Profiles: Well Casing and Cementing Market
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
Halliburton Company
Integrated cementing, casing running and real-time job monitoring
IOCs, NOCs, independents
Leader
Schlumberger N.V.
Cementing chemistry and digital well-integrity platforms
Deepwater and HPHT operators
Leader
Baker Hughes
Cementing equipment, additives and well construction portfolio
Onshore and offshore operators
Leader
China Oilfield Services Limited
Domestic NOC coverage and offshore cementing vessels
CNOOC and regional NOCs
Leader (Asia-Pacific)
Nine Energy Service Inc.
Cementing and completion services for North American shale
US independents
Challenger
Calfrac Well Services Ltd.
Pressure pumping and cementing in North America and Argentina
Shale and tight-gas operators
Challenger
Magnum Cementing Services Ltd.
Regional cementing and blending capability
Western Canadian producers
Niche
Consolidated Oil Well Services LLC
Remedial cementing and well servicing
Mature onshore fields
Niche
Gulf Energy SAOC
Regional oilfield services and energy trading
Middle East E&P
Niche
The Onshore Oilfield Services Market remains the largest addressable pool by job count, while deepwater contracts carry the highest revenue per job.
Halliburton Company: the largest cementing service provider by revenue, with integrated casing running, additive manufacturing and automated job execution across all major basins.
Schlumberger N.V.: differentiates on cementing chemistry and digital well-integrity workflows that support barrier verification documentation for deepwater operators.
Baker Hughes: combines cementing equipment, additives and broader well construction hardware, giving it cross-sell reach into operator engineering teams.
China Oilfield Services Limited: dominant in Chinese offshore cementing through vessel-based capability and NOC relationships that limit foreign entry.
Nine Energy Service Inc.: North American challenger focused on shale cementing and completion services with faster mobilisation than integrated peers.
Calfrac Well Services Ltd.: leverages pressure pumping scale in North America and Argentina to bundle cementing into completions packages.
Magnum Cementing Services Ltd.: regional niche player serving Western Canadian producers with local blending and responsive scheduling.
Consolidated Oil Well Services LLC: focused on remedial cementing and well servicing for mature onshore fields with limited capital intensity.
Gulf Energy SAOC: niche regional services and trading position in Middle East upstream activity.
Strategic Milestones & Recent Developments in Well Casing and Cementing Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2025
Halliburton Company
Portfolio expansion
Expanded automated cementing and real-time monitoring offering
2024
Schlumberger N.V.
Technology launch
Digital well-integrity workflow integrated into job design
2024
Baker Hughes
Equipment launch
Next-generation cementing unit reducing crew footprint
Pumping and cementing capacity redeployed to Argentina
Table entries summarise publicly reported portfolio, capacity and technology activity; verify specifics against company filings.
2023-2024: Regional capacity redeployment toward Argentina and the Middle East reflected a shift of service intensity away from a flat North American rig market.
2024: Equipment and digital launches concentrated on reducing crew size per job, the binding constraint on cementing throughput.
2025: Portfolio expansion toward automated monitoring aligns service offerings with new barrier verification requirements.
Structural implication: consolidation and capability bundling favour integrated majors, pressuring single-line regional contractors on price.
Regional Market Analysis & Growth Corridors for Well Casing and Cementing Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation (2024, $M)
Primary Catalyst
Regulatory Stringency
North America
5.2
2,079.2
Shale pad drilling and P&A backlog
High
Europe
4.3
1,039.6
Mature field integrity and North Sea abandonment
Very high
Asia-Pacific
7.4
2,227.7
NOC development drilling and gas expansion
Medium-high
Middle East & Africa
6.8
1,410.9
GCC gas capacity and North African programs
Medium
South America
6.0
668.3
Brazil pre-salt and Vaca Muerta development
Medium-high
Fastest growth: Asia-Pacific at 7.4% CAGR. State-backed operators in China and India prioritise development drilling and domestic gas output over shareholder returns, keeping casing and cementing volumes insulated from price cycles. The Offshore Drilling Services Market in China and Southeast Asia reinforces this trend as shallow-water and deepwater blocks are developed.
Middle East & Africa at 6.8% CAGR. Low lifting costs and gas capacity targets in the GCC sustain multi-year drilling programs with stable cementing demand.
Most mature: Europe at 4.3% CAGR. Growth comes from integrity work and North Sea decommissioning rather than new drilling, but regulatory stringency keeps service intensity per well high.
North America at 5.2% CAGR. The largest single regional pool at $2,079.2 million, yet the most cyclical; P&A obligations provide a partial hedge to rig count declines.
South America at 6.0% CAGR. Brazil pre-salt and Argentine unconventional activity drive offshore-weighted revenue with premium casing grades.
Export, Cross-Border Trade & Tariff Impact on Well Casing and Cementing Market
Trade Corridor
Principal Products
Direction
Trade Barrier Exposure
East Asia to North America
OCTG casing, couplings
Net export
Section 232 steel tariffs, anti-dumping duties
Europe to Middle East & Africa
Cement additives, blending equipment
Net export
Low, logistics-driven
China to Asia-Pacific and Africa
Casing and tubulars
Net export
Moderate, freight and quota risk
North America to South America
Cementing units, service crews
Net export
Low, services largely unrestricted
Middle East to Asia
Cement raw materials, clinker
Net export
Freight rates, energy cost pass-through
Steel tubulars dominate cross-border value. Casing and coupling imports into the United States face tariff structures that raise landed cost by an estimated 10-25%, pushing operators toward domestic mills or premium-connection suppliers with local inventory. Cement and additive trade is less politicised but freight-sensitive: bulk Class G cement shipments over long distances lose economic viability beyond roughly 2,000 nautical miles, favouring regional blending terminals. Services remain the least trade-restricted element, so crew and equipment mobility is rarely the binding constraint.
Supply Chain & Raw Material Dynamics: Well Casing and Cementing Market
Material
Function
Price Trend
Supply Risk
API Class G/H cement
Primary barrier slurry base
Rising, energy-linked
Medium
Silica flour and fly ash
Strength retrogression control
Stable to rising
Low
Fluid-loss and retarder additives
Slurry placement control
Rising
High (concentrated suppliers)
Steel casing (J55 to Q125)
Structural wellbore barrier
Volatile, tariff-linked
Medium
Premium connections and float equipment
Pressure integrity at connections
Rising
Medium
The Oil Well Cement Market sits at the base of the value chain. Clinker production is energy-intensive, so cement pricing tracks fuel and power costs, and logistics constrain sourcing radius. The Drilling Fluids and Cement Additives Market overlaps heavily here: fluid-loss control, retarders, dispersants and weighting agents are frequently blended by the same specialty chemical suppliers that serve drilling fluids, creating shared upstream dependencies.
Historical disruptions are instructive. Pandemic-era plant shutdowns and freight congestion lengthened additive lead times from weeks to several months, forcing operators to accept substitute formulations. Tariff changes on steel tubulars shifted casing procurement toward domestic mills within a single budget cycle. Current risk concentrates in three areas: additive supplier concentration, steel trade policy, and crew availability, which together determine whether cementing capacity can scale with a drilling upturn.
Well Casing and Cementing Market Segmentation
1. Operation Type
1.1. Remedial Cementing
1.2. Primary Cementing
1.3. Others
2. Application
2.1. Onshore
2.2. Offshore
Well Casing and Cementing Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Well Casing and Cementing Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.1% from 2020-2034
Segmentation
By Operation Type
Remedial Cementing
Primary Cementing
Others
By Application
Onshore
Offshore
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Operation Type
5.1.1. Remedial Cementing
5.1.2. Primary Cementing
5.1.3. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Onshore
5.2.2. Offshore
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Operation Type
6.1.1. Remedial Cementing
6.1.2. Primary Cementing
6.1.3. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Onshore
6.2.2. Offshore
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Operation Type
7.1.1. Remedial Cementing
7.1.2. Primary Cementing
7.1.3. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Onshore
7.2.2. Offshore
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Operation Type
8.1.1. Remedial Cementing
8.1.2. Primary Cementing
8.1.3. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Onshore
8.2.2. Offshore
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Operation Type
9.1.1. Remedial Cementing
9.1.2. Primary Cementing
9.1.3. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Onshore
9.2.2. Offshore
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Operation Type
10.1.1. Remedial Cementing
10.1.2. Primary Cementing
10.1.3. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Onshore
10.2.2. Offshore
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Schlumberger N.V.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. GE company
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Baker Hughes
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Gulf Energy SAOC
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Nine Energy Service Inc.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. China Oilfield Services Limited
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Magnum Cementing Services Ltd.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Halliburton Company
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Calfrac Well Services Ltd.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Consolidated Oil Well Services LLC
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Well Casing and Cementing Market Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Well Casing and Cementing Market Revenue (million), by Operation Type 2026 & 2034
Figure 3: North America Well Casing and Cementing Market Revenue Share (%), by Operation Type 2026 & 2034
Figure 4: North America Well Casing and Cementing Market Revenue (million), by Application 2026 & 2034
Figure 5: North America Well Casing and Cementing Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Well Casing and Cementing Market Revenue (million), by Country 2026 & 2034
Figure 7: North America Well Casing and Cementing Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Well Casing and Cementing Market Revenue (million), by Operation Type 2026 & 2034
Figure 9: South America Well Casing and Cementing Market Revenue Share (%), by Operation Type 2026 & 2034
Figure 10: South America Well Casing and Cementing Market Revenue (million), by Application 2026 & 2034
Figure 11: South America Well Casing and Cementing Market Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Well Casing and Cementing Market Revenue (million), by Country 2026 & 2034
Figure 13: South America Well Casing and Cementing Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Well Casing and Cementing Market Revenue (million), by Operation Type 2026 & 2034
Figure 15: Europe Well Casing and Cementing Market Revenue Share (%), by Operation Type 2026 & 2034
Figure 16: Europe Well Casing and Cementing Market Revenue (million), by Application 2026 & 2034
Figure 17: Europe Well Casing and Cementing Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Well Casing and Cementing Market Revenue (million), by Country 2026 & 2034
Figure 19: Europe Well Casing and Cementing Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Well Casing and Cementing Market Revenue (million), by Operation Type 2026 & 2034
Figure 21: Middle East & Africa Well Casing and Cementing Market Revenue Share (%), by Operation Type 2026 & 2034
Figure 22: Middle East & Africa Well Casing and Cementing Market Revenue (million), by Application 2026 & 2034
Figure 23: Middle East & Africa Well Casing and Cementing Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Middle East & Africa Well Casing and Cementing Market Revenue (million), by Country 2026 & 2034
Figure 25: Middle East & Africa Well Casing and Cementing Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Well Casing and Cementing Market Revenue (million), by Operation Type 2026 & 2034
Figure 27: Asia Pacific Well Casing and Cementing Market Revenue Share (%), by Operation Type 2026 & 2034
Figure 28: Asia Pacific Well Casing and Cementing Market Revenue (million), by Application 2026 & 2034
Figure 29: Asia Pacific Well Casing and Cementing Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Well Casing and Cementing Market Revenue (million), by Country 2026 & 2034
Figure 31: Asia Pacific Well Casing and Cementing Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Well Casing and Cementing Market Revenue million Forecast, by Operation Type 2020 & 2034
Table 2: Well Casing and Cementing Market Revenue million Forecast, by Application 2020 & 2034
Table 3: Well Casing and Cementing Market Revenue million Forecast, by Region 2020 & 2034
Table 4: North America Well Casing and Cementing Market Revenue million Forecast, by Operation Type 2020 & 2034
Table 5: North America Well Casing and Cementing Market Revenue million Forecast, by Application 2020 & 2034
Table 6: North America Well Casing and Cementing Market Revenue million Forecast, by Country 2020 & 2034
Table 7: United States Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 8: Canada Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 9: Mexico Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 10: South America Well Casing and Cementing Market Revenue million Forecast, by Operation Type 2020 & 2034
Table 11: South America Well Casing and Cementing Market Revenue million Forecast, by Application 2020 & 2034
Table 12: South America Well Casing and Cementing Market Revenue million Forecast, by Country 2020 & 2034
Table 13: Brazil Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 14: Argentina Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 15: Rest of South America Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 16: Europe Well Casing and Cementing Market Revenue million Forecast, by Operation Type 2020 & 2034
Table 17: Europe Well Casing and Cementing Market Revenue million Forecast, by Application 2020 & 2034
Table 18: Europe Well Casing and Cementing Market Revenue million Forecast, by Country 2020 & 2034
Table 19: United Kingdom Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 20: Germany Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 21: France Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 22: Italy Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 23: Spain Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Russia Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 25: Benelux Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 26: Nordics Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 27: Rest of Europe Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 28: Middle East & Africa Well Casing and Cementing Market Revenue million Forecast, by Operation Type 2020 & 2034
Table 29: Middle East & Africa Well Casing and Cementing Market Revenue million Forecast, by Application 2020 & 2034
Table 30: Middle East & Africa Well Casing and Cementing Market Revenue million Forecast, by Country 2020 & 2034
Table 31: Turkey Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Israel Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 33: GCC Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 34: North Africa Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 35: South Africa Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 36: Rest of Middle East & Africa Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Asia Pacific Well Casing and Cementing Market Revenue million Forecast, by Operation Type 2020 & 2034
Table 38: Asia Pacific Well Casing and Cementing Market Revenue million Forecast, by Application 2020 & 2034
Table 39: Asia Pacific Well Casing and Cementing Market Revenue million Forecast, by Country 2020 & 2034
Table 40: China Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 41: India Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 42: Japan Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 43: South Korea Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 44: ASEAN Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 45: Oceania Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Table 46: Rest of Asia Pacific Well Casing and Cementing Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70-80% of total project effort, with 20-30% derived from secondary and syndicated sources.
Structured interviews and surveys were conducted with cementing product line directors, cementing operations managers, well integrity engineers, drilling and completions superintendents, and procurement and supply chain directors across integrated majors, NOCs and independent operators.
Value-chain participants interviewed span integrated oilfield service cementing product lines, independent regional cementing service contractors, OCTG casing and coupling manufacturers, oil well cement and specialty additive blenders, and cementing unit and float equipment OEMs.
Regulatory and technical input was benchmarked against bodies including the American Petroleum Institute (API), the International Association of Drilling Contractors (IADC), the Bureau of Safety and Environmental Enforcement (BSEE), ISO/TC 67, and the Society of Petroleum Engineers (SPE).
Interview coverage was stratified by region (North America, Europe, Asia-Pacific, South America, Middle East & Africa), by application (onshore, offshore) and by operation type (primary cementing, remedial cementing, others).
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Cementing Operations Managers
26%
Well Integrity Engineers
22%
Procurement and Supply Chain Directors
18%
Drilling and Completions Superintendents
16%
Cementing Product Line Directors
12%
HSE and Regulatory Compliance Leads
6%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Integrated Oilfield Service Cementing Lines
28%
Independent Regional Cementing Contractors
22%
OCTG Casing and Coupling Manufacturers
18%
Oil Well Cement and Additive Blenders
16%
Cementing Unit and Float Equipment OEMs
10%
E&P Operator Cementing Procurement Teams
6%
Secondary Research & Industry Benchmarking
Secondary research draws on financial and transaction databases including Bloomberg, Factiva, Hoovers and PitchBook for company financials, capital expenditure disclosures, service contract awards and M&A activity.
Company annual reports, 10-K and 20-F filings, investor presentations and operator well programs were triangulated against national drilling statistics and rig count series.
Every report is updated to the date of purchase, incorporating the latest disclosed contract awards, tariff changes and drilling permit data.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously. The top-down view sizes the segment as a share of total upstream oilfield services spend, adjusted for the non-discretionary nature of barrier placement.
The bottom-up view aggregates basin-level demand using specific quantitative inputs: rig counts by basin, number of wells spudded and completed per year, average casing tonnage per well by total depth, average cement slurry volume (barrels) per hole section, average service revenue per cementing job, and the idle and orphan well backlog available for plugging and abandonment.
Volume estimates are multiplied by regional service price benchmarks and blended by onshore and offshore cost structures, where offshore jobs carry materially higher revenue per well.
Multi-level data triangulation reconciles top-down share allocation against bottom-up basin aggregation until variance falls within tolerance.
Data Accuracy & Quality Check
The methodology delivers a guaranteed estimated data accuracy level of 85-90%, supported by cross-validation across at least three independent source families per data point.
Sensitivity analysis is run on the two most volatile inputs: active rig count and well cement and steel casing price movements.
Growth rates are stress-tested against low, base and high upstream capital expenditure scenarios, with the 6.1% CAGR positioned in the base case.
All primary transcripts and secondary extracts are retained for audit, and figures are re-verified against post-publication disclosures at the point of purchase.
Frequently Asked Questions
1. What are the main growth drivers behind the Well Casing and Cementing Market?
Three forces dominate: development drilling by national oil companies, deepwater and HPHT project sanctions, and tightening well-integrity regulation such as ISO 16530 and BSEE barrier verification rules. The market was valued at $7,425.75 million in 2024 and is forecast to reach $12,655.6 million by 2033 at a 6.1% CAGR. Deepwater wells consume 3-5x the casing tonnage of comparable onshore wells, which raises revenue per well even when rig counts are flat.
2. How much investment is flowing into well cementing technology and services?
Capital is concentrated in incremental capability rather than new entrants, with the three largest service companies directing an estimated 8-10% of cementing service revenue toward digital job monitoring, automated mixing and downhole sensing. Private equity interest is limited to regional cementing contractors serving mature onshore basins, where decommissioning backlogs create contracted multi-year revenue. Upstream operators, not service companies, carry the larger capital burden: a single deepwater development can absorb 50-150 casing strings across its drilling program.
3. How are operator purchasing patterns changing in well construction?
Operators are consolidating discrete tenders into bundled multi-year contracts covering cementing, casing running and liner hangers, which now represent an estimated 55-65% of outsourced cementing spend in North America. Performance-based clauses tied to barrier verification and non-productive-time reduction are increasingly standard. For service contractors, bundling improves backlog visibility but compresses standalone cementing margins by an estimated 200-400 basis points.
4. Who are the leading companies in the well casing and cementing market?
Halliburton Company, Schlumberger N.V. and Baker Hughes hold a combined estimated 40-45% of the outsourced global cementing service market, supported by integrated casing running and additive manufacturing capability. China Oilfield Services Limited leads domestic Chinese offshore work, while Nine Energy Service Inc., Calfrac Well Services Ltd., Magnum Cementing Services Ltd. and Consolidated Oil Well Services LLC compete regionally on responsiveness and price. Gulf Energy SAOC holds a niche position in Middle East oilfield services.
5. What technological innovations are shaping cementing and casing operations?
Adoption is fastest in real-time downhole monitoring, where fiber-optic distributed sensing and instrumented cementing units provide verification-grade evidence of barrier placement. Self-healing and geopolymer cement systems are being field-tested to cut Portland clinker intensity and improve long-term zonal isolation. Expandable liner hangers and automated surface mixing skids reduce crew size per job, addressing a labor constraint that limits how quickly contractors can scale.
6. How are raw material supply chains for well cement and casing managed?
API Class G and H well cement, silica flour, fluid-loss additives and OCTG steel dominate the input stack, with slurry materials accounting for 30-45% of cementing job cost. Steel casing grades J55 through Q125 are sourced heavily from Asian mills, exposing contractors to freight rates and Section 232-type tariff structures. Specialty additive blending remains concentrated among a small group of suppliers, so a single plant outage can lengthen lead times across an entire basin.