Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Residential Generators Market Outlook 2033: 4.7% CAGR
Residential Generators Market
Residential Generators Market Outlook 2033: 4.7% CAGR
Residential Generators Market by Type (Stationary and Portable), by Fuel Type (Gasoline, Diesel, Others), by Power Rating (Less than 4 KW, 4- 8 KW, 8-17 KW, More than 17 KW), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 14, 2026|Base Year : 2025|Pages : 200
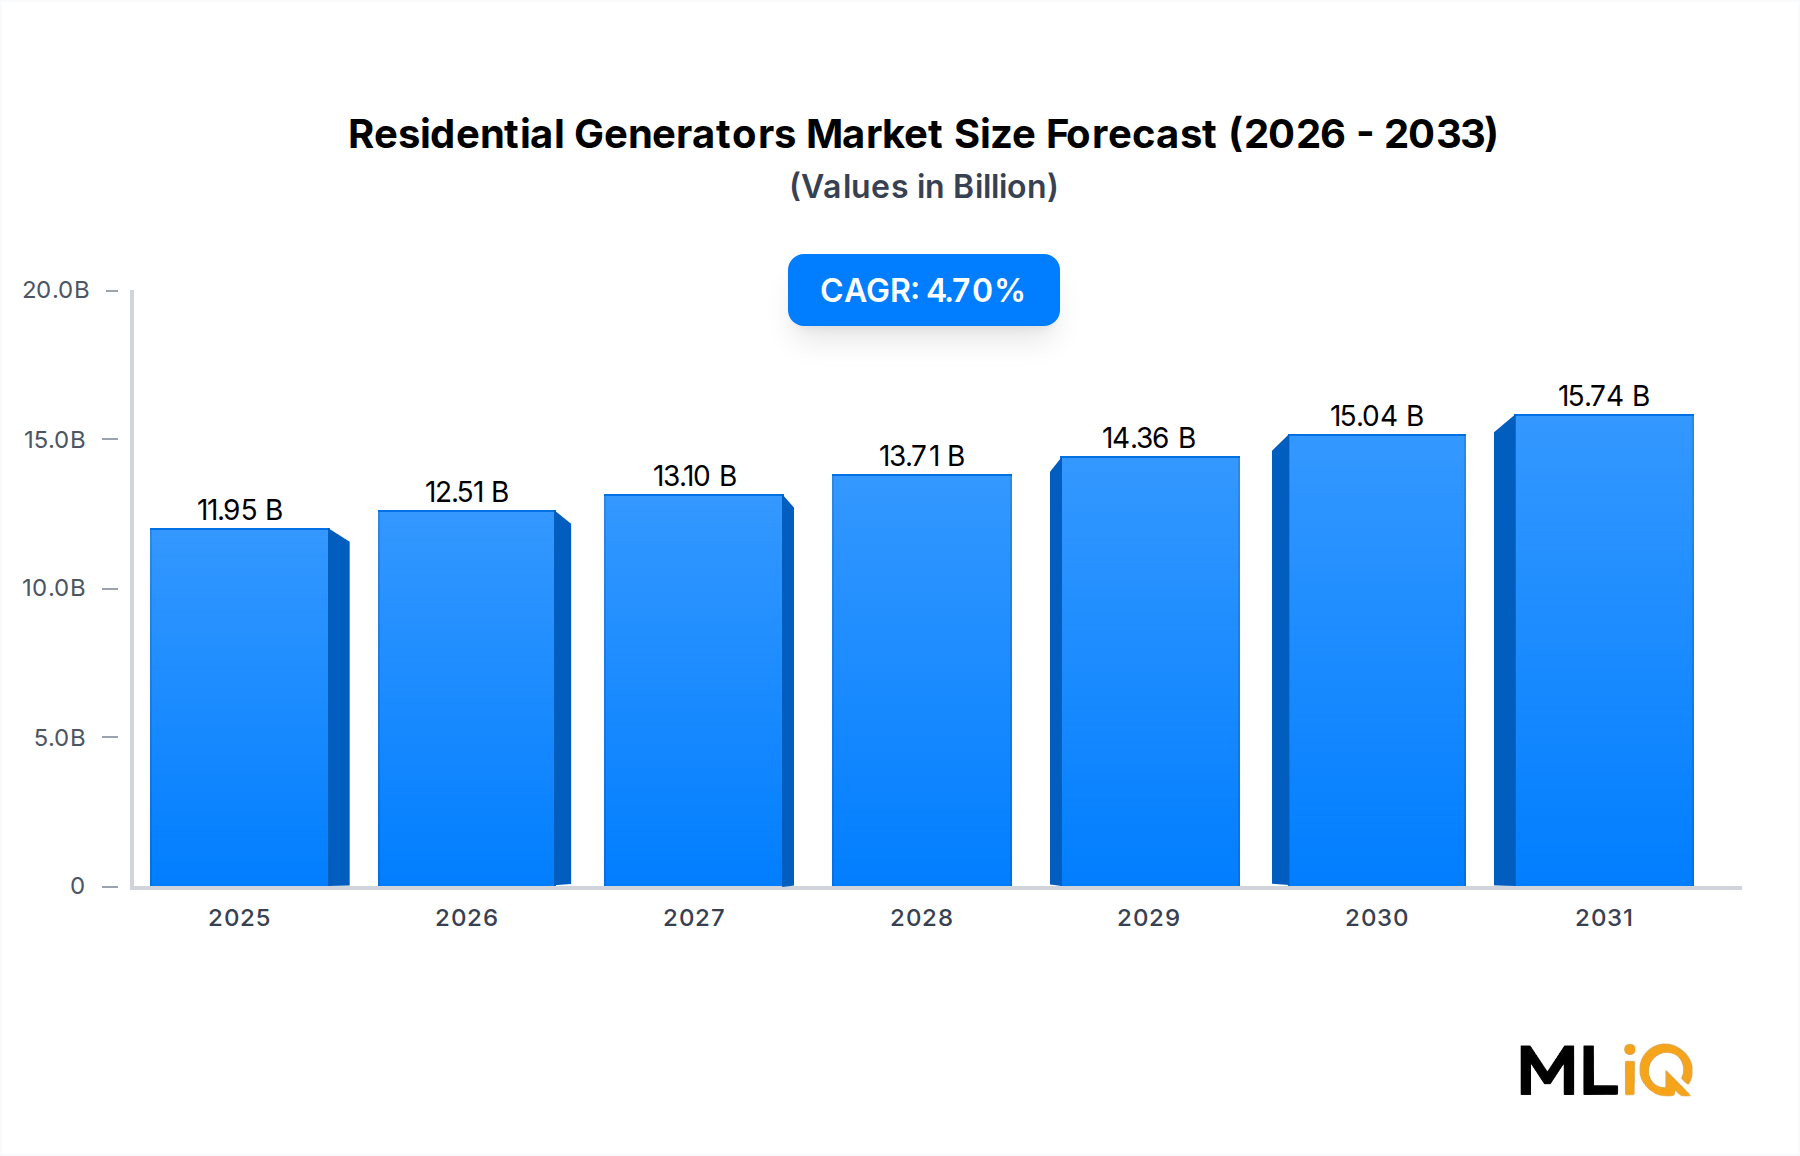
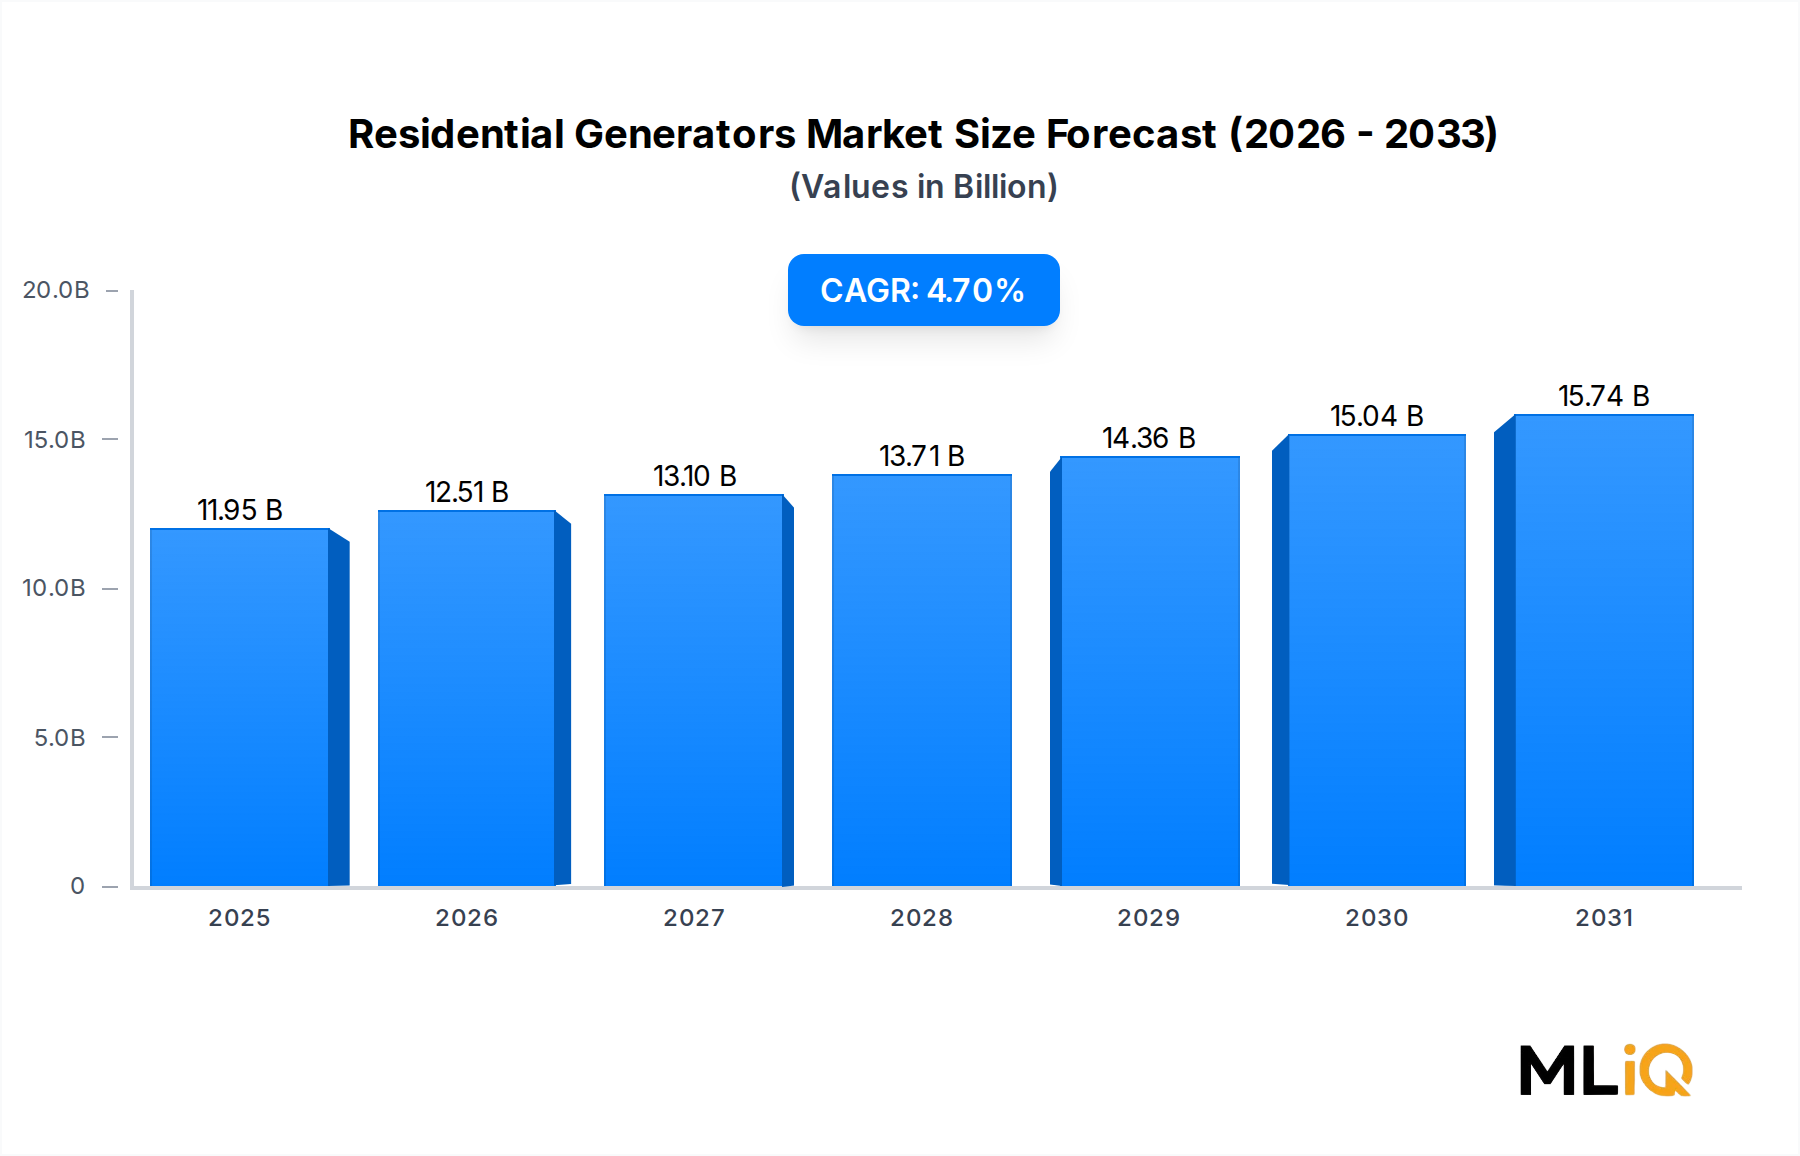
The global Residential Generators Market is valued at $11.95 billion in 2025 and is projected to reach $17.24 billion by 2033, expanding at a 4.7% CAGR. Growth is anchored in rising grid instability, extreme weather events, and residential backup power requirements. The Portable Generators Market and Stationary Generators Market together represent the core product split, with stationary units generating 62% of revenue. The Backup Power Market within residential applications has gained urgency as average U.S. outage duration reached 5.5 hours in 2024, up from 4.2 hours in 2019. The Power Generation Equipment Market benefits from broader electrification and distributed energy investments.
Residential Generators Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
11.95 B
2025
12.51 B
2026
13.10 B
2027
13.71 B
2028
14.36 B
2029
15.04 B
2030
15.74 B
2031
Key accelerants include:
Hurricane and wildfire frequency: NOAA recorded 28 billion-dollar weather disasters in the U.S. in 2023, driving standby generator adoption in Florida, Texas, and California.
Aging grid infrastructure: Over 70% of U.S. transmission lines are more than 25 years old, increasing outage risk and homeowner willingness to invest in backup systems.
Remote work permanence: 28% of U.S. employees work hybrid or fully remote, raising the cost of downtime and pushing 8-17 kW installations.
Fuel flexibility: Gasoline Generators Market remains the largest by unit volume, while Diesel Generators Market holds higher runtime value for long outages.
Restraints include high installation costs ($3,000-$10,000 for home standby systems) and permitting delays in dense urban areas. The Home Standby Generators Market is forecast to grow at 5.1% CAGR, outpacing portable units at 4.2%. Lithium-Ion Battery Storage Market substitutes are gaining for short-duration outages but remain limited by cost per kWh and recharge rates. Overall, the market shows steady, non-cyclical growth tied to reliability demand rather than new construction alone.
Segment Deep-Dive: Stationary Generators Dominance in Residential Generators Market
Segment Analysis Matrix
Segment
CAGR (%)
Market Share (%)
Key Demand Driver
Stationary Generators
5.1
62
Whole-home backup during multi-day outages
Portable Generators
4.2
38
Emergency response, recreation, job sites
Gasoline Generators
3.9
44
Low upfront cost and portability
Diesel Generators
4.5
31
High runtime and heavy-load capability
Natural Gas/LPG Generators
5.6
25
Continuous fuel supply and lower emissions
Stationary Generator Revenue Leadership
Stationary generators, including home standby systems, dominate the Residential Generators Market with 62% revenue share in 2025. These units are permanently installed and connected to an automatic transfer switch, delivering 8-48 kW of power. The Home Standby Generators Market is expanding because homeowners face multi-day outages from hurricanes, ice storms, and public safety power shutoffs. In California, utilities de-energized lines for more than 1.2 million customers in 2024, directly correlating with standby generator sales.
Portable Generator Sub-Segment Dynamics
Portable generators hold 38% share and serve price-sensitive and mobile users. The Portable Generators Market grew 4.2% in 2024, with inverter models gaining share due to lower total harmonic distortion for electronics. Gasoline remains the dominant fuel, but the Gasoline Generators Market faces regulatory pressure in California and New York, where small off-road engine rules phase out many portable units by 2028. The Diesel Generators Market is preferred for 17 kW+ portable units and small commercial backup.
Margin Pressures and Cost Structure
Copper and steel costs represent 35-40% of bill-of-materials for stationary units; copper prices rose 12% year-over-year in 2024.
Semiconductor shortages for inverter boards have eased but remain a 6-8 week lead-time risk.
Emissions compliance adds $150-$400 per portable unit for catalytic converters and fuel injection.
The Stationary Generators Market benefits from higher average selling prices ($4,000-$8,000 installed) and recurring service revenue. The Backup Power Market increasingly integrates generators with Lithium-Ion Battery Storage Market systems for hybrid resilience. Natural gas and LPG units are the fastest-growing fuel sub-segment at 5.6% CAGR because they eliminate fuel storage and refueling logistics. Overall, stationary generators will remain the profit engine, while portables defend volume share in lower-income and recreational segments.
Primary Market Drivers & Growth Restraints in Residential Generators Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Increasing grid outage frequency and duration
High
Short term
Driver
Extreme weather events and public safety power shutoffs
High
Short term
Driver
Aging electrical infrastructure in North America and Europe
Medium
Long term
Driver
Remote work and home-based business continuity
Medium
Medium term
Restraint
High upfront installation and permitting costs
High
Short term
Restraint
Emissions regulations on small gasoline engines
Medium
Long term
Restraint
Competition from lithium-ion home batteries
Medium
Medium term
Restraint
Supply chain volatility in copper and semiconductors
Medium
Short term
Quantified Growth Catalysts
The Residential Generators Market is primarily driven by reliability demand, not new housing. In 2024, U.S. utility customers experienced an average of 5.5 hours of outages, up 31% from 2019. States with the highest outage hours—Louisiana, Texas, and Florida—account for 42% of U.S. standby generator installations. The Power Generation Equipment Market benefits as homeowners view generators as essential infrastructure. Backup Power Market spending is also supported by federal incentives for resilient home energy systems, including FEMA reimbursement for medically necessary backup power.
Bottlenecks and Restraints
Installation cost: A 22 kW home standby system costs $5,000-$12,000 installed, limiting adoption to households earning above $75,000 annually.
Regulatory friction: California Air Resources Board regulations require zero-emission portable generators by 2028, affecting 15% of U.S. portable sales.
Battery substitution: The Lithium-Ion Battery Storage Market offers silent, emission-free backup for outages under 12 hours, capturing 8% of new residential backup installations in 2024.
Supply chain: Copper and electrical steel tariffs increased input costs by 9-14% in 2023-2024, compressing OEM margins.
Net Impact Assessment
Drivers outweigh restraints through 2033, but growth will concentrate in regions with high outage frequency and low regulatory barriers. Vendors that integrate Home Standby Generators Market products with battery storage and smart home controls will capture premium pricing. The Gasoline Generators Market faces a long-term volume decline in developed markets, offset by growth in Asia-Pacific and Africa where grid reliability is lower and emissions rules are less stringent.
Generac Holdings Inc.: Controls an estimated 40% of the North American home standby market and invests in Lithium-Ion Battery Storage Market products through its PWRcell line.
Kohler Co.: Targets high-income homeowners with 26-48 kW stationary units and emphasizes quiet operation and long warranty coverage.
Honda Motor Co.: Leads the Portable Generators Market in inverter technology, with EU2200i models achieving 8-10 hour runtime on 0.95 gallons.
Champion Power Equipment: Competes on price in the Gasoline Generators Market, offering 4-8 kW units at 20-30% below premium brands.
Eaton Corporation plc: Provides automatic transfer switches and integrated power management for hybrid residential systems.
Cummins Inc.: Supplies diesel generators above 17 kW and has a growing natural gas portfolio for residential microgrids.
Briggs & Stratton: Maintains a niche in portable gasoline generators, with distribution through home improvement retailers.
Atlas Copco AB: Focuses on rental and construction channels, not primary residential retail.
Caterpillar Inc.: Leverages diesel engine reliability for large residential estates and off-grid properties.
The competitive landscape is moderately concentrated, with the top five vendors accounting for 62% of global revenue. The Power Generation Equipment Market includes these firms plus regional assemblers in China and India. Backup Power Market competition is shifting toward integrated generator-plus-battery solutions, where Generac and Eaton hold early advantages.
Strategic Milestones & Recent Developments in Residential Generators Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2024-03
Generac Holdings Inc.
Launch
Released 26 kW home standby unit with 200-amp transfer switch
2024-06
Kohler Co.
Partnership
Collaborated with solar installers for hybrid backup systems
2023-11
Cummins Inc.
M&A
Acquired hydrogen fuel cell assets for stationary power
2024-01
Eaton Corporation plc
Launch
Introduced smart ATS with generator and battery coordination
2023-09
Honda Motor Co.
Launch
Released EU3200i portable inverter for small business backup
2024-04
Champion Power Equipment
Partnership
Expanded retail distribution with Lowe's and Costco
March 2024: Generac expanded its home standby lineup with a 26 kW model targeting 4,000-5,000 sq ft homes. The unit supports dual-fuel conversion and Wi-Fi monitoring.
June 2024: Kohler partnered with regional solar installers to bundle stationary generators with Lithium-Ion Battery Storage Market systems, reducing generator run hours by 30-40%.
November 2023: Cummins acquired hydrogen fuel cell assets, signaling diversification into zero-emission stationary power for residential microgrids.
January 2024: Eaton launched an intelligent automatic transfer switch that prioritizes battery discharge before generator start, extending generator life.
September 2023: Honda introduced the EU3200i, a 3.2 kW portable inverter with CO-Minder, addressing safety regulations in the Portable Generators Market.
These moves indicate a strategic shift toward hybrid backup power, digital monitoring, and regulatory compliance. The Home Standby Generators Market will see more product launches with integrated energy management through 2033.
Regional Market Analysis & Growth Corridors for Residential Generators Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
4.9
$3.82 billion
Hurricane and wildfire outages
Medium
Europe
4.3
$2.87 billion
Aging grid and severe storms
High
Asia-Pacific
5.2
$3.82 billion
Urbanization and power deficits
Medium
LAMEA
4.1
$1.44 billion
Off-grid demand and mining
Low
Fastest-Growing Region: Asia-Pacific
Asia-Pacific is the fastest-growing region at 5.2% CAGR, driven by rapid urbanization, unreliable grid supply, and industrial expansion. India and China account for 68% of regional demand. The Portable Generators Market dominates in Southeast Asia due to affordability and mobility. However, the Stationary Generators Market is rising in China as wealthy households install 8-17 kW units. Emissions standards in China and India are tightening but remain less stringent than in Europe.
Most Mature Market: North America
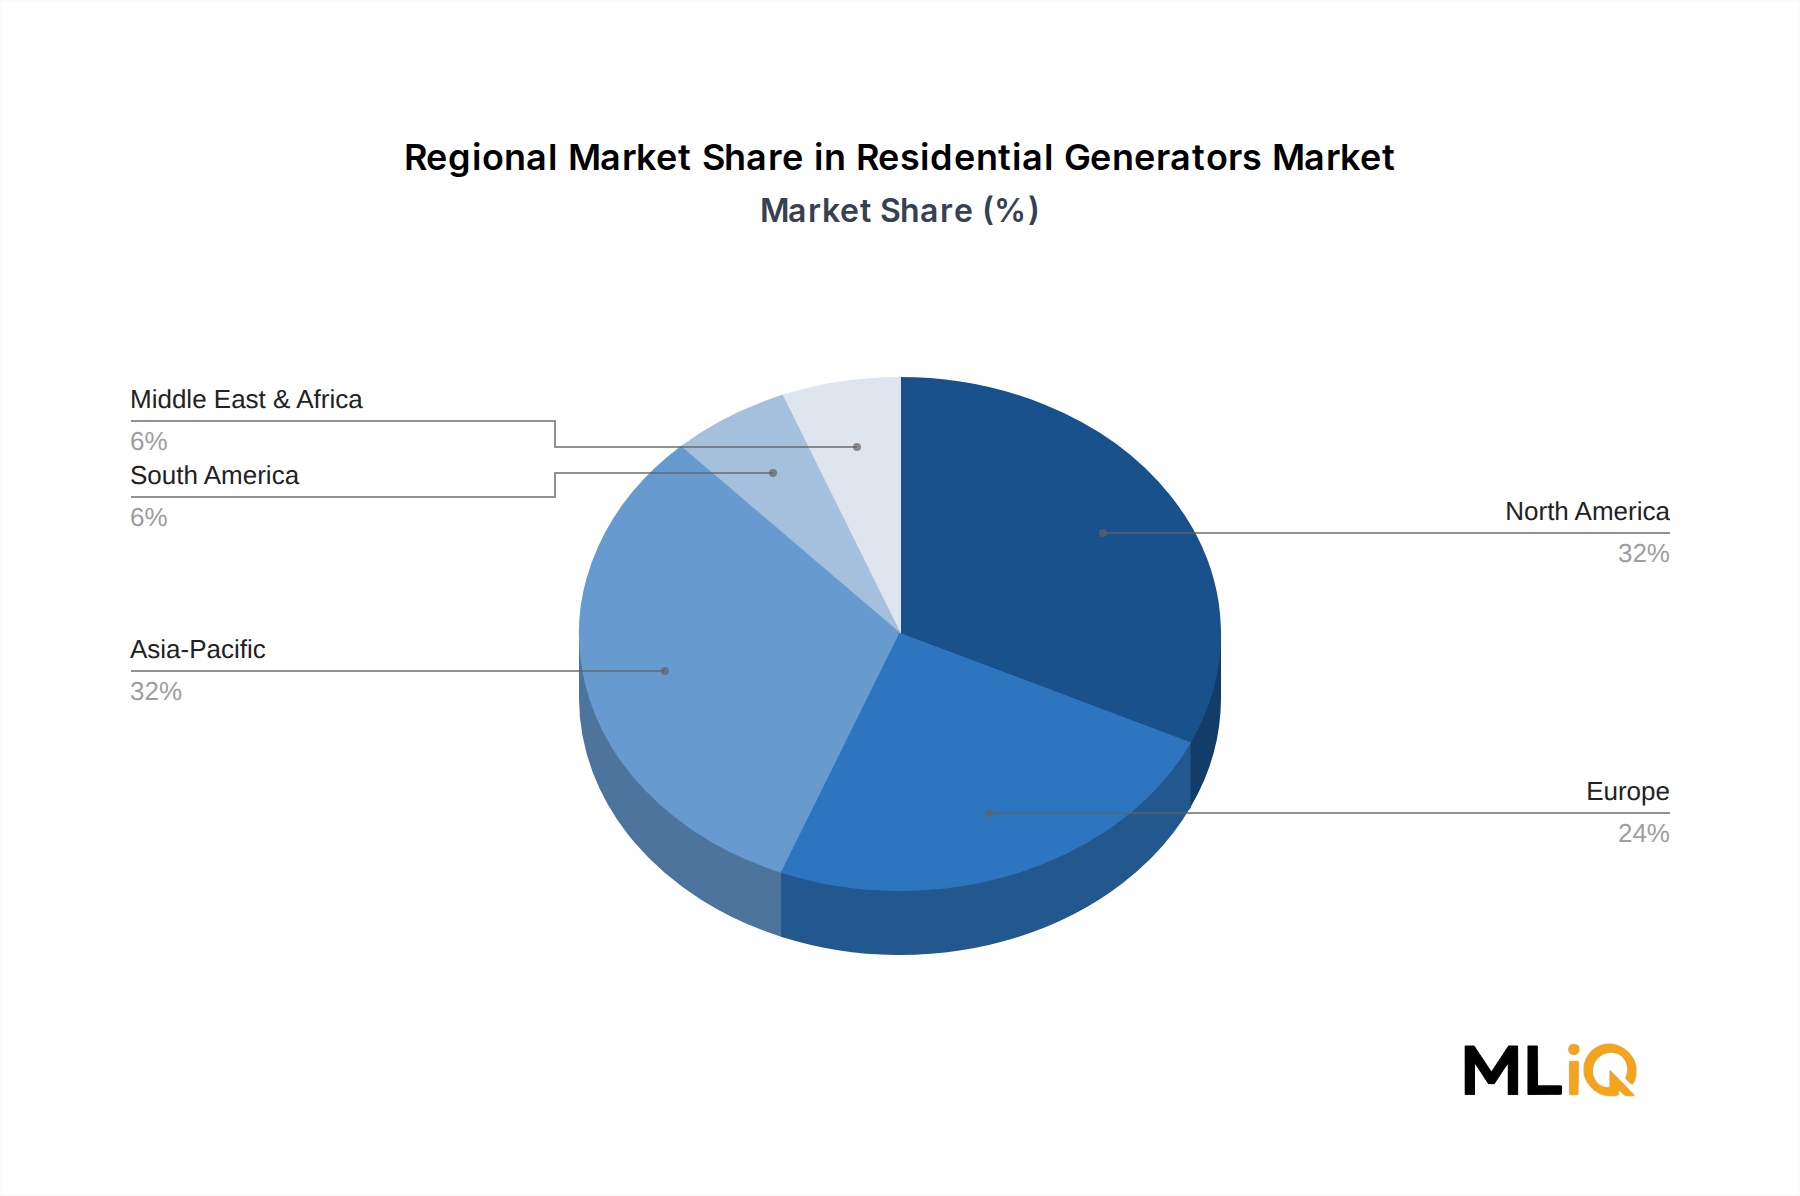
North America remains the largest market at $3.82 billion in 2025, with 32% global share. The U.S. represents 85% of regional revenue. Generac Holdings Inc. and Kohler Co. control the majority of home standby sales. The Backup Power Market is mature, with 5.5% penetration in single-family detached homes. Growth is sustained by extreme weather, with 28 billion-dollar disasters in 2023. Canada and Mexico add incremental demand, especially for portable units in rural areas.
Europe and LAMEA
Europe is the most regulated region, with EU Stage V emissions rules and noise ordinances limiting gasoline generators. The Diesel Generators Market and natural gas units are favored for higher efficiency. Germany, France, and the UK are key markets. LAMEA grows at 4.1% CAGR, led by South Africa, GCC states, and Turkey. Off-grid solar-plus-generator hybrids are common. The Power Generation Equipment Market in LAMEA benefits from mining and telecom backup. Overall, regional growth corridors favor Asia-Pacific for volume and North America for value.
Supply Chain & Raw Material Dynamics: Residential Generators Market
Upstream supply chain for residential generators depends on raw materials and components:
Copper: Used in alternator windings and wiring; prices rose 12% in 2024 to $9,200/metric ton on the LME. The Steel and Copper Materials Market directly influences generator costs.
Electrical steel: Critical for alternator cores; tariffs and energy costs increased prices by 9-14% in 2023-2024.
Aluminum: Used for frames and castings; supply is stable but energy-intensive smelting ties prices to power costs.
Semiconductors: Inverter boards and microcontrollers faced 26-40 week lead times in 2022-2023, easing to 6-8 weeks by 2024.
Engines: Honda, Kohler, and Briggs & Stratton manufacture engines in-house or source from Yanmar and Lombardini. Engine shortages peaked in 2021-2022.
Historical disruptions include the 2021 Texas winter storm, which caused generator demand to spike 300% and depleted inventory for six months. The 2022 semiconductor shortage delayed portable generator production by 15-20%. In 2024, Red Sea shipping disruptions added 10-15 days to Asian exports. Vendors are dual-sourcing copper and electronics to reduce risk. The Gasoline Generators Market is most exposed to fuel system component shortages, while the Home Standby Generators Market depends on automatic transfer switch availability.
Export, Cross-Border Trade & Tariff Impact on Residential Generators Market
Major Trade Corridors and Barriers
Corridor
Key Exporters
Key Importers
Tariff/Barrier
China to U.S.
China
United States
25% Section 301 tariff
China to Europe
China
Germany, UK, France
EU 2.7-4.5% duty
Mexico to U.S.
Mexico
United States
USMCA 0% tariff
Japan to Asia
Japan
ASEAN, India
0-5% duty
Germany to LAMEA
Germany
Brazil, GCC
6-14% duty
China is the largest net exporter of portable generators, shipping over 8 million units annually. The U.S. Section 301 tariff of 25% on Chinese generators has shifted assembly to Mexico and Vietnam. Mexico now supplies 18% of U.S. portable generator imports under USMCA. Germany and Japan export high-value stationary units, particularly diesel and natural gas models above 17 kW. India and Brazil remain net importers, with tariffs of 10-20% protecting local assembly.
The Power Generation Equipment Market faces increasing non-tariff barriers, including emissions certification and noise limits. EU Stage V rules require expensive aftertreatment, adding $300-$600 per portable unit. In 2024, the U.S. extended tariffs on Chinese inverters, affecting $1.2 billion in trade. Geopolitical tensions in the Red Sea added 10-15% to freight costs for Asia-Europe routes. The Lithium-Ion Battery Storage Market also faces tariff scrutiny, with U.S. tariffs on Chinese batteries rising to 25% in 2026. These trade policies will influence generator sourcing and final pricing through 2033.
Residential Generators Market Segmentation
1. Type
1.1. Stationary and Portable
2. Fuel Type
2.1. Gasoline
2.2. Diesel
2.3. Others
3. Power Rating
3.1. Less than 4 KW
3.2. 4- 8 KW
3.3. 8-17 KW
3.4. More than 17 KW
Residential Generators Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Residential Generators Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.7% from 2020-2034
Segmentation
By Type
Stationary and Portable
By Fuel Type
Gasoline
Diesel
Others
By Power Rating
Less than 4 KW
4- 8 KW
8-17 KW
More than 17 KW
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Stationary and Portable
5.2. Market Analysis, Insights and Forecast - by Fuel Type
5.2.1. Gasoline
5.2.2. Diesel
5.2.3. Others
5.3. Market Analysis, Insights and Forecast - by Power Rating
5.3.1. Less than 4 KW
5.3.2. 4- 8 KW
5.3.3. 8-17 KW
5.3.4. More than 17 KW
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Stationary and Portable
6.2. Market Analysis, Insights and Forecast - by Fuel Type
6.2.1. Gasoline
6.2.2. Diesel
6.2.3. Others
6.3. Market Analysis, Insights and Forecast - by Power Rating
6.3.1. Less than 4 KW
6.3.2. 4- 8 KW
6.3.3. 8-17 KW
6.3.4. More than 17 KW
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Stationary and Portable
7.2. Market Analysis, Insights and Forecast - by Fuel Type
7.2.1. Gasoline
7.2.2. Diesel
7.2.3. Others
7.3. Market Analysis, Insights and Forecast - by Power Rating
7.3.1. Less than 4 KW
7.3.2. 4- 8 KW
7.3.3. 8-17 KW
7.3.4. More than 17 KW
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Stationary and Portable
8.2. Market Analysis, Insights and Forecast - by Fuel Type
8.2.1. Gasoline
8.2.2. Diesel
8.2.3. Others
8.3. Market Analysis, Insights and Forecast - by Power Rating
8.3.1. Less than 4 KW
8.3.2. 4- 8 KW
8.3.3. 8-17 KW
8.3.4. More than 17 KW
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Stationary and Portable
9.2. Market Analysis, Insights and Forecast - by Fuel Type
9.2.1. Gasoline
9.2.2. Diesel
9.2.3. Others
9.3. Market Analysis, Insights and Forecast - by Power Rating
9.3.1. Less than 4 KW
9.3.2. 4- 8 KW
9.3.3. 8-17 KW
9.3.4. More than 17 KW
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Stationary and Portable
10.2. Market Analysis, Insights and Forecast - by Fuel Type
10.2.1. Gasoline
10.2.2. Diesel
10.2.3. Others
10.3. Market Analysis, Insights and Forecast - by Power Rating
10.3.1. Less than 4 KW
10.3.2. 4- 8 KW
10.3.3. 8-17 KW
10.3.4. More than 17 KW
11. Competitive Analysis
11.1. Company Profiles
11.1.1. KOHLER CO.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Scott's Emergency Lighting
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. HONDA MOTOR CO.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. LTD.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Champion Power Equipment
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Inc.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. GENERAC HOLDINGS INC.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. EATON CORPORATION PLC
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. BRIGGS & STRATTON
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Atlas Copco AB
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Cummins Inc.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Caterpillar Inc.
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Residential Generators Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Residential Generators Market Revenue (billion), by Type 2026 & 2034
Figure 3: North America Residential Generators Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Residential Generators Market Revenue (billion), by Fuel Type 2026 & 2034
Figure 5: North America Residential Generators Market Revenue Share (%), by Fuel Type 2026 & 2034
Figure 6: North America Residential Generators Market Revenue (billion), by Power Rating 2026 & 2034
Figure 7: North America Residential Generators Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 8: North America Residential Generators Market Revenue (billion), by Country 2026 & 2034
Figure 9: North America Residential Generators Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Residential Generators Market Revenue (billion), by Type 2026 & 2034
Figure 11: South America Residential Generators Market Revenue Share (%), by Type 2026 & 2034
Figure 12: South America Residential Generators Market Revenue (billion), by Fuel Type 2026 & 2034
Figure 13: South America Residential Generators Market Revenue Share (%), by Fuel Type 2026 & 2034
Figure 14: South America Residential Generators Market Revenue (billion), by Power Rating 2026 & 2034
Figure 15: South America Residential Generators Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 16: South America Residential Generators Market Revenue (billion), by Country 2026 & 2034
Figure 17: South America Residential Generators Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Residential Generators Market Revenue (billion), by Type 2026 & 2034
Figure 19: Europe Residential Generators Market Revenue Share (%), by Type 2026 & 2034
Figure 20: Europe Residential Generators Market Revenue (billion), by Fuel Type 2026 & 2034
Figure 21: Europe Residential Generators Market Revenue Share (%), by Fuel Type 2026 & 2034
Figure 22: Europe Residential Generators Market Revenue (billion), by Power Rating 2026 & 2034
Figure 23: Europe Residential Generators Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 24: Europe Residential Generators Market Revenue (billion), by Country 2026 & 2034
Figure 25: Europe Residential Generators Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Residential Generators Market Revenue (billion), by Type 2026 & 2034
Figure 27: Middle East & Africa Residential Generators Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Middle East & Africa Residential Generators Market Revenue (billion), by Fuel Type 2026 & 2034
Figure 29: Middle East & Africa Residential Generators Market Revenue Share (%), by Fuel Type 2026 & 2034
Figure 30: Middle East & Africa Residential Generators Market Revenue (billion), by Power Rating 2026 & 2034
Figure 31: Middle East & Africa Residential Generators Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 32: Middle East & Africa Residential Generators Market Revenue (billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Residential Generators Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Residential Generators Market Revenue (billion), by Type 2026 & 2034
Figure 35: Asia Pacific Residential Generators Market Revenue Share (%), by Type 2026 & 2034
Figure 36: Asia Pacific Residential Generators Market Revenue (billion), by Fuel Type 2026 & 2034
Figure 37: Asia Pacific Residential Generators Market Revenue Share (%), by Fuel Type 2026 & 2034
Figure 38: Asia Pacific Residential Generators Market Revenue (billion), by Power Rating 2026 & 2034
Figure 39: Asia Pacific Residential Generators Market Revenue Share (%), by Power Rating 2026 & 2034
Figure 40: Asia Pacific Residential Generators Market Revenue (billion), by Country 2026 & 2034
Figure 41: Asia Pacific Residential Generators Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Residential Generators Market Revenue billion Forecast, by Type 2020 & 2034
Table 2: Residential Generators Market Revenue billion Forecast, by Fuel Type 2020 & 2034
Table 3: Residential Generators Market Revenue billion Forecast, by Power Rating 2020 & 2034
Table 4: Residential Generators Market Revenue billion Forecast, by Region 2020 & 2034
Table 5: North America Residential Generators Market Revenue billion Forecast, by Type 2020 & 2034
Table 6: North America Residential Generators Market Revenue billion Forecast, by Fuel Type 2020 & 2034
Table 7: North America Residential Generators Market Revenue billion Forecast, by Power Rating 2020 & 2034
Table 8: North America Residential Generators Market Revenue billion Forecast, by Country 2020 & 2034
Table 9: United States Residential Generators Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Residential Generators Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research constitutes 70-80% of total research effort, targeting direct value chain participants in the Residential Generators Market.
We conduct semi-structured interviews with Residential Generator Product Line Directors, Home Energy Procurement Managers, Electrical Distribution Channel Managers, and Regulatory Compliance Lead for Backup Power.
Company types interviewed include residential standby generator OEMs, portable inverter generator assemblers, engine and alternator component suppliers, automatic transfer switch (ATS) manufacturers, and home battery storage integrators.
Each interview covers unit shipments, average selling prices, channel margins, installation bottlenecks, and regulatory compliance costs.
Primary data is validated through follow-up surveys and cross-referencing with distributor sell-through data.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Residential Generator Product Line Director
35%
Home Energy Procurement Manager
30%
Electrical Distribution Channel Manager
20%
Regulatory Compliance Lead for Backup Power
15%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Residential standby generator OEMs
30%
Portable inverter generator assemblers
25%
Engine and alternator component suppliers
15%
Automatic transfer switch (ATS) manufacturers
10%
Home battery storage integrators
10%
Electrical distributors and installers
10%
Secondary Research & Industry Benchmarking
Secondary research accounts for 20-30% of the study, drawing on Bloomberg, Factiva, Hoovers, and PitchBook for financial and competitive benchmarks.
We analyze utility outage reports, building codes, emissions regulations, and trade statistics from .gov and .org domains.
No market research websites are cited. All reports are updated to the date of purchase.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up quantitative metrics include: annual residential generator unit shipments by power rating, average selling price per kW by fuel type, number of grid outage events exceeding 8 hours per state, and home standby penetration rate in single-family detached homes.
Top-down modeling applies regional GDP, construction spending, and utility reliability indices to allocate global market value.
Segment splits by type, fuel type, and power rating are cross-checked against OEM revenue disclosures and import-export records.
Guaranteed estimated data accuracy level of 85-90%.
Data Accuracy & Quality Check
All primary interview transcripts are coded and checked for response bias by a second analyst.
Historical data from 2019-2024 is reconciled with utility outage databases and trade statistics.
Forecasts are stress-tested against weather scenarios, regulatory changes, and battery substitution rates.
Final report is updated to the date of purchase.
Frequently Asked Questions
1. How are lithium-ion battery storage systems disrupting the Residential Generators Market?
Lithium-ion battery storage systems, such as the Tesla Powerwall with 13.5 kWh capacity, provide silent backup power and reduce reliance on fuel-based generators for short outages. These systems integrate with solar arrays and can lower lifetime operating costs by 20-30% compared with diesel generators. However, for outages exceeding 48 hours, residential generators retain an advantage due to rapid refueling and higher continuous output.
2. What end-user industries drive downstream demand in the Residential Generators Market?
Residential homeowners represent the largest end-user group, accounting for over 70% of unit demand, followed by small commercial establishments, telecom towers, and healthcare clinics. Demand patterns spike during hurricane season in the U.S. Southeast, where outages above 8 hours increased 15% year-over-year in 2024. Rural agricultural operations and construction sites also rely on portable units for remote power.
3. How are consumer purchasing behaviors shifting in the Residential Generators Market?
Consumers increasingly prefer home standby generators with automatic transfer switches, with 2024 sales rising 12% for units above 17 kW. Online research and financing options now influence 65% of residential purchases, pushing vendors toward e-commerce and subscription maintenance plans. Noise reduction and emissions compliance are top-3 decision factors for 58% of buyers in urban markets.
4. Who are the leading companies and what is the competitive landscape of the Residential Generators Market?
Generac Holdings Inc. leads the North American residential standby segment with an estimated 40% market share, followed by Kohler Co. and Cummins Inc. Honda Motor Co. dominates the portable inverter generator niche, while Champion Power Equipment competes on price in the 4-8 kW range. The competitive landscape is moderately concentrated, with the top five vendors controlling approximately 62% of global revenue.
5. What are the export-import dynamics and trade flows in the Residential Generators Market?
China is the largest net exporter of portable generators, shipping over 8 million units annually, primarily to the United States, Europe, and Southeast Asia. The U.S. imposes a 25% Section 301 tariff on Chinese generators, which has shifted some assembly to Mexico and Vietnam. Germany and Japan export high-value stationary units, while India and Brazil remain net importers of diesel generators above 17 kW.
6. Which region dominates the Residential Generators Market and why?
North America dominates with a 32% revenue share in 2025, valued at $3.82 billion, driven by frequent extreme weather events and an aging electrical grid. The region experiences more than 180,000 outage events per year, with average duration rising to 5.5 hours in 2024. Stringent local building codes and high homeownership rates further sustain demand for stationary generators.