Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Petroleum Liquid Feedstock Market by Type (Light Naphtha, Heavy Naphtha, Gas Oil), by Product Type (Ethylene, Propylene, Hexane, Benzene, Naphthalene, Others), by Application (Industrial Solvents, Cleaning Fluids, Adulterant to Petrol, Gasoline, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
The petroleum liquid feedstock market closed 2024 at USD 1,210 billion and is forecast to reach USD 1,797 billion by 2033, expanding at a 4.5% CAGR. More than two-thirds of that increment is volume rather than price: naphtha crack spreads have held inside a USD 60-95 per tonne band since 2022 while global steam cracker capacity added approximately 9.4 million tonnes per year of ethylene nameplate between 2022 and 2024.
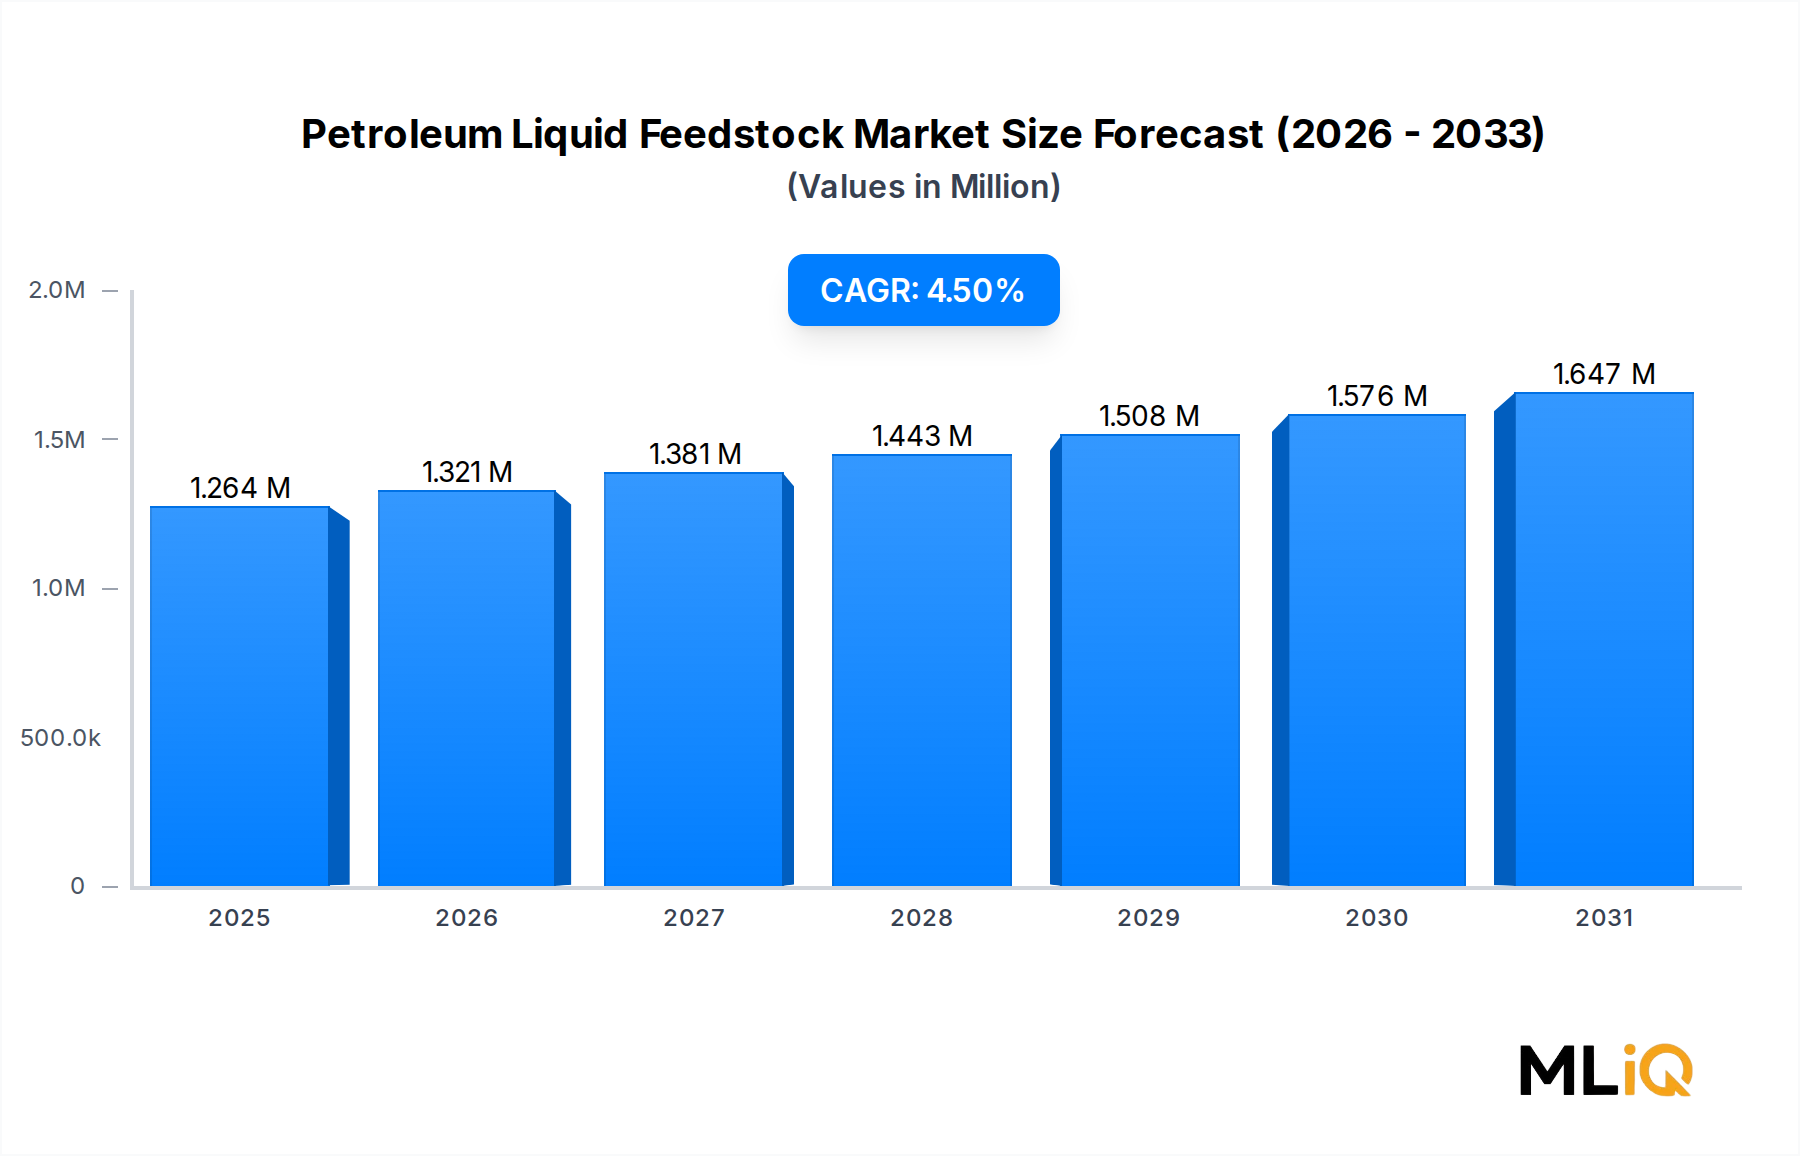
Petroleum Liquid Feedstock Market Size (In Million)
2.0M
1.5M
1.0M
500.0k
0
1.264 M
2025
1.321 M
2026
1.381 M
2027
1.443 M
2028
1.508 M
2029
1.576 M
2030
1.647 M
2031
Three structural forces define the forecast window:
Asia-Pacific capacity build-out. China and India account for about 61% of new liquid-feed cracker capacity announced through 2030, pulling naphtha and gas oil into the region and tightening Atlantic Basin surplus.
Feedstock substitution pressure. The North American ethane advantage caps naphtha at roughly 12% of United States ethylene feed, concentrating liquid feedstock demand in Europe, Northeast Asia and South Asia.
Tightening fuel specifications. Tier 3 and Euro 7 limits on sulfur and aromatics raise hydrotreating intensity, adding an estimated USD 8-14 per tonne of processing cost per unit of finished blendstock.
Capital allocation across the Petrochemical Feedstock Market now favors integrated refinery-cracker complexes able to swing between light and heavy naphtha as spreads move. Integrated operators captured an estimated 54% of 2024 liquid feedstock offtake, against 31% for merchant petrochemical buyers and 15% for trading houses and blend blenders.
Strategic takeaways for 2025-2033:
Light naphtha is the highest-growth cut at 5.1% CAGR, outpacing heavy naphtha by 150 basis points.
Gas oil demand is decoupling from the diesel pool as crackers co-process hydrotreated grades.
Contract structure is migrating from spot to indexed term deals, with Mean of Platts Arab Gulf assessments now referenced in roughly 48% of merchant volume.
Margin risk concentrates in feedstock cost, which absorbs 72-80% of variable cash cost at a typical naphtha cracker.
Segment Deep-Dive: Light Naphtha Dominance in Petroleum Liquid Feedstock Market
Type segmentation splits the market into light naphtha, heavy naphtha and gas oil, with condensates, raffinates and specialty cuts forming a residual category. Light naphtha is simultaneously the largest revenue pool and the fastest-growing cut.
Segment Analysis Matrix
Segment
CAGR (2025-2033)
Share of Demand (2024)
Key Demand Driver
Light Naphtha
5.1%
38%
High ethylene yield in steam crackers; paraxylene and benzene feed
Heavy Naphtha
3.6%
31%
Catalytic reforming into high-octane gasoline blendstock
Gas Oil
4.2%
24%
Hydrocracking, diesel pool balancing and cracker co-feed
Others (condensate, raffinate)
3.0%
7%
Specialty solvent, diluent and process stream applications
Light Naphtha: The Volume Engine
The Light Naphtha Market is anchored by Northeast Asian and Indian steam crackers, where full-range naphtha with 65-70% paraffin content delivers the highest ethylene yield per tonne of feed. Aromatics complexes in China consume a further 22% of light naphtha for paraxylene and benzene production, and that pull has grown faster than cracker demand since 2021.
Ethylene yield from light naphtha averages 30-33%, versus 26-29% for heavy naphtha.
Cracker co-processing of light naphtha with LPG has increased as operators chase lower feedstock cost per tonne of olefin.
Light naphtha availability is tightening in Europe as refinery rationalization removed roughly 1.6 million barrels per day of distillation capacity since 2020.
Heavy Naphtha Dynamics
The Heavy Naphtha Market remains tied to reforming economics. Gasoline blending absorbs about 78% of heavy naphtha offtake, so reformate octane value and aromatics content limits drive pricing more than petrochemical demand. Euro 7 and Tier 3 aromatic caps squeeze gasoline pool economics and push reformer operators toward lower-severity operation, reducing hydrogen yield and raising net processing cost by 6-9%.
Gas Oil and Co-Feed Economics
The Gas Oil Market has decoupled from diesel. Hydrotreated gas oil now enters crackers as a partial substitute for naphtha where price spreads exceed USD 70 per tonne, and roughly 4 million tonnes per year of gas oil is consumed as cracker co-feed globally. Diesel pool demand destruction from electrification in passenger transport is gradually shifting gas oil's value base toward the chemical chain.
Margin Pressure Points
Feedstock accounts for 72-80% of variable cash cost, leaving limited room for operational hedging.
Freight, tankage and working capital add 7-11% to delivered cost for import-dependent Asian buyers.
Crackers running below 85% utilization lose roughly USD 45-60 per tonne of fixed-cost absorption.
Asia-Pacific steam cracker and aromatics capacity additions of over 9 Mtpa ethylene nameplate
High
Long term
Driver
Rising paraxylene and benzene demand for polyester and styrenics chains
High
Long term
Driver
Hydrotreated gas oil co-feed adoption displacing marginal naphtha volumes
Medium
Short term
Driver
Indexed term contracting improving price transparency and offtake visibility
Medium
Short term
Restraint
North American ethane advantage displacing naphtha in United States crackers
High
Long term
Restraint
Tier 3 and Euro 7 sulfur and aromatics limits raising processing intensity
High
Medium term
Restraint
Refinery closures in Europe and Oceania reducing regional naphtha supply
Medium
Long term
Restraint
Carbon intensity disclosure requirements and Scope 3 reporting burdens
Medium
Short term
The Ethylene Market remains the single largest pull on liquid feedstock, consuming an estimated 52% of naphtha directed to chemicals. Ethylene capacity additions in China alone totaled approximately 7.8 million tonnes per year in 2023-2024, and each tonne of new ethylene capacity requires roughly 3.1-3.3 tonnes of naphtha feed at typical yields. That relationship makes cracker project announcements the most reliable forward indicator for light naphtha demand.
The Propylene Market is a secondary but faster-moving demand node. Propylene from liquid feedstock routes, including naphtha cracker co-product and metathesis, supplies about 58% of global propylene, and on-purpose routes have not displaced that share as quickly as forecast in 2020. Propylene demand growth of 4.8% annually through 2030 supports naphtha cracking runs even when ethylene margins compress.
Restraints operate on the supply side. European refinery closures removed approximately 1.6 million barrels per day of distillation capacity since 2020, reducing straight-run naphtha availability and forcing import dependence of 35-40% in the Benelux and Nordics. Carbon intensity disclosure requirements add administrative cost but have not yet materially altered naphtha trade flows, though several European crackers now require supplier-level Scope 3 data before contract award.
Integrated refinery and cracker network, Baytown and Singapore complexes
Chemical and fuels offtakers
Leader
Royal Dutch Shell plc.
Global trading desk and feedstock optimization across Puget Sound and Moerdijk
Merchant chemical buyers
Leader
China National Petroleum Corporation
Domestic crude access and large-scale refining integration
Chinese petrochemical complexes
Leader
China Petroleum and Chemical Corporation
Largest global paraxylene and aromatics feedstock position
Polyester chain buyers
Leader
Reliance Industries
Crude and feedstock flexibility at Jamnagar, export-oriented aromatics
Asian and European buyers
Leader
Chevron Phillips Chemical Company
Ethane and naphtha dual-feed cracker flexibility on the United States Gulf Coast
Olefins and polyolefins buyers
Challenger
Total S.A.
European refining footprint plus Middle East feedstock partnerships
European chemical offtakers
Challenger
Flint Hills Resources
United States refining and chemical feedstock logistics
Regional blenders and chemical producers
Niche
Idemitsu Kosan Co., Ltd.
Japanese aromatics and solvents integration
Northeast Asian chemical buyers
Niche
YPF
South American refining feedstock supply and domestic chemical demand
Argentine and regional buyers
Niche
Exxon Mobil Corporation: Operates integrated refinery-cracker complexes in the United States, Europe and Asia, giving it the widest internal transfer capability for naphtha and gas oil between fuels and chemicals.
Royal Dutch Shell plc.: Combines refining assets with one of the largest physical naphtha trading books, allowing it to arbitrage Atlantic and Pacific Basin spreads at scale.
China National Petroleum Corporation: Controls a refining base above 3 million barrels per day and supplies a substantial share of domestic naphtha to Chinese crackers and reformers.
China Petroleum and Chemical Corporation: Holds the largest single paraxylene portfolio globally, making it the reference buyer for heavy and light naphtha aromatics feed.
Reliance Industries: Runs the world's largest single-site refining complex at Jamnagar with feedstock flexibility that supports both export aromatics and domestic olefins.
Chevron Phillips Chemical Company: Maintains ethane and naphtha dual-feed capability that hedges Gulf Coast crackers against ethane price spikes and preserves liquid feedstock optionality.
Total S.A.: Uses European refining and Middle East supply agreements to balance naphtha procurement against its Antwerp and Normandy chemical operations.
Flint Hills Resources: Focuses on Midwest and Gulf Coast refining feedstock logistics, supplying regional blenders and independent chemical producers.
Idemitsu Kosan Co., Ltd.: Integrates Japanese aromatics and specialty solvent production, giving it a defensible position in high-purity cuts.
YPF: Functions as the principal South American integrated feedstock supplier, linking domestic crude production to Argentine chemical and fuel demand.
Strategic Milestones & Recent Developments in Petroleum Liquid Feedstock Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Q3 2024
China Petroleum and Chemical Corporation
Capacity Launch
Added aromatics and reforming capacity, increasing light and heavy naphtha intake
Q2 2024
Reliance Industries
Partnership
Feedstock and offtake agreements supporting export-oriented aromatics volumes
Q1 2024
Exxon Mobil Corporation
Capacity Launch
Gulf Coast chemical expansion raised liquid and gas feedstock flexibility
Divestment of upstream assets while retaining refining and trading feedstock positions
Q2 2023
Total S.A.
Partnership
Middle East feedstock supply agreement covering naphtha and condensate volumes
Q1 2023
China National Petroleum Corporation
Capacity Launch
Refinery upgrading project increased hydrotreated gas oil and naphtha output
Q1 2023 - China National Petroleum Corporation: Refinery upgrading added hydrotreating capacity, shifting the product slate toward higher-value naphtha and low-sulfur gas oil.
Q2 2023 - Total S.A.: Middle East supply agreement reduced spot exposure for European crackers and locked in condensate volumes at indexed pricing.
Q3 2023 - Royal Dutch Shell plc.: Upstream divestment preserved the refining and trading core that generates feedstock arbitrage margin.
Q3 2024 - China Petroleum and Chemical Corporation: Aromatics and reforming additions lifted domestic naphtha consumption and reduced reliance on imported blendstock.
The pattern across these moves is consolidation around integrated feedstock positions rather than standalone merchant supply. Companies with internal transfer capability between fuels and chemicals continue to outbid pure merchant buyers during spread inversions.
Cracker and aromatics capacity additions in China and India
Medium-High
North America
3.4%
266
Integrated chemical expansion and export blending economics
High
Europe
2.8%
218
Feedstock import substitution after refinery closures
Very High
Middle East & Africa
5.0%
133
Low-cost condensate and naphtha export surplus
Medium
South America
4.2%
85
Domestic refining and chemical demand recovery
Medium
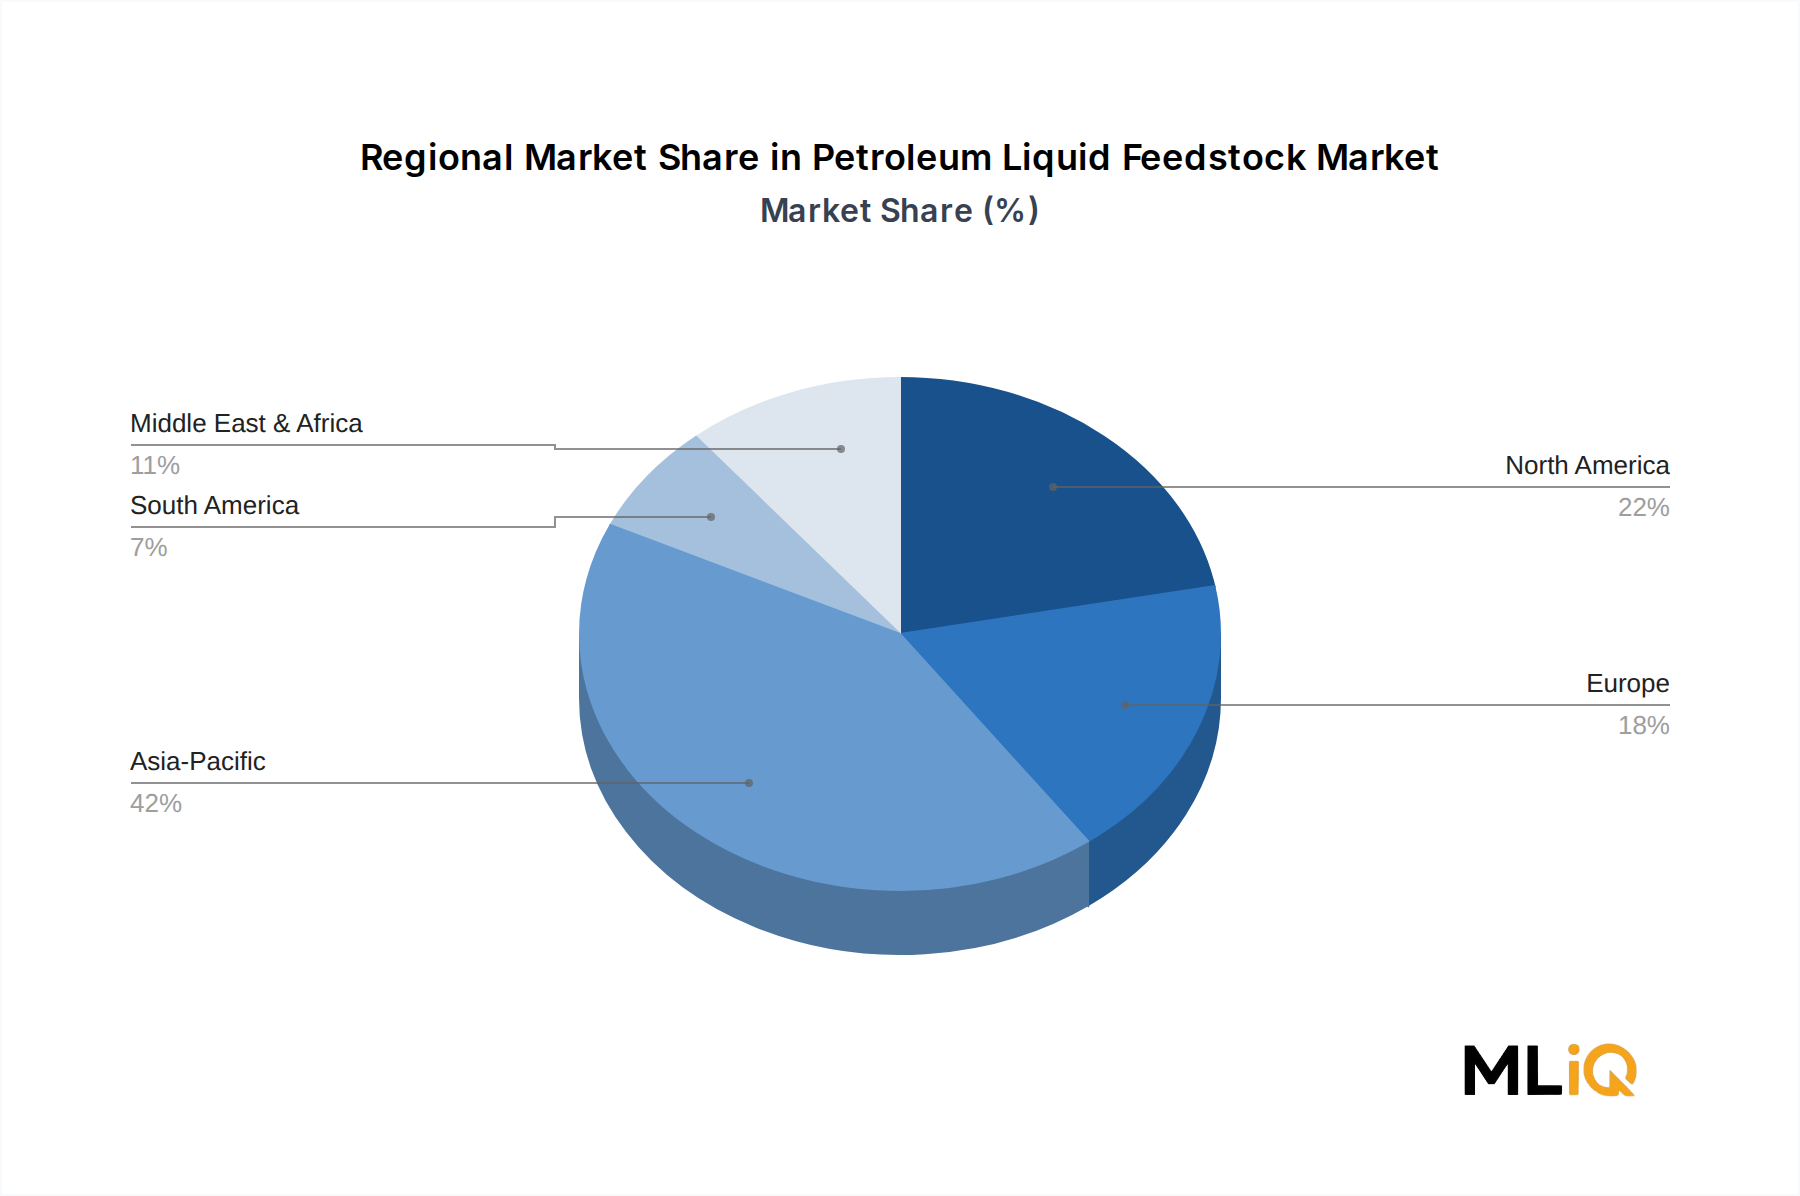
Asia-Pacific is the fastest-growing region and the largest consumer, absorbing 42% of global liquid feedstock. China's paraxylene and ethylene build-out explains most of the increment, supported by India's expanding refining base.
China: accounts for roughly 61% of announced liquid-feed capacity additions through 2030.
India: refining expansions position the country as both a naphtha importer and a rising exporter of aromatics.
Japan and South Korea: mature markets where cracker consolidation offsets modest demand growth.
North America is the most mature high-value market. Ethane availability caps naphtha use in domestic crackers at about 12% of ethylene feed, so regional liquid feedstock demand is tied to export blending, reformate and aromatics rather than olefins.
Europe faces the sharpest structural constraint. Refinery rationalization since 2020 removed approximately 1.6 million barrels per day of distillation capacity, and import dependence for naphtha now runs at 35-40% in Benelux and the Nordics. Euro 7 and REACH compliance costs push marginal operators toward feedstock import rather than domestic upgrading.
Middle East & Africa is the fastest-growing export corridor. Low-cost condensate and naphtha surplus from the GCC feeds Asian crackers, and new refining capacity in North Africa and Turkey adds blending-grade supply. South America remains a modest but recovering market, with Brazil and Argentina driving refinery utilization improvements.
The Gasoline Market in Latin America and Africa still absorbs a meaningful share of heavy naphtha reformate, sustaining regional demand even as electrification trims gasoline pool growth in Europe and North America.
Investment, M&A & Funding Activity in Petroleum Liquid Feedstock Market
Capital formation in liquid feedstock has shifted decisively toward integrated complexes and feedstock logistics rather than standalone merchant supply. Over the past three years, the largest disclosed transactions targeted refining and chemical integration, aromatics expansion and tank storage capacity along the United States Gulf Coast, the Persian Gulf and Northeast Asia.
Refining and chemical integration: transactions pairing distillation with steam cracking attracted the highest valuations because they capture spread arbitrage between Crude Oil Market cycles and chemical margins.
Aromatics and paraxylene: Chinese and Indian projects dominated announced capital expenditure, supported by polyester chain demand growth above 5% annually.
Feedstock logistics: tank storage, blending terminals and pipeline connectivity drew infrastructure and private equity capital seeking contracted, inflation-indexed revenue.
Gas oil upgrading: hydrocracker and hydrotreater projects attracted capital as operators repositioned diesel-range molecules for chemical co-feed.
High-growth sub-segments attracting capital include light naphtha fractionation, aromatics extraction and low-sulfur gas oil hydrotreating. Strategic acquirers have concentrated on assets with feedstock flexibility, because dual-feed crackers and refineries with crude optionality command a demonstrable margin premium of USD 30-55 per tonne during spread inversions.
Venture and growth capital activity remains limited relative to upstream and renewable sectors, with most private investment directed at digital trading platforms, feedstock quality analytics and emissions measurement tooling rather than physical capacity. Strategic partnerships, rather than outright acquisitions, remain the dominant structure for securing feedstock in Asia, since joint ventures reduce capital exposure while preserving offtake rights.
Customer Segmentation & Buying Behavior in Petroleum Liquid Feedstock Market
Buyer Segmentation Snapshot
Buyer Segment
Share of Merchant Volume
Primary Decision Criteria
Price Elasticity
Steam cracker operators
34%
Yield, sulfur content, delivery reliability
Medium
Aromatics and paraxylene producers
26%
Purity, N+2A content, contaminant limits
Low
Solvent and specialty chemical producers
18%
Distillation range, odor, trace metals
High
Fuel blenders and refiners
15%
Octane value, sulfur compliance, logistics
High
Traders and intermediaries
7%
Spread capture and tankage availability
Very High
The Industrial Solvents Market represents a high-margin, low-volume buyer group that prioritizes specification consistency over price. These buyers typically accept premiums of USD 40-80 per tonne for tightly controlled distillation ranges and low aromatic content, and they negotiate annual contracts rather than spot cargoes.
Procurement behavior has changed measurably since 2020:
Term contracting: indexed term deals referencing Mean of Platts Arab Gulf naphtha now cover roughly 48% of merchant volume, up from about 30% in 2019.
Carbon intensity requirements: European and Japanese buyers increasingly require supplier-level Scope 3 data before contract award, adding a qualifying gate to supplier lists.
Digital purchasing: electronic tenders and platform-based cargo matching now handle an estimated 35% of merchant transactions.
Logistics integration: buyers increasingly contract tankage alongside cargoes to secure blending flexibility, particularly in the Amsterdam-Rotterdam-Antwerp hub.
Price elasticity varies sharply by segment. Aromatics producers show low elasticity because reformer feed specifications cannot be swapped quickly, while fuel blenders and solvent producers can substitute alternative streams within weeks when spreads widen beyond USD 70 per tonne. This asymmetry gives sellers leverage with specification-sensitive buyers and exposes commodity-grade volume to rapid demand destruction during price spikes.
Petroleum Liquid Feedstock Market Segmentation
1. Type
1.1. Light Naphtha
1.2. Heavy Naphtha
1.3. Gas Oil
2. Product Type
2.1. Ethylene
2.2. Propylene
2.3. Hexane
2.4. Benzene
2.5. Naphthalene
2.6. Others
3. Application
3.1. Industrial Solvents
3.2. Cleaning Fluids
3.3. Adulterant to Petrol
3.4. Gasoline
3.5. Others
Petroleum Liquid Feedstock Market Segmentation By Geography
Table 52: Rest of Asia Pacific Petroleum Liquid Feedstock Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Coverage and split: 70-80% of total research effort is primary, with 20-30% allocated to secondary validation. Primary interviews and surveys were conducted across the liquid feedstock value chain in North America, Europe, Asia-Pacific, the Middle East and South America.
Company types interviewed: integrated oil and gas majors supplying straight-run naphtha and gas oil; steam cracker and petrochemical complex operators; independent refiners and condensate splitters; naphtha trading houses and gasoline blend blenders; aromatics and specialty solvent producers; and bulk liquid terminal and tank storage operators.
Stakeholder designations interviewed: Feedstock Procurement Director; Refinery Operations Manager; Petrochemical Trading Desk Head; Supply Chain and Logistics Manager; Regulatory Compliance and HSE Lead; and Process Technology and R&D Manager.
Interview structure: structured questionnaires captured feedstock sourcing patterns, contract tenor and indexation, cracker utilization, substitution thresholds between naphtha, gas oil and LPG, and compliance cost per tonne.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Feedstock Procurement Director
28%
Refinery Operations Manager
22%
Petrochemical Trading Desk Head
18%
Supply Chain & Logistics Manager
16%
Regulatory Compliance & HSE Lead
10%
Process Technology & R&D Manager
6%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Integrated Oil & Gas Majors
30%
Steam Cracker & Petrochemical Complex Operators
24%
Independent Refiners & Condensate Splitters
18%
Naphtha Trading Houses & Gasoline Blenders
14%
Aromatics & Specialty Solvent Producers
9%
Bulk Liquid Terminal & Tank Storage Operators
5%
Secondary Research & Industry Benchmarking
Financial and deal databases:Bloomberg, Factiva, Hoovers and PitchBook were used for corporate filings, capital expenditure tracking and M&A activity.
Trade and association sources: API, AFPM, Cefic and IEA publications supplied refinery throughput, naphtha trade volumes and petrochemical capacity data. No market research resale websites were used as primary evidence.
Benchmarking approach: reported capacity, utilization and trade volumes were normalized to a common calendar-year basis and reconciled against national statistics before modeling.
Demand Modeling & Market Estimation
Dual methodology: top-down and bottom-up models were run simultaneously. The top-down model allocates global refinery naphtha and gas oil output by region, application and product type; the bottom-up model builds demand from individual cracker, reformer and solvent units.
Bottom-up quantitative inputs: annual steam cracker ethylene nameplate capacity by region and feed slate; average naphtha feed ratio of 3.1-3.3 tonnes per tonne of ethylene; paraxylene and benzene production capacity requiring reformer feed; number of operating solvent extraction and hydrotreating units by specification tier; and average plant utilization rate by region.
Additional inputs: refinery distillation capacity and straight-run naphtha yield by crude slate; cross-border naphtha trade volumes by origin and destination; and contracted versus spot merchant volume splits.
Triangulation: multi-level data triangulation reconciled top-down totals, bottom-up unit-level aggregation, trade statistics and company-level offtake disclosures. Variance between models was held within a 4% tolerance before a single market estimate was accepted.
Scenario framework: base, high and low scenarios were built on cracker utilization, substitution thresholds between naphtha and gas oil, and regulatory compliance timelines.
Data Accuracy & Quality Check
Accuracy guarantee: the report carries a guaranteed estimated data accuracy level of 85-90%, validated through cross-source reconciliation and analyst review.
Completeness checks: every segment, product type, application and regional sub-market was verified against at least two independent sources before inclusion.
Currency and unit normalization: all valuations are expressed in United States dollars, with volumetric data converted on a consistent tonne and barrel basis across regions.
Refresh policy: every report is updated to the date of purchase, incorporating the latest capacity announcements, trade data releases and regulatory changes available at delivery, so buyers receive current base-year and forecast figures rather than a static snapshot.
Frequently Asked Questions
1. What are the main barriers to entry in the petroleum liquid feedstock market?
Entry requires either owned refining and cracker capacity or long-term supply contracts, because feedstock cost represents 72-80% of variable cash cost and spot buyers absorb full price volatility. Integrated majors such as Exxon Mobil and Sinopec control an estimated 54% of global liquid feedstock offtake, leaving merchant entrants to compete on blending flexibility and logistics rather than scale. Regulatory permitting for new hydrotreating and storage capacity adds 3-5 years of lead time in the United States and European Union.
2. How do export-import flows shape the petroleum liquid feedstock market?
Roughly 30% of global naphtha moves across borders, with the Middle East and Russia exporting surplus light and heavy naphtha into Northeast Asia. China, Japan and South Korea import an estimated 45 million tonnes annually, while the United States flips between net exporter and net importer depending on ethane cracking economics. Freight economics on a Persian Gulf to Japan route move the delivered cost by USD 25-40 per tonne, directly influencing cracker feedstock switching.
3. Which regulations most affect petroleum liquid feedstock market operations?
United States EPA Tier 3 gasoline rules cap sulfur at 10 ppm, and the International Maritime Organization 0.50% sulfur cap reshaped gas oil and vacuum gas oil flows after 2020. EU REACH registration and Euro 7 aromatics limits force additional hydrotreating, raising hydrogen consumption per tonne of blendstock by 8-12%. Operators in the GCC and India face lighter compliance burdens but increasingly align export specifications to EU and Japanese buyer requirements.
4. What raw material sourcing considerations matter most for feedstock buyers?
Crude slate selection drives naphtha yield, with light sweet grades delivering 22-28% straight-run naphtha versus 14-18% for heavy sour. Refiners with full crude flexibility, such as Reliance Industries at Jamnagar, can swing between domestic and imported barrels to capture spread arbitrage. Hydrogen availability, desalting capacity and condensate co-processing capability are the three constraints that most often limit a plant's ability to upgrade its feedstock diet.
5. Why do naphtha and gas oil prices diverge from crude benchmarks?
Naphtha typically trades at a discount or premium of USD 40-110 per tonne against Brent, driven by petrochemical cracker run rates rather than crude supply. Gas oil spreads widened to more than USD 35 per barrel in 2022 when diesel inventories fell below 30 days of forward cover in Europe and the United States. Cost structure is dominated by feedstock at 72-80%, followed by energy at 9-14% and catalyst and chemicals at 3-5%.
6. How is buyer behavior changing in the petroleum liquid feedstock market?
Procurement teams are shifting from spot purchases to indexed term contracts linked to Mean of Platts Arab Gulf naphtha assessments, with 18-24 month tenors now common. Buyers increasingly demand verified carbon intensity data, and several European cracker operators require supplier-level Scope 3 reporting before contract award. Digital platforms and electronic tender processes now cover an estimated 35% of merchant naphtha transactions, up from roughly 20% in 2019.