Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Solar Control Films Market: 2025-2033 Trends & Forecast
Solar Control Films Market
Solar Control Films Market: 2025-2033 Trends & Forecast
Solar Control Films Market by Type (Clear (Non-Reflective), by Dyed (Non-Reflective), by Vacuum coated (Reflective), by Application (Automotive, Construction, Marine, Decorative, Others), by Absorber Type (Organic, Inorganic, Metallic), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 12, 2026|Base Year : 2025|Pages : 0
Key Insights & Executive Summary: Solar Control Films Market
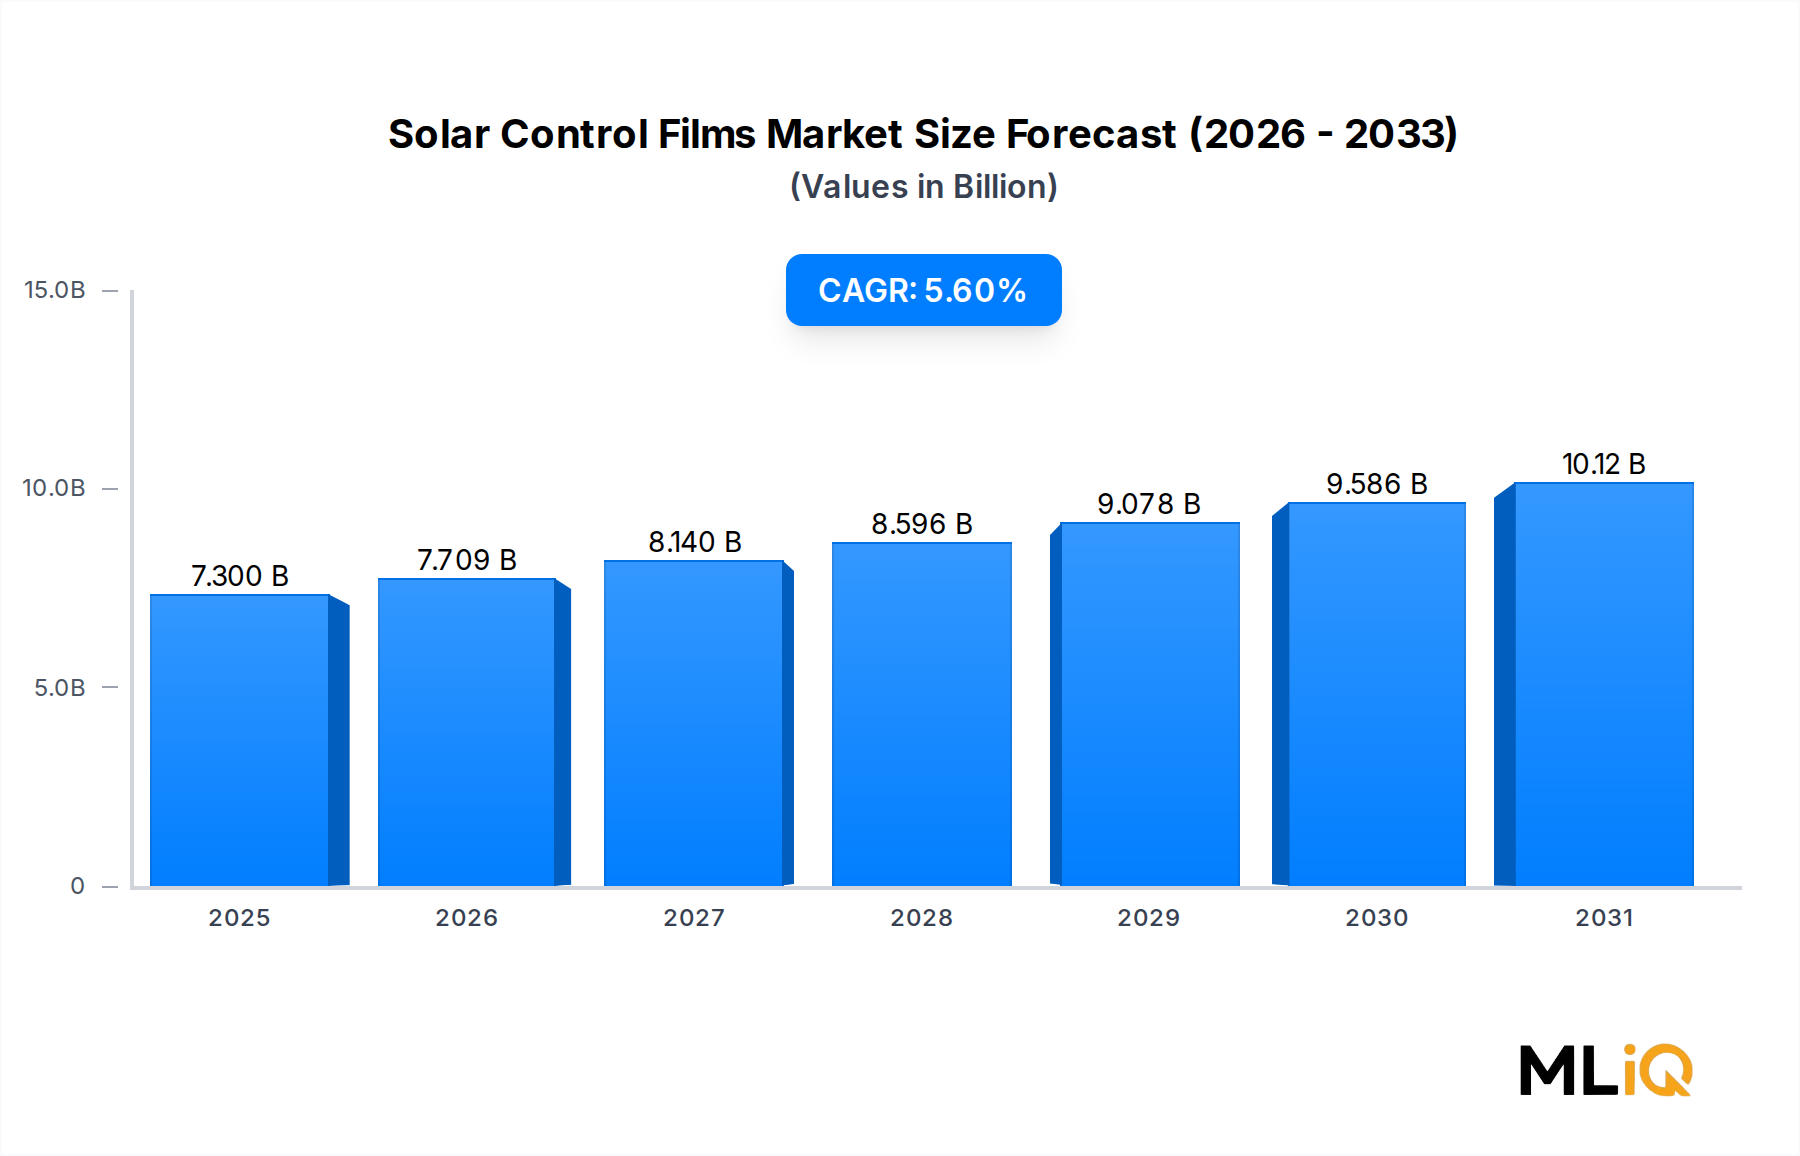
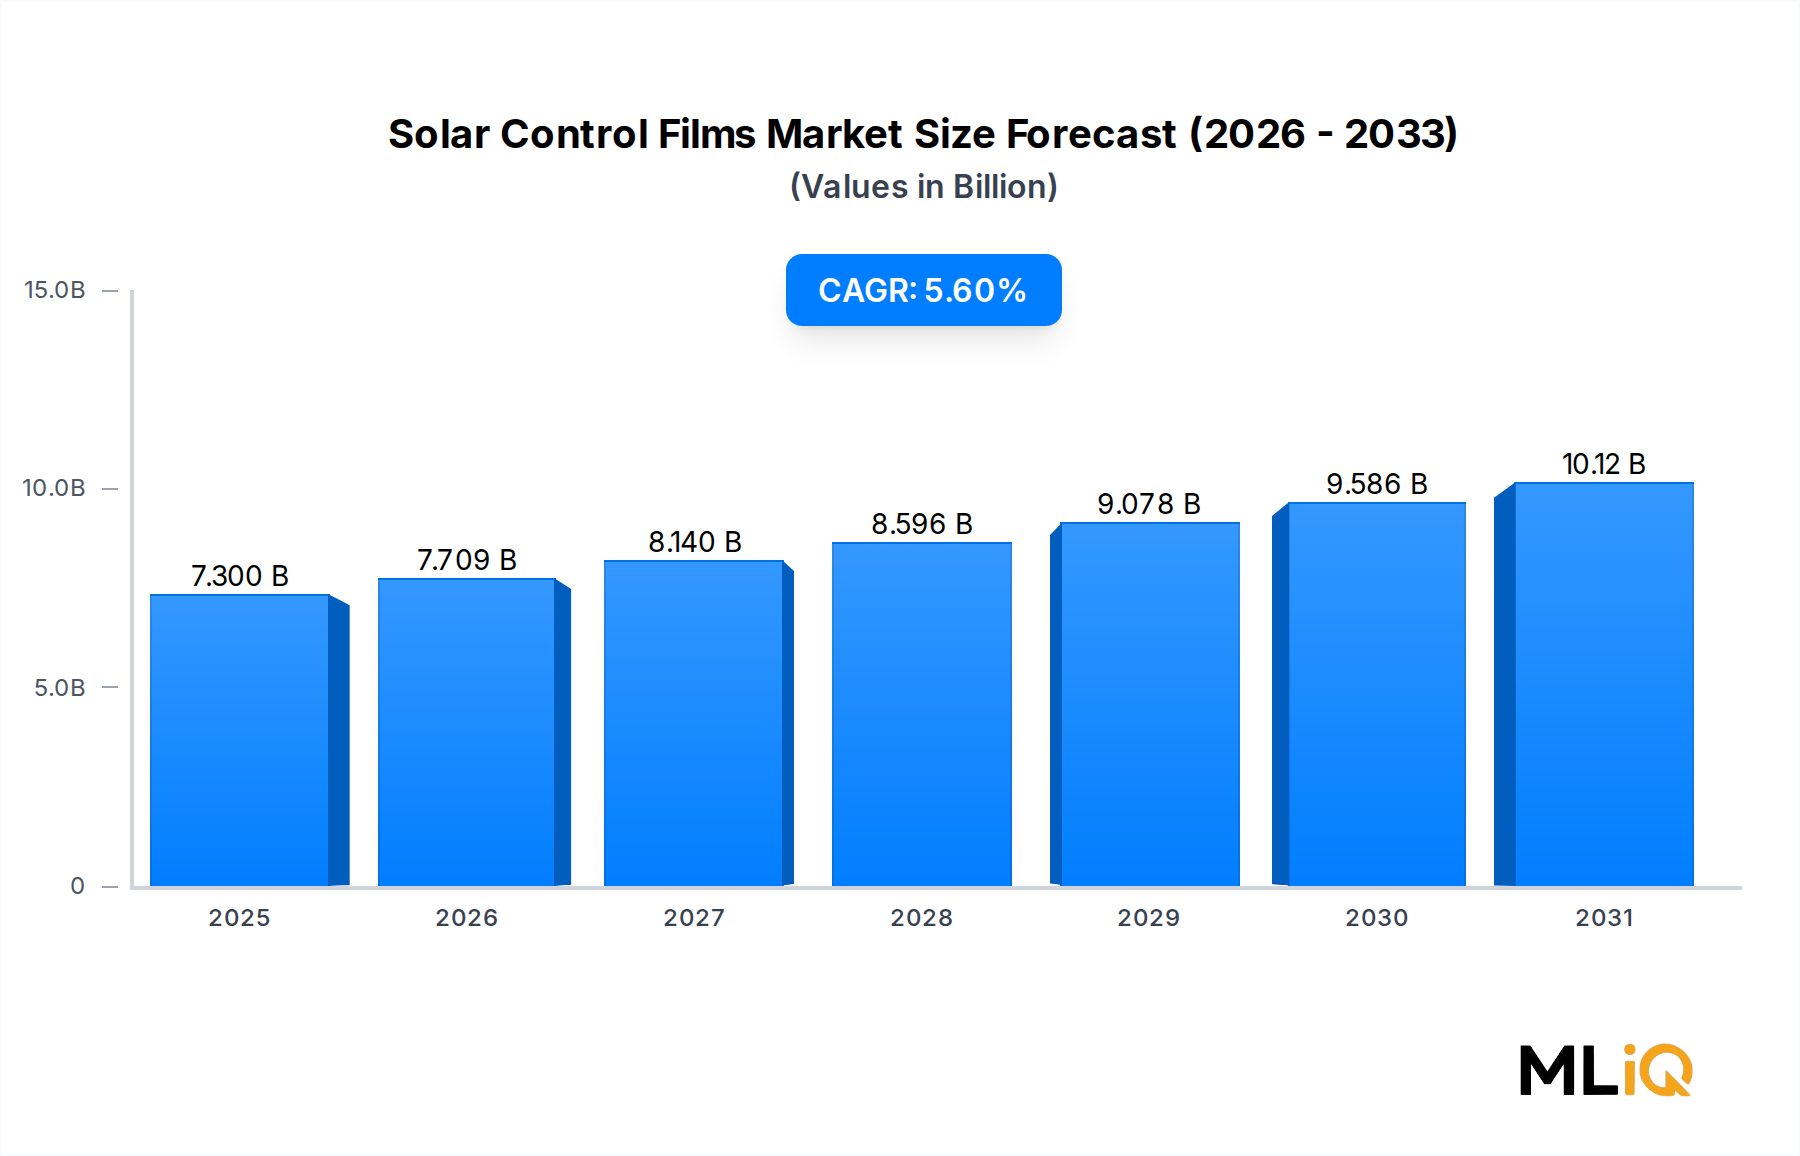
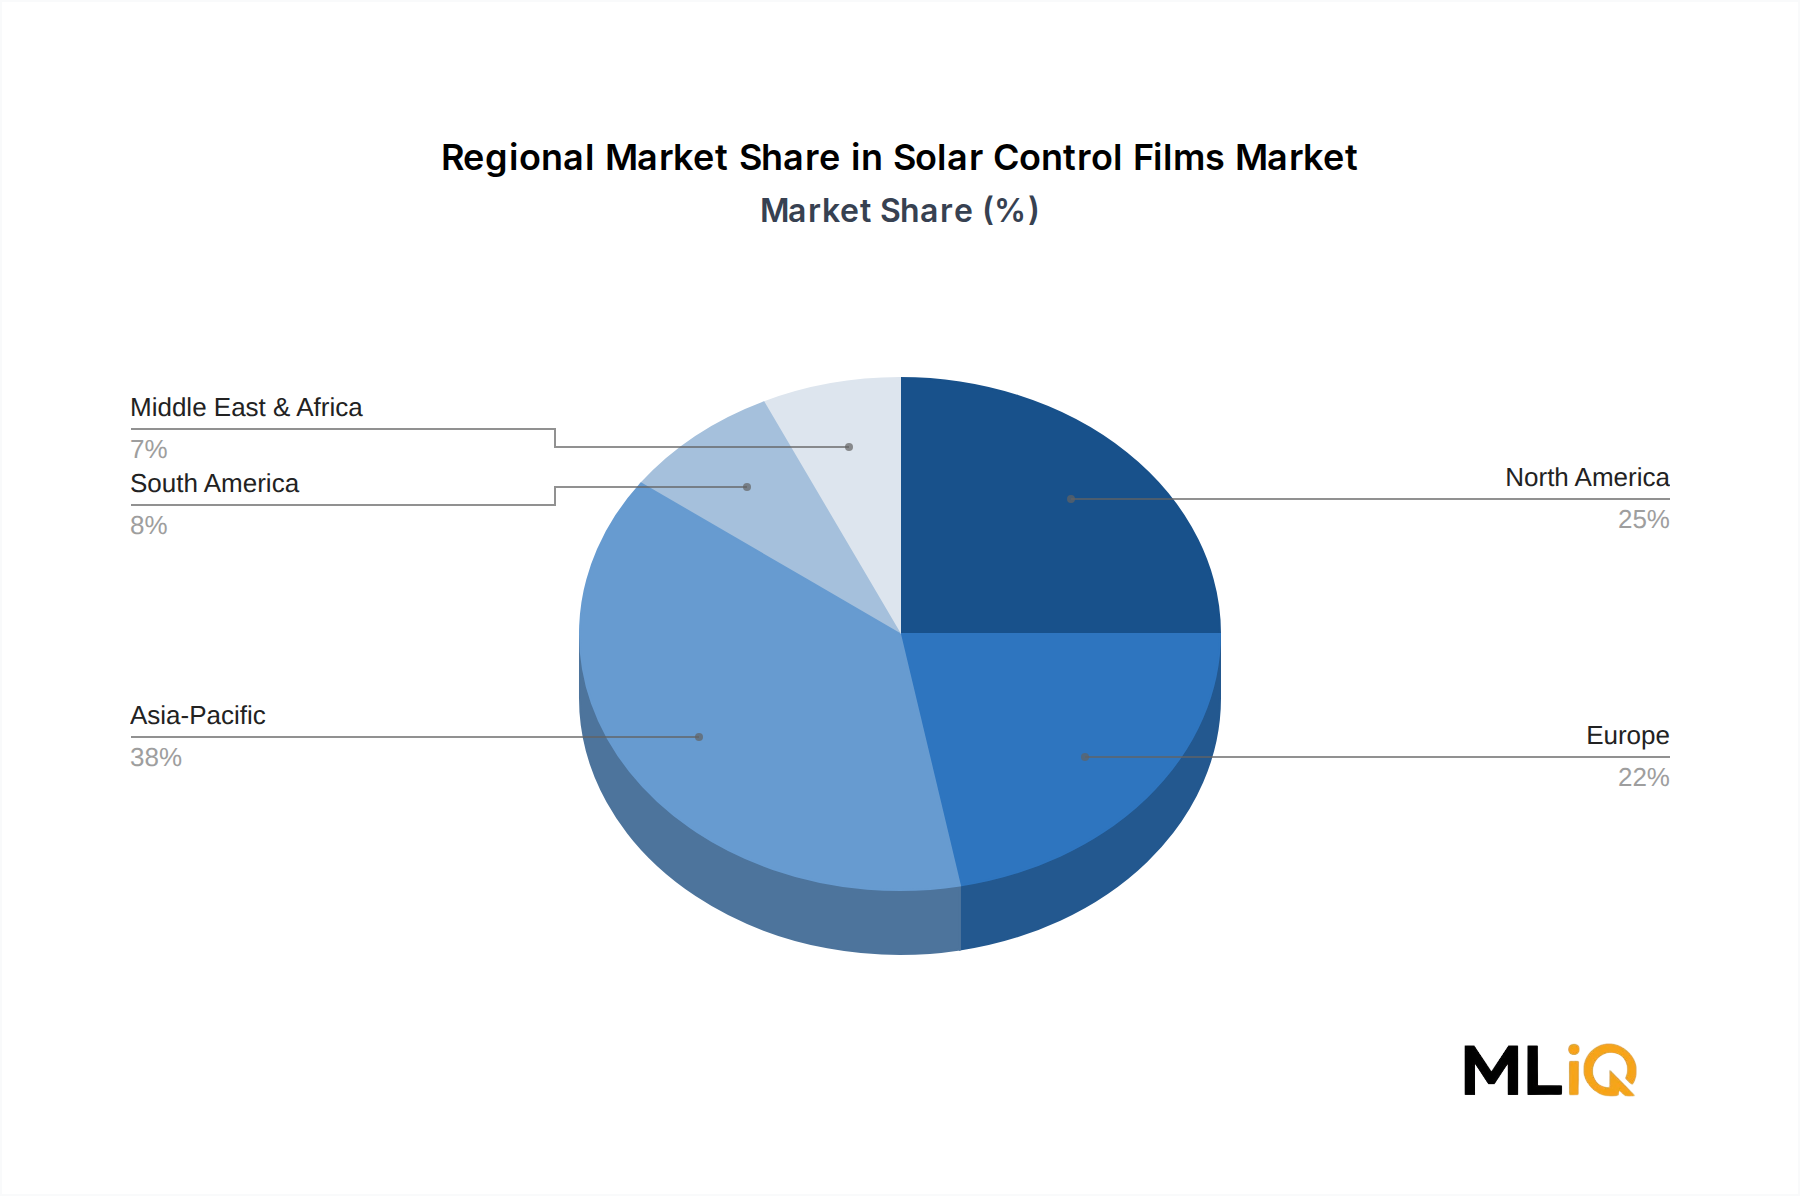
The Solar Control Films Market is positioned for steady expansion, driven by regulatory mandates for energy-efficient buildings and rising automotive production. The global market was valued at $7.3 billion in 2025 and is projected to reach $12.1 billion by 2033, registering a 5.6% CAGR. Asia-Pacific dominates with a 38% revenue share, fueled by rapid urbanization in China and India. The construction sector remains the largest application, accounting for 45% of total demand, as builders increasingly adopt films to meet green building standards.
Solar Control Films Market Size (In Billion)
15.0B
10.0B
5.0B
0
7.300 B
2025
7.709 B
2026
8.140 B
2027
8.596 B
2028
9.078 B
2029
9.586 B
2030
10.12 B
2031
Key growth drivers include stringent energy codes such as ASHRAE 90.1 and EU's Energy Performance of Buildings Directive. The automotive segment is gaining traction, with solar control films enhancing passenger comfort and reducing HVAC loads in electric vehicles. However, raw material price volatility and competition from low-cost alternatives pose restraints. The market is moderately consolidated, with top players like 3M and Saint-Gobain investing in R&D for advanced ceramic and nanostructured films. Overall, the outlook remains positive, with technological advancements and sustainability imperatives shaping demand.
Segment Deep-Dive: Construction Dominance in Solar Control Films Market
Application Segment Analysis
The construction sector dominates the Solar Control Films Market, representing 45% of global revenue in 2025. This segment is driven by retrofitting and new construction projects aiming for energy efficiency certifications (LEED, BREEAM). The Construction Solar Control Films Market is projected to grow at a 6.0% CAGR, outpacing the overall market. Sub-segments include architectural flat glass and automotive aftermarket, with the latter showing resilience.
Segment Analysis Matrix
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Construction
6.0%
45%
Green building regulations and retrofit activity
Automotive
5.2%
30%
Rising vehicle production and EV adoption
Marine & Others
4.8%
25%
Luxury yacht and specialty vehicle demand
Type and Absorber Dynamics
Among film types, Vacuum Coated Solar Control Films Market (reflective) holds the largest share at 50%, valued for superior heat rejection. Dyed films (non-reflective) are cost-effective but losing ground due to durability issues. Clear films (non-reflective) cater to residential applications. Absorber type is shifting from organic to inorganic and metallic, as metallic nanoparticles offer enhanced UV stability. The Metallic Nanoparticles Market is expanding at 7% annually, supporting film performance.
Margin Pressures
Manufacturers face margin pressure from rising costs of PET substrates and silver-based coatings. The PET Film Market has seen price increases of 8-10% since 2023, while metallic nanoparticle costs grew by 12%. To mitigate, firms are scaling production and negotiating long-term supply contracts. The Automotive Window Films Market remains competitive, with tier-1 suppliers demanding price concessions.
Primary Market Drivers & Growth Restraints in Solar Control Films Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Stringent building energy codes (e.g., ASHRAE 90.1, EU EPBD) mandating solar control in new constructions
High
Short term
Driver
Rapid EV production and consumer demand for cabin comfort, boosting automotive film installations
High
Medium term
Driver
Technological advancements in ceramic and nanostructured films, improving performance and durability
Medium
Long term
Restraint
Volatility in raw material prices (PET, silver, titanium) leading to margin erosion
High
Short term
Restraint
Competition from low-cost dyed films, especially in price-sensitive regions
Medium
Medium term
Restraint
Lack of awareness and skilled labor for proper film installation in emerging markets
Low
Long term
Quantitative evaluation: The global push for net-zero emissions has accelerated adoption, with over 60 countries enacting building efficiency standards. In the U.S., the Inflation Reduction Act provides tax incentives for energy-efficient retrofits, potentially adding $500 million in annual film demand. Conversely, raw material costs are squeezing margins; PET film prices rose by 9% in 2024, and silver nanoparticles by 15%. The Building & Construction Films Market is thus challenged by cost pass-through limits. However, innovation in Ceramic Window Films Market offers a premium avenue, with ceramic films priced 20-30% higher than conventional options, appealing to high-end projects.
Competitive Ecosystem & Key Vendor Profiles: Solar Control Films Market
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
3M
Advanced multi-layer optical films; strong R&D
Automotive OEMs, architectural
Leader
Saint-Gobain SA
Broad building materials portfolio; global distribution
3M: Maintains a dominant position with its Crystalline and Ceramic IR series. The company invests $1.8 billion annually in R&D, focusing on films that reject up to 97% of infrared light.
Saint-Gobain SA: Leverages its building materials ecosystem to cross-sell solar control films, particularly in Europe. Recent acquisition of a stake in a European film manufacturer strengthens its supply chain.
Solar Gard: Known for its Vortex and LX series, the company targets the automotive aftermarket with a network of 5,000+ installers globally.
Madico: Focuses on commercial and marine segments, offering films with 10-year warranties. Its competitive pricing strategy appeals to cost-conscious buyers.
Garware Suncontrol: Dominates the Indian market with a 35% share, expanding into Southeast Asia through partnerships with local distributors.
Guangdong New Vision Film Technology Co., Ltd: Operates one of the largest film manufacturing facilities in China, serving global OEMs with private-label products. The company's scale enables 15-20% cost advantage.
Strategic Milestones & Recent Developments in Solar Control Films Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Jan 2024
3M
Product Launch
Introduced ceramic-infused film for EVs, improving heat rejection by 20%
Mar 2024
Saint-Gobain
Partnership
Collaborated with a European glass fabricator to integrate films into smart windows
Jun 2024
Madico
M&A
Acquired a small U.S. film distributor to expand direct sales
Sep 2024
Garware Suncontrol
Capacity Expansion
Announced new production line in India, increasing output by 30%
Nov 2024
Guangdong New Vision
Product Launch
Released a new line of low-emissivity films for cold climates
January 2024: 3M launched its Ceramic IR 70 film, specifically designed for electric vehicle windows. The film reduces solar heat gain by 20% compared to previous generations, addressing EV range anxiety from HVAC loads.
March 2024: Saint-Gobain partnered with a major European glass fabricator to co-develop smart windows with integrated solar control films. The partnership targets commercial buildings aiming for net-zero certification.
June 2024: Madico acquired a U.S.-based distributor, strengthening its direct-to-installer channel and reducing reliance on third-party distribution.
September 2024: Garware Suncontrol expanded its Indian manufacturing capacity by 30%, anticipating growing domestic demand from automotive and construction sectors.
November 2024: Guangdong New Vision introduced a low-emissivity film for cold climates, expanding its product portfolio beyond solar control to thermal insulation.
Regional Market Analysis & Growth Corridors for Solar Control Films Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation ($B)
Primary Catalyst
Regulatory Stringency
North America
5.2%
1.83
Energy code adoption, EV production
High
Europe
5.0%
1.61
EU Green Deal, building retrofits
Very High
Asia-Pacific
6.8%
2.77
Urbanization, construction boom
Medium
South America
4.5%
0.58
Infrastructure investment, automotive growth
Low
Middle East & Africa
4.8%
0.51
Mega-projects, harsh climate
Medium
Asia-Pacific is the fastest-growing region, projected to expand at a 6.8% CAGR through 2033, driven by China's construction sector and India's automotive boom. The region accounted for $2.77 billion in 2025, or 38% of global value. China alone contributes 60% of regional demand, with films increasingly specified in green building projects. The Construction Solar Control Films Market in Asia-Pacific is set to benefit from government initiatives like China's 14th Five-Year Plan for energy efficiency.
North America and Europe are mature markets, growing at 5.2% and 5.0% respectively, but remain significant due to stringent regulations. Europe leads in regulatory stringency, with the Energy Performance of Buildings Directive driving retrofits. The Automotive Solar Control Films Market in North America is bolstered by EV tax credits and consumer preference for privacy and comfort. South America and MEA offer emerging opportunities, with Brazil and UAE investing in infrastructure. However, low awareness and price sensitivity constrain growth.
Customer Segmentation & Buying Behavior in Solar Control Films Market
Customer Segment
Primary Decision Criteria
Price Elasticity
Procurement Channel
Automotive OEMs
Heat rejection, durability, aesthetics
Low
Direct contracts with film manufacturers
Construction Contractors
Energy savings, certifications, cost
Medium
Distributors, building material suppliers
Residential Consumers
Privacy, UV protection, price
High
Retail stores, online marketplaces
Marine & Specialty
Corrosion resistance, custom sizes
Low
Specialty marine suppliers
Buyers are increasingly prioritizing performance metrics such as Total Solar Energy Rejected (TSER) and UV protection over upfront cost. The Automotive Window Films Market has seen a shift toward ceramic films, which offer superior heat rejection without interfering with electronics. Procurement channels are digitalizing: over 40% of residential buyers now purchase films online, influenced by DIY installation trends. However, complex installation requirements keep B2B channels dominant. Price elasticity varies; while residential demand is highly elastic, automotive OEMs exhibit low elasticity due to performance requirements. The Building & Construction Films Market is seeing growing demand for bundled services including installation and maintenance.
Sustainability, ESG & Decarbonization Pressures on Solar Control Films Market
ESG Factor
Impact on Film Manufacturers
Strategic Response
Circular Economy Mandates
Pressure to use recyclable PET and reduce solvent emissions
Developing bio-based films and closed-loop recycling
Net-Zero Targets
Demand for films that reduce building energy consumption
Promoting films as carbon reduction tools (LEED credits)
ESG Investor Criteria
Scrutiny on supply chain transparency and carbon footprint
Investing in renewable energy and supplier audits
Environmental regulations are reshaping the Solar Control Films Market. The EU's Circular Economy Action Plan mandates higher recyclability, pushing manufacturers to develop PET films with 30% recycled content. Net-zero commitments drive demand for films that improve building energy efficiency, with studies showing solar control films can reduce cooling loads by 15-25%. ESG investors increasingly evaluate companies on scope 3 emissions, prompting firms like 3M and Saint-Gobain to publish lifecycle assessments. The Window Films Market is benefiting from green building certifications such as LEED v4.1, which award points for solar control. However, the shift to sustainable materials may increase costs by 10-15%, requiring manufacturers to balance environmental goals with competitiveness.
Solar Control Films Market Segmentation
1. Type
1.1. Clear (Non-Reflective
2. Dyed
2.1. Non-Reflective
3. Vacuum coated
3.1. Reflective
4. Application
4.1. Automotive
4.2. Construction
4.3. Marine
4.4. Decorative
4.5. Others
5. Absorber Type
5.1. Organic
5.2. Inorganic
5.3. Metallic
Solar Control Films Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Solar Control Films Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.6% from 2020-2034
Segmentation
By Type
Clear (Non-Reflective
By Dyed
Non-Reflective
By Vacuum coated
Reflective
By Application
Automotive
Construction
Marine
Decorative
Others
By Absorber Type
Organic
Inorganic
Metallic
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Clear (Non-Reflective
5.2. Market Analysis, Insights and Forecast - by Dyed
5.2.1. Non-Reflective
5.3. Market Analysis, Insights and Forecast - by Vacuum coated
5.3.1. Reflective
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Automotive
5.4.2. Construction
5.4.3. Marine
5.4.4. Decorative
5.4.5. Others
5.5. Market Analysis, Insights and Forecast - by Absorber Type
5.5.1. Organic
5.5.2. Inorganic
5.5.3. Metallic
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. South America
5.6.3. Europe
5.6.4. Middle East & Africa
5.6.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Clear (Non-Reflective
6.2. Market Analysis, Insights and Forecast - by Dyed
6.2.1. Non-Reflective
6.3. Market Analysis, Insights and Forecast - by Vacuum coated
6.3.1. Reflective
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Automotive
6.4.2. Construction
6.4.3. Marine
6.4.4. Decorative
6.4.5. Others
6.5. Market Analysis, Insights and Forecast - by Absorber Type
6.5.1. Organic
6.5.2. Inorganic
6.5.3. Metallic
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Clear (Non-Reflective
7.2. Market Analysis, Insights and Forecast - by Dyed
7.2.1. Non-Reflective
7.3. Market Analysis, Insights and Forecast - by Vacuum coated
7.3.1. Reflective
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Automotive
7.4.2. Construction
7.4.3. Marine
7.4.4. Decorative
7.4.5. Others
7.5. Market Analysis, Insights and Forecast - by Absorber Type
7.5.1. Organic
7.5.2. Inorganic
7.5.3. Metallic
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Clear (Non-Reflective
8.2. Market Analysis, Insights and Forecast - by Dyed
8.2.1. Non-Reflective
8.3. Market Analysis, Insights and Forecast - by Vacuum coated
8.3.1. Reflective
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Automotive
8.4.2. Construction
8.4.3. Marine
8.4.4. Decorative
8.4.5. Others
8.5. Market Analysis, Insights and Forecast - by Absorber Type
8.5.1. Organic
8.5.2. Inorganic
8.5.3. Metallic
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Clear (Non-Reflective
9.2. Market Analysis, Insights and Forecast - by Dyed
9.2.1. Non-Reflective
9.3. Market Analysis, Insights and Forecast - by Vacuum coated
9.3.1. Reflective
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Automotive
9.4.2. Construction
9.4.3. Marine
9.4.4. Decorative
9.4.5. Others
9.5. Market Analysis, Insights and Forecast - by Absorber Type
9.5.1. Organic
9.5.2. Inorganic
9.5.3. Metallic
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Clear (Non-Reflective
10.2. Market Analysis, Insights and Forecast - by Dyed
10.2.1. Non-Reflective
10.3. Market Analysis, Insights and Forecast - by Vacuum coated
10.3.1. Reflective
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Automotive
10.4.2. Construction
10.4.3. Marine
10.4.4. Decorative
10.4.5. Others
10.5. Market Analysis, Insights and Forecast - by Absorber Type
10.5.1. Organic
10.5.2. Inorganic
10.5.3. Metallic
11. Competitive Analysis
11.1. Company Profiles
11.1.1. 3M
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Recon Blinds
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Guangdong New Vision Film Technology Co.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Ltd
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Solar Gard
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Madico
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Recon Blinds.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Garware Suncontrol
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Saint-Gobain SA
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Jupiter International
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Solar Control Films Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Solar Control Films Market Revenue (billion), by Type 2026 & 2034
Figure 3: North America Solar Control Films Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Solar Control Films Market Revenue (billion), by Dyed 2026 & 2034
Figure 5: North America Solar Control Films Market Revenue Share (%), by Dyed 2026 & 2034
Figure 6: North America Solar Control Films Market Revenue (billion), by Vacuum coated 2026 & 2034
Figure 7: North America Solar Control Films Market Revenue Share (%), by Vacuum coated 2026 & 2034
Figure 8: North America Solar Control Films Market Revenue (billion), by Application 2026 & 2034
Figure 9: North America Solar Control Films Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Solar Control Films Market Revenue (billion), by Absorber Type 2026 & 2034
Figure 11: North America Solar Control Films Market Revenue Share (%), by Absorber Type 2026 & 2034
Figure 12: North America Solar Control Films Market Revenue (billion), by Country 2026 & 2034
Figure 13: North America Solar Control Films Market Revenue Share (%), by Country 2026 & 2034
Figure 14: South America Solar Control Films Market Revenue (billion), by Type 2026 & 2034
Figure 15: South America Solar Control Films Market Revenue Share (%), by Type 2026 & 2034
Figure 16: South America Solar Control Films Market Revenue (billion), by Dyed 2026 & 2034
Figure 17: South America Solar Control Films Market Revenue Share (%), by Dyed 2026 & 2034
Figure 18: South America Solar Control Films Market Revenue (billion), by Vacuum coated 2026 & 2034
Figure 19: South America Solar Control Films Market Revenue Share (%), by Vacuum coated 2026 & 2034
Figure 20: South America Solar Control Films Market Revenue (billion), by Application 2026 & 2034
Figure 21: South America Solar Control Films Market Revenue Share (%), by Application 2026 & 2034
Figure 22: South America Solar Control Films Market Revenue (billion), by Absorber Type 2026 & 2034
Figure 23: South America Solar Control Films Market Revenue Share (%), by Absorber Type 2026 & 2034
Figure 24: South America Solar Control Films Market Revenue (billion), by Country 2026 & 2034
Figure 25: South America Solar Control Films Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Europe Solar Control Films Market Revenue (billion), by Type 2026 & 2034
Figure 27: Europe Solar Control Films Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Europe Solar Control Films Market Revenue (billion), by Dyed 2026 & 2034
Figure 29: Europe Solar Control Films Market Revenue Share (%), by Dyed 2026 & 2034
Figure 30: Europe Solar Control Films Market Revenue (billion), by Vacuum coated 2026 & 2034
Figure 31: Europe Solar Control Films Market Revenue Share (%), by Vacuum coated 2026 & 2034
Figure 32: Europe Solar Control Films Market Revenue (billion), by Application 2026 & 2034
Figure 33: Europe Solar Control Films Market Revenue Share (%), by Application 2026 & 2034
Figure 34: Europe Solar Control Films Market Revenue (billion), by Absorber Type 2026 & 2034
Figure 35: Europe Solar Control Films Market Revenue Share (%), by Absorber Type 2026 & 2034
Figure 36: Europe Solar Control Films Market Revenue (billion), by Country 2026 & 2034
Figure 37: Europe Solar Control Films Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Middle East & Africa Solar Control Films Market Revenue (billion), by Type 2026 & 2034
Figure 39: Middle East & Africa Solar Control Films Market Revenue Share (%), by Type 2026 & 2034
Figure 40: Middle East & Africa Solar Control Films Market Revenue (billion), by Dyed 2026 & 2034
Figure 41: Middle East & Africa Solar Control Films Market Revenue Share (%), by Dyed 2026 & 2034
Figure 42: Middle East & Africa Solar Control Films Market Revenue (billion), by Vacuum coated 2026 & 2034
Figure 43: Middle East & Africa Solar Control Films Market Revenue Share (%), by Vacuum coated 2026 & 2034
Figure 44: Middle East & Africa Solar Control Films Market Revenue (billion), by Application 2026 & 2034
Figure 45: Middle East & Africa Solar Control Films Market Revenue Share (%), by Application 2026 & 2034
Figure 46: Middle East & Africa Solar Control Films Market Revenue (billion), by Absorber Type 2026 & 2034
Figure 47: Middle East & Africa Solar Control Films Market Revenue Share (%), by Absorber Type 2026 & 2034
Figure 48: Middle East & Africa Solar Control Films Market Revenue (billion), by Country 2026 & 2034
Figure 49: Middle East & Africa Solar Control Films Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Asia Pacific Solar Control Films Market Revenue (billion), by Type 2026 & 2034
Figure 51: Asia Pacific Solar Control Films Market Revenue Share (%), by Type 2026 & 2034
Figure 52: Asia Pacific Solar Control Films Market Revenue (billion), by Dyed 2026 & 2034
Figure 53: Asia Pacific Solar Control Films Market Revenue Share (%), by Dyed 2026 & 2034
Figure 54: Asia Pacific Solar Control Films Market Revenue (billion), by Vacuum coated 2026 & 2034
Figure 55: Asia Pacific Solar Control Films Market Revenue Share (%), by Vacuum coated 2026 & 2034
Figure 56: Asia Pacific Solar Control Films Market Revenue (billion), by Application 2026 & 2034
Figure 57: Asia Pacific Solar Control Films Market Revenue Share (%), by Application 2026 & 2034
Figure 58: Asia Pacific Solar Control Films Market Revenue (billion), by Absorber Type 2026 & 2034
Figure 59: Asia Pacific Solar Control Films Market Revenue Share (%), by Absorber Type 2026 & 2034
Figure 60: Asia Pacific Solar Control Films Market Revenue (billion), by Country 2026 & 2034
Figure 61: Asia Pacific Solar Control Films Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Solar Control Films Market Revenue billion Forecast, by Type 2020 & 2034
Table 2: Solar Control Films Market Revenue billion Forecast, by Dyed 2020 & 2034
Table 3: Solar Control Films Market Revenue billion Forecast, by Vacuum coated 2020 & 2034
Table 4: Solar Control Films Market Revenue billion Forecast, by Application 2020 & 2034
Table 5: Solar Control Films Market Revenue billion Forecast, by Absorber Type 2020 & 2034
Table 6: Solar Control Films Market Revenue billion Forecast, by Region 2020 & 2034
Table 7: North America Solar Control Films Market Revenue billion Forecast, by Type 2020 & 2034
Table 8: North America Solar Control Films Market Revenue billion Forecast, by Dyed 2020 & 2034
Table 9: North America Solar Control Films Market Revenue billion Forecast, by Vacuum coated 2020 & 2034
Table 10: North America Solar Control Films Market Revenue billion Forecast, by Application 2020 & 2034
Table 11: North America Solar Control Films Market Revenue billion Forecast, by Absorber Type 2020 & 2034
Table 12: North America Solar Control Films Market Revenue billion Forecast, by Country 2020 & 2034
Table 13: United States Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 14: Canada Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 16: South America Solar Control Films Market Revenue billion Forecast, by Type 2020 & 2034
Table 17: South America Solar Control Films Market Revenue billion Forecast, by Dyed 2020 & 2034
Table 18: South America Solar Control Films Market Revenue billion Forecast, by Vacuum coated 2020 & 2034
Table 19: South America Solar Control Films Market Revenue billion Forecast, by Application 2020 & 2034
Table 20: South America Solar Control Films Market Revenue billion Forecast, by Absorber Type 2020 & 2034
Table 21: South America Solar Control Films Market Revenue billion Forecast, by Country 2020 & 2034
Table 22: Brazil Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 23: Argentina Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Rest of South America Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 25: Europe Solar Control Films Market Revenue billion Forecast, by Type 2020 & 2034
Table 26: Europe Solar Control Films Market Revenue billion Forecast, by Dyed 2020 & 2034
Table 27: Europe Solar Control Films Market Revenue billion Forecast, by Vacuum coated 2020 & 2034
Table 28: Europe Solar Control Films Market Revenue billion Forecast, by Application 2020 & 2034
Table 29: Europe Solar Control Films Market Revenue billion Forecast, by Absorber Type 2020 & 2034
Table 30: Europe Solar Control Films Market Revenue billion Forecast, by Country 2020 & 2034
Table 31: United Kingdom Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Germany Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 33: France Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 34: Italy Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 35: Spain Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 36: Russia Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: Benelux Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: Nordics Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: Rest of Europe Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: Middle East & Africa Solar Control Films Market Revenue billion Forecast, by Type 2020 & 2034
Table 41: Middle East & Africa Solar Control Films Market Revenue billion Forecast, by Dyed 2020 & 2034
Table 42: Middle East & Africa Solar Control Films Market Revenue billion Forecast, by Vacuum coated 2020 & 2034
Table 43: Middle East & Africa Solar Control Films Market Revenue billion Forecast, by Application 2020 & 2034
Table 44: Middle East & Africa Solar Control Films Market Revenue billion Forecast, by Absorber Type 2020 & 2034
Table 45: Middle East & Africa Solar Control Films Market Revenue billion Forecast, by Country 2020 & 2034
Table 46: Turkey Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 47: Israel Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 48: GCC Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 49: North Africa Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 50: South Africa Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 51: Rest of Middle East & Africa Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Asia Pacific Solar Control Films Market Revenue billion Forecast, by Type 2020 & 2034
Table 53: Asia Pacific Solar Control Films Market Revenue billion Forecast, by Dyed 2020 & 2034
Table 54: Asia Pacific Solar Control Films Market Revenue billion Forecast, by Vacuum coated 2020 & 2034
Table 55: Asia Pacific Solar Control Films Market Revenue billion Forecast, by Application 2020 & 2034
Table 56: Asia Pacific Solar Control Films Market Revenue billion Forecast, by Absorber Type 2020 & 2034
Table 57: Asia Pacific Solar Control Films Market Revenue billion Forecast, by Country 2020 & 2034
Table 58: China Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 59: India Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 60: Japan Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 61: South Korea Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 62: ASEAN Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 63: Oceania Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 64: Rest of Asia Pacific Solar Control Films Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% of total research through primary interviews with industry experts across the value chain.
Interviewed specific company types: Solar control film manufacturers and OEMs, automotive OEMs and tier-1 suppliers, construction contractors and architects, raw material suppliers (PET film, metallic nanoparticles), and distributors and installers.
Interviewed specific job titles: Procurement Director for Automotive Glazing, Construction Project Manager, R&D Manager for Advanced Films, Sales Director for Building Materials.
Consulted key industry associations and regulatory bodies: International Window Film Association (IWFA), American Society of Heating, Refrigerating and Air-Conditioning Engineers (ASHRAE), European Commission's Energy Performance of Buildings Directive (EPBD), U.S. Department of Energy (DOE) Building Technologies Office.
Data accuracy level guaranteed at 85–90%.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Product Manager
25%
R&D Manager
15%
Sales Director
20%
Operations Manager
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Solar Control Film Manufacturers
40%
Automotive OEMs & Tier-1 Suppliers
20%
Construction Contractors & Architects
15%
Raw Material Suppliers
15%
Distributors & Installers
10%
Secondary Research & Industry Benchmarking
20–30% of research derived from secondary sources including Bloomberg, Factiva, Hoovers, and PitchBook for financial and company data.
Utilized .gov, .org, and trade association sources such as the U.S. Department of Energy (energy.gov), European Commission (europa.eu), and International Window Film Association (iwfa.com).
Benchmarked against historical data and industry reports to validate primary findings.
All reports are updated to the date of purchase to ensure currency.
Demand Modeling & Market Estimation
Employed both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up quantitative metrics: number of new building permits issued annually, average square footage of film installed per vehicle, automotive production volumes by region, average price per square foot of film by type.
Top-down approach utilized regional construction spending and automotive sales data to estimate total addressable market.
Cross-verified results with supply-side production capacity and import/export data.
Data Accuracy & Quality Check
Multi-level triangulation across primary interviews, secondary databases, and demand models ensures high reliability.
Estimated data accuracy level of 85–90% with a confidence interval of ±5%.
Regular calibration against actual sales data from key manufacturers and distributors.
Reports are updated to the date of purchase, incorporating latest market developments.
Frequently Asked Questions
1. What is the current market size and projected growth rate of the Solar Control Films Market?
The global Solar Control Films Market was valued at $7.3 billion in 2025 and is projected to reach $12.1 billion by 2033, growing at a CAGR of 5.6%. Growth is driven by increasing demand for energy-efficient building solutions and automotive window films. The construction sector accounts for the largest share, followed by automotive applications.
2. How are pricing trends and cost structures evolving in the Solar Control Films Market?
Pricing for solar control films varies by type, with vacuum-coated reflective films commanding premium prices (e.g., $8–$12 per square foot) compared to dyed films ($3–$5 per square foot). Raw material costs, particularly for metallic absorbers and PET substrates, have risen by 8-10% annually since 2023, squeezing manufacturer margins. Manufacturers are offsetting costs through automation and scale.
3. Which region is expected to be the fastest-growing in the Solar Control Films Market?
Asia-Pacific is the fastest-growing region, projected to expand at a CAGR of 6.8% from 2025 to 2033, driven by rapid urbanization and construction booms in China and India. The region is expected to account for over 40% of global market value by 2033. Emerging opportunities exist in Southeast Asia and the Middle East.
4. Who are the leading companies in the Solar Control Films Market and what is the competitive landscape?
Key players include 3M, Saint-Gobain SA, Solar Gard, Madico, and Garware Suncontrol. The market is moderately consolidated, with the top five companies holding approximately 55% of global market share. Competition is intense, with frequent product launches and strategic partnerships.
5. What recent developments, M&A activity, or product launches have occurred in the Solar Control Films Market?
In 2024, 3M launched a new line of ceramic-infused solar control films for automotive applications, enhancing heat rejection by 20%. Saint-Gobain acquired a minority stake in a European film manufacturer to expand its footprint. Additionally, Madico partnered with a major automotive OEM to supply films for electric vehicle windows.
6. What are the key raw material sourcing and supply chain considerations for Solar Control Films?
Key raw materials include PET film, metallic nanoparticles (e.g., silver, titanium), and dyes. Supply chains are concentrated in Asia, with China and South Korea dominating PET film production. Recent disruptions have led to 15-20% price volatility, prompting manufacturers to diversify suppliers and increase inventory buffers.