Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Superconducting Magnetic Energy Storage by Type Market 2033
Superconducting Magnetic Energy Storage System market by Type
Superconducting Magnetic Energy Storage by Type Market 2033
Superconducting Magnetic Energy Storage System market by Type by Type (Low Temperature, High Temperature), by Application (Power System, Industrial Use, Research Institution, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 12, 2026|Base Year : 2025|Pages : 0
Key Insights & Executive Summary: Superconducting Magnetic Energy Storage System market by Type
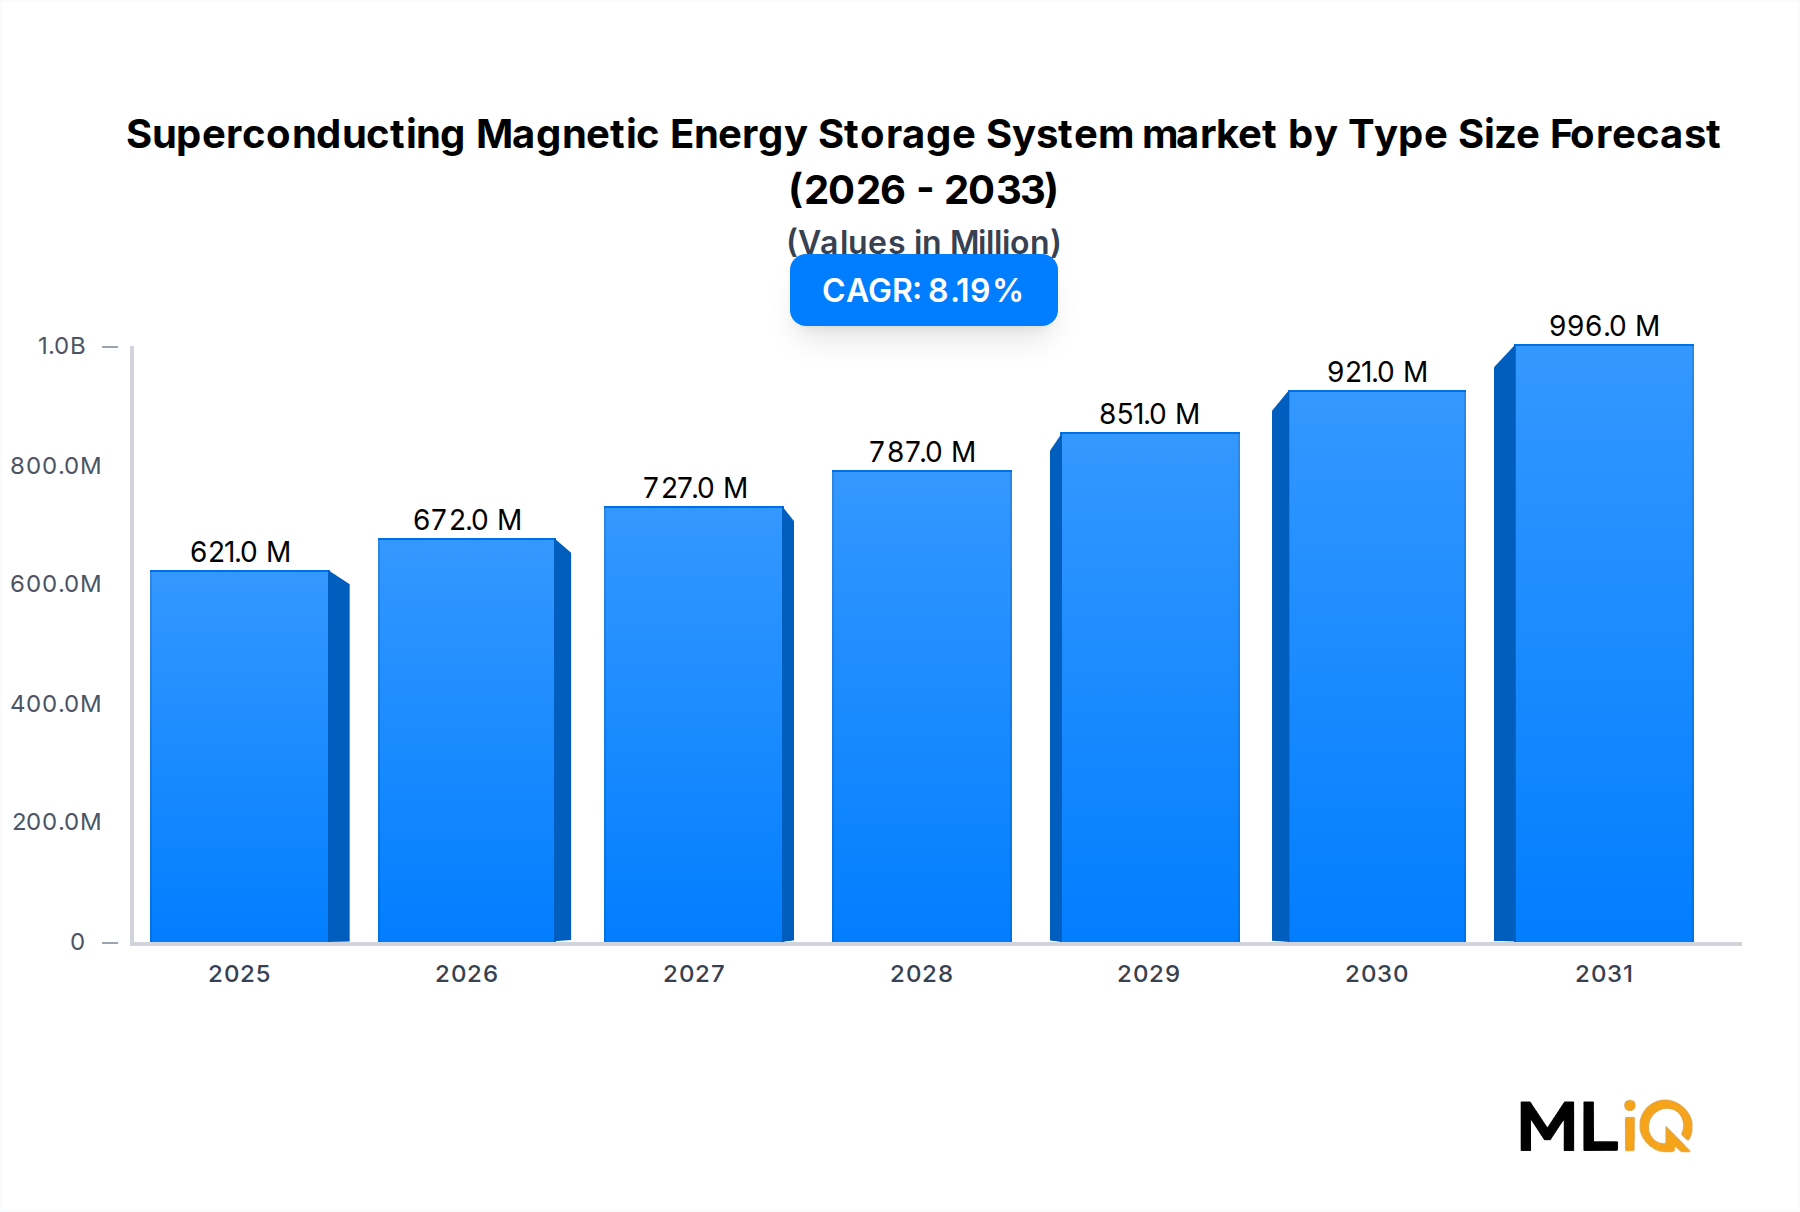
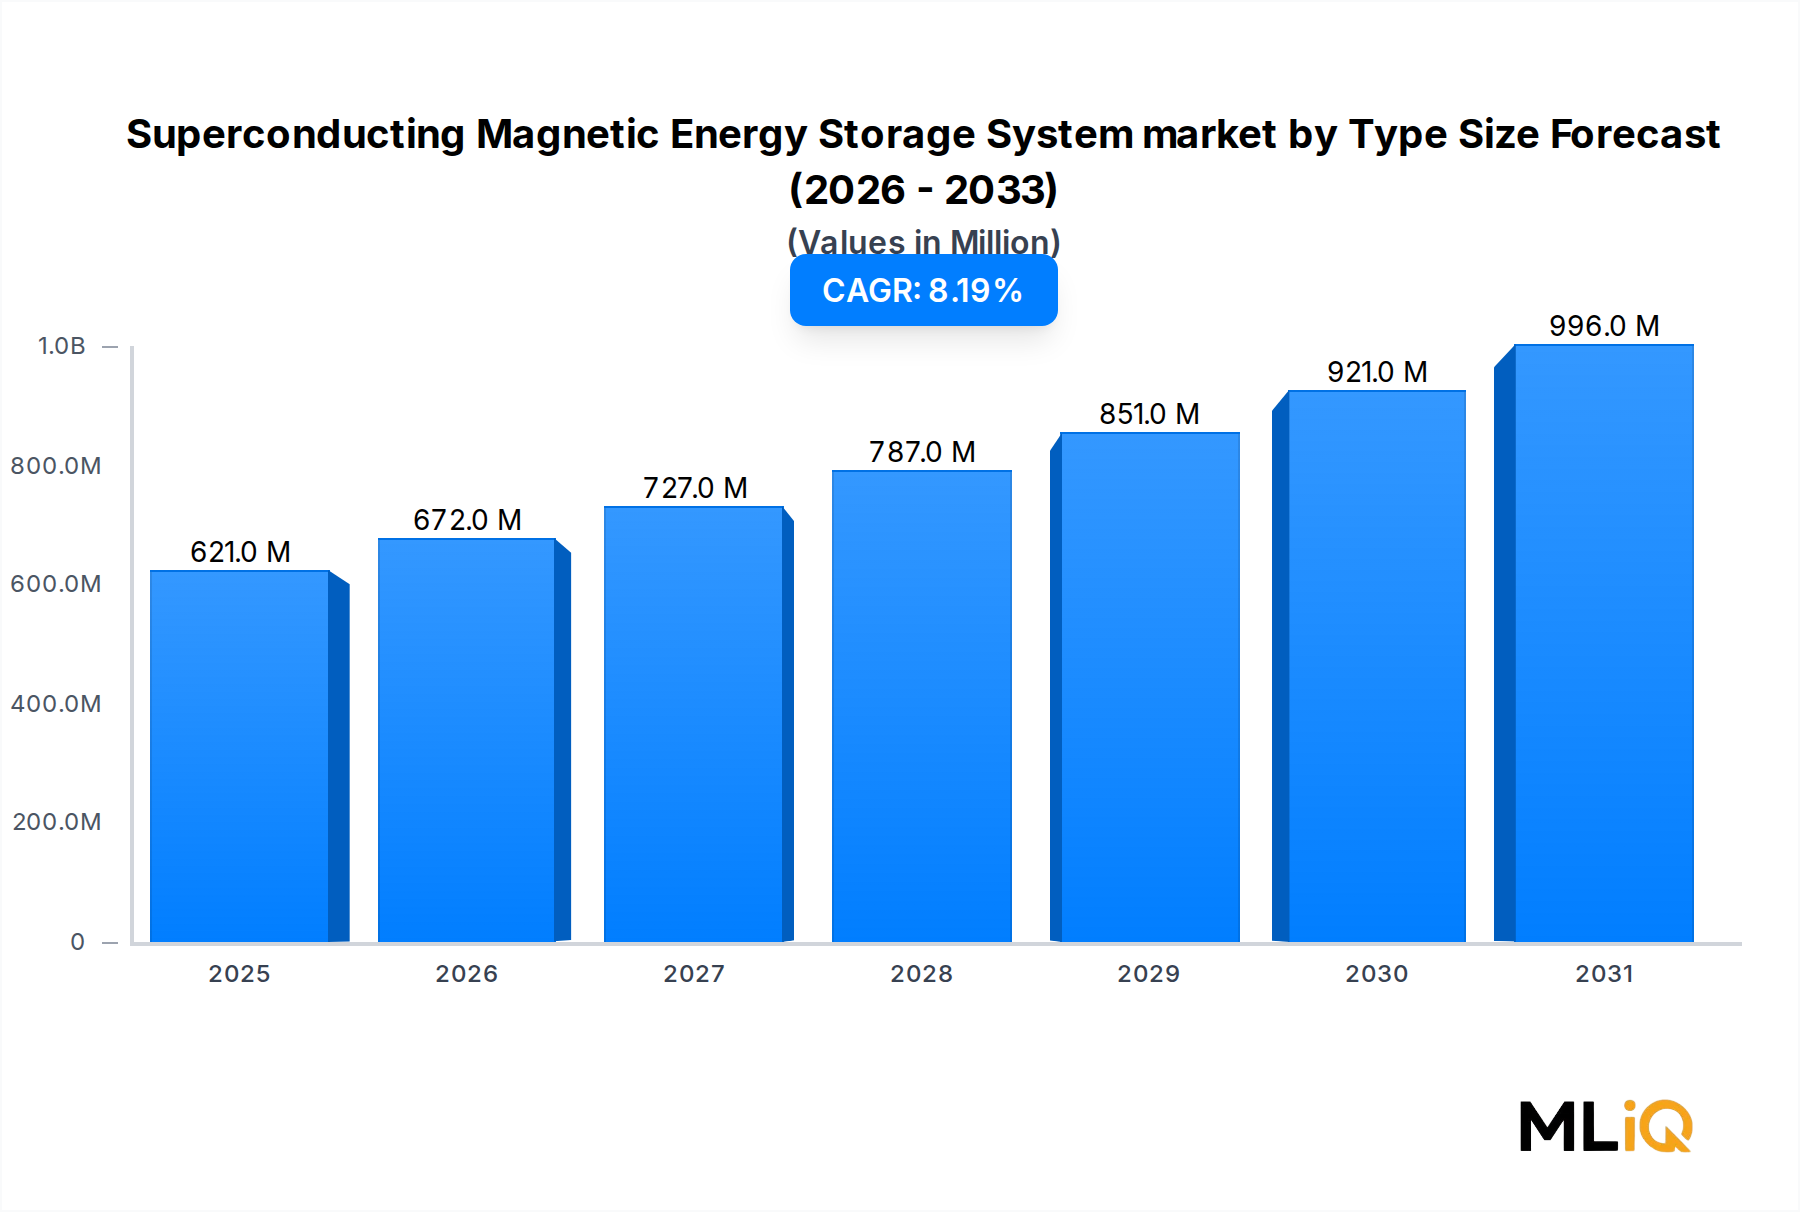
Superconducting Magnetic Energy Storage System by Type Market Size (In Million)
1.0B
800.0M
600.0M
400.0M
200.0M
0
621.0 M
2025
672.0 M
2026
727.0 M
2027
787.0 M
2028
851.0 M
2029
921.0 M
2030
996.0 M
2031
Market at a Glance
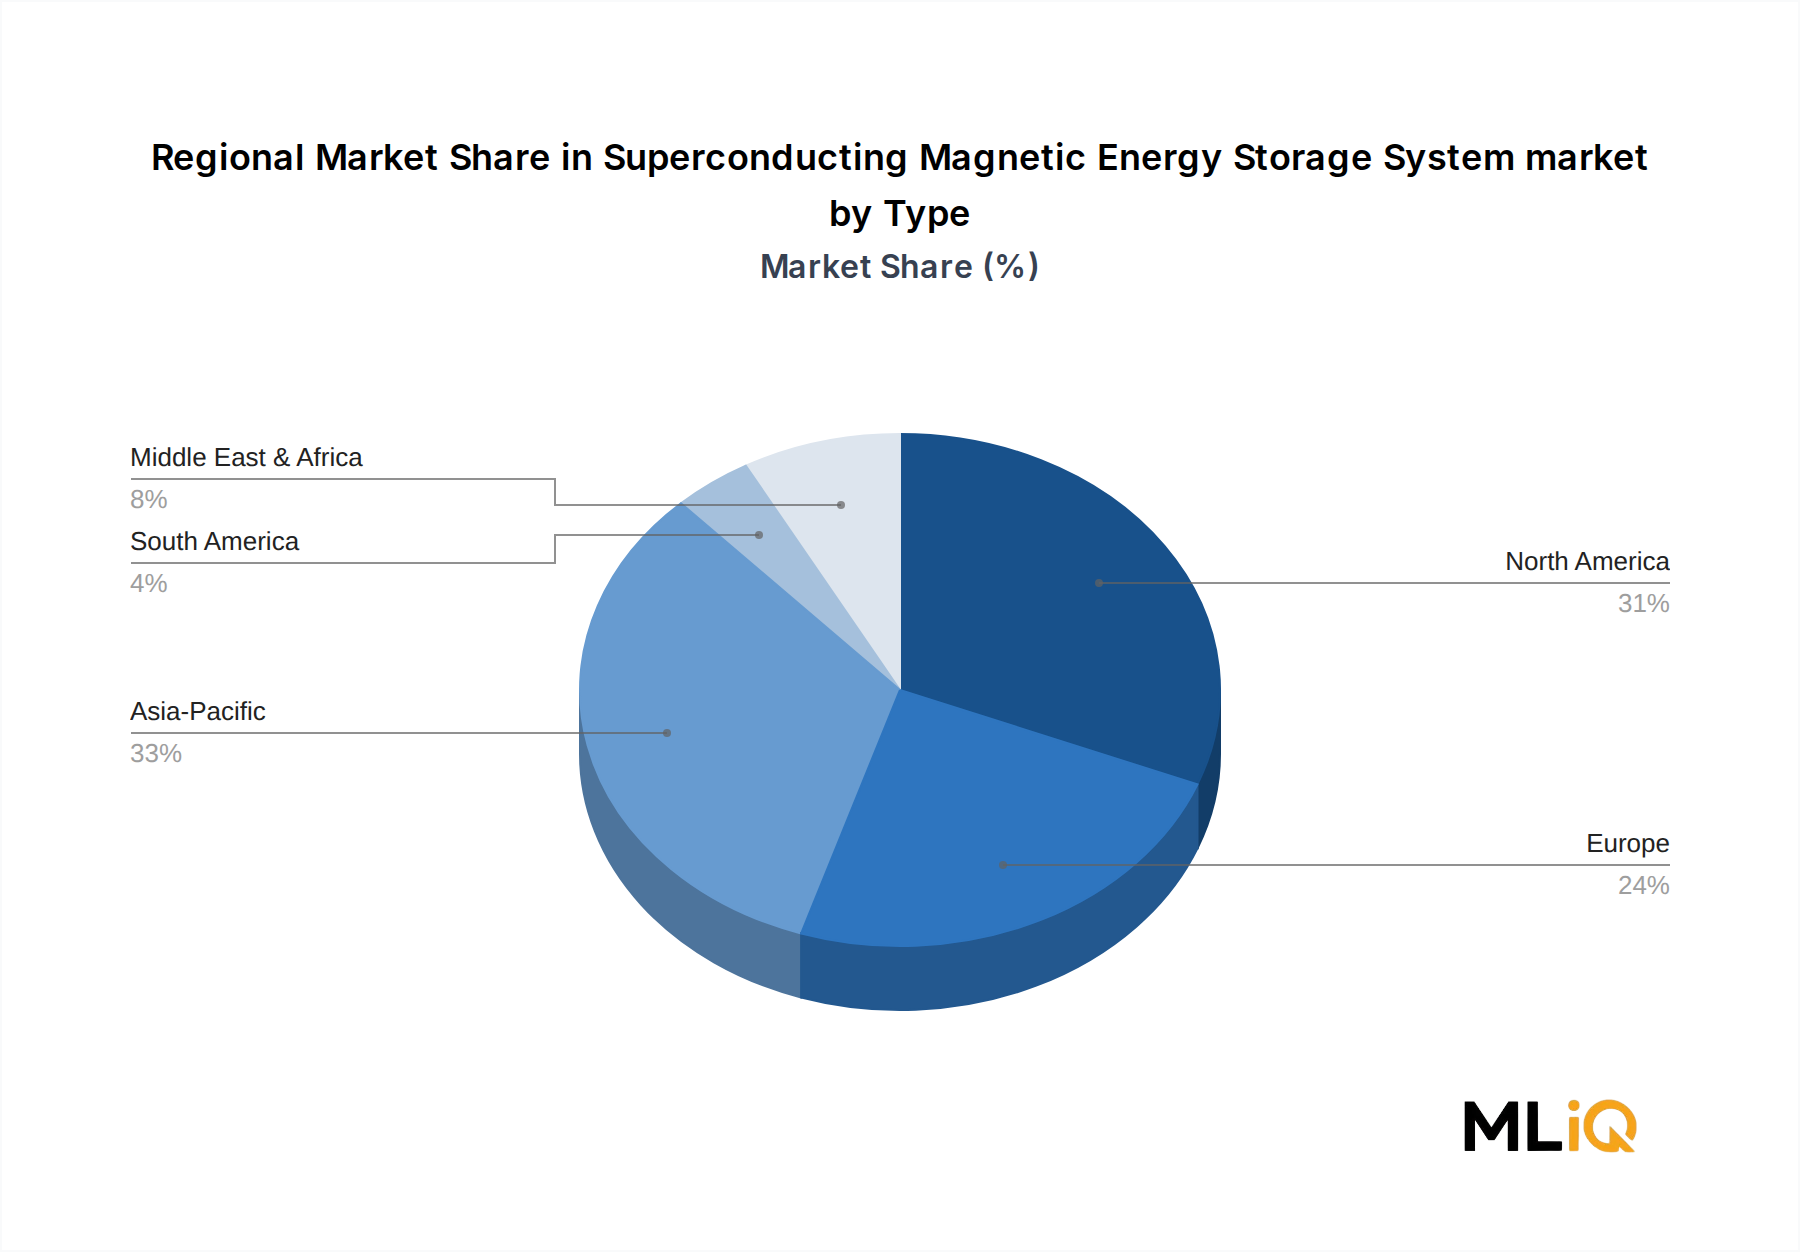
The Superconducting Magnetic Energy Storage System market by Type is valued at $621.3 million in 2025 and is projected to reach $1,165.5 million by 2033, advancing at a 8.18% CAGR. The market remains niche relative to lithium-ion and flow batteries, yet its millisecond response time and near-infinite cycle life create defensible demand in grid stability and power quality applications. Asia-Pacific controls 33.0% of global revenue, supported by China’s utility-scale demonstration projects and Japan’s HTS wire manufacturing base. North America follows at 31.0%, while Europe holds 24.0%; South America and Middle East & Africa collectively represent 12.0%. The broader Superconducting Magnetic Energy Storage Market is shifting from research procurement to commercial grid services, with Low Temperature systems accounting for 64.0% of installed capacity. High Temperature systems are smaller in volume but growing at 9.4% CAGR as coated conductor prices fall. Key demand catalysts include renewable curtailment reduction, transmission congestion relief, and high-value industrial power conditioning. Restraints include cryogenic cooling complexity, helium supply volatility, and capital costs exceeding $2.5 million per MW for turnkey SMES installations. The forecast window sees incremental capacity additions of 180–220 MW globally, concentrated in frequency regulation and voltage support. Strategic attention is moving toward modular designs that lower installation costs by 15–20% and hybrid systems pairing SMES with batteries for bulk energy shifting. The market’s small base means each 10 MW project can shift regional share by 1–2 percentage points.
Segment Deep-Dive: Low Temperature Dominance in Superconducting Magnetic Energy Storage System market by Type
Segment Analysis Matrix
Segment
CAGR (%)
Market Share (%)
Key Demand Driver
Low Temperature
7.6
64.0
Grid-scale frequency regulation and UPS backup
High Temperature
9.4
36.0
Lower HTS tape cost and higher operating temperature
Application: Power System
8.9
48.0
Renewable integration and transmission deferral
Low Temperature SMES Market remains the revenue anchor, capturing 64.0% of 2025 global revenue. These systems use niobium-titanium (NbTi) coils cooled by liquid helium to 4.2 K, delivering high current density and mature manufacturing yields. Demand concentrates in Power System and Industrial Use applications where response time below 5 milliseconds justifies premium pricing. Utilities in Japan and the United States operate low-temperature SMES for frequency regulation, while industrial facilities use them to protect sensitive manufacturing lines from voltage sags. The segment faces margin pressure from helium price volatility, which rose 18% between 2022 and 2024, and from competition with lithium-ion systems for shorter-duration backup.
High Temperature Momentum
High Temperature SMES Market is the faster-growing type, expanding at 9.4% CAGR from a smaller base. HTS coated conductors, primarily rare-earth barium copper oxide (ReBCO) tapes, operate at 20–77 K, reducing cryogenic load and enabling smaller footprints. This makes high-temperature SMES attractive for Research Institution Energy Storage Market projects and urban substations with space constraints. Cost reductions in HTS tape, down 35% since 2020, are the primary driver, though tape still accounts for 40–50% of system bill of materials. Vendors such as American Superconductor and FujikuraCG are expanding HTS wire capacity, which should lower system prices by 10–15% by 2028.
Application Sub-Segment Dynamics
Power System: 48.0% of demand; driven by renewable integration, transmission deferral, and grid frequency regulation.
Industrial Use: 27.0% of demand; focused on power quality for semiconductor, data center, and heavy manufacturing operations.
Research Institution: 18.0% of demand; funded by national laboratories and university fusion or physics programs.
Others: 7.0% of demand; includes military, aerospace, and medical imaging niche applications.
Margin Pressures
Gross margins for SMES system integrators range from 22% to 30%, lower than typical power electronics peers due to cryogenic assembly and testing. Low Temperature systems carry higher helium-related operating costs, while High Temperature systems face elevated HTS tape input costs. Integrators with in-house coil winding and cryostat manufacturing sustain 5–8 percentage points higher margins than assembly-only vendors.
Primary Market Drivers & Growth Restraints in Superconducting Magnetic Energy Storage System market by Type
Factor Type
Description
Impact Level
Timeline
Driver
Grid Stability Energy Storage Market demand for sub-5 ms response and 100,000+ cycles
High
Short term
Driver
Renewable portfolio standards requiring fast frequency regulation
High
Short term
Driver
HTS tape cost decline of 35% since 2020 enabling High Temperature systems
Medium
Long term
Driver
Government funding for grid modernization and SMES pilots
Medium
Short term
Restraint
Capital cost above $2.5 million per MW for turnkey systems
High
Long term
Restraint
Helium supply volatility and cryogenic maintenance complexity
High
Short term
Restraint
Limited vendor base for HTS wire and cryostats
Medium
Long term
The Power System Energy Storage Market provides the strongest pull for SMES, as grid operators need assets that can inject real power within milliseconds. In the United States, FERC Order 755 and subsequent market rules compensate fast-ramping regulation resources, improving SMES project economics by 12–18% in organized markets. China’s State Grid has funded MW-scale SMES demonstrations, while Japan’s NEDO supports HTS coil development. Industrial Energy Storage Market buyers, particularly semiconductor fabs and data centers, adopt SMES to avoid production losses that can exceed $500,000 per voltage sag event. On the restraint side, lithium-ion battery costs below $150 per kWh make SMES uncompetitive for energy shifting beyond a few seconds. Cryogenic cooling systems also require specialized maintenance, and helium price spikes add 8–12% to annual operating expenses. Regulatory approval for grid interconnection can take 12–18 months, slowing revenue recognition for smaller vendors. High Temperature systems reduce cooling loads but remain dependent on a concentrated HTS tape supply chain. Overall, drivers outweigh restraints for short-duration, high-value applications, but mass adoption requires further cost reduction and standardization.
Competitive Ecosystem & Key Vendor Profiles: Superconducting Magnetic Energy Storage System market by Type
Company Name
Core Strength
Target Audience
Market Position
American Superconductor
HTS wire and grid project integration
Utilities, grid operators
Leader
Nexans
Cryogenic cable and magnet systems
Transmission and industrial
Leader
Bruker
Superconducting magnet design and cryogenics
Research institutions
Challenger
Hitachi
Power electronics and grid automation
Utilities, industrial
Challenger
The Furukawa Electric Co., Ltd
HTS tape and cryogenic components
System integrators
Leader
FujikuraCG
HTS coated conductors
OEMs, research
Challenger
Luvata
Superconducting wire and specialty metals
Coil manufacturers
Niche
Jastec
Cryogenic equipment and vacuum vessels
Research, industrial
Niche
Innost
Power conversion and control systems
System integrators
Niche
The Superconducting Wire Market is concentrated among a few suppliers, with American Superconductor, The Furukawa Electric Co., Ltd, FujikuraCG, and Luvata controlling most HTS and LTS wire capacity. Cryogenic Cooling Systems Market vendors include Bruker and Jastec, who supply cryostats, helium compressors, and vacuum vessels. Below are strategic profiles of the leading vendors.
American Superconductor: Supplies HTS wire and complete SMES systems for grid stability, with a strong installed base in U.S. and Asian utility projects. Its vertical integration from wire to coil gives it a cost advantage over assembly-only competitors.
Nexans: Leverages cryogenic cable expertise to offer turnkey SMES interconnection and magnet integration for transmission operators. The company targets high-value grid deferral projects in Europe and North America.
Bruker: Known for superconducting magnet design and cryogenic engineering, serving research institutions and national laboratories. Its SMES offerings are customized and lower-volume but technically differentiated.
Hitachi: Combines power electronics, grid automation, and SMES control systems for utility and industrial customers. Its strength lies in integrating SMES with broader grid management platforms.
The Furukawa Electric Co., Ltd: A leading HTS tape manufacturer with deep cryogenic component capabilities. It supplies major SMES integrators and participates in Japanese demonstration projects.
FujikuraCG: Produces HTS coated conductors and focuses on cost reduction for high-temperature SMES coils. Its tapes are used in research and early commercial systems.
Luvata: Provides superconducting wire and specialty copper components, serving coil manufacturers rather than end users. It holds a niche position in the LTS supply chain.
Jastec: Manufactures cryogenic equipment and vacuum vessels for SMES and research applications. Its products are critical for maintaining 4.2 K operating temperatures.
Innost: Supplies power conversion and control systems that manage SMES charging, discharging, and grid interface. It partners with system integrators rather than selling directly to utilities.
Strategic Milestones & Recent Developments in Superconducting Magnetic Energy Storage System market by Type
Date
Company
Event Type
Impact
Q1 2024
American Superconductor
Partnership
Expanded HTS wire supply for grid-scale SMES pilots
Q3 2024
Nexans
Launch
Introduced cryogenic cable assembly for SMES interconnection
Q1 2025
Hitachi
Partnership
Integrated SMES control with utility grid automation platform
Q2 2025
The Furukawa Electric Co., Ltd
Launch
Released lower-cost HTS tape for high-temperature SMES coils
Q4 2025
Bruker
M&A
Acquired cryogenic vacuum vessel assets to expand SMES component offering
Q1 2024 – American Superconductor: Signed supply agreements with two U.S. utilities to provide HTS wire for 10–20 MW SMES demonstration projects. The move strengthens its position in the Superconducting Wire Market and validates commercial demand.
Q3 2024 – Nexans: Launched a modular cryogenic cable assembly designed to cut SMES installation time by 20%. The product targets transmission deferral projects in Europe.
Q1 2025 – Hitachi: Partnered with a Japanese grid operator to integrate SMES control into an existing automation platform. This reduces integration costs for utilities evaluating fast frequency regulation.
Q2 2025 – The Furukawa Electric Co., Ltd: Commercialized an HTS tape with 12% lower cost per meter, aimed at High Temperature SMES coils. The launch supports the segment’s 9.4% CAGR trajectory.
Q4 2025 – Bruker: Acquired cryogenic vacuum vessel assets from a smaller supplier to internalize production. The deal improves margin control for research-grade SMES systems.
Regional Market Analysis & Growth Corridors for Superconducting Magnetic Energy Storage System market by Type
Region
Projected CAGR (%)
Base Year Valuation ($M)
Primary Catalyst
Regulatory Stringency
Asia-Pacific
9.3
205.0
China and Japan grid pilots, HTS supply chain
High
North America
8.0
192.6
FERC Order 755, DOE funding, grid modernization
High
Europe
7.5
149.1
Renewable integration, transmission deferral
Very High
South America
6.8
24.9
Mining and industrial power quality
Medium
Middle East & Africa
7.2
49.7
Islanded grids, oil and gas power reliability
Medium
Asia-Pacific is the fastest-growing region at 9.3% CAGR, with China accounting for roughly 55% of regional SMES revenue. State Grid’s renewable smoothing projects and Japan’s HTS manufacturing base create a self-reinforcing supply chain. North America follows with 8.0% CAGR, supported by FERC Order 755 compensation for fast regulation and U.S. Department of Energy grants. The region’s Research Institution Energy Storage Market remains active, with national laboratories testing high-temperature coils for fusion and grid applications. Europe grows at 7.5% CAGR under strict grid codes and high renewable penetration; Germany, the United Kingdom, and France lead pilot deployments. The region’s regulatory stringency is the highest globally, requiring rigorous grid interconnection studies. South America and Middle East & Africa represent smaller but emerging corridors. South America’s 6.8% CAGR is driven by mining and industrial power quality, while Middle East & Africa’s 7.2% CAGR benefits from islanded grids and oil and gas facilities needing voltage support. The most mature markets are Japan and the United States, where SMES has moved from research to commercial validation. The fastest-growing opportunities are China, South Korea, and Australia, where grid congestion and renewable curtailment create immediate demand for fast-response storage.
Sustainability, ESG & Decarbonization Pressures on Superconducting Magnetic Energy Storage System market by Type
Environmental regulations and net-zero targets are reshaping SMES design and procurement. Helium recovery systems now recover 90–95% of helium in closed-loop cryostats, cutting operating emissions and costs. The Superconducting Wire Market faces pressure to reduce rare-earth content in HTS tapes, with suppliers exploring substituted ReBCO compositions. Circular economy mandates in the EU encourage recyclable cryostat materials and take-back programs for HTS coils. ESG investor criteria favor SMES over lithium-ion for long-duration stationary applications because SMES contains no flammable electrolytes and has a 20+ year design life. However, the cryogenic cooling systems market must address refrigerant leakage and energy consumption, which can account for 8–12% of total system energy use. Utilities with net-zero commitments are procuring SMES for its minimal degradation and high round-trip efficiency of 95–98%. Procurement teams increasingly require life-cycle assessments and conflict-mineral disclosures from wire suppliers. These pressures add 3–5% to upfront costs but improve project bankability with green finance.
Pricing Dynamics, Cost Structures & Margin Pressure in Superconducting Magnetic Energy Storage System market by Type
Average selling prices for turnkey SMES systems range from $2.5 million to $3.2 million per MW in 2025, depending on type and application. Low Temperature systems command a 5–8% premium due to helium cooling and NbTi coil costs. High Temperature systems are priced 10–15% lower per MW but carry higher HTS tape costs. The cost breakdown for a 10 MW SMES system is approximately:
HTS/LTS wire and coils: 40–50%
Cryogenic cooling and vacuum vessels: 15–20%
Power conversion and control electronics: 12–18%
Labor, assembly, and testing: 10–15%
Installation and grid interconnection: 8–12%
Industrial Energy Storage Market buyers negotiate volume discounts of 5–10% for multi-unit orders, while Research Institution Energy Storage Market purchases are often single-unit and price-insensitive but grant-funded. Power System Energy Storage Market projects face competitive pressure from lithium-ion batteries below $150 per kWh, forcing SMES vendors to emphasize cycle life and response speed rather than energy cost. Margins are compressed by helium price volatility, rising HTS tape demand, and long sales cycles. Integrators with in-house coil manufacturing sustain 25–30% gross margins, while assembly-only vendors operate at 18–22%. Pricing power is strongest for high-temperature SMES in space-constrained urban substations and for low-temperature systems in mission-critical industrial power quality. By 2033, scale economies and HTS tape cost reductions should lower average system prices by 12–18%, expanding the addressable market.
Superconducting Magnetic Energy Storage System market by Type Segmentation
1. Type
1.1. Low Temperature
1.2. High Temperature
2. Application
2.1. Power System
2.2. Industrial Use
2.3. Research Institution
2.4. Others
Superconducting Magnetic Energy Storage System market by Type Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Superconducting Magnetic Energy Storage System market by Type REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.18% from 2020-2034
Segmentation
By Type
Low Temperature
High Temperature
By Application
Power System
Industrial Use
Research Institution
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Low Temperature
5.1.2. High Temperature
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Power System
5.2.2. Industrial Use
5.2.3. Research Institution
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Low Temperature
6.1.2. High Temperature
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Power System
6.2.2. Industrial Use
6.2.3. Research Institution
6.2.4. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Low Temperature
7.1.2. High Temperature
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Power System
7.2.2. Industrial Use
7.2.3. Research Institution
7.2.4. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Low Temperature
8.1.2. High Temperature
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Power System
8.2.2. Industrial Use
8.2.3. Research Institution
8.2.4. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Low Temperature
9.1.2. High Temperature
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Power System
9.2.2. Industrial Use
9.2.3. Research Institution
9.2.4. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Low Temperature
10.1.2. High Temperature
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Power System
10.2.2. Industrial Use
10.2.3. Research Institution
10.2.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Bruker
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Nexans
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. American Superconductor
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Jastec
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Luvata
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. The Furukawa Electric Co.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Ltd
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. FujikuraCG
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Innost
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Hitachi
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Superconducting Magnetic Energy Storage System market by Type Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Type 2026 & 2034
Figure 3: North America Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Application 2026 & 2034
Figure 5: North America Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Country 2026 & 2034
Figure 7: North America Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Type 2026 & 2034
Figure 9: South America Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Type 2026 & 2034
Figure 10: South America Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Application 2026 & 2034
Figure 11: South America Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Country 2026 & 2034
Figure 13: South America Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Type 2026 & 2034
Figure 15: Europe Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Application 2026 & 2034
Figure 17: Europe Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Country 2026 & 2034
Figure 19: Europe Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Type 2026 & 2034
Figure 21: Middle East & Africa Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Type 2026 & 2034
Figure 22: Middle East & Africa Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Application 2026 & 2034
Figure 23: Middle East & Africa Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Application 2026 & 2034
Figure 24: Middle East & Africa Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Country 2026 & 2034
Figure 25: Middle East & Africa Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Type 2026 & 2034
Figure 27: Asia Pacific Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Type 2026 & 2034
Figure 28: Asia Pacific Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Application 2026 & 2034
Figure 29: Asia Pacific Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Superconducting Magnetic Energy Storage System market by Type Revenue (million), by Country 2026 & 2034
Figure 31: Asia Pacific Superconducting Magnetic Energy Storage System market by Type Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Type 2020 & 2034
Table 2: Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Application 2020 & 2034
Table 3: Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Region 2020 & 2034
Table 4: North America Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Type 2020 & 2034
Table 5: North America Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Application 2020 & 2034
Table 6: North America Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Country 2020 & 2034
Table 7: United States Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 8: Canada Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 9: Mexico Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 10: South America Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Type 2020 & 2034
Table 11: South America Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Application 2020 & 2034
Table 12: South America Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Country 2020 & 2034
Table 13: Brazil Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 14: Argentina Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 15: Rest of South America Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 16: Europe Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Type 2020 & 2034
Table 17: Europe Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Application 2020 & 2034
Table 18: Europe Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Country 2020 & 2034
Table 19: United Kingdom Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 20: Germany Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 21: France Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 22: Italy Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 23: Spain Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Russia Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 25: Benelux Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 26: Nordics Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 27: Rest of Europe Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 28: Middle East & Africa Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Type 2020 & 2034
Table 29: Middle East & Africa Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Application 2020 & 2034
Table 30: Middle East & Africa Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Country 2020 & 2034
Table 31: Turkey Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Israel Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 33: GCC Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 34: North Africa Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 35: South Africa Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 36: Rest of Middle East & Africa Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Asia Pacific Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Type 2020 & 2034
Table 38: Asia Pacific Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Application 2020 & 2034
Table 39: Asia Pacific Superconducting Magnetic Energy Storage System market by Type Revenue million Forecast, by Country 2020 & 2034
Table 40: China Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 41: India Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 42: Japan Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 43: South Korea Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 44: ASEAN Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 45: Oceania Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Table 46: Rest of Asia Pacific Superconducting Magnetic Energy Storage System market by Type Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conduct 70–80% primary research and 20–30% secondary research, with a guaranteed estimated data accuracy level of 85–90%.
Primary interviews cover SMES coil manufacturers using low-temperature superconducting (LTS) niobium-titanium wire, high-temperature superconducting (HTS) coated conductor tape suppliers, cryogenic refrigeration and vacuum vessel OEMs, power conversion system integrators, and utility-scale grid storage project developers.
We interview titles including Grid Storage Systems Engineering Director, Utility Transmission Asset Manager, Cryogenic Procurement Manager, and Superconducting Magnet R&D Lead.
Interviews are structured to capture installed capacity, pricing, project pipelines, and technology adoption barriers across Low Temperature and High Temperature segments.
Secondary research establishes regional regulatory stringency, grid code requirements, and historical SMES project costs.
Every report is updated to the date of purchase with the latest available project announcements and tariff data.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation across type, application, and region.
The bottom-up model integrates quantitative metrics: installed SMES capacity (MW) per region, average project duration and megawatt-hour rating, number of grid-scale storage tenders requiring sub-5 ms response, average replacement cycle for cryogenic components, and HTS wire cost per meter.
Segment sizes are built from unit shipments, average selling prices, and application-specific attach rates for Power System, Industrial Use, Research Institution, and Others.
Regional forecasts for North America, South America, Europe, Middle East & Africa, and Asia Pacific are reconciled with utility procurement plans and national energy storage targets.
Data Accuracy & Quality Check
All data passes through a multi-level triangulation process comparing primary interview medians against secondary trade data and financial filings.
We guarantee an estimated data accuracy level of 85–90% for market sizing and CAGR projections.
Outlier responses are re-verified with at least two independent sources, and regional totals are cross-checked against grid operator capacity registries.
Reports are updated to the date of purchase, ensuring that the 2025 base year and 2033 forecast reflect the latest commercial and regulatory developments.
Frequently Asked Questions
1. What are the main barriers to entry in the Superconducting Magnetic Energy Storage System market by Type?
Barriers include cryogenic engineering expertise, HTS wire supply contracts, and capital costs above $2.5 million per MW. American Superconductor and Bruker hold proprietary coil and magnet designs that create technical moats. Regulatory certification for grid interconnection adds 12–18 months to deployment timelines.
2. How are purchasing trends shifting for SMES systems across power and industrial users?
Buyers increasingly request modular SMES units with lower installed cost and shorter lead times. Power System Energy Storage Market procurement now bundles SMES with frequency regulation and voltage support services. Industrial users prioritize 10-year service agreements covering cryogenic maintenance, which can represent 18–22% of total contract value.
3. Which region is the fastest-growing for the Superconducting Magnetic Energy Storage System market by Type?
Asia-Pacific is the fastest-growing region with a projected 9.3% CAGR, driven by China and Japan. China’s State Grid has commissioned multiple MW-scale SMES pilots for renewable smoothing. Emerging opportunities also exist in South Korea and Australia, where grid congestion and islanded microgrids create niche demand.
4. What are the primary growth drivers and demand catalysts for SMES adoption?
Millisecond response and 100,000+ charge-discharge cycles make SMES attractive for Grid Stability Energy Storage Market applications. Renewable portfolio standards and transmission deferral needs are catalysts, especially where lithium-ion cycle life is insufficient. Government grants, such as U.S. DOE awards, reduce project risk and accelerate commercial validation.
5. Who are the leading companies and what does the competitive landscape look like?
American Superconductor, Nexans, Bruker, Hitachi, and The Furukawa Electric Co., Ltd lead SMES component and system supply. American Superconductor holds a strong position in HTS wire and grid projects, while Nexans targets cryogenic cable and magnet integration. The market remains fragmented, with no single vendor exceeding 20% revenue share in 2025.
6. How do sustainability and ESG factors affect SMES raw materials and procurement?
Helium recovery and closed-loop cryogenic systems reduce environmental impact and operating cost by 12–16%. ESG criteria push suppliers toward recyclable HTS tape substrates and lead-free solders in coil assemblies. Utilities with net-zero targets favor SMES for its long service life and minimal degradation, supporting circular procurement policies.