Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Bunker Fuel Market Outlook 2025-2033: 4.41% CAGR, $178.1B
Bunker Fuel Market
Bunker Fuel Market Outlook 2025-2033: 4.41% CAGR, $178.1B
Bunker Fuel Market by Type (High Sulfur Fuel Oil, Low Sulfur Fuel Oil, Marine Gas Oil, Bio-LNG, Methanol, Ammonia, Hydrogen, Others), by Commercial Distributor (Oil Majors, Large Independent, Small Independent), by Application (Bulk Carrier, Oil Tanker, General Cargo, Container Lines, Chemical Tanker, Fishing Vessels, Gas Tankers, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 9, 2026|Base Year : 2025|Pages : 499
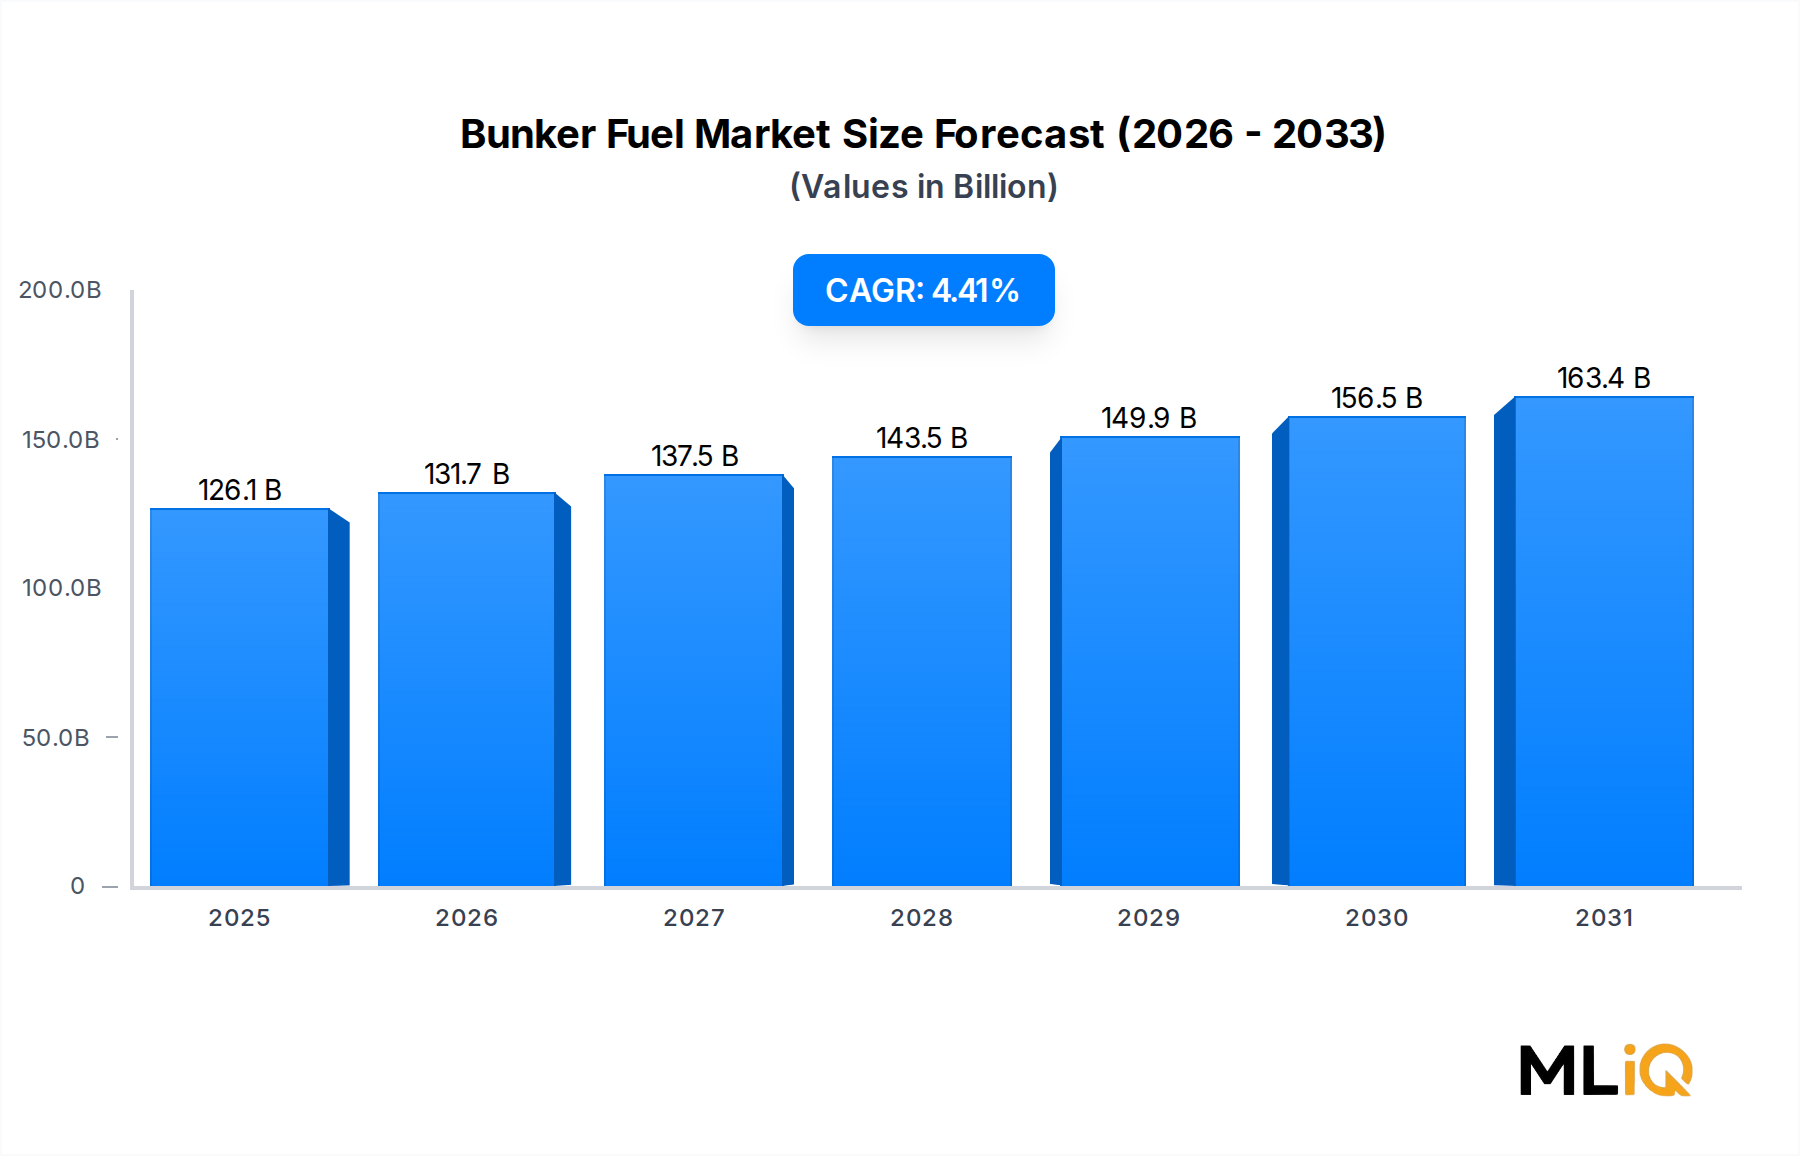
Bunker Fuel Market growth is anchored in seaborne trade recovery, the retrofit cycle for older tonnage, and the parallel need for compliant fuel switching. Global fuel spend is projected to rise from USD 126.1 billion in 2025 to USD 178.1 billion by 2033 at a 4.41% CAGR. Value expansion will not be linear because fuel-price spreads are regional and policy-driven. Bunker demand is derived demand: it follows vessel routing, cargo volumes and fleet productivity rather than engine capacity alone.
Bunker Fuel Market Size (In Billion)
200.0B
150.0B
100.0B
50.0B
0
126.1 B
2025
131.7 B
2026
137.5 B
2027
143.5 B
2028
149.9 B
2029
156.5 B
2030
163.4 B
2031
Low Sulfur Fuel Oil Market activity is the commercial core of the forecast. IMO regulations force most global tonnage to burn VLSFO with a 0.50% sulfur limit, or marine gas oil inside emission control areas. From 2025, FuelEU Maritime adds lifecycle GHG intensity limits, gradually pulling procurement toward bio-blended VLSFO and lower-carbon alternatives. Suppliers are reorganizing refinery streams, blending and barge delivery around these specifications.
Despite the compliance shift, the High Sulfur Fuel Oil Market remains resilient. Scrubber-equipped bulk carriers, tankers and container vessels continue to consume HSFO where the price gap to VLSFO covers scrubber capital costs. The Marine Scrubber Market now has enough installed base and maintenance infrastructure to shape fuel economics.
The demand base is concentrated by vessel segment. The Container Shipping Market drives voyage frequency and port-call volume at hub ports such as Singapore, Shanghai and Rotterdam. Bulk carriers add voyage distance, oil and chemical tankers add specialized parcel demand, and fishing vessels and gas tankers contribute coastal or niche requirements. Fuel suppliers therefore match sulfur content, viscosity, density and energy content to operational profiles instead of selling a homogeneous product.
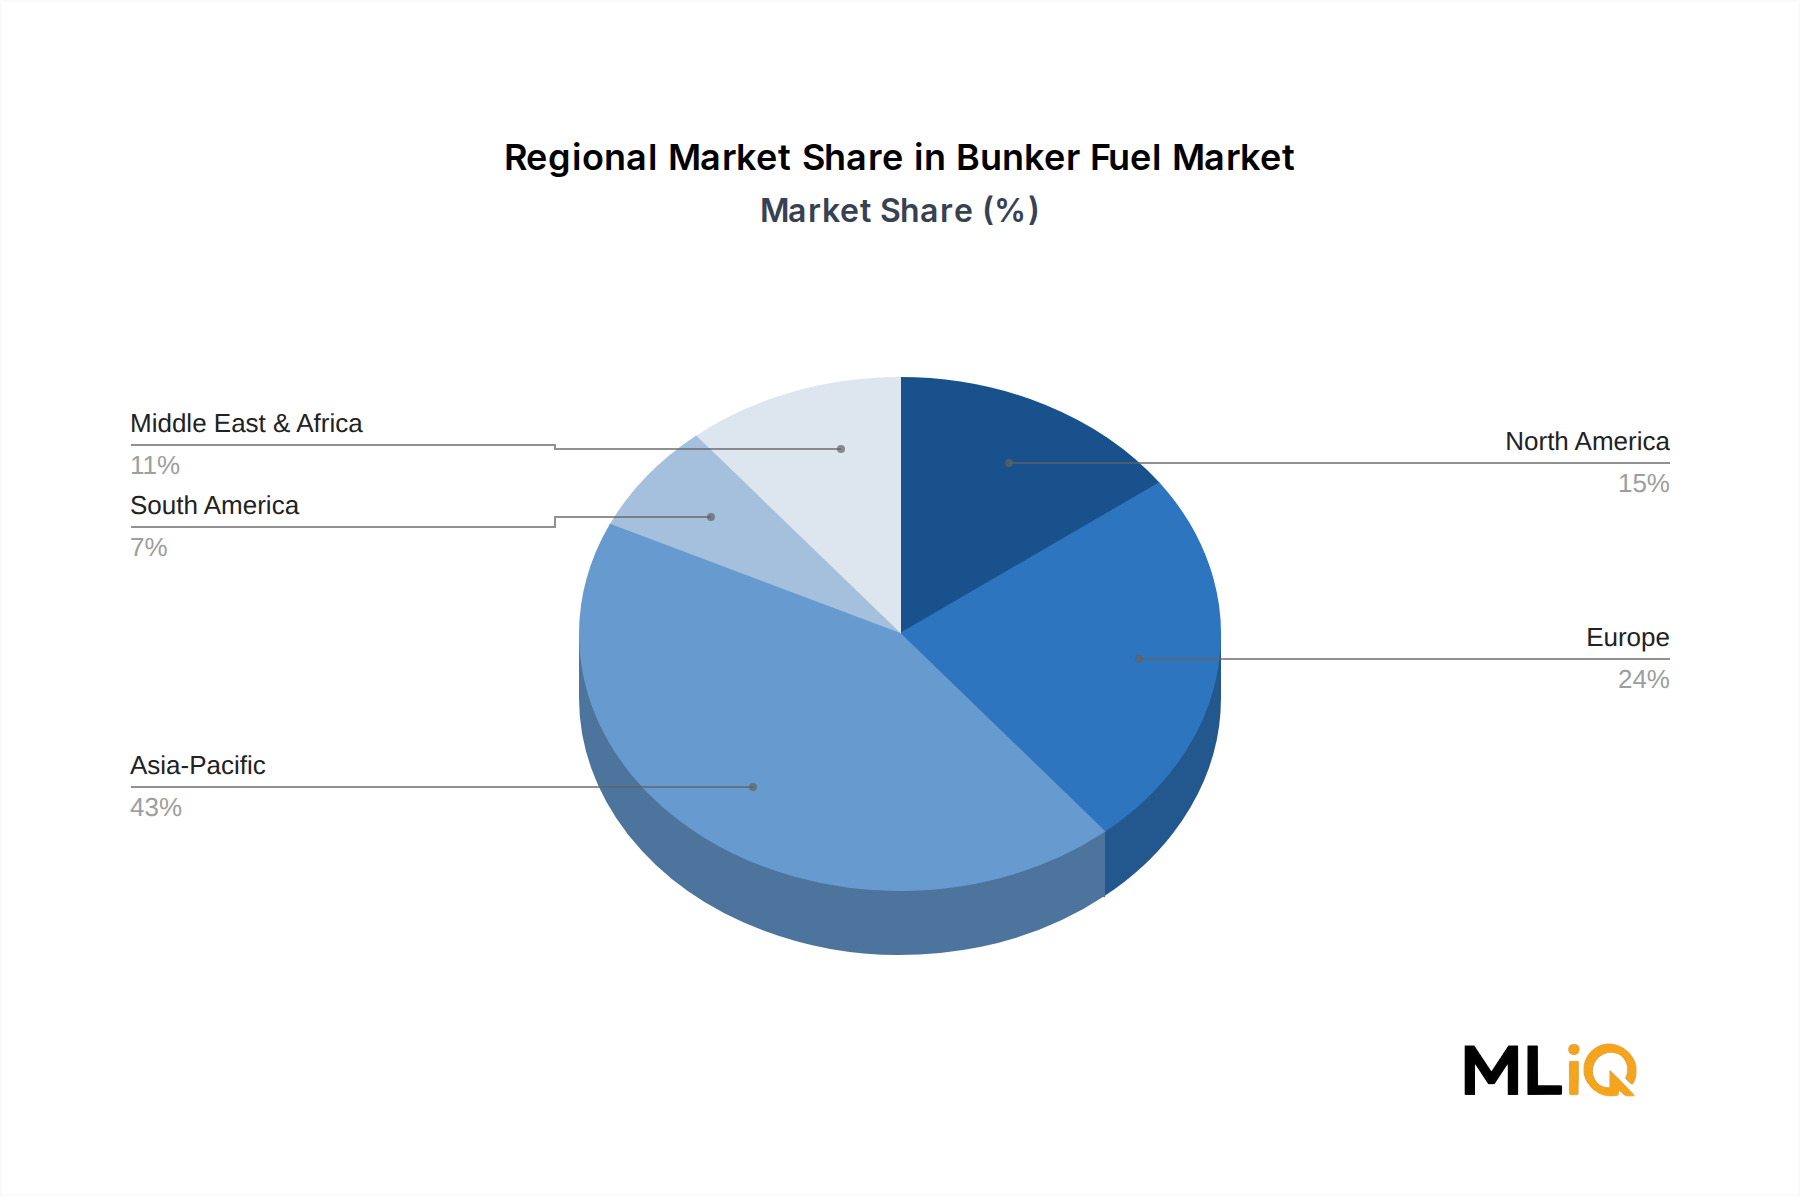
The Asia-Pacific region remains the world's largest refueling area, representing roughly 43% of global bunker demand, while Europe is becoming the regulatory laboratory for low-carbon marine fuels. Marine Fuel Market participants must balance lower carbon intensity with fuel availability, cold-flow properties and engine warranties. That complexity creates margin opportunities for independent traders and refiners with high-conversion capacity.
The Low Sulfur Fuel Oil Market is the largest value pool in this forecast, estimated at 46-48% of total Bunker Fuel Market spend in 2025. VLSFO, not low sulfur marine gas oil, is the default ocean-going fuel. The segment carries a price premium over HSFO while lacking the energy density of distillate, which compresses net energy cost when expressed per megajoule.
Compliance Foundation and Product Quality Restrictions
The Low Sulfur Fuel Oil Market is shaped by more than sulfur content. VLSFO blends must respect pour point, total sediment, cat fines and cold-flow behaviour. A port-call delay or engine failure caused by unstable VLSFO has direct consequences for charterers, vessel owners and P&I insurers. Procurement teams increasingly use quality clauses, fuel testing and algorithmic blending to protect engine uptime.
FuelEU Maritime changes the value equation again. Vessels trading in EU waters must reduce GHG intensity from 2025, with obligations extending to the full mix of energy used. This creates immediate operational demand for bio-blended VLSFO and for marine distillate products that carry lower well-to-wake carbon values. In parallel, the Marine Gas Oil Market supports emergency switching, ECA operation, auxiliary engine load and cold-weather voyages where residual fuel handling becomes unreliable.
Scrubber Competition and Future Fuel Decarbonization
The direct substitute for VLSFO is HSFO plus a scrubber. The installed and contracted scrubber fleet is large enough to limit future Low Sulfur Fuel Oil Market share growth. As the IMO Net-Zero Framework matures, after-treatment carbon capture is not yet commercial; therefore compliant fuels and engine upgrades will fight for the same retrofit budgets.
Distribution logistics also affect this segment. Oil majors offer back-to-back supply at large hubs, while large independent suppliers manage price risk by blending at storage tanks. Small independent suppliers gain position in port niches but take volume risk when VLSFO inventory quality drifts. By 2030, the Low Sulfur Fuel Oil Market will likely peak in volume and then transition to a fuel that is blended with advanced biofuel and renewable components.
Primary Market Drivers & Growth Restraints in Bunker Fuel Market
Seaborne trade growth is the foundational Bunker Fuel Market driver. UNCTAD baseline projections point to annual maritime trade expansion near 2%; longer east-west routes create ton-miles ahead of volume growth. Higher ton-miles raise consumption even when vessel speeds decline.
The Marine Scrubber Market is a second structural driver. Industry polls and port inspection data put the scrubber-fitted fleet at roughly 5,000 ships, which sustains HSFO demand and exposes owners to fuel-spread risk. When HSFO discounts exceed USD 100 per metric ton, scrubber payback falls below two years on main engine routes.
Regulation is also a net demand shifter. CII and EEXI have reduced speed, while EU ETS carbon cost increases fuel prices. The LNG Bunkering Market is expanding from a very low base, but LNG is not growing fast enough to satisfy total emissions constraints. Bio-LNG and liquefied biomethane face feedstock limits and certification bottlenecks.
Restraints are mainly logistical and feedstock related. Only a handful of ports can offer certified biofuel blends in large volumes. Cold-flow and stability issues in VLSFO still create off-spec stems that push ships toward the Marine Gas Oil Market at short notice. The Low Sulfur Fuel Oil Market also carries mandatory blending risk because variations in sour crude supply, Chinese refining output or Indian and Middle Eastern refinery output change residual-fuel quality.
High capital costs for dual-fuel engines and limited green hydrogen supply slow the adoption of methanol and ammonia. Without a global marine fuel standard or a pricing mechanism, shipowners face route-based regulation splits, making fuel-platform choices difficult. These constraints appear in the 4.41% CAGR, which is moderate rather than exceptional for an energy market recovering from pandemic demand shocks.
Shell plc: Integrated marine fuels provider with trading, refining and terminal supply across the Atlantic basin, Asia and the Mediterranean; active in VLSFO, HSFO, MGO, Bio-LNG and methanol-ready pilots.
BP p.l.c.: Global marine fuel seller with physical supply in Rotterdam, Singapore and key U.S. ports, and a marine biofuels program tied to its downstream network.
Exxon Mobil Corporation: Refining-led supplier offering coordinated VLSFO, HSFO and MGO inventories to liner, tanker and offshore customers through ExxonMobil Marine.
Chevron Corporation: Marine fuels and lubricants owner with strong U.S. Gulf and Asia-Pacific supply positions; active in conventional bunkering markets.
TotalEnergies: Integrated energy supplier with LNG bunker vessels, marine biofuel blending, and established supply into European SECAs and Asian hubs.
Hindustan Petroleum Corporation Limited: Indian state-controlled refiner with marine fuel infrastructure along the west and east coasts; terminals serve the expanding Indian coastal trade.
Indian Oil Corporation Ltd.: Indian refiner and marketer whose port terminals and inland distribution network supply vessels calling at Indian anchor ports.
Petroliam Nasional Berhad (PETRONAS): Malaysian national energy company building a regional bunkering position in Southeast Asia, including LNG bunkering and supply into the Strait of Malacca.
Bunker Holding A/S: Independent bunker trading group with worldwide physical supply, risk management, credit and logistics services, operating through multiple regional subsidiaries.
LUKOIL: International energy company active in marine fuel supply in Baltic and Black Sea markets, with refining links in southern Europe and Russia.
Neste: Renewable products refiner converting waste and residue raw materials into renewable diesel, sustainable aviation fuel and marine biofuel blends for maritime customers.
Vitol Bunkers: Large independent physical supplier active through terminals and barges in Singapore, Fujairah, Amsterdam-Rotterdam-Antwerp and major U.S. Gulf locations.
Strategic Milestones & Recent Developments in Bunker Fuel Market
January 2020: The IMO global sulfur cap reduced sulfur content from 3.50% to 0.50% outside emission control areas, resetting fuel procurement systems and creating the modern Low Sulfur Fuel Oil Market.
July 2021: The European Commission's Fit for 55 package proposed maritime ETS and FuelEU Maritime, altering capex signals for LNG, biofuel and green methanol projects.
January 2023: EEXI and the Carbon Intensity Indicator entered into force, tying a vessel's operating efficiency to measures such as speed reduction and hull cleaning.
January 2024: Ships calling in the European Economic Area began to surrender EU ETS allowances for their CO2 emissions, making carbon costs a visible component of bunker buying decisions.
January 2025: FuelEU Maritime began to apply lifecycle GHG intensity limits to energy used on voyages within and between EU ports, creating a compliance incentive for bio-blended VLSFO and bio-LNG.
April 2025: IMO Member States advanced the net-zero framework by setting dates for a marine fuel standard and global GHG pricing, reinforcing long-range investment in alternative fuel production capacity.
Regional Market Analysis & Growth Corridors for Bunker Fuel Market
The Asia-Pacific region remains the volume anchor for the Bunker Fuel Market. This report assigns 43% of global bunker demand to the region in 2025. Singapore is the world's largest bunkering port, with volumes close to 50 million metric tons per year. China's Zhoushan and Shanghai hubs, South Korea's Ulsan and Busan, and Japan's Nagoya maintain round-the-clock supply. Regional growth is supported by intra-Asia container routes and Australian and Indonesian dry bulk exports.
Europe holds roughly 24% of global demand and is the most policy-advanced market. EU ETS and FuelEU Maritime raise fuel costs but also accelerate procurement of bio-blended fuels. Rotterdam and Gibraltar are important supply points for scrubber-equipped vessels, while the North Sea and Baltic ECAs continue to require marine gas oil or ULSFO bunker alternatives.
North America accounts for around 15% of global Bunker Fuel Market demand. The U.S. Gulf refinery system provides heavy sour crude conversion capacity, enabling HSFO and VLSFO output for the Panama Canal route. Houston, New York and Los Angeles/Long Beach serve container, tanker and cruise segments under strict North American ECA limits.
Middle East & Africa is projected to grow faster than the global average, at about 5.2% CAGR, because Fujairah and Saudi Red Sea ports are expanding their bunker terminal capacity. Fujairah benefits from its position after the Strait of Hormuz for eastbound and westbound tanker voyages. South America, at about 7% share, is supported by Brazilian and Argentine grain exports, but smaller bunkering infrastructure limits the pace of low-sulfur fuel availability.
Europe is the most mature region, while Middle East & Africa offers the fastest growth corridor. Asia-Pacific remains the most consequential market for fuel suppliers, with severe price competition and growing incentive for large independent players.
Supply Chain & Raw Material Dynamics: Bunker Fuel Market
Upstream physical sourcing determines almost every Bunker Fuel Market margin. Crude Oil Market fundamentals, specifically the supply of sour crude and high-sulfur residual fuels, set the base for HSFO prices. VLSFO production requires deep hydrodesulfurization, which consumes refinery hydrogen and raises operating cost. MGO comes from diesel desulfurization units and tracks crude and gasoil crack spreads.
Three raw material chains are strengthening. Bio-LNG uses biomethane from landfill, manure and agricultural residues; available volumes are far below shipping demand. Methanol can be produced from natural gas or biomass, but green methanol requires renewable hydrogen and either biogenic CO2 or captured CO2. Ammonia, mostly coal or natural gas-based today, needs green hydrogen with carbon capture to earn a sustainability rating.
Vendor dependence is high in specialized inputs: hydrotreating catalysts, biofuel feedstock aggregators, hydrogen producers and scrubber washwater handling systems. The price direction for high-sulfur crude and low-sulfur crudes diverges when refinery capacity cannot keep pace with regulatory demand. VLSFO premiums widen in winter months when gasoil demand pulls cutter stock away from bunker blending.
Supply chain disruptions are part of the pricing environment. The 2021 Suez Canal blockage stalled more than 400 vessels and delayed bunker deliveries; the 2022 Russia-Ukraine conflict shifted global trade flows for Russian HSFO and increased Middle East and U.S. Gulf supply into Asia. Regional fuel quality incidents still cause demurrage, emergency MGO purchases and engine damage claims.
Sustainability, ESG & Decarbonization Pressures on Bunker Fuel Market
The sustainability agenda moved from boardroom language to commercial contracts after 2023. The Renewable Methanol Market is currently one of the most investable alternative marine fuel categories because methanol can be stored as a liquid at ambient temperature and pressure. Container lines have committed a meaningful share of newbuild orders to methanol-capable engines, although project-level green methanol offtake remains concentrated.
Bio-LNG is further along than methanol but competes for biomethane feedstocks with road transport and heating. The EU requires member states to hold biofuel suppliers to binding GHG savings thresholds, limiting the amount of converted cooking oil and animal fat that can flow into marine fuel.
ESG investors and Poseidon Principles banks now require shipowners to report carbon intensity metrics. That creates indirect pressure on the Bunker Fuel Market because financing conditions improve for operators with lower emissions trajectories. However, sustainability goals also collide with fuel availability. Scrubber washwater rules, local air pollution standards and green hydrogen scarcity affect the speed and cost of transitioning.
By 2033, the Low Sulfur Fuel Oil Market will likely contain higher levels of bio-blended VLSFO alongside synthetic e-fuels. The role of oil majors will widen, while independent suppliers must offer differentiated fuel carbon accounting. The transition will not be linear; regulation, feedstock prices and engine warranties will determine the actual mix.
Bunker Fuel Market Segmentation
1. Type
1.1. High Sulfur Fuel Oil
1.2. Low Sulfur Fuel Oil
1.3. Marine Gas Oil
1.4. Bio-LNG
1.5. Methanol
1.6. Ammonia
1.7. Hydrogen
1.8. Others
2. Commercial Distributor
2.1. Oil Majors
2.2. Large Independent
2.3. Small Independent
3. Application
3.1. Bulk Carrier
3.2. Oil Tanker
3.3. General Cargo
3.4. Container Lines
3.5. Chemical Tanker
3.6. Fishing Vessels
3.7. Gas Tankers
3.8. Others
Bunker Fuel Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Bunker Fuel Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.28% from 2020-2034
Segmentation
By Type
High Sulfur Fuel Oil
Low Sulfur Fuel Oil
Marine Gas Oil
Bio-LNG
Methanol
Ammonia
Hydrogen
Others
By Commercial Distributor
Oil Majors
Large Independent
Small Independent
By Application
Bulk Carrier
Oil Tanker
General Cargo
Container Lines
Chemical Tanker
Fishing Vessels
Gas Tankers
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. High Sulfur Fuel Oil
5.1.2. Low Sulfur Fuel Oil
5.1.3. Marine Gas Oil
5.1.4. Bio-LNG
5.1.5. Methanol
5.1.6. Ammonia
5.1.7. Hydrogen
5.1.8. Others
5.2. Market Analysis, Insights and Forecast - by Commercial Distributor
5.2.1. Oil Majors
5.2.2. Large Independent
5.2.3. Small Independent
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Bulk Carrier
5.3.2. Oil Tanker
5.3.3. General Cargo
5.3.4. Container Lines
5.3.5. Chemical Tanker
5.3.6. Fishing Vessels
5.3.7. Gas Tankers
5.3.8. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. High Sulfur Fuel Oil
6.1.2. Low Sulfur Fuel Oil
6.1.3. Marine Gas Oil
6.1.4. Bio-LNG
6.1.5. Methanol
6.1.6. Ammonia
6.1.7. Hydrogen
6.1.8. Others
6.2. Market Analysis, Insights and Forecast - by Commercial Distributor
6.2.1. Oil Majors
6.2.2. Large Independent
6.2.3. Small Independent
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Bulk Carrier
6.3.2. Oil Tanker
6.3.3. General Cargo
6.3.4. Container Lines
6.3.5. Chemical Tanker
6.3.6. Fishing Vessels
6.3.7. Gas Tankers
6.3.8. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. High Sulfur Fuel Oil
7.1.2. Low Sulfur Fuel Oil
7.1.3. Marine Gas Oil
7.1.4. Bio-LNG
7.1.5. Methanol
7.1.6. Ammonia
7.1.7. Hydrogen
7.1.8. Others
7.2. Market Analysis, Insights and Forecast - by Commercial Distributor
7.2.1. Oil Majors
7.2.2. Large Independent
7.2.3. Small Independent
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Bulk Carrier
7.3.2. Oil Tanker
7.3.3. General Cargo
7.3.4. Container Lines
7.3.5. Chemical Tanker
7.3.6. Fishing Vessels
7.3.7. Gas Tankers
7.3.8. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. High Sulfur Fuel Oil
8.1.2. Low Sulfur Fuel Oil
8.1.3. Marine Gas Oil
8.1.4. Bio-LNG
8.1.5. Methanol
8.1.6. Ammonia
8.1.7. Hydrogen
8.1.8. Others
8.2. Market Analysis, Insights and Forecast - by Commercial Distributor
8.2.1. Oil Majors
8.2.2. Large Independent
8.2.3. Small Independent
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Bulk Carrier
8.3.2. Oil Tanker
8.3.3. General Cargo
8.3.4. Container Lines
8.3.5. Chemical Tanker
8.3.6. Fishing Vessels
8.3.7. Gas Tankers
8.3.8. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. High Sulfur Fuel Oil
9.1.2. Low Sulfur Fuel Oil
9.1.3. Marine Gas Oil
9.1.4. Bio-LNG
9.1.5. Methanol
9.1.6. Ammonia
9.1.7. Hydrogen
9.1.8. Others
9.2. Market Analysis, Insights and Forecast - by Commercial Distributor
9.2.1. Oil Majors
9.2.2. Large Independent
9.2.3. Small Independent
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Bulk Carrier
9.3.2. Oil Tanker
9.3.3. General Cargo
9.3.4. Container Lines
9.3.5. Chemical Tanker
9.3.6. Fishing Vessels
9.3.7. Gas Tankers
9.3.8. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. High Sulfur Fuel Oil
10.1.2. Low Sulfur Fuel Oil
10.1.3. Marine Gas Oil
10.1.4. Bio-LNG
10.1.5. Methanol
10.1.6. Ammonia
10.1.7. Hydrogen
10.1.8. Others
10.2. Market Analysis, Insights and Forecast - by Commercial Distributor
10.2.1. Oil Majors
10.2.2. Large Independent
10.2.3. Small Independent
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Bulk Carrier
10.3.2. Oil Tanker
10.3.3. General Cargo
10.3.4. Container Lines
10.3.5. Chemical Tanker
10.3.6. Fishing Vessels
10.3.7. Gas Tankers
10.3.8. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Hindustan Petroleum Corporation Limited
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Petroliam Nasional Berhad (PETRONAS)
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Bunker Holding A/S
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Shell plc
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Chevron Corporation
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. LUKOIL
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Neste
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Vitol Bunkers
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Exxon Mobil Corporation
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. TotalEnergies
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Indian Oil Corporation Ltd.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. BP p.l.c.
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Bunker Fuel Market Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Bunker Fuel Market Revenue (million), by Type 2026 & 2034
Figure 3: North America Bunker Fuel Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Bunker Fuel Market Revenue (million), by Commercial Distributor 2026 & 2034
Figure 5: North America Bunker Fuel Market Revenue Share (%), by Commercial Distributor 2026 & 2034
Figure 6: North America Bunker Fuel Market Revenue (million), by Application 2026 & 2034
Figure 7: North America Bunker Fuel Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Bunker Fuel Market Revenue (million), by Country 2026 & 2034
Figure 9: North America Bunker Fuel Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Bunker Fuel Market Revenue (million), by Type 2026 & 2034
Figure 11: South America Bunker Fuel Market Revenue Share (%), by Type 2026 & 2034
Figure 12: South America Bunker Fuel Market Revenue (million), by Commercial Distributor 2026 & 2034
Figure 13: South America Bunker Fuel Market Revenue Share (%), by Commercial Distributor 2026 & 2034
Figure 14: South America Bunker Fuel Market Revenue (million), by Application 2026 & 2034
Figure 15: South America Bunker Fuel Market Revenue Share (%), by Application 2026 & 2034
Figure 16: South America Bunker Fuel Market Revenue (million), by Country 2026 & 2034
Figure 17: South America Bunker Fuel Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Bunker Fuel Market Revenue (million), by Type 2026 & 2034
Figure 19: Europe Bunker Fuel Market Revenue Share (%), by Type 2026 & 2034
Figure 20: Europe Bunker Fuel Market Revenue (million), by Commercial Distributor 2026 & 2034
Figure 21: Europe Bunker Fuel Market Revenue Share (%), by Commercial Distributor 2026 & 2034
Figure 22: Europe Bunker Fuel Market Revenue (million), by Application 2026 & 2034
Figure 23: Europe Bunker Fuel Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Europe Bunker Fuel Market Revenue (million), by Country 2026 & 2034
Figure 25: Europe Bunker Fuel Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Bunker Fuel Market Revenue (million), by Type 2026 & 2034
Figure 27: Middle East & Africa Bunker Fuel Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Middle East & Africa Bunker Fuel Market Revenue (million), by Commercial Distributor 2026 & 2034
Figure 29: Middle East & Africa Bunker Fuel Market Revenue Share (%), by Commercial Distributor 2026 & 2034
Figure 30: Middle East & Africa Bunker Fuel Market Revenue (million), by Application 2026 & 2034
Figure 31: Middle East & Africa Bunker Fuel Market Revenue Share (%), by Application 2026 & 2034
Figure 32: Middle East & Africa Bunker Fuel Market Revenue (million), by Country 2026 & 2034
Figure 33: Middle East & Africa Bunker Fuel Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Bunker Fuel Market Revenue (million), by Type 2026 & 2034
Figure 35: Asia Pacific Bunker Fuel Market Revenue Share (%), by Type 2026 & 2034
Figure 36: Asia Pacific Bunker Fuel Market Revenue (million), by Commercial Distributor 2026 & 2034
Figure 37: Asia Pacific Bunker Fuel Market Revenue Share (%), by Commercial Distributor 2026 & 2034
Figure 38: Asia Pacific Bunker Fuel Market Revenue (million), by Application 2026 & 2034
Figure 39: Asia Pacific Bunker Fuel Market Revenue Share (%), by Application 2026 & 2034
Figure 40: Asia Pacific Bunker Fuel Market Revenue (million), by Country 2026 & 2034
Figure 41: Asia Pacific Bunker Fuel Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Bunker Fuel Market Revenue million Forecast, by Type 2020 & 2034
Table 2: Bunker Fuel Market Revenue million Forecast, by Commercial Distributor 2020 & 2034
Table 3: Bunker Fuel Market Revenue million Forecast, by Application 2020 & 2034
Table 4: Bunker Fuel Market Revenue million Forecast, by Region 2020 & 2034
Table 5: North America Bunker Fuel Market Revenue million Forecast, by Type 2020 & 2034
Table 6: North America Bunker Fuel Market Revenue million Forecast, by Commercial Distributor 2020 & 2034
Table 7: North America Bunker Fuel Market Revenue million Forecast, by Application 2020 & 2034
Table 8: North America Bunker Fuel Market Revenue million Forecast, by Country 2020 & 2034
Table 9: United States Bunker Fuel Market Revenue (million) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Bunker Fuel Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We use a research split of 70-80% primary interviews and 20-30% secondary validation throughout the Bunker Fuel Market study.
Primary interviews target four specialized company groups: crude and refinery residue scheduling managers, marine fuel blending and quality teams, independent bunker trading platforms, and port bunkering terminal operators.
Stakeholder titles include Global Bunker Procurement Director, Marine Compliance and Sustainability Superintendent, Vessel Operations Manager, and Chartering and Voyage Optimization Lead.
Structured surveys also capture demand signals from bulk carrier, container line, tanker, fishing vessel and gas tanker operators.
Regulatory inputs are gathered from the International Maritime Organization (IMO), Marine Environment Protection Committee (MEPC), European Maritime Safety Agency (EMSA), and the International Bunker Industry Association (IBIA).
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Fuel Supply Leaders
28%
Compliance & Sustainability Directors
24%
Vessel & Fleet Operations Managers
20%
Commercial & Chartering Managers
18%
Strategy & Corporate Development
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Oil Majors & Integrated Refiners
40%
Independent Bunker Suppliers
38%
Port & Terminal Operators
14%
Vessel Owners & Operators
8%
Secondary Research & Industry Benchmarking
Secondary research starts with public annual reports, IMO MARPOL Annex VI revisions, EU FuelEU Maritime implementation texts, and port authority bunker sales statistics.
Additional cross-checks use .gov and .org repositories, including UNCTADstat, IMO GISIS, the U.S. Energy Information Administration and European Commission regulatory pages; no commercial market research website is used as a citable source.
Demand Modeling & Market Estimation
Top-down and bottom-up estimation are executed in parallel. Top-down modeling derives total addressable marine energy from global seaborne ton-miles and freight activity reported by UNCTAD and national shipping registries.
Bottom-up estimation builds from port bunker volumes at Singapore, Rotterdam, Hong Kong, Fujairah, Houston, Antwerp and Busan, then applies average stem sizes and vessel call frequencies by segment.
Quantitative metrics include port calls by vessel type, average bunker stem size, scrubber-fitted vessel counts, delivered marine fuel price by grade, vessel energy efficiency existing ship index (EEXI) values and carbon intensity indicator (CII) ratings.
Multi-level data triangulation is performed at global, regional, country and port levels to remove double counting and reconcile IMO data with trader imports and customs export filings.
Data Accuracy & Quality Check
Every Bunker Fuel Market estimate is validated by our internal data quality team and carries a guaranteed accuracy range of 85-90%.
All datasets, model inputs and interview notes are stored by date, source and confidence score.
This report is updated to the date of purchase, including IMO MEPC decisions, EU ETS allowance trajectories and refinery maintenance schedules that affect bunker availability.
Frequently Asked Questions
1. Why do supply-chain and regulatory mismatches create the largest challenges in the Bunker Fuel Market?
Regulatory fragmentation across the IMO sulfur cap, FuelEU Maritime and EU ETS creates compliance uncertainty for suppliers and vessel operators. The Low Sulfur Fuel Oil Market faces thinning margins because biofuel blending mandates raise feedstock costs, while scrubber retrofits and dual-fuel engine orders avoid a single predictable trajectory. In 2025, methanol and ammonia still contribute less than 1% of global bunker energy consumed.
2. How do export-import flows shape the Bunker Fuel Market's geography?
More than 80% of global merchandise trade volume is transported by sea, and seaborne ton-miles define bunkering corridors. Asia-Pacific handles around 43% of global bunker volume, anchored by Singapore, because a high share of east-west and intra-Asia cargo routes pass through the Malacca Strait. Shifts in crude oil and LNG exports also raise fuel demand at Fujairah, Houston, Rotterdam and Busan.
3. What post-pandemic recovery pattern is shaping Bunker Fuel Market demand?
Containerized cargo growth rebounded strongly after 2021, lifting the Container Shipping Market and port calls, but high freight rates also encouraged slow steaming, which reduces fuel consumption per ton-mile. The scrubber fleet allowed owners to return to HSFO when price spreads were favourable. Overall, the Bunker Fuel Market is expected to grow at a 4.41% CAGR between 2025 and 2033, overlapping with the first enforcement cycle of carbon intensity rules.
4. Which end-user segments have the largest impact on bunker fuel purchases?
Container lines and bulk carriers account for the majority of global bunker stems. Container Shipping Market demand is highly port-call intensive, while bulk carriers consume more fuel per voyage due to long dry-bulk routes. Oil tankers, chemical tankers, fishing vessels and gas tankers add specialised demand for marine gas oil and, increasingly, LNG bunker fuels.
5. Who is investing in alternative marine fuel projects across the Bunker Fuel Market?
Investment is clustered in biofuel blending and green methanol capacity, with Neste expanding renewable feedstock output and TotalEnergies building Bio-LNG facilities. Shipping lines, including Maersk, have ordered more than 100 methanol-capable vessels, but alternative fuels still represent less than 2% of total maritime energy demand. Independent bunker suppliers are also spending on digital bunker systems and multi-fuel barges to prepare for rotating fuel types.
6. How do raw material sourcing risks affect Bunker Fuel Market pricing?
Residual marine fuel output depends on crude slate, refinery conversion units and hydrodesulfurization capacity, making the Crude Oil Market the primary pricing anchor. Sour crude availability and refinery maintenance create VLSFO shortage events, while renewable methanol production depends on biomass and green hydrogen availability. In 2024, the HSFO-VLSFO price spread in Singapore exceeded USD 100 per metric ton during several trading weeks, lifting scrubber payback incentives.