Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Off-Road Fuels Market Size $544.1B, 6.9% CAGR
Off-Road Fuels Market
Off-Road Fuels Market Size $544.1B, 6.9% CAGR
Off-Road Fuels Market by Product Type (Red Dyed Off Road Fuels, Blue Dyed Off Road Fuels, Green Dyed Off Road Fuels, Others), by Application (Heating Oil, Farming, Construction, Mining, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
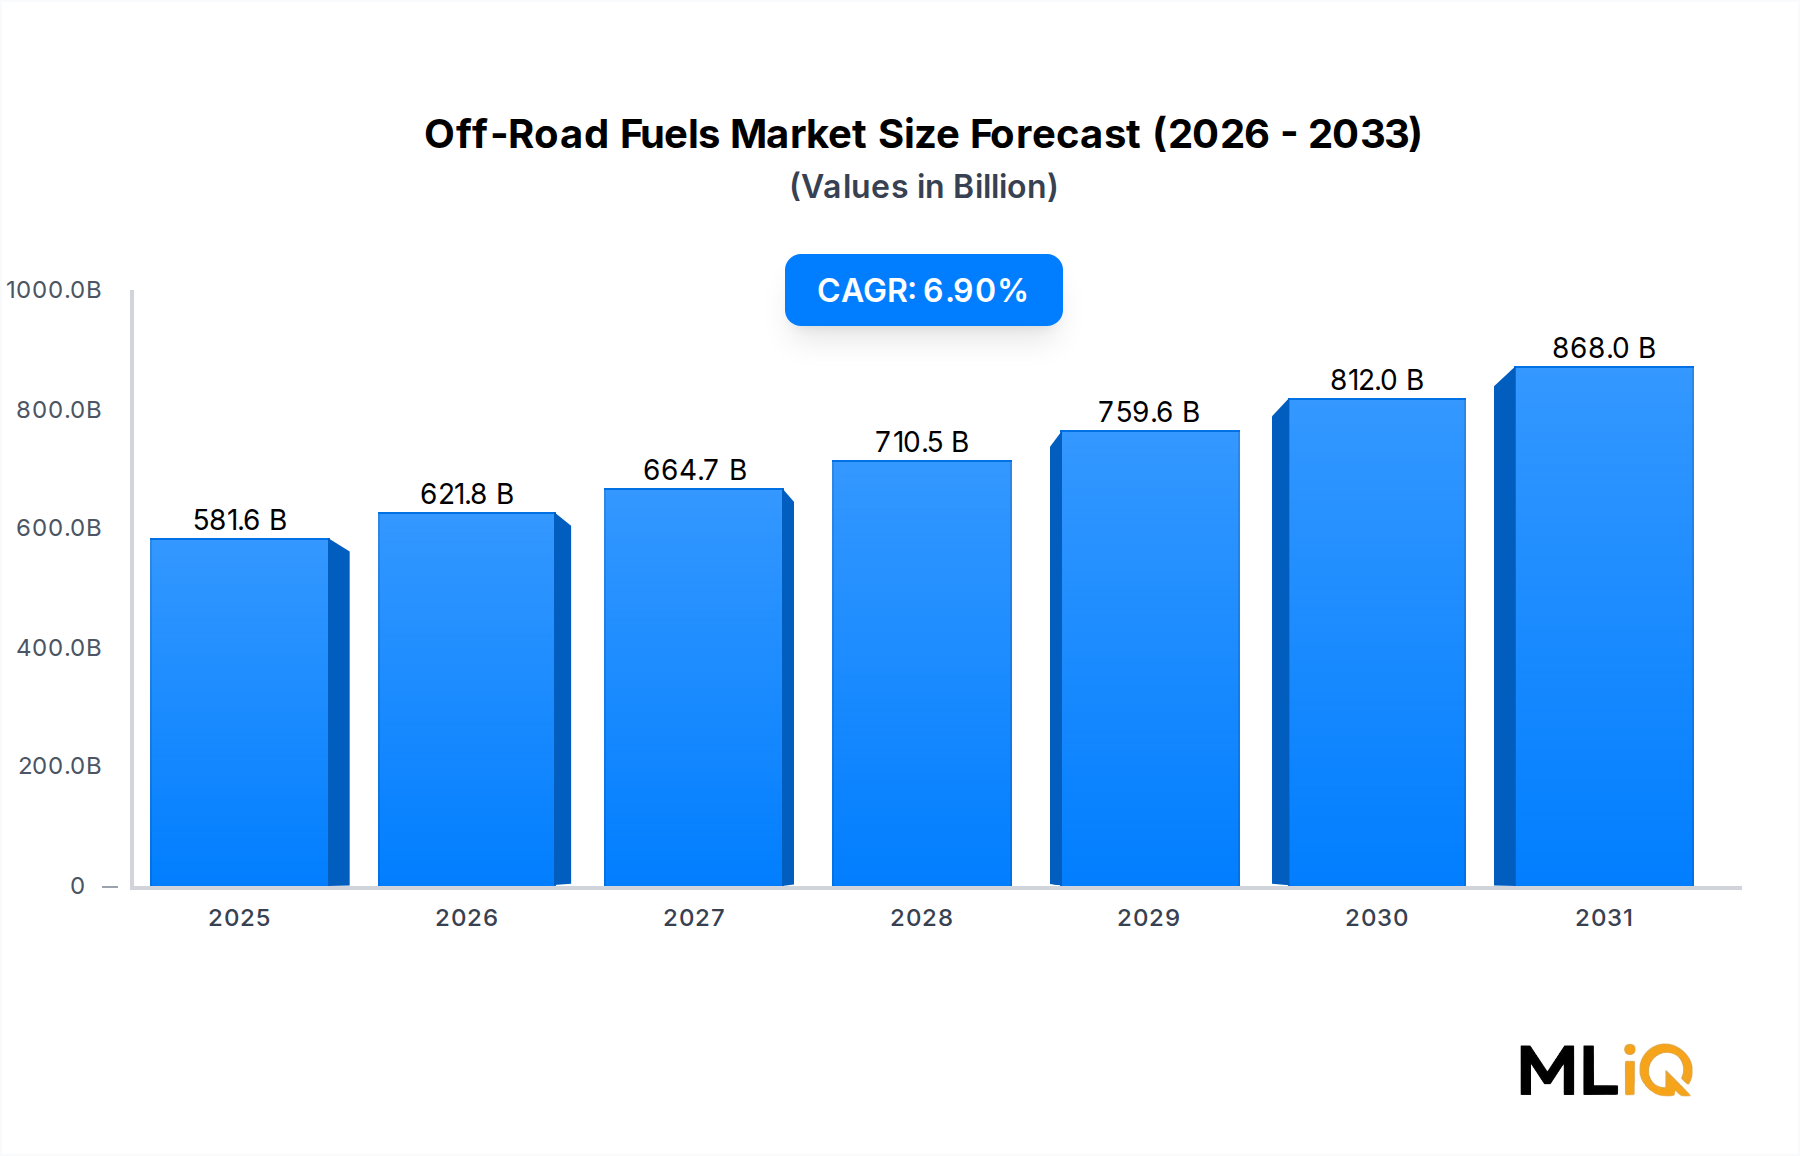
The Off-Road Fuels Market reached $544.1 billion in 2024 and is projected to reach $990.3 billion by 2033, expanding at a 6.9% CAGR. Demand is anchored in tax-exempt dyed diesel for agricultural, construction, and mining equipment. The Red Dyed Off-Road Diesel Market alone accounts for nearly half of product volume because red dye signals excise-tax exemption for non-highway use. The Construction Equipment Fuel Market is the fastest-growing application, supported by infrastructure spending and fleet expansion in Asia-Pacific and North America.
Off-Road Fuels Market Size (In Billion)
1000.0B
800.0B
600.0B
400.0B
200.0B
0
581.6 B
2025
621.8 B
2026
664.7 B
2027
710.5 B
2028
759.6 B
2029
812.0 B
2030
868.0 B
2031
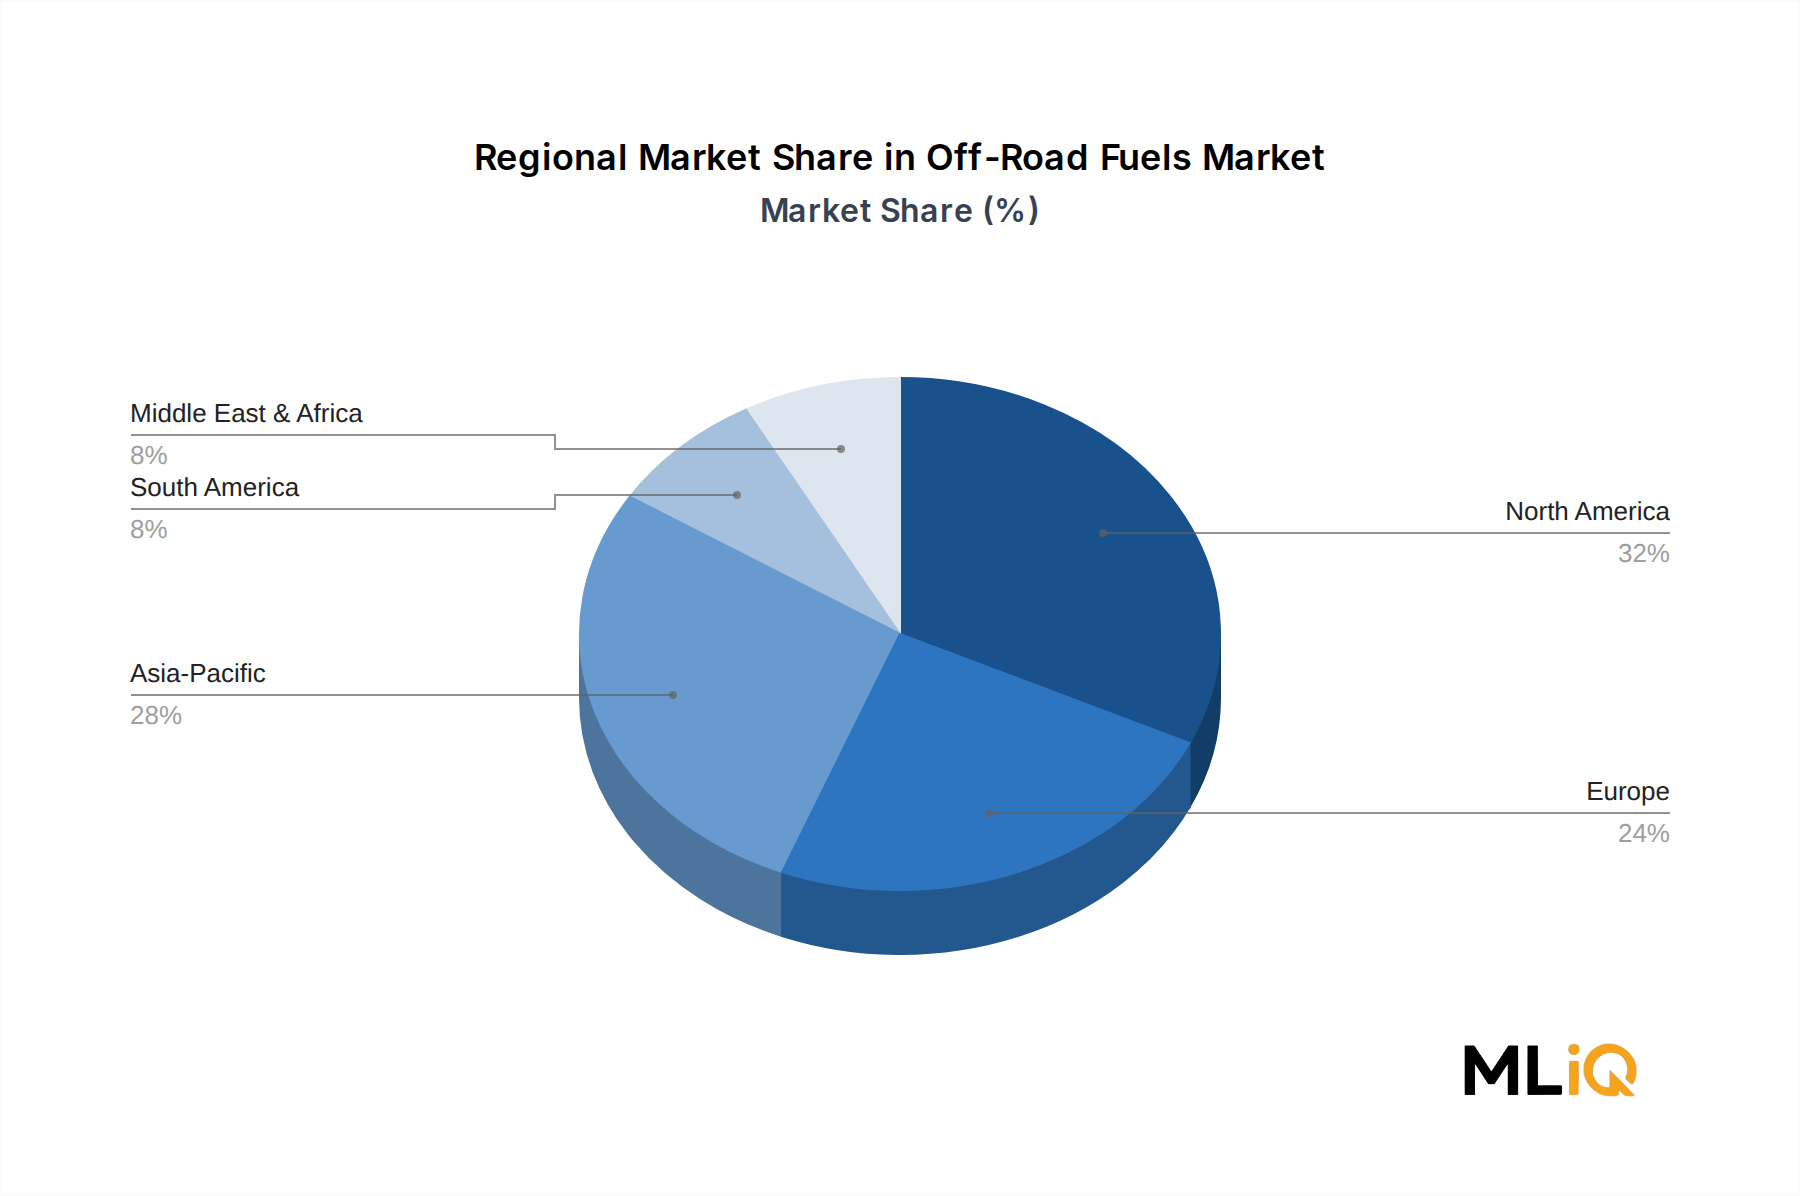
Regional momentum diverges. North America holds 32% of global revenue due to high equipment density and established fuel distribution. Asia-Pacific is the second-largest region at 28%, driven by China and India construction activity. Europe follows at 24%, where decarbonization rules are reshaping product specifications. South America and Middle East & Africa each contribute 8%, with growth linked to mining and agricultural exports.
Key macro drivers include:
Infrastructure investment: Global construction output above $13 trillion in 2024 increases off-road diesel consumption.
Agricultural mechanization: Tractor and harvester fleets in Brazil, India, and the U.S. rely on dyed diesel for field operations.
Mining output: Copper, lithium, and iron ore extraction require high-horsepower off-road equipment and bulk fuel deliveries.
Fuel marking regulation: Compliance programs in the U.S., EU, and India sustain demand for red, blue, and green dyed fuels.
Restraints include fuel theft, tax evasion enforcement, and electrification pilot programs in compact construction equipment. However, for heavy-duty mining and agricultural machinery, diesel remains dominant through 2033. The Distillate Fuel Market supplies the base stock for all off-road grades, tying off-road pricing to broader refining economics.
Segment Deep-Dive: Red Dyed Off-Road Fuels Dominance in Off-Road Fuels Market
Segment Analysis Matrix
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Red Dyed Off-Road Fuels
7.1
46
Tax-exempt agricultural and construction diesel
Blue Dyed Off-Road Fuels
6.2
18
Heating oil and industrial burner fuel
Green Dyed Off-Road Fuels
6.5
14
Mining and marine off-road applications
Others
5.8
22
Specialty dyed fuels and emergency generators
Red Dyed Off-Road Fuels: Core Revenue Engine
Red dyed diesel is the largest product category, generating approximately $250 billion in 2024. Its dominance stems from excise tax exemptions for farming, construction, and mining. In the United States, IRS rules require red dye concentration at 11.5 ppm for tax-exempt use. This regulatory moat limits substitution.
Blue Dyed and Green Dyed Fuels: Niche Compliance Segments
The Blue Dyed Off-Road Fuels Market serves heating oil and industrial burners, particularly in the U.S. Northeast and Europe. The Green Dyed Off-Road Fuels Market is smaller but growing in mining regions where environmental markers distinguish fuel for emissions tracking. Both segments face margin pressure from alternative heating sources and natural gas.
Application Sub-Segments
The Agricultural Diesel Market consumes 38% of off-road fuel volume, followed by construction at 27%, mining at 18%, heating oil at 12%, and others at 5%. The Mining Fuel Market is projected to grow at 7.4% CAGR due to copper and lithium demand. Construction Equipment Fuel Market growth is tied to public infrastructure packages in the U.S., EU, and India.
Margin Pressures
Off-road fuel margins are thin, typically 8–12% for distributors. Volatility in crude oil and refining spreads compresses margins. Terminal blenders and wholesalers manage risk through fuel surcharges and inventory hedging. The Diesel Exhaust Fluid Market is adjacent but separate, adding aftertreatment cost for fleet operators.
Primary Market Drivers & Growth Restraints in Off-Road Fuels Market
Factor Type
Description
Impact Level
Timeline
Driver
Global infrastructure and construction spending above $13 trillion
High
Long term
Driver
Agricultural mechanization in Brazil, India, and Southeast Asia
High
Long term
Driver
Mining capital expenditure for copper and lithium
High
Medium term
Driver
Excise tax exemptions for dyed diesel
Medium
Long term
Restraint
Electrification of compact construction equipment
Medium
Long term
Restraint
Fuel theft and tax evasion enforcement
Medium
Short term
Restraint
Refinery closures and distillate supply tightness
High
Short term
Quantitative evaluation: The Agricultural Diesel Market depends on planted acreage and tractor horsepower. In Brazil, soybean and corn area exceeded 90 million hectares in 2024, requiring 35 billion liters of diesel for farm operations. The Mining Fuel Market consumes roughly 8 billion liters annually in Chile, Peru, and Australia. Construction Equipment Fuel Market volumes are tied to highway, rail, and renewable energy projects.
Regulatory drivers include U.S. EPA ultra-low sulfur diesel rules and EU Fuel Quality Directive. These mandate 10 ppm sulfur maximum for off-road diesel, increasing hydrotreating costs. The Ultra-Low Sulfur Diesel Market is therefore integrated with off-road fuel production. Restraints include fuel switching to natural gas in mining haul trucks and battery-electric pilot fleets.
Renewable diesel blending and terminal infrastructure
Construction, mining, agriculture
Leader
Marathon Petroleum Company LP
Large-scale distillate production and distribution
Regional wholesalers, retail
Leader
Neste Oyj
Renewable and circular raw material diesel
ESG-focused fleets, mining
Challenger
Suncor Energy Inc.
Canadian oil sands integration and retail
Mining, construction, agriculture
Leader
Lehigh Fuels LLC
Regional off-road fuel distribution
Construction, farming
Niche
Lion Oil Company
Refining and wholesale dyed fuels
Agricultural cooperatives
Challenger
Whiteley Fuel Oil Company
Heating oil and off-road diesel delivery
Northeast U.S. heating, construction
Niche
Mauger & Co., Inc
Specialty fuel blending and marking
Industrial, mining
Niche
Exxon Mobil Corporation: Operates refineries and terminals that supply red dyed diesel across North America. Its scale enables cost leadership in bulk off-road fuel contracts.
Chevron Corporation: Invests in renewable diesel co-processing and maintains a strong position in mining and construction fuel supply.
Marathon Petroleum Company LP: Leverages Gulf Coast and Midwest refining to serve agricultural and construction distributors.
Neste Oyj: Produces renewable diesel from waste feedstocks, targeting mining and construction fleets with decarbonization mandates.
Suncor Energy Inc.: Supplies dyed diesel from Canadian refineries to mining and agricultural customers in North America.
Lehigh Fuels LLC: Regional distributor focused on construction and farming accounts in the U.S. Northeast.
Lion Oil Company: Refines and wholesales off-road fuels to agricultural cooperatives and independent retailers.
Whiteley Fuel Oil Company: Delivers heating oil and off-road diesel to commercial and residential customers.
Mauger & Co., Inc: Provides specialty fuel blending, dye injection, and compliance services for industrial fleets.
The Diesel Exhaust Fluid Market is not a direct substitute but influences total cost of ownership for off-road fleets. Vendor competition centers on terminal access, fuel quality, and compliance documentation.
Strategic Milestones & Recent Developments in Off-Road Fuels Market
Date
Company
Event Type
Impact
2023
Neste Oyj
Expansion
Increased renewable diesel capacity in Singapore to 2.6 million tons per annum
2024
Marathon Petroleum Company LP
Operational
Optimized Garyville refinery distillate output for off-road diesel supply
2024
Chevron Corporation
Partnership
Expanded renewable diesel blending at El Segundo for construction fleets
2025
Suncor Energy Inc.
Launch
Announced renewable diesel co-processing at Commerce City refinery
2025
Exxon Mobil Corporation
M&A
Acquired terminal assets to strengthen off-road fuel distribution
2024: Marathon Petroleum optimized distillate yields, supporting reliable supply of red dyed off-road fuel.
2024: Chevron partnered with construction fleet operators to test renewable diesel blends above 20%.
2025: Suncor Energy announced co-processing of biofeedstocks, targeting mining customers in Canada.
2025: Exxon Mobil acquired terminal assets, improving bulk delivery for agricultural and construction distributors.
Regional Market Analysis & Growth Corridors for Off-Road Fuels Market
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
6.1
$174.1 billion
Infrastructure and agricultural demand
High
Europe
5.8
$130.6 billion
Heating oil and construction
Very High
Asia-Pacific
8.2
$152.3 billion
Construction and mining expansion
Medium
LAMEA
7.5
$87.1 billion
Mining, agriculture, and fuel distribution
Low to Medium
North America is the most mature market, with 32% share. The Ultra-Low Sulfur Diesel Market is fully regulated, and red dyed diesel volumes are stable. Europe follows at 24%, but regulatory stringency is highest due to EU decarbonization targets. Asia-Pacific is the fastest-growing region at 8.2% CAGR, driven by China, India, and ASEAN construction. LAMEA offers emerging opportunities in Brazil, Chile, and South Africa.
Fastest-growing: Asia-Pacific, led by India's $1.4 trillion infrastructure pipeline and China's mining output.
Most mature: North America, where off-road diesel demand grows with replacement and fleet expansion.
Europe: High regulatory pressure accelerates renewable diesel and HVO blending.
LAMEA: Mining corridors in Chile and Peru require reliable off-road fuel logistics.
Average selling prices for red dyed off-road diesel track the Distillate Fuel Market with a discount of 10–20 cents per gallon versus clear on-highway diesel. In 2024, U.S. off-road diesel averaged $3.45 per gallon, while European gasoil prices were higher due to taxes and specification. Margin pressure is intense for distributors because crude volatility can swing input costs by 30% within a year. Pricing power is limited unless suppliers offer guaranteed supply, fuel quality, and compliance documentation. Terminal blenders use hedging and fuel surcharges to protect 8–12% gross margins.
Sustainability, ESG & Decarbonization Pressures on Off-Road Fuels Market
ESG Pressure
Impact on Off-Road Fuels
Timeline
Net-zero targets
Renewable diesel and HVO blending mandates
2025–2035
Circular economy
Waste feedstock and used cooking oil sourcing
Medium term
Investor ESG criteria
Disclosure of Scope 1 and 3 emissions
Short term
Air quality rules
Ultra-low sulfur and dye marker compliance
Ongoing
Carbon pricing
Higher operating costs for diesel fleets
Long term
Environmental regulations are reshaping raw material selection. The Ultra-Low Sulfur Diesel Market requires hydrotreating, while renewable diesel from Neste Oyj and Chevron uses waste oils and fats. ESG investor criteria push refiners to disclose carbon intensity per gallon. Mining and construction fleets face pressure to blend 10–30% renewable diesel. However, red dyed diesel remains essential for tax-exempt agricultural and construction use through 2033. Circular economy mandates increase demand for bio-based feedstocks, but supply is constrained by competing uses in sustainable aviation fuel. Procurement preferences are shifting toward low-carbon off-road fuels, yet cost remains the primary barrier for price-sensitive farming and construction customers.
Off-Road Fuels Market Segmentation
1. Product Type
1.1. Red Dyed Off Road Fuels
1.2. Blue Dyed Off Road Fuels
1.3. Green Dyed Off Road Fuels
1.4. Others
2. Application
2.1. Heating Oil
2.2. Farming
2.3. Construction
2.4. Mining
2.5. Others
Off-Road Fuels Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Off-Road Fuels Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.9% from 2020-2034
Segmentation
By Product Type
Red Dyed Off Road Fuels
Blue Dyed Off Road Fuels
Green Dyed Off Road Fuels
Others
By Application
Heating Oil
Farming
Construction
Mining
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Red Dyed Off Road Fuels
5.1.2. Blue Dyed Off Road Fuels
5.1.3. Green Dyed Off Road Fuels
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Heating Oil
5.2.2. Farming
5.2.3. Construction
5.2.4. Mining
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Red Dyed Off Road Fuels
6.1.2. Blue Dyed Off Road Fuels
6.1.3. Green Dyed Off Road Fuels
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Heating Oil
6.2.2. Farming
6.2.3. Construction
6.2.4. Mining
6.2.5. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Red Dyed Off Road Fuels
7.1.2. Blue Dyed Off Road Fuels
7.1.3. Green Dyed Off Road Fuels
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Heating Oil
7.2.2. Farming
7.2.3. Construction
7.2.4. Mining
7.2.5. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Red Dyed Off Road Fuels
8.1.2. Blue Dyed Off Road Fuels
8.1.3. Green Dyed Off Road Fuels
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Heating Oil
8.2.2. Farming
8.2.3. Construction
8.2.4. Mining
8.2.5. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Red Dyed Off Road Fuels
9.1.2. Blue Dyed Off Road Fuels
9.1.3. Green Dyed Off Road Fuels
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Heating Oil
9.2.2. Farming
9.2.3. Construction
9.2.4. Mining
9.2.5. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Red Dyed Off Road Fuels
10.1.2. Blue Dyed Off Road Fuels
10.1.3. Green Dyed Off Road Fuels
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Heating Oil
10.2.2. Farming
10.2.3. Construction
10.2.4. Mining
10.2.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Exxon Mobil Corporation
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Lehigh Fuels LLC
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Neste Oyj
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Mauger & Co.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Inc
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Lion Oil Company
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Whiteley Fuel Oil Company
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Suncor Energy Inc.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Chevron Corporation
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Marathon Petroleum Company LP
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Off-Road Fuels Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Off-Road Fuels Market Revenue (billion), by Product Type 2026 & 2034
Figure 3: North America Off-Road Fuels Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Off-Road Fuels Market Revenue (billion), by Application 2026 & 2034
Figure 5: North America Off-Road Fuels Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Off-Road Fuels Market Revenue (billion), by Country 2026 & 2034
Figure 7: North America Off-Road Fuels Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Off-Road Fuels Market Revenue (billion), by Product Type 2026 & 2034
Figure 9: South America Off-Road Fuels Market Revenue Share (%), by Product Type 2026 & 2034
Figure 10: South America Off-Road Fuels Market Revenue (billion), by Application 2026 & 2034
Figure 11: South America Off-Road Fuels Market Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Off-Road Fuels Market Revenue (billion), by Country 2026 & 2034
Figure 13: South America Off-Road Fuels Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Off-Road Fuels Market Revenue (billion), by Product Type 2026 & 2034
Figure 15: Europe Off-Road Fuels Market Revenue Share (%), by Product Type 2026 & 2034
Figure 16: Europe Off-Road Fuels Market Revenue (billion), by Application 2026 & 2034
Figure 17: Europe Off-Road Fuels Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Off-Road Fuels Market Revenue (billion), by Country 2026 & 2034
Figure 19: Europe Off-Road Fuels Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Off-Road Fuels Market Revenue (billion), by Product Type 2026 & 2034
Figure 21: Middle East & Africa Off-Road Fuels Market Revenue Share (%), by Product Type 2026 & 2034
Figure 22: Middle East & Africa Off-Road Fuels Market Revenue (billion), by Application 2026 & 2034
Figure 23: Middle East & Africa Off-Road Fuels Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Middle East & Africa Off-Road Fuels Market Revenue (billion), by Country 2026 & 2034
Figure 25: Middle East & Africa Off-Road Fuels Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Off-Road Fuels Market Revenue (billion), by Product Type 2026 & 2034
Figure 27: Asia Pacific Off-Road Fuels Market Revenue Share (%), by Product Type 2026 & 2034
Figure 28: Asia Pacific Off-Road Fuels Market Revenue (billion), by Application 2026 & 2034
Figure 29: Asia Pacific Off-Road Fuels Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Off-Road Fuels Market Revenue (billion), by Country 2026 & 2034
Figure 31: Asia Pacific Off-Road Fuels Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Off-Road Fuels Market Revenue billion Forecast, by Product Type 2020 & 2034
Table 46: Rest of Asia Pacific Off-Road Fuels Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–30 research split: 70–80% of data is collected through primary interviews and surveys; 20–30% is validated through secondary sources.
We interview Off-Road Fuel Procurement Directors, Fleet Fuel Operations Managers, Regulatory Compliance and Excise Tax Managers, and Refinery Distillate Supply Chain Analysts.
Primary contacts include red-dyed off-road diesel terminal blenders and regional fuel wholesalers, agricultural cooperative fuel distributors, construction and mining equipment fleet fuel management providers, fuel dye and marker additive manufacturers, and diesel exhaust fluid (DEF) producers and bulk DEF distributors.
All reports are updated to the date of purchase, incorporating the latest excise tax changes, refinery outages, and fuel marking rules.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up quantitative metrics include number of registered agricultural, construction, and mining diesel equipment units by region; average annual off-road diesel consumption per equipment unit by application; percentage of dyed diesel volume versus clear diesel in total distillate sales; excise tax exemption volumes and red-dye marker concentration compliance rates; and fleet fuel card transaction volumes and average refueling frequency.
Top-down modeling uses national distillate supply, tax-exempt fuel volumes, and equipment population forecasts.
Segment and regional splits are cross-checked against trade association data and refinery production reports.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%.
Every data point is triangulated across at least three independent sources, including primary interviews, government statistics, and financial filings.
Outlier detection, growth-rate sanity checks, and historical back-testing are applied to all forecasts.
Final estimates are reviewed by senior analysts with domain expertise in off-road fuels, excise tax policy, and distillate refining.
Frequently Asked Questions
1. What are the key segments and product types in the Off-Road Fuels Market?
The market is segmented by product type into red dyed, blue dyed, green dyed, and other off-road fuels. Red dyed off-road fuels dominate with about 46% of volume because they serve tax-exempt agricultural, construction, and mining equipment. By application, farming, construction, mining, and heating oil are the largest end uses.
2. What are the primary growth drivers and demand catalysts for the Off-Road Fuels Market?
Infrastructure spending above $13 trillion, agricultural mechanization in Brazil and India, and mining output for copper and lithium are primary drivers. The Construction Equipment Fuel Market is growing at 7.1% CAGR, while the Agricultural Diesel Market consumes 38% of off-road fuel volume. Excise tax exemptions for dyed diesel also sustain demand.
3. How do export-import dynamics and international trade flows affect the Off-Road Fuels Market?
Off-road fuels are largely consumed domestically because dyeing and tax exemptions are national. However, distillate trade flows from the U.S. Gulf Coast, Middle East, and India influence prices in import-dependent regions like Europe. In 2024, global distillate exports exceeded 1.2 billion barrels, linking off-road diesel prices to international markets.
4. What post-pandemic recovery patterns and long-term structural shifts are visible in the Off-Road Fuels Market?
After the 2020 demand shock, off-road diesel volumes recovered by 2022 as construction and mining restarted. Long-term shifts include renewable diesel blending, stricter sulfur limits, and fleet telematics for fuel management. The Ultra-Low Sulfur Diesel Market is now standard, and ESG criteria are reshaping procurement.
5. What raw material sourcing and supply chain considerations shape the Off-Road Fuels Market?
Crude oil, biofeedstocks, and dye additives are key raw materials. Refinery closures in the U.S. and Europe have tightened distillate supply, while renewable diesel feedstocks like used cooking oil face competition from sustainable aviation fuel. Distributors manage supply chain risk through terminal contracts and inventory hedging.
6. Which region is fastest-growing and what emerging geographic opportunities exist in the Off-Road Fuels Market?
Asia-Pacific is the fastest-growing region at 8.2% CAGR, driven by India's $1.4 trillion infrastructure pipeline and China's mining sector. LAMEA offers emerging opportunities in Brazil, Chile, and South Africa, where agricultural and mining diesel demand is rising. North America remains the largest market at 32% share.