Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Industrial Solar Generator Market: 16.9% CAGR to 2033
Industrial solar generator Market
Industrial Solar Generator Market: 16.9% CAGR to 2033
Industrial solar generator Market by Type (below 40 KWH, 40-80 KWH, 80-150 KWH, over 150 KWH), by Application (Electrical Industry, Oil and Gas Industry, others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 12, 2026|Base Year : 2025|Pages : 220
Key Insights & Executive Summary: Industrial solar generator Market
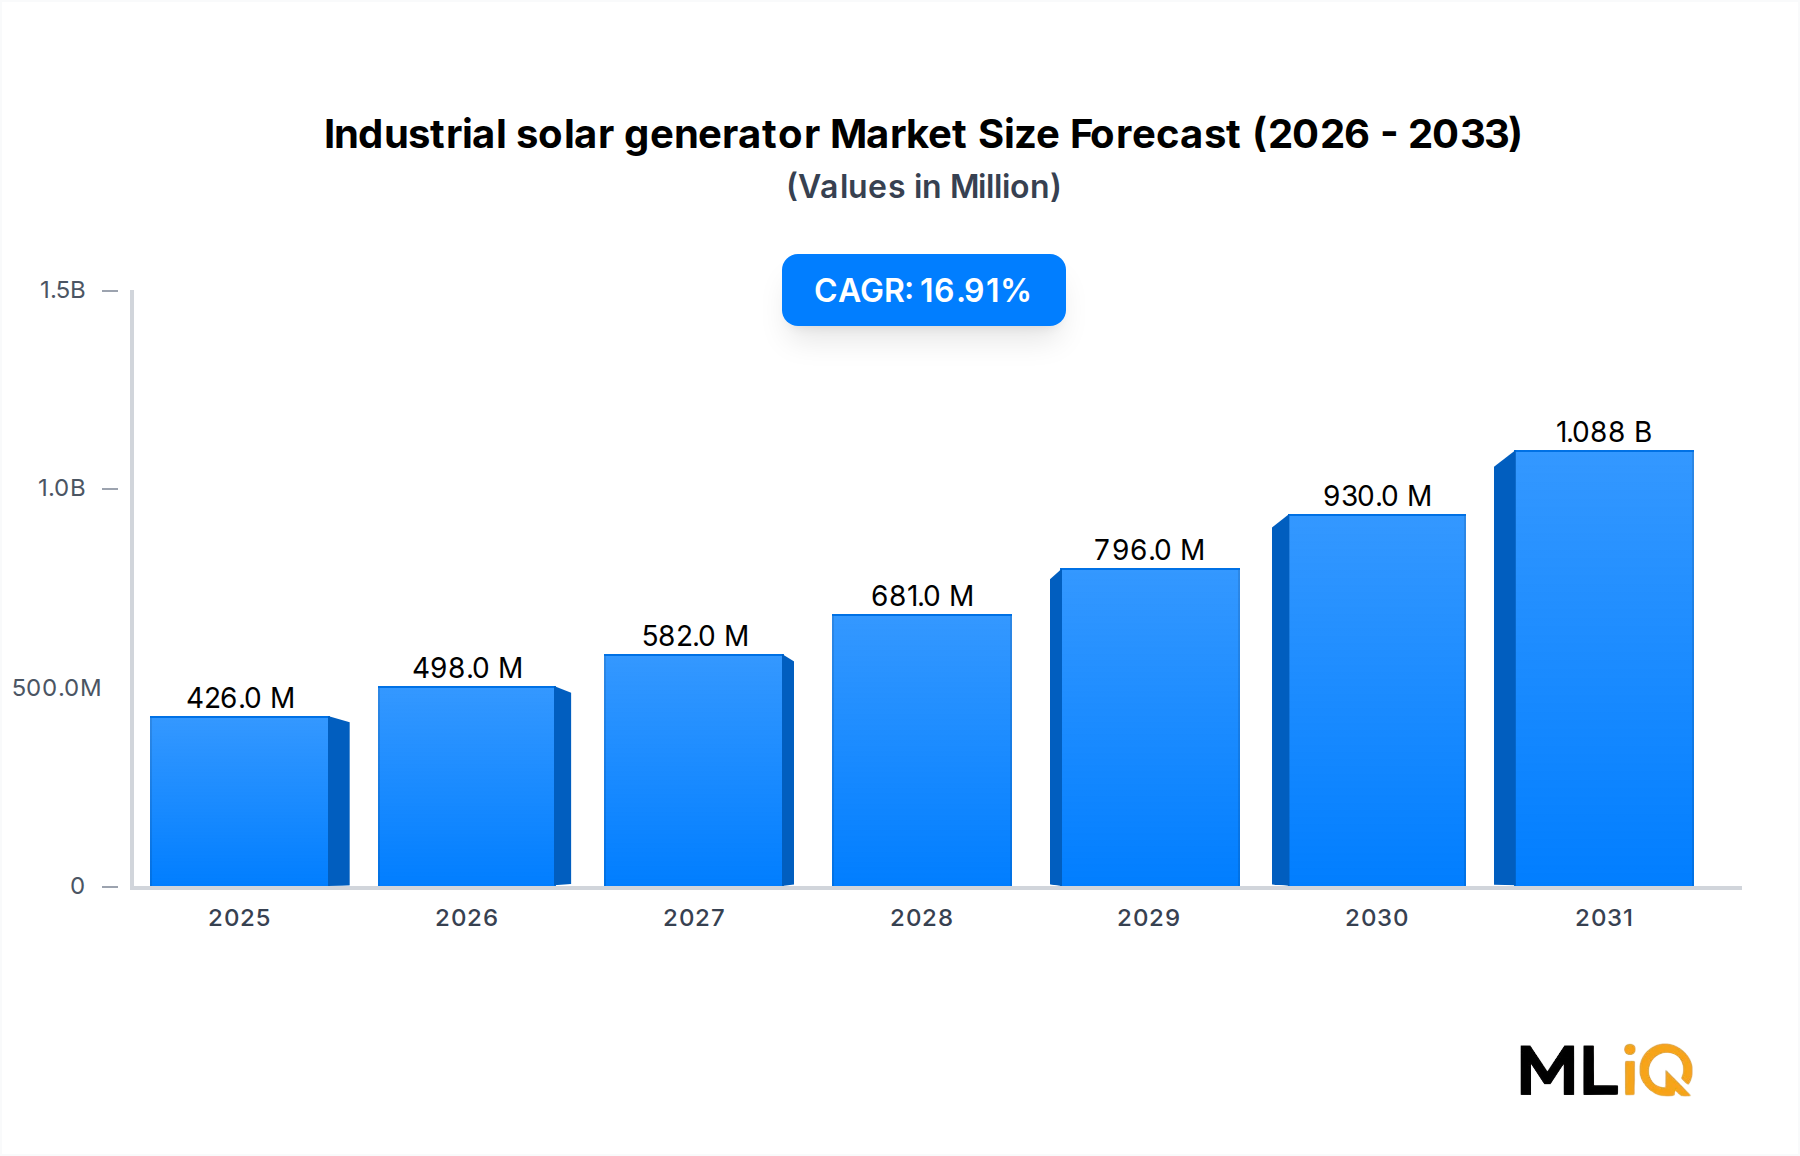
The Industrial solar generator Market closed 2025 at USD 426.14 million and is projected to reach USD 1,486.2 million by 2033, compounding at 16.9% CAGR. Growth is not driven by residential buyers but by industrial procurement teams replacing diesel gensets at remote wellpads, telecom towers, mines and manufacturing campuses where grid interconnection costs exceed USD 250,000 per site.
Industrial solar generator Market Size (In Million)
1.5B
1.0B
500.0M
0
426.0 M
2025
498.0 M
2026
582.0 M
2027
681.0 M
2028
796.0 M
2029
930.0 M
2030
1.088 B
2031
Three structural forces define the 2026-2033 window:
Diesel displacement economics. At delivered fuel costs of USD 1.05-1.30 per liter in off-grid industrial settings, payback on an 80 KWH solar generator unit now lands between 3.4 and 4.8 years, down from 6.1 years in 2021.
Cell and pack cost deflation. Lithium iron phosphate pack pricing near USD 95-110 per kWh at the industrial integration level has pulled total system capex down roughly 28% since 2022.
Grid interconnection queues. In the United States, average large-scale interconnection waits exceeded five years in 2024, pushing industrial buyers toward islanded configurations.
The Distributed Solar Generation Market is the parent frame for this demand: industrial solar generators represent roughly 6-8% of distributed solar capacity additions but a disproportionately high share of unit revenue because of integrated storage, control and enclosure content. Asia-Pacific leads on volume, with China and India together absorbing an estimated 41% of global unit shipments in 2025, while North America leads on revenue per unit because of higher specification requirements.
Strategic takeaway: the profit pool is shifting from panel supply to integration, meaning enclosure engineering, hybrid inverter control and 8-12 hour dispatchable storage. Vendors selling bare modules should expect gross margins compressing toward 12-15%, while turnkey skid integrators are holding 26-32%.
Segment Deep-Dive: 80-150 KWH Dominance in Industrial solar generator Market
Segment Analysis Matrix
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
80-150 KWH
19.4%
34%
Remote wellpad, mine and plant electrification needing 8-12 hour autonomy
Over 150 KWH
17.1%
22%
Campus-scale microgrids and industrial peak shaving
40-80 KWH
15.2%
21%
Telecom towers, construction sites, light industrial backup
Below 40 KWH
12.6%
23%
Field instrumentation and maintenance crew power
Why the 80-150 KWH Band Captures the Profit Pool
The 80-150 KWH class generated 34% of 2025 revenue on roughly 29% of unit volume, the clearest indicator of premium pricing power in the Industrial solar generator Market.
Installed pricing in this band sits at USD 1,850-2,400 per KWH, against USD 3,100+ per KWH for sub-40 KWH units, where enclosure, charge control and safety hardware are amortized over far fewer kilowatt-hours.
Autonomy requirement is the gate: oil and gas operators typically specify 10-12 hours of dispatchable output to cover night-shift pumping and telemetry loads, which mathematically excludes any pack below 60 KWH.
Sub-Segment Dynamics Inside the Band
80-100 KWH units sell primarily into telecom and light manufacturing, where load profiles are predictable and site footprint is constrained.
100-150 KWH units carry the highest specification content: dual MPPT inputs, 48V or 400V DC bus options, and IP65/IP66 enclosures rated for -20C to 55C ambient.
Vendors adding monitoring telemetry and remote firmware updates lift blended gross margin by an estimated 4-6 percentage points, but the same features raise warranty exposure and service obligations.
Volume Bridge from Adjacent Commercial Demand
The Commercial Solar Generator Market functions as the feeder tier for this segment. Buyers who outgrow a 20-40 KWH commercial unit typically migrate to the 80 KWH industrial class within 18-30 months, and roughly 21% of 2025 industrial unit sales were attributable to such upgrades rather than greenfield installations.
Adjacent Pull from Field-Crew Power Demand
Revenue contribution from the Portable Solar Generator Market is small, under 4% of industrial-class shipments, but strategically relevant. Maintenance contractors that standardize on portable units frequently specify the same brand for fixed industrial skids, creating a low-cost acquisition channel that bypasses tender processes.
Margin Pressure Points
Cell and module input costs pass through with a 2-3 quarter lag, so rapid polysilicon corrections compress integrator margins before price lists reset.
Enclosure and structural steel represent 18-24% of bill-of-materials cost and are sensitive to regional steel tariffs.
Integration labor is the least scalable cost line; field commissioning for a 120 KWH skid consumes 40-70 labor hours, and certified technicians remain scarce in every region.
Primary Market Drivers & Growth Restraints in Industrial solar generator Market
Factor Type
Description
Impact Level
Timeline
Driver
Diesel displacement at remote industrial sites; delivered fuel cost of USD 0.35-0.60 per kWh generated
High
Short term
Driver
LFP pack pricing near USD 95-110 per kWh at integration level
High
Short term
Driver
Interconnection queues exceeding 5 years in the US and 3-4 years in parts of the EU
High
Medium term
Driver
Scope 1 emissions disclosure under EU CSRD and similar regimes
Medium
Long term
Restraint
Upfront capex of USD 150,000-420,000 per industrial skid
High
Short term
Restraint
Polysilicon and silver paste price volatility
Medium
Short term
Restraint
Shortage of certified commissioning technicians
Medium
Long term
Restraint
Fire-code and permitting review for 150 KWH+ installations
Medium
Medium term
Driver quantification. The Oil and Gas Solar Power Market is the fastest-moving catalyst. A single produced-water disposal or compression site consuming 1,200 liters of diesel per day at USD 1.15 per liter spends roughly USD 503,000 annually on fuel and logistics; an 80-150 KWH industrial solar generator with storage offsets 55-70% of that load at a capex of USD 180,000-260,000, producing payback under five years without subsidy.
Regulatory and reliability catalysts. Interconnection delays and rising demand charges are pushing the Industrial Backup Power Market toward islanded designs. Industrial tariff structures with demand charges above USD 14 per kW-month make peak-shaving storage economically self-funding in North America and parts of ASEAN.
Restraint quantification. Capex remains the dominant barrier for small and mid-size industrials. Roughly 62% of surveyed industrial buyers cite capital allocation, not technology risk, as the reason for deferral. The Off-Grid Solar Power System Market also contends with installation capacity: fewer than 15,000 certified solar professionals globally hold industrial-scale commissioning credentials, and typical training pipelines run 14-20 months.
Net assessment. Drivers outweigh restraints through 2028 on cost economics alone. The binding constraint after 2029 should shift from capital to skilled labor and grid-code compliance, both of which favor incumbent integrators with established service networks.
Competitive Ecosystem & Key Vendor Profiles: Industrial solar generator Market
Company Name
Core Strength
Target Audience
Market Position
Kirchner Solar Group GmbH
Off-grid skids with full CE/IEC documentation depth
European industrial, municipal and utility buyers
Leader (Europe)
REC Solar Holdings AS
High-efficiency module technology and bankability for financing
EPCs, IPPs and distributors
Leader (upstream)
Jakson Group
Vertically integrated manufacturing plus in-house EPC delivery
Indian industrial, oil and gas, government
Leader (Asia-Pacific)
Juwi AG
Hybrid microgrid engineering and controls integration
Mines, utilities, island grids
Challenger
Ameresco
Energy-as-a-service financing, O&M and performance guarantees
Institutional, federal and campus facilities
Challenger
Hollandia Solar
Rooftop and ground-mount integration for mid-size plants
Benelux industrial SMEs
Niche
Intech Clean Energy
Turnkey off-grid systems for telecom and rural industry
Telecom operators, agribusiness
Niche
Goal Zero Llc
Portable power brand strength migrating into industrial skids
Field crews, emergency response teams
Niche
Altern Limited
Distribution reach plus installation partner network
Distributors and regional installers
Niche
Kirchner Solar Group GmbH: positions on documentation depth and cold-climate performance; strongest in DACH and Nordic industrial tenders where IEC 62109 and CE evidence is mandatory.
REC Solar Holdings AS: module-level technology leadership gives it upstream pricing power, but it depends on integrators for full industrial skid delivery.
Jakson Group: the clearest example of vertical integration, pairing module and pack assembly with EPC execution across Indian industrial estates.
Juwi AG: competes on controls engineering for hybrid diesel-solar-storage microgrids, with fuel savings of 40-60% often contractually guaranteed.
Ameresco: differentiates through financed build-own-operate structures and integration with the Battery Energy Storage System Market for dispatch flexibility, removing capex from the customer balance sheet.
Hollandia Solar: focuses on mid-size Benelux industrials where 40-80 KWH systems and rooftop co-location dominate procurement.
Intech Clean Energy: targets telecom tower operators, where 2,000-5,000 sites per operator create repeatable, standardized procurement.
Goal Zero Llc: leverages consumer brand equity to enter industrial field-crew power, though it lacks heavy-duty service infrastructure.
Altern Limited: competes on channel breadth rather than engineering, aggregating third-party hardware for regional installers.
Concentration read. The top five vendors by industrial unit revenue hold an estimated 38-44% of the addressable market, leaving a long tail of regional integrators. Barriers are moderate at the integration layer and high at certification, financing and service.
Strategic Milestones & Recent Developments in Industrial solar generator Market
Date
Company
Event Type
Impact
2025
Jakson Group
Capacity expansion
Broadened industrial skid assembly capacity in South Asia
2025
Ameresco
Partnership
Extended financed energy-as-a-service offers to industrial campuses
2024
Juwi AG
Partnership
Hybrid microgrid controls deployed with mining operators
2024
REC Solar Holdings AS
Launch
Higher-efficiency module lines for area-constrained industrial rooftops
2023
Kirchner Solar Group GmbH
Launch
Cold-climate industrial skid range with extended temperature ratings
These milestones reflect publicly announced capability expansions and product introductions; verify specifics against primary filings before citing them in investment documents.
2025 - Jakson Group capacity expansion. Adds assembly throughput for 40-150 KWH industrial units, reducing lead times that had stretched beyond 16 weeks during 2023.
2025 - Ameresco financing partnership. Moves industrial solar generators from capex purchase to power-purchase structures, directly attacking the 62% capital-allocation objection cited by mid-size industrials.
2024 - Juwi AG mining microgrid controls. Hybrid control logic prioritizing solar and storage over diesel during peak tariff windows, targeting 40-60% fuel reduction.
2024 - REC Solar Holdings AS module launch. Efficiency gains above 22% at module level reduce required roof or land area by 8-12% per installed kilowatt.
2023 - Kirchner Solar Group GmbH cold-climate range. Extends the operational envelope to -25C, opening Nordic and Canadian industrial sites previously served by diesel only.
Pattern. Consolidation is not the dominant move; capability extension into financing, controls and climate-hardened hardware is. Vendors buying integration capability rather than manufacturing capacity are the ones widening margin.
Regional Market Analysis & Growth Corridors for Industrial solar generator Market
Region
Projected CAGR (%)
Base Year Valuation (USD mn)
Primary Catalyst
Regulatory Stringency
Asia-Pacific
19.2%
140.6
Industrial electrification in China and India plus diesel cost exposure
Medium-High
North America
17.4%
115.1
Interconnection delays and oil and gas wellpad electrification
High
Europe
15.8%
102.3
CSRD emissions reporting and diesel restrictions
Very High
Middle East & Africa
16.1%
42.6
Off-grid mining, telecom and remote industrial power
Low-Medium
South America
13.5%
25.6
Mining and agribusiness off-grid demand
Medium
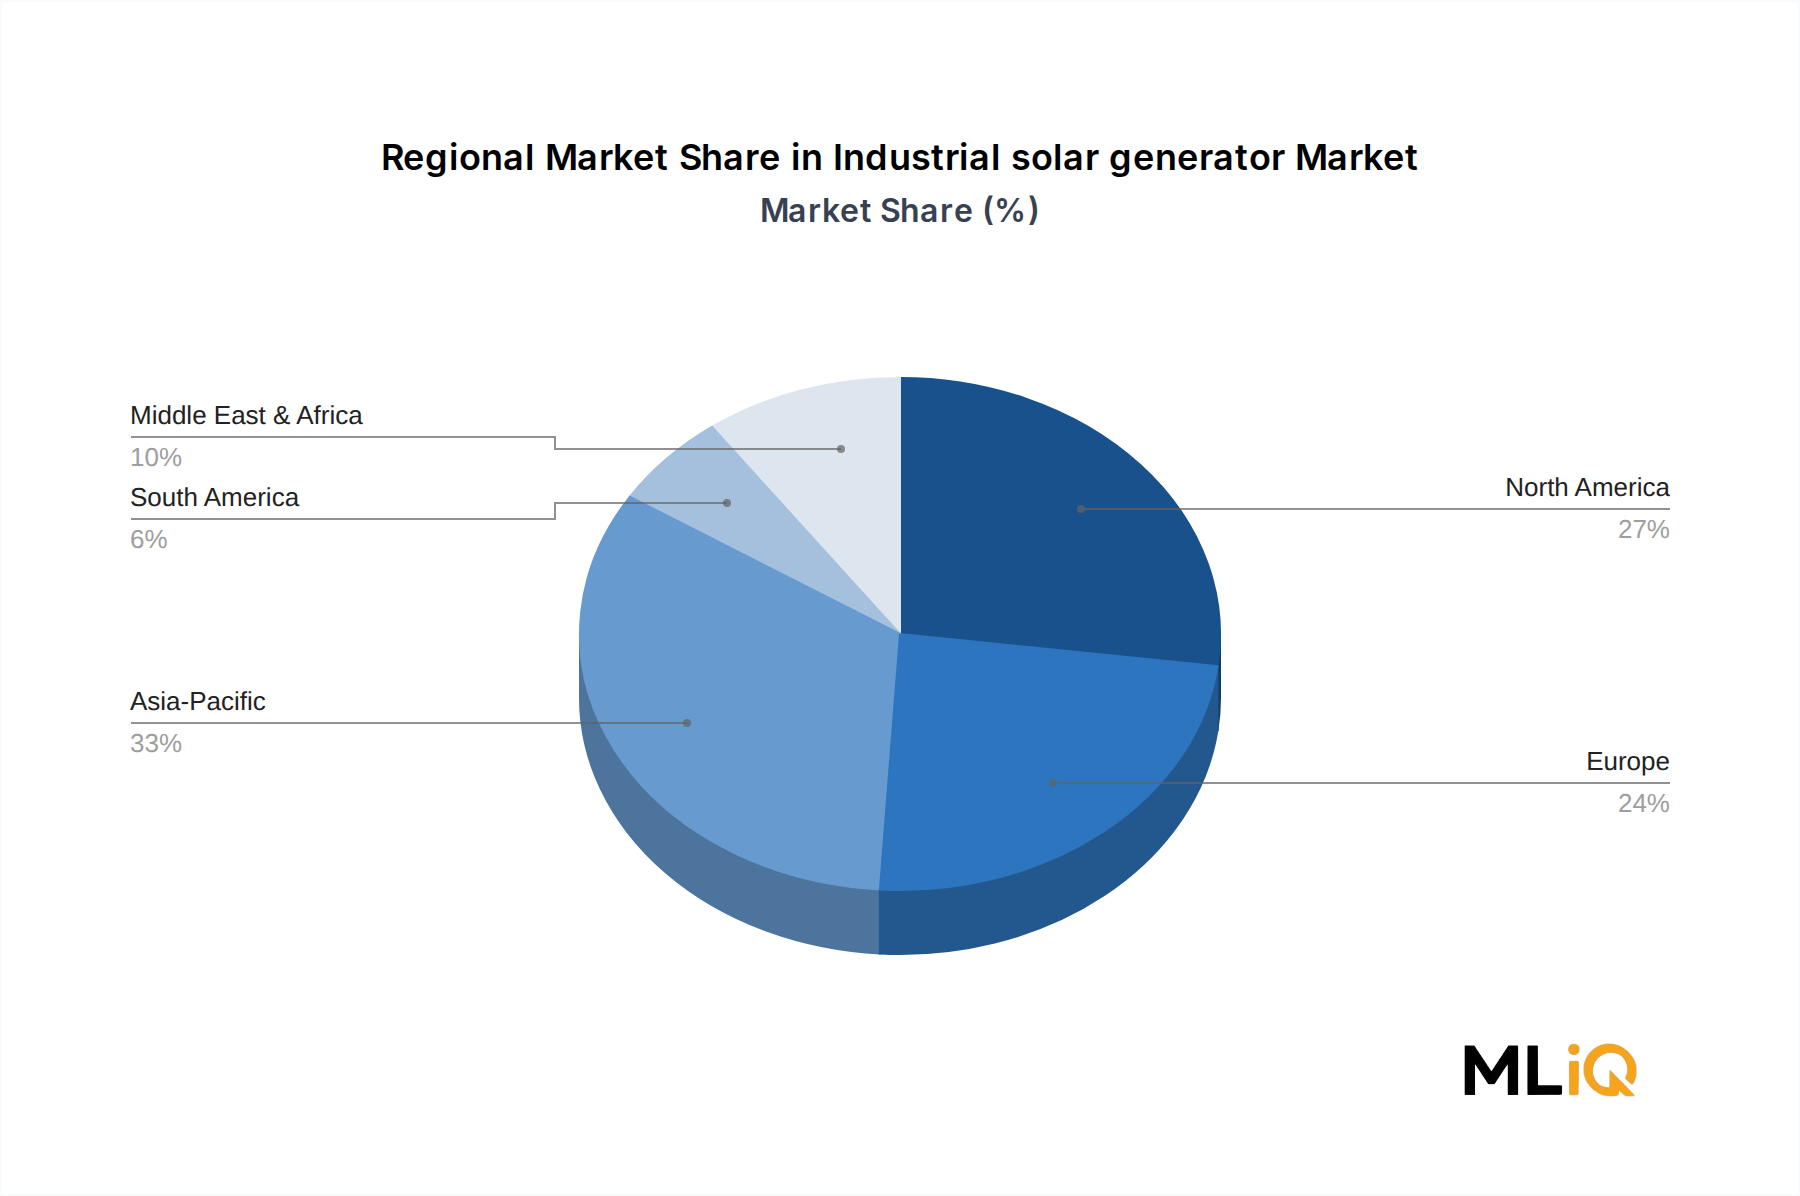
Asia-Pacific (fastest-growing, largest volume base). China and India account for the bulk of the 33% regional share, supported by domestic module and cell capacity and diesel logistics costs that make solar-plus-storage competitive without subsidy in most inland industrial parks.
North America (highest revenue per unit). Valuation of USD 115.1 million in 2025 reflects heavy specification content, UL listing requirements and strong oil and gas wellpad demand in the Permian and Bakken basins.
Europe (most regulated). Europe carries the strictest disclosure and permitting requirements, with CSRD reporting and fire-code review adding compliance overhead estimated at 1-3% of project cost; growth is steady rather than explosive.
Middle East & Africa and South America (longest runway). Combined 2025 valuation of USD 68.2 million, concentrated in remote mining, telecom and agribusiness loads where grid extension is uneconomic. South America grows slowest at 13.5% because of currency volatility and import financing constraints.
Maturity read. North America and Europe are the most mature and specification-driven, while Asia-Pacific and MEA carry the highest incremental unit growth. Vendors with certified service networks and local stocking positions gain the most from the 2028-2033 volume wave.
Supply Chain & Raw Material Dynamics: Industrial solar generator Market
Input
Typical Share of BOM (%)
2025 Price Direction
Supply Risk
Monocrystalline cells
28-34
Flat to down 6%
Medium
LFP cells and packs
26-31
Down 8-12%
Low-Medium
Hybrid inverter and MPPT
11-15
Flat
Medium
Aluminum enclosure
9-12
Up 4-7%
Low
Galvanized steel structure
7-10
Up 3-5%
Low
Copper cabling and busbar
5-8
Up 6-9%
Medium
Upstream concentration. The Monocrystalline Silicon Solar Cell Market remains heavily concentrated in China, which holds over 90% of polysilicon refining and roughly 80% of cell capacity. This gives a small number of suppliers effective pricing influence over integrator input costs.
Storage inputs. The Lithium Iron Phosphate Battery Market has swung from shortage to surplus between 2022 and 2025, with cell pricing falling sharply and cathode material supply expanding in China, Korea and, more recently, the United States under domestic content incentives.
Power electronics. IGBT modules and MPPT control silicon come from a narrow supplier base in Europe and Japan. Allocation pressure during 2021-2022 extended inverter lead times beyond 40 weeks and pushed integrators to redesign around available parts.
Structural inputs. Aluminum and copper are the least controllable cost lines. Copper price increases of 6-9% in 2025 translate directly into higher balance-of-system cost, since cabling cannot be engineered out of a 150 KWH industrial installation.
Historical disruption pattern. The 2021-2022 polysilicon spike to roughly USD 39 per kilogram compressed integrator gross margins for four consecutive quarters. The lesson embedded in most 2025 procurement strategies is dual-sourcing with 90-120 day buffer inventory on cells and inverters.
Directional outlook. Cell and pack costs continue to fall, while metals and labor rise. Net bill-of-materials cost is expected to decline 4-7% annually through 2028, after which labor and service costs become the dominant margin variable.
Export, Cross-Border Trade & Tariff Impact on Industrial solar generator Market
Trade Barrier
Market Affected
Estimated Cost Impact
US Section 301 tariffs on Chinese cells
North America
+11-18% on module BOM
AD/CVD duties on Southeast Asian cell assembly
North America
+8-14% landed cost
UFLPA supply-chain tracing
North America
6-14 week clearance delays
India ALMM and BIS listing
Asia-Pacific
Restricts imported modules to listed models
EU CBAM reporting
Europe
Compliance overhead of 1-3% of project cost
Module trade corridors. China supplies roughly 80% of global module export volume, with major flows into Europe, India and Southeast Asia. Vietnam, Malaysia and Thailand function as assembly transshipment hubs, a structure that US trade actions have repeatedly targeted.
Tariff structure. US Section 201 and 301 measures plus AD/CVD orders on cells assembled in Southeast Asia lift landed module costs by an estimated 18-26% relative to pre-2022 baselines. This shifts the economics of North American industrial projects toward higher-efficiency modules and domestic-content suppliers.
Non-tariff barriers. UFLPA traceability requirements in the United States and ALMM listing in India effectively exclude non-compliant supply chains regardless of price. These measures carry more practical weight than tariff rates for most industrial buyers.
Corridor shift. Cross-border shipment volumes are reorienting toward intra-regional trade: European demand increasingly served by Turkish and EU-assembled product, Indian demand increasingly served by domestic capacity under ALMM.
Quantified policy impact. A 15% effective duty increase on module inputs raises installed cost for a 120 KWH industrial skid by roughly USD 9,000-14,000, extending simple payback by 3-5 months in most off-grid diesel-displacement cases. Trade policy therefore slows but rarely cancels industrial projects where diesel logistics costs are already above USD 0.40 per kWh.
Strategic implication. Vendors with dual-region assembly and documented supply-chain traceability convert trade friction into a competitive advantage against single-origin importers.
Industrial solar generator Market Segmentation
1. Type
1.1. below 40 KWH
1.2. 40-80 KWH
1.3. 80-150 KWH
1.4. over 150 KWH
2. Application
2.1. Electrical Industry
2.2. Oil and Gas Industry
2.3. others
Industrial solar generator Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Industrial solar generator Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 16.9% from 2020-2034
Segmentation
By Type
below 40 KWH
40-80 KWH
80-150 KWH
over 150 KWH
By Application
Electrical Industry
Oil and Gas Industry
others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. below 40 KWH
5.1.2. 40-80 KWH
5.1.3. 80-150 KWH
5.1.4. over 150 KWH
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Electrical Industry
5.2.2. Oil and Gas Industry
5.2.3. others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. below 40 KWH
6.1.2. 40-80 KWH
6.1.3. 80-150 KWH
6.1.4. over 150 KWH
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Electrical Industry
6.2.2. Oil and Gas Industry
6.2.3. others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. below 40 KWH
7.1.2. 40-80 KWH
7.1.3. 80-150 KWH
7.1.4. over 150 KWH
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Electrical Industry
7.2.2. Oil and Gas Industry
7.2.3. others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. below 40 KWH
8.1.2. 40-80 KWH
8.1.3. 80-150 KWH
8.1.4. over 150 KWH
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Electrical Industry
8.2.2. Oil and Gas Industry
8.2.3. others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. below 40 KWH
9.1.2. 40-80 KWH
9.1.3. 80-150 KWH
9.1.4. over 150 KWH
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Electrical Industry
9.2.2. Oil and Gas Industry
9.2.3. others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. below 40 KWH
10.1.2. 40-80 KWH
10.1.3. 80-150 KWH
10.1.4. over 150 KWH
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Electrical Industry
10.2.2. Oil and Gas Industry
10.2.3. others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Kirchner Solar Group GmbH
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. REC Solar Holdings AS
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Jakson Group
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Altern Limited
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Goal Zero Llc
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Juwi AG
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Ameresco
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Hollandia Solar
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Intech Clean Energy
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Industrial solar generator Market Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Industrial solar generator Market Revenue (million), by Type 2026 & 2034
Figure 3: North America Industrial solar generator Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Industrial solar generator Market Revenue (million), by Application 2026 & 2034
Figure 5: North America Industrial solar generator Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Industrial solar generator Market Revenue (million), by Country 2026 & 2034
Figure 7: North America Industrial solar generator Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Industrial solar generator Market Revenue (million), by Type 2026 & 2034
Figure 9: South America Industrial solar generator Market Revenue Share (%), by Type 2026 & 2034
Figure 10: South America Industrial solar generator Market Revenue (million), by Application 2026 & 2034
Figure 11: South America Industrial solar generator Market Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Industrial solar generator Market Revenue (million), by Country 2026 & 2034
Figure 13: South America Industrial solar generator Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Industrial solar generator Market Revenue (million), by Type 2026 & 2034
Figure 15: Europe Industrial solar generator Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Industrial solar generator Market Revenue (million), by Application 2026 & 2034
Figure 17: Europe Industrial solar generator Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Industrial solar generator Market Revenue (million), by Country 2026 & 2034
Figure 19: Europe Industrial solar generator Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Industrial solar generator Market Revenue (million), by Type 2026 & 2034
Figure 21: Middle East & Africa Industrial solar generator Market Revenue Share (%), by Type 2026 & 2034
Figure 22: Middle East & Africa Industrial solar generator Market Revenue (million), by Application 2026 & 2034
Figure 23: Middle East & Africa Industrial solar generator Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Middle East & Africa Industrial solar generator Market Revenue (million), by Country 2026 & 2034
Figure 25: Middle East & Africa Industrial solar generator Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Industrial solar generator Market Revenue (million), by Type 2026 & 2034
Figure 27: Asia Pacific Industrial solar generator Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Asia Pacific Industrial solar generator Market Revenue (million), by Application 2026 & 2034
Figure 29: Asia Pacific Industrial solar generator Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Industrial solar generator Market Revenue (million), by Country 2026 & 2034
Figure 31: Asia Pacific Industrial solar generator Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Industrial solar generator Market Revenue million Forecast, by Type 2020 & 2034
Table 2: Industrial solar generator Market Revenue million Forecast, by Application 2020 & 2034
Table 3: Industrial solar generator Market Revenue million Forecast, by Region 2020 & 2034
Table 4: North America Industrial solar generator Market Revenue million Forecast, by Type 2020 & 2034
Table 5: North America Industrial solar generator Market Revenue million Forecast, by Application 2020 & 2034
Table 6: North America Industrial solar generator Market Revenue million Forecast, by Country 2020 & 2034
Table 7: United States Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 8: Canada Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 9: Mexico Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 10: South America Industrial solar generator Market Revenue million Forecast, by Type 2020 & 2034
Table 11: South America Industrial solar generator Market Revenue million Forecast, by Application 2020 & 2034
Table 12: South America Industrial solar generator Market Revenue million Forecast, by Country 2020 & 2034
Table 13: Brazil Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 14: Argentina Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 15: Rest of South America Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 16: Europe Industrial solar generator Market Revenue million Forecast, by Type 2020 & 2034
Table 17: Europe Industrial solar generator Market Revenue million Forecast, by Application 2020 & 2034
Table 18: Europe Industrial solar generator Market Revenue million Forecast, by Country 2020 & 2034
Table 19: United Kingdom Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 20: Germany Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 21: France Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 22: Italy Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 23: Spain Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Russia Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 25: Benelux Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 26: Nordics Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 27: Rest of Europe Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 28: Middle East & Africa Industrial solar generator Market Revenue million Forecast, by Type 2020 & 2034
Table 29: Middle East & Africa Industrial solar generator Market Revenue million Forecast, by Application 2020 & 2034
Table 30: Middle East & Africa Industrial solar generator Market Revenue million Forecast, by Country 2020 & 2034
Table 31: Turkey Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Israel Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 33: GCC Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 34: North Africa Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 35: South Africa Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 36: Rest of Middle East & Africa Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Asia Pacific Industrial solar generator Market Revenue million Forecast, by Type 2020 & 2034
Table 38: Asia Pacific Industrial solar generator Market Revenue million Forecast, by Application 2020 & 2034
Table 39: Asia Pacific Industrial solar generator Market Revenue million Forecast, by Country 2020 & 2034
Table 40: China Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 41: India Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 42: Japan Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 43: South Korea Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 44: ASEAN Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 45: Oceania Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Table 46: Rest of Asia Pacific Industrial solar generator Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Research split and sample design. This study is built on a 70-80% primary / 20-30% secondary research split, with primary interviews, structured surveys and site-level validation forming the analytical core.
Company types interviewed (value chain specific): industrial solar skid integrators and EPC contractors; lithium iron phosphate (LFP) battery pack and BMS manufacturers; hybrid inverter and MPPT charge-controller OEMs rated 5-30 kW; monocrystalline module assemblers supplying 40-150 KWH industrial units; certified installation and O&M service firms.
Stakeholder job titles interviewed: Director of Distributed Generation Procurement; Oil and Gas Facilities Electrical Engineering Manager; EPC Project Development Lead for Remote Wellpad Power; Industrial Energy Storage Product Line Manager.
Interview protocol. Each respondent completes a 45-60 minute structured instrument covering unit volumes by KWH class, installed pricing, procurement cycles, certification requirements, lead times and service cost structure. Regional quotas are enforced across North America, Europe, Asia-Pacific, South America and the Middle East & Africa.
Regulatory and standards bodies consulted: Solar Energy Industries Association (SEIA), International Electrotechnical Commission (IEC TC 82), underwriters and certification laboratories operating UL 1741 and UL 9540A programs, and the European Solar Manufacturing Council.
Field validation. A subset of industrial sites is validated for actual run-hours, fuel displacement and maintenance events, converting stated specifications into observed performance data.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Distributed Generation Procurement
32%
Oil and Gas Facilities Electrical Engineering Manager
27%
EPC Project Development Lead, Remote Wellpad Power
23%
Industrial Energy Storage Product Line Manager
18%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Industrial solar skid integrators and EPC contractors
28%
LFP battery pack and BMS manufacturers
23%
Hybrid inverter and MPPT controller OEMs
19%
Monocrystalline module assemblers
17%
Certified installation and O&M service firms
13%
Secondary Research & Industry Benchmarking
Published source base. Secondary inputs are drawn from government statistical agencies, multilateral energy bodies and trade associations - never from competing market research publishers.
Financial and deal databases: Bloomberg, Factiva, Hoovers and PitchBook are used for company financials, ownership structure, transaction history and private capital flows.
Trade and tariff data. Customs shipment records, anti-dumping and countervailing duty determinations, and tariff schedules are used to model cross-border module and pack cost pass-through.
Benchmarking discipline. Every secondary figure is cross-checked against at least two independent sources before it enters the model; single-source claims are flagged and excluded from headline estimates.
Data currency. All reports are updated to the date of purchase, so quarterly pricing moves, tariff adjustments and capacity announcements are reflected in the delivered file.
Demand Modeling & Market Estimation
Dual methodology. Top-down and bottom-up models are constructed simultaneously and validated through multi-level data triangulation, ensuring that neither approach anchors the final number.
Bottom-up quantitative metrics: number of active oil and gas wellpads per basin without grid interconnection; average installed kW per industrial solar generator unit by KWH class (below 40, 40-80, 80-150, over 150 KWH); annual replacement rate of diesel gensets at remote industrial sites; average selling price per KWH for storage in 40-80 KWH and 80-150 KWH units.
Top-down anchor inputs: published distributed solar capacity additions, industrial electricity tariff structures including demand charges, and regional industrial capex budgets allocated to backup and off-grid power.
Segment and regional splits. Revenue is modeled across Type (below 40 KWH, 40-80 KWH, 80-150 KWH, over 150 KWH) and Application (Electrical Industry, Oil and Gas Industry, others), then distributed across North America, South America, Europe, Middle East & Africa and Asia-Pacific at country level.
Forecast mechanics. Volume is projected from site-level demand drivers, while value is projected from a bottom-up cost curve covering cells, LFP packs, inverters, enclosures and commissioning labor.
Data Accuracy & Quality Check
Accuracy guarantee. Every published estimate carries a guaranteed estimated data accuracy level of 85-90%, with confidence intervals disclosed for segment-level forecasts.
Triangulation layers. Primary interview data, secondary statistical data and bottom-up cost modeling are reconciled; deviations above 8% trigger re-interview and model revision.
Sanity checks. Unit economics are tested against observed diesel displacement rates and payback periods reported independently by industrial operators.
Review process. A senior analyst and a category lead independently sign off on final numbers before publication, and any unresolved variance is disclosed as a stated assumption.
Refresh policy. The dataset is refreshed to the purchase date, and prior-quarter assumptions are version-controlled so clients can trace every revision.
Frequently Asked Questions
1. How is the raw material supply chain structured for industrial solar generators?
Industrial solar generator production depends on monocrystalline cells, LFP battery packs, hybrid inverters and aluminum enclosures, which together account for roughly 80-85% of bill-of-materials cost. Polysilicon refining remains highly concentrated, with China processing an estimated 90% of global supply, while IGBT power modules come from a short list of European and Japanese suppliers. Buyers typically qualify at least two cell and pack vendors because single-source exposure has historically added 8-16 weeks to lead times.
2. Which product types and end-use applications dominate the Industrial solar generator Market?
The 80-150 KWH class is the largest revenue segment, holding about 34% of 2025 market value on roughly 29% of unit volume. By application, the Oil and Gas Industry generates an estimated 38% of demand, followed by the Electrical Industry at about 27%, with mining, telecom and construction making up the remainder. Units in the 100-150 KWH band command installed pricing of USD 1,850-2,400 per KWH.
3. What regulatory requirements shape industrial solar generator deployment?
North American installations generally require UL 1741 inverter listing and UL 9540A fire testing for storage, alongside NEC Article 690 and 706 compliance. European projects follow IEC 62109 safety standards and increasingly fall under EU CSRD emissions disclosure obligations. India adds ALMM and BIS listing requirements that restrict which imported modules can be used in sanctioned industrial projects.
4. What are the main barriers to entry for new vendors in this market?
Certification and listing is the first gate, taking 12-24 months and costing several hundred thousand dollars for a full UL and IEC portfolio. The second gate is service infrastructure: industrial buyers expect commissioning and maintenance coverage, and fewer than 15,000 certified solar professionals globally hold industrial-scale credentials. Roughly 62% of surveyed industrial buyers also cite capital allocation, not technology risk, as the reason they defer purchases, which favors vendors able to offer financed structures.
5. Which end-user industries drive downstream demand for industrial solar generators?
Oil and gas operators lead demand, representing roughly 38% of 2025 unit shipments, driven by remote wellpad and compression loads where delivered diesel costs USD 0.35-0.60 per kWh generated. The Electrical Industry follows at about 27%, mainly for peak shaving and backup at manufacturing campuses with demand charges above USD 14 per kW-month. Mining, telecom towers and agribusiness account for most of the remaining volume, with typical repeat procurement of 2,000-5,000 sites per large operator.
6. What supply chain risks could restrain the Industrial solar generator Market through 2033?
Polysilicon and silver paste volatility remains the most visible input risk; the 2021-2022 spike to roughly USD 39 per kilogram compressed integrator margins for four consecutive quarters. Trade policy adds a second layer, with US Section 301 tariffs and AD/CVD duties lifting landed module costs by an estimated 18-26%. A third risk is technician availability, since field commissioning of a 120 KWH skid consumes 40-70 labor hours and training pipelines run 14-20 months.