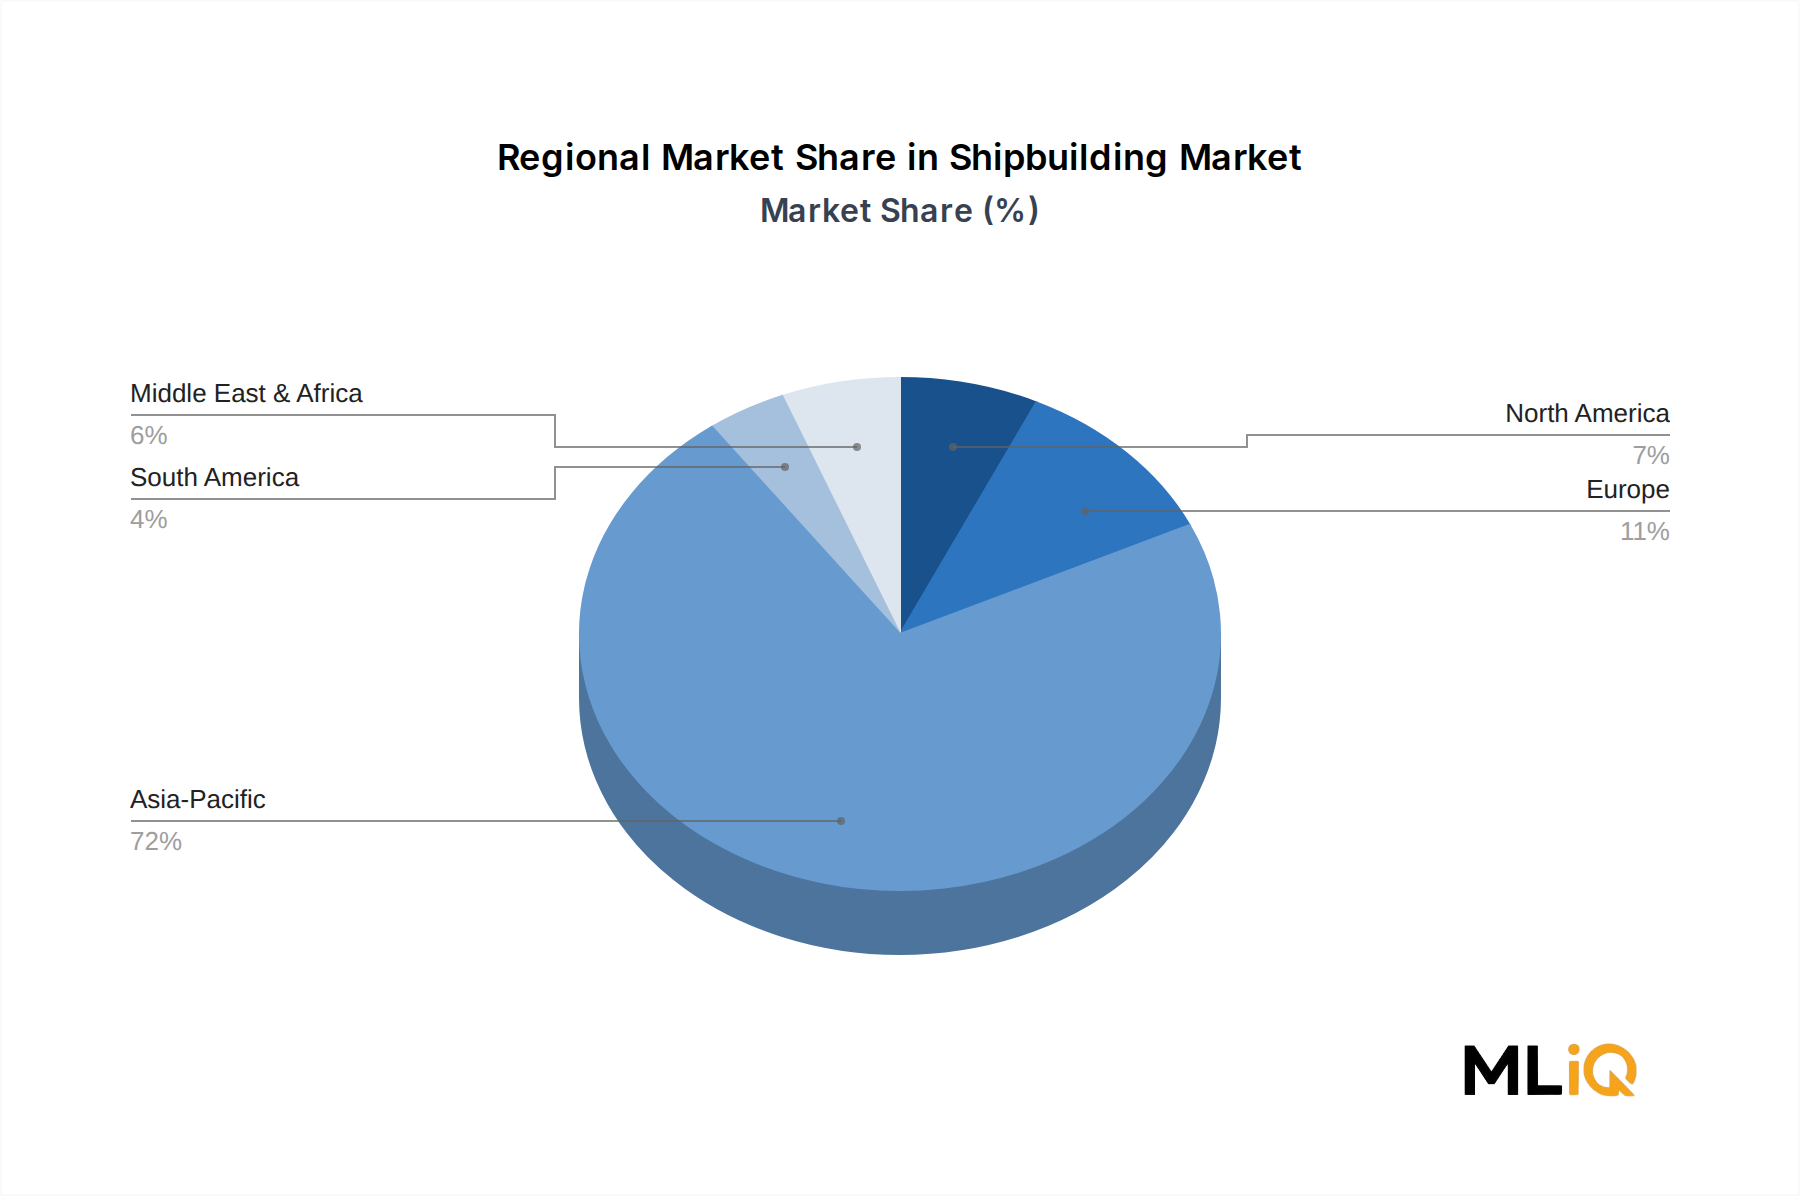
The geographic distribution of shipbuilding activity is highly concentrated, with Asia Pacific commanding an overwhelming share of global output. However, notable divergences in growth rates and end-market focus are evident across regions.
Asia Pacific — Dominant Region: Asia Pacific accounts for over 90% of global gross tonnage output, driven by China, South Korea, and Japan. China leads in volume, producing approximately 45–50% of global deadweight tonnage annually, with particular strength in bulk carriers, oil tankers, and container vessels for domestic and international operators. South Korea commands the highest per-unit revenue share, specializing in LNG carriers, VLCCs, and high-specification container ships. The South Korean segment is growing at an estimated 4.1% CAGR through 2033, underpinned by green transition orders. Japan maintains its position in niche, high-quality segments but is growing more slowly at approximately 1.8% CAGR due to demographic constraints and domestic market saturation. India is emerging as a secondary Asia Pacific player, with government-backed initiatives under the Sagarmala program targeting a tripling of domestic shipbuilding capacity by 2030.
North America — Defense-Driven Stability: North America's Shipbuilding Market is almost entirely defense-oriented, with commercial shipbuilding severely limited by the Jones Act's requirement for U.S.-built vessels in domestic trade. The United States accounts for the vast majority of regional output, growing at an estimated 2.9% CAGR, supported by sustained naval procurement budgets exceeding $30 billion annually. Canada's naval shipbuilding program, including the National Shipbuilding Strategy, is contributing incremental growth.
Europe — Specialized and Premium Segment: European yards, while no longer competitive in bulk commercial shipbuilding, retain global leadership in cruise ships (FINCANTIERI GROUP, Meyer Werft), naval vessels (BAE SYSTEMS PLC, Naval Group), and offshore support vessels. The region is growing at an estimated 2.5% CAGR, with Germany, Italy, France, and the United Kingdom as principal contributors. The EU's green maritime regulations are catalyzing investment in hybrid and hydrogen-ready vessel construction.
Middle East & Africa — Emerging Capacity: This region represents a nascent but strategically significant market, with Gulf states investing in domestic shipbuilding and repair capabilities to reduce dependence on Asian yards for offshore and tanker maintenance. Growth is estimated at 3.8% CAGR from a low base, making it the fastest-growing region in percentage terms.
South America — Constrained Growth: Brazil's Petrobras-linked shipbuilding program, which saw significant investment in the 2010s, has contracted due to fiscal pressures and corruption-related project delays. Regional CAGR is estimated at approximately 1.5%, with recovery dependent on offshore energy investment cycles.