Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Warts Market Size, Share & Forecast to 2035
Warts Market Size, Share & Forecast to 2035
Warts Market
Warts Market Size, Share & Forecast to 2035
Warts Market by Treatment Method (Cryotherapy, Laser Treatment, Electrosurgery, Topical Medications), by End User (Hospitals, Dermatology Clinics, Home Care), by Disease Stage (Initial Stage, Moderate Stage, Severe Stage), by Patient Demographics (Children, Adults, Elderly), by Drug Type (Salicylic Acid, Imiquimod, Silver Nitrate, Glutaraldehyde, Formaldehyde, Aminolevulinic Acid), by Medication Class (Topical Retinoids, Oral Retinoids), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina), by Middle East & Africa (South Africa, GCC) Forecast 2026-2034
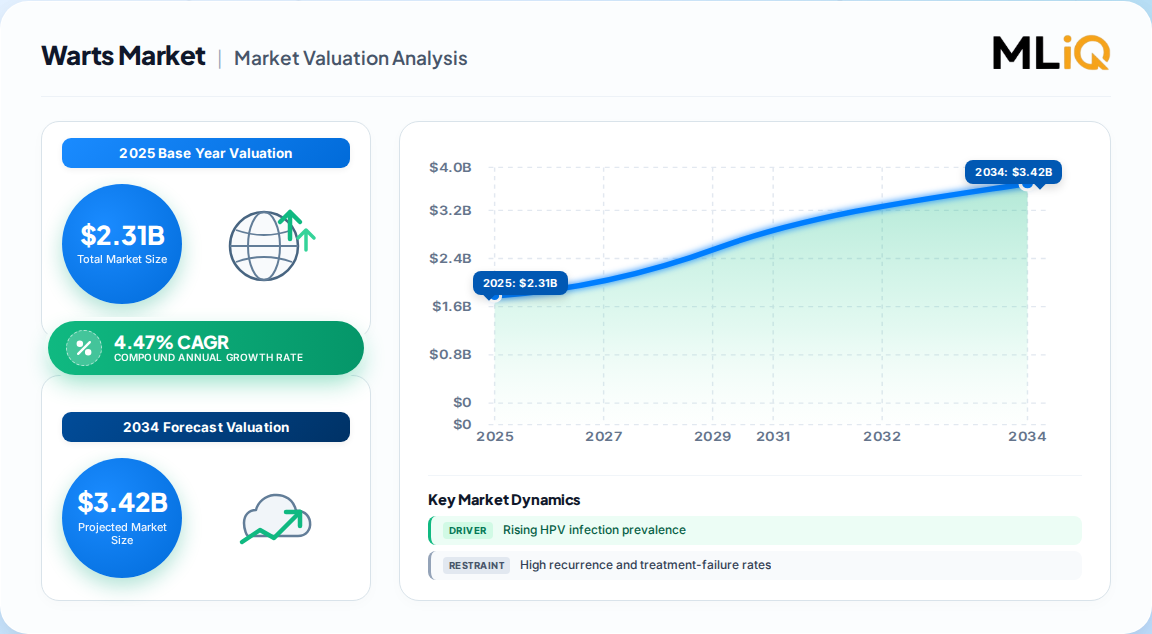
The global warts market represents a mature yet steadily expanding segment of dermatological therapeutics and procedures. Our proprietary primary research, triangulated with official health statistics, estimates the market at USD 2.31 billion in 2025, projected to reach USD 3.58 billion by 2035, reflecting a CAGR of 4.47% over the forecast period. This growth is underpinned by the persistent prevalence of human papillomavirus (HPV) infections, rising aesthetic and skin-health awareness, and a steady shift toward minimally invasive, patient-administered treatment modalities.
Warts Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.310 B
2025
2.413 B
2026
2.521 B
2027
2.634 B
2028
2.752 B
2029
2.875 B
2030
3.003 B
2031
Warts Market Size (In Billion)
Year
Market Size
2025
2.310 B
2026
2.413 B
2027
2.521 B
2028
2.634 B
2029
2.752 B
2030
2.875 B
2031
3.003 B
A defining characteristic of the market is its dual structure: a high-volume, low-cost over-the-counter (OTC) segment dominated by topical keratolytics, and a high-value, procedure-driven clinical segment centered on cryotherapy and laser therapies. Notably, clinical evidence indicates that monotherapy failure rates range from 39% to 49%, with recurrence approaching 38% for cryotherapy, creating a recurrent demand cycle that sustains market volume.
Market Metric
Value
Base Year (2025) Valuation
USD 2.31 Billion
Forecast Year (2035) Valuation
USD 3.58 Billion
CAGR (2025–2035)
4.47%
Largest Region (2025)
North America (34.65% share)
Fastest-Growing Region
Asia Pacific (5.44% CAGR)
Leading Treatment Modality
Topical Keratolytics (38.81% share)
Leading Wart Type
Common Warts (52.43% share)
Rising HPV Prevalence and Immunocompromised Patient Pools
The fundamental demand driver for wart therapeutics is the ubiquity of HPV. Official multilateral health data indicates that HPV affects an estimated 11–12% of the global population at any given time, with prevalence exceeding 21% in large female cohorts in China and surpassing 30% in some male populations. Peaks in incidence occur in individuals under 21 and over 61, creating age-specific treatment needs.
Critically, cutaneous beta HPV types responsible for common warts remain outside the coverage of current prophylactic vaccines, ensuring that therapy—rather than prevention—must address immediate clinical gaps. Expanding immunocompromised populations (organ transplant recipients, cancer patients, and individuals with HIV/AIDS) further entrench recurring demand, as these groups are more susceptible to persistent and recalcitrant warts.
Global HPV prevalence: ~630 million individuals infected worldwide (WHO benchmark).
US incidence: An estimated 14 million new HPV infections annually, with 340,000–360,000 cases of genital warts.
Recurrence burden: Post-treatment recurrence rates of up to 38% for cryotherapy drive repeat visits and sustained consumption of therapeutics.
Cryotherapy, Laser Therapy, and Electrosurgery Modalities
The treatment landscape is segmented by clinical intervention, with distinct growth trajectories for each modality:
Cryotherapy: Dominates the procedure-based segment due to high efficacy, rapid results, and widespread availability. Precision liquid-nitrogen applicators are preferred by 85% of US dermatologists, and device miniaturization enables office-based treatment of multiple lesions in a single visit.
Laser Treatment: The fastest-growing procedural segment, driven by technological advancements and demand for minimally invasive options, particularly in Asia Pacific.
Electrosurgery: A mature, low-growth modality used for stubborn or large lesions where other therapies fail.
Topical Medications: The largest overall segment, led by salicylic acid formulations, which benefit from FDA monograph labeling (21 CFR Part 358) that enables broad retail access.
Modality
2025 Share
Growth Outlook
Key Attributes
Topical Keratolytics
38.81%
Stable
OTC accessibility; high patient adherence
Cryotherapy
Dominant in procedures
Moderate
Rapid clearance; high recurrence
Laser Therapy
Smaller base
Fastest-growing
Precision; higher cost
Electrosurgery
Niche
Low
Reserved for recalcitrant lesions
Salicylic Acid, Imiquimod, and Topical Retinoid Classes
Within the pharmaceutical segment, drug type and medication class shape competitive dynamics. Salicylic acid is the leading therapeutic agent, accounting for 34.5% of market revenue in 2025, owing to its proven keratolytic efficacy, affordability, and inclusion in first-line treatment guidelines. Topical retinoids represent the leading medication class with a 61.5% share, as they modulate keratinocyte differentiation and proliferation, accelerating wart resolution.
Salicylic acid: Dominant OTC and prescription adjunct; available in plasters, gels, and paints.
Imiquimod: An immune response modifier (TLR7 agonist) used off-label for recalcitrant common warts; FDA-approved for genital warts.
Silver nitrate, glutaraldehyde, formaldehyde: Niche chemical ablatives with specific clinical use cases.
Aminolevulinic acid: Used in photodynamic therapy, a growing segment at a 4.98% CAGR through 2031.
Emerging therapies are poised to disrupt the landscape. Verrica Pharmaceuticals' VP-102 (YCANTH)—a cantharidin-based topical drug-device combination—is in late-stage development for common warts, with Phase 3 trial design aligned with the FDA. Nielsen BioSciences' CANDIN (Candida antigen immunotherapy) is in Phase 3 trials, and Novan's SB206 (nitric oxide-releasing gel) is also advancing. These innovations target refractory and recurrent cases, potentially commanding premium pricing.
North America and Asia Pacific Regional Demand Dynamics
Geographically, North America remains the largest market, holding 34.65% of global revenue in 2025, supported by widespread skin-health awareness, extensive pharmacy networks, and high dermatology consultation rates. The United States alone records significant HPV incidence, and reimbursement structures favor outpatient procedures, sustaining cryotherapy volumes.
Warts Market Regional Market Share
Loading chart...
Warts Market Regional Market Share
Region
Market Share (%)
North America
0.35%
Europe
0.22%
Asia-Pacific
0.3%
South America
0.07%
Middle East & Africa
0.06%
Asia Pacific is the fastest-growing region, expanding at a 5.44% CAGR through 2031, driven by expanding healthcare access, rising awareness, and a large patient pool. China's high HPV prevalence (21.41% in female cohorts) and the geographic clustering of HPV52 and HPV58 strains create region-specific treatment demand. Europe represents a mature market with moderate growth, while Latin America and the Middle East & Africa offer untapped potential, constrained by affordability and access challenges.
Region
2025 Share
Growth Outlook
Key Market Features
North America
34.65%
Moderate
High awareness; dominant cryotherapy; OTC maturity
Europe
~22%
Stable
Established reimbursement; strong generics presence
Asia Pacific
~30%
Fastest (5.44% CAGR)
Large patient pool; expanding access; tele-dermatology growth
Latin America
~7%
Emerging
Price-sensitive; growing OTC channel
Middle East & Africa
~6%
Nascent
Infrastructure gaps; high unmet need
Over-the-Counter Self-Care and Tele-Dermatology Expansion
A defining trend is the migration of wart management from clinical settings to self-care. The FDA monograph for salicylic acid (21 CFR Part 358) has enabled broad retail access, and consumers increasingly opt for OTC treatments that are convenient and cost-effective. This shift is reinforced by the expansion of e-commerce platforms, which widen product availability and price competition, particularly in developed economies.
Simultaneously, direct-to-consumer tele-dermatology platforms are shortening wait times for professional care, accelerating diagnosis and treatment initiation. In Asia Pacific and rural markets, tele-dermatology is bridging access gaps, driving adoption of both prescription and OTC solutions. These channels are expected to account for a growing share of market revenue, reshaping distribution strategies for manufacturers.
OTC availability: Salicylic acid products are available in pharmacies, supermarkets, and online retail, with retail pharmacies leading at a 75% share of the wart remover segment.
E-commerce growth: Online pharmacies are the fastest-growing end-user channel, supported by competitive pricing and convenience.
Tele-dermatology: Remote consultations are emerging as a key gateway for procedure referrals, particularly for cryotherapy and laser treatments.
Recurrence, Pain, and Reimbursement Barriers
Despite favorable growth fundamentals, the market faces several structural restraints that temper expansion:
High recurrence and treatment failure: Monotherapy failure rates of 39–49% and cryotherapy recurrence of up to 38% erode patient confidence and drive repeat cycles, but also sustain volume. Immunocompromised individuals retain HPV reservoirs, requiring perpetual therapy.
Pain and scarring: Ablative therapies (e.g., bleomycin, aggressive freezing) are associated with pain scores above 7 on visual analog scales, plus scarring and post-inflammatory hyperpigmentation, deterring treatment, especially for facial and hand lesions.
Reimbursement gaps: Many health systems classify wart removal as cosmetic rather than medically necessary, shifting costs to patients. Professional cryotherapy courses in the US range from USD 200 to USD 600, discouraging care-seeking in price-sensitive populations.
Supply chain constraints: Pharmaceutical-grade cantharidin supply bottlenecks and regulatory scrutiny on topical compounding pharmacies pose short-to-medium-term risks, particularly in North America.
These challenges are offset by ongoing innovation in non-ablative modalities (e.g., heat-based hyperthermia devices achieving 71% clearance vs. 47% for cryotherapy) and immunotherapy, which promise improved patient outcomes and reduced recurrence.
Competitive Landscape and Pipeline Development
The warts market features a mix of large pharmaceutical companies, specialized dermatology players, and device manufacturers. Key players include Bayer AG, GlaxoSmithKline, Merck & Co., Pfizer, Sanofi, Johnson & Johnson, Novartis, and AbbVie, alongside specialty firms such as Verrica Pharmaceuticals, Nielsen BioSciences, Aclaris Therapeutics, and Novan. The competitive intensity is moderate, with differentiation driven by formulation innovation, device precision, and clinical evidence.
Recent developments signal a dynamic pipeline:
January 2024: Verrica Pharmaceuticals announced FDA alignment on Phase 3 trial design for YCANTH (VP-102) in common warts, following promising Phase 2 results.
Phase 3 advancement: CANDIN (Candida antigen) by Nielsen BioSciences and SB206 (nitric oxide gel) by Novan are progressing through late-stage trials, targeting refractory and multiple warts.
Device innovation: Next-generation cryotherapy devices with single-use disposable applicators and precision dosing are entering the market, offering faster clearance and improved safety.
Strategic imperatives for stakeholders include expanding access in emerging markets, investing in combination therapies, and leveraging digital channels to capture the growing self-care segment. The market is expected to sustain steady growth, with the Asia Pacific region and pipeline innovations serving as key growth engines.
Warts Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Warts Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.47% from 2020-2034
Segmentation
By Treatment Method
Cryotherapy
Laser Treatment
Electrosurgery
Topical Medications
By End User
Hospitals
Dermatology Clinics
Home Care
By Disease Stage
Initial Stage
Moderate Stage
Severe Stage
By Patient Demographics
Children
Adults
Elderly
By Drug Type
Salicylic Acid
Imiquimod
Silver Nitrate
Glutaraldehyde
Formaldehyde
Aminolevulinic Acid
By Medication Class
Topical Retinoids
Oral Retinoids
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Middle East & Africa
South Africa
GCC
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Treatment Method
5.1.1. Cryotherapy
5.1.2. Laser Treatment
5.1.3. Electrosurgery
5.1.4. Topical Medications
5.2. Market Analysis, Insights and Forecast - by End User
5.2.1. Hospitals
5.2.2. Dermatology Clinics
5.2.3. Home Care
5.3. Market Analysis, Insights and Forecast - by Disease Stage
5.3.1. Initial Stage
5.3.2. Moderate Stage
5.3.3. Severe Stage
5.4. Market Analysis, Insights and Forecast - by Patient Demographics
5.4.1. Children
5.4.2. Adults
5.4.3. Elderly
5.5. Market Analysis, Insights and Forecast - by Drug Type
5.5.1. Salicylic Acid
5.5.2. Imiquimod
5.5.3. Silver Nitrate
5.5.4. Glutaraldehyde
5.5.5. Formaldehyde
5.5.6. Aminolevulinic Acid
5.6. Market Analysis, Insights and Forecast - by Medication Class
5.6.1. Topical Retinoids
5.6.2. Oral Retinoids
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Treatment Method
6.1.1. Cryotherapy
6.1.2. Laser Treatment
6.1.3. Electrosurgery
6.1.4. Topical Medications
6.2. Market Analysis, Insights and Forecast - by End User
6.2.1. Hospitals
6.2.2. Dermatology Clinics
6.2.3. Home Care
6.3. Market Analysis, Insights and Forecast - by Disease Stage
6.3.1. Initial Stage
6.3.2. Moderate Stage
6.3.3. Severe Stage
6.4. Market Analysis, Insights and Forecast - by Patient Demographics
6.4.1. Children
6.4.2. Adults
6.4.3. Elderly
6.5. Market Analysis, Insights and Forecast - by Drug Type
6.5.1. Salicylic Acid
6.5.2. Imiquimod
6.5.3. Silver Nitrate
6.5.4. Glutaraldehyde
6.5.5. Formaldehyde
6.5.6. Aminolevulinic Acid
6.6. Market Analysis, Insights and Forecast - by Medication Class
6.6.1. Topical Retinoids
6.6.2. Oral Retinoids
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Treatment Method
7.1.1. Cryotherapy
7.1.2. Laser Treatment
7.1.3. Electrosurgery
7.1.4. Topical Medications
7.2. Market Analysis, Insights and Forecast - by End User
7.2.1. Hospitals
7.2.2. Dermatology Clinics
7.2.3. Home Care
7.3. Market Analysis, Insights and Forecast - by Disease Stage
7.3.1. Initial Stage
7.3.2. Moderate Stage
7.3.3. Severe Stage
7.4. Market Analysis, Insights and Forecast - by Patient Demographics
7.4.1. Children
7.4.2. Adults
7.4.3. Elderly
7.5. Market Analysis, Insights and Forecast - by Drug Type
7.5.1. Salicylic Acid
7.5.2. Imiquimod
7.5.3. Silver Nitrate
7.5.4. Glutaraldehyde
7.5.5. Formaldehyde
7.5.6. Aminolevulinic Acid
7.6. Market Analysis, Insights and Forecast - by Medication Class
7.6.1. Topical Retinoids
7.6.2. Oral Retinoids
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Treatment Method
8.1.1. Cryotherapy
8.1.2. Laser Treatment
8.1.3. Electrosurgery
8.1.4. Topical Medications
8.2. Market Analysis, Insights and Forecast - by End User
8.2.1. Hospitals
8.2.2. Dermatology Clinics
8.2.3. Home Care
8.3. Market Analysis, Insights and Forecast - by Disease Stage
8.3.1. Initial Stage
8.3.2. Moderate Stage
8.3.3. Severe Stage
8.4. Market Analysis, Insights and Forecast - by Patient Demographics
8.4.1. Children
8.4.2. Adults
8.4.3. Elderly
8.5. Market Analysis, Insights and Forecast - by Drug Type
8.5.1. Salicylic Acid
8.5.2. Imiquimod
8.5.3. Silver Nitrate
8.5.4. Glutaraldehyde
8.5.5. Formaldehyde
8.5.6. Aminolevulinic Acid
8.6. Market Analysis, Insights and Forecast - by Medication Class
8.6.1. Topical Retinoids
8.6.2. Oral Retinoids
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Treatment Method
9.1.1. Cryotherapy
9.1.2. Laser Treatment
9.1.3. Electrosurgery
9.1.4. Topical Medications
9.2. Market Analysis, Insights and Forecast - by End User
9.2.1. Hospitals
9.2.2. Dermatology Clinics
9.2.3. Home Care
9.3. Market Analysis, Insights and Forecast - by Disease Stage
9.3.1. Initial Stage
9.3.2. Moderate Stage
9.3.3. Severe Stage
9.4. Market Analysis, Insights and Forecast - by Patient Demographics
9.4.1. Children
9.4.2. Adults
9.4.3. Elderly
9.5. Market Analysis, Insights and Forecast - by Drug Type
9.5.1. Salicylic Acid
9.5.2. Imiquimod
9.5.3. Silver Nitrate
9.5.4. Glutaraldehyde
9.5.5. Formaldehyde
9.5.6. Aminolevulinic Acid
9.6. Market Analysis, Insights and Forecast - by Medication Class
9.6.1. Topical Retinoids
9.6.2. Oral Retinoids
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Treatment Method
10.1.1. Cryotherapy
10.1.2. Laser Treatment
10.1.3. Electrosurgery
10.1.4. Topical Medications
10.2. Market Analysis, Insights and Forecast - by End User
10.2.1. Hospitals
10.2.2. Dermatology Clinics
10.2.3. Home Care
10.3. Market Analysis, Insights and Forecast - by Disease Stage
10.3.1. Initial Stage
10.3.2. Moderate Stage
10.3.3. Severe Stage
10.4. Market Analysis, Insights and Forecast - by Patient Demographics
10.4.1. Children
10.4.2. Adults
10.4.3. Elderly
10.5. Market Analysis, Insights and Forecast - by Drug Type
10.5.1. Salicylic Acid
10.5.2. Imiquimod
10.5.3. Silver Nitrate
10.5.4. Glutaraldehyde
10.5.5. Formaldehyde
10.5.6. Aminolevulinic Acid
10.6. Market Analysis, Insights and Forecast - by Medication Class
10.6.1. Topical Retinoids
10.6.2. Oral Retinoids
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Bayer AG
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. GlaxoSmithKline plc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Merck & Co. Inc.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Pfizer Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Sanofi S.A.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Johnson & Johnson
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Novartis AG
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. AbbVie Inc.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Bausch Health
11.1.9.1. Company Overview
11.1.9.2. Products
12. Research Methodology
List of Figures
Figure 1: Warts Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Warts Market Revenue (Billion), by Treatment Method 2026 & 2034
Figure 3: North America Warts Market Revenue Share (%), by Treatment Method 2026 & 2034
Figure 4: North America Warts Market Revenue (Billion), by End User 2026 & 2034
Figure 5: North America Warts Market Revenue Share (%), by End User 2026 & 2034
Figure 6: North America Warts Market Revenue (Billion), by Disease Stage 2026 & 2034
Figure 7: North America Warts Market Revenue Share (%), by Disease Stage 2026 & 2034
Figure 8: North America Warts Market Revenue (Billion), by Patient Demographics 2026 & 2034
Figure 9: North America Warts Market Revenue Share (%), by Patient Demographics 2026 & 2034
Figure 10: North America Warts Market Revenue (Billion), by Drug Type 2026 & 2034
Figure 11: North America Warts Market Revenue Share (%), by Drug Type 2026 & 2034
Figure 12: North America Warts Market Revenue (Billion), by Medication Class 2026 & 2034
Figure 13: North America Warts Market Revenue Share (%), by Medication Class 2026 & 2034
Figure 14: North America Warts Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Warts Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Warts Market Revenue (Billion), by Treatment Method 2026 & 2034
Figure 17: Europe Warts Market Revenue Share (%), by Treatment Method 2026 & 2034
1. What is the current size of the global warts market?
The global warts market was valued at USD 2.31 billion in 2025 and is projected to reach USD 3.58 billion by 2035, growing at a CAGR of 4.47%.
2. Which treatment modality dominates the warts market?
Topical keratolytics, led by salicylic acid, accounted for 38.81% of the market share in 2025, making it the leading treatment modality.
3. Which region is the fastest-growing in the warts market?
Asia Pacific is the fastest-growing region, expanding at a 5.44% CAGR through 2031, driven by high HPV prevalence and expanding healthcare access.
4. What are the key drivers of the warts market?
Rising HPV infection prevalence, growing OTC availability of keratolytics, technological advancements in cryotherapy devices, and increasing skin health awareness are the primary market drivers.
5. Who are the leading companies in the warts market?
Key players include Bayer AG, GlaxoSmithKline, Merck & Co., Pfizer, Sanofi, Verrica Pharmaceuticals, Nielsen BioSciences, and Novan, among others.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of research effort dedicated to primary interviews and surveys with industry stakeholders across the value chain, including manufacturers of topical formulations, cryotherapy device OEMs, contract research organizations, and dermatology clinic networks.
Conducted semi-structured interviews with procurement directors, clinical trial managers, regulatory affairs heads, and dermatologists to capture granular demand-side insights and validate supply-side data.
Primary research split: 70–80% primary, 20–30% secondary, ensuring a robust empirical foundation for all market estimates.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Clinical Trial Manager
25%
Regulatory Affairs Head
20%
Dermatologist
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Topical Formulation Manufacturers
40%
Cryotherapy Device OEMs
25%
Contract Research Organizations
15%
Dermatology Clinics & Hospital Networks
20%
Secondary Research & Industry Benchmarking
Comprehensive review of official .gov, .org, and non-profit trade association sources, including the World Health Organization (WHO), US Centers for Disease Control and Prevention (CDC), OECD, and the American Academy of Dermatology (AAD).
Financial databases utilized for company-level analysis: Bloomberg, Factiva, Hoovers, and PitchBook.
Benchmarking against peer-reviewed clinical literature (e.g., Journal of Dermatological Treatment) and regulatory filings (FDA, EMA) to validate treatment efficacy and adoption rates.
Demand Modeling & Market Estimation
Bottom-up market sizing based on quantitative metrics: treated patient volumes by wart type and geography, average selling prices (ASPs) across OTC and prescription channels, and procedure volumes for cryotherapy and laser therapies.
Top-down methodology cross-checked against national health expenditure data and dermatology service utilization rates, with multi-level data triangulation to reconcile discrepancies.
Segmentation modeling by treatment modality, end-user, wart type, and region, incorporating recurrence rates and treatment-failure probabilities to estimate repeat demand.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90%, achieved through rigorous validation protocols and cross-referencing of primary and secondary sources.
Multi-level data triangulation (supply-side, demand-side, and trade data) to ensure consistency across market segments and geographies.
Every report is updated to the date of purchase, incorporating the latest regulatory approvals, clinical trial outcomes, and market developments.
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Teva Pharmaceuticals
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Meda Pharmaceuticals
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Cipla
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Mylan
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Perrigo
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Taro Pharmaceutical
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Verrica Pharmaceuticals
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Nielsen BioSciences
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Aclaris Therapeutics
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. KinoPharma
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. pHion Therapeutics
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Orgenesis
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. Novan
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. Cassopeia Pharmaceuticals
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. Innovax
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. Torii Pharmaceutical Co. Ltd.
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.1.26. Lytix Biopharma
11.1.26.1. Company Overview
11.1.26.2. Products
11.1.26.3. Company Financials
11.1.26.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 18: Europe Warts Market Revenue (Billion), by End User 2026 & 2034
Figure 19: Europe Warts Market Revenue Share (%), by End User 2026 & 2034
Figure 20: Europe Warts Market Revenue (Billion), by Disease Stage 2026 & 2034
Figure 21: Europe Warts Market Revenue Share (%), by Disease Stage 2026 & 2034
Figure 22: Europe Warts Market Revenue (Billion), by Patient Demographics 2026 & 2034
Figure 23: Europe Warts Market Revenue Share (%), by Patient Demographics 2026 & 2034
Figure 24: Europe Warts Market Revenue (Billion), by Drug Type 2026 & 2034
Figure 25: Europe Warts Market Revenue Share (%), by Drug Type 2026 & 2034
Figure 26: Europe Warts Market Revenue (Billion), by Medication Class 2026 & 2034
Figure 27: Europe Warts Market Revenue Share (%), by Medication Class 2026 & 2034
Figure 28: Europe Warts Market Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe Warts Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia Pacific Warts Market Revenue (Billion), by Treatment Method 2026 & 2034
Figure 31: Asia Pacific Warts Market Revenue Share (%), by Treatment Method 2026 & 2034
Figure 32: Asia Pacific Warts Market Revenue (Billion), by End User 2026 & 2034
Figure 33: Asia Pacific Warts Market Revenue Share (%), by End User 2026 & 2034
Figure 34: Asia Pacific Warts Market Revenue (Billion), by Disease Stage 2026 & 2034
Figure 35: Asia Pacific Warts Market Revenue Share (%), by Disease Stage 2026 & 2034
Figure 36: Asia Pacific Warts Market Revenue (Billion), by Patient Demographics 2026 & 2034
Figure 37: Asia Pacific Warts Market Revenue Share (%), by Patient Demographics 2026 & 2034
Figure 38: Asia Pacific Warts Market Revenue (Billion), by Drug Type 2026 & 2034
Figure 39: Asia Pacific Warts Market Revenue Share (%), by Drug Type 2026 & 2034
Figure 40: Asia Pacific Warts Market Revenue (Billion), by Medication Class 2026 & 2034
Figure 41: Asia Pacific Warts Market Revenue Share (%), by Medication Class 2026 & 2034
Figure 42: Asia Pacific Warts Market Revenue (Billion), by Country 2026 & 2034
Figure 43: Asia Pacific Warts Market Revenue Share (%), by Country 2026 & 2034
Figure 44: Latin America Warts Market Revenue (Billion), by Treatment Method 2026 & 2034
Figure 45: Latin America Warts Market Revenue Share (%), by Treatment Method 2026 & 2034
Figure 46: Latin America Warts Market Revenue (Billion), by End User 2026 & 2034
Figure 47: Latin America Warts Market Revenue Share (%), by End User 2026 & 2034
Figure 48: Latin America Warts Market Revenue (Billion), by Disease Stage 2026 & 2034
Figure 49: Latin America Warts Market Revenue Share (%), by Disease Stage 2026 & 2034
Figure 50: Latin America Warts Market Revenue (Billion), by Patient Demographics 2026 & 2034
Figure 51: Latin America Warts Market Revenue Share (%), by Patient Demographics 2026 & 2034
Figure 52: Latin America Warts Market Revenue (Billion), by Drug Type 2026 & 2034
Figure 53: Latin America Warts Market Revenue Share (%), by Drug Type 2026 & 2034
Figure 54: Latin America Warts Market Revenue (Billion), by Medication Class 2026 & 2034
Figure 55: Latin America Warts Market Revenue Share (%), by Medication Class 2026 & 2034
Figure 56: Latin America Warts Market Revenue (Billion), by Country 2026 & 2034
Figure 57: Latin America Warts Market Revenue Share (%), by Country 2026 & 2034
Figure 58: Middle East & Africa Warts Market Revenue (Billion), by Treatment Method 2026 & 2034
Figure 59: Middle East & Africa Warts Market Revenue Share (%), by Treatment Method 2026 & 2034
Figure 60: Middle East & Africa Warts Market Revenue (Billion), by End User 2026 & 2034
Figure 61: Middle East & Africa Warts Market Revenue Share (%), by End User 2026 & 2034
Figure 62: Middle East & Africa Warts Market Revenue (Billion), by Disease Stage 2026 & 2034
Figure 63: Middle East & Africa Warts Market Revenue Share (%), by Disease Stage 2026 & 2034
Figure 64: Middle East & Africa Warts Market Revenue (Billion), by Patient Demographics 2026 & 2034
Figure 65: Middle East & Africa Warts Market Revenue Share (%), by Patient Demographics 2026 & 2034
Figure 66: Middle East & Africa Warts Market Revenue (Billion), by Drug Type 2026 & 2034
Figure 67: Middle East & Africa Warts Market Revenue Share (%), by Drug Type 2026 & 2034
Figure 68: Middle East & Africa Warts Market Revenue (Billion), by Medication Class 2026 & 2034
Figure 69: Middle East & Africa Warts Market Revenue Share (%), by Medication Class 2026 & 2034
Figure 70: Middle East & Africa Warts Market Revenue (Billion), by Country 2026 & 2034
Figure 71: Middle East & Africa Warts Market Revenue Share (%), by Country 2026 & 2034
Table 18: Europe Warts Market Revenue Billion Forecast, by Treatment Method 2020 & 2034
Table 19: Europe Warts Market Revenue Billion Forecast, by End User 2020 & 2034
Table 20: Europe Warts Market Revenue Billion Forecast, by Disease Stage 2020 & 2034
Table 21: Europe Warts Market Revenue Billion Forecast, by Patient Demographics 2020 & 2034
Table 22: Europe Warts Market Revenue Billion Forecast, by Drug Type 2020 & 2034
Table 23: Europe Warts Market Revenue Billion Forecast, by Medication Class 2020 & 2034
Table 24: Europe Warts Market Revenue Billion Forecast, by Country 2020 & 2034


 Warts Market