Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Allergy Treatment Market Size, Growth & Forecast to 2033
Allergy Treatment Market
Allergy Treatment Market Size, Growth & Forecast to 2033
Allergy Treatment Market by Type (Rhinitis, Asthma, Skin Allergy, Food Allergy, Eye Allergy, Others), by Treatment (Anti-Allergy Drugs(Antihistamines, Corticosteroids, Decongestants, Leukotriene Inhibitors, Epinephrine), Immunotherapy(SCIT, SLIT, OIT), Biologics), by Route of Administration (Oral, Parenteral, Inhalation, Intranasal, Others), by End-Users (Hospitals, Specialty Clinics, Homecare, Others), by Distribution Channel (Hospital Pharmacy, Retail Pharmacy, Online Pharmacy, Others), by Allergen Type (Peanuts, Tree Nuts, Dairy, Shellfish & Fish, Wheat, Soy, Others), by Animal Type (Canine, Feline, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Netherlands, Switzerland, Italy, Spain, Belgium, Russia, Turkey), by Asia Pacific (China, Japan, India, South Korea, Singapore, Malaysia, Australia, Thailand, Indonesia, Philippines), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Egypt, Israel), by South America (Brazil, Argentina) Forecast 2026-2034
Updated On : Nov 11, 2026|Base Year : 2025|Pages : 220
Allergy Treatment Market Valuation Timeline and Structural Overview
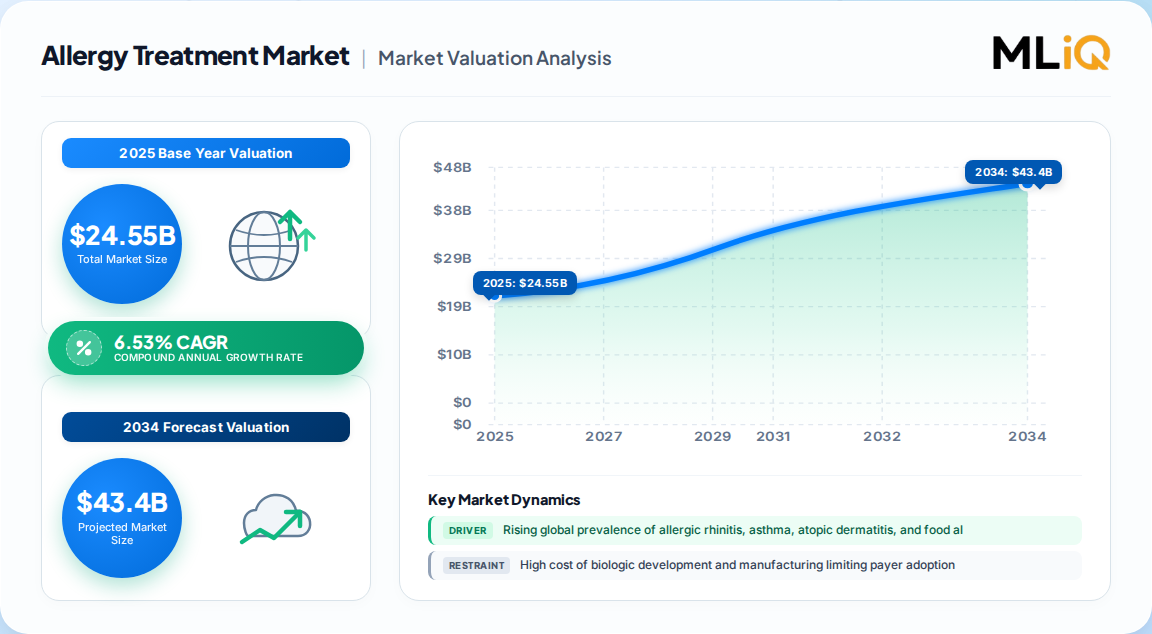
The global allergy treatment market represents one of the most resilient and steadily expanding therapeutic segments in immunology and primary care. Our proprietary first-party research places the market at USD 24.55 billion in 2025, with a projected trajectory to USD 40.72 billion by 2033, expanding at a 6.53% CAGR over the 2026–2033 forecast window. The intermediate milestone of USD 31.62 billion by 2029 underscores the non-cyclical, prevalence-linked nature of demand.
Allergy Treatment Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
24.55 B
2025
26.15 B
2026
27.86 B
2027
29.68 B
2028
31.62 B
2029
33.68 B
2030
35.88 B
2031
Allergy Treatment Market Size (In Billion)
Year
Market Size
2025
24.55 B
2026
26.15 B
2027
27.86 B
2028
29.68 B
2029
31.62 B
2030
33.68 B
2031
35.88 B
Metric
Value
2025 Market Size
USD 24.55 Billion
2029 Interim Forecast
USD 31.62 Billion
2033 Forecast Size
USD 40.72 Billion
Forecast CAGR (2026–2033)
6.53%
Largest Region (2025)
North America (42.7%)
Fastest-Growing Region
Asia-Pacific
Leading Treatment Segment
Anti-Allergy Drugs (60.4%)
This growth architecture is anchored in three structural realities: rising global prevalence of allergic rhinitis, asthma, atopic dermatitis, and food allergies; intensifying environmental pollution and urbanization-driven allergen exposure; and a therapeutic mix shifting from symptomatic relief toward disease-modifying immunotherapy and biologic intervention.
Anti-Allergy Drugs and Immunotherapy Treatment Modality Split
The treatment modality axis is the single most commercially decisive segmentation in this market. Anti-allergy drugs commanded 60.4% of 2025 revenue, sustained by high-volume antihistamine and corticosteroid utilization, broad prescription and OTC availability, and rapid symptomatic efficacy in mild-to-moderate presentations.
Immunotherapy, while smaller in absolute revenue, carries the superior growth multiple. Sublingual and oral immunotherapy platforms are migrating from specialist-only administration toward structured, label-approved protocols—most visibly in peanut desensitization, where FDA label expansions down to children aged 1–3 years have materially widened the addressable pediatric cohort.
Anti-allergy drugs: antihistamines, intranasal and inhaled corticosteroids, leukotriene inhibitors, mast cell stabilizers, decongestants, and epinephrine auto-injectors.
Biologics: anti-IgE monoclonal antibodies (omalizumab), anti-IL-31 agents, and anti-IL-4/IL-13 pathway inhibitors now migrating from asthma into broader allergic indications.
The economic logic favors portfolio breadth: manufacturers spanning entry-level OTC symptom relief through specialist-led biologics retain patients as disease complexity escalates.
Allergen-Type Segments: Rhinitis Asthma and Food Allergy Economics
Highest-volume chronic segment; intranasal steroid and antihistamine anchored
Asthma
Highest per-patient value; biologic-intensive severe cohort
Food Allergy
Fastest-growing; 8.0%–8.3% CAGR range
Skin Allergy / Atopic Dermatitis
Rapid uptake of JAK inhibitors and injectable biologics
Eye Allergy
Seasonal, OTC-heavy, low ticket value
Standalone food allergy therapeutics represent a distinct USD 7.47 billion in 2025, forecast to reach USD 15.32 billion by 2034. Within that sub-market, peanut allergy accounts for approximately 21.2% of allergen-type revenue, reflecting high prevalence (6.1 million affected individuals in the U.S. alone) and severity-driven treatment intensity. Tree nut allergy is the fastest-growing allergen sub-segment.
Route of Administration and Distribution Channel Dynamics
Route of administration shapes both clinical adoption and channel economics. Parenteral delivery held approximately 53.0% of food allergy treatment sales in 2025, driven by epinephrine auto-injectors where 100% bioavailability and immediate onset are clinically non-negotiable in anaphylaxis. Oral administration is the fastest-growing route, aligned with OIT scale-up and pediatric preference.
Route
Share / Trajectory
Primary Use Case
Parenteral
~53.0% (2025), fastest CAGR
Epinephrine emergency rescue; biologics
Oral
Fastest-growing (food allergy)
OIT, antihistamines, JAK inhibitors
Intranasal
Stable, high-volume
Rhinitis corticosteroids
Inhalation
Stable
Asthma controllers
Distribution is hospital-pharmacy weighted at the severe end—hospital pharmacies captured approximately 47.8% of food allergy treatment revenue in 2024—while retail pharmacies represent the fastest-growing channel, buoyed by OTC access, refill convenience, and online pharmacy penetration.
North America and Europe Regional Revenue Concentration
North America dominated with a 42.7% revenue share in 2025, underpinned by high disease awareness, advanced allergist networks, robust reimbursement, and dense concentration of immunotherapy and biologic innovators. The U.S. allergy diagnostics and therapeutics market alone was calculated at USD 10.88 billion in 2024, rising to an estimated USD 21.20 billion by 2034 at a 6.9% CAGR.
Allergy Treatment Market Regional Market Share
Loading chart...
Allergy Treatment Market Regional Market Share
Region
Market Share (%)
North America
0.43%
Europe
0.24%
Asia-Pacific
0.22%
South America
0.07%
Middle East & Africa
0.05%
U.S.: therapeutics account for roughly 82% of the diagnostics-and-therapeutics envelope; in vitro testing contributes ~55% of diagnostic revenue, with in vivo testing growing faster.
Europe: Germany, the U.K., France, and the Netherlands anchor revenue; SCIT/SLIT reimbursement frameworks are comparatively mature, supporting immunotherapy penetration above global averages.
Asia-Pacific: the fastest-growing region, propelled by expanding healthcare access, deteriorating urban air quality, large untreated patient pools, and rapid adoption of modern diagnostics in China, India, and Japan.
The Middle East & Africa and South America remain underpenetrated, with growth contingent on reimbursement maturation and specialist allergy workforce expansion.
Competitive Landscape and Named Product Approvals
The vendor ecosystem divides into immunotherapy specialists, diversified pharmaceutical majors, and veterinary-focused animal health leaders addressing companion-animal atopic disease.
Animal health: Zoetis (19.5% share of the pet allergy treatment segment), Elanco, Merck Animal Health, Boehringer Ingelheim, Virbac.
Recent named developments include FDA approval of Xolair (omalizumab) for severe food allergy in adults and children aged 1+, expanded Palforzia labeling for toddlers aged 1–3, FDA approvals of Apoquel Chewable (June 2023) and Zenrelia (September 2024) for canine allergic dermatitis, and the emergence of needle-free epinephrine formats including nasal-spray alternatives.
Growth Drivers Restraints and Trade-Adjacent Supply Considerations
Drivers
Rising global prevalence of allergic rhinitis, asthma, atopic dermatitis, and food allergy, with food allergies affecting more than 7% of children worldwide.
Environmental pollution, urbanization, and changing dietary patterns intensifying allergen exposure across both developed and emerging economies.
Biologic and monoclonal antibody expansion into allergic indications previously served only symptomatically.
Digital allergy diagnostics, AI-assisted ingredient screening, wearable anaphylaxis monitoring, and telehealth-based allergy care platforms.
Restraints and Challenges
High cost of biologic development and manufacturing, constraining payer adoption in cost-sensitive markets.
Limited access to specialist allergy testing and reimbursement friction, particularly in emerging Asia-Pacific and Africa.
Environmental scrutiny of pharmaceutical residues in freshwater, as documented by the OECD—roughly 2,000 active pharmaceutical ingredients are administered worldwide, with municipal wastewater effluent the dominant pathway into freshwater bodies. This regulatory pressure is gradually influencing formulation and disposal standards across allergy and respiratory drug classes.
Under-management and treatment non-persistence, notably in companion-animal allergy care where roughly 20 million dogs worldwide remain untreated or undertreated.
Cross-border trade patterns in this market are dominated by finished-dose immunotherapy extracts, biologic drug substance, and diagnostic reagents rather than raw commodity flows. Allergen extract sourcing remains a supply-chain bottleneck given the biological origin of materials and the regulatory burden of batch consistency across jurisdictions.
Table 5: Allergy Treatment Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: Allergy Treatment Market Revenue Billion Forecast, by Allergen Type 2020 & 2034
Table 7: Allergy Treatment Market Revenue Billion Forecast, by Animal Type 2020 & 2034
Table 8: Allergy Treatment Market Revenue Billion Forecast, by Region 2020 & 2034
Table 9: North America Allergy Treatment Market Revenue Billion Forecast, by Type 2020 & 2034
Table 10: North America Allergy Treatment Market Revenue Billion Forecast, by Treatment 2020 & 2034
Table 11: North America Allergy Treatment Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Table 12: North America Allergy Treatment Market Revenue Billion Forecast, by End-Users 2020 & 2034
Table 13: North America Allergy Treatment Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 14: North America Allergy Treatment Market Revenue Billion Forecast, by Allergen Type 2020 & 2034
Table 15: North America Allergy Treatment Market Revenue Billion Forecast, by Animal Type 2020 & 2034
Table 16: North America Allergy Treatment Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1. What is the current size of the allergy treatment market?
Our first-party research values the global allergy treatment market at USD 24.55 billion in 2025, with an expected expansion to USD 40.72 billion by 2033 at a 6.53% CAGR.
2. Which region holds the largest share of the allergy treatment market?
North America held the largest revenue share at 42.7% in 2025, supported by advanced allergist networks, strong reimbursement frameworks, and a dense concentration of immunotherapy and biologic innovators. Asia-Pacific is the fastest-growing region.
3. Which treatment segment dominates allergy treatment revenue?
Anti-allergy drugs accounted for 60.4% of 2025 market revenue, driven by antihistamines and corticosteroids as first-line therapies. Immunotherapy and biologics are the fastest-growing treatment modalities.
4. Why is the food allergy treatment sub-market growing faster than the overall market?
Food allergy therapeutics expanded from USD 7.47 billion in 2025 toward USD 15.32 billion by 2034 at a 8.3% CAGR, fueled by FDA approvals such as Xolair for severe food allergy and expanded Palforzia labeling for children aged 1–3.
5. Who are the leading companies in the allergy treatment market?
Key players include ALK-Abelló A/S, Stallergenes Greer plc, Allergy Therapeutics plc, HAL Allergy Group, DBV Technologies S.A., Regeneron Pharmaceuticals, Sanofi, AbbVie, Pfizer, GSK, Novartis, Merck & Co., and AstraZeneca.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Approximately 70–80% of total research effort is allocated to primary intelligence, generating a guaranteed estimated data accuracy level of 85–90%.
We conduct structured interviews and surveys with allergen extract and immunotherapy manufacturers, biologic and monoclonal antibody developers, diagnostic reagent and microarray suppliers, hospital and specialty allergy clinic operators, and veterinary dermatology therapeutic providers.
Stakeholder job titles interviewed include Chief Medical Officer / Head of Immunology, VP of Commercial Strategy, Procurement and Supply Chain Director for biologics, and Allergy Clinic Director / Practicing Allergist.
Every report is updated to the date of purchase, ensuring that approval timelines, label expansions, and reimbursement changes are reflected at delivery.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation across prevalence cohorts, prescription volumes, and revenue-per-treated-patient benchmarks.
Bottom-up quantification integrates specific metrics including diagnosed prevalent cases by allergen type, treated-patient share and persistence rates, average annual cost of therapy per patient by drug class, and immunotherapy course completion volumes.
Biologic revenue is modeled separately using eligible severe-asthma and severe-food-allergy cohort sizing and per-unit annual pricing benchmarks, preventing symptomatic-drug volume from distorting the blended market estimate.
Data Accuracy & Quality Check
All estimates pass a three-tier validation gate: cross-source triangulation, analyst peer review, and reconciliation against audited public-company segment disclosures.
We enforce an 85–90% accuracy confidence band and flag any segment where primary interview variance exceeds 10% for re-fielding.
Final figures are stress-tested against regulatory approval calendars, patent-expiry timelines, and reimbursement policy changes to confirm forward CAGR defensibility.
UAE
South Africa
Egypt
Israel
South America
Brazil
Argentina
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. AbbVie Inc.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Pfizer Inc.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. GSK plc
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Novartis AG
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Merck & Co. Inc.
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Bayer AG
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Teva Pharmaceutical Industries Ltd.
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. AstraZeneca
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Circassia Pharmaceuticals plc
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. HollisterStier Allergy
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Thermo Fisher Scientific Inc.
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Danaher Corporation (Beckman Coulter)
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. Siemens Healthineers AG
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. bioMérieux SA
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. Bio-Rad Laboratories Inc.
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. Zoetis
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.1.26. Elanco Animal Health Incorporated
11.1.26.1. Company Overview
11.1.26.2. Products
11.1.26.3. Company Financials
11.1.26.4. SWOT Analysis
11.1.27. Merck Animal Health
11.1.27.1. Company Overview
11.1.27.2. Products
11.1.27.3. Company Financials
11.1.27.4. SWOT Analysis
11.1.28. Boehringer Ingelheim International
11.1.28.1. Company Overview
11.1.28.2. Products
11.1.28.3. Company Financials
11.1.28.4. SWOT Analysis
11.1.29. Virbac
11.1.29.1. Company Overview
11.1.29.2. Products
11.1.29.3. Company Financials
11.1.29.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17: North America Allergy Treatment Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Allergy Treatment Market Revenue (Billion), by Type 2026 & 2034
Figure 19: Europe Allergy Treatment Market Revenue Share (%), by Type 2026 & 2034
Figure 20: Europe Allergy Treatment Market Revenue (Billion), by Treatment 2026 & 2034
Figure 21: Europe Allergy Treatment Market Revenue Share (%), by Treatment 2026 & 2034
Figure 22: Europe Allergy Treatment Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 23: Europe Allergy Treatment Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 24: Europe Allergy Treatment Market Revenue (Billion), by End-Users 2026 & 2034
Figure 25: Europe Allergy Treatment Market Revenue Share (%), by End-Users 2026 & 2034
Figure 26: Europe Allergy Treatment Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 27: Europe Allergy Treatment Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 28: Europe Allergy Treatment Market Revenue (Billion), by Allergen Type 2026 & 2034
Figure 29: Europe Allergy Treatment Market Revenue Share (%), by Allergen Type 2026 & 2034
Figure 30: Europe Allergy Treatment Market Revenue (Billion), by Animal Type 2026 & 2034
Figure 31: Europe Allergy Treatment Market Revenue Share (%), by Animal Type 2026 & 2034
Figure 32: Europe Allergy Treatment Market Revenue (Billion), by Country 2026 & 2034
Figure 33: Europe Allergy Treatment Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Allergy Treatment Market Revenue (Billion), by Type 2026 & 2034
Figure 35: Asia Pacific Allergy Treatment Market Revenue Share (%), by Type 2026 & 2034
Figure 36: Asia Pacific Allergy Treatment Market Revenue (Billion), by Treatment 2026 & 2034
Figure 37: Asia Pacific Allergy Treatment Market Revenue Share (%), by Treatment 2026 & 2034
Figure 38: Asia Pacific Allergy Treatment Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 39: Asia Pacific Allergy Treatment Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 40: Asia Pacific Allergy Treatment Market Revenue (Billion), by End-Users 2026 & 2034
Figure 41: Asia Pacific Allergy Treatment Market Revenue Share (%), by End-Users 2026 & 2034
Figure 42: Asia Pacific Allergy Treatment Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 43: Asia Pacific Allergy Treatment Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 44: Asia Pacific Allergy Treatment Market Revenue (Billion), by Allergen Type 2026 & 2034
Figure 45: Asia Pacific Allergy Treatment Market Revenue Share (%), by Allergen Type 2026 & 2034
Figure 46: Asia Pacific Allergy Treatment Market Revenue (Billion), by Animal Type 2026 & 2034
Figure 47: Asia Pacific Allergy Treatment Market Revenue Share (%), by Animal Type 2026 & 2034
Figure 48: Asia Pacific Allergy Treatment Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Asia Pacific Allergy Treatment Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Allergy Treatment Market Revenue (Billion), by Type 2026 & 2034
Figure 51: Middle East & Africa Allergy Treatment Market Revenue Share (%), by Type 2026 & 2034
Figure 52: Middle East & Africa Allergy Treatment Market Revenue (Billion), by Treatment 2026 & 2034
Figure 53: Middle East & Africa Allergy Treatment Market Revenue Share (%), by Treatment 2026 & 2034
Figure 54: Middle East & Africa Allergy Treatment Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 55: Middle East & Africa Allergy Treatment Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 56: Middle East & Africa Allergy Treatment Market Revenue (Billion), by End-Users 2026 & 2034
Figure 57: Middle East & Africa Allergy Treatment Market Revenue Share (%), by End-Users 2026 & 2034
Figure 58: Middle East & Africa Allergy Treatment Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 59: Middle East & Africa Allergy Treatment Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 60: Middle East & Africa Allergy Treatment Market Revenue (Billion), by Allergen Type 2026 & 2034
Figure 61: Middle East & Africa Allergy Treatment Market Revenue Share (%), by Allergen Type 2026 & 2034
Figure 62: Middle East & Africa Allergy Treatment Market Revenue (Billion), by Animal Type 2026 & 2034
Figure 63: Middle East & Africa Allergy Treatment Market Revenue Share (%), by Animal Type 2026 & 2034
Figure 64: Middle East & Africa Allergy Treatment Market Revenue (Billion), by Country 2026 & 2034
Figure 65: Middle East & Africa Allergy Treatment Market Revenue Share (%), by Country 2026 & 2034
Figure 66: South America Allergy Treatment Market Revenue (Billion), by Type 2026 & 2034
Figure 67: South America Allergy Treatment Market Revenue Share (%), by Type 2026 & 2034
Figure 68: South America Allergy Treatment Market Revenue (Billion), by Treatment 2026 & 2034
Figure 69: South America Allergy Treatment Market Revenue Share (%), by Treatment 2026 & 2034
Figure 70: South America Allergy Treatment Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 71: South America Allergy Treatment Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 72: South America Allergy Treatment Market Revenue (Billion), by End-Users 2026 & 2034
Figure 73: South America Allergy Treatment Market Revenue Share (%), by End-Users 2026 & 2034
Figure 74: South America Allergy Treatment Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 75: South America Allergy Treatment Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 76: South America Allergy Treatment Market Revenue (Billion), by Allergen Type 2026 & 2034
Figure 77: South America Allergy Treatment Market Revenue Share (%), by Allergen Type 2026 & 2034
Figure 78: South America Allergy Treatment Market Revenue (Billion), by Animal Type 2026 & 2034
Figure 79: South America Allergy Treatment Market Revenue Share (%), by Animal Type 2026 & 2034
Figure 80: South America Allergy Treatment Market Revenue (Billion), by Country 2026 & 2034
Figure 81: South America Allergy Treatment Market Revenue Share (%), by Country 2026 & 2034
Table 17: USA Allergy Treatment Market Revenue (Billion) Forecast, by Application 2020 & 2034


 Allergy Treatment Market