 BRIC Diabetes Care Devices Market
 Size, Trends & Forecast 2033
Updated On : Nov 11, 2026|Base Year : 2025|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 BRIC Diabetes Care Devices Market

Amit Mardhekar
Research Analyst

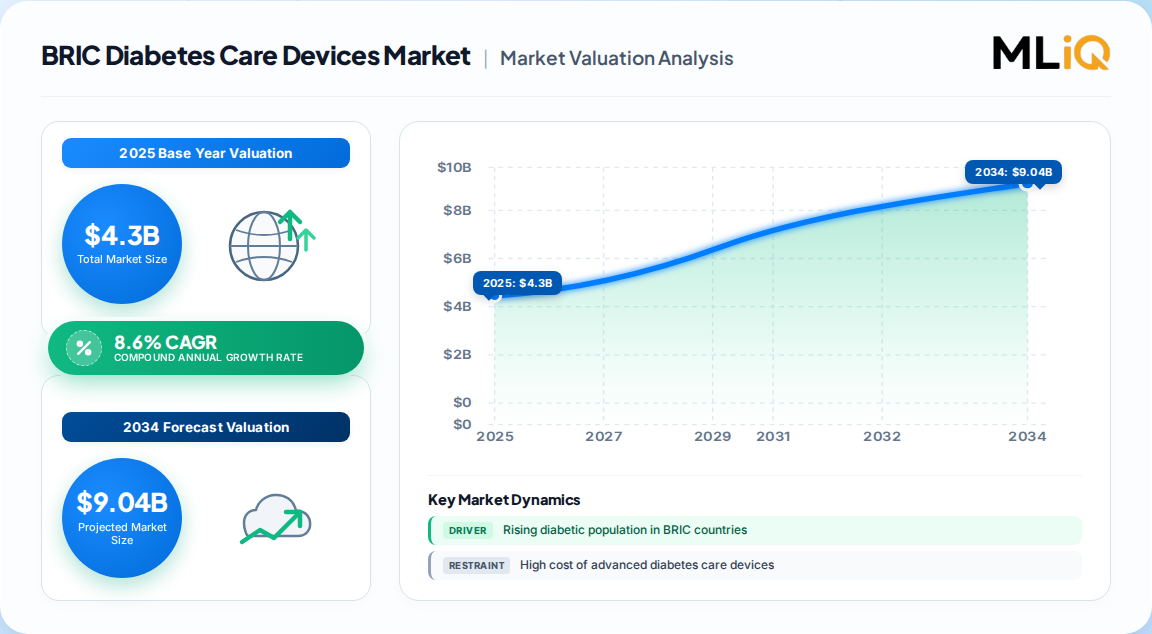
The BRIC diabetes care devices market was valued at USD 4.3 billion in 2025 and is projected to expand to USD 8.2 billion by 2033, registering a CAGR of 8.6% over the forecast period. This growth is underpinned by an escalating diabetic population across Brazil, Russia, India, and China, alongside expanding national health programs and rising adoption of connected care technologies.
| Year | Market Size |
|---|---|
| 2025 | 4.300 B |
| 2026 | 4.670 B |
| 2027 | 5.071 B |
| 2028 | 5.508 B |
| 2029 | 5.981 B |
| 2030 | 6.496 B |
| 2031 | 7.054 B |

China dominated the regional landscape with a 47.0% revenue share in 2025, followed by India, Brazil, and Russia. The market's expansion is further supported by a shift toward remote monitoring, digital therapeutics, and localized manufacturing initiatives.
| Market Metric | Value |
|---|---|
| Base Year Valuation (2025) | USD 4.3 Billion |
| Estimated Valuation (2026) | USD 4.6 Billion |
| Forecast Valuation (2033) | USD 8.2 Billion |
| CAGR (2026-2033) | 8.6% |
| Leading Country (2025) | China (47.0% share) |
The insulin delivery devices segment accounted for the largest revenue share of 53.0% in 2025, driven by the rising number of insulin-dependent diabetes patients and increasing adoption of smart insulin pens and pumps. Within this category, insulin pens held the dominant position owing to their user-friendly design and ease of use, while insulin pumps are expected to witness accelerated adoption due to automation and closed-loop capabilities.
Blood glucose monitoring devices are projected to grow at a notable CAGR, supported by favorable insurance policies, the rising prevalence of type 2 diabetes, and the introduction of smartphone-connected glucometers with long battery life. Continuous glucose monitoring (CGM) systems are gaining traction as real-time data improves glycemic control and reduces complications.
| Product Segment | 2025 Share | Growth Outlook |
|---|---|---|
| Insulin Delivery Devices | 53.0% | Stable dominance |
| Blood Glucose Monitoring Devices | 47.0% | Fastest CAGR |
The hospital pharmacies segment held the largest market share of 52.0% in 2025, as hospitals provide a one-stop solution for diabetes management, including consultations, treatments, and device access. Retail pharmacies are expected to grow robustly, driven by the expanding geriatric population and the convenience of neighborhood access to diabetes supplies.
Online distribution channels are also emerging, particularly in China and India, where e-pharmacies and digital health platforms are improving access to devices and consumables. However, reimbursement complexities and cold-chain requirements for insulin continue to favor hospital and retail settings.
Hospitals led the end-use segment with a revenue share of 38.5% in 2025, reflecting their central role in diabetes diagnosis, treatment, and patient education. Home healthcare settings are gaining significance as patients increasingly self-manage their condition using connected devices and telemonitoring solutions. Diagnostic centers and specialty clinics also contribute meaningfully, particularly in urban centers where diabetes prevalence is highest.
While China leads the BRIC diabetes care devices market, India and Brazil are emerging as critical growth engines. India is expected to register the fastest CAGR, driven by a large diabetic population, government initiatives such as the National Programme for Prevention and Control of Cancer, Diabetes, Cardiovascular Diseases and Stroke (NPCDCS), and increasing penetration of digital health platforms.
Brazil is positioned as the second-largest BRIC market after China, supported by a growing patient pool and improving healthcare infrastructure. Russia, meanwhile, is witnessing steady adoption of insulin pumps and CGM systems, although economic constraints and reimbursement limitations temper growth.
The BRIC diabetes care devices market is characterized by intense competition among global and regional players. Companies are focusing on localized manufacturing, strategic partnerships, and digital health integration to capture market share. Recent developments include:
Key players operating in the region include Abbott, Medtronic, Roche Diagnostics, Johnson & Johnson, Becton Dickinson, Novo Nordisk, Sanofi, Dexcom, Ypsomed, and Terumo Corporation, among others.
The BRIC diabetes care devices market is propelled by several factors, including rising diabetes prevalence, technological advancements, and supportive government initiatives. However, high device costs, limited reimbursement, and regulatory heterogeneity pose challenges.
| Drivers | Restraints | Opportunities |
|---|---|---|
| Rising diabetic population (China and India account for ~40% of global diabetics) | High cost of advanced devices (CGM, insulin pumps) | Digital health and telemedicine adoption |
| Government awareness and screening programs (e.g., NPCDCS in India) | Limited reimbursement coverage across BRIC nations | AI-powered personalized diabetes management |
| Technological advancements (smart pens, CGM, closed-loop systems) | Inconsistent regulatory frameworks and import restrictions | Localized manufacturing and public-private partnerships |
The BRIC diabetes care devices market is increasingly shaped by trade flows and local manufacturing policies. China and India are major importers of advanced CGM sensors and insulin pump components, while also emerging as export hubs for blood glucose meters and test strips. Russia and Brazil rely heavily on imports for high-end devices, creating opportunities for localized assembly and distribution partnerships. Regulatory harmonization and tariff structures remain critical factors influencing supply chain decisions across these markets.
| Region | Market Share (%) |
|---|---|
| China | 0.47% |
| India | 0.23% |
| Brazil | 0.18% |
| Russia | 0.12% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.6% from 2020-2034 |
| Segmentation |
|
The BRIC diabetes care devices market was valued at USD 4.3 billion in 2025 and is projected to reach USD 8.2 billion by 2033, growing at a CAGR of 8.6% from 2026 to 2033.
China dominates the market, accounting for a 47.0% revenue share in 2025, driven by its large diabetic population and expanding healthcare infrastructure.
The market is segmented into insulin delivery devices and blood glucose monitoring devices. Insulin delivery devices held the largest share of 53.0% in 2025, while blood glucose monitoring devices are expected to grow at the fastest CAGR.
Hospitals led the end-use segment with a revenue share of 38.5% in 2025, owing to their central role in diabetes diagnosis and treatment.
Key drivers include the rising prevalence of diabetes, increasing awareness and government screening programs, and technological advancements such as smart insulin pens and continuous glucose monitors.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Chief Medical Officer | 25% |
| Endocrinologist | 25% |
| Diabetes Educator | 20% |
| Company Type | Representation (%) |
|---|---|
| Insulin Delivery Device Manufacturers | 35% |
| Blood Glucose Monitoring Device OEMs | 25% |
| Hospital & Retail Pharmacies | 20% |
| Distributors & Supply Chain Partners | 12% |
| Digital Health & Telemedicine Providers | 8% |