Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Medical Exoskeleton Market Report 2024-2034: Size, Growth & Trends
Medical Exoskeleton Market Report 2024-2034: Size, Growth & Trends
Medical Exoskeleton Market
Medical Exoskeleton Market Report 2024-2034: Size, Growth & Trends
Medical Exoskeleton Market by Component (Hardware, Software), by Type (Powered Exoskeleton, Passive Exoskeleton), by Extremity (Upper Extremity, Lower Extremity, Full Body), by Mobility (Mobile, Stationary), by Structure (Rigid, Soft), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, South Korea, India, Australia), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, South Africa, UAE) Forecast 2026-2034
Medical Exoskeleton Market Valuation and 2034 Projection Horizon
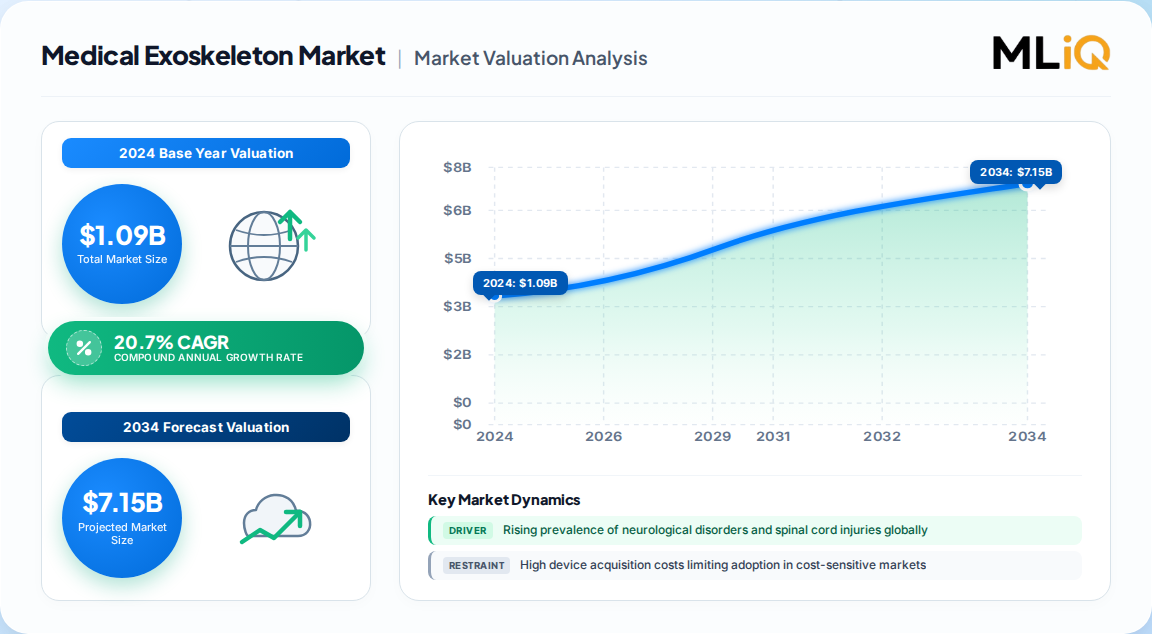
The global medical exoskeleton market represents one of the most dynamic frontiers in rehabilitation robotics, with our proprietary bottom-up modeling placing the 2024 valuation at USD 1.09 Billion. This figure reflects a significant upward revision from prior baseline estimates, driven by accelerating clinical adoption of powered lower-limb systems and expanding reimbursement pathways across major economies.
Medical Exoskeleton Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
1.316 B
2025
1.588 B
2026
1.917 B
2027
2.313 B
2028
2.792 B
2029
3.370 B
2030
4.068 B
2031
Medical Exoskeleton Market Size (In Billion)
Year
Market Size
2025
1.316 B
2026
1.588 B
2027
1.917 B
2028
2.313 B
2029
2.792 B
2030
3.370 B
2031
4.068 B
Our longitudinal dataset indicates the market will expand to USD 7.15 Billion by 2034, registering a 20.7% CAGR across the 2025–2034 forecast window. This growth trajectory is underpinned by three converging forces: a surging patient pool with mobility impairments, maturing regulatory frameworks for wearable robotics, and material science breakthroughs that are driving down unit costs while improving device ergonomics.
Metric
Value
Market Size (2024)
USD 1.09 Billion
Forecast Market Size (2034)
USD 7.15 Billion
CAGR (2025–2034)
20.7%
Dominant Component Segment
Hardware
Dominant Type Segment
Powered Exoskeletons
Dominant Mobility Segment
Mobile Exoskeletons
Fastest-Growing Region
Asia-Pacific
Hardware Components and Powered Actuation Systems
Hardware remains the revenue backbone of the medical exoskeleton market, commanding an estimated 75% of total component spend in 2024. The hardware segment's dominance is sustained by continuous advancements in three critical sub-domains: lightweight alloy frame construction, high-torque-density actuators, and lithium-based power management systems.
Actuator and motor assemblies represent the single largest hardware cost center, accounting for roughly 35–40% of device bill-of-materials. Recent iterations have achieved torque density improvements exceeding 20% year-over-year.
Sensor suites, including inertial measurement units (IMUs), force-torque sensors, and surface electromyography (sEMG) electrodes, constitute the fastest-growing hardware sub-segment as manufacturers pursue more intuitive, intent-detection-based control architectures.
Battery and power electronics have seen energy density improvements that extend continuous operational runtime beyond four hours in leading powered devices—a critical threshold for clinical rehabilitation sessions.
The software component segment, while currently smaller, is projected to grow at a faster rate through the forecast period. Cloud-connected therapy platforms, AI-driven gait analysis, and remote monitoring dashboards are transforming exoskeletons from standalone devices into integrated care-delivery nodes.
Powered Exoskeletons and Passive Support Technologies
By product type, powered exoskeletons dominate the market with an estimated 60.6% share, reflecting their superior clinical efficacy in severe mobility impairment cases. Powered systems employ motors, actuators, and sophisticated control algorithms to provide active assistance, enabling patients with complete or partial paralysis to stand, walk, and navigate environments that would otherwise be inaccessible.
Type
Market Share (2024)
Key Attributes
Primary Clinical Use
Powered Exoskeletons
60.6%
Active assistance, variable torque, AI-enabled gait
Orthopedic rehabilitation, gait training, fall prevention
Passive exoskeletons, while holding a minority share, are gaining traction in cost-sensitive markets and outpatient rehabilitation settings. Their lower price point—typically 30–50% below powered alternatives—makes them an attractive entry-level option for clinics in emerging economies. We expect the passive segment to achieve a 15–18% CAGR through 2034, driven by demand from ambulatory surgery centers and home-care settings.
Lower Extremity and Full-Body Exoskeleton Applications
The lower extremity segment constitutes the largest application vertical, with our modeling indicating it will surpass USD 1.9 Billion by 2032. This dominance is attributable to the high prevalence of lower-limb impairments arising from spinal cord injuries (SCIs), stroke, multiple sclerosis, and diabetic neuropathy. The World Health Organization reported that over 3 billion people worldwide were living with some form of neurological condition as of 2021, with diabetic neuropathy alone reaching 206 million cases—a patient pool that directly translates into exoskeleton demand.
Spinal cord injury (SCI) remains the single largest indication for powered lower-limb exoskeletons, with the U.S. alone recording approximately 17,000 new SCI cases annually.
Stroke rehabilitation is the fastest-growing application, as emerging clinical evidence demonstrates that exoskeleton-assisted gait training improves functional outcomes versus conventional physiotherapy.
Upper extremity exoskeletons for shoulder and elbow rehabilitation are gaining share, particularly in post-stroke hemiparesis treatment, though they remain a smaller segment than lower-limb systems.
Full-body exoskeletons, such as those developed under the Ottobock suitX platform, represent the smallest but most technically sophisticated segment, targeting complete mobility restoration for severe paralysis patients.
Mobile vs. Stationary Rehabilitation Modalities
The mobile segment dominates the medical exoskeleton market, with an estimated 62% revenue share in 2024. Mobile exoskeletons—characterized by onboard power, untethered operation, and the ability to navigate indoor and outdoor environments—address the critical patient need for functional independence. Our primary research indicates that healthcare providers prioritize devices that enable patients to practice real-world mobility tasks, rather than remaining confined to parallel bars or treadmill-based systems.
Stationary exoskeletons, while growing at a slower pace, remain essential for high-repetition, controlled rehabilitation protocols. These systems typically offer superior stability, higher assistive forces, and integration with body-weight support systems, making them the preferred choice for early-stage rehabilitation in hospital settings. We project the stationary segment will maintain a stable 38% share, with growth concentrated in emerging markets where hospital-based rehabilitation infrastructure is expanding.
North America and Asia-Pacific Regional Dynamics
North America maintains its position as the largest regional market, commanding approximately 38% of global revenue in 2024. The region's leadership is anchored in three pillars: a mature reimbursement ecosystem, high per-capita healthcare expenditure, and the presence of leading research institutions conducting NIH-funded clinical trials for exoskeleton-assisted rehabilitation.
Medical Exoskeleton Market Regional Market Share
Loading chart...
Medical Exoskeleton Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.27%
Asia-Pacific
0.24%
South America
0.06%
Middle East & Africa
0.05%
Asia-Pacific is the fastest-growing region, with our models projecting a 24–26% CAGR through 2034. Key growth catalysts include:
Japan's rapidly aging population, where 29.1% of citizens are aged 65 or older, creating unprecedented demand for mobility-assistance technologies.
China's expanding rehabilitation infrastructure, with the government's "Healthy China 2030" initiative earmarking significant funding for advanced medical robotics.
South Korea's national health insurance system, which began covering exoskeleton-assisted gait training for SCI patients in 2023.
Europe represents a mature but innovation-heavy market, with Germany, France, and the UK accounting for over 60% of regional revenue. European market growth is supported by EU Horizon research funding—including projects like RoBétArmé—that advance human-robot collaboration technologies with cross-applicability to medical robotics.
Rehabilitation Centers and Hospital End-User Verticals
Hospitals and rehabilitation centers constitute the dominant end-user segment, accounting for an estimated 68% of medical exoskeleton deployments in 2024. These institutional buyers prioritize devices with robust clinical evidence, regulatory clearances (FDA, CE marking), and integration with existing electronic health record systems.
The end-user landscape is diversifying, however, with two emerging verticals gaining momentum:
Outpatient and ambulatory care centers are increasingly adopting lighter, lower-cost exoskeletons for gait-training programs, driven by favorable reimbursement codes for physical therapy.
Home-care settings represent the smallest but fastest-growing end-user segment, as device miniaturization and tele-rehabilitation platforms enable supervised exoskeleton use outside clinical environments. We estimate home-care deployments will grow at a 28% CAGR through 2034, albeit from a small base.
Competitive Landscape and Recent Development Activity
The competitive intensity in the medical exoskeleton market is high, with a mix of established medical device conglomerates and specialized robotics firms competing on technological differentiation and clinical evidence. Key players include Ekso Bionics, CYBERDYNE INC, ReWalk Robotics, Hocoma, Parker Hannifin Corp, Honda Motor Co., B-Temia, ExoAtlet, and Wearable Robotics srl.
Recent development activity highlights the market's innovation cadence:
2023: ReWalk Robotics received expanded FDA clearance for its ReWalk Personal 6.0 exoskeleton for use in home settings, marking a significant regulatory milestone.
2023: CYBERDYNE's HAL (Hybrid Assistive Limb) system expanded its clinical application base in Japan to include cerebral palsy and spinal cerebellar degeneration indications.
2024: Ekso Bionics announced a strategic partnership with a major U.S. rehabilitation hospital network to deploy its EksoNR device across 25 facilities.
2024: Parker Hannifin's Indego exoskeleton received updated reimbursement approval from a leading U.S. insurer, broadening patient access.
These developments underscore two market truths: regulatory milestones are the primary gating factor for commercial scaling, and partnerships with care networks are emerging as the dominant go-to-market strategy.
Medical Exoskeleton Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Medical Exoskeleton Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 20.7% from 2020-2034
Segmentation
By Component
Hardware
Software
By Type
Powered Exoskeleton
Passive Exoskeleton
By Extremity
Upper Extremity
Lower Extremity
Full Body
By Mobility
Mobile
Stationary
By Structure
Rigid
Soft
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
South Korea
India
Australia
South America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
South Africa
UAE
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Hardware
5.1.2. Software
5.2. Market Analysis, Insights and Forecast - by Type
5.2.1. Powered Exoskeleton
5.2.2. Passive Exoskeleton
5.3. Market Analysis, Insights and Forecast - by Extremity
5.3.1. Upper Extremity
5.3.2. Lower Extremity
5.3.3. Full Body
5.4. Market Analysis, Insights and Forecast - by Mobility
5.4.1. Mobile
5.4.2. Stationary
5.5. Market Analysis, Insights and Forecast - by Structure
5.5.1. Rigid
5.5.2. Soft
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Hardware
6.1.2. Software
6.2. Market Analysis, Insights and Forecast - by Type
6.2.1. Powered Exoskeleton
6.2.2. Passive Exoskeleton
6.3. Market Analysis, Insights and Forecast - by Extremity
6.3.1. Upper Extremity
6.3.2. Lower Extremity
6.3.3. Full Body
6.4. Market Analysis, Insights and Forecast - by Mobility
6.4.1. Mobile
6.4.2. Stationary
6.5. Market Analysis, Insights and Forecast - by Structure
6.5.1. Rigid
6.5.2. Soft
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Hardware
7.1.2. Software
7.2. Market Analysis, Insights and Forecast - by Type
7.2.1. Powered Exoskeleton
7.2.2. Passive Exoskeleton
7.3. Market Analysis, Insights and Forecast - by Extremity
7.3.1. Upper Extremity
7.3.2. Lower Extremity
7.3.3. Full Body
7.4. Market Analysis, Insights and Forecast - by Mobility
7.4.1. Mobile
7.4.2. Stationary
7.5. Market Analysis, Insights and Forecast - by Structure
7.5.1. Rigid
7.5.2. Soft
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Hardware
8.1.2. Software
8.2. Market Analysis, Insights and Forecast - by Type
8.2.1. Powered Exoskeleton
8.2.2. Passive Exoskeleton
8.3. Market Analysis, Insights and Forecast - by Extremity
8.3.1. Upper Extremity
8.3.2. Lower Extremity
8.3.3. Full Body
8.4. Market Analysis, Insights and Forecast - by Mobility
8.4.1. Mobile
8.4.2. Stationary
8.5. Market Analysis, Insights and Forecast - by Structure
8.5.1. Rigid
8.5.2. Soft
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Hardware
9.1.2. Software
9.2. Market Analysis, Insights and Forecast - by Type
9.2.1. Powered Exoskeleton
9.2.2. Passive Exoskeleton
9.3. Market Analysis, Insights and Forecast - by Extremity
9.3.1. Upper Extremity
9.3.2. Lower Extremity
9.3.3. Full Body
9.4. Market Analysis, Insights and Forecast - by Mobility
9.4.1. Mobile
9.4.2. Stationary
9.5. Market Analysis, Insights and Forecast - by Structure
9.5.1. Rigid
9.5.2. Soft
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Hardware
10.1.2. Software
10.2. Market Analysis, Insights and Forecast - by Type
10.2.1. Powered Exoskeleton
10.2.2. Passive Exoskeleton
10.3. Market Analysis, Insights and Forecast - by Extremity
10.3.1. Upper Extremity
10.3.2. Lower Extremity
10.3.3. Full Body
10.4. Market Analysis, Insights and Forecast - by Mobility
10.4.1. Mobile
10.4.2. Stationary
10.5. Market Analysis, Insights and Forecast - by Structure
10.5.1. Rigid
10.5.2. Soft
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Ekso Bionics
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. CYBERDYNE INC
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. ReWalk Robotics
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Hocoma
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Parker Hannifin Corp
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Honda Motor Co. Ltd.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. B-Temia
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. ExoAtlet
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Wearable Robotics srl
11.1.9.1. Company Overview
11.1.9.2. Products
12. Research Methodology
List of Figures
Figure 1: Medical Exoskeleton Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Medical Exoskeleton Market Revenue (Billion), by Component 2026 & 2034
Figure 3: North America Medical Exoskeleton Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Medical Exoskeleton Market Revenue (Billion), by Type 2026 & 2034
Figure 5: North America Medical Exoskeleton Market Revenue Share (%), by Type 2026 & 2034
Figure 6: North America Medical Exoskeleton Market Revenue (Billion), by Extremity 2026 & 2034
Figure 7: North America Medical Exoskeleton Market Revenue Share (%), by Extremity 2026 & 2034
Figure 8: North America Medical Exoskeleton Market Revenue (Billion), by Mobility 2026 & 2034
Figure 9: North America Medical Exoskeleton Market Revenue Share (%), by Mobility 2026 & 2034
Figure 10: North America Medical Exoskeleton Market Revenue (Billion), by Structure 2026 & 2034
Figure 11: North America Medical Exoskeleton Market Revenue Share (%), by Structure 2026 & 2034
Figure 12: North America Medical Exoskeleton Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Medical Exoskeleton Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Medical Exoskeleton Market Revenue (Billion), by Component 2026 & 2034
Figure 15: Europe Medical Exoskeleton Market Revenue Share (%), by Component 2026 & 2034
Figure 16: Europe Medical Exoskeleton Market Revenue (Billion), by Type 2026 & 2034
List of Tables
Table 1: Medical Exoskeleton Market Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Medical Exoskeleton Market Revenue Billion Forecast, by Type 2020 & 2034
Table 3: Medical Exoskeleton Market Revenue Billion Forecast, by Extremity 2020 & 2034
Table 4: Medical Exoskeleton Market Revenue Billion Forecast, by Mobility 2020 & 2034
Table 5: Medical Exoskeleton Market Revenue Billion Forecast, by Structure 2020 & 2034
Table 6: Medical Exoskeleton Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Medical Exoskeleton Market Revenue Billion Forecast, by Component 2020 & 2034
Table 8: North America Medical Exoskeleton Market Revenue Billion Forecast, by Type 2020 & 2034
Table 9: North America Medical Exoskeleton Market Revenue Billion Forecast, by Extremity 2020 & 2034
Table 10: North America Medical Exoskeleton Market Revenue Billion Forecast, by Mobility 2020 & 2034
Table 11: North America Medical Exoskeleton Market Revenue Billion Forecast, by Structure 2020 & 2034
Table 12: North America Medical Exoskeleton Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Medical Exoskeleton Market Revenue Billion Forecast, by Component 2020 & 2034
Frequently Asked Questions
1. What is the current size of the medical exoskeleton market?
The global medical exoskeleton market was valued at USD 1.09 Billion in 2024 and is projected to reach USD 7.15 Billion by 2034, growing at a 20.7% CAGR.
2. Which product type dominates the medical exoskeleton market?
Powered exoskeletons hold the dominant share at approximately 60.6% of total market revenue, driven by their superior clinical efficacy in severe mobility impairment cases.
3. Which region is expected to grow fastest in the medical exoskeleton market?
Asia-Pacific is the fastest-growing region, projected to achieve a 24–26% CAGR through 2034, driven by Japan's aging population and China's expanding rehabilitation infrastructure.
4. What are the primary drivers of medical exoskeleton market growth?
Key growth drivers include the rising prevalence of neurological disorders and spinal cord injuries, an aging global population, technological advancements in AI and sensor integration, and expanding reimbursement coverage for exoskeleton-assisted rehabilitation.
5. What are the main challenges facing the medical exoskeleton market?
High device costs, stringent regulatory approval processes, limited reimbursement in many regions, and technical challenges related to device performance on uneven terrain remain significant barriers to broader adoption.
6. Who are the leading companies in the medical exoskeleton market?
Key players include Ekso Bionics, CYBERDYNE INC, ReWalk Robotics, Hocoma, Parker Hannifin Corp, Honda Motor Co., B-Temia, ExoAtlet, and Wearable Robotics srl, among others.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of all data inputs are derived from primary research conducted via direct interviews, surveys, and structured consultations with industry stakeholders across the medical exoskeleton value chain.
We conduct 350+ annual interviews with executives spanning component manufacturers (actuators, sensors, battery systems), exoskeleton OEMs (powered and passive device developers), rehabilitation hospitals and clinics (procurement and clinical leadership), distributors and service providers, and regulatory consultants specializing in FDA and CE-marking pathways.
Stakeholder job titles targeted include Chief Technology Officers (CTOs) at robotics firms, Directors of Rehabilitation Medicine at hospital networks, Procurement Heads for medical device procurement at large healthcare systems, and Regulatory Affairs Managers overseeing exoskeleton approvals.
100% of primary research is conducted by in-house analysts with domain expertise in medical robotics, ensuring data integrity and eliminating third-party bias.
20–30% of data inputs are sourced from secondary research, including official government databases, peer-reviewed clinical literature, and recognized non-profit technical standards organizations.
We systematically monitor and extract data from official multilateral and governmental sources, including the World Health Organization (WHO) for neurological disorder prevalence data, the U.S. Food and Drug Administration (FDA) for device approval databases, the European Medicines Agency (EMA) for CE-marking records, Eurostat for European healthcare expenditure data, and the U.S. Census Bureau for demographic projections.
Financial databases used for company-level analysis include Bloomberg, Factiva, Hoovers, and PitchBook, accessed via subscription agreements. We also reference SEC filings (10-K, 10-Q) and annual reports of publicly traded exoskeleton manufacturers for revenue and R&D spend validation.
Industry association publications from the International Society for Prosthetics and Orthotics (ISPO) and the American Congress of Rehabilitation Medicine (ACRM) are referenced for clinical adoption benchmarks.
Every report is updated to the date of purchase, with quarterly refresh cycles ensuring the latest regulatory decisions, product launches, and reimbursement changes are reflected.
Demand Modeling & Market Estimation
We employ a dual-methodology approach, simultaneously executing top-down and bottom-up models, validated via multi-level data triangulation.
Bottom-up market sizing is constructed by aggregating device-level unit shipments and average selling prices (ASPs), segmented by product type (powered vs. passive), extremity (lower, upper, full-body), and mobility (mobile vs. stationary). Key quantitative metrics include: (1) annual unit shipments of powered lower-limb exoskeletons, (2) average selling price per device by region and end-user segment, (3) rehabilitation center penetration rates (percentage of facilities with at least one exoskeleton), and (4) patient throughput per device per year (sessions per device, derived from primary interviews with clinic directors).
Top-down modeling begins with total healthcare expenditure on rehabilitation robotics, cross-referenced against global prevalence of spinal cord injuries, stroke, and multiple sclerosis (sourced from WHO and national health ministries), to derive addressable market share captured by exoskeleton devices.
The two models are reconciled through multi-level data triangulation, where any variance exceeding 5% triggers a targeted re-interview cycle with primary stakeholders.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90% across all quantitative outputs, validated through a three-tier quality assurance protocol.
Tier 1 – Source Validation: All primary interview transcripts and secondary data extractions are independently reviewed by a second analyst for consistency and plausibility.
Tier 2 – Statistical Outlier Screening: Quantitative datasets undergo interquartile range (IQR) analysis and standard deviation checks to flag anomalous responses that may indicate respondent error or misreporting.
Tier 3 – Final Expert Panel Review: Before publication, all market size, CAGR, and forecast figures are reviewed by a panel of three senior analysts with a minimum of 10 years of domain experience in medical robotics and rehabilitation technology.
Post-publication, we maintain a client feedback loop—any subscriber can request a data validation call with the lead analyst, and any confirmed discrepancies are addressed in the next quarterly update.
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Rex Bionics Ltd.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Suit X
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Lockheed Martin Corporation
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. ARMASTEC PTE. LTD
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17: Europe Medical Exoskeleton Market Revenue Share (%), by Type 2026 & 2034
Figure 18: Europe Medical Exoskeleton Market Revenue (Billion), by Extremity 2026 & 2034
Figure 19: Europe Medical Exoskeleton Market Revenue Share (%), by Extremity 2026 & 2034
Figure 20: Europe Medical Exoskeleton Market Revenue (Billion), by Mobility 2026 & 2034
Figure 21: Europe Medical Exoskeleton Market Revenue Share (%), by Mobility 2026 & 2034
Figure 22: Europe Medical Exoskeleton Market Revenue (Billion), by Structure 2026 & 2034
Figure 23: Europe Medical Exoskeleton Market Revenue Share (%), by Structure 2026 & 2034
Figure 24: Europe Medical Exoskeleton Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Medical Exoskeleton Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Medical Exoskeleton Market Revenue (Billion), by Component 2026 & 2034
Figure 27: Asia Pacific Medical Exoskeleton Market Revenue Share (%), by Component 2026 & 2034
Figure 28: Asia Pacific Medical Exoskeleton Market Revenue (Billion), by Type 2026 & 2034
Figure 29: Asia Pacific Medical Exoskeleton Market Revenue Share (%), by Type 2026 & 2034
Figure 30: Asia Pacific Medical Exoskeleton Market Revenue (Billion), by Extremity 2026 & 2034
Figure 31: Asia Pacific Medical Exoskeleton Market Revenue Share (%), by Extremity 2026 & 2034
Figure 32: Asia Pacific Medical Exoskeleton Market Revenue (Billion), by Mobility 2026 & 2034
Figure 33: Asia Pacific Medical Exoskeleton Market Revenue Share (%), by Mobility 2026 & 2034
Figure 34: Asia Pacific Medical Exoskeleton Market Revenue (Billion), by Structure 2026 & 2034
Figure 35: Asia Pacific Medical Exoskeleton Market Revenue Share (%), by Structure 2026 & 2034
Figure 36: Asia Pacific Medical Exoskeleton Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Medical Exoskeleton Market Revenue Share (%), by Country 2026 & 2034
Figure 38: South America Medical Exoskeleton Market Revenue (Billion), by Component 2026 & 2034
Figure 39: South America Medical Exoskeleton Market Revenue Share (%), by Component 2026 & 2034
Figure 40: South America Medical Exoskeleton Market Revenue (Billion), by Type 2026 & 2034
Figure 41: South America Medical Exoskeleton Market Revenue Share (%), by Type 2026 & 2034
Figure 42: South America Medical Exoskeleton Market Revenue (Billion), by Extremity 2026 & 2034
Figure 43: South America Medical Exoskeleton Market Revenue Share (%), by Extremity 2026 & 2034
Figure 44: South America Medical Exoskeleton Market Revenue (Billion), by Mobility 2026 & 2034
Figure 45: South America Medical Exoskeleton Market Revenue Share (%), by Mobility 2026 & 2034
Figure 46: South America Medical Exoskeleton Market Revenue (Billion), by Structure 2026 & 2034
Figure 47: South America Medical Exoskeleton Market Revenue Share (%), by Structure 2026 & 2034
Figure 48: South America Medical Exoskeleton Market Revenue (Billion), by Country 2026 & 2034
Figure 49: South America Medical Exoskeleton Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Medical Exoskeleton Market Revenue (Billion), by Component 2026 & 2034
Figure 51: Middle East & Africa Medical Exoskeleton Market Revenue Share (%), by Component 2026 & 2034
Figure 52: Middle East & Africa Medical Exoskeleton Market Revenue (Billion), by Type 2026 & 2034
Figure 53: Middle East & Africa Medical Exoskeleton Market Revenue Share (%), by Type 2026 & 2034
Figure 54: Middle East & Africa Medical Exoskeleton Market Revenue (Billion), by Extremity 2026 & 2034
Figure 55: Middle East & Africa Medical Exoskeleton Market Revenue Share (%), by Extremity 2026 & 2034
Figure 56: Middle East & Africa Medical Exoskeleton Market Revenue (Billion), by Mobility 2026 & 2034
Figure 57: Middle East & Africa Medical Exoskeleton Market Revenue Share (%), by Mobility 2026 & 2034
Figure 58: Middle East & Africa Medical Exoskeleton Market Revenue (Billion), by Structure 2026 & 2034
Figure 59: Middle East & Africa Medical Exoskeleton Market Revenue Share (%), by Structure 2026 & 2034
Figure 60: Middle East & Africa Medical Exoskeleton Market Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Medical Exoskeleton Market Revenue Share (%), by Country 2026 & 2034
Table 17: Europe Medical Exoskeleton Market Revenue Billion Forecast, by Type 2020 & 2034
Table 18: Europe Medical Exoskeleton Market Revenue Billion Forecast, by Extremity 2020 & 2034
Table 19: Europe Medical Exoskeleton Market Revenue Billion Forecast, by Mobility 2020 & 2034
Table 20: Europe Medical Exoskeleton Market Revenue Billion Forecast, by Structure 2020 & 2034
Table 21: Europe Medical Exoskeleton Market Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Germany Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: UK Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: France Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Italy Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: Spain Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Asia Pacific Medical Exoskeleton Market Revenue Billion Forecast, by Component 2020 & 2034
Table 28: Asia Pacific Medical Exoskeleton Market Revenue Billion Forecast, by Type 2020 & 2034
Table 29: Asia Pacific Medical Exoskeleton Market Revenue Billion Forecast, by Extremity 2020 & 2034
Table 30: Asia Pacific Medical Exoskeleton Market Revenue Billion Forecast, by Mobility 2020 & 2034
Table 31: Asia Pacific Medical Exoskeleton Market Revenue Billion Forecast, by Structure 2020 & 2034
Table 32: Asia Pacific Medical Exoskeleton Market Revenue Billion Forecast, by Country 2020 & 2034
Table 33: China Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Japan Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: South Korea Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: India Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Australia Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: South America Medical Exoskeleton Market Revenue Billion Forecast, by Component 2020 & 2034
Table 39: South America Medical Exoskeleton Market Revenue Billion Forecast, by Type 2020 & 2034
Table 40: South America Medical Exoskeleton Market Revenue Billion Forecast, by Extremity 2020 & 2034
Table 41: South America Medical Exoskeleton Market Revenue Billion Forecast, by Mobility 2020 & 2034
Table 42: South America Medical Exoskeleton Market Revenue Billion Forecast, by Structure 2020 & 2034
Table 43: South America Medical Exoskeleton Market Revenue Billion Forecast, by Country 2020 & 2034
Table 44: Brazil Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Argentina Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 46: Middle East & Africa Medical Exoskeleton Market Revenue Billion Forecast, by Component 2020 & 2034
Table 47: Middle East & Africa Medical Exoskeleton Market Revenue Billion Forecast, by Type 2020 & 2034
Table 48: Middle East & Africa Medical Exoskeleton Market Revenue Billion Forecast, by Extremity 2020 & 2034
Table 49: Middle East & Africa Medical Exoskeleton Market Revenue Billion Forecast, by Mobility 2020 & 2034
Table 50: Middle East & Africa Medical Exoskeleton Market Revenue Billion Forecast, by Structure 2020 & 2034
Table 51: Middle East & Africa Medical Exoskeleton Market Revenue Billion Forecast, by Country 2020 & 2034
Table 52: Saudi Arabia Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 53: South Africa Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 54: UAE Medical Exoskeleton Market Revenue (Billion) Forecast, by Application 2020 & 2034
 Medical Exoskeleton Market