Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Diabetes Therapeutics Market by Product (Injectables(Insulin, GLP-1 Receptor Agonists), Oral-Antidiabetic Drugs(Metformin, DPP-4 Inhibitors, SGLT2 Inhibitors)), by Drug Class (Insulin, DPP-4 Inhibitors, GLP-1 Receptor Agonists, SGLT2 Inhibitors, Others), by Diabetes Type (Type 1, Type 2, Gestational), by Route of Administration (Oral, Injectable/IV), by Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Others), by End User (Hospitals and Clinics, Home Care Settings, Diagnostic Centers), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia) Forecast 2026-2034
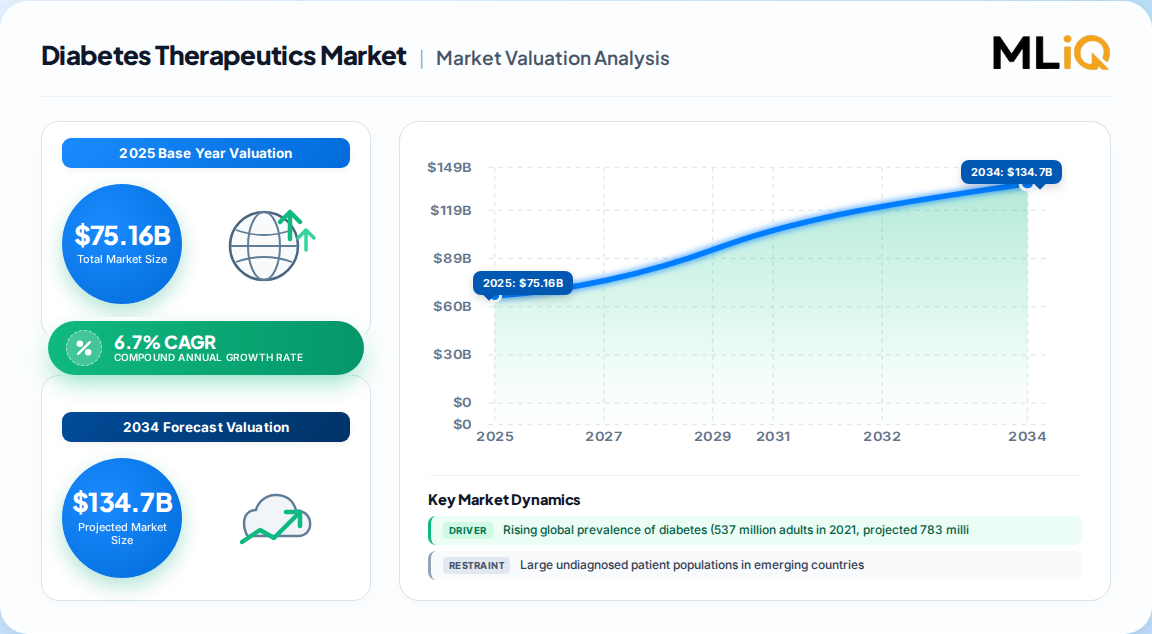
Diabetes Therapeutics Market Valuation Timeline and Growth Trajectory
The global diabetes therapeutics market was valued at $75.16 billion in 2025 and is projected to reach $143.76 billion by 2035, expanding at a CAGR of 6.7%.
A broader therapeutic and diagnostics framing places the market at $120.6 billion in 2024, rising to $241.5 billion by 2030 at a CAGR of 12.4%, underscoring the accelerating integration of drugs, monitoring, and delivery systems.
The type 2 diabetes mellitus treatment sub-segment alone accounted for $57.5 billion in 2023, forecast to reach $91.9 billion by 2030 at a 6.9% CAGR.
North America remains the dominant revenue pool, holding 39.5% of the T2DM treatment market in 2023 and commanding the highest regional share across the broader therapeutics landscape.
Metric
Base Value
Forecast Value
CAGR
Diabetes Drugs Market (2025–2035)
$75.16 Billion
$143.76 Billion
6.7%
Therapeutics & Diagnostics (2024–2030)
$120.6 Billion
$241.5 Billion
12.4%
T2DM Treatment (2023–2030)
$57.5 Billion
$91.9 Billion
6.9%
Diabetes Therapeutics Market Size (In Billion)
150.0B
100.0B
50.0B
0
75.16 B
2025
80.20 B
2026
85.57 B
2027
91.30 B
2028
97.42 B
2029
103.9 B
2030
110.9 B
2031
Diabetes Therapeutics Market Size (In Billion)
Year
Market Size
2025
75.16 B
2026
80.20 B
2027
85.57 B
2028
91.30 B
2029
97.42 B
2030
103.9 B
2031
110.9 B
Insulin and GLP-1 Receptor Agonist Drug Class Dynamics
Insulin remains the most lucrative drug class, generating $57.47 billion in 2023 within the T2DM segment alone, and is projected to register the fastest growth through 2030.
GLP-1 receptor agonists (semaglutide, liraglutide, dulaglutide) and SGLT2 inhibitors (empagliflozin, dapagliflozin) are reshaping the treatment paradigm by delivering glycemic control alongside weight loss and cardiovascular protection.
Combination therapies targeting multiple mechanisms are gaining traction, supported by extensive clinical trials and regulatory endorsements that reduce hypoglycemia risk.
Oral antidiabetic drugs (OADs), led by metformin as the first-line standard, continue to anchor early-stage treatment, while once-weekly injectables and oral GLP-1 candidates represent the next innovation frontier.
The rise of dual agonist therapies and non-invasive insulin delivery systems is expected to intensify competition and expand addressable patient populations.
Drug Class
2023 Revenue (T2DM)
Growth Outlook
Insulin
$57.47 Billion
Fastest CAGR through 2030
DPP-4 Inhibitors
Significant share
Moderate growth
GLP-1 Receptor Agonists
Rapidly expanding
High growth, weight/cardio benefits
SGLT2 Inhibitors
Expanding
High growth, renal/cardio protection
Type 2 Diabetes Prevalence and Geriatric Population Drivers
The International Diabetes Federation reported 537 million adults (20–79 years) with diabetes in 2021, projected to reach 643 million by 2030 and 783 million by 2045.
Type 2 diabetes accounts for approximately 90–95% of all diabetes cases, driven by sedentary lifestyles, obesity, and aging populations.
The UN projects the global population aged 65+ will more than double from 761 million in 2021 to 1.6 billion by 2050, directly expanding the at-risk cohort.
In the U.S., 38.4 million people (11.6% of the population) had diabetes in 2021, per the National Institute of Diabetes and Digestive and Kidney Diseases.
More than 75% of diabetic adults reside in low- and middle-income countries, creating a vast underpenetrated demand pool.
Technological Integration in Glucose Monitoring and Insulin Delivery
Continuous glucose monitoring (CGM) systems enable real-time glucose tracking and predictive alerts, improving glycemic control and reducing hypoglycemia risk.
Automated insulin delivery (AID) systems and wearable insulin pumps reduce manual injection burden and enhance adherence.
AI and machine learning integration supports predictive analytics, personalized care plans, and remote monitoring via digital health platforms.
Smart insulin pens and connected devices are improving patient engagement and data-driven treatment adjustments.
The type 1 diabetes segment is a key beneficiary, with TZIELD (teplizumab) expected to garner the highest market share in the 7MM during 2026–2036.
North America and Asia-Pacific Regional Growth Contrast
North America leads with advanced healthcare infrastructure, high disease prevalence, supportive reimbursement, and widespread CGM adoption.
Asia-Pacific is expected to register the highest CAGR, fueled by expanding healthcare infrastructure, rising awareness, and large undiagnosed populations.
Europe maintains a strong position through government initiatives and favorable regulatory frameworks.
Latin America and Middle East & Africa present long-term opportunities, constrained by limited access and underdeveloped diagnostic services.
Competitive Landscape and Strategic Industry Developments
Leading companies include Novo Nordisk, Eli Lilly, Sanofi, AstraZeneca, Boehringer Ingelheim, Merck, Abbott, and Dexcom.
In March 2024, Eli Lilly partnered with Amazon Pharmacy to distribute GLP-1 drugs (Mounjaro, Zepbound), expanding global reach.
In January 2024, Glenmark launched Lirafit, a biosimilar liraglutide, in India at approximately $1.21 per 1.2 mg daily dose.
In August 2023, Lupin acquired diabetes brands ONDERO and ONDERO MET from Boehringer Ingelheim, strengthening its portfolio.
In June 2023, Pfizer advanced a late-stage oral GLP-1 receptor agonist candidate for obesity and diabetes.
The FDA and EMA facilitate faster access through Breakthrough Therapy and Fast Track designations, while the ADA's Standards of Care 2024 update evidence-based guidelines.
Undiagnosed Populations and Access Barriers in Emerging Economies
Large undiagnosed patient populations in emerging countries restrain market growth, as low awareness and limited diagnostic access delay treatment initiation.
High treatment costs and limited reimbursement in low- and middle-income countries restrict adoption of advanced therapies and monitoring devices.
Patent expirations on key molecules are expected to accelerate biosimilar entry, improving affordability but pressuring branded revenues.
Government initiatives such as the CDC's National Diabetes Prevention Program and the WHO Global Diabetes Compact aim to bridge access gaps and expand early intervention.
Public-private partnerships and increased R&D investment (e.g., Sun Pharma's GLP-1 studies) are critical to addressing unmet needs.
1. What is the current size of the diabetes therapeutics market?
The global diabetes drugs market was valued at $75.16 billion in 2025 and is projected to reach $143.76 billion by 2035, growing at a 6.7% CAGR. The broader therapeutics and diagnostics market was $120.6 billion in 2024, forecast to reach $241.5 billion by 2030.
2. Which region dominates the diabetes therapeutics market?
North America holds the largest share, accounting for 39.5% of the type 2 diabetes treatment market in 2023, driven by high disease prevalence, advanced healthcare infrastructure, and widespread adoption of CGM systems. Asia-Pacific is expected to register the fastest CAGR.
3. What are the key drivers of the diabetes therapeutics market?
Key drivers include the rising global prevalence of diabetes (537 million adults in 2021, projected to reach 783 million by 2045), an aging population (1.6 billion aged 65+ by 2050), technological advancements in insulin delivery and CGM, and increasing R&D investment in novel therapies like GLP-1 receptor agonists and SGLT2 inhibitors.
4. Which drug class leads the diabetes therapeutics market?
Insulin remains the most lucrative drug class, generating $57.47 billion in 2023 within the T2DM segment. However, GLP-1 receptor agonists and SGLT2 inhibitors are the fastest-growing classes, offering glycemic control plus cardiovascular and renal benefits.
5. What are the main challenges facing the diabetes therapeutics market?
Major challenges include large undiagnosed patient populations in emerging countries, high treatment costs, limited access in low- and middle-income countries, and patent expirations on key molecules leading to biosimilar competition. More than 75% of diabetic adults reside in low- or middle-income countries.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is allocated to primary research, engaging directly with industry executives across the diabetes therapeutics value chain.
Target respondents include: Pharmaceutical and Biologics Manufacturers, Insulin and GLP-1 API Suppliers, Medical Device and CGM System OEMs, Specialty Pharmacy and Distribution Channels, and Clinical Research Organizations (CROs).
Senior stakeholder interviews cover job titles such as Chief Medical Officer, VP of Diabetes Franchise, Director of Market Access, and Head of Clinical Development.
Structured questionnaires, in-depth interviews, and expert panel discussions are conducted across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Medical Officer
30%
VP of Diabetes Franchise
25%
Director of Market Access
25%
Head of Clinical Development
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Pharmaceutical and Biologics Manufacturers
40%
Insulin and GLP-1 API Suppliers
25%
CGM and Insulin Delivery Device OEMs
20%
Specialty Pharmacy and Distribution Channels
15%
Secondary Research & Industry Benchmarking
20–30% of effort is devoted to secondary research, drawing on official multilateral sources including the World Health Organization (WHO), International Diabetes Federation (IDF), Centers for Disease Control and Prevention (CDC), National Institute of Diabetes and Digestive and Kidney Diseases (NIDDK), and United Nations (UN) population data.
Financial and corporate data are sourced from Bloomberg, Factiva, Hoovers, and PitchBook, alongside company annual reports, SEC filings, and regulatory submissions to the FDA and EMA.
Industry association benchmarks are drawn from the American Diabetes Association (ADA), European Association for the Study of Diabetes (EASD), and Diabetes Technology Society (DTS).
All data are validated against government health statistics (.gov), non-profit technical standards (.org), and recognized trade association publications; no commercial market research websites are cited.
Demand Modeling & Market Estimation
Bottom-up market sizing is built from patient-level quantification, incorporating diagnosed prevalence, treatment penetration rates, average annual cost of therapy, and units per patient per year across drug classes and geographies.
Top-down estimation leverages total healthcare expenditure on diabetes and manufacturer revenue aggregation, enabling multi-level data triangulation.
Key quantitative metrics include: global diagnosed diabetes population (537 million in 2021), type 2 share of total cases (90–95%), insulin revenue per patient, and GLP-1 prescription volume growth rates.
Segment-level forecasts are developed by drug class (insulin, GLP-1, SGLT2, DPP-4, OADs), route of administration (oral, injectable), and distribution channel (hospital pharmacies, retail, online).
Data Accuracy & Quality Check
Guaranteed data accuracy level of 85–90%, achieved through rigorous cross-validation of primary responses against official statistics.
Multi-level data triangulation is applied, comparing bottom-up patient-based estimates with top-down revenue aggregation and supply-side API volume data.
Every report is updated to the date of purchase, incorporating the latest clinical trial results, regulatory approvals, and market developments.
Quality assurance includes outlier detection, confidence interval testing, and reconciliation of regional market shares with published epidemiological data from the WHO and IDF.
9.1.9.3. Company Financials
9.1.9.4. SWOT Analysis
9.1.10. Medtronic
9.1.10.1. Company Overview
9.1.10.2. Products
9.1.10.3. Company Financials
9.1.10.4. SWOT Analysis
9.1.11. F. Hoffmann-La Roche Ltd.
9.1.11.1. Company Overview
9.1.11.2. Products
9.1.11.3. Company Financials
9.1.11.4. SWOT Analysis
9.1.12. B. Braun SE
9.1.12.1. Company Overview
9.1.12.2. Products
9.1.12.3. Company Financials
9.1.12.4. SWOT Analysis
9.1.13. Terumo Corp.
9.1.13.1. Company Overview
9.1.13.2. Products
9.1.13.3. Company Financials
9.1.13.4. SWOT Analysis
9.1.14. Insulet Corp.
9.1.14.1. Company Overview
9.1.14.2. Products
9.1.14.3. Company Financials
9.1.14.4. SWOT Analysis
9.1.15. Lifescan IP Holdings LLC
9.1.15.1. Company Overview
9.1.15.2. Products
9.1.15.3. Company Financials
9.1.15.4. SWOT Analysis
9.1.16. Bayer AG
9.1.16.1. Company Overview
9.1.16.2. Products
9.1.16.3. Company Financials
9.1.16.4. SWOT Analysis
9.1.17. Dr. Reddy's Laboratories
9.1.17.1. Company Overview
9.1.17.2. Products
9.1.17.3. Company Financials
9.1.17.4. SWOT Analysis
9.1.18. Sun Pharmaceuticals
9.1.18.1. Company Overview
9.1.18.2. Products
9.1.18.3. Company Financials
9.1.18.4. SWOT Analysis
9.1.19. Takeda Pharmaceuticals
9.1.19.1. Company Overview
9.1.19.2. Products
9.1.19.3. Company Financials
9.1.19.4. SWOT Analysis
9.1.20. Novartis AG
9.1.20.1. Company Overview
9.1.20.2. Products
9.1.20.3. Company Financials
9.1.20.4. SWOT Analysis
9.1.21. Glenmark Pharmaceuticals
9.1.21.1. Company Overview
9.1.21.2. Products
9.1.21.3. Company Financials
9.1.21.4. SWOT Analysis
9.1.22. Lupin
9.1.22.1. Company Overview
9.1.22.2. Products
9.1.22.3. Company Financials
9.1.22.4. SWOT Analysis
9.1.23. Pfizer Inc.
9.1.23.1. Company Overview
9.1.23.2. Products
9.1.23.3. Company Financials
9.1.23.4. SWOT Analysis
9.1.24. Provention Bio
9.1.24.1. Company Overview
9.1.24.2. Products
9.1.24.3. Company Financials
9.1.24.4. SWOT Analysis
9.1.25. Diamyd Medical
9.1.25.1. Company Overview
9.1.25.2. Products
9.1.25.3. Company Financials
9.1.25.4. SWOT Analysis
9.2. Market Entropy
9.2.1. Company's Key Areas Served
9.2.2. Recent Developments
9.3. Company Market Share Analysis, 2026
9.3.1. Top 5 Companies Market Share Analysis
9.3.2. Top 3 Companies Market Share Analysis
9.4. List of Potential Customers
Figure 16:
Figure 17: Europe Diabetes Therapeutics Market Revenue Share (%), by Product 2026 & 2034
Figure 18: Europe Diabetes Therapeutics Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 19: Europe Diabetes Therapeutics Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 20: Europe Diabetes Therapeutics Market Revenue (Billion), by Diabetes Type 2026 & 2034
Figure 21: Europe Diabetes Therapeutics Market Revenue Share (%), by Diabetes Type 2026 & 2034
Figure 22: Europe Diabetes Therapeutics Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 23: Europe Diabetes Therapeutics Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 24: Europe Diabetes Therapeutics Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 25: Europe Diabetes Therapeutics Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 26: Europe Diabetes Therapeutics Market Revenue (Billion), by End User 2026 & 2034
Figure 27: Europe Diabetes Therapeutics Market Revenue Share (%), by End User 2026 & 2034
Figure 28: Europe Diabetes Therapeutics Market Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe Diabetes Therapeutics Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia Pacific Diabetes Therapeutics Market Revenue (Billion), by Product 2026 & 2034
Figure 31: Asia Pacific Diabetes Therapeutics Market Revenue Share (%), by Product 2026 & 2034
Figure 32: Asia Pacific Diabetes Therapeutics Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 33: Asia Pacific Diabetes Therapeutics Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 34: Asia Pacific Diabetes Therapeutics Market Revenue (Billion), by Diabetes Type 2026 & 2034
Figure 35: Asia Pacific Diabetes Therapeutics Market Revenue Share (%), by Diabetes Type 2026 & 2034
Figure 36: Asia Pacific Diabetes Therapeutics Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 37: Asia Pacific Diabetes Therapeutics Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 38: Asia Pacific Diabetes Therapeutics Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 39: Asia Pacific Diabetes Therapeutics Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 40: Asia Pacific Diabetes Therapeutics Market Revenue (Billion), by End User 2026 & 2034
Figure 41: Asia Pacific Diabetes Therapeutics Market Revenue Share (%), by End User 2026 & 2034
Figure 42: Asia Pacific Diabetes Therapeutics Market Revenue (Billion), by Country 2026 & 2034
Figure 43: Asia Pacific Diabetes Therapeutics Market Revenue Share (%), by Country 2026 & 2034


 Diabetes Therapeutics Market