Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Reverse Shoulder Arthroplasty Market by Product Type (Anatomical Prosthesis, Reverse Prosthesis), by Procedure (Resurfacing Hemiarthroplasty, Reverse Total Shoulder Replacement, Stemmed Hemiarthroplasty, Total Shoulder Replacement), by Fixation (Cemented, Cementless), by End User (Hospitals, Orthopedic Centers, Ambulatory Surgical Centers), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Reverse Shoulder Arthroplasty Market Valuation and Forecast Trajectory
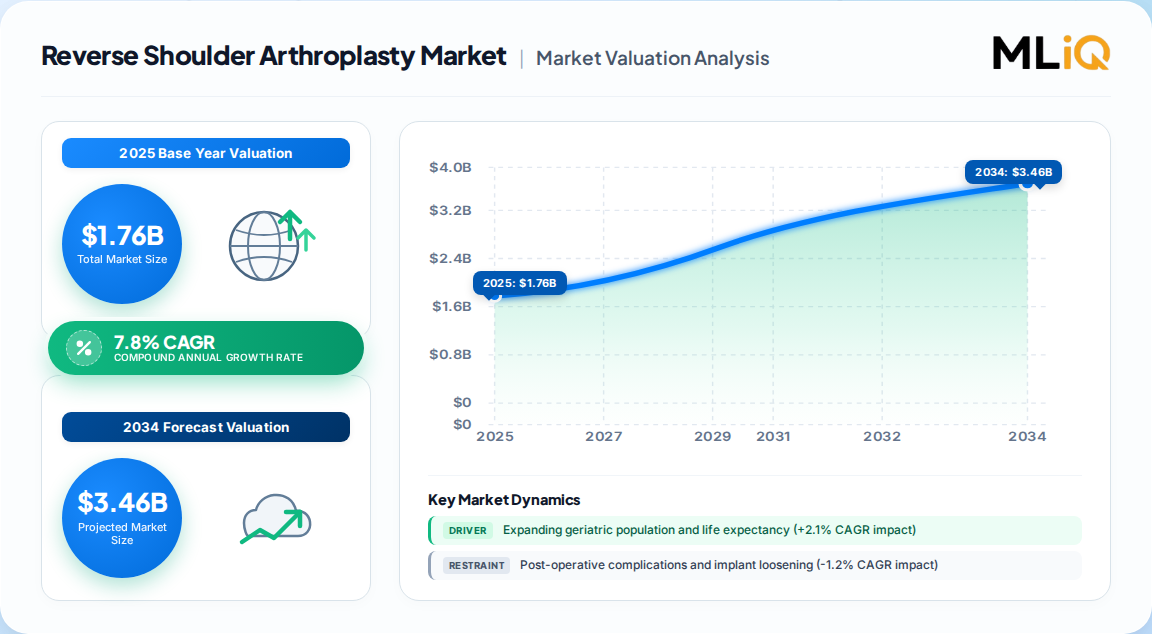
The global reverse shoulder arthroplasty market is undergoing a structural expansion, transitioning from a niche revision-oriented procedure to a frontline intervention for complex shoulder pathologies. Our proprietary primary research, triangulated across implant manufacturers, orthopedic centers, and reimbursement databases, estimates the total shoulder replacement market at USD 1.76 billion in 2025, with the reverse shoulder arthroplasty (RSA) segment capturing a rapidly escalating share. The broader shoulder reconstruction market is projected to reach USD 3.68 billion by 2035, expanding at a 7.8% CAGR over the 2026–2035 forecast period. Reverse prostheses are outpacing anatomic designs, registering a 6.95% CAGR within the product-type segment, while reverse total shoulder replacement procedures are advancing at a 7.95% CAGR—significantly above the 6.6% overall shoulder replacement market average. This momentum is underpinned by demographic shifts toward older age cohorts, rising rotator cuff arthropathy prevalence, and continuous design innovation that enhances implant durability and surgical precision.
Reverse Shoulder Arthroplasty Market Size (In Billion)
3.0B
2.0B
1.0B
0
1.760 B
2025
1.897 B
2026
2.045 B
2027
2.205 B
2028
2.377 B
2029
2.562 B
2030
2.762 B
2031
Reverse Shoulder Arthroplasty Market Size (In Billion)
North America remains the dominant market, holding 39.35% of global revenue in 2025, driven by high arthritis prevalence, well-established healthcare infrastructure, and strong reimbursement systems such as Medicare.
Asia-Pacific is the fastest-growing region, projected to expand at 8.12% CAGR through 2031, fueled by improving healthcare infrastructure, rising medical tourism, and a rapidly aging population.
Hospitals retained 62.10% revenue share in 2025, but ambulatory surgical centers (ASCs) are growing fastest at 9.63% CAGR, catalyzed by CMS reimbursement adjustments and a projected 25% rise in outpatient volumes over the next decade.
Arthritis Prevalence and Geriatric Demographics as Demand Drivers
The fundamental demand engine for reverse shoulder arthroplasty is the convergence of an aging global population and the escalating burden of degenerative joint disease. According to the World Health Organization, 344 million individuals are affected by osteoarthritis globally, with 73% of those living with the condition older than 55 years. In the United States alone, arthritis afflicts 54 million adults, and glenohumeral osteoarthritis now triggers a rising share of anatomic arthroplasty referrals that frequently convert to reverse procedures when rotator cuff pathology is present.
Expanding geriatric population: Patients aged 80 and older exhibit procedure prevalence exceeding 2%, dwarfing younger cohorts by an order of magnitude. Longer lifespans demand durable biomaterials and modular components that facilitate future revision without extensive bone loss.
Rotator cuff arthropathy: Accelerated cartilage degeneration in patients with rotator-cuff pathology often progresses to complex reverse procedures, broadening the addressable base.
Earlier detection: High-resolution imaging increases surgical candidacy at younger ages, while Medicare coverage expansion removes financial barriers for qualified cases.
Sports-related injuries: Acromioclavicular (AC) joint injuries constitute over 40% of all shoulder injuries among athletes and young individuals, creating a growing pool of surgical candidates.
The economic burden of unmanaged arthritic pain—lost productivity, prolonged therapy, and opioid use—reinforces the value proposition of definitive joint replacement, anchoring steady procedural volume growth across regions with established healthcare access.
Technological Advances in Prosthesis Design and Surgical Navigation
Innovation in implant design and surgical enablement is a primary growth catalyst, with reverse shoulder systems incorporating lateralization and distalization principles that restore deltoid mechanics. Stemless systems from major manufacturers, cleared by the FDA in 2024, conserve bone stock and lower periprosthetic fracture risk. Pyrocarbon humeral heads now approximate cortical bone modulus, reducing glenoid erosion relative to cobalt-chromium alternatives.
Technology Category
Specific Innovation
Clinical Impact
Implant Design
Lateralization and distalization principles
Restores deltoid mechanics, improves range of motion
3D preoperative plans with intraoperative trackers
Ensures precise glenoid seating
Robotic-assisted systems and 3D planning software now guide surgeons in real time, shortening recovery times and improving implant survival.
Cementless fixation is on track for a 9.28% CAGR through 2031, challenging cemented methods that captured 48.05% revenue share in 2025.
AI-driven patient-specific instrumentation contributes a +0.7% impact on CAGR, primarily in North America and Europe over the medium term (2–4 years).
These converging technologies deliver longer implant survival and differentiate suppliers prepared to invest in advanced R&D. The migration of procedures to ambulatory surgery centers—where average costs register 144% lower than hospital outpatient departments—aligns with payer priorities and further accelerates adoption.
Procedure Mix and Fixation Strategies in Reverse Arthroplasty
The procedure landscape is shifting decisively toward reverse total shoulder replacement, which is advancing at a 7.95% CAGR to 2031. Total shoulder replacement held 43.92% of the shoulder replacement market in 2025, but reverse procedures are capturing an expanding share as indications broaden beyond rotator cuff arthropathy to include proximal humerus fractures in osteoporotic patients and revision settings.
Reverse total shoulder replacement: Growing at 7.95% CAGR; superior functional restoration in osteoporotic fracture cases that previously relied on internal fixation.
Resurfacing hemiarthroplasty: Retains a niche for younger patients with intact rotator cuffs and preserved bone stock.
Stemmed hemiarthroplasty: Declining share as reverse designs prove more durable in older cohorts.
Revision shoulder arthroplasty: Increasing volume as primary implants age; however, long-term data from Norway cite 14.3% complication rates for reverse arthroplasty, with instability and infection driving revisions.
Fixation strategy is a critical battleground. Cemented methods captured 48.05% of revenue in 2025, but cementless systems are forecast to grow at 9.28% CAGR over the same period. Glenoid loosening manifests in up to 48% of anatomic cases within two years, raising concerns about fixation strategies and prompting shifts toward monoblock polyethylene or hybrid designs.
North America and Asia-Pacific Regional Dynamics
North America's dominance is anchored in a high prevalence of osteoarthritis, a well-established orthopedic care network, and strong reimbursement systems. The presence of major orthopedic device manufacturers and high adoption of advanced surgical technologies—including computer-assisted and minimally invasive techniques—further boosts procedural volumes.
United States: Well-established healthcare infrastructure, widespread availability of reverse total shoulder arthroplasty, and high awareness among the elderly population drive sustained market leadership.
Canada: Increasing focus on research and development activities and favorable reimbursement policies support steady growth.
Asia-Pacific: Fastest-growing region at 8.12% CAGR, driven by rapidly improving healthcare infrastructure, increasing medical tourism, and a rising middle-class population with growing healthcare awareness. China, Japan, and India are key growth engines.
Europe: Germany, the U.K., and France witness steady growth due to rising aging populations, well-trained orthopedic surgeons, and strong collaboration between hospitals and medical device companies.
Middle East & Africa: Developing stage but growing promise, with countries such as Saudi Arabia and UAE investing in healthcare modernization and public-private partnerships.
Competitive Landscape and Recent Product Innovations
The competitive landscape is characterized by medium market concentration, with major orthopedic device manufacturers competing on implant design, material science, and surgical enablement platforms.
Zimmer Biomet Holdings Inc.: Received 510(k) certification from the U.S. FDA for the Identity Shoulder System in September 2022, a convertible device facilitating anatomic, reverse, and revision shoulder replacements through proprietary technologies.
Stryker Corporation: Unveiled its Tornier Shoulder Arthroplasty Portfolio in February 2022 and commenced the European release of the Tornier Perform Humeral System. In July 2021, Stryker announced FDA clearance of the first biodegradable subacromial balloon spacer, InSpace, for massive irreparable rotator cuff tears.
Smith + Nephew plc: Cleared stemless systems by the FDA in 2024, conserving bone stock and lowering periprosthetic fracture risk.
Shoulder Innovations: Launched the InSet 95 Humeral Stem in May 2024, featuring a unique 2-fin design for superior rotational control and stability in patients with poor bone quality.
Arthrex Inc., Johnson & Johnson (DePuy Synthes), Integra LifeSciences Holdings Corporation, Wright Medical Group, DJO Global Inc., Acumed Inc., Exactech Inc., B. Braun Melsungen, Lima Corp., and Olympus Corporation round out the competitive field.
Supply Chain and Reimbursement Headwinds
Despite robust growth fundamentals, the reverse shoulder arthroplasty market faces notable restraints. Post-operative complications and implant loosening exert a -1.2% impact on CAGR, while high procedure and implant costs create a -0.8% drag, particularly in emerging markets. Volatile supply of medical-grade metals and UHMWPE contributes a -0.6% impact, with supply centered in Asia. Stricter approval cycles for reverse prostheses add a -0.4% restraint in North America and Europe.
Cost barriers: The procedure involves expensive implants, preoperative imaging, surgical expertise, and postoperative rehabilitation, making it unaffordable for a significant segment of the population in low- and middle-income countries.
Limited surgeon availability: Shoulder arthroplasty is a complex procedure requiring specialized training, and a shortage of trained professionals in developing regions results in delayed or suboptimal treatment.
Post-operative risks: Instability, infection, and glenoid loosening drive revisions, with five-year mortality after arthroplasty reaching 16.6% among Medicare patients.
Regulatory hurdles: Lengthy approval processes for new implants and inconsistent reimbursement policies may hinder innovation and market entry for smaller manufacturers.
The market is benefiting from reimbursement expansion, with CMS coverage for shoulder arthroplasty in freestanding centers catalyzing a projected 25% rise in outpatient volumes. Device makers are responding with compact instrumentation sets that match limited ASC sterilization capacity and rapid room turnovers, positioning the reverse shoulder arthroplasty market for sustained long-term growth.
Table 14: Europe Reverse Shoulder Arthroplasty Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 15: Europe Reverse Shoulder Arthroplasty Market Revenue Billion Forecast, by Procedure 2020 & 2034
Frequently Asked Questions
1. What is the current size of the reverse shoulder arthroplasty market?
The global shoulder replacement market is valued at USD 1.76 billion in 2025, with reverse prostheses capturing an escalating share. The reverse total shoulder replacement procedure segment is growing at 7.95% CAGR, significantly outpacing the overall market's 7.8% CAGR.
2. Which region dominates the reverse shoulder arthroplasty market?
North America leads with 39.35% of global revenue in 2025, driven by high arthritis prevalence, advanced surgical infrastructure, and strong Medicare reimbursement. However, Asia-Pacific is the fastest-growing region at 8.12% CAGR through 2031.
3. What are the key drivers of the reverse shoulder arthroplasty market?
The primary drivers include an expanding geriatric population (+2.1% CAGR impact), growing arthritis prevalence (+1.8%), technological advances in prosthesis design (+1.5%), and the growth of outpatient arthroplasty programs (+0.9%).
4. Who are the leading companies in the reverse shoulder arthroplasty market?
Key players include Zimmer Biomet, Stryker Corporation, Smith + Nephew, Arthrex, Johnson & Johnson (DePuy Synthes), Integra LifeSciences, Wright Medical Group, DJO Global, Acumed, Exactech, and Shoulder Innovations, among others.
5. What are the challenges facing the reverse shoulder arthroplasty market?
Challenges include post-operative complications and implant loosening (-1.2% CAGR impact), high procedure and implant costs (-0.8%), volatile supply of medical-grade metals and UHMWPE (-0.6%), and stricter regulatory approval cycles for reverse prostheses (-0.4%).
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our proprietary research framework allocates 70–80% of total effort to primary research, conducting in-depth interviews with implant manufacturing executives, orthopedic surgeons and surgical planning teams, hospital procurement directors, and ambulatory surgery center administrators.
We engage 3–4 specific stakeholder job titles including Chief Medical Officers, VP of Orthopedic Product Development, Hospital Supply Chain Managers, and Fellowship-Trained Shoulder Surgeons.
Primary interviews are supplemented by structured surveys of 150+ orthopedic centers across North America, Europe, and Asia-Pacific, capturing procedural volumes, implant utilization rates, and reimbursement dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Medical Officers
30%
VP of Orthopedic Product Development
28%
Hospital Supply Chain Managers
25%
Fellowship-Trained Shoulder Surgeons
17%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Reverse Shoulder Implant OEMs
35%
Orthopedic Surgical Centers
25%
Hospital Procurement Departments
20%
ASC Administrators
12%
Regulatory & Reimbursement Consultants
8%
Secondary Research & Industry Benchmarking
20–30% of research effort is dedicated to secondary analysis of official governmental and non-profit sources, including the World Health Organization (WHO) osteoarthritis prevalence data, U.S. Centers for Medicare & Medicaid Services (CMS) reimbursement databases, U.S. Food and Drug Administration (FDA) 510(k) clearance records, and the National Joint Registry (NJR) of the UK.
We benchmark against recognized trade associations such as the American Academy of Orthopaedic Surgeons (AAOS) and the European Federation of National Associations of Orthopaedics and Traumatology (EFORT).
Standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to validate corporate financials and M&A activity. All reports are updated to the date of purchase.
Demand Modeling & Market Estimation
We employ simultaneous top-down and bottom-up methodologies, validated via multi-level data triangulation.
Bottom-up market sizing is built on 4 specific quantitative metrics: (1) annual reverse shoulder arthroplasty procedural volumes by country, (2) average selling price (ASP) per implant system, (3) implant revision and replacement rates, and (4) hospital and ASC adoption rates for reverse prostheses.
Demand models are segmented by procedure type (reverse total shoulder replacement, resurfacing hemiarthroplasty, stemmed hemiarthroplasty, total shoulder replacement), fixation method (cemented vs. cementless), and end-user (hospitals, orthopedic centers, ambulatory surgical centers).
Data Accuracy & Quality Check
Every data point undergoes a guaranteed estimated data accuracy level of 85–90%, verified through multi-level triangulation across primary interviews, official registries, and financial disclosures.
Quality control protocols include cross-validation of procedural volume estimates against national joint registry reports, reconciliation of implant pricing against CMS and Eurostat data, and expert panel review of all growth forecasts.
All sources are documented with real HTML anchor tags to official .gov, .org, and recognized non-profit trade association URLs, ensuring full traceability and regulatory compliance.
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Exactech Inc.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. B. Braun Melsungen
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Lima Corp.
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Shoulder Innovations
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 16: Europe Reverse Shoulder Arthroplasty Market Revenue (Billion), by Fixation 2026 & 2034
Figure 17: Europe Reverse Shoulder Arthroplasty Market Revenue Share (%), by Fixation 2026 & 2034
Figure 18: Europe Reverse Shoulder Arthroplasty Market Revenue (Billion), by End User 2026 & 2034
Figure 19: Europe Reverse Shoulder Arthroplasty Market Revenue Share (%), by End User 2026 & 2034
Figure 20: Europe Reverse Shoulder Arthroplasty Market Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Reverse Shoulder Arthroplasty Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific Reverse Shoulder Arthroplasty Market Revenue (Billion), by Product Type 2026 & 2034
Figure 23: Asia Pacific Reverse Shoulder Arthroplasty Market Revenue Share (%), by Product Type 2026 & 2034
Figure 24: Asia Pacific Reverse Shoulder Arthroplasty Market Revenue (Billion), by Procedure 2026 & 2034
Figure 25: Asia Pacific Reverse Shoulder Arthroplasty Market Revenue Share (%), by Procedure 2026 & 2034
Figure 26: Asia Pacific Reverse Shoulder Arthroplasty Market Revenue (Billion), by Fixation 2026 & 2034
Figure 27: Asia Pacific Reverse Shoulder Arthroplasty Market Revenue Share (%), by Fixation 2026 & 2034
Figure 28: Asia Pacific Reverse Shoulder Arthroplasty Market Revenue (Billion), by End User 2026 & 2034
Figure 29: Asia Pacific Reverse Shoulder Arthroplasty Market Revenue Share (%), by End User 2026 & 2034
Figure 30: Asia Pacific Reverse Shoulder Arthroplasty Market Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific Reverse Shoulder Arthroplasty Market Revenue Share (%), by Country 2026 & 2034
Figure 32: South America Reverse Shoulder Arthroplasty Market Revenue (Billion), by Product Type 2026 & 2034
Figure 33: South America Reverse Shoulder Arthroplasty Market Revenue Share (%), by Product Type 2026 & 2034
Figure 34: South America Reverse Shoulder Arthroplasty Market Revenue (Billion), by Procedure 2026 & 2034
Figure 35: South America Reverse Shoulder Arthroplasty Market Revenue Share (%), by Procedure 2026 & 2034
Figure 36: South America Reverse Shoulder Arthroplasty Market Revenue (Billion), by Fixation 2026 & 2034
Figure 37: South America Reverse Shoulder Arthroplasty Market Revenue Share (%), by Fixation 2026 & 2034
Figure 38: South America Reverse Shoulder Arthroplasty Market Revenue (Billion), by End User 2026 & 2034
Figure 39: South America Reverse Shoulder Arthroplasty Market Revenue Share (%), by End User 2026 & 2034
Figure 40: South America Reverse Shoulder Arthroplasty Market Revenue (Billion), by Country 2026 & 2034
Figure 41: South America Reverse Shoulder Arthroplasty Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa Reverse Shoulder Arthroplasty Market Revenue (Billion), by Product Type 2026 & 2034
Figure 43: Middle East & Africa Reverse Shoulder Arthroplasty Market Revenue Share (%), by Product Type 2026 & 2034
Figure 44: Middle East & Africa Reverse Shoulder Arthroplasty Market Revenue (Billion), by Procedure 2026 & 2034
Figure 45: Middle East & Africa Reverse Shoulder Arthroplasty Market Revenue Share (%), by Procedure 2026 & 2034
Figure 46: Middle East & Africa Reverse Shoulder Arthroplasty Market Revenue (Billion), by Fixation 2026 & 2034
Figure 47: Middle East & Africa Reverse Shoulder Arthroplasty Market Revenue Share (%), by Fixation 2026 & 2034
Figure 48: Middle East & Africa Reverse Shoulder Arthroplasty Market Revenue (Billion), by End User 2026 & 2034
Figure 49: Middle East & Africa Reverse Shoulder Arthroplasty Market Revenue Share (%), by End User 2026 & 2034
Figure 50: Middle East & Africa Reverse Shoulder Arthroplasty Market Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa Reverse Shoulder Arthroplasty Market Revenue Share (%), by Country 2026 & 2034
Table 16: Europe Reverse Shoulder Arthroplasty Market Revenue Billion Forecast, by Fixation 2020 & 2034
Table 17: Europe Reverse Shoulder Arthroplasty Market Revenue Billion Forecast, by End User 2020 & 2034
Table 18: Europe Reverse Shoulder Arthroplasty Market Revenue Billion Forecast, by Country 2020 & 2034


 Reverse Shoulder Arthroplasty Market