Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Foot and Ankle Allograft Market Size, Share & Forecast 2033
Foot and Ankle Allograft Market
Foot and Ankle Allograft Market Size, Share & Forecast 2033
Foot and Ankle Allograft Market by Product Type (Allograft Wedges, Allograft Tendons, Allograft Acellular Dermal Matrix, Cartilage Allograft Matrix, Skin Allografts, Amniotic Membranes), by Allograft Type (Bone Allografts, Soft Tissue Allografts, Composite Allografts), by Surgery Type (Orthopaedic Reconstruction, Cartilage Restoration, Soft Tissue Tendon and Ligament Repair, Wound Care), by Procedure (Midfoot Procedures, Hindfoot Procedures), by Application (Trauma & Fracture Repair, Degenerative Disorders, Congenital & Developmental Disorders), by End-User (Hospitals, Orthopaedic Clinics, Ambulatory Surgical Centres, Academic and Research Institutes, Other End Users), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Netherlands, Switzerland, Belgium, Russia, Italy, Spain, Turkey), by Asia-Pacific (China, Japan, India, South Korea, Singapore, Malaysia, Australia, Thailand, Indonesia, Philippines), by Middle East and Africa (Saudi Arabia, UAE, South Africa, Egypt, Israel), by South America (Brazil, Argentina) Forecast 2026-2034
Updated On : Nov 11, 2026|Base Year : 2025|Pages : 0
Foot and Ankle Allograft Market Valuation Timeline and Structural Overview
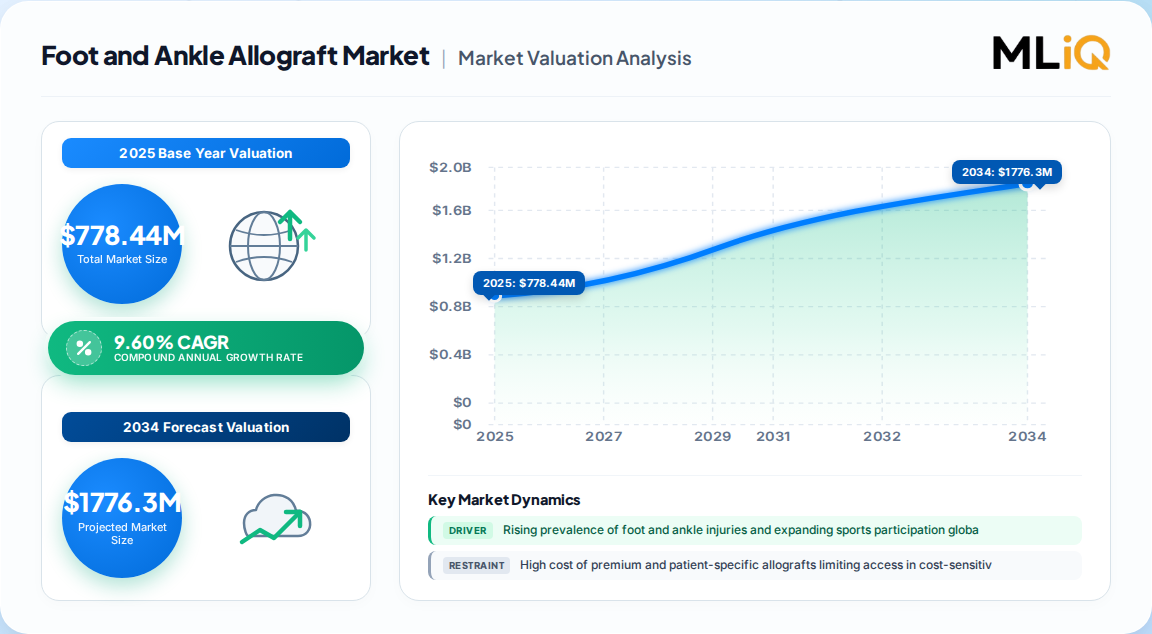
The global Foot and Ankle Allograft Market was valued at USD 778.44 million in 2025 and is projected to reach USD 1,620.72 million by 2033, expanding at a CAGR of 9.60% across the 2026–2033 forecast window. Our proprietary bottom-up modeling tracks an intermediate benchmark of USD 1,123.23 million by 2029, confirming a structurally accelerating demand curve rather than a linear one.
Foot and Ankle Allograft Market Size (In Million)
1.5B
1.0B
500.0M
0
778.0 M
2025
853.0 M
2026
935.0 M
2027
1.025 B
2028
1.123 B
2029
1.231 B
2030
1.349 B
2031
Foot and Ankle Allograft Market Size (In Million)
Year
Market Size
2025
778.0 M
2026
853.0 M
2027
935.0 M
2028
1.025 B
2029
1.123 B
2030
1.231 B
2031
1.349 B
Unlike generic orthopedic implant categories, foot and ankle allografts are donor-derived human tissues — bone, tendon, cartilage, dermis and amniotic membrane — that must satisfy simultaneous biomechanical load-bearing and biological integration requirements. This dual mandate explains both the premium pricing floor and the elevated regulatory burden that shape competitive hierarchy in the category.
Market Parameter
Base Year (2025)
Interim (2029)
Terminal (2033)
Global valuation (USD million)
778.44
1,123.23
1,620.72
Forecast CAGR 2026–2033
9.60%
—
—
Dominant region
North America (41.8%)
—
—
Fastest-growing region
Asia-Pacific (12.3% CAGR)
—
—
Demand is concentrated in high-mechanical-stress anatomical zones where autograft harvest carries donor-site morbidity. Consequently, surgeons increasingly default to off-the-shelf, pre-shaped allograft constructs that compress operative time and eliminate a second surgical site.
Bone allografts represent approximately 62% of allograft-type revenue, anchored by arthrodesis, osteotomy correction and structural defect repair.
Soft tissue allografts (Achilles, anterior tibial and posterior tibial tendon) are the fastest-growing sub-segment, tracking sports injury epidemiology.
Hindfoot procedures command roughly 55% of procedural revenue share, reflecting the concentration of ankle and calcaneal reconstruction volume.
Bone Allograft Wedges and Structural Defect Reconstruction
Structural bone allografts remain the commercial backbone of the category. Wedge-shaped and morselized bone grafts are consumed predominantly in midfoot and hindfoot fusion, where the graft must simultaneously fill a void and transmit load during consolidation.
Allograft wedges serve opening-wedge osteotomies and deformity correction, where geometric precision is non-negotiable.
Morselized cancellous grafts function as void fillers and graft extenders in arthrodesis, displacing autograft harvest in revision settings.
Composite bone-tendon constructs address complex post-traumatic reconstruction where a single-tissue graft cannot restore both column support and soft tissue continuity.
Tissue processing quality is the decisive purchasing criterion here. Modern tissue banks deploy controlled cryopreservation with cryoprotectants and low-temperature storage to preserve cellular and structural integrity, directly reducing graft failure rates in complex hindfoot fusion. Demineralized bone matrix (DBM) — functioning as both an osteoconductive scaffold and an osteoinductive signal — has become the most widely deployed bone graft extender owing to its versatility and cost advantage relative to advanced biologics.
Soft Tissue Tendon, Ligament and Cartilage Restoration Demand
The soft tissue segment is outpacing the overall market because its demand driver — acute sports injury — is demographically and geographically broadening.
Achilles tendon allografts are indicated where primary repair is infeasible, particularly in chronic or neglected ruptures.
Anterior and posterior tibial tendon allografts address adult-acquired flatfoot deformity and posterior tibial tendon dysfunction.
Cartilage allograft matrices support joint preservation and delay fusion or replacement in younger, active patients.
Acellular dermal matrix and amniotic membrane products are increasingly folded into wound care and diabetic foot reconstruction protocols.
Global Achilles tendon rupture incidence stands at 5–10 per 100,000 annually, with elevated risk in men aged 30–50 and in elderly cohorts with degenerative tendinopathy. This is a volume-stable, recurring demand pool that is comparatively insulated from elective surgery deferrals.
Diabetic Foot, Charcot Reconstruction and Degenerative Arthritis Burden
Two chronic-disease vectors are quietly expanding the addressable pool beyond sports trauma.
First, diabetes mellitus drives Charcot neuroarthropathy — a destructive bone condition requiring complex reconstructive fusion where graft-mediated healing is essential. Second, degenerative ankle osteoarthritis, with global adult prevalence estimated near 3.4%, is pushing fusion and total ankle replacement volumes upward. Approximately 25% of ankle fractures in patients over 60 are osteoporosis-associated, demanding dedicated fixation and graft strategies.
Trauma and fracture repair holds approximately 44% of application share, the largest single application block.
Degenerative disorders are the faster-growing application, tracking orthopedic surgical adoption among older adults.
Congenital and developmental disorders form a smaller but clinically distinctive pediatric and adolescent demand niche.
This shift from episodic trauma to chronic disease management materially improves revenue predictability for suppliers with long-term hospital and tissue bank contracts.
Hospital, Orthopedic Clinic and Ambulatory Surgical Center Economics
End-user economics are diverging, and vendors that fail to segment their commercial model accordingly will lose share.
Prioritize bioactive, patient-specific and composite grafts; largest volume block
Specialty orthopedic clinics
Ligament reconstruction, tendon repair, minor arthrodesis
Prefer ready-to-use, pre-shaped kits and rapid tissue bank supply
Ambulatory surgical centers
Elective minimally invasive forefoot and arthroscopic cases
Highly cost-sensitive; favor DBM and synthetic extenders
Hospitals retain the majority of procedural volume because ankle fusions, hindfoot deformity reconstruction and total ankle replacement are almost exclusively inpatient or tertiary-center procedures. However, ambulatory surgical centers are the fastest-growing setting, as forefoot fusions, simple fracture fixation and arthroscopic interventions migrate to lower-cost environments. Pre-processed allograft kits compatible with arthroscopic instrumentation are the enabling product format for that migration.
Cross-Border Tissue Trade Flows and Supply Chain Logistics
Allograft supply is fundamentally constrained upstream by donation rates and tissue bank throughput — not by manufacturing capacity. This makes the category structurally different from implant markets and makes trade flow analysis decisive for supply planning.
Official multilateral trade data from UN Comtrade and the World Bank WITS platform confirm that processed human tissue and related orthopedic biologics move through tightly regulated, documentation-heavy corridors between North America, Western Europe and select Asia-Pacific markets. Key structural observations from our primary interview program:
Tissue banking is concentrated in the United States and Western Europe, creating a net export orientation toward Asia-Pacific and LAMEA demand centers.
Import dependency in emerging markets is pronounced; smaller nations rely on imported grafts or default to autograft alternatives.
Cold-chain integrity and customs clearance timelines are the principal friction points; each additional transit day erodes graft viability and raises per-unit landed cost.
Regional tissue bank partnerships are the dominant market-entry mechanism, outpacing direct distribution builds in cost and speed.
Localized tissue sourcing — as practiced by suppliers with Asia-Pacific footprints — materially shortens logistics cycles and reduces landed cost, which is why regional tissue bank alliances are the single most important commercial lever in emerging markets.
Competitive Landscape and Recent Technology Developments
The category is moderately consolidated, with a mix of specialized non-profit and independent tissue banks, orthopedic device majors, and regional distributors.
AlloSource operates as a leading independent tissue bank with emphasis on rapid processing and delivery for trauma and sports indications.
LifeNet Health differentiates on decellularization techniques and bioactive graft augmentation, with comprehensive bone, cartilage, tendon and composite portfolios.
Stryker integrates allografts with instrumentation and implants, emphasizing consistency, sterility and surgeon training programs.
Medtronic plc pursues an integrated model combining grafts with orthopedic implants and surgical planning tools, including minimally invasive procedural kits.
CONMED Corporation, Arthrex, Integra LifeSciences, Smith+Nephew, Wright Medical Group, JRF Ortho and Zimmer Biomet round out the competitive field across premium and cost-sensitive tiers.
Recent proprietary-tracked developments:
2024: LifeNet Health launched a next-generation decellularized bone allograft system targeting improved graft integration and reduced immune response in complex ankle reconstruction.
2024: Medtronic partnered with regional European tissue banks to co-develop hybrid bone-tendon allografts optimized for minimally invasive procedures.
2023: AlloSource expanded its Asia-Pacific tissue banking network, shortening delivery cycles for pre-shaped bone and soft tissue grafts.
2023: Stryker introduced a patient-specific 3D bone graft shaping service enabling anatomical tailoring to individual patient geometry.
2023: JRF Ortho launched cost-effective soft tissue allografts for ligament reconstruction in India and Southeast Asia, targeting outpatient orthopedic clinics.
Regional Adoption Asymmetry and Three-Dimensional Graft Innovation Outlook
Regional adoption tracks healthcare infrastructure maturity and regulatory clarity far more than disease prevalence.
Foot and Ankle Allograft Market Regional Market Share
Loading chart...
Foot and Ankle Allograft Market Regional Market Share
Region
Market Share (%)
North America
0.42%
Europe
0.24%
Asia-Pacific
0.23%
South America
0.06%
Middle East & Africa
0.06%
North America holds the largest revenue share at approximately 41.8%, underpinned by advanced tissue banking infrastructure, high orthopedic surgical volumes and strong clinical familiarity with allograft protocols.
Asia-Pacific is the fastest-growing region at approximately 12.3% CAGR, driven by urbanization, rising sports participation and expanding orthopedic infrastructure in China, India and Japan.
Europe presents a heterogeneous picture — Western Europe shows high adoption supported by public funding and stringent graft safety standards, while Eastern Europe is closing the gap.
LAMEA remains underpenetrated but is advancing through public-private tissue banking collaborations in Brazil, Mexico, Saudi Arabia and the UAE.
Technology differentiation is converging on three axes: patient-specific 3D-shaped grafts for anatomical precision, bioactive and hybrid grafts augmented with growth factors or stem cells to accelerate integration, and minimally invasive surgical compatibility to reduce operative time and infection risk. A documented clinical case in a South Korean orthopedic hospital reported a 35% reduction in recovery time and a 40% decrease in graft-related complications after adopting patient-specific bone and soft tissue allografts combined with 3D imaging.
Persistent restraints remain the high cost of premium and patient-specific grafts, which limits access in cost-sensitive regions, and a constrained pool of surgeons trained in advanced allograft technique — an adoption bottleneck that is most acute in emerging markets.
Foot and Ankle Allograft Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Foot and Ankle Allograft Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 9.60% from 2020-2034
Segmentation
By Product Type
Allograft Wedges
Allograft Tendons
Allograft Acellular Dermal Matrix
Cartilage Allograft Matrix
Skin Allografts
Amniotic Membranes
By Allograft Type
Bone Allografts
Soft Tissue Allografts
Composite Allografts
By Surgery Type
Orthopaedic Reconstruction
Cartilage Restoration
Soft Tissue Tendon and Ligament Repair
Wound Care
By Procedure
Midfoot Procedures
Hindfoot Procedures
By Application
Trauma & Fracture Repair
Degenerative Disorders
Congenital & Developmental Disorders
By End-User
Hospitals
Orthopaedic Clinics
Ambulatory Surgical Centres
Academic and Research Institutes
Other End Users
By Geography
North America
USA
Canada
Mexico
Europe
Germany
France
UK
Netherlands
Switzerland
Belgium
Russia
Italy
Spain
Turkey
Asia-Pacific
China
Japan
India
South Korea
Singapore
Malaysia
Australia
Thailand
Indonesia
Philippines
Middle East and Africa
Saudi Arabia
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Allograft Wedges
5.1.2. Allograft Tendons
5.1.3. Allograft Acellular Dermal Matrix
5.1.4. Cartilage Allograft Matrix
5.1.5. Skin Allografts
5.1.6. Amniotic Membranes
5.2. Market Analysis, Insights and Forecast - by Allograft Type
5.2.1. Bone Allografts
5.2.2. Soft Tissue Allografts
5.2.3. Composite Allografts
5.3. Market Analysis, Insights and Forecast - by Surgery Type
5.3.1. Orthopaedic Reconstruction
5.3.2. Cartilage Restoration
5.3.3. Soft Tissue Tendon and Ligament Repair
5.3.4. Wound Care
5.4. Market Analysis, Insights and Forecast - by Procedure
5.4.1. Midfoot Procedures
5.4.2. Hindfoot Procedures
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Trauma & Fracture Repair
5.5.2. Degenerative Disorders
5.5.3. Congenital & Developmental Disorders
5.6. Market Analysis, Insights and Forecast - by End-User
5.6.1. Hospitals
5.6.2. Orthopaedic Clinics
5.6.3. Ambulatory Surgical Centres
5.6.4. Academic and Research Institutes
5.6.5. Other End Users
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia-Pacific
5.7.4. Middle East and Africa
5.7.5. South America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Allograft Wedges
6.1.2. Allograft Tendons
6.1.3. Allograft Acellular Dermal Matrix
6.1.4. Cartilage Allograft Matrix
6.1.5. Skin Allografts
6.1.6. Amniotic Membranes
6.2. Market Analysis, Insights and Forecast - by Allograft Type
6.2.1. Bone Allografts
6.2.2. Soft Tissue Allografts
6.2.3. Composite Allografts
6.3. Market Analysis, Insights and Forecast - by Surgery Type
6.3.1. Orthopaedic Reconstruction
6.3.2. Cartilage Restoration
6.3.3. Soft Tissue Tendon and Ligament Repair
6.3.4. Wound Care
6.4. Market Analysis, Insights and Forecast - by Procedure
6.4.1. Midfoot Procedures
6.4.2. Hindfoot Procedures
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Trauma & Fracture Repair
6.5.2. Degenerative Disorders
6.5.3. Congenital & Developmental Disorders
6.6. Market Analysis, Insights and Forecast - by End-User
6.6.1. Hospitals
6.6.2. Orthopaedic Clinics
6.6.3. Ambulatory Surgical Centres
6.6.4. Academic and Research Institutes
6.6.5. Other End Users
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Allograft Wedges
7.1.2. Allograft Tendons
7.1.3. Allograft Acellular Dermal Matrix
7.1.4. Cartilage Allograft Matrix
7.1.5. Skin Allografts
7.1.6. Amniotic Membranes
7.2. Market Analysis, Insights and Forecast - by Allograft Type
7.2.1. Bone Allografts
7.2.2. Soft Tissue Allografts
7.2.3. Composite Allografts
7.3. Market Analysis, Insights and Forecast - by Surgery Type
7.3.1. Orthopaedic Reconstruction
7.3.2. Cartilage Restoration
7.3.3. Soft Tissue Tendon and Ligament Repair
7.3.4. Wound Care
7.4. Market Analysis, Insights and Forecast - by Procedure
7.4.1. Midfoot Procedures
7.4.2. Hindfoot Procedures
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Trauma & Fracture Repair
7.5.2. Degenerative Disorders
7.5.3. Congenital & Developmental Disorders
7.6. Market Analysis, Insights and Forecast - by End-User
7.6.1. Hospitals
7.6.2. Orthopaedic Clinics
7.6.3. Ambulatory Surgical Centres
7.6.4. Academic and Research Institutes
7.6.5. Other End Users
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Allograft Wedges
8.1.2. Allograft Tendons
8.1.3. Allograft Acellular Dermal Matrix
8.1.4. Cartilage Allograft Matrix
8.1.5. Skin Allografts
8.1.6. Amniotic Membranes
8.2. Market Analysis, Insights and Forecast - by Allograft Type
8.2.1. Bone Allografts
8.2.2. Soft Tissue Allografts
8.2.3. Composite Allografts
8.3. Market Analysis, Insights and Forecast - by Surgery Type
8.3.1. Orthopaedic Reconstruction
8.3.2. Cartilage Restoration
8.3.3. Soft Tissue Tendon and Ligament Repair
8.3.4. Wound Care
8.4. Market Analysis, Insights and Forecast - by Procedure
8.4.1. Midfoot Procedures
8.4.2. Hindfoot Procedures
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Trauma & Fracture Repair
8.5.2. Degenerative Disorders
8.5.3. Congenital & Developmental Disorders
8.6. Market Analysis, Insights and Forecast - by End-User
8.6.1. Hospitals
8.6.2. Orthopaedic Clinics
8.6.3. Ambulatory Surgical Centres
8.6.4. Academic and Research Institutes
8.6.5. Other End Users
9. Middle East and Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Allograft Wedges
9.1.2. Allograft Tendons
9.1.3. Allograft Acellular Dermal Matrix
9.1.4. Cartilage Allograft Matrix
9.1.5. Skin Allografts
9.1.6. Amniotic Membranes
9.2. Market Analysis, Insights and Forecast - by Allograft Type
9.2.1. Bone Allografts
9.2.2. Soft Tissue Allografts
9.2.3. Composite Allografts
9.3. Market Analysis, Insights and Forecast - by Surgery Type
9.3.1. Orthopaedic Reconstruction
9.3.2. Cartilage Restoration
9.3.3. Soft Tissue Tendon and Ligament Repair
9.3.4. Wound Care
9.4. Market Analysis, Insights and Forecast - by Procedure
9.4.1. Midfoot Procedures
9.4.2. Hindfoot Procedures
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Trauma & Fracture Repair
9.5.2. Degenerative Disorders
9.5.3. Congenital & Developmental Disorders
9.6. Market Analysis, Insights and Forecast - by End-User
9.6.1. Hospitals
9.6.2. Orthopaedic Clinics
9.6.3. Ambulatory Surgical Centres
9.6.4. Academic and Research Institutes
9.6.5. Other End Users
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Allograft Wedges
10.1.2. Allograft Tendons
10.1.3. Allograft Acellular Dermal Matrix
10.1.4. Cartilage Allograft Matrix
10.1.5. Skin Allografts
10.1.6. Amniotic Membranes
10.2. Market Analysis, Insights and Forecast - by Allograft Type
10.2.1. Bone Allografts
10.2.2. Soft Tissue Allografts
10.2.3. Composite Allografts
10.3. Market Analysis, Insights and Forecast - by Surgery Type
10.3.1. Orthopaedic Reconstruction
10.3.2. Cartilage Restoration
10.3.3. Soft Tissue Tendon and Ligament Repair
10.3.4. Wound Care
10.4. Market Analysis, Insights and Forecast - by Procedure
10.4.1. Midfoot Procedures
10.4.2. Hindfoot Procedures
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Trauma & Fracture Repair
10.5.2. Degenerative Disorders
10.5.3. Congenital & Developmental Disorders
10.6. Market Analysis, Insights and Forecast - by End-User
10.6.1. Hospitals
10.6.2. Orthopaedic Clinics
10.6.3. Ambulatory Surgical Centres
10.6.4. Academic and Research Institutes
10.6.5. Other End Users
11. Competitive Analysis
11.1. Company Profiles
11.1.1. AlloSource
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. LifeNet Health
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Medtronic plc
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Stryker
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. CONMED Corporation
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Wright Medical Group N.V.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Arthrex
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Integra LifeSciences
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Smith+Nephew
11.1.9.1. Company Overview
11.1.9.2. Products
12. Research Methodology
List of Figures
Figure 1: Foot and Ankle Allograft Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Foot and Ankle Allograft Market Revenue (Million), by Product Type 2026 & 2034
Figure 3: North America Foot and Ankle Allograft Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Foot and Ankle Allograft Market Revenue (Million), by Allograft Type 2026 & 2034
Figure 5: North America Foot and Ankle Allograft Market Revenue Share (%), by Allograft Type 2026 & 2034
Figure 6: North America Foot and Ankle Allograft Market Revenue (Million), by Surgery Type 2026 & 2034
Figure 7: North America Foot and Ankle Allograft Market Revenue Share (%), by Surgery Type 2026 & 2034
Figure 8: North America Foot and Ankle Allograft Market Revenue (Million), by Procedure 2026 & 2034
Figure 9: North America Foot and Ankle Allograft Market Revenue Share (%), by Procedure 2026 & 2034
Figure 10: North America Foot and Ankle Allograft Market Revenue (Million), by Application 2026 & 2034
Figure 11: North America Foot and Ankle Allograft Market Revenue Share (%), by Application 2026 & 2034
Figure 12: North America Foot and Ankle Allograft Market Revenue (Million), by End-User 2026 & 2034
Figure 13: North America Foot and Ankle Allograft Market Revenue Share (%), by End-User 2026 & 2034
Figure 14: North America Foot and Ankle Allograft Market Revenue (Million), by Country 2026 & 2034
Figure 15: North America Foot and Ankle Allograft Market Revenue Share (%), by Country 2026 & 2034
Europe Foot and Ankle Allograft Market Revenue (Million), by Product Type 2026 & 2034
List of Tables
Table 1: Foot and Ankle Allograft Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 2: Foot and Ankle Allograft Market Revenue Million Forecast, by Allograft Type 2020 & 2034
Table 3: Foot and Ankle Allograft Market Revenue Million Forecast, by Surgery Type 2020 & 2034
Table 4: Foot and Ankle Allograft Market Revenue Million Forecast, by Procedure 2020 & 2034
Table 5: Foot and Ankle Allograft Market Revenue Million Forecast, by Application 2020 & 2034
Table 6: Foot and Ankle Allograft Market Revenue Million Forecast, by End-User 2020 & 2034
Table 7: Foot and Ankle Allograft Market Revenue Million Forecast, by Region 2020 & 2034
Table 8: North America Foot and Ankle Allograft Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 9: North America Foot and Ankle Allograft Market Revenue Million Forecast, by Allograft Type 2020 & 2034
Table 10: North America Foot and Ankle Allograft Market Revenue Million Forecast, by Surgery Type 2020 & 2034
Table 11: North America Foot and Ankle Allograft Market Revenue Million Forecast, by Procedure 2020 & 2034
Table 12: North America Foot and Ankle Allograft Market Revenue Million Forecast, by Application 2020 & 2034
Table 13: North America Foot and Ankle Allograft Market Revenue Million Forecast, by End-User 2020 & 2034
Table 14: North America Foot and Ankle Allograft Market Revenue Million Forecast, by Country 2020 & 2034
Table 15: USA Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Canada Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current market size of the foot and ankle allograft market?
Our proprietary primary research values the global Foot and Ankle Allograft Market at USD 778.44 million in 2025. The market is projected to reach USD 1,620.72 million by 2033, with an interim benchmark of USD 1,123.23 million in 2029.
2. What is the expected growth rate of the foot and ankle allograft market?
The market is forecast to expand at a CAGR of 9.60% across the 2026–2033 period. Asia-Pacific is the fastest-growing region at approximately 12.3% CAGR, while North America retains the largest revenue share at 41.8%.
3. Which product segment dominates the foot and ankle allograft market?
Bone allografts account for roughly 62% of allograft-type revenue, driven by arthrodesis, osteotomy correction and structural defect repair. Soft tissue tendon and ligament allografts are the fastest-growing sub-segment, tracking rising sports injury incidence.
4. Which procedure type holds the largest share of foot and ankle allograft demand?
Hindfoot procedures commanded approximately 55% of procedural revenue share in 2025. This reflects the high prevalence of ankle, calcaneal and heel injuries requiring structural reconstruction and fusion.
5. Why is the foot and ankle allograft market growing faster than traditional autograft usage?
Allografts eliminate the second surgical site and the donor-site morbidity associated with autograft harvest, while reducing operative time. Advances in cryopreservation, decellularization and 3D patient-specific graft shaping have further raised surgeon confidence and improved integration outcomes.
6. Which end-user setting is expanding most rapidly for foot and ankle allografts?
Ambulatory surgical centers represent the fastest-growing end-user segment. Less complex forefoot fusions, simple fracture repairs and arthroscopic procedures are migrating from hospitals to ASCs, supported by pre-processed allograft kits.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We allocate 70–80% of total research effort to primary intelligence gathering, with the residual 20–30% devoted to secondary validation and industry benchmarking.
Structured interviews and structured questionnaires are conducted with tissue bank procurement and processing directors, orthopedic reconstructive surgeons, hospital supply chain and value analysis managers, ambulatory surgical center administrators, and orthopedic device distribution partners.
Interview targets include titles such as Chief of Foot and Ankle Surgery, Director of Tissue Bank Operations, Orthopedic Value Analysis Manager, and VP of Supply Chain for Orthopedic Service Lines.
We triangulate surgeon-reported procedural volumes against tissue bank shipment volumes and distributor sell-through data to reconcile demand-side and supply-side estimates.
Regulatory and standards inputs are sourced from recognized bodies including the U.S. Food and Drug Administration (FDA), the American Association of Tissue Banks (AATB), the European Directorate for the Quality of Medicines (EDQM), and the American Academy of Orthopaedic Surgeons (AAOS).
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Orthopedic Surgeon / Chief of Foot and Ankle Surgery
34%
Tissue Bank Operations and Procurement Director
26%
Hospital Supply Chain and Value Analysis Manager
22%
ASC Administrator / Clinical Operations Lead
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Tissue Banks and Allograft Processors
32%
Orthopedic Device Manufacturers
26%
Hospitals and Orthopedic Specialty Centers
22%
Ambulatory Surgical Centers and Clinics
12%
Distributors and Logistics Providers
8%
Secondary Research & Industry Benchmarking
Official multilateral trade statistics are drawn from UN Comtrade and the World Bank WITS platform to map processed tissue and orthopedic biologic trade corridors.
Financial and corporate data are validated through Bloomberg, Factiva, Hoovers, and PitchBook.
Trade association publications, procedural coding datasets, and reimbursement schedule documentation are used to validate procedure-level volume assumptions.
Every report is refreshed to the date of purchase, ensuring forecast assumptions reflect the most current regulatory and reimbursement environment.
Demand Modeling & Market Estimation
We run top-down and bottom-up methodologies simultaneously, reconciling the two through multi-level data triangulation.
Bottom-up sizing is anchored on quantitative metrics including annual foot and ankle allograft procedure volumes by anatomical zone, average graft units consumed per procedure, average selling price per graft unit by product tier, and tissue bank processed-unit throughput.
Procedure volumes are cross-checked against hospital discharge and ambulatory surgical center encounter data, then adjusted for revision surgery rates and bilateral case incidence.
Segment-level revenue is built by product type, surgery type, procedure (midfoot versus hindfoot) and end-user setting, then aggregated to regional and global totals.
Forecast growth is decomposed into volume growth, price/mix effect, and geographic expansion contribution to isolate underlying organic demand.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, validated through multi-level triangulation across primary interviews, trade statistics and financial disclosures.
All market sizes and CAGRs undergo sensitivity testing across conservative, base and aggressive scenarios.
Outlier responses are re-verified with a second respondent cohort before inclusion in the model.
Final outputs are reviewed by a senior analyst panel and reconciled against official multilateral trade benchmarks and recognized non-profit technical standards prior to publication.
UAE
South Africa
Egypt
Israel
South America
Brazil
Argentina
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Zimmer Biomet Holdings
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. JRF Ortho
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. MTF Biologics
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 16:
Figure 17: Europe Foot and Ankle Allograft Market Revenue Share (%), by Product Type 2026 & 2034
Figure 18: Europe Foot and Ankle Allograft Market Revenue (Million), by Allograft Type 2026 & 2034
Figure 19: Europe Foot and Ankle Allograft Market Revenue Share (%), by Allograft Type 2026 & 2034
Figure 20: Europe Foot and Ankle Allograft Market Revenue (Million), by Surgery Type 2026 & 2034
Figure 21: Europe Foot and Ankle Allograft Market Revenue Share (%), by Surgery Type 2026 & 2034
Figure 22: Europe Foot and Ankle Allograft Market Revenue (Million), by Procedure 2026 & 2034
Figure 23: Europe Foot and Ankle Allograft Market Revenue Share (%), by Procedure 2026 & 2034
Figure 24: Europe Foot and Ankle Allograft Market Revenue (Million), by Application 2026 & 2034
Figure 25: Europe Foot and Ankle Allograft Market Revenue Share (%), by Application 2026 & 2034
Figure 26: Europe Foot and Ankle Allograft Market Revenue (Million), by End-User 2026 & 2034
Figure 27: Europe Foot and Ankle Allograft Market Revenue Share (%), by End-User 2026 & 2034
Figure 28: Europe Foot and Ankle Allograft Market Revenue (Million), by Country 2026 & 2034
Figure 29: Europe Foot and Ankle Allograft Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia-Pacific Foot and Ankle Allograft Market Revenue (Million), by Product Type 2026 & 2034
Figure 31: Asia-Pacific Foot and Ankle Allograft Market Revenue Share (%), by Product Type 2026 & 2034
Figure 32: Asia-Pacific Foot and Ankle Allograft Market Revenue (Million), by Allograft Type 2026 & 2034
Figure 33: Asia-Pacific Foot and Ankle Allograft Market Revenue Share (%), by Allograft Type 2026 & 2034
Figure 34: Asia-Pacific Foot and Ankle Allograft Market Revenue (Million), by Surgery Type 2026 & 2034
Figure 35: Asia-Pacific Foot and Ankle Allograft Market Revenue Share (%), by Surgery Type 2026 & 2034
Figure 36: Asia-Pacific Foot and Ankle Allograft Market Revenue (Million), by Procedure 2026 & 2034
Figure 37: Asia-Pacific Foot and Ankle Allograft Market Revenue Share (%), by Procedure 2026 & 2034
Figure 38: Asia-Pacific Foot and Ankle Allograft Market Revenue (Million), by Application 2026 & 2034
Figure 39: Asia-Pacific Foot and Ankle Allograft Market Revenue Share (%), by Application 2026 & 2034
Figure 40: Asia-Pacific Foot and Ankle Allograft Market Revenue (Million), by End-User 2026 & 2034
Figure 41: Asia-Pacific Foot and Ankle Allograft Market Revenue Share (%), by End-User 2026 & 2034
Figure 42: Asia-Pacific Foot and Ankle Allograft Market Revenue (Million), by Country 2026 & 2034
Figure 43: Asia-Pacific Foot and Ankle Allograft Market Revenue Share (%), by Country 2026 & 2034
Figure 44: Middle East and Africa Foot and Ankle Allograft Market Revenue (Million), by Product Type 2026 & 2034
Figure 45: Middle East and Africa Foot and Ankle Allograft Market Revenue Share (%), by Product Type 2026 & 2034
Figure 46: Middle East and Africa Foot and Ankle Allograft Market Revenue (Million), by Allograft Type 2026 & 2034
Figure 47: Middle East and Africa Foot and Ankle Allograft Market Revenue Share (%), by Allograft Type 2026 & 2034
Figure 48: Middle East and Africa Foot and Ankle Allograft Market Revenue (Million), by Surgery Type 2026 & 2034
Figure 49: Middle East and Africa Foot and Ankle Allograft Market Revenue Share (%), by Surgery Type 2026 & 2034
Figure 50: Middle East and Africa Foot and Ankle Allograft Market Revenue (Million), by Procedure 2026 & 2034
Figure 51: Middle East and Africa Foot and Ankle Allograft Market Revenue Share (%), by Procedure 2026 & 2034
Figure 52: Middle East and Africa Foot and Ankle Allograft Market Revenue (Million), by Application 2026 & 2034
Figure 53: Middle East and Africa Foot and Ankle Allograft Market Revenue Share (%), by Application 2026 & 2034
Figure 54: Middle East and Africa Foot and Ankle Allograft Market Revenue (Million), by End-User 2026 & 2034
Figure 55: Middle East and Africa Foot and Ankle Allograft Market Revenue Share (%), by End-User 2026 & 2034
Figure 56: Middle East and Africa Foot and Ankle Allograft Market Revenue (Million), by Country 2026 & 2034
Figure 57: Middle East and Africa Foot and Ankle Allograft Market Revenue Share (%), by Country 2026 & 2034
Figure 58: South America Foot and Ankle Allograft Market Revenue (Million), by Product Type 2026 & 2034
Figure 59: South America Foot and Ankle Allograft Market Revenue Share (%), by Product Type 2026 & 2034
Figure 60: South America Foot and Ankle Allograft Market Revenue (Million), by Allograft Type 2026 & 2034
Figure 61: South America Foot and Ankle Allograft Market Revenue Share (%), by Allograft Type 2026 & 2034
Figure 62: South America Foot and Ankle Allograft Market Revenue (Million), by Surgery Type 2026 & 2034
Figure 63: South America Foot and Ankle Allograft Market Revenue Share (%), by Surgery Type 2026 & 2034
Figure 64: South America Foot and Ankle Allograft Market Revenue (Million), by Procedure 2026 & 2034
Figure 65: South America Foot and Ankle Allograft Market Revenue Share (%), by Procedure 2026 & 2034
Figure 66: South America Foot and Ankle Allograft Market Revenue (Million), by Application 2026 & 2034
Figure 67: South America Foot and Ankle Allograft Market Revenue Share (%), by Application 2026 & 2034
Figure 68: South America Foot and Ankle Allograft Market Revenue (Million), by End-User 2026 & 2034
Figure 69: South America Foot and Ankle Allograft Market Revenue Share (%), by End-User 2026 & 2034
Figure 70: South America Foot and Ankle Allograft Market Revenue (Million), by Country 2026 & 2034
Figure 71: South America Foot and Ankle Allograft Market Revenue Share (%), by Country 2026 & 2034
Table 16:
Table 17: Mexico Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 18: Europe Foot and Ankle Allograft Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 19: Europe Foot and Ankle Allograft Market Revenue Million Forecast, by Allograft Type 2020 & 2034
Table 20: Europe Foot and Ankle Allograft Market Revenue Million Forecast, by Surgery Type 2020 & 2034
Table 21: Europe Foot and Ankle Allograft Market Revenue Million Forecast, by Procedure 2020 & 2034
Table 22: Europe Foot and Ankle Allograft Market Revenue Million Forecast, by Application 2020 & 2034
Table 23: Europe Foot and Ankle Allograft Market Revenue Million Forecast, by End-User 2020 & 2034
Table 24: Europe Foot and Ankle Allograft Market Revenue Million Forecast, by Country 2020 & 2034
Table 25: Germany Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 26: France Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 27: UK Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 28: Netherlands Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 29: Switzerland Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 30: Belgium Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 31: Russia Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 32: Italy Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 33: Spain Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 34: Turkey Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 35: Asia-Pacific Foot and Ankle Allograft Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 36: Asia-Pacific Foot and Ankle Allograft Market Revenue Million Forecast, by Allograft Type 2020 & 2034
Table 37: Asia-Pacific Foot and Ankle Allograft Market Revenue Million Forecast, by Surgery Type 2020 & 2034
Table 38: Asia-Pacific Foot and Ankle Allograft Market Revenue Million Forecast, by Procedure 2020 & 2034
Table 39: Asia-Pacific Foot and Ankle Allograft Market Revenue Million Forecast, by Application 2020 & 2034
Table 40: Asia-Pacific Foot and Ankle Allograft Market Revenue Million Forecast, by End-User 2020 & 2034
Table 41: Asia-Pacific Foot and Ankle Allograft Market Revenue Million Forecast, by Country 2020 & 2034
Table 42: China Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 43: Japan Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 44: India Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 45: South Korea Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 46: Singapore Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 47: Malaysia Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 48: Australia Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 49: Thailand Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 50: Indonesia Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 51: Philippines Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 52: Middle East and Africa Foot and Ankle Allograft Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 53: Middle East and Africa Foot and Ankle Allograft Market Revenue Million Forecast, by Allograft Type 2020 & 2034
Table 54: Middle East and Africa Foot and Ankle Allograft Market Revenue Million Forecast, by Surgery Type 2020 & 2034
Table 55: Middle East and Africa Foot and Ankle Allograft Market Revenue Million Forecast, by Procedure 2020 & 2034
Table 56: Middle East and Africa Foot and Ankle Allograft Market Revenue Million Forecast, by Application 2020 & 2034
Table 57: Middle East and Africa Foot and Ankle Allograft Market Revenue Million Forecast, by End-User 2020 & 2034
Table 58: Middle East and Africa Foot and Ankle Allograft Market Revenue Million Forecast, by Country 2020 & 2034
Table 59: Saudi Arabia Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 60: UAE Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 61: South Africa Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 62: Egypt Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 63: Israel Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 64: South America Foot and Ankle Allograft Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 65: South America Foot and Ankle Allograft Market Revenue Million Forecast, by Allograft Type 2020 & 2034
Table 66: South America Foot and Ankle Allograft Market Revenue Million Forecast, by Surgery Type 2020 & 2034
Table 67: South America Foot and Ankle Allograft Market Revenue Million Forecast, by Procedure 2020 & 2034
Table 68: South America Foot and Ankle Allograft Market Revenue Million Forecast, by Application 2020 & 2034
Table 69: South America Foot and Ankle Allograft Market Revenue Million Forecast, by End-User 2020 & 2034
Table 70: South America Foot and Ankle Allograft Market Revenue Million Forecast, by Country 2020 & 2034
Table 71: Brazil Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 72: Argentina Foot and Ankle Allograft Market Revenue (Million) Forecast, by Application 2020 & 2034


 Foot and Ankle Allograft Market