Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Companion Animal Pharmaceuticals Market by Product Type (Therapeutic Drugs(Anti-infectives, Cardiovascular Drugs, Hormonal and Metabolic Drugs, Dermatological Drugs, Pain Relief and Anti-inflammatory Drugs, Gastrointestinal Drugs, Respiratory Drugs, CNS Drugs), Vaccines(Bacterial Vaccines, Viral Vaccines, Combination Vaccines), Other Product Types(Nutraceuticals and Supplements, Specialty Pharmaceuticals)), by Animal Type (Dogs, Cats, Equines, Other Animal Types), by Route of Administration (Oral, Injectable, Topical, Inhalation, Other), by Distribution Channel (Veterinary Hospitals and Clinics, Retail Pharmacies, Online Pharmacies/E-commerce, Veterinary Distributors, Direct Sales), by End User (Veterinarians, Pet Owners, Animal Care Centers, Pet Specialty Stores), by Indication (Infectious Diseases, Dermatologic Diseases, Pain, Orthopedic Diseases, Behavioral Diseases, Neurologic Disorders, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia-Pacific (China, Japan, India, Australia, South Korea), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, UAE, Saudi Arabia) Forecast 2026-2034
Updated On : Nov 11, 2026|Base Year : 2025|Pages : 0
Companion Animal Pharmaceuticals Market Valuation and 2030 Outlook
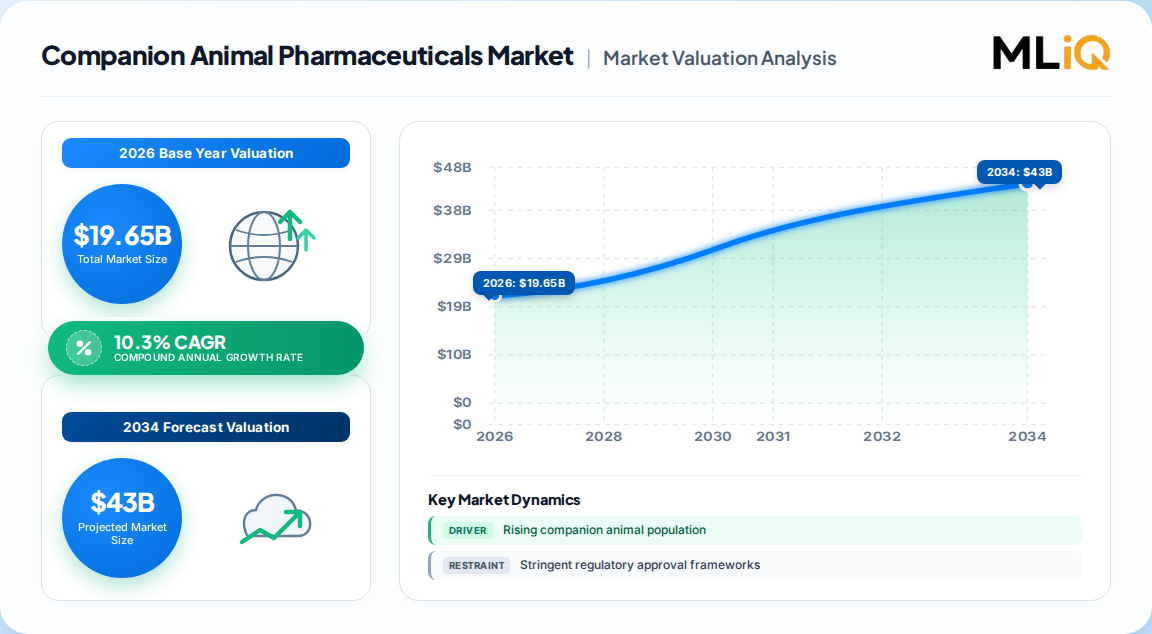
The global Companion Animal Pharmaceuticals Market reached USD 19.65 billion in 2026 and is projected to expand to USD 29.14 billion by 2030, registering a 10.3% CAGR. This trajectory is underpinned by sustained increases in pet ownership, humanization of companion animals, and the rapid introduction of advanced therapeutics such as monoclonal antibodies and long-acting injectables. Between 2022 and 2025, the market grew from USD 21.1 billion to USD 26.8 billion in the broader companion animal drugs category, reflecting resilient demand even amid macroeconomic pressures. In-house primary research indicates that the top five players—Zoetis, Boehringer Ingelheim, Elanco, Merck Animal Health, and Virbac—collectively held 68% of global revenue in 2025, signaling a moderately concentrated competitive landscape.
Companion Animal Pharmaceuticals Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
17.82 B
2025
19.65 B
2026
21.67 B
2027
23.91 B
2028
26.37 B
2029
29.09 B
2030
32.08 B
2031
Companion Animal Pharmaceuticals Market Size (In Billion)
Largest region: North America (41.85% share in 2025)
Fastest-growing region: Asia-Pacific (7.11% CAGR to 2031, led by China)
Zoonotic Disease Burden and Pet Humanization Drivers
The growing prevalence of zoonotic diseases is a primary demand driver. Up to 75% of newly emerging infectious diseases and 60% of recognized infectious diseases have zoonotic origins, causing 2.7 million human fatalities and 2.5 billion disease episodes annually. Companion animal pharmaceuticals help control these risks by reducing infections in pets, thereby lowering transmission to humans. In parallel, pet humanization has elevated spending: 68% of U.S. households own a pet, and average annual pet spending rose from USD 460 in 2013 to USD 770 in 2021. The global companion animal population reached approximately 967 million (522 million dogs and 445 million cats), creating a vast patient pool for parasiticides, vaccines, and chronic-care therapies.
Rising pet insurance adoption: North American premiums more than doubled to USD 4.5 billion in 2024, boosting owners' capacity for advanced diagnostics and specialty drugs.
Human–animal bond: Projected global pet economy value of USD 279 billion by 2030 sustains demand for premium therapeutics.
Feline health gap: Only 40% of cats receive annual veterinary visits versus 82% of dogs, representing untapped potential for species-specific innovations.
Therapeutic Drugs and Parasiticides Segment Leadership
By product type, parasiticides captured 29.08% of the companion animal pharmaceuticals market in 2025, while anti-inflammatory analgesics are advancing at a 7.58% CAGR through 2031. The drugs segment (including anti-infectives, cardiovascular drugs, dermatologicals, and pain relief) accounted for the highest revenue share at USD 17.1 billion in 2025 within the broader companion animal drugs market. Vaccines and medicated feed additives follow, with innovation focused on combination vaccines and oral formulations that improve compliance.
Product Segment
2025 Share / Metric
Growth Outlook
Parasiticides
29.08% of pharmaceuticals market
Steady, driven by year-round prevention
Anti-inflammatory analgesics
—
7.58% CAGR to 2031
Dermatologicals
31.02% of indication share
Largest indication segment
Neurologic disorders
—
8.12% CAGR to 2031 (fastest)
Vaccines
Second-largest product type
Supported by preventive care trends
Canine Dominance and Feline Growth Dynamics
Dogs remain the primary revenue driver, accounting for 62.02% of 2025 revenue, while cats represent the fastest-growing cohort at a 6.72% CAGR through 2031. This feline acceleration is supported by launches such as Bonqat for anxiety and Felycin-CA1 for hypertrophic cardiomyopathy. The canine segment benefits from a high prevalence of chronic conditions: approximately 14 million adult dogs in the U.S. suffer from osteoarthritis, and 90% of cats over 10 years experience osteoarthritis in at least one joint. These epidemiological factors underpin sustained demand for pain management and anti-inflammatory therapeutics.
Osteoarthritis prevalence: 14 million U.S. dogs; 90% of senior cats
Diabetes incidence: Over half a million cats and dogs diagnosed annually
Species-specific innovation: Monoclonal antibodies (Librela, Solensia) treated more than 1 million dogs within two years of launch
Veterinary Clinic Pharmacies and E-Commerce Channels
Distribution is anchored in veterinary hospitals and clinics, which held 53.98% of 2025 revenue. However, e-commerce is the fastest-growing channel, projected at an 8.95% CAGR to 2031, driven by online pharmacies, telehealth-enabled prescribing, and price transparency platforms. Corporate consolidators now control roughly 30% of clinics, leveraging scale to negotiate pharmaceutical purchasing and drive protocol adoption. This shift is creating omnichannel ecosystems that reinforce prescription adherence and open new access points for pet owners.
Clinic/hospital pharmacy: 53.98% share (2025)
E-commerce: 8.95% CAGR (2026–2031)
Retail pharmacies and veterinary distributors: Stable but losing relative share
North American Leadership and Asia-Pacific Momentum
North America accounted for 41.85% of 2025 sales, supported by high pet insurance penetration and advanced veterinary infrastructure. The U.S. remains the largest single market, with 68% household pet ownership and rising expenditure on specialty drugs. Asia-Pacific is the fastest-growing region at a 7.11% CAGR, led by China's rapidly maturing pet economy and increasing disposable incomes. Europe follows with a strong emphasis on regulatory harmonization and antimicrobial stewardship.
Region
2025 Share
Growth Outlook
North America
41.85%
Mature, innovation-driven
Europe
~24.5%
Moderate, regulatory focus
Asia-Pacific
~22.2%
7.11% CAGR, China-led
South America
~6.0%
Emerging, improving access
Middle East & Africa
~5.5%
Nascent, limited infrastructure
Monoclonal Antibodies and Conditional Approvals Reshaping Pipelines
Innovation is accelerating through regulatory pathways that enable first-in-class therapies to reach clinics sooner. In March 2025, the U.S. FDA granted conditional approval for Felycin-CA1 (sirolimus delayed-release tablets), the first approved treatment for feline subclinical hypertrophic cardiomyopathy. Monoclonal antibodies such as Librela and Solensia deliver durable pain relief, while long-acting otic formulations reduce dosing burdens. AI and machine learning are revolutionizing veterinary drug discovery by accelerating targeted treatment development and enabling novel delivery methods like transdermal patches and oral vaccines. Strategic activity remains robust: in February 2025, Felix Pharmaceuticals announced plans to raise USD 200–250 million by selling a controlling stake in its pet drug subsidiary, Felix Generics, to expand its portfolio.
Conditional approvals: Felycin-CA1 (HCM in cats), first-in-class
Monoclonal antibodies: Librela, Solensia — durable pain relief, high compliance
AI in drug discovery: Accelerating targeted treatments and novel delivery
M&A activity: Moderate to high, with investment firms and emerging players
Regulatory Complexity and Antimicrobial Stewardship Constraints
Stringent regulatory approval frameworks impose a -0.8% impact on CAGR, particularly for first-in-class modalities requiring new safety endpoints. Antimicrobial stewardship pressures (-0.6%) are reshaping prescribing practices in developed markets, while high development and compliance costs (-0.7%) and price transparency platforms (-0.5%) squeeze brand premiums. Workforce shortages in veterinary practices remain a constraint, signaling demand for digital triage and targeted medical solutions that reduce in-clinic time. Despite these headwinds, the overall growth trajectory remains robust, with innovation and geographic expansion offsetting regulatory friction.
Table 7: Companion Animal Pharmaceuticals Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Companion Animal Pharmaceuticals Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 9: North America Companion Animal Pharmaceuticals Market Revenue Billion Forecast, by Animal Type 2020 & 2034
Table 10: North America Companion Animal Pharmaceuticals Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Table 11: North America Companion Animal Pharmaceuticals Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: North America Companion Animal Pharmaceuticals Market Revenue Billion Forecast, by End User 2020 & 2034
Table 13: North America Companion Animal Pharmaceuticals Market Revenue Billion Forecast, by Indication 2020 & 2034
Table 14: North America Companion Animal Pharmaceuticals Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Companion Animal Pharmaceuticals Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the Companion Animal Pharmaceuticals market size in 2026?
The market reached USD 19.65 billion in 2026 and is projected to grow to USD 29.14 billion by 2030 at a 10.3% CAGR.
2. Which region dominates the Companion Animal Pharmaceuticals market?
North America held the largest share at 41.85% in 2025, while Asia-Pacific is the fastest-growing region at a 7.11% CAGR.
3. What are the key drivers of the Companion Animal Pharmaceuticals market?
Rising pet ownership, increasing prevalence of zoonotic and chronic diseases, pet humanization, and advances in drug innovations such as monoclonal antibodies drive market growth.
4. Which animal type dominates revenue in this market?
Dogs accounted for 62.02% of 2025 revenue, while cats represent the fastest-growing cohort at a 6.72% CAGR through 2031.
5. Who are the leading companies in the Companion Animal Pharmaceuticals market?
Zoetis, Boehringer Ingelheim, Elanco Animal Health, Merck Animal Health, and Virbac collectively held 68% of the market in 2025, with Zoetis leading at over 28% share.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% of research through primary interviews with executives across the value chain: veterinary pharmaceutical manufacturers, contract research organizations (CROs), veterinary clinic chains, and pet insurance providers.
Interviewed stakeholders including Chief Veterinary Officers, Director of Pharmaceutical R&D, Procurement Heads for Veterinary Distributors, and Regulatory Affairs Managers.
Engaged with industry associations such as the World Veterinary Association (WVA), the Federation of European Companion Animal Veterinary Associations (FECAVA), and the American Veterinary Medical Association (AVMA) for validation.
Utilized quantitative metrics: number of prescriptions per clinic, average revenue per companion animal, dosage volumes by species, and pricing per therapeutic class.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Veterinary Officers
30%
Director of Pharmaceutical R&D
25%
Procurement Heads for Veterinary Distributors
25%
Regulatory Affairs Managers
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Veterinary Pharmaceutical Manufacturers
35%
Contract Research Organizations (CROs)
20%
Veterinary Clinic Chains & Hospitals
25%
Pet Insurance Providers
10%
Distributors & Online Pharmacies
10%
Secondary Research & Industry Benchmarking
20–30% of research derived from secondary sources including official government databases (U.S. FDA, EMA), non-profit trade associations (Animal Health Institute, NOAH), and recognized multilateral organizations (OECD, World Bank).
Financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook used for company-level data and deal tracking.
Cross-referenced with peer-reviewed journals and clinical trial registries (ClinicalTrials.gov) for pipeline intelligence.
All sources are .gov, .org, or official trade bodies; no commercial market research reports were used.
Demand Modeling & Market Estimation
Employed both top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up calculation: (Number of companion animals by species × treatment prevalence) × average annual pharmaceutical spend per treated animal × compliance rate, cross-checked with clinic-level prescription volumes.
Top-down approach: Global veterinary pharmaceutical revenue aggregated from company filings and adjusted for companion animal share.
Segment-level splits validated through primary interviews and historical trend analysis (2022–2025).
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90% through rigorous validation.
Multi-level triangulation: primary interview data cross-verified with secondary trade statistics and company financials.
Every report is updated to the date of purchase to ensure the latest market developments are incorporated.
Quality assurance conducted by senior analysts with domain expertise in veterinary health.
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 16: Europe Companion Animal Pharmaceuticals Market Revenue (Billion), by Product Type 2026 & 2034
Figure 17: Europe Companion Animal Pharmaceuticals Market Revenue Share (%), by Product Type 2026 & 2034
Figure 18: Europe Companion Animal Pharmaceuticals Market Revenue (Billion), by Animal Type 2026 & 2034
Figure 19: Europe Companion Animal Pharmaceuticals Market Revenue Share (%), by Animal Type 2026 & 2034
Figure 20: Europe Companion Animal Pharmaceuticals Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 21: Europe Companion Animal Pharmaceuticals Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 22: Europe Companion Animal Pharmaceuticals Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 23: Europe Companion Animal Pharmaceuticals Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 24: Europe Companion Animal Pharmaceuticals Market Revenue (Billion), by End User 2026 & 2034
Figure 25: Europe Companion Animal Pharmaceuticals Market Revenue Share (%), by End User 2026 & 2034
Figure 26: Europe Companion Animal Pharmaceuticals Market Revenue (Billion), by Indication 2026 & 2034
Figure 27: Europe Companion Animal Pharmaceuticals Market Revenue Share (%), by Indication 2026 & 2034
Figure 28: Europe Companion Animal Pharmaceuticals Market Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe Companion Animal Pharmaceuticals Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia-Pacific Companion Animal Pharmaceuticals Market Revenue (Billion), by Product Type 2026 & 2034
Figure 31: Asia-Pacific Companion Animal Pharmaceuticals Market Revenue Share (%), by Product Type 2026 & 2034
Figure 32: Asia-Pacific Companion Animal Pharmaceuticals Market Revenue (Billion), by Animal Type 2026 & 2034
Figure 33: Asia-Pacific Companion Animal Pharmaceuticals Market Revenue Share (%), by Animal Type 2026 & 2034
Figure 34: Asia-Pacific Companion Animal Pharmaceuticals Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 35: Asia-Pacific Companion Animal Pharmaceuticals Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 36: Asia-Pacific Companion Animal Pharmaceuticals Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 37: Asia-Pacific Companion Animal Pharmaceuticals Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 38: Asia-Pacific Companion Animal Pharmaceuticals Market Revenue (Billion), by End User 2026 & 2034
Figure 39: Asia-Pacific Companion Animal Pharmaceuticals Market Revenue Share (%), by End User 2026 & 2034


 Companion Animal Pharmaceuticals Market