Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Nasogastric Tubes Market by Product Type (Levin Tubes, Salem-Sump Tubes, Other Specialty Tubes), by Technology (Polyvinyl Chloride, Polyurethane, Silicone), by Indication (Dysphagia & Swallowing Disorders, Drug & Nutrient Administration, Gastric Decompression, Others), by End User (Hospitals, Home Healthcare, Long-Term Care Facilities), by Patient Type (Adult, Pediatric, Geriatric), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia-Pacific (China, Japan, India, Australia, South Korea, Rest of Asia-Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, South Africa, Rest of Middle East & Africa) Forecast 2026-2034
Updated On : Nov 11, 2026|Base Year : 2025|Pages : 0
Nasogastric Tubes Market Valuation Timeline and Growth Trajectory (2026–2035)
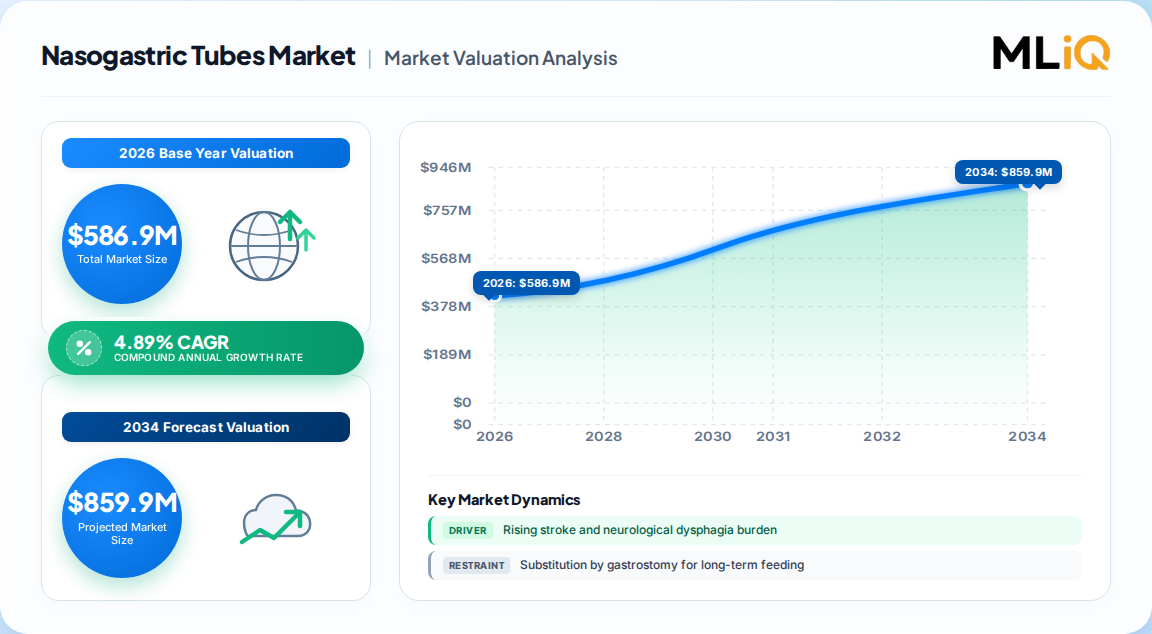
The global nasogastric tubes market is set to expand from USD 586.9 million in 2026 to USD 902.0 million by 2035, registering a CAGR of 4.89%. This trajectory builds on a 2025 base of USD 559.6 million and reflects a fundamental shift from raw unit volume growth toward value-dense specialty designs. Unit demand remains anchored in acute care, but revenue growth is increasingly driven by material upgrades, guided placement technologies, and the migration of enteral feeding into home settings.
Nasogastric Tubes Market Size (In Million)
750.0M
600.0M
450.0M
300.0M
150.0M
0
560.0 M
2025
587.0 M
2026
616.0 M
2027
646.0 M
2028
677.0 M
2029
710.0 M
2030
745.0 M
2031
Nasogastric Tubes Market Size (In Million)
Year
Market Size
2025
560.0 M
2026
587.0 M
2027
616.0 M
2028
646.0 M
2029
677.0 M
2030
710.0 M
2031
745.0 M
North America commands a 38.6% revenue share in 2025, supported by high ICU bed density and early adoption of electromagnetic placement systems.
Europe ranks second with a valuation of USD 153.3 million, where EU MDR material rules and silicone preferences for long-dwell placements shape purchasing.
Asia-Pacific is the fastest-growing region at a 6.2% CAGR, propelled by hospital construction in China and India and rapid ageing in Japan.
Metric
2021–2025 (Historical)
2026–2035 (Forecast)
Market Size (Base)
USD 559.6 million (2025)
USD 586.9 million (2026) to USD 902.0 million (2035)
CAGR
Moderate (inventory normalization in 2022)
4.89%
Growth Driver
Pandemic-era ICU stockpiling
Specialty designs and home-based care
Price Mix
Stable
Shift toward silicone and polyurethane
Stroke and Neurological Dysphagia Demand Drivers
Stroke is the single largest source of tube-dependent dysphagia. The World Stroke Organization counts more than 12 million new strokes annually and over 100 million people living with after-effects. ASPEN guidance supports early enteral access when oral intake is unsafe, and nasogastric placement remains the default first-line route in the acute phase because it requires no procedure room or anesthesia.
Dysphagia & swallowing disorders represented 48.6% of 2025 revenue, driven by stroke and neurodegenerative disease.
Parkinson's disease, ALS, and dementia add a slower but persistent demand layer in ageing high-income populations.
The driver carries a +1.1% impact on CAGR globally over a long-term (≥4 year) timeline.
Placement Safety Mandates and Verification Protocols
NHS Improvement identified 95 incidents of feeding into the lungs through misplaced tubes between 2011 and 2016, and misplaced tubes remain on the NHS England Never Events list. Hospitals have responded by standardizing tube types, adding pH testing and radiographic confirmation, and piloting electromagnetic guidance. Each step raises value per placement even where unit volumes stay flat.
Placement safety mandates contribute a +0.9% impact on CAGR across North America and Europe over a medium-term (2–4 year) horizon.
The August 2026 MHRA safety alert for the NGPod pH-testing device reinforced the need for reliable placement verification, supporting demand for guided placement systems.
Safer enteral connectors built to ISO 80369-3 (ENFit) are becoming standard, reducing the risk of wrong-route connections.
Levin, Salem-Sump and Specialty Tube Product Mix
The product landscape is segmented by design and clinical function, with distinct growth trajectories across the forecast period.
Product Type
2025 Share / Value
Growth Outlook
Levin Tubes
42.4% share
Anchored by low unit cost and routine acute decompression
Salem-Sump Tubes
USD 205.9 million
Dual-lumen demand in upper-GI and bariatric surgery
Other Specialty Tubes
—
6.9% CAGR as hospitals adopt electromagnetic and pH-guided placement
Levin tubes remain the dominant revenue generator due to affordability, ease of manufacturing, and broad application in general medical and surgical care. However, specialty tubes are gaining ground as safety protocols demand objective placement verification. Salem-sump tubes benefit from enhanced recovery protocols that cut typical dwell time to around 24 hours, but rising surgical throughput keeps aggregate unit demand climbing.
Polyurethane, Silicone and PVC Material Migration
Material selection is shifting faster than at any point in the past two decades. Basic PVC Levin tubes, placed blind and checked by aspirate testing, are giving ground to polyurethane and silicone alternatives.
Polyurethane accounted for 40.3% of 2025 demand, favored for short-dwell emergency and surgical placements.
Silicone is projected to post a 7.6% CAGR as long-duration placements shift toward inert, softer materials.
EU MDR Annex I requires manufacturers to justify any carcinogenic or endocrine-disrupting phthalate above 0.1% weight by weight, steering hospital procurement away from DEHP-plasticized PVC.
This regulatory accelerant is reshaping supply chains, with manufacturers reformulating compounds and qualifying alternative plasticizers. The migration creates a pricing umbrella for compliant products, supporting value growth even as unit volumes moderate.
Hospital, Home Healthcare and Long-Term Care End-User Dynamics
Hospitals remain the dominant end-user setting, but the site of care is shifting.
End-User Setting
2025 Share
Forecast CAGR
Hospitals
65.0%
Steady, reflecting ICU and surgical ward concentration
Home Healthcare
—
7.9% CAGR as enteral care moves out of inpatient settings
Long-Term Care Facilities
—
Moderate growth, tied to ageing populations
Payer pressure and patient preference are driving the migration of enteral care to home settings. Technological developments, including easy-to-use feeding pumps and simple-to-install tubes, have made nasogastric tubes a reliable choice for long-term nutritional therapy at home. Companies are funding training programs to help caregivers safely handle these devices, addressing issues with correct insertion, upkeep, and hygiene.
Oncology Nutrition Support and Bariatric Surgery Demand
GLOBOCAN 2022 records more than 900,000 new head and neck cancers worldwide each year. Mucositis during chemoradiation often makes oral feeding impossible for weeks, and many cancer centers now place tubes either prophylactically or at the first sign of weight loss. Esophageal and gastric cancer surgery adds post-operative demand.
Drug & nutrient administration is the fastest-growing indication at a 9.4% CAGR, supported by oncology nutrition protocols.
The American Society for Metabolic and Bariatric Surgery estimates roughly 280,000 metabolic and bariatric procedures were performed in the United States in 2022.
Upper-GI, hepatobiliary, and colorectal surgery all rely on nasogastric decompression tubes for post-operative gastric emptying, with dual-lumen designs preferred under continuous suction.
Competitive Landscape and Strategic Developments
The nasogastric tubes market is moderately consolidated, with key players focusing on material innovation, guided placement systems, and geographic expansion.
Cardinal Health, Avanos Medical, B. Braun, Fresenius Kabi, Medline Industries, and Vygon are among the leading suppliers.
Strategic activity centers on ENFit-compatible connectors, electromagnetic tracking systems, and pH-sensing placement verification.
Manufacturers are investing in local production in emerging markets to capture Asia-Pacific growth and mitigate supply chain risk.
Recent developments include the MHRA safety alert on the NGPod pH-testing device in August 2026, which prompted healthcare professionals to switch to alternative verification methods, reinforcing demand for reliable placement technologies. CMS also issued updated guidance on enteral nutrition in February 2026, covering documentation, billing, and patient eligibility, which supports access to tube-based nutrition in the United States.
Nasogastric Tubes Market Regional Market Share
Loading chart...
Nasogastric Tubes Market Regional Market Share
Region
Market Share (%)
North America
0.39%
Europe
0.27%
Asia-Pacific
0.22%
South America
0.06%
Middle East & Africa
0.06%
Nasogastric Tubes Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Nasogastric Tubes Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.89% from 2020-2034
Segmentation
By Product Type
Levin Tubes
Salem-Sump Tubes
Other Specialty Tubes
By Technology
Polyvinyl Chloride
Polyurethane
Silicone
By Indication
Dysphagia & Swallowing Disorders
Drug & Nutrient Administration
Gastric Decompression
Others
By End User
Hospitals
Home Healthcare
Long-Term Care Facilities
By Patient Type
Adult
Pediatric
Geriatric
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
Asia-Pacific
China
Japan
India
Australia
South Korea
Rest of Asia-Pacific
South America
Brazil
Argentina
Rest of South America
Middle East & Africa
Saudi Arabia
South Africa
Rest of Middle East & Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Levin Tubes
5.1.2. Salem-Sump Tubes
5.1.3. Other Specialty Tubes
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. Polyvinyl Chloride
5.2.2. Polyurethane
5.2.3. Silicone
5.3. Market Analysis, Insights and Forecast - by Indication
5.3.1. Dysphagia & Swallowing Disorders
5.3.2. Drug & Nutrient Administration
5.3.3. Gastric Decompression
5.3.4. Others
5.4. Market Analysis, Insights and Forecast - by End User
5.4.1. Hospitals
5.4.2. Home Healthcare
5.4.3. Long-Term Care Facilities
5.5. Market Analysis, Insights and Forecast - by Patient Type
5.5.1. Adult
5.5.2. Pediatric
5.5.3. Geriatric
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia-Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Levin Tubes
6.1.2. Salem-Sump Tubes
6.1.3. Other Specialty Tubes
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. Polyvinyl Chloride
6.2.2. Polyurethane
6.2.3. Silicone
6.3. Market Analysis, Insights and Forecast - by Indication
6.3.1. Dysphagia & Swallowing Disorders
6.3.2. Drug & Nutrient Administration
6.3.3. Gastric Decompression
6.3.4. Others
6.4. Market Analysis, Insights and Forecast - by End User
6.4.1. Hospitals
6.4.2. Home Healthcare
6.4.3. Long-Term Care Facilities
6.5. Market Analysis, Insights and Forecast - by Patient Type
6.5.1. Adult
6.5.2. Pediatric
6.5.3. Geriatric
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Levin Tubes
7.1.2. Salem-Sump Tubes
7.1.3. Other Specialty Tubes
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. Polyvinyl Chloride
7.2.2. Polyurethane
7.2.3. Silicone
7.3. Market Analysis, Insights and Forecast - by Indication
7.3.1. Dysphagia & Swallowing Disorders
7.3.2. Drug & Nutrient Administration
7.3.3. Gastric Decompression
7.3.4. Others
7.4. Market Analysis, Insights and Forecast - by End User
7.4.1. Hospitals
7.4.2. Home Healthcare
7.4.3. Long-Term Care Facilities
7.5. Market Analysis, Insights and Forecast - by Patient Type
7.5.1. Adult
7.5.2. Pediatric
7.5.3. Geriatric
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Levin Tubes
8.1.2. Salem-Sump Tubes
8.1.3. Other Specialty Tubes
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. Polyvinyl Chloride
8.2.2. Polyurethane
8.2.3. Silicone
8.3. Market Analysis, Insights and Forecast - by Indication
8.3.1. Dysphagia & Swallowing Disorders
8.3.2. Drug & Nutrient Administration
8.3.3. Gastric Decompression
8.3.4. Others
8.4. Market Analysis, Insights and Forecast - by End User
8.4.1. Hospitals
8.4.2. Home Healthcare
8.4.3. Long-Term Care Facilities
8.5. Market Analysis, Insights and Forecast - by Patient Type
8.5.1. Adult
8.5.2. Pediatric
8.5.3. Geriatric
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Levin Tubes
9.1.2. Salem-Sump Tubes
9.1.3. Other Specialty Tubes
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. Polyvinyl Chloride
9.2.2. Polyurethane
9.2.3. Silicone
9.3. Market Analysis, Insights and Forecast - by Indication
9.3.1. Dysphagia & Swallowing Disorders
9.3.2. Drug & Nutrient Administration
9.3.3. Gastric Decompression
9.3.4. Others
9.4. Market Analysis, Insights and Forecast - by End User
9.4.1. Hospitals
9.4.2. Home Healthcare
9.4.3. Long-Term Care Facilities
9.5. Market Analysis, Insights and Forecast - by Patient Type
9.5.1. Adult
9.5.2. Pediatric
9.5.3. Geriatric
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Levin Tubes
10.1.2. Salem-Sump Tubes
10.1.3. Other Specialty Tubes
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. Polyvinyl Chloride
10.2.2. Polyurethane
10.2.3. Silicone
10.3. Market Analysis, Insights and Forecast - by Indication
10.3.1. Dysphagia & Swallowing Disorders
10.3.2. Drug & Nutrient Administration
10.3.3. Gastric Decompression
10.3.4. Others
10.4. Market Analysis, Insights and Forecast - by End User
10.4.1. Hospitals
10.4.2. Home Healthcare
10.4.3. Long-Term Care Facilities
10.5. Market Analysis, Insights and Forecast - by Patient Type
10.5.1. Adult
10.5.2. Pediatric
10.5.3. Geriatric
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Cardinal Health
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Avanos Medical
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. B. Braun
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Fresenius Kabi
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Medline Industries
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Vygon
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Nasogastric Tubes Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Nasogastric Tubes Market Revenue (Million), by Product Type 2026 & 2034
Figure 3: North America Nasogastric Tubes Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Nasogastric Tubes Market Revenue (Million), by Technology 2026 & 2034
Figure 5: North America Nasogastric Tubes Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Nasogastric Tubes Market Revenue (Million), by Indication 2026 & 2034
Figure 7: North America Nasogastric Tubes Market Revenue Share (%), by Indication 2026 & 2034
Figure 8: North America Nasogastric Tubes Market Revenue (Million), by End User 2026 & 2034
Figure 9: North America Nasogastric Tubes Market Revenue Share (%), by End User 2026 & 2034
Figure 10: North America Nasogastric Tubes Market Revenue (Million), by Patient Type 2026 & 2034
Figure 11: North America Nasogastric Tubes Market Revenue Share (%), by Patient Type 2026 & 2034
Figure 12: North America Nasogastric Tubes Market Revenue (Million), by Country 2026 & 2034
Figure 13: North America Nasogastric Tubes Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Nasogastric Tubes Market Revenue (Million), by Product Type 2026 & 2034
Figure 15: Europe Nasogastric Tubes Market Revenue Share (%), by Product Type 2026 & 2034
Figure 16: Europe Nasogastric Tubes Market Revenue (Million), by Technology 2026 & 2034
List of Tables
Table 1: Nasogastric Tubes Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 2: Nasogastric Tubes Market Revenue Million Forecast, by Technology 2020 & 2034
Table 3: Nasogastric Tubes Market Revenue Million Forecast, by Indication 2020 & 2034
Table 4: Nasogastric Tubes Market Revenue Million Forecast, by End User 2020 & 2034
Table 5: Nasogastric Tubes Market Revenue Million Forecast, by Patient Type 2020 & 2034
Table 6: Nasogastric Tubes Market Revenue Million Forecast, by Region 2020 & 2034
Table 7: North America Nasogastric Tubes Market Revenue Million Forecast, by Product Type 2020 & 2034
Table 8: North America Nasogastric Tubes Market Revenue Million Forecast, by Technology 2020 & 2034
Table 9: North America Nasogastric Tubes Market Revenue Million Forecast, by Indication 2020 & 2034
Table 10: North America Nasogastric Tubes Market Revenue Million Forecast, by End User 2020 & 2034
Table 11: North America Nasogastric Tubes Market Revenue Million Forecast, by Patient Type 2020 & 2034
Table 12: North America Nasogastric Tubes Market Revenue Million Forecast, by Country 2020 & 2034
Table 13: USA Nasogastric Tubes Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 16: Europe Nasogastric Tubes Market Revenue Million Forecast, by Product Type 2020 & 2034
Frequently Asked Questions
1. What is the nasogastric tubes market size in 2026?
The global nasogastric tubes market is valued at USD 586.9 million in 2026 and is projected to reach USD 902.0 million by 2035, growing at a CAGR of 4.89%.
2. Which region dominates the nasogastric tubes market?
North America holds the leading position with a 38.6% revenue share in 2025, supported by high ICU bed density and early adoption of guided placement systems. Asia-Pacific is the fastest-growing region at a 6.2% CAGR.
3. What are the key drivers of the nasogastric tubes market?
Rising stroke and neurological dysphagia burden, placement safety mandates, expanding gastrointestinal and bariatric surgery, oncology nutrition support, and the migration of enteral care to home settings are the primary growth drivers.
4. Which product type leads the nasogastric tubes market?
Levin tubes held a 42.4% share in 2025, anchored by low unit cost and routine use in acute decompression. Salem-sump tubes generated USD 205.9 million, reflecting dual-lumen demand in upper-GI and bariatric surgery.
5. What material is expected to grow fastest in the nasogastric tubes market?
Silicone is projected to post a 7.6% CAGR as long-duration placements shift toward inert, softer materials. Polyurethane accounted for 40.3% of 2025 demand for short-dwell emergency and surgical placements.
6. Who are the leading companies in the nasogastric tubes market?
Key players include Cardinal Health, Avanos Medical, B. Braun, Fresenius Kabi, Medline Industries, and Vygon, focusing on material innovation, guided placement systems, and geographic expansion.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% primary research through interviews with procurement directors, clinical nurse specialists, critical care physicians, and enteral feeding specialists across hospitals, home healthcare agencies, and long-term care facilities.
Interviewed 3–4 specific stakeholder job titles: Critical Care Nurse Manager, Hospital Procurement Director, Enteral Nutrition Specialist, and Home Healthcare Operations Manager.
Collected 4–5 specific company types data: nasogastric tube manufacturers, contract manufacturers of medical tubing, raw material suppliers (silicone and polyurethane compounders), distributors and group purchasing organizations, and guided placement technology providers.
Gathered granular data on 3–4 specific quantitative metrics: average selling price by product type and material, unit volumes per hospital bed, placement success rates, and dwell-time distributions.
Engaged with 3–4 real industry associations and regulatory bodies: the American Society for Parenteral and Enteral Nutrition (ASPEN), the World Stroke Organization, the Medicines and Healthcare products Regulatory Agency (MHRA), and the U.S. Centers for Medicare & Medicaid Services (CMS).
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Critical Care Nurse Manager
30%
Hospital Procurement Director
25%
Enteral Nutrition Specialist
25%
Home Healthcare Operations Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Nasogastric Tube Manufacturers
35%
Contract Manufacturers of Medical Tubing
20%
Raw Material Suppliers (Silicone & Polyurethane)
20%
Distributors and Group Purchasing Organizations
15%
Guided Placement Technology Providers
10%
Secondary Research & Industry Benchmarking
Leveraged 20–30% secondary research from standard financial databases: Bloomberg, Factiva, Hoovers, and PitchBook.
Cross-referenced official government and non-profit sources, including the World Stroke Organization stroke incidence data, GLOBOCAN 2022 head and neck cancer statistics, the American Society for Metabolic and Bariatric Surgery procedure volumes, and NHS Improvement patient safety alerts.
Utilized trade and regulatory publications from the U.S. Food and Drug Administration (FDA), the European Medicines Agency (EMA), and the International Organization for Standardization (ISO 80369-3) for connector standards and material compliance.
Benchmarked against official multilateral data from the World Bank, OECD, and WHO for population ageing, chronic disease prevalence, and healthcare expenditure.
Demand Modeling & Market Estimation
Applied top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up model built from hospital admission, surgical, oncology, and stroke incidence data, multiplied by average selling prices by product type and material, then cross-checked against manufacturer disclosures, distributor interviews, and tender records.
Top-down model reconciled regional revenue shares with procedure-level demand and supply-side validation.
Incorporated 4–5 specific quantitative metrics in the calculation: ICU bed density per 100,000 population, stroke incidence per 100,000, bariatric procedure volumes, enteral feeding penetration rates, and average tube replacement frequency.
Forecast years assume steady price-mix gains from specialty and silicone tubes alongside moderate volume growth, with the 2022 slowdown reflecting inventory normalization after pandemic-era ICU stockpiling.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90% through multi-level data triangulation and cross-validation.
Every report is updated to the date of purchase to ensure current market intelligence.
All data points are validated through at least two independent primary interviews and one secondary source.
Quality assurance protocols include outlier detection, consistency checks across regional and segment-level data, and reconciliation with official trade and regulatory filings.
Figure 17: Europe Nasogastric Tubes Market Revenue Share (%), by Technology 2026 & 2034
Figure 18: Europe Nasogastric Tubes Market Revenue (Million), by Indication 2026 & 2034
Figure 19: Europe Nasogastric Tubes Market Revenue Share (%), by Indication 2026 & 2034
Figure 20: Europe Nasogastric Tubes Market Revenue (Million), by End User 2026 & 2034
Figure 21: Europe Nasogastric Tubes Market Revenue Share (%), by End User 2026 & 2034
Figure 22: Europe Nasogastric Tubes Market Revenue (Million), by Patient Type 2026 & 2034
Figure 23: Europe Nasogastric Tubes Market Revenue Share (%), by Patient Type 2026 & 2034
Figure 24: Europe Nasogastric Tubes Market Revenue (Million), by Country 2026 & 2034
Figure 25: Europe Nasogastric Tubes Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia-Pacific Nasogastric Tubes Market Revenue (Million), by Product Type 2026 & 2034
Figure 27: Asia-Pacific Nasogastric Tubes Market Revenue Share (%), by Product Type 2026 & 2034


 Nasogastric Tubes Market