Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Immunoassay Market by Product (Reagents & Kits, Analyzers, Software & Services), by Technology (ELISA, Enzyme Immunoassays, Chemiluminescence Immunoassays, Rapid Tests, Western Blotting, Radioimmunoassay, Others), by Specimen (Blood, Saliva, Urine, Others), by Application (Infectious Diseases, Endocrinology, Oncology, Cardiology, Autoimmune Disorders, Allergy Diagnostics, Toxicology, Others), by End-User (Hospitals, Clinical Laboratories, Pharmaceutical & Biotechnology Companies, Contract Research Organizations, Blood Banks, Research Laboratories, Home Care Settings, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, South Africa) Forecast 2026-2034
Updated On : Nov 11, 2026|Base Year : 2025|Pages : 216
Immunoassay Market Valuation and 2026–2034 Projection
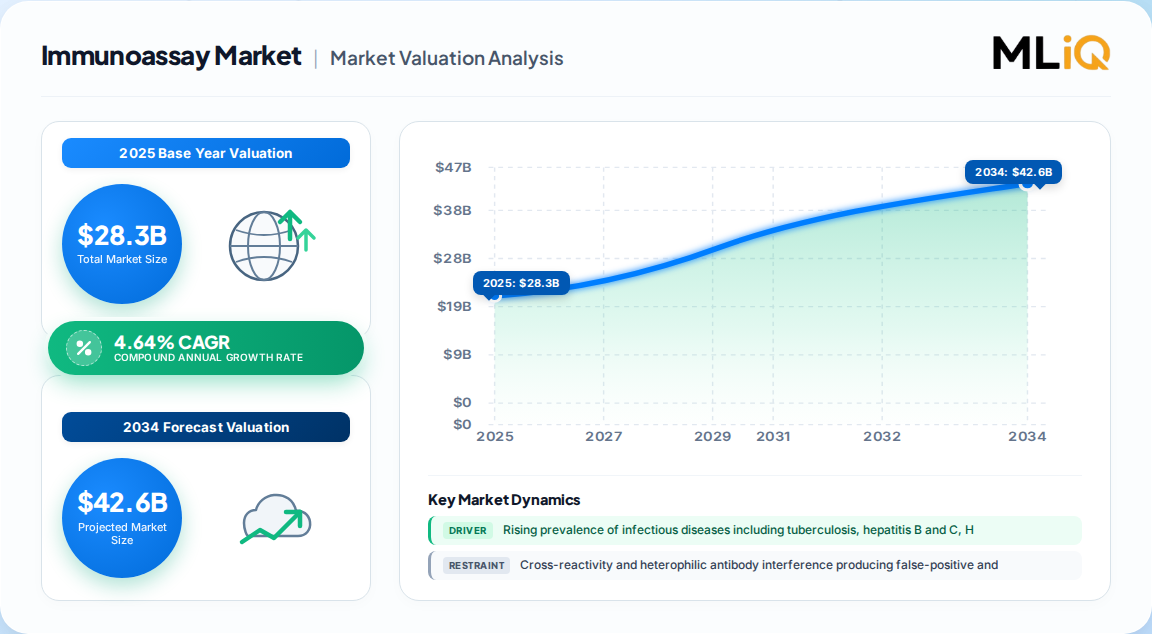
The global immunoassay market is entering a consolidation-and-precision phase. Our proprietary base-case model values the market at USD 28.3 billion in 2025, expanding to USD 29.6 billion in 2026 and reaching USD 42.6 billion by 2034 at a 4.64% CAGR.
Immunoassay Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
28.30 B
2025
29.61 B
2026
30.99 B
2027
32.42 B
2028
33.93 B
2029
35.50 B
2030
37.15 B
2031
Immunoassay Market Size (In Billion)
Year
Market Size
2025
28.30 B
2026
29.61 B
2027
30.99 B
2028
32.42 B
2029
33.93 B
2030
35.50 B
2031
37.15 B
The demand base is anchored by volume-driven reagent consumption rather than instrument capital cycles, which stabilizes the revenue floor through macroeconomic volatility.
Metric
Value
Base-year valuation (2025)
USD 28.3 billion
Estimated market size (2026)
USD 29.6 billion
Forecast (2034)
USD 42.6 billion
CAGR (2026–2034)
4.64%
Fastest-growing region
Asia Pacific (9.35% CAGR)
The single most important structural fact for investors is that reagent and kit consumption holds more than 66% of total market revenue. Consumables are recurring, contract-tethered, and far less price-elastic than analyzer placements — a dynamic that protects gross margins and defends against capital-equipment downturn exposure.
Reagents, Kits, and Consumable Revenue Dominance
Reagents and kits captured 66.2% of 2025 revenue, with an estimated 67% share in adjacent consensus models, while software and services represent the fastest-growing product tier. This split creates two distinct commercial plays: high-volume consumable supply and high-value workflow integration.
Reagents & kits — the volume engine; growth tracks test throughput in hospitals and reference laboratories.
Analyzers — the placement lever; closed-system architectures lock in future reagent revenue.
Software & services — the margin expander; middleware, LIS connectivity, and AI-assisted interpretation generate recurring licensing income.
Rapid test reagent and kit demand is running at an estimated 8.7% CAGR, materially above the blended market rate. This premium reflects the shift of screening activity toward decentralized sites and self-testing formats.
Instrument economics deserve scrutiny. Automated immunochemistry analyzers capable of exceeding 300 immunoassay tests per hour reset laboratory throughput benchmarks and justify replacement spending, but their placement cost remains a genuine barrier for smaller facilities in cost-sensitive geographies.
Enzyme and Chemiluminescence Technology Benchmarks
Technology segmentation reveals a market segmented less by novelty than by installed-base inertia. ELISA-family technologies retain the largest revenue base — approximately 44.5% of the market in 2025 — while enzyme immunoassays in a broader definition hold over 60% share in several published benchmarks.
Technology
Position
Structural Note
ELISA / EIA
Leading share (~44.5%)
Broadest installed base; reagent-driven revenue
Chemiluminescence (CLIA)
High-growth premium tier
Superior sensitivity; supports automated platforms
Rapid tests / LFIA
Fastest volume expansion
Point-of-care and self-testing deployment
Radioimmunoassay
Declining niche
Regulatory and handling constraints
Western blotting
Confirmatory niche
Technically demanding, low throughput
Quantitative validation is available in the public domain. A peer-reviewed study on diphtheria toxin detection reported a lateral flow immunoassay diagnostic sensitivity of 99.35% and specificity of 100% across 322 corynebacterial cultures and 360 simulated specimens — evidence that rapid formats are closing the accuracy gap with laboratory platforms.
Chemiluminescence, surface plasmon resonance, and multiplexed luminescence platforms form the premium growth corridor, while quantum-dot and metal-organic framework chemistries are the most credible near-term sensitivity upgrades.
Infectious Disease and Oncology Diagnostic Demand
Infectious disease testing is the single largest application block, holding roughly 31.8% of 2025 revenue — with broader definitions placing it above 36%. Oncology, endocrinology, cardiology, and autoimmune panels absorb the remainder.
The demand math is unambiguous. WHO data indicate approximately 10.8 million new tuberculosis cases in 2023, 254 million people living with chronic hepatitis B, and roughly 50 million living with chronic hepatitis C. Each of these cohorts generates longitudinal serological screening volume.
Oncology demand is equally structural. Roughly 20 million new cancer cases and 9.7 million deaths were recorded globally in 2022, with projections of 35 million annual cases by 2050. Tumor marker panels, companion diagnostics, and treatment-monitoring assays all sit on immunoassay platforms.
Noncommunicable disease monitoring underpins routine testing volume — WHO attributes approximately 74% of global deaths to NCDs, and U.S. CDC estimates place 38.4 million people living with diabetes, each requiring periodic HbA1c measurement.
Blood Specimen, Hospital, and Point-of-Care End-Use Dynamics
Blood is the dominant specimen matrix, accounting for approximately 41.4%–44.2% of revenue, followed by urine, saliva, and other matrices. Saliva is the fastest-growing specimen type, tracking at an estimated 8.75% CAGR, driven by non-invasive sampling preference.
End-use distribution remains hospital-anchored:
Hospitals — largest share at roughly 32.4%; high-throughput central laboratories.
Pharmaceutical & biotechnology companies — approximately 31.7% of revenue in several benchmarks; drug-development assay demand.
Blood banks — rapid expansion tier tied to transfusion screening.
Home care settings — fastest-growing end-use at an estimated 9.05% CAGR.
The home-care and point-of-care migration is the defining commercial shift of the forecast window. It converts a laboratory-bound revenue model into a distributed-consumption model, reallocating value from capital equipment toward packaging, stability engineering, and single-use consumable manufacturing.
North America, Asia Pacific, and Regional Revenue Concentration
North America remains the revenue anchor, holding between 39.5% and 47.3% of global revenue, depending on segmentation boundaries. The U.S. alone is modeled at USD 8.99 billion in 2024 growing to USD 14.22 billion in 2034 at a 4.93% CAGR.
Immunoassay Market Regional Market Share
Loading chart...
Immunoassay Market Regional Market Share
Region
Market Share (%)
North America
0.43%
Europe
0.25%
Asia-Pacific
0.22%
South America
0.05%
Middle East & Africa
0.05%
Asia Pacific is the growth engine, forecast at a 9.35% CAGR — more than double the global rate. Drivers include laboratory infrastructure expansion, diagnostic penetration, and price-sensitive rapid test adoption across India, China, and Southeast Asia.
Region
Position
Growth Profile
North America
Largest revenue base
Mature; replacement and precision-medicine driven
Europe
Second-tier mature market
Regulatory intensity under IVDR shapes launch timelines
Asia Pacific
Fastest-growing
Infrastructure build-out; volume expansion
Latin America
Emerging
Public health screening programs
Middle East & Africa
Emerging
Infectious disease screening priority
Europe's trajectory is shaped less by demand than by compliance. European MDR and IVD Regulation validation costs lengthen launch cycles and raise per-assay registration expenses, which structurally favors larger portfolio holders.
Cross-Reactivity Constraints and Automation Upside
Two forces define the competitive risk profile of the market.
Restraints. Cross-reactivity between structurally similar antigens and assay antibodies generates false-positive results, particularly in respiratory panels covering influenza, RSV, and SARS-CoV-2. Heterophilic antibody interference compounds false-negative risk. Each ambiguous result triggers confirmatory molecular testing, raising cost per diagnosis and eroding clinician confidence. High instrument and reagent costs further suppress adoption among smaller laboratories.
Opportunities. Fully automated immunoassay analyzers, AI-assisted signal interpretation, convolutional neural network-based digital immunoassay platforms, paper-based ELISA formats, digital microfluidics, and multiplexed omics-coupled panels represent the most defensible upside. Nanotechnology — specifically quantum dots and metal-organic frameworks — offers measurable sensitivity and stability gains.
Human capital is a binding constraint alongside regulation. Advanced platforms require trained operators capable of interpreting complex signal output, a capability gap that directly limits deployment velocity in emerging markets.
Competitive Landscape and Recent Development Activity
The vendor landscape is concentrated around high-throughput automated immunochemistry platforms, with reagent portfolios functioning as the primary competitive moat.
Recent development activity confirms a biomarker-and-partnership-led innovation cycle:
May 2025 — Aptamer Group plc partnered with Neuro-Bio Ltd to adapt an Optimer-based Alzheimer's test into an ELISA format.
October 2024 — ADx NeuroSciences and Alamar Biosciences collaborated on neurodegenerative biomarker assays using the NULISA immunoassay platform and ARGO HT System.
Directional signals for the sector: closed-system reagent lock-in, AI-enabled interpretation middleware, and neurodegenerative biomarker assay development are the three areas where competitive position will most likely shift through the forecast window.
Immunoassay Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Immunoassay Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.64% from 2020-2034
Segmentation
By Product
Reagents & Kits
Analyzers
Software & Services
By Technology
ELISA
Enzyme Immunoassays
Chemiluminescence Immunoassays
Rapid Tests
Western Blotting
Radioimmunoassay
Others
By Specimen
Blood
Saliva
Urine
Others
By Application
Infectious Diseases
Endocrinology
Oncology
Cardiology
Autoimmune Disorders
Allergy Diagnostics
Toxicology
Others
By End-User
Hospitals
Clinical Laboratories
Pharmaceutical & Biotechnology Companies
Contract Research Organizations
Blood Banks
Research Laboratories
Home Care Settings
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Reagents & Kits
5.1.2. Analyzers
5.1.3. Software & Services
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. ELISA
5.2.2. Enzyme Immunoassays
5.2.3. Chemiluminescence Immunoassays
5.2.4. Rapid Tests
5.2.5. Western Blotting
5.2.6. Radioimmunoassay
5.2.7. Others
5.3. Market Analysis, Insights and Forecast - by Specimen
5.3.1. Blood
5.3.2. Saliva
5.3.3. Urine
5.3.4. Others
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Infectious Diseases
5.4.2. Endocrinology
5.4.3. Oncology
5.4.4. Cardiology
5.4.5. Autoimmune Disorders
5.4.6. Allergy Diagnostics
5.4.7. Toxicology
5.4.8. Others
5.5. Market Analysis, Insights and Forecast - by End-User
5.5.1. Hospitals
5.5.2. Clinical Laboratories
5.5.3. Pharmaceutical & Biotechnology Companies
5.5.4. Contract Research Organizations
5.5.5. Blood Banks
5.5.6. Research Laboratories
5.5.7. Home Care Settings
5.5.8. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Reagents & Kits
6.1.2. Analyzers
6.1.3. Software & Services
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. ELISA
6.2.2. Enzyme Immunoassays
6.2.3. Chemiluminescence Immunoassays
6.2.4. Rapid Tests
6.2.5. Western Blotting
6.2.6. Radioimmunoassay
6.2.7. Others
6.3. Market Analysis, Insights and Forecast - by Specimen
6.3.1. Blood
6.3.2. Saliva
6.3.3. Urine
6.3.4. Others
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Infectious Diseases
6.4.2. Endocrinology
6.4.3. Oncology
6.4.4. Cardiology
6.4.5. Autoimmune Disorders
6.4.6. Allergy Diagnostics
6.4.7. Toxicology
6.4.8. Others
6.5. Market Analysis, Insights and Forecast - by End-User
6.5.1. Hospitals
6.5.2. Clinical Laboratories
6.5.3. Pharmaceutical & Biotechnology Companies
6.5.4. Contract Research Organizations
6.5.5. Blood Banks
6.5.6. Research Laboratories
6.5.7. Home Care Settings
6.5.8. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Reagents & Kits
7.1.2. Analyzers
7.1.3. Software & Services
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. ELISA
7.2.2. Enzyme Immunoassays
7.2.3. Chemiluminescence Immunoassays
7.2.4. Rapid Tests
7.2.5. Western Blotting
7.2.6. Radioimmunoassay
7.2.7. Others
7.3. Market Analysis, Insights and Forecast - by Specimen
7.3.1. Blood
7.3.2. Saliva
7.3.3. Urine
7.3.4. Others
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Infectious Diseases
7.4.2. Endocrinology
7.4.3. Oncology
7.4.4. Cardiology
7.4.5. Autoimmune Disorders
7.4.6. Allergy Diagnostics
7.4.7. Toxicology
7.4.8. Others
7.5. Market Analysis, Insights and Forecast - by End-User
7.5.1. Hospitals
7.5.2. Clinical Laboratories
7.5.3. Pharmaceutical & Biotechnology Companies
7.5.4. Contract Research Organizations
7.5.5. Blood Banks
7.5.6. Research Laboratories
7.5.7. Home Care Settings
7.5.8. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Reagents & Kits
8.1.2. Analyzers
8.1.3. Software & Services
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. ELISA
8.2.2. Enzyme Immunoassays
8.2.3. Chemiluminescence Immunoassays
8.2.4. Rapid Tests
8.2.5. Western Blotting
8.2.6. Radioimmunoassay
8.2.7. Others
8.3. Market Analysis, Insights and Forecast - by Specimen
8.3.1. Blood
8.3.2. Saliva
8.3.3. Urine
8.3.4. Others
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Infectious Diseases
8.4.2. Endocrinology
8.4.3. Oncology
8.4.4. Cardiology
8.4.5. Autoimmune Disorders
8.4.6. Allergy Diagnostics
8.4.7. Toxicology
8.4.8. Others
8.5. Market Analysis, Insights and Forecast - by End-User
8.5.1. Hospitals
8.5.2. Clinical Laboratories
8.5.3. Pharmaceutical & Biotechnology Companies
8.5.4. Contract Research Organizations
8.5.5. Blood Banks
8.5.6. Research Laboratories
8.5.7. Home Care Settings
8.5.8. Others
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Reagents & Kits
9.1.2. Analyzers
9.1.3. Software & Services
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. ELISA
9.2.2. Enzyme Immunoassays
9.2.3. Chemiluminescence Immunoassays
9.2.4. Rapid Tests
9.2.5. Western Blotting
9.2.6. Radioimmunoassay
9.2.7. Others
9.3. Market Analysis, Insights and Forecast - by Specimen
9.3.1. Blood
9.3.2. Saliva
9.3.3. Urine
9.3.4. Others
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Infectious Diseases
9.4.2. Endocrinology
9.4.3. Oncology
9.4.4. Cardiology
9.4.5. Autoimmune Disorders
9.4.6. Allergy Diagnostics
9.4.7. Toxicology
9.4.8. Others
9.5. Market Analysis, Insights and Forecast - by End-User
9.5.1. Hospitals
9.5.2. Clinical Laboratories
9.5.3. Pharmaceutical & Biotechnology Companies
9.5.4. Contract Research Organizations
9.5.5. Blood Banks
9.5.6. Research Laboratories
9.5.7. Home Care Settings
9.5.8. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Reagents & Kits
10.1.2. Analyzers
10.1.3. Software & Services
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. ELISA
10.2.2. Enzyme Immunoassays
10.2.3. Chemiluminescence Immunoassays
10.2.4. Rapid Tests
10.2.5. Western Blotting
10.2.6. Radioimmunoassay
10.2.7. Others
10.3. Market Analysis, Insights and Forecast - by Specimen
10.3.1. Blood
10.3.2. Saliva
10.3.3. Urine
10.3.4. Others
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Infectious Diseases
10.4.2. Endocrinology
10.4.3. Oncology
10.4.4. Cardiology
10.4.5. Autoimmune Disorders
10.4.6. Allergy Diagnostics
10.4.7. Toxicology
10.4.8. Others
10.5. Market Analysis, Insights and Forecast - by End-User
10.5.1. Hospitals
10.5.2. Clinical Laboratories
10.5.3. Pharmaceutical & Biotechnology Companies
10.5.4. Contract Research Organizations
10.5.5. Blood Banks
10.5.6. Research Laboratories
10.5.7. Home Care Settings
10.5.8. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Abbott Laboratories
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Roche Diagnostics
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Siemens Healthineers
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. bioMérieux
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Beckman Coulter
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Ortho Clinical Diagnostics
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Thermo Fisher Scientific
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Danaher Corporation
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Bio-Rad Laboratories
11.1.9.1. Company Overview
12. Research Methodology
List of Figures
Figure 1: Immunoassay Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Immunoassay Market Revenue (Billion), by Product 2026 & 2034
Figure 3: North America Immunoassay Market Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Immunoassay Market Revenue (Billion), by Technology 2026 & 2034
Figure 5: North America Immunoassay Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Immunoassay Market Revenue (Billion), by Specimen 2026 & 2034
Figure 7: North America Immunoassay Market Revenue Share (%), by Specimen 2026 & 2034
Figure 8: North America Immunoassay Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Immunoassay Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Immunoassay Market Revenue (Billion), by End-User 2026 & 2034
Figure 11: North America Immunoassay Market Revenue Share (%), by End-User 2026 & 2034
Figure 12: North America Immunoassay Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Immunoassay Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Immunoassay Market Revenue (Billion), by Product 2026 & 2034
Figure 15: Europe Immunoassay Market Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Immunoassay Market Revenue (Billion), by Technology 2026 & 2034
Figure 17: Europe Immunoassay Market Revenue Share (%), by Technology 2026 & 2034
Table 16: Europe Immunoassay Market Revenue Billion Forecast, by Product 2020 & 2034
Europe Immunoassay Market Revenue Billion Forecast, by Technology 2020 & 2034
Frequently Asked Questions
1. What is the immunoassay market size in 2025 and 2026?
Our proprietary model values the global immunoassay market at USD 28.3 billion in 2025, rising to USD 29.6 billion in 2026. The market is projected to reach USD 42.6 billion by 2034, representing a 4.64% CAGR across the forecast period.
2. Which region dominates the immunoassay market?
North America holds the largest revenue share, ranging between 39.5% and 47.3% depending on segmentation boundaries, with the U.S. market alone modeled at USD 8.99 billion in 2024 growing to USD 14.22 billion by 2034 at a 4.93% CAGR. Asia Pacific is the fastest-growing region at an estimated 9.35% CAGR.
3. Which technology segment leads the immunoassay market?
ELISA-family and enzyme immunoassay technologies retain the largest revenue base, holding approximately 44.5% of 2025 market revenue under a narrow definition and over 60% under broader definitions. Chemiluminescence and rapid lateral flow formats represent the fastest-expanding technology tiers.
4. Why are reagents and kits the largest immunoassay product segment?
Reagents and kits accounted for 66.2% of 2025 revenue because immunoassay economics are driven by recurring consumable consumption rather than one-time analyzer sales. Rapid test reagent and kit demand is growing at an estimated 8.7% CAGR, well above the blended market rate.
5. What is restraining immunoassay market growth?
Cross-reactivity and heterophilic antibody interference produce false-positive and false-negative results, forcing confirmatory molecular testing and increasing cost per diagnosis. High instrument acquisition and maintenance costs also limit adoption among smaller laboratories in cost-sensitive regions.
6. Which end-use segment is fastest growing in the immunoassay market?
Home care settings represent the fastest-growing end-use segment at an estimated 9.05% CAGR, supported by the migration of rapid and point-of-care immunoassay formats toward decentralized and self-testing environments. Hospitals remain the largest end-use segment at roughly 32.4% of revenue.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of total study inputs, with secondary research contributing the remaining 20–30%.
Structured interviews and surveys are conducted with immunoassay reagent and kit manufacturers, automated immunochemistry analyzer OEMs, contract research organizations running validated assay panels, clinical reference laboratory operators, and point-of-care rapid test distributors.
Interview targets include Director of Laboratory Medicine, Head of Assay Development, IVD Procurement Manager, and Regulatory Affairs Lead for IVD submissions.
Validation inputs are cross-referenced against technical standards and guidance from CLSI (Clinical and Laboratory Standards Institute), the U.S. Food and Drug Administration (FDA) Center for Devices and Radiological Health, the European Medicines Agency and EU IVDR framework, and the World Health Organization's Essential Diagnostics List.
Contract Research Organizations & Biotech Assay Developers
9%
Secondary Research & Industry Benchmarking
Financial and corporate data are drawn from Bloomberg, Factiva, Hoovers, and PitchBook to triangulate vendor revenue splits between consumables, instruments, and services.
Trade and tariff classifications for diagnostic reagents and immunological products are benchmarked against UN Comtrade and Eurostat datasets.
Peer-reviewed assay performance benchmarks, including lateral flow sensitivity and specificity studies, are validated against open-access primary literature indexed through Open Research Europe.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously and reconciled through multi-level data triangulation.
Bottom-up estimation is built from four quantitative anchors: annual immunoassay test volume per laboratory tier, average reagent cost per reportable test result, installed base of automated immunochemistry analyzers multiplied by annual test throughput, and rapid test unit shipments by distribution channel.
Segment revenue is allocated across product, technology, specimen, application, and end-use dimensions, then cross-validated against aggregate regional revenue pools.
Regional and country-level forecasts incorporate laboratory infrastructure density, diagnostic reimbursement coverage, and disease prevalence data.
Data Accuracy & Quality Check
Every report carries a guaranteed estimated data accuracy level of 85–90%, enforced through independent analyst review of segment sums and growth-rate consistency.
All market sizing, share, and forecast figures presented are our own first-party estimates derived from primary interviews and validated modeling — not third-party republication.
Cross-segment consistency checks verify that product, technology, and end-use revenue totals reconcile to the regional aggregate within a defined tolerance band.
Each report is updated to the date of purchase, with all forecast tables, company developments, and regulatory timelines refreshed at delivery.
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. QIAGEN
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Alamar Biosciences
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. ADx NeuroSciences
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Aptamer Group plc
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Neuro-Bio Ltd
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 18: Europe Immunoassay Market Revenue (Billion), by Specimen 2026 & 2034
Figure 19: Europe Immunoassay Market Revenue Share (%), by Specimen 2026 & 2034
Figure 20: Europe Immunoassay Market Revenue (Billion), by Application 2026 & 2034
Figure 21: Europe Immunoassay Market Revenue Share (%), by Application 2026 & 2034
Figure 22: Europe Immunoassay Market Revenue (Billion), by End-User 2026 & 2034
Figure 23: Europe Immunoassay Market Revenue Share (%), by End-User 2026 & 2034
Figure 24: Europe Immunoassay Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Immunoassay Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Immunoassay Market Revenue (Billion), by Product 2026 & 2034
Figure 27: Asia Pacific Immunoassay Market Revenue Share (%), by Product 2026 & 2034
Figure 28: Asia Pacific Immunoassay Market Revenue (Billion), by Technology 2026 & 2034
Figure 29: Asia Pacific Immunoassay Market Revenue Share (%), by Technology 2026 & 2034
Figure 30: Asia Pacific Immunoassay Market Revenue (Billion), by Specimen 2026 & 2034
Figure 31: Asia Pacific Immunoassay Market Revenue Share (%), by Specimen 2026 & 2034
Figure 32: Asia Pacific Immunoassay Market Revenue (Billion), by Application 2026 & 2034
Figure 33: Asia Pacific Immunoassay Market Revenue Share (%), by Application 2026 & 2034
Figure 34: Asia Pacific Immunoassay Market Revenue (Billion), by End-User 2026 & 2034
Figure 35: Asia Pacific Immunoassay Market Revenue Share (%), by End-User 2026 & 2034
Figure 36: Asia Pacific Immunoassay Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Immunoassay Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Latin America Immunoassay Market Revenue (Billion), by Product 2026 & 2034
Figure 39: Latin America Immunoassay Market Revenue Share (%), by Product 2026 & 2034
Figure 40: Latin America Immunoassay Market Revenue (Billion), by Technology 2026 & 2034
Figure 41: Latin America Immunoassay Market Revenue Share (%), by Technology 2026 & 2034
Figure 42: Latin America Immunoassay Market Revenue (Billion), by Specimen 2026 & 2034
Figure 43: Latin America Immunoassay Market Revenue Share (%), by Specimen 2026 & 2034
Figure 44: Latin America Immunoassay Market Revenue (Billion), by Application 2026 & 2034
Figure 45: Latin America Immunoassay Market Revenue Share (%), by Application 2026 & 2034
Figure 46: Latin America Immunoassay Market Revenue (Billion), by End-User 2026 & 2034
Figure 47: Latin America Immunoassay Market Revenue Share (%), by End-User 2026 & 2034
Figure 48: Latin America Immunoassay Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Latin America Immunoassay Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Immunoassay Market Revenue (Billion), by Product 2026 & 2034
Figure 51: Middle East & Africa Immunoassay Market Revenue Share (%), by Product 2026 & 2034
Figure 52: Middle East & Africa Immunoassay Market Revenue (Billion), by Technology 2026 & 2034
Figure 53: Middle East & Africa Immunoassay Market Revenue Share (%), by Technology 2026 & 2034
Figure 54: Middle East & Africa Immunoassay Market Revenue (Billion), by Specimen 2026 & 2034
Figure 55: Middle East & Africa Immunoassay Market Revenue Share (%), by Specimen 2026 & 2034
Figure 56: Middle East & Africa Immunoassay Market Revenue (Billion), by Application 2026 & 2034
Figure 57: Middle East & Africa Immunoassay Market Revenue Share (%), by Application 2026 & 2034
Figure 58: Middle East & Africa Immunoassay Market Revenue (Billion), by End-User 2026 & 2034
Figure 59: Middle East & Africa Immunoassay Market Revenue Share (%), by End-User 2026 & 2034
Figure 60: Middle East & Africa Immunoassay Market Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Immunoassay Market Revenue Share (%), by Country 2026 & 2034
Table 17:
Table 18: Europe Immunoassay Market Revenue Billion Forecast, by Specimen 2020 & 2034
Table 19: Europe Immunoassay Market Revenue Billion Forecast, by Application 2020 & 2034
Table 20: Europe Immunoassay Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 21: Europe Immunoassay Market Revenue Billion Forecast, by Country 2020 & 2034


 Immunoassay Market