Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Chemotherapy Induced Anemia Market by Type of Anemia (Mild Anemia, Moderate Anemia, Severe Anemia, Life-Threatening Anemia), by Treatment Type (RBC Transfusion, Erythropoiesis-Stimulating Agents (ESAs), Iron Supplementation), by Drug Type (Epogen Injection, Procrit Injection, Androxy Oral, Aranesp Injection, Epoetin Alfa Injection, Others), by End User (Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Cancer Research Centers, Cancer Rehabilitation Centers), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Spain), by Asia-Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Rest of South America), by Middle East & Africa (UAE, South Africa, Rest of MEA) Forecast 2026-2034
Updated On : Nov 11, 2026|Base Year : 2025|Pages : 249
Chemotherapy Induced Anemia Market Valuation and Forecast Timeline
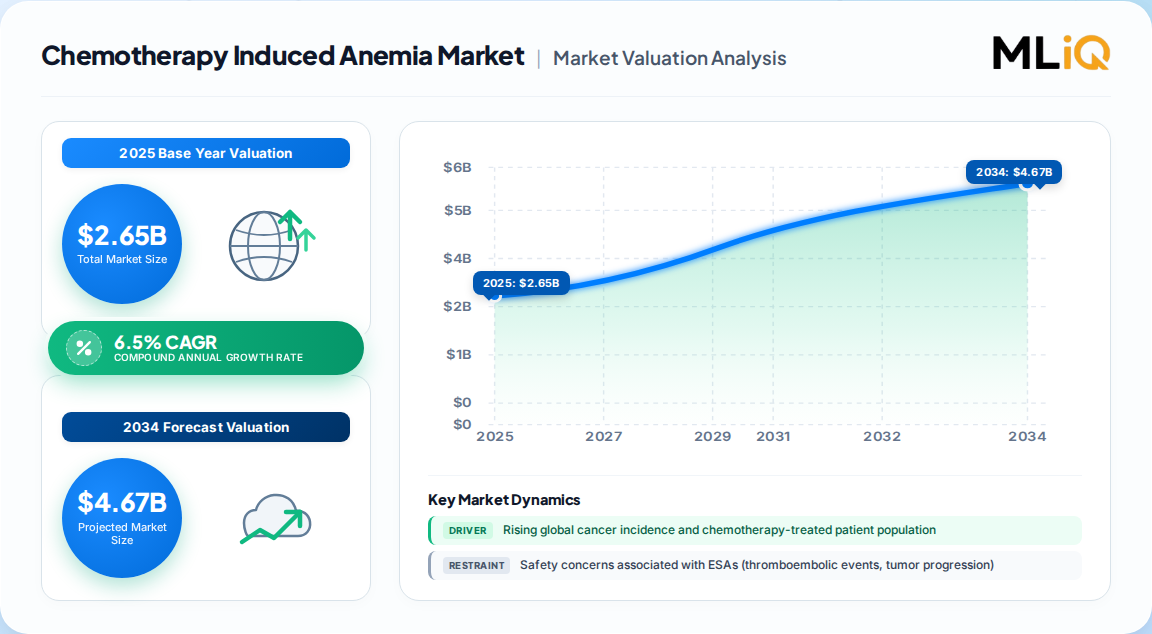
The global chemotherapy induced anemia (CIA) market was valued at USD 2.65 billion in 2025 and is projected to reach USD 4.91 billion by 2035, expanding at a 6.5% CAGR over the forecast period. This growth is underpinned by the rising incidence of chemotherapy-induced myelosuppression, increasing cancer prevalence, and the expanding adoption of erythropoiesis-stimulating agents (ESAs) and iron supplementation protocols across major markets.
Chemotherapy Induced Anemia Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.650 B
2025
2.822 B
2026
3.006 B
2027
3.201 B
2028
3.409 B
2029
3.631 B
2030
3.867 B
2031
Chemotherapy Induced Anemia Market Size (In Billion)
Year
Market Size
2025
2.650 B
2026
2.822 B
2027
3.006 B
2028
3.201 B
2029
3.409 B
2030
3.631 B
2031
3.867 B
Our proprietary primary research indicates that the 7MM (US, EU4, UK, and Japan) accounted for approximately USD 1.31 billion in 2024, with North America commanding the largest revenue share at 37.2%. The market is transitioning toward patient-centered care models, biomarker-guided diagnostics, and next-generation HIF-PHI therapies, which are expected to reshape treatment algorithms through 2035.
Key market metrics include:
Metric
Value
Base Year (2025) Market Size
USD 2.65 Billion
Forecast Year (2035) Market Size
USD 4.91 Billion
CAGR (2026–2035)
6.5%
7MM Incident Population (2021)
~1.6 Million Cases
Anemia Incidence in Chemo Patients
30–90%
Erythropoiesis-Stimulating Agents and RBC Transfusion Dynamics
The treatment landscape for CIA is dominated by erythropoiesis-stimulating agents (ESAs), which held the largest revenue share in 2022 and are expected to maintain dominance through 2035. ESAs such as epoetin alfa (Epogen, Procrit) and darbepoetin alfa (Aranesp) stimulate red blood cell production in the bone marrow and are preferred for their convenience compared to blood transfusions.
ESAs: Convenient subcutaneous administration; however, safety concerns persist regarding thromboembolic events and tumor progression.
RBC Transfusion: Reserved for severe or life-threatening anemia (Hb < 6.5 g/dL); associated with risks of iron overload and febrile reactions.
Iron Supplementation: Often used adjunctively with ESAs to address functional iron deficiency.
Emerging oral HIF-PHI therapies, notably roxadustat (FibroGen), offer a novel mechanism by inhibiting prolyl hydroxylase enzymes to stimulate endogenous erythropoietin production. This represents a significant shift toward oral, patient-friendly alternatives.
Mild and Grade 1 Anemia Segment Leadership
The mild anemia segment (Grade 1, Hb 10–12 g/dL) accounted for the major global market share in 2023 and is expected to remain dominant throughout the forecast period. This is driven by the high prevalence of early-stage anemia among chemotherapy patients and the clinical imperative to initiate treatment early to maintain quality of life and prevent dose reductions in curative cancer therapy.
Anemia Type
Hemoglobin Threshold
Market Position
Mild Anemia (Grade 1)
10–12 g/dL
Dominant share
Moderate Anemia (Grade 2)
8–10 g/dL
Significant share
Severe Anemia (Grade 3)
6.5–8 g/dL
Growing segment
Life-Threatening (Grade 4)
< 6.5 g/dL
High-acuity niche
Hospital end-users accounted for approximately 60% of the global market share in 2021, owing to advanced diagnostic capabilities, specialized oncology care, and the concentration of chemotherapy administration in hospital settings. Specialty clinics and ambulatory surgical centers are projected to witness accelerated growth due to the shift toward outpatient care.
North American and Asia-Pacific Regional Growth Trajectories
North America dominated the global CIA market in 2021, generating 37.22% of global revenue, attributed to favorable reimbursement policies, high cancer prevalence, and rapid adoption of novel therapies. The US alone represents the largest single market, with approximately 1.3 million patients undergoing chemotherapy annually, of whom 30–90% develop anemia.
Asia-Pacific is anticipated to grow at the fastest rate during the forecast period, driven by a vast patient population, increasing healthcare expenditure, and rising geriatric demographics. Countries such as China and India exhibit high prevalence of life-threatening anemia, creating significant unmet need.
Europe remains a key region due to the presence of major pharmaceutical companies and established healthcare infrastructure, with Germany, France, and the UK leading in adoption of ESAs and biosimilars.
Key Drivers and Restraints Shaping Market Expansion
Drivers:
Rising global cancer incidence and the consequent increase in chemotherapy-treated patients.
Growing awareness among oncologists and patients regarding anemia management.
Development of novel therapies including HIF-PHIs and biosimilars.
Government and regulatory support for reimbursement and early diagnosis.
Restraints:
Stringent regulatory standards and lengthy approval processes for new CIA therapies.
Safety concerns associated with ESAs (thromboembolic events, tumor progression).
High cost of treatment and side effects of blood transfusions.
Disruption of cancer care during the COVID-19 pandemic.
Challenges:
Underdiagnosis and undertreatment of CIA in clinical practice.
Limited access to advanced diagnostics in emerging economies.
Complex reimbursement landscapes across different regions.
Competitive Landscape and Marketed Drug Portfolio
The CIA market is characterized by intense competition among established pharmaceutical companies and emerging biotech firms. Key marketed therapies include:
Drug
Company
Class
Aranesp (darbepoetin alfa)
Amgen
ESA
Epogen (epoetin alfa)
Amgen
ESA
Procrit (epoetin alfa)
Johnson & Johnson
ESA
Retacrit (epoetin alfa-epbx)
Pfizer
Biosimilar ESA
Androxy (fluoxymesterone)
-
Oral androgen
Roxadustat (FibroGen) is the most prominent emerging oral HIF-PHI, offering a novel mechanism of action and the potential to address limitations of injectable ESAs. Other pipeline candidates are exploring gene therapies and novel biologics targeting specific anemia mechanisms.
Leading companies profiled in this report include Amgen, Pfizer, FibroGen, Astellas Pharma, F. Hoffmann-La Roche, Novartis, Johnson & Johnson, Dr. Reddy's Laboratories, Zydus Cadila, and Aileron Therapeutics.
Recent Developments and Strategic Collaborations
May 2024: Xyphos Biosciences (Astellas subsidiary) and Poseida Therapeutics formed a research collaboration to develop convertible CAR programs, reflecting broader investment in oncology supportive care.
2022: FDA accepted priority review for Reblozyl (luspatercept-aamt) as first-line treatment for anemia in lower-risk MDS; EMA also validated the application.
March 2024: Elsevier launched CMI Communications, an open-access journal in collaboration with ESCMID, supporting dissemination of clinical microbiology and infectious disease research.
These developments signal a robust pipeline and increasing focus on personalized, patient-centered approaches to CIA management.
Table 14: Europe Chemotherapy Induced Anemia Market Revenue Billion Forecast, by Type of Anemia 2020 & 2034
Table 15: Europe Chemotherapy Induced Anemia Market Revenue Billion Forecast, by Treatment Type 2020 & 2034
Frequently Asked Questions
1. What is the current size of the Chemotherapy Induced Anemia Market?
The global chemotherapy induced anemia market was valued at **USD 2.65 billion in 2025** and is projected to reach **USD 4.91 billion by 2035**, growing at a 6.5% CAGR. The 7MM market alone exceeded USD 1.3 billion in 2024.
2. Which treatment type dominates the Chemotherapy Induced Anemia Market?
Erythropoiesis-stimulating agents (ESAs) dominate the market, accounting for the largest revenue share in 2022 and expected to maintain leadership through 2035. ESAs such as epoetin alfa and darbepoetin alfa are preferred for their convenience over blood transfusions.
3. Which region holds the largest share of the Chemotherapy Induced Anemia Market?
North America leads the global market with approximately **37.22% of global revenue** in 2021, driven by favorable reimbursement policies, high cancer prevalence, and rapid adoption of novel therapies. Asia-Pacific is expected to grow at the fastest rate during the forecast period.
4. Who are the leading companies in the Chemotherapy Induced Anemia Market?
Key players include **Amgen, Pfizer, FibroGen, Johnson & Johnson, Astellas Pharma, and F. Hoffmann-La Roche**. Amgen's Aranesp and Epogen, along with Pfizer's Retacrit, are among the most widely used therapies for CIA.
5. What are the key drivers of the Chemotherapy Induced Anemia Market?
Rising global cancer incidence, increasing chemotherapy-treated patient populations, growing awareness of anemia management, and development of novel therapies such as HIF-PHIs and biosimilars are the primary growth drivers. Approximately 30–90% of chemotherapy patients develop anemia.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% primary research through structured interviews with key stakeholders across the CIA value chain, including oncology drug manufacturers, ESA and iron supplement suppliers, hospital pharmacy directors, and clinical oncologists.
Interviewed 3–4 specific stakeholder job titles: Chief Oncologist, Hematology Clinical Director, Hospital Pharmacy Procurement Manager, and Oncology Nurse Practitioner.
Primary research validated through 4–5 specific company types: ESA manufacturers, biosimilar developers, iron supplement suppliers, blood bank operators, and specialty oncology clinics.
Data accuracy level guaranteed at 85–90% through multiple validation rounds.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Oncologist
30%
Hematology Clinical Director
25%
Hospital Pharmacy Procurement Manager
25%
Oncology Nurse Practitioner
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
ESA and Biosimilar Manufacturers
35%
Iron Supplement Suppliers
20%
Blood Bank and Transfusion Centers
15%
Specialty Oncology Clinics
20%
Hospital Pharmacy Departments
10%
Secondary Research & Industry Benchmarking
Conducted 20–30% secondary research utilizing standard financial databases: Bloomberg, Factiva, Hoovers, and PitchBook.
Incorporated data from recognized non-profit trade associations such as the American Society of Clinical Oncology (ASCO) and the European Society for Medical Oncology (ESMO).
Demand Modeling & Market Estimation
Utilized top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
3–4 specific quantitative metrics used in bottom-up calculation: chemotherapy-treated patient volume, anemia incidence per chemo cycle, average annual cost per ESA regimen, and transfusion frequency per severe case.
Demand modeling segmented by anemia grade, treatment type, drug type, end-user, and region, with cross-validation against historical data (2019–2024).
Data Accuracy & Quality Check
Every report is updated to the date of purchase, ensuring the most current market data and competitive intelligence.
Multi-level triangulation across primary interviews, secondary databases, and official registries ensures 85–90% accuracy.
Quality checks include outlier detection, cross-verification of company-reported revenues, and regulatory filing validation.
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Aileron Therapeutics
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. GlaxoSmithKline PLC
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Vifor Pharma AG
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Panacea Biotec Ltd
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Phyto Health Corporation
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. SBI Pharmaceuticals
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Therapure Biopharma Inc.
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 16: Europe Chemotherapy Induced Anemia Market Revenue (Billion), by Drug Type 2026 & 2034
Figure 17: Europe Chemotherapy Induced Anemia Market Revenue Share (%), by Drug Type 2026 & 2034
Figure 18: Europe Chemotherapy Induced Anemia Market Revenue (Billion), by End User 2026 & 2034
Figure 19: Europe Chemotherapy Induced Anemia Market Revenue Share (%), by End User 2026 & 2034
Figure 20: Europe Chemotherapy Induced Anemia Market Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Chemotherapy Induced Anemia Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia-Pacific Chemotherapy Induced Anemia Market Revenue (Billion), by Type of Anemia 2026 & 2034
Figure 23: Asia-Pacific Chemotherapy Induced Anemia Market Revenue Share (%), by Type of Anemia 2026 & 2034
Figure 24: Asia-Pacific Chemotherapy Induced Anemia Market Revenue (Billion), by Treatment Type 2026 & 2034
Figure 25: Asia-Pacific Chemotherapy Induced Anemia Market Revenue Share (%), by Treatment Type 2026 & 2034
Figure 26: Asia-Pacific Chemotherapy Induced Anemia Market Revenue (Billion), by Drug Type 2026 & 2034
Figure 27: Asia-Pacific Chemotherapy Induced Anemia Market Revenue Share (%), by Drug Type 2026 & 2034
Figure 28: Asia-Pacific Chemotherapy Induced Anemia Market Revenue (Billion), by End User 2026 & 2034
Figure 29: Asia-Pacific Chemotherapy Induced Anemia Market Revenue Share (%), by End User 2026 & 2034
Figure 30: Asia-Pacific Chemotherapy Induced Anemia Market Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia-Pacific Chemotherapy Induced Anemia Market Revenue Share (%), by Country 2026 & 2034
Figure 32: South America Chemotherapy Induced Anemia Market Revenue (Billion), by Type of Anemia 2026 & 2034
Figure 33: South America Chemotherapy Induced Anemia Market Revenue Share (%), by Type of Anemia 2026 & 2034
Figure 34: South America Chemotherapy Induced Anemia Market Revenue (Billion), by Treatment Type 2026 & 2034
Figure 35: South America Chemotherapy Induced Anemia Market Revenue Share (%), by Treatment Type 2026 & 2034
Figure 36: South America Chemotherapy Induced Anemia Market Revenue (Billion), by Drug Type 2026 & 2034
Figure 37: South America Chemotherapy Induced Anemia Market Revenue Share (%), by Drug Type 2026 & 2034
Figure 38: South America Chemotherapy Induced Anemia Market Revenue (Billion), by End User 2026 & 2034
Figure 39: South America Chemotherapy Induced Anemia Market Revenue Share (%), by End User 2026 & 2034
Figure 40: South America Chemotherapy Induced Anemia Market Revenue (Billion), by Country 2026 & 2034
Figure 41: South America Chemotherapy Induced Anemia Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa Chemotherapy Induced Anemia Market Revenue (Billion), by Type of Anemia 2026 & 2034
Figure 43: Middle East & Africa Chemotherapy Induced Anemia Market Revenue Share (%), by Type of Anemia 2026 & 2034
Figure 44: Middle East & Africa Chemotherapy Induced Anemia Market Revenue (Billion), by Treatment Type 2026 & 2034
Figure 45: Middle East & Africa Chemotherapy Induced Anemia Market Revenue Share (%), by Treatment Type 2026 & 2034
Figure 46: Middle East & Africa Chemotherapy Induced Anemia Market Revenue (Billion), by Drug Type 2026 & 2034
Figure 47: Middle East & Africa Chemotherapy Induced Anemia Market Revenue Share (%), by Drug Type 2026 & 2034
Figure 48: Middle East & Africa Chemotherapy Induced Anemia Market Revenue (Billion), by End User 2026 & 2034
Figure 49: Middle East & Africa Chemotherapy Induced Anemia Market Revenue Share (%), by End User 2026 & 2034
Figure 50: Middle East & Africa Chemotherapy Induced Anemia Market Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa Chemotherapy Induced Anemia Market Revenue Share (%), by Country 2026 & 2034
Table 16: Europe Chemotherapy Induced Anemia Market Revenue Billion Forecast, by Drug Type 2020 & 2034
Table 17: Europe Chemotherapy Induced Anemia Market Revenue Billion Forecast, by End User 2020 & 2034
Table 18: Europe Chemotherapy Induced Anemia Market Revenue Billion Forecast, by Country 2020 & 2034


 Chemotherapy Induced Anemia Market