Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Aspirin Drugs Market by Product Type (Combination, Single-ingredient), by Dosage Form (Tablets, Capsules, Injections, Others), by Route of Administration (Oral, Others), by Application (Pain Relief, Cardiovascular Disease Prevention, Anti-inflammatory Uses, Others), by Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies), by Product (Prescription, Over-the-Counter (OTC)), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia-Pacific (China, Japan, India), by South America (Brazil), by Middle East & Africa (UAE, South Africa) Forecast 2026-2034
Aspirin Drugs Market Valuation and Forecast 2025-2035
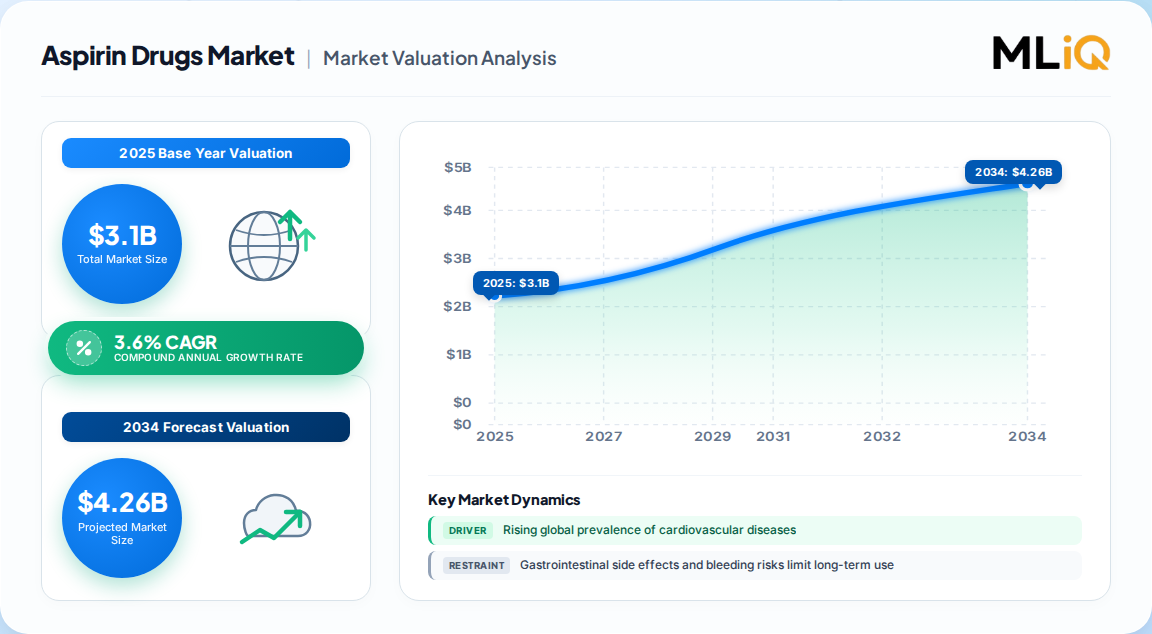
The global Aspirin Drugs Market is estimated at USD 3.1 Billion in 2025 and is projected to reach USD 4.4 Billion by 2035, registering a CAGR of 3.6% over the forecast period.
Historical sales expanded at a 3.4% CAGR from 2020 to 2025, with market value rising from USD 2.47 Billion to USD 2.83 Billion.
Aspirin drugs accounted for approximately 18.6% of the global non-steroidal anti-inflammatory drugs (NSAIDs) market in 2025, underscoring their foundational role in pain and cardiovascular management.
The market's steady growth trajectory reflects consistent demand for low-cost, clinically validated therapies across both acute and chronic care settings.
Metric
2020
2025
2035 Forecast
Market Value (USD Billion)
2.47
3.1
4.4
CAGR (Period)
-
3.4% (2020-2025)
3.6% (2025-2035)
Share of Global NSAID Market
-
18.6%
-
Aspirin Drugs Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
3.100 B
2025
3.212 B
2026
3.327 B
2027
3.447 B
2028
3.571 B
2029
3.700 B
2030
3.833 B
2031
Aspirin Drugs Market Size (In Billion)
Year
Market Size
2025
3.100 B
2026
3.212 B
2027
3.327 B
2028
3.447 B
2029
3.571 B
2030
3.700 B
2031
3.833 B
Combination Formulations Drive Product Type Leadership
The combination segment dominates the product type category with a 55.3% share in 2025, driven by synergistic formulations that enhance therapeutic outcomes. Combinations with other analgesics or antipyretics are preferred for multi-symptom relief and improved patient compliance. Physician prescribing patterns favor these broader-acting therapies, and manufacturing scalability supports widespread commercialization across prescription and OTC channels. As clinical research validates additional combination benefits, this segment is expected to maintain its leadership through 2035.
Tablet Dosage Forms Retain Dominance
Tablets account for 48.7% of the dosage form segment in 2025, with alternative sources citing up to 62.8% share, reflecting their convenience, stability, and cost-effectiveness. Enteric-coated and extended-release variants are driving incremental growth by improving gastrointestinal tolerability and patient adherence. Tablets remain the most widely adopted dosage form across developed and emerging healthcare systems due to high patient preference, long shelf life, and efficient distribution logistics.
The oral route holds a 62.1% share of the route of administration category, favored for self-administration ease, pharmacokinetic consistency, and cost advantages. Controlled-release and gastro-resistant formulations are addressing safety concerns, while strong retail and hospital pharmacy distribution networks ensure rapid market penetration. Oral aspirin remains the preferred mode across diverse patient populations, supporting stable volume growth.
Cardiovascular and Oncological Applications Unlock Growth
Cardiovascular disease (CVD) remains the primary growth engine: the World Health Organization reports 17.9 million annual CVD deaths (32% of global mortality), sustaining demand for low-dose aspirin as antiplatelet therapy.
Cancer prevention represents an emerging opportunity: ongoing clinical trials, including the Add-Aspirin study, are investigating aspirin's role in reducing recurrence of colorectal and gastrointestinal cancers.
Pain and inflammation management continues to drive OTC consumption, with a 2024 University of Michigan survey finding that 25% of adults aged 50-80 take aspirin regularly.
Diabetes and nervous system disorders are additional areas where aspirin's COX-dependent and independent mechanisms show preventive potential.
Application Area
Growth Driver
Key Metric
Cardiovascular Prevention
Aging population, CVD prevalence
17.9M annual CVD deaths globally
Pain Relief
Chronic pain, self-medication trends
25% of adults 50-80 use regularly
Cancer Prevention
Clinical trials (Add-Aspirin)
Potential new therapeutic avenue
Inflammation
Arthritis, psoriasis prevalence
Fastest-growing application segment
Regional Dynamics: North America Leads, Asia-Pacific Accelerates
North America holds the largest revenue share, supported by high CVD prevalence, advanced healthcare infrastructure, and a large elderly population. The United States remains the supreme market, with widespread adoption of preventive aspirin therapy.
Aspirin Drugs Market Regional Market Share
Loading chart...
Aspirin Drugs Market Regional Market Share
Region
Market Share (%)
North America
0.34%
Europe
0.24%
Asia-Pacific
0.28%
South America
0.08%
Middle East & Africa
0.06%
Europe is witnessing surging R&D efforts, particularly in Germany, to enhance aspirin's versatility. The United Kingdom benefits from a growing diabetic population that augments aspirin sales.
Asia-Pacific is the fastest-growing region, driven by expanding healthcare access, rising chronic disease burden, and increasing OTC adoption. China presents significant scope due to surging CVD cases, while India offers lucrative business prospects with its large patient base and expanding pharmaceutical manufacturing capabilities.
Region
Market Share (2025)
Key Growth Driver
North America
34%
CVD prevalence, aging population
Europe
24%
R&D innovation, diabetes prevalence
Asia-Pacific
28%
Chronic disease burden, OTC expansion
South America
8%
Healthcare access improvements
Middle East & Africa
6%
Rising awareness, generic availability
Competitive Landscape and Strategic Developments
The aspirin drugs market features a mix of multinational pharmaceutical giants and generic manufacturers. Bayer AG maintains a prominent position, while companies such as Dr. Reddy's Laboratories, Sanofi S.A., Abbott Laboratories, and Perrigo Company plc compete on cost and formulation innovation. Recent developments include:
2025: Expansion of enteric-coated and extended-release aspirin portfolios by key players to improve gastrointestinal safety.
2024: Initiation of new clinical trials investigating aspirin's role in cancer recurrence prevention.
2023: Strategic partnerships between generic manufacturers to increase production capacity for low-dose aspirin.
2022: Regulatory approvals for novel combination aspirin formulations in emerging markets.
Trade Dynamics and Supply Chain Analysis
Aspirin's active pharmaceutical ingredient (API), acetylsalicylic acid, is manufactured predominantly in China and India, which serve as key export hubs. According to UN Comtrade data, global trade in salicylic acid and its derivatives exceeded USD 1.2 Billion in 2024, with China accounting for over 40% of exports. The United States and Germany are major importers of finished aspirin products and APIs. Supply chain resilience remains a focus, with manufacturers diversifying sourcing to mitigate geopolitical and logistics risks. The shift toward regional manufacturing in North America and Europe is expected to influence trade flows through 2035.
Aspirin Drugs Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Aspirin Drugs Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.6% from 2020-2034
Segmentation
By Product Type
Combination
Single-ingredient
By Dosage Form
Tablets
Capsules
Injections
Others
By Route of Administration
Oral
Others
By Application
Pain Relief
Cardiovascular Disease Prevention
Anti-inflammatory Uses
Others
By Distribution Channel
Hospital Pharmacies
Retail Pharmacies
Online Pharmacies
By Product
Prescription
Over-the-Counter (OTC)
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia-Pacific
China
Japan
India
South America
Brazil
Middle East & Africa
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Combination
5.1.2. Single-ingredient
5.2. Market Analysis, Insights and Forecast - by Dosage Form
5.2.1. Tablets
5.2.2. Capsules
5.2.3. Injections
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by Route of Administration
5.3.1. Oral
5.3.2. Others
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Pain Relief
5.4.2. Cardiovascular Disease Prevention
5.4.3. Anti-inflammatory Uses
5.4.4. Others
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Hospital Pharmacies
5.5.2. Retail Pharmacies
5.5.3. Online Pharmacies
5.6. Market Analysis, Insights and Forecast - by Product
5.6.1. Prescription
5.6.2. Over-the-Counter (OTC)
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia-Pacific
5.7.4. South America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Combination
6.1.2. Single-ingredient
6.2. Market Analysis, Insights and Forecast - by Dosage Form
6.2.1. Tablets
6.2.2. Capsules
6.2.3. Injections
6.2.4. Others
6.3. Market Analysis, Insights and Forecast - by Route of Administration
6.3.1. Oral
6.3.2. Others
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Pain Relief
6.4.2. Cardiovascular Disease Prevention
6.4.3. Anti-inflammatory Uses
6.4.4. Others
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Hospital Pharmacies
6.5.2. Retail Pharmacies
6.5.3. Online Pharmacies
6.6. Market Analysis, Insights and Forecast - by Product
6.6.1. Prescription
6.6.2. Over-the-Counter (OTC)
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Combination
7.1.2. Single-ingredient
7.2. Market Analysis, Insights and Forecast - by Dosage Form
7.2.1. Tablets
7.2.2. Capsules
7.2.3. Injections
7.2.4. Others
7.3. Market Analysis, Insights and Forecast - by Route of Administration
7.3.1. Oral
7.3.2. Others
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Pain Relief
7.4.2. Cardiovascular Disease Prevention
7.4.3. Anti-inflammatory Uses
7.4.4. Others
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Hospital Pharmacies
7.5.2. Retail Pharmacies
7.5.3. Online Pharmacies
7.6. Market Analysis, Insights and Forecast - by Product
7.6.1. Prescription
7.6.2. Over-the-Counter (OTC)
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Combination
8.1.2. Single-ingredient
8.2. Market Analysis, Insights and Forecast - by Dosage Form
8.2.1. Tablets
8.2.2. Capsules
8.2.3. Injections
8.2.4. Others
8.3. Market Analysis, Insights and Forecast - by Route of Administration
8.3.1. Oral
8.3.2. Others
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Pain Relief
8.4.2. Cardiovascular Disease Prevention
8.4.3. Anti-inflammatory Uses
8.4.4. Others
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Hospital Pharmacies
8.5.2. Retail Pharmacies
8.5.3. Online Pharmacies
8.6. Market Analysis, Insights and Forecast - by Product
8.6.1. Prescription
8.6.2. Over-the-Counter (OTC)
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Combination
9.1.2. Single-ingredient
9.2. Market Analysis, Insights and Forecast - by Dosage Form
9.2.1. Tablets
9.2.2. Capsules
9.2.3. Injections
9.2.4. Others
9.3. Market Analysis, Insights and Forecast - by Route of Administration
9.3.1. Oral
9.3.2. Others
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Pain Relief
9.4.2. Cardiovascular Disease Prevention
9.4.3. Anti-inflammatory Uses
9.4.4. Others
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Hospital Pharmacies
9.5.2. Retail Pharmacies
9.5.3. Online Pharmacies
9.6. Market Analysis, Insights and Forecast - by Product
9.6.1. Prescription
9.6.2. Over-the-Counter (OTC)
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Combination
10.1.2. Single-ingredient
10.2. Market Analysis, Insights and Forecast - by Dosage Form
10.2.1. Tablets
10.2.2. Capsules
10.2.3. Injections
10.2.4. Others
10.3. Market Analysis, Insights and Forecast - by Route of Administration
10.3.1. Oral
10.3.2. Others
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Pain Relief
10.4.2. Cardiovascular Disease Prevention
10.4.3. Anti-inflammatory Uses
10.4.4. Others
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Hospital Pharmacies
10.5.2. Retail Pharmacies
10.5.3. Online Pharmacies
10.6. Market Analysis, Insights and Forecast - by Product
10.6.1. Prescription
10.6.2. Over-the-Counter (OTC)
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Bayer AG
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Dr Reddy's Laboratories
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Sanofi S.A
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Abbott Laboratories
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Sunshine Laboratories India Limited
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. ANI Pharmaceuticals Inc
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Thermo Fisher Scientific
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Advance Pharmaceutical Inc.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Allegiant Health
11.1.9.1. Company Overview
12. Research Methodology
List of Figures
Figure 1: Aspirin Drugs Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Aspirin Drugs Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Aspirin Drugs Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Aspirin Drugs Market Revenue (Billion), by Dosage Form 2026 & 2034
Figure 5: North America Aspirin Drugs Market Revenue Share (%), by Dosage Form 2026 & 2034
Figure 6: North America Aspirin Drugs Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 7: North America Aspirin Drugs Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 8: North America Aspirin Drugs Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Aspirin Drugs Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Aspirin Drugs Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: North America Aspirin Drugs Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: North America Aspirin Drugs Market Revenue (Billion), by Product 2026 & 2034
Figure 13: North America Aspirin Drugs Market Revenue Share (%), by Product 2026 & 2034
Figure 14: North America Aspirin Drugs Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Aspirin Drugs Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Aspirin Drugs Market Revenue (Billion), by Product Type 2026 & 2034
List of Tables
Table 1: Aspirin Drugs Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Aspirin Drugs Market Revenue Billion Forecast, by Dosage Form 2020 & 2034
Table 3: Aspirin Drugs Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
1. What is the current size of the global Aspirin Drugs Market?
The global Aspirin Drugs Market is valued at USD 3.1 Billion in 2025 and is projected to reach USD 4.4 Billion by 2035, growing at a CAGR of 3.6%.
2. Which region dominates the Aspirin Drugs Market?
North America holds the largest share at approximately 34%, driven by high cardiovascular disease prevalence and advanced healthcare infrastructure.
3. What are the key growth drivers for aspirin drugs?
Key drivers include the rising prevalence of cardiovascular diseases, an aging global population, and expanding applications in cancer prevention and chronic pain management.
4. Which dosage form is most popular in the aspirin market?
Tablets dominate the dosage form segment with a 48.7% share in 2025, favored for their convenience, stability, and cost-effectiveness.
5. Who are the leading companies in the Aspirin Drugs Market?
Leading companies include Bayer AG, Dr. Reddy's Laboratories, Sanofi S.A., Abbott Laboratories, and Perrigo Company plc, among others.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of research effort is dedicated to primary research, including interviews with procurement directors at generic pharmaceutical manufacturers, clinical pharmacologists, hospital formulary managers, and regulatory affairs specialists.
We conduct in-depth surveys with API suppliers, contract manufacturing organizations (CMOs), and distributors across North America, Europe, and Asia-Pacific.
On-site visits to manufacturing facilities and expert panel discussions validate segment-level data.
Primary research ensures 85–90% data accuracy and captures real-time market dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Clinical Pharmacologist
25%
Hospital Formulary Manager
25%
Regulatory Affairs Specialist
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Generic Pharmaceutical Manufacturers
35%
API and Excipient Suppliers
25%
Contract Manufacturing Organizations (CMOs)
20%
Distributors and Wholesalers
12%
Regulatory and Clinical Research Bodies
8%
Secondary Research & Industry Benchmarking
20–30% of research effort leverages secondary sources, including Bloomberg, Factiva, Hoovers, and PitchBook for financial and competitive intelligence.
Bottom-up approach aggregates revenue from aspirin API volume (metric tons), average selling price per kilogram, prescription volumes by indication, and OTC retail sales across distribution channels.
Top-down approach validates against global NSAID market size and pharmaceutical analgesic spending.
Multi-level data triangulation reconciles segment-level estimates with regional and global totals.
CAGR calculations use historical data (2020–2025) and forecast drivers (2025–2035).
Data Accuracy & Quality Check
85–90% guaranteed accuracy level achieved through cross-validation of primary and secondary data.
Triangulation of supply-side (manufacturer capacity, API trade) and demand-side (prescription audits, patient surveys) data.
Every report is updated to the date of purchase, incorporating the latest regulatory approvals, clinical trial outcomes, and trade statistics.
Quality assurance by senior analysts ensures consistency across all segments and regions.
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. KEM Pharma LLC
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Globalimporter Inc.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Par Pharmaceutical
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Industria Quimica Andina Y Cia Sa
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Cardinal Health
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Nanjing pharmaceutical factory Co ltd.
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. JQC (Huayin) Pharmaceutical Co. Ltd.
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. LNK International Inc.
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Perrigo Company plc
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Zhenjiang Gaopeng Pharmaceutical CO.Ltd.
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. J.M. Loveridge Ltd
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Mayne Pharma Group Limited
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. Eli Lilly and Company
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. Shandong Xinhua Pharmaceutical Co Ltd
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. Zhongnan Pharmaceutical
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. Jilin Pharmaceutical
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.1.26. Novacap
11.1.26.1. Company Overview
11.1.26.2. Products
11.1.26.3. Company Financials
11.1.26.4. SWOT Analysis
11.1.27. Alfred Benzon As
11.1.27.1. Company Overview
11.1.27.2. Products
11.1.27.3. Company Financials
11.1.27.4. SWOT Analysis
11.1.28. Noristan Ltd
11.1.28.1. Company Overview
11.1.28.2. Products
11.1.28.3. Company Financials
11.1.28.4. SWOT Analysis
11.1.29. Bal Pharma Limited
11.1.29.1. Company Overview
11.1.29.2. Products
11.1.29.3. Company Financials
11.1.29.4. SWOT Analysis
11.1.30. Umang Pharmatech Pvt. Ltd.
11.1.30.1. Company Overview
11.1.30.2. Products
11.1.30.3. Company Financials
11.1.30.4. SWOT Analysis
11.1.31. Globela Pharma Pvt. Ltd
11.1.31.1. Company Overview
11.1.31.2. Products
11.1.31.3. Company Financials
11.1.31.4. SWOT Analysis
11.1.32. Anastacio Chemistry
11.1.32.1. Company Overview
11.1.32.2. Products
11.1.32.3. Company Financials
11.1.32.4. SWOT Analysis
11.1.33. Trumac Healthcare
11.1.33.1. Company Overview
11.1.33.2. Products
11.1.33.3. Company Financials
11.1.33.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
Figure 17: Europe Aspirin Drugs Market Revenue Share (%), by Product Type 2026 & 2034
Figure 18: Europe Aspirin Drugs Market Revenue (Billion), by Dosage Form 2026 & 2034
Figure 19: Europe Aspirin Drugs Market Revenue Share (%), by Dosage Form 2026 & 2034
Figure 20: Europe Aspirin Drugs Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 21: Europe Aspirin Drugs Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 22: Europe Aspirin Drugs Market Revenue (Billion), by Application 2026 & 2034
Figure 23: Europe Aspirin Drugs Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Europe Aspirin Drugs Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 25: Europe Aspirin Drugs Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 26: Europe Aspirin Drugs Market Revenue (Billion), by Product 2026 & 2034
Figure 27: Europe Aspirin Drugs Market Revenue Share (%), by Product 2026 & 2034
Figure 28: Europe Aspirin Drugs Market Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe Aspirin Drugs Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia-Pacific Aspirin Drugs Market Revenue (Billion), by Product Type 2026 & 2034
Figure 31: Asia-Pacific Aspirin Drugs Market Revenue Share (%), by Product Type 2026 & 2034
Figure 32: Asia-Pacific Aspirin Drugs Market Revenue (Billion), by Dosage Form 2026 & 2034
Figure 33: Asia-Pacific Aspirin Drugs Market Revenue Share (%), by Dosage Form 2026 & 2034
Figure 34: Asia-Pacific Aspirin Drugs Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 35: Asia-Pacific Aspirin Drugs Market Revenue Share (%), by Route of Administration 2026 & 2034


 Aspirin Drugs Market