Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
U.S. Clinical Trial Imaging Services Market 2025
U.S. Clinical Trial Imaging Services Market
U.S. Clinical Trial Imaging Services Market 2025
U.S. Clinical Trial Imaging Services Market by Service Type (Clinical Trial Design & Consultation, Reading & Analytical, Operational Imaging, Project & Data Management, Others), by Modality (CT, MRI, PET, Ultrasound, X-ray), by Therapeutic Area (Oncology, Neurology, Endocrinology, Cardiology, Gastroenterology, Others), by End User (Pharmaceutical & Biotechnology, Medical Device Manufacturers, Academic & Government Research Institutes, Integrated CROs, Non-Integrated CROs, Others), by South (Texas, North Carolina, Florida), by Northeast (Massachusetts, New York, Pennsylvania), by West (California, Washington), by Midwest (Illinois, Minnesota, Michigan) Forecast 2026-2034
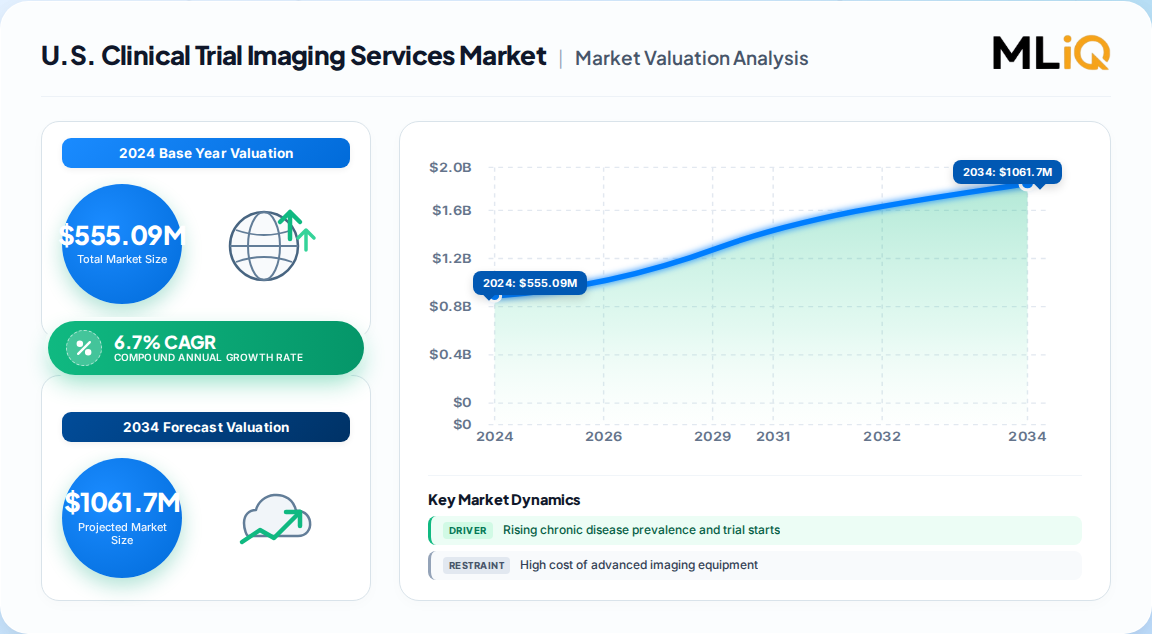
The U.S. clinical trial imaging services market is valued at 555.09 Million in 2024, with scope defined as outsourced imaging for drug and device trials.
Forecasts project 768.95 Million by 2029, a 6.7% CAGR (2025–2029), reflecting sustained demand from oncology, cardiology, and neurology studies.
Reading and analytical services dominate at 30.95% of global share, while CT leads modalities at 25.87%; MRI is close behind on soft-tissue strength.
Integrated and non-integrated CROs control the largest end-user revenue pool, positioning them as the primary procurement channel for sponsors.
Oncology is the leading therapeutic area (23.63% global share), but neurology is the fastest-growing at 8.2% CAGR through 2029.
Why this matters for decision-makers: Vendors must pivot to AI-enabled reading and decentralized imaging workflows to capture neurology and precision-medicine demand, or risk margin compression from commoditized acquisition services.
U.S. Clinical Trial Imaging Services Market Size (In Million)
1.0B
800.0M
600.0M
400.0M
200.0M
0
555.0 M
2024
592.0 M
2025
632.0 M
2026
674.0 M
2027
719.0 M
2028
768.0 M
2029
U.S. Clinical Trial Imaging Services Market Size (In Million)
Year
Market Size
2024
555.0 M
2025
592.0 M
2026
632.0 M
2027
674.0 M
2028
719.0 M
2029
768.0 M
What is the U.S. Clinical Trial Imaging Services Market?
U.S. clinical trial imaging services are outsourced, standardized imaging and analysis capabilities—MRI, CT, PET, ultrasound—used by sponsors and CROs to capture objective endpoints, monitor safety, and support FDA submissions in drug and device trials across therapeutic areas.
Scope: what this report covers and excludes
This report covers U.S.-based clinical trial imaging service providers across modality (CT, MRI, PET, ultrasound, X-ray), service type (design/consultation, reading/analytics, operational imaging, project/data management), therapeutic area (oncology, neurology, cardiology, endocrinology, gastroenterology), and end user (pharma/biotech, device makers, academic/government, CROs).
This analysis does not cover diagnostic imaging for routine clinical care, medical imaging device manufacturing, radiology practice management software, or preclinical imaging.
How big is the market for U.S. Clinical Trial Imaging Services Market?
The most defensible U.S. figure is 555.09 Million in 2024, rising to 768.95 Million by 2029 at 6.7% CAGR, anchored to a dedicated country-level forecast rather than a global share allocation.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
555.09 Million
2024
2029
6.7%
U.S. outsourced clinical trial imaging services, all service types
One published country-level analysis
~47.93% of 1.23 Billion global
2024
2030
7.8%
Global clinical trial imaging, North America share applied to U.S.
A competing global analysis (implied allocation)
780 Million (global)
2025
2035
6.1%
Global clinical trial imaging service market, product-type lens
A second global benchmark
The 555.09 Million figure is most defensible because it is built from U.S.-specific end-user and service-type segmentation. The 47.93% North America allocation implies roughly 590 Million for the U.S. alone, a 6% divergence from the country forecast.
Our analysis suggests the gap reflects scope differences: the global study bundles all imaging-related services and may include device-trial imaging and software fees that the U.S. country report classifies separately. For procurement planning, use the 555 Million base and stress-test at ±7%.
How is the market segmented?
Segmentation is defined by service type, modality, therapeutic area, and end user, with reading and analytical services and CRO channels dominating revenue.
Pharmaceutical & Biotechnology, Medical Device Manufacturers, Academic & Government Research Institutes, Integrated CROs, Non-Integrated CROs, Others
Reading and analytical services hold 30.95% of global revenue and grow at 8.4% CAGR, making them the highest-value segment. Operational imaging (site coordination, acquisition) is lower-margin and increasingly commoditized, which is why our analysis suggests providers should shift revenue mix toward analytics and AI-assisted reads.
Which U.S. region leads in U.S. Clinical Trial Imaging Services Market?
The South leads the U.S. clinical trial imaging services market, driven by concentrated academic medical centers, CRO headquarters, and biotech clusters in Texas, North Carolina, and Florida.
U.S. Clinical Trial Imaging Services Market Regional Market Share
Loading chart...
U.S. Clinical Trial Imaging Services Market Regional Market Share
Region
Market Share (%)
Northeast
0.24%
South
0.31%
Midwest
0.21%
West
0.24%
South (31%) — Texas Medical Center, Research Triangle Park, Florida biotech corridors
Northeast (24%) — Boston/Cambridge, New York, Philadelphia academic and pharma hubs
West (24%) — San Francisco Bay Area, San Diego, Seattle
Midwest (21%) — Chicago, Minneapolis, Ann Arbor
Our analysis indicates the South's lead is structural, not cyclical: lower operating costs, state-level trial incentives, and growing CRO back-office presence make it the preferred expansion geography for imaging core labs. The Northeast remains the highest-value market per trial because of Phase I/II density.
What is driving growth — and what is holding it back?
Growth is driven by rising chronic disease prevalence, precision-medicine trial design, CRO outsourcing economics, and AI-enabled image analytics; it is restrained by high equipment costs and complex regulatory compliance.
Factor
Direction
Evidence strength
Mechanism
Rising chronic disease prevalence
Driver
High
More oncology, cardiology, and neurology trials require imaging endpoints
CRO outsourcing of imaging
Driver
High
4,321 U.S. CROs in 2024 (+2.1%) absorb complexity and cost
AI and 3D imaging accuracy
Driver
Medium
25% diagnostic accuracy gains reported vs. 2D imaging
The balance favors growth. Our analysis suggests the restraint is not demand-side but capability-side: sponsors are not reducing imaging use, they are consolidating vendors to those who can demonstrate regulatory-grade standardization. That consolidation favors large CROs and specialist core labs.
Who are the leading vendors?
The market is highly concentrated and competitive, with integrated CROs, specialist imaging core labs, and device OEMs competing on standardization, AI analytics, and global site networks.
Vendor Type
Representative Players
Differentiation
Moat
Integrated CROs
IQVIA, Parexel, ICON, Syneos
End-to-end trial + imaging bundle
Site network, regulatory track record
Imaging Core Labs
Clario, Bioclinica (Clario), Medpace Imaging
Reading/analytics depth
Reader networks, AI tooling
Device OEM Services
GE HealthCare, Siemens Healthineers, Canon Medical
Modality-integrated workflows
Installed base, software lock-in
Niche Analytics
AI imaging specialists
Algorithmic differentiation
Proprietary datasets, FDA-cleared algorithms
Differentiation is shifting from acquisition capacity to analytical rigor. Vendors that own reader networks and validated AI pipelines command premium pricing, while pure acquisition providers face margin compression. Strategic partnerships with academic medical centers remain a key moat, as evidenced by Mayo Clinic-type collaborations cited in industry disclosures.
What do buyers and operators need to know? (Decision Support)
Buyers should prioritize vendors with demonstrated regulatory-grade standardization (QIBA-aligned protocols), validated AI reading tools, and multi-region site coverage. Procurement risk concentrates in reader variability and image data compliance; sponsors should contract for explicit inter-reader reproducibility metrics and audit rights.
Switching costs are high once a vendor holds the imaging charter, because protocol amendments and reader training are expensive to replicate mid-trial. Our analysis suggests sponsors should run competitive bids at the protocol-design stage rather than after site activation. Operators, conversely, should invest in decentralized imaging capabilities—remote acquisition, cloud reads—to reduce site burden and capture neurology and rare-disease trials where sites are scarce.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a 6.5–7.0% U.S. CAGR through 2029, with upside if neurology and precision-medicine imaging endpoints accelerate. The strongest counter-argument is that CRO consolidation could compress service fees faster than volume grows; however, reading and analytics is growing at 8.4%, outpacing acquisition, which protects blended margins.
Our analysis suggests the most important second-order effect is the migration of value from image acquisition to image interpretation. As AI-assisted reads become table stakes, vendors that only coordinate acquisition will be squeezed between CRO bundlers and specialized analytics firms. The winners will be those that combine reader networks, regulatory documentation, and validated algorithms.
For investors: Favor assets with reading/analytics revenue above 30% of mix and proprietary reader networks; avoid pure acquisition-service roll-ups.
For operators: Build neurology and decentralized-imaging capabilities now to capture the 8.2% CAGR segment before competitor scale locks in.
For sponsors/buyers: Negotiate reproducibility SLAs and AI-validation clauses at protocol design to avoid mid-trial switching costs.
The evidence that would change this conclusion: a sustained decline in oncology trial starts, or FDA guidance that reduces imaging-endpoint requirements in favor of liquid biopsy. Neither is currently indicated in public trial registries.
U.S. Clinical Trial Imaging Services Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
U.S. Clinical Trial Imaging Services Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.7% from 2020-2034
Segmentation
By Service Type
Clinical Trial Design & Consultation
Reading & Analytical
Operational Imaging
Project & Data Management
Others
By Modality
CT
MRI
PET
Ultrasound
X-ray
By Therapeutic Area
Oncology
Neurology
Endocrinology
Cardiology
Gastroenterology
Others
By End User
Pharmaceutical & Biotechnology
Medical Device Manufacturers
Academic & Government Research Institutes
Integrated CROs
Non-Integrated CROs
Others
By Geography
South
Texas
North Carolina
Florida
Northeast
Massachusetts
New York
Pennsylvania
West
California
Washington
Midwest
Illinois
Minnesota
Michigan
Table of Contents
1. U.S. Clinical Trial Imaging Services Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. U.S. Clinical Trial Imaging Services Market Executive Summary
2.1. Market Snapshot
3. U.S. Clinical Trial Imaging Services Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. U.S. Clinical Trial Imaging Services Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. U.S. Clinical Trial Imaging Services Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Service Type
5.1.1. Clinical Trial Design & Consultation
5.1.2. Reading & Analytical
5.1.3. Operational Imaging
5.1.4. Project & Data Management
5.1.5. Others
5.2. Analysis, Insights and Forecast - by Modality
5.2.1. CT
5.2.2. MRI
5.2.3. PET
5.2.4. Ultrasound
5.2.5. X-ray
5.3. Analysis, Insights and Forecast - by Therapeutic Area
5.3.1. Oncology
5.3.2. Neurology
5.3.3. Endocrinology
5.3.4. Cardiology
5.3.5. Gastroenterology
5.3.6. Others
5.4. Analysis, Insights and Forecast - by End User
5.4.1. Pharmaceutical & Biotechnology
5.4.2. Medical Device Manufacturers
5.4.3. Academic & Government Research Institutes
5.4.4. Integrated CROs
5.4.5. Non-Integrated CROs
5.4.6. Others
5.5. Analysis, Insights and Forecast - by Region
5.5.1. South
5.5.2. Northeast
5.5.3. West
5.5.4. Midwest
6. U.S. Clinical Trial Imaging Services Market South Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Service Type
6.1.1. Clinical Trial Design & Consultation
6.1.2. Reading & Analytical
6.1.3. Operational Imaging
6.1.4. Project & Data Management
6.1.5. Others
6.2. Analysis, Insights and Forecast - by Modality
6.2.1. CT
6.2.2. MRI
6.2.3. PET
6.2.4. Ultrasound
6.2.5. X-ray
6.3. Analysis, Insights and Forecast - by Therapeutic Area
6.3.1. Oncology
6.3.2. Neurology
6.3.3. Endocrinology
6.3.4. Cardiology
6.3.5. Gastroenterology
6.3.6. Others
6.4. Analysis, Insights and Forecast - by End User
6.4.1. Pharmaceutical & Biotechnology
6.4.2. Medical Device Manufacturers
6.4.3. Academic & Government Research Institutes
6.4.4. Integrated CROs
6.4.5. Non-Integrated CROs
6.4.6. Others
7. U.S. Clinical Trial Imaging Services Market Northeast Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Service Type
7.1.1. Clinical Trial Design & Consultation
7.1.2. Reading & Analytical
7.1.3. Operational Imaging
7.1.4. Project & Data Management
7.1.5. Others
7.2. Analysis, Insights and Forecast - by Modality
7.2.1. CT
7.2.2. MRI
7.2.3. PET
7.2.4. Ultrasound
7.2.5. X-ray
7.3. Analysis, Insights and Forecast - by Therapeutic Area
7.3.1. Oncology
7.3.2. Neurology
7.3.3. Endocrinology
7.3.4. Cardiology
7.3.5. Gastroenterology
7.3.6. Others
7.4. Analysis, Insights and Forecast - by End User
7.4.1. Pharmaceutical & Biotechnology
7.4.2. Medical Device Manufacturers
7.4.3. Academic & Government Research Institutes
7.4.4. Integrated CROs
7.4.5. Non-Integrated CROs
7.4.6. Others
8. U.S. Clinical Trial Imaging Services Market West Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Service Type
8.1.1. Clinical Trial Design & Consultation
8.1.2. Reading & Analytical
8.1.3. Operational Imaging
8.1.4. Project & Data Management
8.1.5. Others
8.2. Analysis, Insights and Forecast - by Modality
8.2.1. CT
8.2.2. MRI
8.2.3. PET
8.2.4. Ultrasound
8.2.5. X-ray
8.3. Analysis, Insights and Forecast - by Therapeutic Area
8.3.1. Oncology
8.3.2. Neurology
8.3.3. Endocrinology
8.3.4. Cardiology
8.3.5. Gastroenterology
8.3.6. Others
8.4. Analysis, Insights and Forecast - by End User
8.4.1. Pharmaceutical & Biotechnology
8.4.2. Medical Device Manufacturers
8.4.3. Academic & Government Research Institutes
8.4.4. Integrated CROs
8.4.5. Non-Integrated CROs
8.4.6. Others
9. U.S. Clinical Trial Imaging Services Market Midwest Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Service Type
9.1.1. Clinical Trial Design & Consultation
9.1.2. Reading & Analytical
9.1.3. Operational Imaging
9.1.4. Project & Data Management
9.1.5. Others
9.2. Analysis, Insights and Forecast - by Modality
9.2.1. CT
9.2.2. MRI
9.2.3. PET
9.2.4. Ultrasound
9.2.5. X-ray
9.3. Analysis, Insights and Forecast - by Therapeutic Area
9.3.1. Oncology
9.3.2. Neurology
9.3.3. Endocrinology
9.3.4. Cardiology
9.3.5. Gastroenterology
9.3.6. Others
9.4. Analysis, Insights and Forecast - by End User
9.4.1. Pharmaceutical & Biotechnology
9.4.2. Medical Device Manufacturers
9.4.3. Academic & Government Research Institutes
9.4.4. Integrated CROs
9.4.5. Non-Integrated CROs
9.4.6. Others
10. U.S. Clinical Trial Imaging Services Market Competitive Analysis
10.1. Company Profiles
10.1.1. IQVIA
10.1.1.1. Company Overview
10.1.1.2. Products
10.1.1.3. Company Financials
10.1.1.4. SWOT Analysis
10.1.2. Parexel
10.1.2.1. Company Overview
10.1.2.2. Products
10.1.2.3. Company Financials
10.1.2.4. SWOT Analysis
10.1.3. ICON
10.1.3.1. Company Overview
10.1.3.2. Products
10.1.3.3. Company Financials
10.1.3.4. SWOT Analysis
10.1.4. Syneos Health
10.1.4.1. Company Overview
10.1.4.2. Products
10.1.4.3. Company Financials
10.1.4.4. SWOT Analysis
10.1.5. Clario
10.1.5.1. Company Overview
10.1.5.2. Products
10.1.5.3. Company Financials
10.1.5.4. SWOT Analysis
10.1.6. Medpace Imaging
10.1.6.1. Company Overview
10.1.6.2. Products
10.1.6.3. Company Financials
10.1.6.4. SWOT Analysis
10.1.7. GE HealthCare
10.1.7.1. Company Overview
10.1.7.2. Products
10.1.7.3. Company Financials
10.1.7.4. SWOT Analysis
10.1.8. Siemens Healthineers
10.1.8.1. Company Overview
10.1.8.2. Products
10.1.8.3. Company Financials
10.1.8.4. SWOT Analysis
10.1.9. Canon Medical Systems
10.1.9.1. Company Overview
11. U.S. Clinical Trial Imaging Services Market Research Methodology
List of Figures
Figure 1: U.S. Clinical Trial Imaging Services Market Revenue Breakdown (Million, %) by Product 2026 & 2034
Figure 2: U.S. Clinical Trial Imaging Services Market Value Share (%), by Service Type 2026 & 2034
Figure 3: U.S. Clinical Trial Imaging Services Market Value Share (%), by Modality 2026 & 2034
Figure 4: U.S. Clinical Trial Imaging Services Market Value Share (%), by Therapeutic Area 2026 & 2034
Figure 5: U.S. Clinical Trial Imaging Services Market Value Share (%), by End User 2026 & 2034
Figure 6: U.S. Clinical Trial Imaging Services Market Share (%) by Company 2026
List of Tables
Table 1: U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by Service Type 2020 & 2034
Table 2: U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by Modality 2020 & 2034
Table 3: U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by Therapeutic Area 2020 & 2034
Table 4: U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by End User 2020 & 2034
Table 5: U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by Region 2020 & 2034
Table 6: South U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by Service Type 2020 & 2034
Table 7: South U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by Modality 2020 & 2034
Table 8: South U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by Therapeutic Area 2020 & 2034
Table 9: South U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by End User 2020 & 2034
Table 10: South U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by Country 2020 & 2034
Table 11: Texas U.S. Clinical Trial Imaging Services Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 12: North Carolina U.S. Clinical Trial Imaging Services Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 13: Florida U.S. Clinical Trial Imaging Services Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 14: Northeast U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by Service Type 2020 & 2034
Table 15: Northeast U.S. Clinical Trial Imaging Services Market Revenue Million Forecast, by Modality 2020 & 2034
Frequently Asked Questions
1. How big is the U.S. clinical trial imaging services market?
The U.S. clinical trial imaging services market was valued at 555.09 Million in 2024 and is projected to reach 768.95 Million by 2029, growing at a 6.7% CAGR from 2025 to 2029, driven by oncology, cardiology, and neurology trial demand.
2. What is the fastest-growing segment in U.S. clinical trial imaging services?
Neurology is the fastest-growing therapeutic area at 8.2% CAGR, while reading and analytical services is the fastest-growing service type at 8.4% CAGR, reflecting the shift of value from image acquisition to interpretation and AI-assisted analytics.
3. Who are the leading providers of clinical trial imaging services in the U.S.?
Leading providers include integrated CROs such as IQVIA, Parexel, ICON, and Syneos; imaging core labs like Clario and Medpace Imaging; and device OEM services from GE HealthCare and Siemens Healthineers, competing on standardization and AI analytics.
4. Why do pharmaceutical sponsors outsource clinical trial imaging?
Sponsors outsource imaging to CROs and core labs to manage regulatory complexity, reduce cost, and ensure standardized, reproducible reads across multicenter trials. There were 4,321 U.S. CROs in 2024, up 2.1% year over year.
5. What restrains growth in the U.S. clinical trial imaging services market?
High costs of advanced imaging equipment and complex regulatory compliance for image data restrain growth, particularly for smaller sponsors and academic researchers with limited budgets for extensive imaging protocols.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split, with in-depth interviews conducted across the clinical trial imaging value chain: imaging core labs, integrated and non-integrated CROs, modality OEM service divisions, academic medical center research units, and AI imaging analytics developers. Decision-maker designations interviewed include VP of Clinical Operations, Heads of Imaging Sciences, Regulatory Affairs Directors, Commercial Operations Leads, and Principal Investigators managing imaging endpoints.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Clinical Operations VPs
35%
Imaging Sciences Heads
30%
Regulatory Affairs Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Imaging Core Labs
30%
Integrated & Non-Integrated CROs
40%
Modality OEM Service Divisions
20%
AI Imaging Analytics Developers
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official databases and filings including ClinicalTrials.gov registrations, FDA guidance documents, U.S. ITC and UN Comtrade trade statistics for imaging equipment, SEC 10-K filings and annual investor presentations from CROs and device OEMs, patent databases, and standards from the Quantitative Imaging Biomarkers Alliance (QIBA) and DICOM/HL7 interoperability frameworks.
Demand Modeling & Market Sizing Triangulation
We triangulate simultaneously via a Top-Down allocation of U.S. R&D spend and trial-start volumes by therapeutic area, and a Bottom-Up build from imaging core lab capacity, per-scan pricing, and end-user consumption modeling across oncology, neurology, and cardiology trial pipelines.


 U.S. Clinical Trial Imaging Services Market