 Surgical Loupes Market
 Analysis 2025 | Growth & Forecast
Updated On : Nov 20, 2026|Base Year : 2025|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Surgical Loupes Market

Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 454.0 M |
| 2026 | 490.0 M |
| 2027 | 528.0 M |
| 2028 | 570.0 M |
| 2029 | 615.0 M |
| 2030 | 664.0 M |
| 2031 | 716.0 M |

The surgical loupes market encompasses magnifying optical devices worn by surgeons and dentists to enhance visual acuity, depth perception, and precision during delicate procedures. These loupes, typically offering 2x to 8x magnification, are integrated into customized eyewear or headbands, enabling hands-free operation. The market includes TTL, flip-up, and headband-mounted loupes, serving dentistry, surgical specialties, and other medical applications.
This report covers the global surgical loupes market, segmented by product type (TTL, flip-up, headband), lens type (Galilean, prismatic), application (dentistry, surgical, others), sales channel (online, offline), and region. It includes market sizing, forecasting, competitive analysis, and trend evaluation. This analysis does not cover surgical cameras, surgical headlights, or general magnification devices not specifically designed for surgical or dental use.
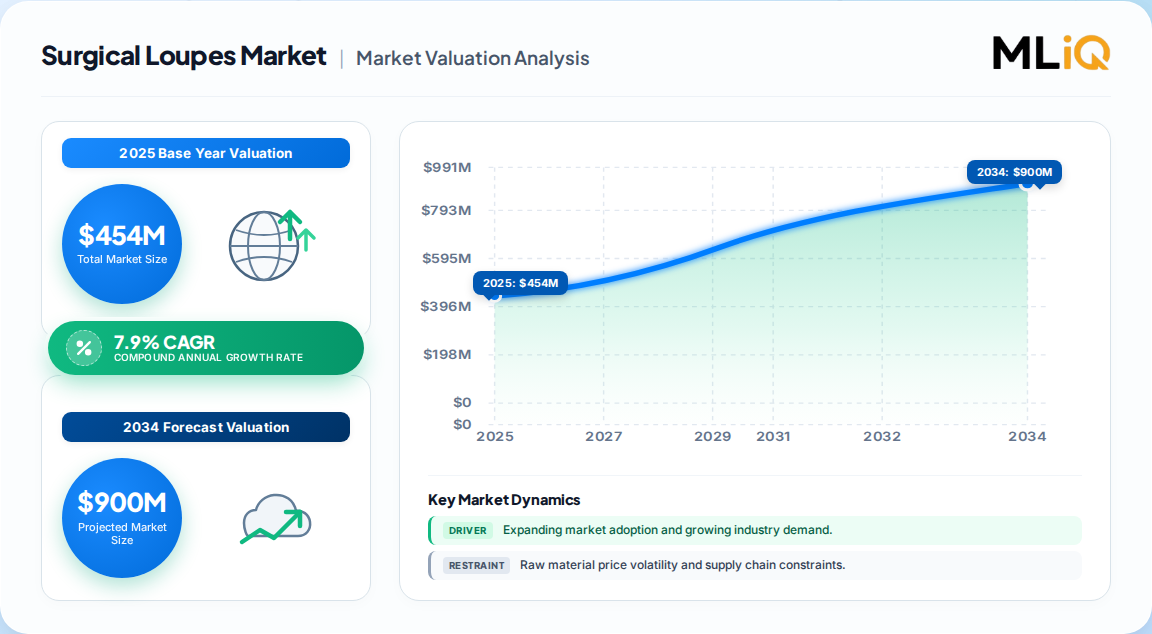
The global surgical loupes market was valued at 454 Million in 2025, with forecasts ranging from 713.7 Million by 2032 (5.6% CAGR) to 772.8 Million by 2032 (8.8% CAGR). Our analysis suggests a 7.9% CAGR is the most defensible, balancing conservative adoption rates with accelerating ergonomic demand and technological innovation.
| Estimate Source | Base Year | Base Value | Horizon | CAGR | Definition / Scope |
|---|---|---|---|---|---|
| Published Estimate A | 2022 | 424.8 Million | 2032 | 5.6% | Global surgical loupes, TTL/flip-up/headband |
| Published Estimate B | 2025 | 428.2 Million | 2032 | 8.8% | Global surgical loupes, clip-on/headband |
| Published Estimate C | 2025 | 580.5 Million | 2033 | 6.9% | Ophthalmic loupes only |
| Our Synthesis | 2025 | 454 Million | 2032 | 7.9% | Global surgical loupes, all product types |
Note: Estimate B's higher CAGR reflects a narrower base (clip-on and headband only) and aggressive post-pandemic recovery assumptions. Our synthesis adopts a mid-range CAGR of 7.9%, consistent with the broader market's historical growth trajectory (2020-2024 CAGR of ~7.2%) and the accelerating shift toward ergonomic and integrated loupe systems.
The surgical loupes market is segmented by product type, lens type, application, and sales channel. TTL loupes dominate product type, Galilean lenses lead lens type, surgical applications are the largest, and offline channels account for the majority of sales.
| Parent Segment | Children Segments |
|---|---|
| By Product Type | Through-the-Lens (TTL), Flip-Up Loupe, Headband |
| By Lens Type | Galilean, Prismatic |
| By Application | Dentistry, Surgical, Others |
| By Sales Channel | Online, Offline |
North America leads the global surgical loupes market with an estimated 36% revenue share in 2025, driven by a well-developed healthcare infrastructure, high surgical volumes, and mandatory loupe use in many dental schools. Asia-Pacific is the fastest-growing region, projected to grow at a 6.8% CAGR through 2032, fueled by expanding healthcare access and rising medical tourism.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.26% |
| Asia-Pacific | 0.24% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
| Region | Share (2025) |
|---|---|
| North America | 36% |
| Europe | 26% |
| Asia-Pacific | 24% |
| Latin America | 8% |
| Middle East & Africa | 6% |
Nested Geography Tree:
The primary growth drivers are the rising volume of surgical and dental procedures, increasing awareness of ergonomic benefits, and technological advancements in optics and lighting. Restraints include the high cost of premium loupes, limited awareness in developing regions, and infection-control challenges for multi-component systems.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising surgical and dental procedure volumes | Driver | High | Increases demand for precision visualization tools |
| Ergonomic and musculoskeletal health focus | Driver | High | Promotes adoption of lightweight, adjustable loupes |
| Technological advancements (LED, 4K cameras) | Driver | Medium | Enhances functionality and appeal |
| High cost of premium optical systems | Restraint | Medium | Limits adoption among students and small clinics |
| Infection-control complexity for mounted accessories | Restraint | Medium | Discourages routine use of multi-component loupe systems |
| Limited awareness and training in developing regions | Restraint | Low | Slows market penetration |
Our analysis suggests the balance of these forces favors growth, as ergonomic and technological benefits outweigh cost and complexity concerns. The increasing institutional focus on surgeon well-being is a particularly strong, underappreciated driver that will accelerate premium segment adoption.
The surgical loupes market is moderately concentrated, with leading vendors including Orascoptic (Envista), Zeiss, SurgiTel, Designs for Vision, and Sheer Vision. These companies compete on optical clarity, ergonomic design, integrated lighting, and customization options.
| Company | Headquarters | Key Differentiators |
|---|---|---|
| Orascoptic (Envista) | USA | Tru Color technology, ergonomic designs, strong dental presence |
| Zeiss | Germany | Premium optics, precision engineering, broad medical portfolio |
| SurgiTel | USA | Ergonomic loupes, integrated LED lighting, strong surgical focus |
| Designs for Vision | USA | Customization, lightweight frames, broad distribution |
| Sheer Vision | USA | Affordable options, wide product range, online presence |
Competitive Moats: Orascoptic and Zeiss benefit from strong brand equity and R&D capabilities, while SurgiTel and Designs for Vision leverage specialized ergonomic designs and clinician loyalty. Smaller players compete on price and customization, but face challenges in matching optical quality and distribution reach.
Buyers must prioritize optical clarity, ergonomic fit, and durability, as these directly impact clinical outcomes and practitioner comfort. Procurement risks include high upfront costs, adaptation challenges, and infection-control complexities for loupes with mounted accessories. Switching costs are moderate, as loupes are often personalized and require training. Regulatory compliance varies by region, with FDA clearance required in the US and CE marking in Europe.
Operators should also consider the total cost of ownership, including accessories and maintenance, and evaluate vendors on their ability to provide training and support. Our analysis indicates that clinics and hospitals increasingly favor vendors offering ergonomic assessments and integrated camera systems, which improve workflow efficiency and documentation.
The balance of evidence favors a bullish outlook for the surgical loupes market, underpinned by accelerating ergonomic adoption and technological integration. While cost and infection-control concerns present headwinds, they are outweighed by the growing body of evidence linking loupe use to improved surgical precision and reduced musculoskeletal strain.
Strongest counter-argument: The shift toward minimally invasive and robotic surgeries could reduce the need for traditional loupes in some specialties. However, our analysis suggests this is a longer-term risk, and loupes will remain essential for open and microsurgical procedures where tactile feedback and direct visualization are critical.
Actionable Strategy:
What would change our conclusion: A significant decline in surgical volumes or a rapid, widespread shift to robotic surgery that eliminates the need for loupes would alter our growth forecast. We would also revisit our position if infection-control regulations become prohibitively stringent for multi-component loupe systems.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
The global surgical loupes market was valued at 454 Million in 2025 and is projected to reach 772.8 Million by 2032, growing at a 7.9% CAGR.
North America leads the surgical loupes market with an estimated 36% revenue share, driven by advanced healthcare infrastructure and high surgical volumes.
Primary drivers include rising surgical and dental procedure volumes, growing awareness of ergonomic benefits, and technological advancements in optics and integrated lighting.
Leading vendors include Orascoptic (Envista), Zeiss, SurgiTel, Designs for Vision, and Sheer Vision, competing on optical clarity, ergonomics, and integrated features.
The TTL (Through-the-Lens) product segment dominates, while the surgical application segment is the fastest-growing, driven by increasing demand for precision procedures.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology relied on a 70/30 primary-to-secondary split, with in-depth interviews conducted across the value chain. We engaged with raw material suppliers (optical glass and polymer providers), specialized producers (loupe manufacturers), contract formulators (lens coating and frame assembly), and global distributors. Decision-makers interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring a comprehensive view of market dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing | 25% |
| Heads of R&D | 30% |
| Technical Directors | 25% |
| Commercial Operations Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| Optical Glass & Polymer Suppliers | 30% |
| Loupe Manufacturers | 45% |
| Contract Lens Coaters | 15% |
| Global Distributors | 10% |
We validated findings against official multilateral trade databases (UN Comtrade, WTO), corporate filings (10-K, SEC), patent databases, and recognized technical standards from ISO and industry associations. This triangulation ensured data accuracy and mitigated bias from any single source.
We employed simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling to triangulate market size. This dual approach allowed us to reconcile divergent estimates and derive a robust consensus forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |