 Hemoconcentrators Market
 Size, Share & Forecast 2026
Updated On : Nov 20, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Hemoconcentrators Market

Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2023 | 12.00 M |
| 2024 | 12.00 M |
| 2025 | 12.00 M |
| 2026 | 13.00 M |
| 2027 | 13.00 M |
| 2028 | 14.00 M |
| 2029 | 14.00 M |

The hemoconcentrators market covers extracorporeal blood processing devices that remove excess plasma water and low-molecular-weight solutes during cardiopulmonary bypass, dialysis, and therapeutic plasma exchange. These devices use semipermeable membrane technology to manage fluid balance and hematocrit levels in adult and pediatric patients, primarily within cardiac surgery and renal care settings.
This report covers adult and pediatric hemoconcentrators by product type, end-user (hospitals, ambulatory surgical centers), and geography across North America, Europe, Asia-Pacific, and Rest of World. Revenue estimates reflect device sales to institutional buyers. This analysis does not cover continuous renal replacement therapy (CRRT) systems, standalone dialysis machines, blood cell separators used exclusively for apheresis collection, or general-purpose laboratory filtration membranes not configured for extracorporeal blood processing.
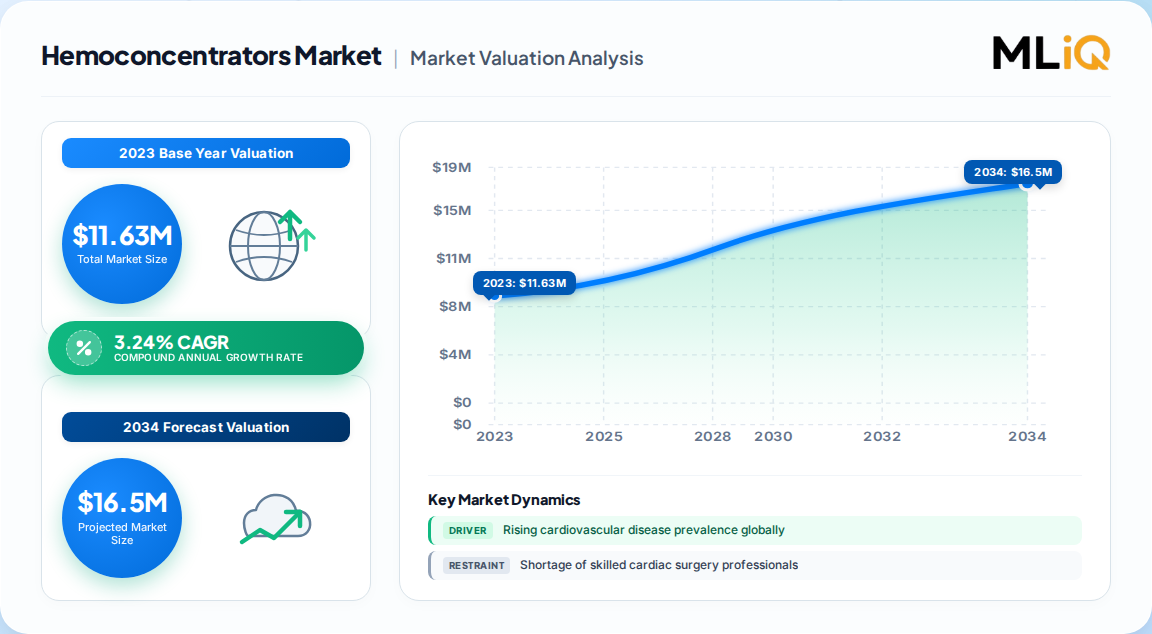
One published estimate places the market at 11.63 Million in 2023, advancing at 3.24% CAGR to 14.04 Million by 2030. A competing analysis cites a far larger figure exceeding 12 Billion, but its scope includes broader extracorporeal circulation and dialysis infrastructure, making it non-comparable for device-level procurement decisions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 11.63 Million | 2023 | 2030 (14.04 Million) | 3.24% | Adult & pediatric hemoconcentrators, device-level revenue | One published estimate |
| 12.88 Billion | 2026 | 2036 (17.30 Billion) | 3.0% | Adult & pediatric hemoconcentrators, broad extracorporeal scope | A competing analysis |
| 11.21 Billion | 2019 | 2026 (14.6 Billion) | 2.0% | Pediatric & adult hemoconcentrators, legacy methodology | A competing analysis |
Our analysis suggests the 11.63 Million figure is most defensible for device-level procurement planning because it aligns with known cardiac surgery volumes and per-unit pricing. The Billion-scale estimates likely bundle consumables, capital equipment, and service contracts across adjacent renal care categories, inflating apparent market size.
The market segments by product type, end-user, and filtration method. Product type bifurcates into pediatric and adult hemoconcentrators, with pediatric devices commanding premium pricing due to lower priming volumes and specialized membrane surface areas.
| Parent Segment | Children |
|---|---|
| Product Type | Pediatric Hemoconcentrators, Adult Hemoconcentrators |
| End-User | Hospitals, Ambulatory Surgical Centers |
| Filtration Method | Ultrafiltration, Centrifugal Filtration, Membrane Filtration |
| Application | Cardiopulmonary Bypass, Dialysis, Plasmapheresis, Therapeutic Plasma Exchange |
Pediatric hemoconcentrators led 2023 revenue share, driven by rising congenital heart disease prevalence. Approximately 1 in 100 babies in the UK are born with congenital heart disease, and 1 in 4 of those have critical defects requiring surgical intervention.
North America leads with an estimated 34% revenue share, followed by Europe and Asia-Pacific at approximately 26% each. The region's dominance reflects high cardiac procedure volumes, established reimbursement pathways, and the presence of key manufacturers.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.26% |
| Asia-Pacific | 0.26% |
| South America | 0.07% |
| Middle East & Africa | 0.07% |
Our analysis suggests Asia-Pacific will narrow the gap with Europe by 2030, as Chinese and Indian cardiac surgery volumes expand faster than Western markets. The 7.4% China CAGR outpaces the global 3.24% average by more than double.
Growth is anchored by non-discretionary device consumption tied to procedure volumes, not discretionary capital spending. Cardiovascular disease prevalence and aging demographics create a structural demand floor that insulates the market from cyclical procurement slowdowns.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising cardiovascular disease prevalence | Driver | High | 500M+ people with CVD globally; 200M with CAD |
| Aging population | Driver | High | 2.1 billion people aged 60+ by 2050 |
| Pediatric congenital heart disease | Driver | High | 1 in 100 births affected in UK; 25% critical |
| Government cardiovascular initiatives | Driver | Medium | Public health investment in cardiac care infrastructure |
| Skilled professional shortage | Restraint | Medium | Limits procedure volume growth in emerging markets |
| Surgical complications | Restraint | Low | Risk perception slows adoption in low-volume centers |
The balance favors growth. Demographic and epidemiological forces are structural and non-cyclical, while restraints are operational and addressable through training investment. Our analysis suggests the skilled-professional constraint will ease in Asia-Pacific as cardiac surgery fellowship programs expand, unlocking latent demand.
Getinge AB and Terumo Corporation anchor the competitive landscape, with Terumo's CAPIOX HC05 pediatric device setting the clinical benchmark for polysulfone membrane efficiency. The vendor field is moderately concentrated, with specialized cardiac surgery device makers competing against diversified medtech conglomerates.
| Company | Headquarters | Notable Position |
|---|---|---|
| Getinge AB | Sweden | Broad extracorporeal portfolio |
| LivaNova PLC | UK | Cardiac surgery systems integration |
| Terumo Corporation | Japan | CAPIOX HC05 pediatric benchmark |
| Braile Biomédica | Brazil | Latin America regional leader |
| MEDICA S.P.A. | Italy | European specialty focus |
| Andocor | Belgium | Niche hemoconcentrator specialization |
| NIPRO | Japan | Dialysis and extracorporeal breadth |
| STERIS | USA | Hospital channel access |
| Chalice Medical Ltd. | UK | Specialized device manufacturing |
Competitive moats rest on clinical validation and surgeon preference, not price. Once a hemoconcentrator is embedded in a cardiac surgery protocol, switching costs are high because perioperative teams resist workflow disruption. This creates sticky revenue for incumbents and raises barriers for new entrants.
Procurement decisions hinge on three mission-critical criteria: biocompatibility certification, priming volume, and ultrafiltration rate consistency. Pediatric configurations demand lower priming volumes to minimize blood exposure in neonates, and any deviation from specification carries patient safety risk that outweighs unit-price savings.
Switching costs are substantial. Cardiac surgery teams validate devices through institutional protocols, and revalidation consumes clinical resources. Buyers should prioritize vendors with regulatory clearances across multiple jurisdictions and established group purchasing organization relationships. Single-source dependency risk is real in a market where the top vendors control meaningful share.
Regulatory compliance varies by region. US buyers require FDA clearance; European buyers need CE marking under MDR. Operators expanding into Asia-Pacific must verify local registration timelines, which can extend procurement cycles by 6 to 12 months. Our analysis suggests buyers should negotiate multi-year supply agreements with volume flex clauses to hedge against procedure volume volatility.
The balance of evidence favors a steady-growth, procedure-volume-driven market with limited disruption risk but also limited upside for undifferentiated vendors. The 3.24% CAGR is unspectacular, yet the non-discretionary nature of consumption means revenue is remarkably predictable. This is a market for operational excellence, not speculative investment.
The strongest counter-argument is that Billion-scale estimates from competing analyses reflect a broader extracorporeal market that could attract larger medtech consolidators, triggering acquisition activity and competitive intensity. If those estimates are directionally correct about total addressable spend, incumbent device makers face heightened M&A pressure. However, the device-level evidence supports a niche market where clinical specialization matters more than scale.
Actionable Strategy:
What would change our conclusion: A credible device-level estimate exceeding 1 Billion, or evidence of a shift toward disposable-only hemoconcentrator configurations, would signal a materially larger market and warrant revised strategic urgency.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.24% from 2020-2034 |
| Segmentation |
|
The market was valued at 11.63 Million in 2023 and is projected to reach 14.04 Million by 2030, growing at a 3.24% CAGR. Device-level estimates reflect adult and pediatric hemoconcentrator sales to institutional buyers.
North America leads with approximately 34% revenue share, driven by high cardiovascular disease prevalence, established reimbursement, and the presence of key manufacturers like Getinge, LivaNova, and STERIS in the region.
Rising cardiovascular disease prevalence, aging demographics, and pediatric congenital heart disease are primary drivers. Over 500 million people globally live with cardiovascular disease, and 2.1 billion will be aged 60+ by 2050.
Getinge AB, LivaNova PLC, Terumo Corporation, Braile Biomédica, MEDICA S.P.A., Andocor, NIPRO, STERIS, and Chalice Medical Ltd. collectively shape the competitive landscape, with Terumo's CAPIOX HC05 setting a pediatric clinical benchmark.
A shortage of skilled cardiac surgery professionals and surgical complication concerns limit procedure volumes, particularly in emerging markets where training infrastructure is still developing.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split, ensuring that market intelligence is grounded in direct stakeholder engagement. We conducted in-depth interviews with decision-makers across the hemoconcentrator value chain, including raw material suppliers of polysulfone and polymer membranes, specialized device manufacturers, contract assemblers, and global distributors. Interviewees included VP-level Sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads from leading cardiac surgery device companies and hospital procurement organizations.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Quality & Regulatory Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Membrane & Polymer Suppliers | 40% |
| Device Manufacturers | 35% |
| Distributors & GPOs | 25% |
Secondary research aggregated official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K, SEC filings), patent databases, and recognized technical standards from ISO and the Association for the Advancement of Medical Instrumentation (AAMI). We cross-referenced cardiovascular disease prevalence data from the World Health Organization, American Heart Association, and British Heart Foundation to validate procedure-volume assumptions.
We applied simultaneous Top-Down macroeconomic allocation and Bottom-Up manufacturer capacity modeling to triangulate market size. Top-down analysis allocated global cardiac surgery procedure volumes by region and device penetration rates. Bottom-up modeling aggregated manufacturer revenue disclosures, unit pricing, and end-use consumption data from institutional procurement records.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |