Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
ACL Reconstruction Market: 2025 Global Outlook & Forecast
ACL Reconstruction Market: 2025 Global Outlook & Forecast
ACL Reconstruction Market
ACL Reconstruction Market: 2025 Global Outlook & Forecast
ACL Reconstruction Market by Procedure Type (Anatomic Reconstruction, Non-Anatomic/Traditional Reconstruction), by Graft Type (Autograft, Allograft, Synthetic Graft, Biologic Scaffold), by Fixation Type (Interference Screws, Cortical Buttons, Staples, Other Fixation), by Product Type (Fixation Devices, Arthroscopic Instruments, Graft Preparation Devices, Biologic Implants), by End User (Hospitals, Ambulatory Surgery Centers, Specialty Orthopedic Clinics), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 0
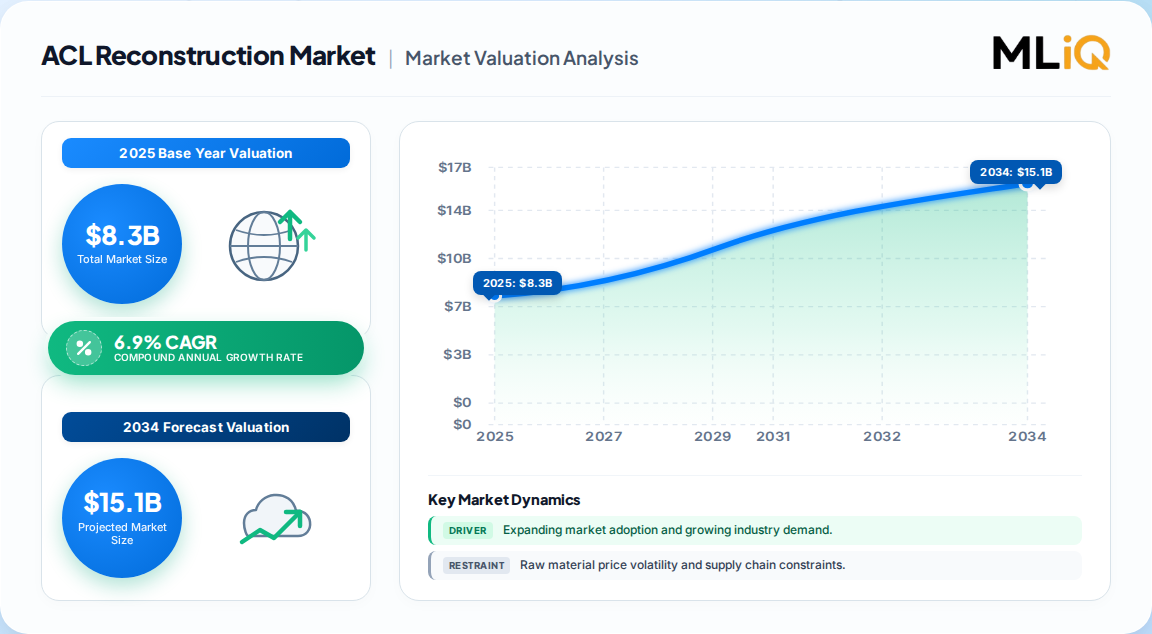
The global ACL reconstruction market was valued at USD 8.3 billion in 2025 across all procedure, graft, fixation, and end-user categories.
Forecast growth to USD 15.1 billion by 2035 implies a 6.9% CAGR, with the 2026 base assessed at approximately USD 8.8 billion.
Anatomic reconstruction dominates procedure mix at an estimated 68.7% share, reflecting surgeons' preference for individualized joint anatomy restoration.
North America holds the largest regional share at roughly 40.3%, while Asia Pacific is the fastest-growing region.
Hospitals remain the leading end-user setting, though ambulatory surgery centers are the fastest-expanding channel.
Leading players include Stryker, Smith+Nephew, Johnson & Johnson (DePuy Synthes), Zimmer Biomet, CONMED, and Arthrex.
Why this matters for decision-makers: With anatomic techniques and biologic scaffolds outpacing the core procedure market, vendors that anchor portfolios on traditional non-anatomic hardware risk margin compression as value migrates to differentiated biologics and AI-assisted planning.
ACL Reconstruction Market Size (In Billion)
15.0B
10.0B
5.0B
0
8.300 B
2025
8.870 B
2026
9.480 B
2027
10.14 B
2028
10.84 B
2029
11.59 B
2030
12.39 B
2031
ACL Reconstruction Market Size (In Billion)
Year
Market Size
2025
8.300 B
2026
8.870 B
2027
9.480 B
2028
10.14 B
2029
10.84 B
2030
11.59 B
2031
12.39 B
What is the ACL Reconstruction Market?
The ACL reconstruction market covers surgical products and procedures that replace a torn anterior cruciate ligament with a graft, including fixation devices, graft harvest and preparation tools, arthroscopic instrumentation, and biologic scaffolds used to restore knee stability. It spans hospitals, ambulatory surgery centers, and specialty orthopedic clinics across all major regions.
Scope: what this report covers and excludes
This analysis covers the global ACL reconstruction market across procedure type (anatomic and non-anatomic/traditional reconstruction), graft type (autograft, allograft, synthetic, and biologic scaffolds), fixation type (interference screws, cortical buttons, and others), product type, and end user (hospitals, ambulatory surgery centers, and others) for the 2025–2035 horizon. This analysis does not cover posterior cruciate ligament repair, multi-ligament reconstruction, knee arthroplasty, or standalone rehabilitation and physical therapy services.
How big is the market for ACL Reconstruction Market?
The most defensible sizing places the global ACL reconstruction market at USD 8.3 billion in 2025, growing to USD 15.1 billion by 2035 at 6.9% CAGR. Competing estimates diverge sharply because they capture different scope boundaries.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 8.3 Billion
2025
2035
6.9%
ACL reconstruction procedures and products, global
One published estimate
USD 8.8 Billion
2026
2035
6.9%
Same scope, 2026 base
Derived from stated base and CAGR
USD 12.3 Billion
2022
2030
7.2%
Cruciate ligament repair procedures (ACL + PCL), global
A competing analysis
USD 17.4 Billion
2026
2031
8.41%
Cruciate ligament repair procedures, broader procedure base
A competing analysis
Our analysis suggests the 6.9% figure is the most defensible for pure ACL reconstruction because it isolates the ACL procedure rather than bundling PCL and multi-ligament work. The higher-growth estimates include adjacent cruciate procedures and biologic scaffolds, inflating the base and CAGR.
How is the market segmented?
The ACL reconstruction market segments along procedure technique, graft material, fixation hardware, product category, and care setting — with anatomic reconstruction and autograft tissue each commanding the largest share.
Hospitals, Ambulatory Surgery Centers, Specialty Orthopedic Clinics
Anatomic reconstruction is projected to hold 68.7% share by 2035, reflecting its superior restoration of native joint kinematics. Among grafts, autograft leads on share while biologic scaffolds show the steepest growth trajectory.
Which region leads in ACL Reconstruction Market?
North America leads the global ACL reconstruction market with approximately 40.3% share, driven by high sports-injury prevalence, advanced surgical infrastructure, and strong public and private reimbursement.
ACL Reconstruction Market Regional Market Share
Loading chart...
ACL Reconstruction Market Regional Market Share
Region
Market Share (%)
North America
0.4%
Europe
0.24%
Asia-Pacific
0.26%
Latin America
0.05%
Middle East & Africa
0.05%
Parent
Children
North America
United States, Canada, Mexico
Europe
Germany, UK, France, Italy, Spain
Asia Pacific
China, Japan, India, South Korea, Australia
Latin America
Brazil, Argentina, Mexico
Middle East & Africa
Saudi Arabia, UAE, South Africa
Our analysis suggests the North American lead is structural rather than cyclical: the U.S. records an estimated 400,000 ACL reconstructions annually, and expanded Medicare outpatient coverage pulls volume toward ambulatory centers. Asia Pacific's faster growth reflects rising surgical access and sports participation, but per-capita procedure penetration remains well below Western levels — implying a longer, multi-decade runway.
What is driving growth — and what is holding it back?
Growth is driven by rising sports-injury incidence, the shift to minimally invasive arthroscopy, and expanding outpatient surgical capacity; it is constrained by procedure cost, limited payer coverage in low-income markets, and surgeon skill gaps.
Factor
Direction
Evidence strength
Mechanism
Rising knee ligament injuries
Driver
High
~75 per 100,000 person-years ACL tear rate; 16–39 age peak
Minimally invasive preference
Driver
High
All-inside arthroscopy reduces pain and hospital stay
Outpatient capacity expansion
Driver
High
275 orthopedic procedures removed from Medicare inpatient-only list
Up to 98% MRI diagnostic accuracy; tunnel placement guidance
Procedure cost and payer limits
Restraint
High
Uninsured U.S. bills of USD 20,000–50,000
Revision and failure risk
Restraint
Medium
Technical error drives 60–70% of graft ruptures
Regulatory pathways for biologics
Restraint
Medium
Stringent approval requirements in North America and EU
The balance of evidence favors the drivers: surgical volumes have climbed roughly 2.15% annually even as injury incidence eased after 2010, indicating that expanded reimbursement and return-to-sport demand, not raw injury counts, now govern market growth.
Who are the leading vendors?
The competitive landscape is medium-concentration, led by diversified orthopedic giants and arthroscopy specialists competing on fixation systems, biologic scaffolds, and procedural workflow.
OrthoGrid and THINK Surgical AI guidance alliances
CONMED Corporation
Arthroscopic instrumentation
Value-focused procedural tooling
Arthrex
All-inside fixation and pediatric systems
TightRope adjustable-loop button leadership
Our analysis suggests moats are shifting from hardware breadth to procedural ecosystems — AI planning, biologic scaffolds, and outpatient workflow integration. Vendors without a differentiated biologic or navigation asset face commoditization in interference screws, where Chinese volume-based procurement has cut knee-implant prices by 82%.
What do buyers and operators need to know?
Procurement decisions in this market hinge on clinical outcomes evidence, total procedural cost, and regulatory clearance for biologic components. Buyers should weight re-tear rates and return-to-sport timelines as heavily as device price, since revision procedures carry substantial downstream cost. Switching costs are moderate for fixation hardware but high for instrument trays and surgeon training programs, creating stickiness around incumbent arthroscopy platforms.
Regulatory compliance is a critical filter: biologic scaffolds face stringent approval pathways in North America and the EU, and expanded indications — such as pediatric and partial-tear clearances — materially change addressable demand. Operators expanding into ambulatory surgery centers must verify reimbursement coverage and surgeon credentialing before committing capital, as payer policy remains the single largest swing factor in procedure volume.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a cautiously bullish outlook: 6.9% CAGR is credible for the core ACL reconstruction market, but the real value creation lies in the faster-growing sub-segments — biologic scaffolds, cortical buttons, and ambulatory surgery centers — which outpace the headline rate.
The strongest counter-argument is that rising procedure costs and payer tightening could suppress volumes in price-sensitive markets, particularly if reimbursement reforms like China's volume-based procurement spread. However, expanded outpatient coverage and return-to-sport demand have historically offset cost pressure, and injury incidence remains structurally elevated among young athletes.
Our analysis suggests the most important second-order effect is the migration of value from commodity fixation hardware toward differentiated biologics and AI-guided planning — a shift that will reward vendors with clinical evidence and penalize those reliant on legacy screw-based portfolios.
Vendors should prioritize biologic scaffold and AI planning portfolios to capture premium pricing as fixation hardware commoditizes.
Operators should build ambulatory surgery center capacity tied to reimbursement-verified procedures to capture the fastest-growing care setting.
Investors should monitor regulatory label expansions for biologic implants as leading indicators of addressable market step-changes.
What would change our conclusion: a sustained reimbursement contraction in North America, or clinical evidence showing biologic scaffolds underperform autograft on re-tear rates, would materially reduce our growth conviction.
ACL Reconstruction Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
ACL Reconstruction Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.9% from 2020-2034
Segmentation
By Procedure Type
Anatomic Reconstruction
Non-Anatomic/Traditional Reconstruction
By Graft Type
Autograft
Allograft
Synthetic Graft
Biologic Scaffold
By Fixation Type
Interference Screws
Cortical Buttons
Staples
Other Fixation
By Product Type
Fixation Devices
Arthroscopic Instruments
Graft Preparation Devices
Biologic Implants
By End User
Hospitals
Ambulatory Surgery Centers
Specialty Orthopedic Clinics
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. ACL Reconstruction Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. ACL Reconstruction Market Executive Summary
2.1. Market Snapshot
3. ACL Reconstruction Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. ACL Reconstruction Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. ACL Reconstruction Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Procedure Type
5.1.1. Anatomic Reconstruction
5.1.2. Non-Anatomic/Traditional Reconstruction
5.2. Analysis, Insights and Forecast - by Graft Type
5.2.1. Autograft
5.2.2. Allograft
5.2.3. Synthetic Graft
5.2.4. Biologic Scaffold
5.3. Analysis, Insights and Forecast - by Fixation Type
5.3.1. Interference Screws
5.3.2. Cortical Buttons
5.3.3. Staples
5.3.4. Other Fixation
5.4. Analysis, Insights and Forecast - by Product Type
5.4.1. Fixation Devices
5.4.2. Arthroscopic Instruments
5.4.3. Graft Preparation Devices
5.4.4. Biologic Implants
5.5. Analysis, Insights and Forecast - by End User
5.5.1. Hospitals
5.5.2. Ambulatory Surgery Centers
5.5.3. Specialty Orthopedic Clinics
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. ACL Reconstruction Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Procedure Type
6.1.1. Anatomic Reconstruction
6.1.2. Non-Anatomic/Traditional Reconstruction
6.2. Analysis, Insights and Forecast - by Graft Type
6.2.1. Autograft
6.2.2. Allograft
6.2.3. Synthetic Graft
6.2.4. Biologic Scaffold
6.3. Analysis, Insights and Forecast - by Fixation Type
6.3.1. Interference Screws
6.3.2. Cortical Buttons
6.3.3. Staples
6.3.4. Other Fixation
6.4. Analysis, Insights and Forecast - by Product Type
6.4.1. Fixation Devices
6.4.2. Arthroscopic Instruments
6.4.3. Graft Preparation Devices
6.4.4. Biologic Implants
6.5. Analysis, Insights and Forecast - by End User
6.5.1. Hospitals
6.5.2. Ambulatory Surgery Centers
6.5.3. Specialty Orthopedic Clinics
7. ACL Reconstruction Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Procedure Type
7.1.1. Anatomic Reconstruction
7.1.2. Non-Anatomic/Traditional Reconstruction
7.2. Analysis, Insights and Forecast - by Graft Type
7.2.1. Autograft
7.2.2. Allograft
7.2.3. Synthetic Graft
7.2.4. Biologic Scaffold
7.3. Analysis, Insights and Forecast - by Fixation Type
7.3.1. Interference Screws
7.3.2. Cortical Buttons
7.3.3. Staples
7.3.4. Other Fixation
7.4. Analysis, Insights and Forecast - by Product Type
7.4.1. Fixation Devices
7.4.2. Arthroscopic Instruments
7.4.3. Graft Preparation Devices
7.4.4. Biologic Implants
7.5. Analysis, Insights and Forecast - by End User
7.5.1. Hospitals
7.5.2. Ambulatory Surgery Centers
7.5.3. Specialty Orthopedic Clinics
8. ACL Reconstruction Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Procedure Type
8.1.1. Anatomic Reconstruction
8.1.2. Non-Anatomic/Traditional Reconstruction
8.2. Analysis, Insights and Forecast - by Graft Type
8.2.1. Autograft
8.2.2. Allograft
8.2.3. Synthetic Graft
8.2.4. Biologic Scaffold
8.3. Analysis, Insights and Forecast - by Fixation Type
8.3.1. Interference Screws
8.3.2. Cortical Buttons
8.3.3. Staples
8.3.4. Other Fixation
8.4. Analysis, Insights and Forecast - by Product Type
8.4.1. Fixation Devices
8.4.2. Arthroscopic Instruments
8.4.3. Graft Preparation Devices
8.4.4. Biologic Implants
8.5. Analysis, Insights and Forecast - by End User
8.5.1. Hospitals
8.5.2. Ambulatory Surgery Centers
8.5.3. Specialty Orthopedic Clinics
9. ACL Reconstruction Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Procedure Type
9.1.1. Anatomic Reconstruction
9.1.2. Non-Anatomic/Traditional Reconstruction
9.2. Analysis, Insights and Forecast - by Graft Type
9.2.1. Autograft
9.2.2. Allograft
9.2.3. Synthetic Graft
9.2.4. Biologic Scaffold
9.3. Analysis, Insights and Forecast - by Fixation Type
9.3.1. Interference Screws
9.3.2. Cortical Buttons
9.3.3. Staples
9.3.4. Other Fixation
9.4. Analysis, Insights and Forecast - by Product Type
9.4.1. Fixation Devices
9.4.2. Arthroscopic Instruments
9.4.3. Graft Preparation Devices
9.4.4. Biologic Implants
9.5. Analysis, Insights and Forecast - by End User
9.5.1. Hospitals
9.5.2. Ambulatory Surgery Centers
9.5.3. Specialty Orthopedic Clinics
10. ACL Reconstruction Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Procedure Type
10.1.1. Anatomic Reconstruction
10.1.2. Non-Anatomic/Traditional Reconstruction
10.2. Analysis, Insights and Forecast - by Graft Type
10.2.1. Autograft
10.2.2. Allograft
10.2.3. Synthetic Graft
10.2.4. Biologic Scaffold
10.3. Analysis, Insights and Forecast - by Fixation Type
10.3.1. Interference Screws
10.3.2. Cortical Buttons
10.3.3. Staples
10.3.4. Other Fixation
10.4. Analysis, Insights and Forecast - by Product Type
10.4.1. Fixation Devices
10.4.2. Arthroscopic Instruments
10.4.3. Graft Preparation Devices
10.4.4. Biologic Implants
10.5. Analysis, Insights and Forecast - by End User
Table 16: Europe ACL Reconstruction Market Revenue Billion Forecast, by Procedure Type 2020 & 2034
Frequently Asked Questions
1. How big is the ACL reconstruction market in 2025?
The global ACL reconstruction market was valued at USD 8.3 billion in 2025 and is forecast to reach USD 15.1 billion by 2035, growing at a 6.9% CAGR over the 2026–2035 period.
2. Which region dominates ACL reconstruction procedures?
North America leads with roughly 40.3% share, supported by high sports-injury prevalence, advanced surgical infrastructure, and strong reimbursement. Asia Pacific is the fastest-growing region as surgical access expands.
3. What is the fastest-growing segment in ACL reconstruction?
Biologic scaffolds and cortical button fixation are growing fastest, while ambulatory surgery centers expand quicker than hospitals as outpatient orthopedic capacity increases and reimbursement rules loosen.
4. Who are the leading ACL reconstruction market companies?
Key players include Stryker, Smith+Nephew, Johnson & Johnson (DePuy Synthes), Zimmer Biomet, CONMED, Arthrex, and B. Braun, competing on fixation systems, biologic scaffolds, and AI-assisted surgical planning.
Expanded payer reimbursement, minimally invasive arthroscopy, and patient demand for faster return-to-sport timelines have driven surgical volumes up roughly 2.15% annually even as raw injury incidence eased after 2010.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the orthopedic value chain, including implant and fixation device manufacturers, biologic scaffold developers, arthroscopy instrument suppliers, and global orthopedic distributors. Decision-makers interviewed included VP-level Sourcing leads, Heads of Orthopedic R&D, Technical Directors for surgical devices, and Commercial Operations Leads across hospital and ambulatory surgery channels.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Leads
35%
Orthopedic R&D Heads
30%
Commercial Operations Leads
20%
Regulatory Affairs Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Implant & Fixation Device Manufacturers
40%
Biologic Scaffold Developers
25%
Arthroscopy Instrument Suppliers
20%
Orthopedic Distributors
15%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and SEC 10-K disclosures from leading orthopedic vendors, patent databases covering fixation and biologic scaffold technologies, and recognized standards bodies including ISO and ASTM surgical implant standards. Procedure volume benchmarks are cross-checked against national arthroplasty and sports-injury registries.
Demand Modeling & Market Sizing Triangulation
Market sizing triangulates top-down macroeconomic and segment allocation against bottom-up manufacturer capacity, device pricing, and end-use procedure consumption modeling. Procedure incidence data, reimbursement coverage, and average selling prices are reconciled to produce a validated base-year value and compound forecast.


 ACL Reconstruction Market