 PCR Test Tubes Market
: Size, Trends & Forecast 2026
Updated On : Nov 20, 2026|Base Year : 2025

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 PCR Test Tubes Market

Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 2.910 B |
| 2026 | 3.170 B |
| 2027 | 3.450 B |
| 2028 | 3.760 B |
| 2029 | 4.090 B |
| 2030 | 4.450 B |
| 2031 | 4.840 B |

The PCR test tubes market covers single-use plastic vessels—typically 0.1 mL to 0.5 mL—used to hold reaction mixtures during polymerase chain reaction amplification. These consumables must ensure thermal conductivity, optical clarity, and nuclease-free integrity. Demand is driven by clinical diagnostics, research laboratories, and molecular biology workflows across hospital and diagnostic settings.
This report covers PCR test tubes by type (V-bottom, cylindrical), volume (0.1 mL, 0.2 mL, 0.5 mL, others), and application (hospitals, clinics, laboratories, diagnostic centers). It spans North America, Europe, Asia-Pacific, South America, and Middle East & Africa.
Excludes: PCR reagents, thermal cyclers, PCR microplates, pipette tips, and other molecular diagnostics consumables. This analysis does not cover adjacent markets such as PCR cosmetic tubes (recycled-content packaging) or PCR machines.
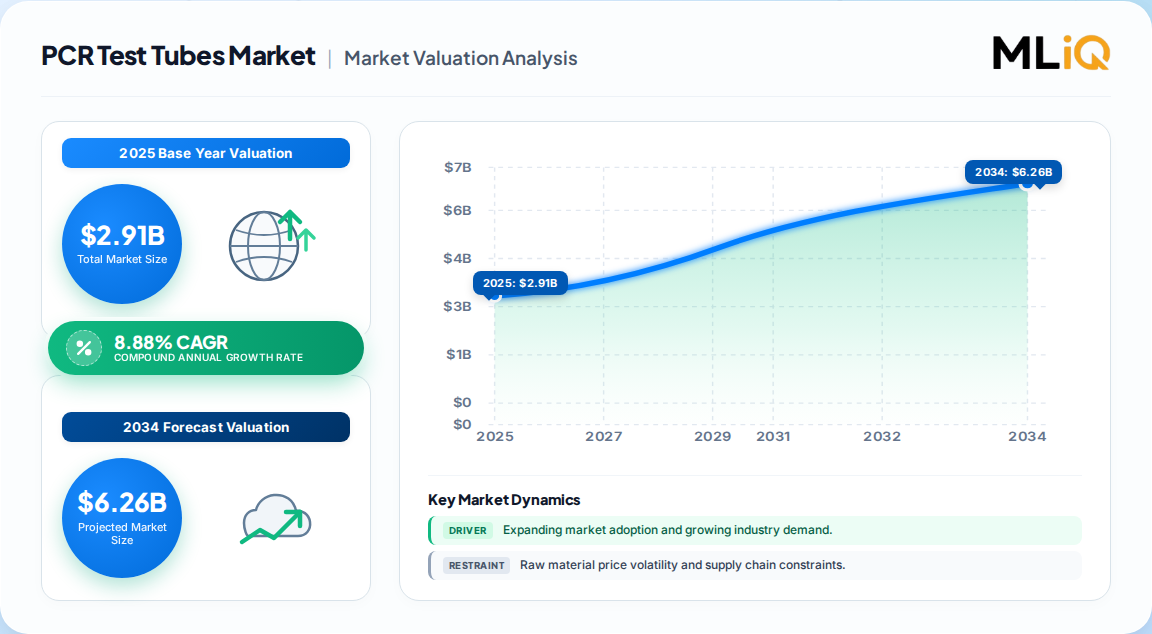
The market was valued at USD 2.91 Billion in 2025 and is projected to reach USD 6.26 Billion by 2034, at an 8.88% CAGR. However, competing estimates vary significantly due to differing scope definitions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 2.91 Billion | 2025 | 2034 | 8.88% | PCR sample tubes, all applications | One published estimate |
| USD 530.5 Million (PCR consumables) | 2023 | 2032 | 4.8% | PCR consumables incl. tubes, plates, caps | A competing analysis |
| USD 352.3 Million (PCR tubes segment) | 2032 | 2032 | — | PCR tubes only, subset of consumables | A competing analysis |
Our analysis suggests the USD 2.91 Billion figure is most defensible for the standalone PCR test tubes market, as it captures tube-specific revenue without dilution from reagents or instruments. The lower consumables estimate reflects a narrower product taxonomy and pre-pandemic baseline. The divergence implies buyers must clarify scope—tube-only versus full consumables—before benchmarking procurement budgets.
Segmentation follows product type, volume format, and end-use application. V-bottom tubes lead on compatibility with standard thermal cyclers, while cylindrical formats are preferred in automated liquid-handling systems.
| Parent Segment | Children |
|---|---|
| By Type | V-bottom Tubes, Cylindrical Tubes |
| By Volume | 0.1 mL, 0.2 mL, 0.5 mL, Others |
| By Application | Hospitals, Laboratories, Diagnostic Centers, Others |
Analyst note: The 0.2 mL format is the de facto standard for real-time PCR, but 0.1 mL tubes are gaining traction in digital PCR workflows where reagent efficiency matters. Suppliers offering both formats with automation-compatible sealing options will capture share.
North America leads in revenue share, supported by advanced molecular diagnostics infrastructure and high PCR testing penetration. Asia-Pacific is the fastest-growing region, driven by expanding healthcare access and diagnostic lab networks in China, Japan, and India.
| Region | Market Share (%) |
|---|---|
| North America | 0.31% |
| Europe | 0.24% |
| Asia-Pacific | 0.33% |
| South America | 0.06% |
| Middle East & Africa | 0.06% |
| Parent Region | Countries / Sub-regions |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain, Rest of Europe |
| Asia-Pacific | China, Japan, India, South Korea, Australia, Rest of APAC |
| South America | Brazil, Argentina, Colombia, Peru, Chile |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Egypt, Rest of MEA |
Regional share (2025): North America 31%, Europe 24%, Asia-Pacific 33%, South America 6%, Middle East & Africa 6%. Our analysis suggests Asia-Pacific's share will rise to 36–38% by 2034 as local manufacturing scales and diagnostic decentralization accelerates.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising infectious disease burden | Driver | High | Expanded PCR testing volumes directly increase tube consumption |
| PCR technology advancements (qPCR, dPCR, multiplex) | Driver | High | Specialized tubes required for sealed, contamination-free workflows |
| Expansion of research and diagnostics | Driver | High | Genomics, oncology, and precision medicine demand more PCR consumables |
| Automation and high-throughput testing | Driver | Medium | Automation-compatible tubes command premium pricing |
| Commodity price pressure and low differentiation | Restraint | Medium | Price competition erodes margins for standard tubes |
| Regulatory compliance and quality standards | Restraint | Medium | Nuclease-free, certified tubes raise production costs |
Balance: Drivers outweigh restraints, but the market is shifting from volume-led to value-led growth. Our analysis suggests suppliers that invest in automation-compatible, certified tubes will outperform those competing on price alone. The key second-order effect: as PCR testing decentralizes to point-of-care, smaller-volume, single-use tube formats will grow faster than bulk laboratory formats.
| Company | Specialization | Differentiation |
|---|---|---|
| NIPPON Genetics | PCR tubes and consumables | Japanese precision manufacturing, nuclease-free certification |
| Analytik Jena AG | Molecular diagnostics consumables | Integrated instrument-consumable ecosystem |
| Sorenson BioScience | PCR tubes and plates | High-volume manufacturing, automation compatibility |
| BioMicroLab, Inc. | Sample management consumables | Specialized in 2D-barcoded tubes |
| AHN Biotechnologie GmbH | PCR tubes and plates | German engineering, ISO-certified production |
| Bioteke Corporation | PCR consumables | Cost-competitive Asian manufacturing |
| Brooks Life Sciences | Sample storage and PCR tubes | Cold-chain and storage integration |
| Boekel Scientific | Laboratory consumables | Broad laboratory product portfolio |
Competitive moats: Vendors with in-house resin qualification and cleanroom molding capabilities can guarantee nuclease-free, PCR-inhibitor-free tubes—a critical differentiator. Our analysis suggests the strongest moat is automation compatibility certification, as liquid-handling vendors increasingly specify validated tube formats.
Buyers must prioritize certified nuclease-free and PCR-inhibitor-free tubes, as contamination directly compromises amplification results. Automation compatibility is the second critical criterion—tubes must match thermal cycler block formats and robotic handling specifications.
Procurement risks include supply chain concentration in Asia-Pacific, where geopolitical disruptions could affect lead times. Switching costs are moderate: tube format changes may require revalidation of PCR workflows, creating inertia but also vendor lock-in opportunities.
Regulatory compliance varies by region: EU IVDR requirements for diagnostic consumables are stringent, while US FDA oversight focuses on clinical diagnostic end-use. Operators should verify ISO 13485 certification and batch-level quality documentation. Our analysis suggests buyers should dual-source critical tube formats to mitigate supply risk, even at a 10–15% cost premium.
The balance of evidence favors a value-led growth strategy over volume expansion. The PCR test tubes market is transitioning from pandemic-driven surge demand to structural growth anchored in molecular diagnostics expansion. Vendors competing on commodity pricing face margin compression as Asian manufacturers scale. The strongest counter-argument—that price-sensitive emerging markets will sustain commodity demand—holds partially true, but even there, diagnostic labs are upgrading to automation-compatible formats.
Our analysis suggests three strategic priorities:
What would change our conclusion: If PCR testing volumes decline sharply due to a shift toward isothermal or sequencing-based diagnostics, the forecast CAGR of 8.88% would be optimistic. Conversely, if decentralized point-of-care PCR adoption accelerates faster than expected, demand for small-format tubes could exceed our projections. The full report provides segment-level forecasts to stress-test these scenarios.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.88% from 2020-2034 |
| Segmentation |
|
The global PCR test tubes market was valued at USD 2.91 Billion in 2025 and is forecast to reach USD 6.26 Billion by 2034, growing at an 8.88% CAGR during 2026–2034.
North America leads in revenue share at approximately 31% in 2025, supported by advanced molecular diagnostics infrastructure. Asia-Pacific is the fastest-growing region at 33% share, driven by expanding diagnostic lab networks.
Key drivers include rising infectious disease burden, PCR technology advancements (qPCR, dPCR, multiplex), expansion of genomics and precision medicine research, and growing automation in high-throughput testing workflows.
Leading vendors include NIPPON Genetics, Analytik Jena AG, Sorenson BioScience, BioMicroLab, AHN Biotechnologie, Bioteke Corporation, Brooks Life Sciences, and Boekel Scientific, among others.
The market is segmented into V-bottom tubes and cylindrical tubes. V-bottom tubes dominate standard thermal cycler workflows, while cylindrical tubes are preferred in automated liquid-handling systems.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employed a 70/30 primary-to-secondary data collection split. In-depth interviews were conducted with stakeholders across the PCR test tubes value chain, including raw material suppliers (medical-grade polypropylene resin), specialized tube manufacturers, contract molders, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews provided granular insight into procurement criteria, switching costs, and qualification timelines.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 35% |
| Heads of R&D | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Resin Suppliers | 30% |
| Specialized Tube Manufacturers | 40% |
| Contract Molders & Assemblers | 20% |
| Global Distributors | 10% |
Secondary research drew from official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards from ISO and industry associations. All secondary benchmarks were cross-validated against primary interview data to ensure consistency and reliability.
We employed simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling) data triangulation. This dual approach enabled robust market sizing and forecast validation across product types, applications, and regions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2034 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |