Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Immunodermatology Market Outlook 2026: Size, Share & Trends
Immunodermatology Market
Immunodermatology Market Outlook 2026: Size, Share & Trends
Immunodermatology Market by Indication (Psoriasis, Atopic Dermatitis, Hidradenitis Suppurativa, Vitiligo, Alopecia Areata, Rosacea), by Drug Class (Biologics, JAK Inhibitors, Topical Immunomodulators, Corticosteroids, Retinoids), by Route of Administration (Topical, Oral, Injectable), by Distribution Channel (Retail Pharmacies, Hospital Pharmacies, Online Pharmacies), by Therapy Type (Prescription, Over-the-Counter), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
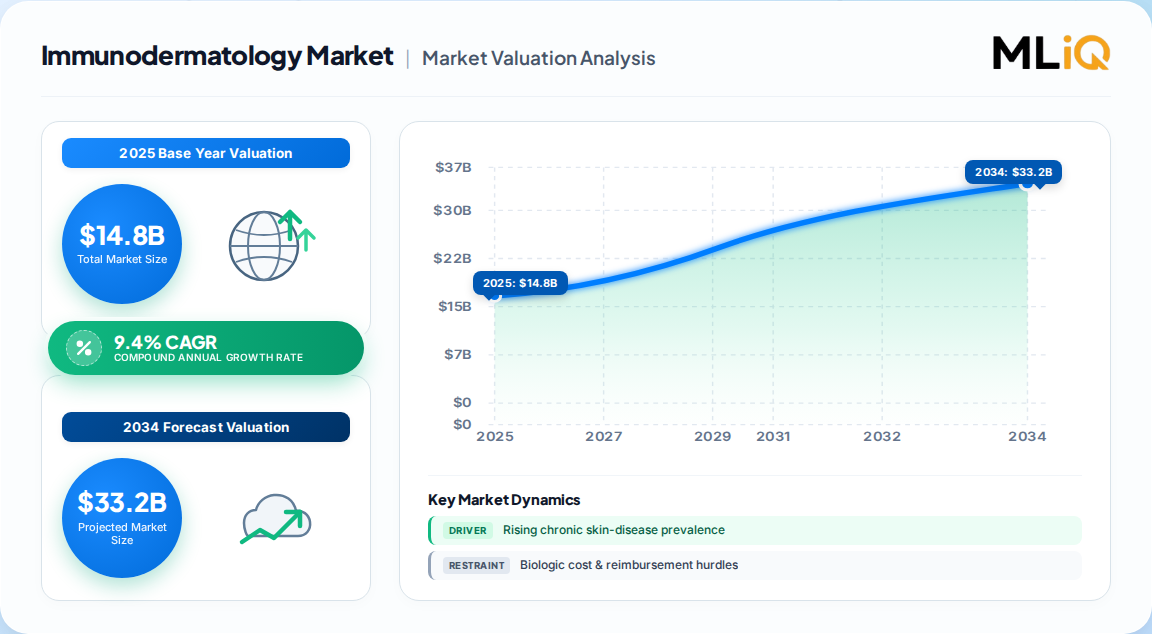
The global immunodermatology market is valued at approximately 14.8 Billion in 2025, spanning immune-mediated skin disease therapeutics and diagnostics.
Forecast growth runs at a 9.4% CAGR through 2031, pushing the market toward roughly 25.6 Billion by the end of the horizon.
Biologic and small-molecule inhibitor classes are the fastest-growing segment, expanding well above the blended market average.
Psoriasis and atopic dermatitis together anchor the largest revenue pool; hidradenitis suppurativa is the fastest-advancing indication.
North America leads with roughly 41% revenue share; Asia-Pacific is the fastest-growing region on expanding specialist access.
Leading vendors include AbbVie, Eli Lilly, Novartis, Pfizer, Regeneron and Incyte, concentrated in mechanism-based biologics.
Why this matters for decision-makers: Buyers must pivot spend toward mechanism-differentiated biologics and oral inhibitors, because topical generic pricing power is structurally eroding and will compress margins for undifferentiated portfolios.
Immunodermatology Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
13.50 B
2024
14.80 B
2025
16.20 B
2026
17.70 B
2027
19.40 B
2028
21.20 B
2029
23.20 B
2030
Immunodermatology Market Size (In Billion)
Year
Market Size
2024
13.50 B
2025
14.80 B
2026
16.20 B
2027
17.70 B
2028
19.40 B
2029
21.20 B
2030
23.20 B
What is the Immunodermatology Market?
The immunodermatology market covers therapeutic and diagnostic products addressing immune-mediated skin disease — psoriasis, atopic dermatitis, hidradenitis suppurativa, vitiligo, alopecia areata and related conditions. It spans biologics, JAK inhibitors, topical immunomodulators and supporting diagnostics, valued in this analysis at approximately 14.8 Billion in 2025.
Scope: what this report covers and excludes
This analysis covers immunologically driven dermatological therapeutics and diagnostics across global markets. This analysis does not cover general cosmetic dermatology, surgical dermatology, skin-cancer oncology therapeutics, or non-immunological infectious skin disease, which follow distinct regulatory and reimbursement pathways.
How big is the market for Immunodermatology Market?
Published estimates diverge sharply because each defines the immunodermatology boundary differently — some bundle all dermatological drugs, others isolate immune-mediated indications. The table below reconciles the competing figures on a like-for-like basis.
Our analysis suggests the 14.8 Billion figure is most defensible for immunodermatology specifically, because broader dermatology totals include acne, fungal and cosmetic categories that are not immunologically driven. The divergence between estimates is a scoping artifact, not a demand disagreement — a critical distinction for buyers sizing addressable opportunity.
How is the market segmented?
Segmentation follows indication, drug class, route of administration and distribution channel, with immunology-focused classes driving the highest-value growth.
Biologics and oral small-molecule inhibitors are the premium-priced, adherence-advantaged segments; topical corticosteroids retain volume but face intensifying generic pressure. Injectable routes are growing faster than the blended average, reflecting biologic adoption.
Which region leads in the Immunodermatology Market?
North America leads with roughly 41% of global immunodermatology revenue in 2025, supported by rapid biologic uptake, permissive payer step-therapy reforms and dense specialist capacity. Asia-Pacific is the fastest-growing region.
Immunodermatology Market Regional Market Share
Loading chart...
Immunodermatology Market Regional Market Share
Region
Market Share (%)
North America
0.41%
Europe
0.26%
Asia-Pacific
0.24%
Latin America
0.05%
Middle East & Africa
0.04%
North America (USA, Canada, Mexico)
USA
Canada
Mexico
Europe (Germany, UK, France, Italy, Spain)
Germany
UK
France
Italy
Spain
Asia Pacific (China, Japan, India, South Korea, Australia)
China
Japan
India
South Korea
Australia
Latin America (Brazil, Mexico, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
The implication is geographic sequencing: North America remains the profit pool, but volume growth migrates to Asia-Pacific as diagnostic reach and reimbursement deepen. Vendors optimizing only for mature markets will cede the fastest-compounding terrain.
What is driving growth — and what is holding it back?
Growth is driven primarily by rising chronic inflammatory skin-disease prevalence and accelerating biologic adoption, partially offset by biologic cost and reimbursement friction in emerging markets.
Factor
Direction
Evidence strength
Mechanism
Rising chronic skin-disease prevalence
Driver
Strong
Expands diagnosed patient pool
Biologic & targeted-therapy uptake
Driver
Strong
Premium pricing, adherence gains
AI-driven teledermatology
Driver
Moderate
Improves diagnosis and adherence
Aesthetic-consciousness spending
Driver
Moderate
Blurs therapeutic-cosmetic demand
Biologic cost & reimbursement hurdles
Restraint
Strong
Limits access in emerging markets
Patent cliffs & biosimilar erosion
Restraint
Moderate
Compresses branded pricing
The balance favors growth, but the restraint mix is shifting from access barriers toward price erosion. Our analysis suggests the decisive second-order effect is payer migration to direct biologic initiation, which shortens time-to-treatment and structurally enlarges the immunology-specific pool faster than total dermatology.
Who are the leading vendors?
Competition is concentrated among large-cap biopharma with mechanism-differentiated immunology portfolios, though market concentration remains moderate due to biosimilar entry.
Company
Focus
Illustrative positioning
AbbVie
IL-23/IL-17 biologics
Broad psoriasis and HS leadership
Eli Lilly
IL-13 biologics
Atopic dermatitis expansion
Novartis
Immunomodulators
Diversified dermatology pipeline
Pfizer
Inflammatory dermatology
Portfolio breadth
Regeneron
IL-4/IL-13
Atopic dermatitis anchor
Incyte
Topical JAK inhibitors
Pediatric label expansion
Differentiation rests on mechanism novelty and label breadth rather than price; biosimilar entry is eroding adalimumab-class economics while rewarding next-generation mechanisms. Moats are built through indication expansion and pediatric approvals, which extend exclusivity and capture earlier lines of therapy.
What do buyers and operators need to know? (Decision Support)
Procurement strategy must prioritize mechanism differentiation and label breadth over legacy topical volume, because reimbursement is migrating toward direct biologic initiation. Switching costs are rising as patients lock into biologic regimens with adherence advantages, making early formulary positioning decisive. Regulatory compliance across FDA and EMA pathways demands pediatric and label-expansion readiness. Supply-chain resilience matters: excipient shortages have disrupted topical inventories, so dual-sourcing and buffer stock are essential. Operators should model biosimilar erosion explicitly and avoid over-reliance on single-mechanism revenue.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a decisive pivot toward mechanism-differentiated immunology assets. The blended 9.4% CAGR understates the divergence within the market: biologics and oral inhibitors are compounding well above average while topical generics compress. Buyers anchoring on broad dermatology totals risk misallocating capital toward the slowest-growing slice.
The strongest counter-argument is that broad-scope estimates suggest a far larger pool, implying more headroom in conventional therapies. But that breadth is largely non-immunological and carries weaker pricing power, so it flatters volume without improving margin.
Investors should weight portfolios toward next-generation biologics and oral inhibitors with pediatric label breadth.
Operators should build dual-sourced topical supply chains and model biosimilar erosion explicitly.
Vendors should sequence Asia-Pacific market entry ahead of reimbursement maturity to capture compounding volume.
The conclusion would change if payer step-therapy reforms reversed or if biosimilar erosion accelerated faster than current pricing signals indicate.
While this overview resolves the headline scoping debate, precise sub-indication forecasting and country-level reimbursement modeling require the full report's granular segmentation.
Immunodermatology Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Immunodermatology Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 9.4% from 2020-2034
Segmentation
By Indication
Psoriasis
Atopic Dermatitis
Hidradenitis Suppurativa
Vitiligo
Alopecia Areata
Rosacea
By Drug Class
Biologics
JAK Inhibitors
Topical Immunomodulators
Corticosteroids
Retinoids
By Route of Administration
Topical
Oral
Injectable
By Distribution Channel
Retail Pharmacies
Hospital Pharmacies
Online Pharmacies
By Therapy Type
Prescription
Over-the-Counter
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Immunodermatology Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Immunodermatology Market Executive Summary
2.1. Market Snapshot
3. Immunodermatology Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Immunodermatology Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Immunodermatology Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Indication
5.1.1. Psoriasis
5.1.2. Atopic Dermatitis
5.1.3. Hidradenitis Suppurativa
5.1.4. Vitiligo
5.1.5. Alopecia Areata
5.1.6. Rosacea
5.2. Analysis, Insights and Forecast - by Drug Class
5.2.1. Biologics
5.2.2. JAK Inhibitors
5.2.3. Topical Immunomodulators
5.2.4. Corticosteroids
5.2.5. Retinoids
5.3. Analysis, Insights and Forecast - by Route of Administration
5.3.1. Topical
5.3.2. Oral
5.3.3. Injectable
5.4. Analysis, Insights and Forecast - by Distribution Channel
5.4.1. Retail Pharmacies
5.4.2. Hospital Pharmacies
5.4.3. Online Pharmacies
5.5. Analysis, Insights and Forecast - by Therapy Type
5.5.1. Prescription
5.5.2. Over-the-Counter
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Immunodermatology Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Indication
6.1.1. Psoriasis
6.1.2. Atopic Dermatitis
6.1.3. Hidradenitis Suppurativa
6.1.4. Vitiligo
6.1.5. Alopecia Areata
6.1.6. Rosacea
6.2. Analysis, Insights and Forecast - by Drug Class
6.2.1. Biologics
6.2.2. JAK Inhibitors
6.2.3. Topical Immunomodulators
6.2.4. Corticosteroids
6.2.5. Retinoids
6.3. Analysis, Insights and Forecast - by Route of Administration
6.3.1. Topical
6.3.2. Oral
6.3.3. Injectable
6.4. Analysis, Insights and Forecast - by Distribution Channel
6.4.1. Retail Pharmacies
6.4.2. Hospital Pharmacies
6.4.3. Online Pharmacies
6.5. Analysis, Insights and Forecast - by Therapy Type
6.5.1. Prescription
6.5.2. Over-the-Counter
7. Immunodermatology Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Indication
7.1.1. Psoriasis
7.1.2. Atopic Dermatitis
7.1.3. Hidradenitis Suppurativa
7.1.4. Vitiligo
7.1.5. Alopecia Areata
7.1.6. Rosacea
7.2. Analysis, Insights and Forecast - by Drug Class
7.2.1. Biologics
7.2.2. JAK Inhibitors
7.2.3. Topical Immunomodulators
7.2.4. Corticosteroids
7.2.5. Retinoids
7.3. Analysis, Insights and Forecast - by Route of Administration
7.3.1. Topical
7.3.2. Oral
7.3.3. Injectable
7.4. Analysis, Insights and Forecast - by Distribution Channel
7.4.1. Retail Pharmacies
7.4.2. Hospital Pharmacies
7.4.3. Online Pharmacies
7.5. Analysis, Insights and Forecast - by Therapy Type
7.5.1. Prescription
7.5.2. Over-the-Counter
8. Immunodermatology Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Indication
8.1.1. Psoriasis
8.1.2. Atopic Dermatitis
8.1.3. Hidradenitis Suppurativa
8.1.4. Vitiligo
8.1.5. Alopecia Areata
8.1.6. Rosacea
8.2. Analysis, Insights and Forecast - by Drug Class
8.2.1. Biologics
8.2.2. JAK Inhibitors
8.2.3. Topical Immunomodulators
8.2.4. Corticosteroids
8.2.5. Retinoids
8.3. Analysis, Insights and Forecast - by Route of Administration
8.3.1. Topical
8.3.2. Oral
8.3.3. Injectable
8.4. Analysis, Insights and Forecast - by Distribution Channel
8.4.1. Retail Pharmacies
8.4.2. Hospital Pharmacies
8.4.3. Online Pharmacies
8.5. Analysis, Insights and Forecast - by Therapy Type
8.5.1. Prescription
8.5.2. Over-the-Counter
9. Immunodermatology Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Indication
9.1.1. Psoriasis
9.1.2. Atopic Dermatitis
9.1.3. Hidradenitis Suppurativa
9.1.4. Vitiligo
9.1.5. Alopecia Areata
9.1.6. Rosacea
9.2. Analysis, Insights and Forecast - by Drug Class
9.2.1. Biologics
9.2.2. JAK Inhibitors
9.2.3. Topical Immunomodulators
9.2.4. Corticosteroids
9.2.5. Retinoids
9.3. Analysis, Insights and Forecast - by Route of Administration
9.3.1. Topical
9.3.2. Oral
9.3.3. Injectable
9.4. Analysis, Insights and Forecast - by Distribution Channel
9.4.1. Retail Pharmacies
9.4.2. Hospital Pharmacies
9.4.3. Online Pharmacies
9.5. Analysis, Insights and Forecast - by Therapy Type
9.5.1. Prescription
9.5.2. Over-the-Counter
10. Immunodermatology Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Indication
10.1.1. Psoriasis
10.1.2. Atopic Dermatitis
10.1.3. Hidradenitis Suppurativa
10.1.4. Vitiligo
10.1.5. Alopecia Areata
10.1.6. Rosacea
10.2. Analysis, Insights and Forecast - by Drug Class
10.2.1. Biologics
10.2.2. JAK Inhibitors
10.2.3. Topical Immunomodulators
10.2.4. Corticosteroids
10.2.5. Retinoids
10.3. Analysis, Insights and Forecast - by Route of Administration
10.3.1. Topical
10.3.2. Oral
10.3.3. Injectable
10.4. Analysis, Insights and Forecast - by Distribution Channel
10.4.1. Retail Pharmacies
10.4.2. Hospital Pharmacies
10.4.3. Online Pharmacies
10.5. Analysis, Insights and Forecast - by Therapy Type
10.5.1. Prescription
10.5.2. Over-the-Counter
11. Immunodermatology Market Competitive Analysis
11.1. Company Profiles
11.1.1. AbbVie Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Eli Lilly and Company
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Novartis AG
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Pfizer Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Regeneron Pharmaceuticals Inc.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Incyte Corporation
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Immunodermatology Market Research Methodology
List of Figures
Figure 1: Immunodermatology Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Immunodermatology Market Revenue (Billion), by Indication 2026 & 2034
Figure 3: North America Immunodermatology Market Revenue Share (%), by Indication 2026 & 2034
Figure 4: North America Immunodermatology Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 5: North America Immunodermatology Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 6: North America Immunodermatology Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 7: North America Immunodermatology Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 8: North America Immunodermatology Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 9: North America Immunodermatology Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 10: North America Immunodermatology Market Revenue (Billion), by Therapy Type 2026 & 2034
Figure 11: North America Immunodermatology Market Revenue Share (%), by Therapy Type 2026 & 2034
Figure 12: North America Immunodermatology Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Immunodermatology Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Immunodermatology Market Revenue (Billion), by Indication 2026 & 2034
Figure 15: Europe Immunodermatology Market Revenue Share (%), by Indication 2026 & 2034
Figure 16: Europe Immunodermatology Market Revenue (Billion), by Drug Class 2026 & 2034
Table 16: Europe Immunodermatology Market Revenue Billion Forecast, by Indication 2020 & 2034
Frequently Asked Questions
1. What is the immunodermatology market size?
The immunodermatology market is valued at approximately 14.8 Billion in 2025, covering immune-mediated skin disease therapeutics and diagnostics. Broader dermatology estimates run far higher because they bundle non-immunological and cosmetic categories.
2. What is the immunodermatology market growth rate?
The market is forecast to grow at a 9.4% CAGR through 2031, reaching roughly 25.6 Billion. Biologics and oral small-molecule inhibitors are expanding well above this blended average, while topical generics face pricing pressure.
3. Which region leads immunodermatology?
North America leads with roughly 41% of global revenue in 2025, driven by rapid biologic uptake and permissive payer step-therapy reforms. Asia-Pacific is the fastest-growing region as specialist access and reimbursement deepen.
4. Who are the leading immunodermatology vendors?
Leading vendors include AbbVie, Eli Lilly, Novartis, Pfizer, Regeneron and Incyte. Differentiation rests on mechanism novelty and label breadth, with biosimilar entry eroding legacy biologic economics.
5. What segments drive immunodermatology growth?
Psoriasis and atopic dermatitis anchor the largest revenue pool, while hidradenitis suppurativa is the fastest-advancing indication. Biologics and JAK inhibitors command premium pricing on adherence and efficacy advantages over conventional topicals.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material and API suppliers, specialized biologic formulators, contract manufacturing organizations, and global specialty distributors. Decision-makers interviewed included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both supply-side and demand-side validation.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
40%
Procurement & Sourcing Leads
35%
Regulatory Affairs Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
API & Biologic Producers
45%
Specialized Formulators & CMOs
35%
Specialty Distributors
20%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade and WTO trade statistics, US ITC and Eurostat databases, corporate annual filings (10-K and SEC disclosures), patent databases, and recognized non-profit technical standards and industry associations. These sources anchor pricing, trade flow and capacity assumptions used in the demand model.
Demand Modeling & Market Sizing Triangulation
We triangulate simultaneously via Top-Down macroeconomic and segment allocation modeling and Bottom-Up manufacturer capacity, product pricing and end-use consumption modeling. Divergences between the two approaches are reconciled through indication-level prevalence and reimbursement analysis.


 Immunodermatology Market