Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
HPV Testing & Pap Test Market Outlook 2025
HPV Testing & Pap Test Market Outlook 2025
HPV Testing & Pap Test Market
HPV Testing & Pap Test Market Outlook 2025
HPV Testing & Pap Test Market by Test Type (HPV test, Pap test, Co-testing), by Technology (PCR, Liquid-based cytology, Immunodiagnostics, Hybrid capture, Others), by Application (Cervical cancer screening, Vaginal cancer screening), by Product (Consumables, Instruments, Services), by End-Use (Hospitals & clinics, Diagnostic centers, Laboratories, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Israel) Forecast 2026-2034
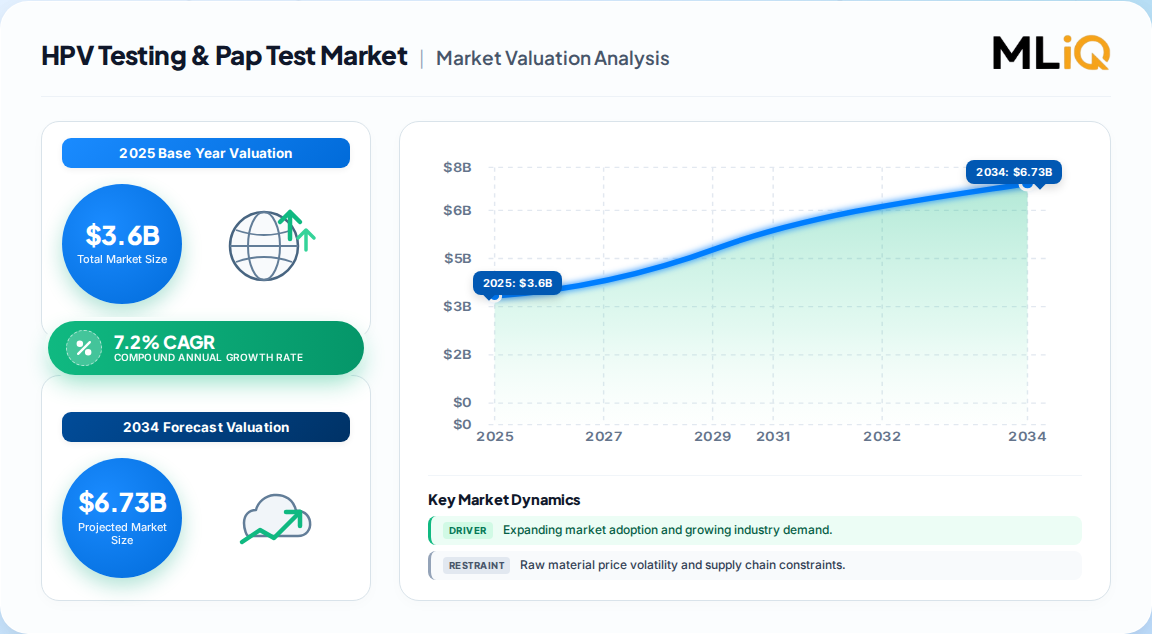
$3.6 Billion base (2025), global scope: the HPV Testing & Pap Test market was valued at USD 3.6 billion in 2025 and is projected to reach USD 6.2 billion by 2033.
Growth rate: 7.2% CAGR over 2026–2033, materially lower than the 15.4% CAGR claimed in one bullish 2023-vintage estimate, signaling consensus has reset downward.
Leading test segment: Pap test holds the largest revenue share (about 56–62% depending on the estimate), but primary HPV DNA testing is the faster-growing format.
Leading technology: PCR-based molecular diagnostics leads at roughly 40% share; liquid-based cytology remains the dominant Pap platform.
Leading regions: North America leads with about 41% revenue share; Asia Pacific is the fastest-growing region on screening-program expansion.
Key players: Roche, Abbott, Hologic, BD, Qiagen, Quest Diagnostics, Seegene and Arbor Vita anchor a moderately concentrated vendor field.
Why this matters for decision-makers: the growth engine is shifting from volume-led cytology to guideline-driven molecular HPV testing, so vendors with PCR menus and self-sampling workflows will capture disproportionate value while pure cytology-exposed suppliers face share erosion.
HPV Testing & Pap Test Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
3.600 B
2025
3.800 B
2026
4.100 B
2027
4.400 B
2028
4.700 B
2029
5.100 B
2030
5.400 B
2031
HPV Testing & Pap Test Market Size (In Billion)
Year
Market Size
2025
3.600 B
2026
3.800 B
2027
4.100 B
2028
4.400 B
2029
4.700 B
2030
5.100 B
2031
5.400 B
What is the HPV Testing & Pap Test Market?
The HPV Testing & Pap Test market covers clinical screening products and services used to detect high-risk human papillomavirus infection and precancerous cervical cell changes. It spans HPV DNA/RNA assays, Pap cytology, co-testing, associated instruments, consumables and laboratory screening services delivered through hospitals, diagnostic centers and national programs.
Scope: what this report covers and excludes
This analysis covers HPV molecular testing, Pap cytology, co-testing, liquid-based cytology and PCR platforms, plus hospital, diagnostic-center and laboratory end-use across five regions. It excludes HPV vaccines, therapeutic oncology drugs, colposcopy and biopsy devices, and general women's health diagnostics. This analysis does not cover standalone cancer treatment markets or fertility testing adjacent to gynecologic care.
How big is the market for HPV Testing & Pap Test Market?
Most current estimates place the global market near USD 3.6 billion in 2025, with long-run growth in the mid-single to low-double digits depending on how aggressively primary HPV screening displaces cytology. The dispersion below is large and must be read through definitional differences, not simply forecast error.
Our analysis suggests the 7.2% and 6.1% trajectories are the most defensible. The 15.4% figure depends on an unusually low 2022 base combined with an assumption that molecular testing fully replaces cytology within a decade, which reimbursement realities in low- and middle-income markets do not support. The 11.8% figure is credible only under its broad product-inclusive definition. For procurement and investment planning, a 6–8% planning band is prudent.
How is the market segmented?
Segmentation is best read along four axes: test format, technology, application and end-use setting. Technology is where competitive advantage is most concentrated, because PCR and hybrid-capture platforms carry higher margins and switching costs than cytology consumables.
Consumables dominate product revenue at roughly 49%, which implies recurring-reagent annuity models outperform instrument-led strategies. Hospitals and clinics lead end-use at about 43–53%, but diagnostic laboratories are the volume anchor for high-throughput molecular screening.
Which region leads in HPV Testing & Pap Test Market?
North America leads with roughly 41% revenue share in 2025, supported by mature screening guidelines, high HPV co-testing adoption and dense molecular-diagnostics infrastructure. Asia Pacific is the fastest-growing region, driven by national elimination programs and expanding laboratory capacity.
HPV Testing & Pap Test Market Regional Market Share
Loading chart...
HPV Testing & Pap Test Market Regional Market Share
Region
Market Share (%)
North America
0.41%
Europe
0.24%
Asia-Pacific
0.22%
Latin America
0.08%
Middle East & Africa
0.05%
Global
North America (USA, Canada, Mexico)
Europe (Germany, UK, France, Italy, Spain, Netherlands)
Asia Pacific (China, Japan, India, South Korea, Australia)
Latin America (Brazil, Mexico, Argentina, Colombia)
Middle East & Africa (Saudi Arabia, UAE, South Africa, Israel)
Our analysis suggests North America's share will erode slowly through 2033 as Asia Pacific screening coverage rises under WHO elimination targets. Europe holds a stable second position, but reimbursement uniformity varies sharply by country, making it a patchwork rather than a single market.
What is driving growth — and what is holding it back?
Growth is driven primarily by cervical cancer burden and guideline migration toward primary HPV testing with higher sensitivity than cytology alone. WHO data showing roughly 660,000 new cases and 350,000 deaths in 2022 anchor the demand case, while the 70% screening-coverage target by ages 35 and 45 creates a quantified volume pipeline.
Factor
Direction
Evidence strength
Mechanism
Cervical cancer burden (~95% HPV-linked)
Driver
High
Sustains guideline-mandated screening volume
Shift to primary HPV / co-testing
Driver
High
Raises revenue per screen vs cytology alone
Self-sampling and home collection
Driver
Medium
Expands access in underscreened populations
WHO 70% screening target
Driver
Medium
Public-program procurement demand
Reimbursement gaps and variability
Restraint
High
Delays adoption, especially in emerging markets
Regulatory heterogeneity
Restraint
Medium
Lengthens approval cycles and raises cost
HPV vaccination coverage gains
Restraint
Medium
Reduces long-run lesion prevalence and screening frequency
The balance favors growth, but with an important second-order effect: vaccination success gradually lowers abnormal-cytology yields, which weakens the economics of stand-alone Pap testing and accelerates the case for molecular triage. Vendors that treat vaccination as a threat rather than a re-segmentation trigger will misallocate R&D.
Who are the leading vendors?
Competition centers on assay menu breadth, regulatory clearances and laboratory workflow integration. Roche and Abbott lead on molecular platforms, Hologic and BD on cytology-plus-HPV integration, and Qiagen and Seegene on assay breadth and cost positioning.
WHO prequalification supports public-program access
Hologic
Cytology + HPV
ThinPrep ecosystem and co-testing integration
Becton Dickinson
HPV assay (Onclarity)
Genotype-specific reporting with ThinPrep pairing
Qiagen
HPV assays
Menu breadth and mid-throughput flexibility
Quest Diagnostics
Laboratory services
Reference-lab scale and payer relationships
Seegene
Multiplex molecular
Cost-competitive multiplexing
Arbor Vita
Point-of-care HPV
Decentralized and low-resource settings
The moat is not the assay alone but the installed platform plus guideline inclusion plus reimbursement listing. Our analysis suggests switching costs rise sharply once a laboratory standardizes on a PCR platform, making the installed base the real competitive asset.
What do buyers and operators need to know? (Decision Support)
Buyers should weight five criteria above price: validated clinical sensitivity for high-risk genotypes, regulatory clearance in the target jurisdiction, integration with existing laboratory workflow, reimbursement or public-program eligibility, and supply continuity for consumables. Genotype-specific reporting (especially 16/18 and 45) is increasingly a tender requirement rather than a differentiator.
Procurement risk concentrates in single-source reagent dependencies and in regulatory reclassification. Where assays are tied to a closed platform, switching costs include staff retraining, validation studies and potential loss of accreditation continuity, often exceeding the instrument's purchase price. Operators should model total cost of ownership over at least five years, not acquisition cost.
Self-sampling introduces a distinct operational risk: specimen stability and validation for off-label collection devices. Buyers adopting home collection should confirm that the assay is validated for self-collected media, since a mismatch here is the most common source of false reassurance and downstream liability.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the conservative 6–8% growth trajectory over the aggressive double-digit narrative. The most credible counter-argument is that a rapid policy push under WHO elimination targets could compress adoption timelines and validate the higher estimates, particularly if low-cost molecular platforms reach sub-Saharan Africa and South Asia faster than expected. That is a real upside scenario, but it depends on funding commitments that have historically lagged targets.
Our judgment is that value will migrate toward vendors combining a validated PCR platform, genotype-specific reporting and a self-sampling pathway. Cytology-only suppliers face structural pressure as guideline preference shifts, though co-testing demand will keep liquid-based cytology relevant well into the forecast window. The divergence between published estimates is itself a signal: buyers should stress-test plans against both the 6% and 12% cases rather than anchoring on a single number.
Actionable strategy:
Investors: prioritize molecular-platform owners with installed-base annuity revenue and public-program prequalification over cytology-exposed suppliers.
Operators: negotiate multi-year reagent pricing and validation support before platform lock-in, and require self-sampling validation evidence in contracts.
Vendors: target Asia Pacific public screening tenders and genotype-specific reporting requirements to capture share as North America matures.
The evidence that would change this conclusion is a sustained acceleration in national screening budgets or a reimbursement mandate for primary HPV testing across major European markets, either of which would justify upgrading to the higher-growth scenario.
HPV Testing & Pap Test Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
HPV Testing & Pap Test Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.2% from 2020-2034
Segmentation
By Test Type
HPV test
Pap test
Co-testing
By Technology
PCR
Liquid-based cytology
Immunodiagnostics
Hybrid capture
Others
By Application
Cervical cancer screening
Vaginal cancer screening
By Product
Consumables
Instruments
Services
By End-Use
Hospitals & clinics
Diagnostic centers
Laboratories
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Israel
Table of Contents
1. HPV Testing & Pap Test Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. HPV Testing & Pap Test Market Executive Summary
2.1. Market Snapshot
3. HPV Testing & Pap Test Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. HPV Testing & Pap Test Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. HPV Testing & Pap Test Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Test Type
5.1.1. HPV test
5.1.2. Pap test
5.1.3. Co-testing
5.2. Analysis, Insights and Forecast - by Technology
5.2.1. PCR
5.2.2. Liquid-based cytology
5.2.3. Immunodiagnostics
5.2.4. Hybrid capture
5.2.5. Others
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Cervical cancer screening
5.3.2. Vaginal cancer screening
5.4. Analysis, Insights and Forecast - by Product
5.4.1. Consumables
5.4.2. Instruments
5.4.3. Services
5.5. Analysis, Insights and Forecast - by End-Use
5.5.1. Hospitals & clinics
5.5.2. Diagnostic centers
5.5.3. Laboratories
5.5.4. Others
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. HPV Testing & Pap Test Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Test Type
6.1.1. HPV test
6.1.2. Pap test
6.1.3. Co-testing
6.2. Analysis, Insights and Forecast - by Technology
6.2.1. PCR
6.2.2. Liquid-based cytology
6.2.3. Immunodiagnostics
6.2.4. Hybrid capture
6.2.5. Others
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Cervical cancer screening
6.3.2. Vaginal cancer screening
6.4. Analysis, Insights and Forecast - by Product
6.4.1. Consumables
6.4.2. Instruments
6.4.3. Services
6.5. Analysis, Insights and Forecast - by End-Use
6.5.1. Hospitals & clinics
6.5.2. Diagnostic centers
6.5.3. Laboratories
6.5.4. Others
7. HPV Testing & Pap Test Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Test Type
7.1.1. HPV test
7.1.2. Pap test
7.1.3. Co-testing
7.2. Analysis, Insights and Forecast - by Technology
7.2.1. PCR
7.2.2. Liquid-based cytology
7.2.3. Immunodiagnostics
7.2.4. Hybrid capture
7.2.5. Others
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Cervical cancer screening
7.3.2. Vaginal cancer screening
7.4. Analysis, Insights and Forecast - by Product
7.4.1. Consumables
7.4.2. Instruments
7.4.3. Services
7.5. Analysis, Insights and Forecast - by End-Use
7.5.1. Hospitals & clinics
7.5.2. Diagnostic centers
7.5.3. Laboratories
7.5.4. Others
8. HPV Testing & Pap Test Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Test Type
8.1.1. HPV test
8.1.2. Pap test
8.1.3. Co-testing
8.2. Analysis, Insights and Forecast - by Technology
8.2.1. PCR
8.2.2. Liquid-based cytology
8.2.3. Immunodiagnostics
8.2.4. Hybrid capture
8.2.5. Others
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Cervical cancer screening
8.3.2. Vaginal cancer screening
8.4. Analysis, Insights and Forecast - by Product
8.4.1. Consumables
8.4.2. Instruments
8.4.3. Services
8.5. Analysis, Insights and Forecast - by End-Use
8.5.1. Hospitals & clinics
8.5.2. Diagnostic centers
8.5.3. Laboratories
8.5.4. Others
9. HPV Testing & Pap Test Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Test Type
9.1.1. HPV test
9.1.2. Pap test
9.1.3. Co-testing
9.2. Analysis, Insights and Forecast - by Technology
9.2.1. PCR
9.2.2. Liquid-based cytology
9.2.3. Immunodiagnostics
9.2.4. Hybrid capture
9.2.5. Others
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Cervical cancer screening
9.3.2. Vaginal cancer screening
9.4. Analysis, Insights and Forecast - by Product
9.4.1. Consumables
9.4.2. Instruments
9.4.3. Services
9.5. Analysis, Insights and Forecast - by End-Use
9.5.1. Hospitals & clinics
9.5.2. Diagnostic centers
9.5.3. Laboratories
9.5.4. Others
10. HPV Testing & Pap Test Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Test Type
10.1.1. HPV test
10.1.2. Pap test
10.1.3. Co-testing
10.2. Analysis, Insights and Forecast - by Technology
10.2.1. PCR
10.2.2. Liquid-based cytology
10.2.3. Immunodiagnostics
10.2.4. Hybrid capture
10.2.5. Others
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Cervical cancer screening
10.3.2. Vaginal cancer screening
10.4. Analysis, Insights and Forecast - by Product
10.4.1. Consumables
10.4.2. Instruments
10.4.3. Services
10.5. Analysis, Insights and Forecast - by End-Use
10.5.1. Hospitals & clinics
10.5.2. Diagnostic centers
10.5.3. Laboratories
10.5.4. Others
11. HPV Testing & Pap Test Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. HPV Testing & Pap Test Market Research Methodology
List of Figures
Figure 1: HPV Testing & Pap Test Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America HPV Testing & Pap Test Market Revenue (Billion), by Test Type 2026 & 2034
Figure 3: North America HPV Testing & Pap Test Market Revenue Share (%), by Test Type 2026 & 2034
Figure 4: North America HPV Testing & Pap Test Market Revenue (Billion), by Technology 2026 & 2034
Figure 5: North America HPV Testing & Pap Test Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America HPV Testing & Pap Test Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America HPV Testing & Pap Test Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America HPV Testing & Pap Test Market Revenue (Billion), by Product 2026 & 2034
Figure 9: North America HPV Testing & Pap Test Market Revenue Share (%), by Product 2026 & 2034
Figure 10: North America HPV Testing & Pap Test Market Revenue (Billion), by End-Use 2026 & 2034
Figure 11: North America HPV Testing & Pap Test Market Revenue Share (%), by End-Use 2026 & 2034
Figure 12: North America HPV Testing & Pap Test Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America HPV Testing & Pap Test Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe HPV Testing & Pap Test Market Revenue (Billion), by Test Type 2026 & 2034
Figure 15: Europe HPV Testing & Pap Test Market Revenue Share (%), by Test Type 2026 & 2034
Figure 16: Europe HPV Testing & Pap Test Market Revenue (Billion), by Technology 2026 & 2034
List of Tables
Table 1: HPV Testing & Pap Test Market Revenue Billion Forecast, by Test Type 2020 & 2034
Table 2: HPV Testing & Pap Test Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 3: HPV Testing & Pap Test Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: HPV Testing & Pap Test Market Revenue Billion Forecast, by Product 2020 & 2034
Table 5: HPV Testing & Pap Test Market Revenue Billion Forecast, by End-Use 2020 & 2034
Table 6: HPV Testing & Pap Test Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America HPV Testing & Pap Test Market Revenue Billion Forecast, by Test Type 2020 & 2034
Table 8: North America HPV Testing & Pap Test Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 9: North America HPV Testing & Pap Test Market Revenue Billion Forecast, by Application 2020 & 2034
Table 10: North America HPV Testing & Pap Test Market Revenue Billion Forecast, by Product 2020 & 2034
Table 11: North America HPV Testing & Pap Test Market Revenue Billion Forecast, by End-Use 2020 & 2034
Table 12: North America HPV Testing & Pap Test Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA HPV Testing & Pap Test Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada HPV Testing & Pap Test Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico HPV Testing & Pap Test Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe HPV Testing & Pap Test Market Revenue Billion Forecast, by Test Type 2020 & 2034
Frequently Asked Questions
1. How big is the HPV testing and Pap test market?
The global HPV testing and Pap test market was valued at approximately USD 3.6 billion in 2025. It is projected to reach USD 6.2 billion by 2033, growing at about 7.2% CAGR, based on consensus mid-range estimates.
2. Which segment leads the HPV testing and Pap test market?
The Pap test segment holds the largest revenue share at roughly 56–62%, because it remains the most widely reimbursed screening format. However, primary HPV DNA testing is growing faster as guidelines favor higher-sensitivity molecular screening.
3. Which region dominates HPV testing and Pap test screening?
North America leads with about 41% revenue share in 2025, supported by mature screening guidelines and high co-testing adoption. Asia Pacific is the fastest-growing region, driven by national cervical cancer elimination programs.
4. Who are the leading companies in the HPV testing and Pap test market?
Leading vendors include Roche, Abbott Laboratories, Hologic, Becton Dickinson, Qiagen, Quest Diagnostics, Seegene and Arbor Vita. Competition centers on assay menu breadth, regulatory clearances and laboratory workflow integration.
5. Why do published market estimates for HPV testing differ so much?
Estimates diverge mainly because of scope differences. Broader definitions include instruments, services and consumables, while narrower ones count test revenue only. Base-year choice and assumptions about cytology replacement also drive significant variation.
6. What is driving growth in HPV testing and Pap test demand?
Growth is driven by the cervical cancer burden, roughly 95% of which is HPV-linked, plus guideline migration to primary HPV testing, WHO screening targets and expanding self-sampling access in underscreened populations.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program maintains a 70/30 primary-to-secondary split, ensuring that market estimates are anchored in direct industry conversation rather than desk aggregation. We conducted in-depth interviews with stakeholders across the diagnostics value chain, including molecular assay and reagent suppliers, cytology consumable producers, instrument OEMs, reference laboratories, and regional diagnostic distributors. Interviews targeted decision-makers with direct commercial or technical authority: VP-level Sourcing, Heads of Molecular R&D, Technical Directors of Laboratory Operations, and Commercial Operations Leads responsible for tender and reimbursement strategy.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Heads of Molecular R&D
35%
Procurement & Sourcing Leads
30%
Laboratory Technical Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Molecular Assay & Reagent Suppliers
40%
Cytology Consumable Producers
25%
Instrument OEMs & Platform Providers
20%
Reference Labs & Distributors
15%
Secondary Benchmarking & Public Trade Validation
Primary findings are benchmarked against official multilateral trade databases including UN Comtrade and WTO statistics, complemented by US ITC and Eurostat filings for diagnostic reagent and instrument trade flows. We review corporate annual filings and SEC 10-K disclosures, investor presentations, patent databases, and technical standards published by recognized non-profit and regulatory bodies. No competitor market-research publications are used as validation inputs.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down and Bottom-Up models. The top-down model allocates macroeconomic health expenditure and screening-program budgets to the HPV and cytology categories. The bottom-up model builds from manufacturer capacity, assay pricing, test volumes and end-use consumption by setting. Divergence between the two is resolved through targeted follow-up interviews.


 HPV Testing & Pap Test Market