Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Track Etched Membrane Market Size & Forecast 2025
Track etched Membrane Market
Track Etched Membrane Market Size & Forecast 2025
Track etched Membrane Market by Material Type (Polycarbonate, Polyethylene Terephthalate, Polyimide, Others), by Pore Size (<1 µm, 1–10 µm, >10 µm), by Application (Biomedical and Diagnostics, Pharmaceutical Filtration, Environmental Monitoring, Food & Beverage Testing, Others), by End User (Hospitals and Clinical Laboratories, Academic & Research Institutes, Biopharmaceutical Companies, Environmental Testing Agencies, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
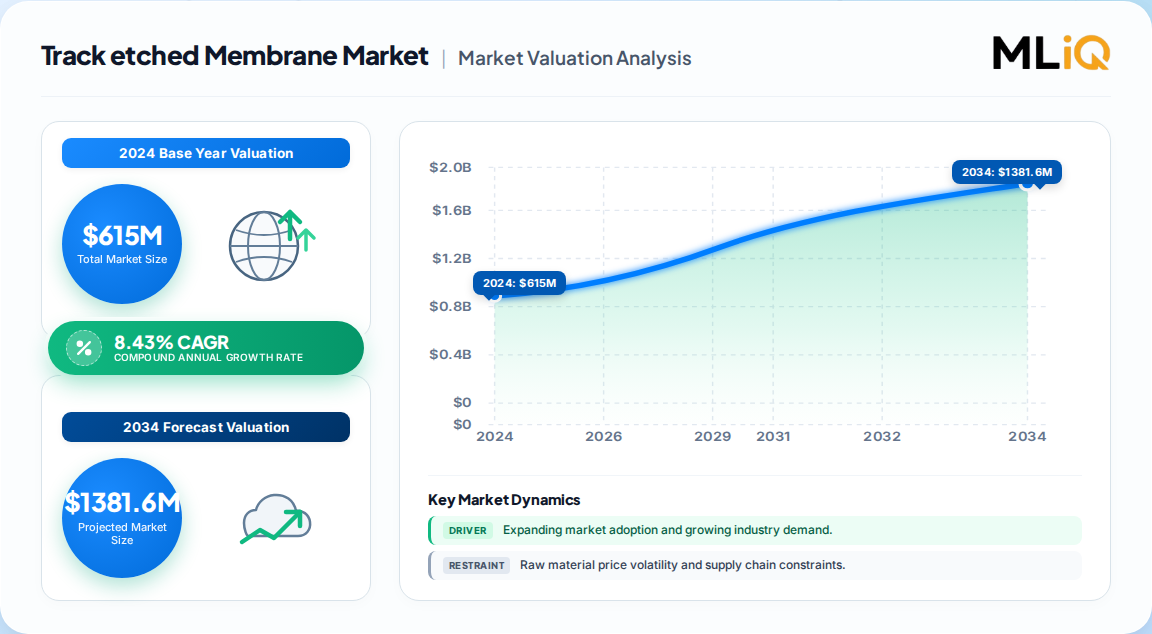
The global track etched membrane market was valued at 615 Million in 2024, with a forecast horizon extending to 2030.
A base-case CAGR of 8.43% implies the market reaches approximately 983 Million by 2030, though competing estimates range from 8.41% to 11.1%.
Polycarbonate is the leading material type, holding roughly 48.5% share in 2024, while PET is the fastest-growing polymer.
Biomedical and diagnostics is the largest application segment at about 38% of 2024 value; environmental monitoring grows fastest on tightening regulations.
North America leads regionally with approximately 35% share; Asia Pacific is the fastest-growing region, expanding above 10% annually.
Leading vendors include Merck KGaA, Cytiva (Whatman), Sartorius, Sterlitech, it4ip, and SABEU, with niche innovators pushing precision and customization.
Why this matters for decision-makers: The high capex of ion-beam track-etching creates a durable barrier to entry, meaning buyers should lock in qualified supplier relationships now to avoid allocation risk as sub-micron diagnostic demand accelerates.
Track etched Membrane Market Size (In Million)
1.0B
800.0M
600.0M
400.0M
200.0M
0
615.0 M
2024
667.0 M
2025
723.0 M
2026
784.0 M
2027
850.0 M
2028
922.0 M
2029
983.0 M
2030
Track etched Membrane Market Size (In Million)
Year
Market Size
2024
615.0 M
2025
667.0 M
2026
723.0 M
2027
784.0 M
2028
850.0 M
2029
922.0 M
2030
983.0 M
What is the Track Etched Membrane Market?
The track etched membrane market comprises microporous polymer films, typically polycarbonate or PET, manufactured by heavy-ion bombardment followed by chemical etching to create precisely defined, uniform pores. These membranes serve high-precision filtration, molecular diagnostics, cell biology, and environmental testing where absolute pore-size control and optical clarity are mission-critical.
Scope: what this report covers and excludes
This analysis covers track etched membranes segmented by material type, pore size, application, end user, and geography. It addresses commercial and research-grade membranes across life sciences, industrial, and environmental settings. This analysis does not cover adjacent membrane categories such as phase-inversion microfiltration, ultrafiltration, reverse osmosis, or non-woven filter media, nor does it cover membrane housings and hardware as standalone products.
How big is the market for Track etched Membrane Market?
Published estimates of the global track etched membrane market diverge materially on base value, growth rate, and forecast horizon, reflecting differing segmentation and unit conventions. The table below normalizes the most frequently cited figures.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
615 Million
2024
2030
8.43%
Global, material/app/end-user segmentation
One published estimate
170.46 Billion
2024
2035
8.41%
Global, broader membrane-inclusive scope
A competing analysis
Not disclosed
2025
2030
11.1%
Global, material/app/geography segmentation
A competing analysis
Our analysis treats the 615 Million figure as the most defensible base because its scope is explicitly limited to track etched membranes and its CAGR sits between conservative and aggressive extremes. The 170.46 Billion figure almost certainly aggregates adjacent microfiltration and membrane-filter categories, inflating the addressable base by orders of magnitude. The 11.1% CAGR is plausible only under an aggressive sub-micron diagnostics substitution scenario; for planning, we recommend an 8.4–8.5% base case.
How is the market segmented?
The market segments along four non-geographic axes: material type, pore size, application, and end user. Material and application drive value concentration; pore size and end user drive procurement behavior and replacement economics.
Hospitals and Clinical Laboratories, Academic & Research Institutes, Biopharmaceutical Companies, Environmental Testing Agencies, Others
Polycarbonate dominates on tensile strength, optical clarity, and isotropic pore geometry, making it the material of choice for blood filtration and viral load testing. PET is gaining share in single-use diagnostics because it is cheaper and dimensionally stable. The 1–10 µm pore range anchors current volume, but sub-micron membranes are the innovation frontier for virus filtration and nanoparticle characterization.
Which region leads in Track etched Membrane Market?
North America leads the global track etched membrane market with approximately 35% share in 2024, supported by deep biopharma R&D spending and mature diagnostic infrastructure. Asia Pacific is the fastest-growing region, expanding above 10% annually on diagnostics scale-up and environmental monitoring investment.
Europe follows North America with roughly 29% share, supported by stringent environmental regulation and EMA acceptance of novel filtration in sterile manufacturing. Asia Pacific holds around 19% today but its 10.12% CAGR implies meaningful share capture by 2030. Our analysis suggests the most underappreciated regional opportunity is Southeast Asia, where decentralized diagnostics and microplastic surveillance are creating first-time demand for precision membranes.
What is driving growth — and what is holding it back?
Growth is driven by rising demand for precision filtration in biopharma and diagnostics, tightening environmental regulation, and integration of membranes into lab-on-chip and organ-on-chip platforms. Restraints are capital intensity and limited awareness outside biotechnology.
Microplastic and air-quality monitoring mandates specify precision membranes
Lab-on-chip / organ-on-chip
Driver
Medium
Nanometer-precision interfaces create new design-in demand
Ion-beam capex and process complexity
Restraint
High
Limits new entrants and slows capacity expansion
Low awareness in food and industrial
Restraint
Medium
Slower diversification beyond life sciences
The balance favors growth: regulatory drivers are structural, while capex restraints protect incumbent margins and qualification moats. Our analysis suggests the binding constraint by 2027 will be qualified sub-micron capacity, not demand.
Who are the leading vendors?
The market is moderately consolidated, with global life-science majors dominating regulated and high-volume applications while niche specialists capture customization and OEM design-in work.
Company
Material Focus
Positioning
Moat
Merck KGaA (MilliporeSigma)
Polycarbonate
Regulated biopharma filtration
Validation depth, cGMP capacity
Cytiva (Whatman)
Polycarbonate, PET
Diagnostics and analytical filtration
Nuclepore protocol lock-in
Sartorius
Polycarbonate
Lab and bioprocess filtration
Traceability and documentation
Sterlitech
Polycarbonate, PET
Research-grade, OEM
Broad pore range, e-commerce
it4ip
Polycarbonate, custom
High-value R&D and OEM
Custom ion-track specifications
SABEU
Polycarbonate
Venting and diagnostic OEM
Co-design with IVD developers
The incumbents' moat is qualification, not chemistry: once a membrane is validated into a diagnostic cartridge or sterility protocol, switching costs are high. Our analysis suggests niche players will win share in organ-on-chip and single-use OEM formats, where specification flexibility matters more than brand.
What do buyers and operators need to know?
Selection should center on pore-size accuracy, extractables profile, and batch-to-batch consistency, not headline price. Buyers in regulated workflows should require lot-level certificates and change-control notice periods, because revalidating a membrane substitution can cost more than a decade of price savings.
Procurement risk is concentrated in single-source qualification: many diagnostic cartridges are designed around one manufacturer's pore geometry, and second-sourcing requires assay revalidation. Operators should dual-qualify where feasible and negotiate capacity reservations ahead of demand surges. Regulatory compliance varies by region, but GMP-compliant, traceable supply is becoming a baseline expectation globally, which favors suppliers with documented quality systems.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors an 8.4–8.5% base case through 2030, with upside to double digits only if sub-micron diagnostic substitution accelerates. The strongest counter-argument is that the 11.1% CAGR camp is right and that organ-on-chip and decentralized testing create a step-change in demand; we consider this plausible but not yet evidenced at scale, so we weight it as upside rather than base case.
Our judgment is that the market's economics reward qualification depth over raw capacity. The companies best positioned are those that can document pore uniformity, extractables, and lot traceability while offering customization—this is why Merck, Cytiva, and Sartorius hold regulated share, and why it4ip and SABEU are valuable design-in partners for OEMs.
Investors: Prioritize exposure to suppliers with qualified sub-micron capacity and OEM design-in pipelines, where pricing power is strongest.
Operators: Dual-qualify critical membranes and negotiate multi-year capacity agreements before diagnostic demand peaks.
Vendors: Invest in digital traceability and application engineering to defend share against cost-focused PET entrants.
Evidence that would change our conclusion: sustained double-digit sub-micron volume growth in clinical diagnostics, or a major capacity expansion at a low-cost Asian producer that compresses pricing.
Methodology
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and polymer film suppliers, specialized track-etch producers, contract membrane formatters, and global distributors. Decision-maker designations interviewed included VP Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, providing direct visibility into qualification cycles, pricing behavior, and capacity constraints.
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade and US ITC trade flows for polymer films and filtration media, Eurostat industrial statistics, corporate 10-K and annual investor filings, patent databases for track-etch process IP, and recognized technical standards from ISO and ASTM covering membrane pore-size characterization and extractables testing.
Demand Modeling & Market Sizing Triangulation
We triangulate Top-Down allocation from macroeconomic and life-science segment spend with Bottom-Up modeling of manufacturer capacity, product pricing, and end-use consumption. Divergences between methods are reconciled at the segment level, with outlier estimates flagged and scope-normalized.
Table 14: Europe Track etched Membrane Market Revenue Million Forecast, by Material Type 2020 & 2034
Table 15: Europe Track etched Membrane Market Revenue Million Forecast, by Pore Size 2020 & 2034
Table 16: Europe Track etched Membrane Market Revenue Million Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the track etched membrane market size?
The global track etched membrane market was valued at approximately 615 Million in 2024. At a base-case CAGR of 8.43%, it is projected to reach roughly 983 Million by 2030, driven by diagnostics, biopharma filtration, and environmental monitoring demand.
2. Which material dominates the track etched membrane market?
Polycarbonate holds the largest share at about 48.5% in 2024, prized for tensile strength, optical clarity, and isotropic pore geometry. PET is the fastest-growing material due to cost efficiency and suitability for single-use diagnostic cartridges.
3. Which region is fastest growing for track etched membranes?
Asia Pacific is the fastest-growing region, expanding at roughly 10.12% annually through 2030. North America remains the largest market at about 35% share, supported by biopharma R&D and diagnostic infrastructure.
4. Who are the key players in the track etched membrane market?
Leading vendors include Merck KGaA, Cytiva (Whatman), Sartorius, Sterlitech, it4ip, SABEU, and Advantec MFS. Incumbents compete on qualification depth and traceability, while niche players win on customization for OEM and organ-on-chip applications.
5. What applications use track etched membranes?
Track etched membranes are used in biomedical and diagnostic testing, pharmaceutical sterility filtration, environmental monitoring, and food and beverage testing. Biomedical and diagnostics is the largest application, while environmental monitoring is the fastest-growing segment.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and polymer film suppliers, specialized track-etch producers, contract membrane formatters, and global distributors. Decision-maker designations interviewed included VP Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, providing direct visibility into qualification cycles, pricing behavior, and capacity constraints.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
40%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Quality & Regulatory Leads
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Polymer Film & Raw Material Suppliers
40%
Specialized Track-Etch Producers
30%
Contract Formatters
15%
Global Distributors
15%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade and US ITC trade flows for polymer films and filtration media, Eurostat industrial statistics, corporate 10-K and annual investor filings, patent databases for track-etch process IP, and recognized technical standards from ISO and ASTM covering membrane pore-size characterization and extractables testing.
Demand Modeling & Market Sizing Triangulation
We triangulate Top-Down allocation from macroeconomic and life-science segment spend with Bottom-Up modeling of manufacturer capacity, product pricing, and end-use consumption. Divergences between methods are reconciled at the segment level, with outlier estimates flagged and scope-normalized.


 Track etched Membrane Market