 Infection Control Market
 Size, Trends & Forecast 2026-2031
Updated On : Nov 20, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Infection Control Market

Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 95.50 B |
| 2025 | 102.4 B |
| 2026 | 108.9 B |
| 2027 | 115.8 B |
| 2028 | 123.2 B |
| 2029 | 131.1 B |
| 2030 | 139.4 B |

The infection control market encompasses products, services, and technologies used to prevent, manage, and reduce healthcare-associated infections (HAIs) in medical settings. It includes sterilization equipment, disinfectants, protective barriers, single-use consumables, and outsourced reprocessing services deployed across hospitals, clinics, and ambulatory surgery centers.
This report covers the global infection control market across products and services (sterilization, cleaning and disinfection, protective barriers, consumables), service delivery modes (in-house vs. contract), and end-users (hospitals, ambulatory surgery centers, clinics). This analysis does not cover adjacent markets such as general medical waste management, pharmaceutical manufacturing cleanroom consumables, or water-treatment chemicals outside clinical settings.
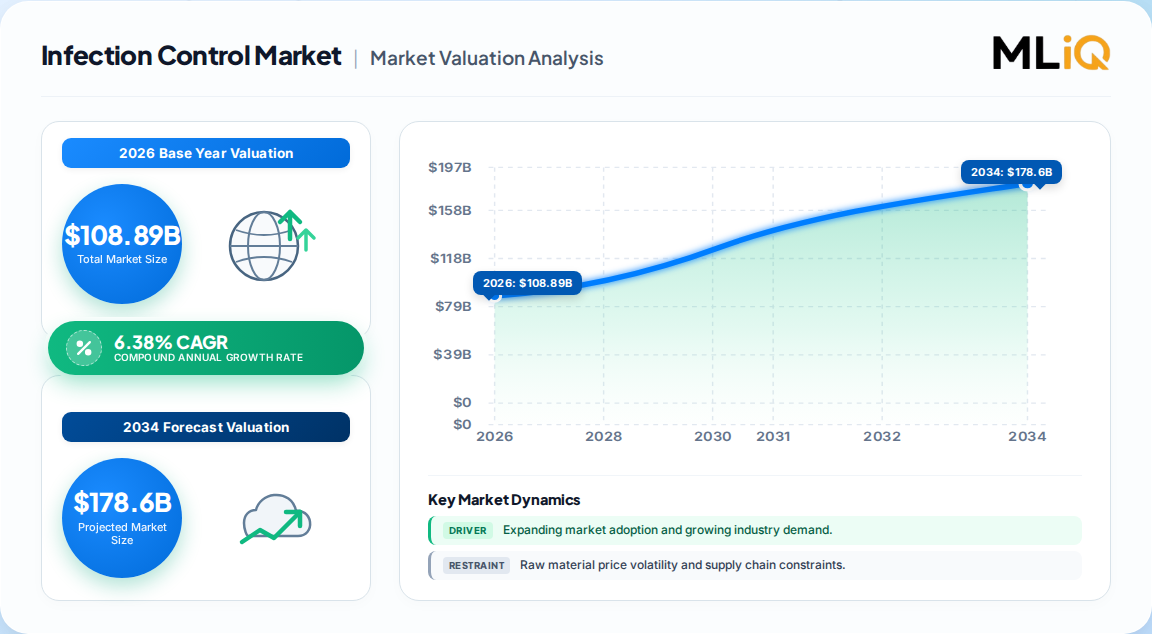
The global infection control market is estimated at USD 108.89 billion in 2026 and is projected to reach USD 148.37 billion by 2031, growing at 6.38% CAGR. This base case reflects accelerating adoption of low-temperature sterilizers, HAI-reduction reimbursement penalties, and sustained demand for single-use protective products.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 108.89 Billion | 2026 | 2031 (USD 148.37B) | 6.38% | Products & services: sterilization, cleaning/disinfection, protective barriers, consumables; in-house & contract modes; hospitals, ASCs, clinics | One published estimate (secondary source) |
| USD 227.21 Billion | 2024 | 2034 (USD 438.67B) | 6.80% | Broader consumables-led definition including single-use items, services, and equipment across all healthcare settings | Competing analysis (Novar One Advisor) |
| USD 22.3 Billion | 2025 | 2033 (USD 37.4B) | 6.70% | Narrower HAI-specific control segment (equipment, services, consumables) within hospital and ICU settings only | Grand View Research (secondary benchmark) |
Our analysis suggests the USD 108.89 billion base is the most defensible for a holistic market view because it captures the full sterilization and disinfection value chain while acknowledging the outsourcing shift. The higher USD 227 billion figure likely includes broad consumables categories (gloves, masks, needles) that overlap with general medical supplies, inflating the addressable market. The narrower USD 22.3 billion HAI-control estimate undercounts preventive sterilization and disinfection spending outside acute-care ICUs. Buyers should anchor strategic planning to the mid-range base and adjust for segment-level growth differentials.
The infection control market is segmented by products and services, service delivery mode, and end-user. Sterilization products and services dominate at 42.10% share, followed by cleaning and disinfection products and protective barriers. Service delivery is split between in-house programs (53.40%) and contract services, while hospitals and clinics represent 37.80% of end-user demand.
| Parent Segment | Children | 2025 Share / Growth |
|---|---|---|
| By Products & Services | Sterilization Products & Services, Cleaning & Disinfection Products, Protective Barriers, Consumables, Others | Sterilization 42.10%; Protective barriers 6.66% CAGR |
| By Service Delivery Mode | In-House Infection Control, Contract Infection Control | In-house 53.40%; Contract 6.62% CAGR |
| By End-User | Hospitals & Clinics, Ambulatory Surgery Centers, Diagnostic Centers, Others | Hospitals 37.80%; ASCs 6.74% CAGR |
North America leads the infection control market with 38.95% revenue share in 2025, driven by stringent CMS reimbursement penalties and early adoption of low-temperature sterilizers. Asia-Pacific is the fastest-growing region at 6.85% CAGR, propelled by China's healthcare spending expansion and rising HAI awareness.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.24% |
| Asia-Pacific | 0.28% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
| Parent Region | Children (Countries) | 2025 Share |
|---|---|---|
| North America | USA, Canada, Mexico | 38.95% |
| Europe | Germany, UK, France, Italy, Spain, Rest of Europe | ~24% |
| Asia-Pacific | China, Japan, India, South Korea, Australia, Rest of APAC | ~28% |
| Latin America | Brazil, Mexico, Argentina, Rest of LATAM | ~7% |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Rest of MEA | ~5% |
Growth is primarily driven by stringent HAI-reduction targets (+1.2% CAGR impact), procedure volume surges (+1.5%), contract sterilization outsourcing (+0.8%), and rapid adoption of low-temperature and plasma sterilizers (+0.9%). Restraints include antimicrobial resistance reducing disinfectant efficacy (-1.1%), safety concerns around reprocessed instruments (-0.9%), and capital-intensive sterilization equipment (-0.7%).
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| HAI-reduction targets & reimbursement penalties | Driver | High (CMS, state policies) | Hospitals invest in compliance-driven equipment upgrades |
| Procedure volume surge from chronic & geriatric disease | Driver | High (demographic data) | Inpatient discharges to 31M; outpatient procedures to 5.82B by 2034 |
| Contract sterilization outsourcing | Driver | Medium (Sterigenics 48 sites, 2,000+ clients) | EtO compliance costs (up to USD 900M) push facilities to outsource |
| Low-temperature & plasma sterilizers | Driver | High (95% sterilization in 75 min) | Heat-sensitive instrument compatibility; no toxic residue |
| Antimicrobial resistance reducing disinfectant efficacy | Restraint | High (biocide-tolerant Klebsiella outbreaks) | Requires newer, more expensive disinfectant formulations |
| Safety & liability concerns around reprocessed instruments | Restraint | Medium (ANSI/AAMI ST24 guidance) | Litigation risk delays upgrades and adoption |
| Capital-intensive advanced sterilization equipment | Restraint | Medium (HVAC, monitoring, training costs) | Stretches payback periods, especially in emerging markets |
The balance of evidence favors drivers over restraints through 2031, with net positive impact on CAGR. The outsourcing boom and low-temperature sterilization adoption are mutually reinforcing: as hospitals avoid capital outlays for EtO-compliant equipment, specialist contract sterilizers achieve scale economies that further lower per-unit costs. However, antimicrobial resistance is a wildcard that could accelerate demand for advanced disinfectants while simultaneously eroding the efficacy of legacy products.
The infection control market is moderately concentrated, with STERIS, Advanced Sterilization Products (ASP), Getinge, Sterigenics (Sotera Health), and Ecolab as leading players. Competition hinges on low-temperature sterilization clearances, AI-driven surveillance platforms, and contract-service compliance expertise. Differentiation is increasingly defined by the ability to offer integrated hardware-plus-service models that amortize regulatory costs across multiple clients.
| Company | Primary Focus | Key Differentiator |
|---|---|---|
| STERIS | Sterilization equipment & consumables | Broad portfolio; duodenoscope processing clearances |
| Advanced Sterilization Products (ASP) | Low-temperature hydrogen peroxide gas plasma | FDA clearances for complex endoscope reprocessing |
| Getinge | Sterilization & disinfection systems | T-DOC sterile supply management; digital traceability |
| Sterigenics (Sotera Health) | Contract sterilization services | 48 sites across 13 countries; 2,000+ clients |
| Ecolab | Cleaning & disinfection chemicals | Global distribution; infection prevention programs |
Procurement decisions in infection control hinge on regulatory compliance (EPA EtO rules, ANSI/AAMI ST24), total cost of ownership (HVAC retrofits, staff training, monitoring), and clinical workflow impact (cycle times, instrument compatibility). Buyers should prioritize vendors that offer validated reprocessing protocols for complex lumened devices and digital traceability to reduce liability exposure. Switching costs are high due to capital equipment lock-in and staff retraining, so multi-year service contracts with performance guarantees are common. Operators must also evaluate contract sterilization partnerships as a hedge against compliance cost volatility, particularly for smaller facilities where capital outlays are prohibitive.
The balance of evidence favors a cautiously optimistic outlook for the infection control market through 2031, with the 6.38% CAGR representing a durable mid-cycle growth trajectory rather than a pandemic-driven spike. The strongest counter-argument is that antimicrobial resistance could accelerate faster than sterilization technology innovation, eroding the efficacy of current disinfectants and forcing a disruptive re-rating of legacy product portfolios. However, this risk is partially offset by the same trend driving demand for advanced, higher-margin disinfection chemistries.
Our analysis suggests the most significant second-order effect is the structural shift toward contract sterilization, which transforms infection control from a capital-expenditure decision into an operating-expense decision for hospitals. This lowers the barrier to adoption for smaller facilities and accelerates technology diffusion, but it also concentrates compliance risk and bargaining power among a handful of specialist operators. Vendors without a services component may find themselves disintermediated.
Actionable Strategy:
What would change our conclusion: A faster-than-expected FDA approval of novel sterilization modalities (e.g., nitrogen dioxide or supercritical CO2) could disrupt the low-temperature plasma dominance and compress margins for incumbents. Additionally, if CMS expands reimbursement penalties beyond HAIs to include environmental contamination metrics, the addressable market for surveillance and disinfection services could expand materially.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.38% from 2020-2034 |
| Segmentation |
|
The global infection control market is estimated at USD 108.89 billion in 2026, growing at a 6.38% CAGR to reach USD 148.37 billion by 2031, driven by HAI-reduction mandates and low-temperature sterilization adoption.
North America leads with 38.95% revenue share in 2025, supported by stringent CMS reimbursement penalties and early adoption of advanced sterilization technologies. Asia-Pacific is the fastest-growing region at 6.85% CAGR.
Key drivers include stringent HAI-reduction targets (+1.2% CAGR impact), procedure volume surges (+1.5%), contract sterilization outsourcing (+0.8%), and rapid adoption of low-temperature and plasma sterilizers (+0.9%).
Leading vendors include STERIS, Advanced Sterilization Products (ASP), Getinge, Sterigenics (Sotera Health), and Ecolab, competing on low-temperature sterilization clearances, AI surveillance, and contract-service compliance expertise.
Contract infection control services are the fastest-growing service delivery mode at 6.62% CAGR, while ambulatory surgery centers are the fastest-growing end-user segment at 6.74% CAGR through 2031.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split, anchoring market sizing in direct industry engagement. We conducted in-depth interviews with stakeholders across the value chain, including raw material and specialty chemical suppliers, sterilization equipment manufacturers, contract formulators and disinfectant producers, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, innovation, and commercialization perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 35% |
| Heads of R&D & Innovation | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Sterilization Equipment Manufacturers | 40% |
| Disinfectant & Chemical Formulators | 30% |
| Contract Sterilization Service Providers | 20% |
| Distributors & Traders | 10% |
We triangulate primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. This validation layer ensures that market sizing reflects actual trade flows and corporate performance rather than survey-level estimates alone.
Our demand modeling simultaneously applies Top-Down macroeconomic and industry segment allocation with Bottom-Up manufacturer capacity, product pricing, and end-use consumption modeling. This dual approach captures both macro-level demand signals and micro-level supply constraints, producing a reconciled market estimate with a defined confidence interval.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |