Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Friction Modifiers Market: Size, CAGR & 2032 Outlook
Friction Modifiers Market
Friction Modifiers Market: Size, CAGR & 2032 Outlook
Friction Modifiers Market by Type (Organic, Organomolybdenum, Polymer), by Compound Class (Organic, Inorganic), by Application (Commercial Vehicle Lubricants, Passenger Vehicle Lubricants, Industrial Lubricants, Rail Lubricants, Aviation Lubricants, Power Generation Lubricants), by Base Oil Compatibility (Mineral, Synthetic, Bio-based), by Function (Anti-wear Performance, Fuel Efficiency Enhancement, Thermal Stability Improvement), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea, Southeast Asia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
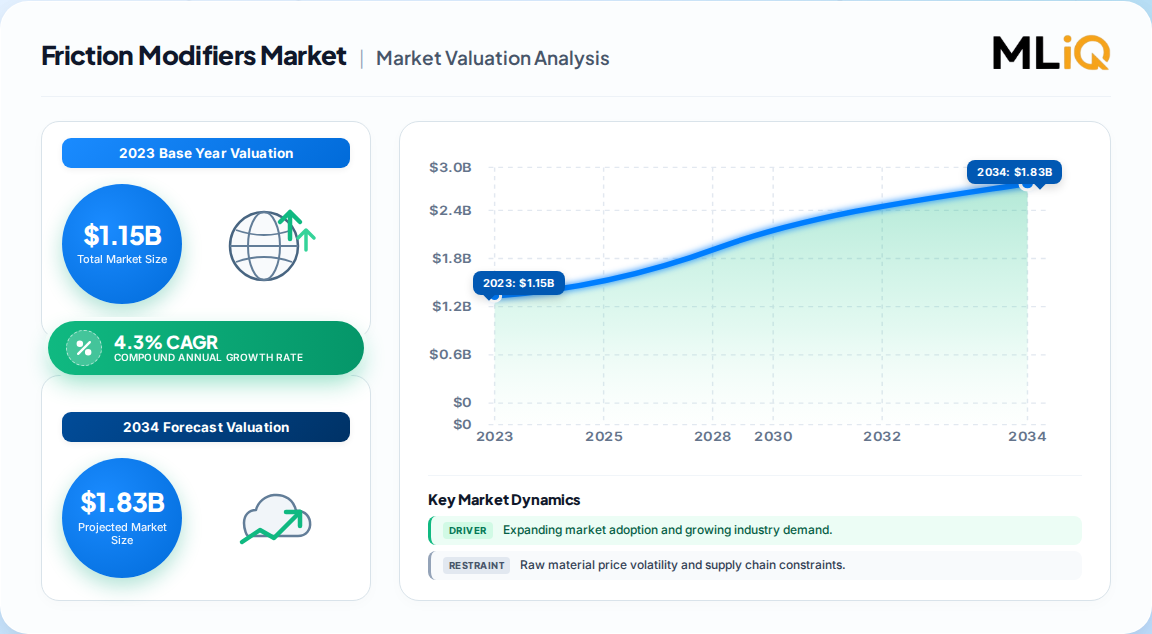
The global friction modifiers market was valued at 1.15 Billion in 2023 and is forecast to reach 1.68 Billion by 2032, a 4.3% CAGR.
Organic friction modifiers led the product mix with roughly 56% share in 2023, favored for base-oil compatibility and environmental profiles.
Commercial vehicles dominate end-use demand at approximately 64% of 2025 revenue, anchored by heavy-duty engine-oil volume growth.
Asia-Pacific is the largest and fastest-growing region, holding around 35.5% of 2025 revenue on automotive output and industrial expansion.
Leading vendors include Afton Chemical, Lubrizol, BASF, Croda, Infineum, ADEKA, and Chevron, competing on additive-package breadth.
Why this matters for decision-makers: Formulators must qualify organic and low-viscosity-compatible chemistry now, because fuel-economy mandates are shifting specification advantage toward suppliers with OEM engine-test validation.
Friction Modifiers Market Size (In Billion)
1.5B
1.0B
500.0M
0
1.150 B
2023
1.200 B
2024
1.250 B
2025
1.300 B
2026
1.360 B
2027
1.420 B
2028
1.480 B
2029
Friction Modifiers Market Size (In Billion)
Year
Market Size
2023
1.150 B
2024
1.200 B
2025
1.250 B
2026
1.300 B
2027
1.360 B
2028
1.420 B
2029
1.480 B
What is the Friction Modifiers Market?
The friction modifiers market covers oil-soluble chemical additives blended into lubricants and functional fluids to alter frictional characteristics, reduce wear between moving surfaces, and support fuel-economy gains. Products serve engine, transmission, industrial, rail, aviation, and power-generation lubricants, typically spanning organic, organomolybdenum, and polymer chemistries.
Scope: what this report covers and excludes
This analysis covers global demand for friction modifier additives by chemistry type (organic, organomolybdenum, polymer, inorganic), compound class (organic versus inorganic), application (passenger and commercial vehicle lubricants, industrial lubricants, rail, aviation, power generation), and base-oil compatibility across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa.
It quantifies base-year sizing, forecast CAGR, segment shares, vendor positioning, and procurement dynamics. This analysis does not cover base oils, viscosity index improvers, anti-wear additives, dispersants, or finished lubricant retail pricing, which are addressed in adjacent additive and lubricant reports.
How big is the market for Friction Modifiers Market?
Published estimates cluster around a 1.0–1.8 Billion base with 3.4–4.3% growth, but the gap is definitional rather than contradictory. The narrower 1.15 Billion reading reflects friction-modifier additives alone; broader 1.8 Billion scopes bundle polymer and MoDTC additives with adjacent functional-fluid chemistries.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
1.15 Billion
2023
2032
4.3%
Friction modifier additives, all chemistries
One published estimate
1.0 Billion
2025
2033
3.8%
Organic and inorganic types, vehicle-led applications
A competing analysis
0.96 Billion
2025
2032
3.4%
Organic, metal-containing modifiers, transport and industrial
A competing analysis
1.8 Billion
2026
2036
4.3%
Broader additive definition incl. polymer and MoDTC
A competing analysis
Our analysis suggests the 1.15 Billion (2023) figure is the most defensible anchor for pure friction-modifier spend, because it aligns with the organic-plus-organomolybdenum revenue split and a mid-single-digit volume trajectory. The 1.8 Billion reading implies a different product boundary rather than a demand disagreement, so buyers comparing vendors should normalize for included chemistries before negotiating on price.
How is the market segmented?
Segmentation is best read along chemistry first, application second, because chemistry determines base-oil compatibility and qualification effort. Organic modifiers carry the largest revenue base, while organomolybdenum and polymer types capture premium high-load and extreme-condition niches respectively.
Parent segment
Children
Share signal
By Type
Organic, Organomolybdenum, Polymer
Organic ~56–57%
By Compound Class
Organic, Inorganic
Organic ~56%
By Application
Commercial vehicles, Passenger vehicles, Industrial, Rail, Aviation, Power generation
Commercial ~64%
By Base Oil Compatibility
Mineral, Synthetic, Bio-based
Mineral ~39%
By Function
Anti-wear, Fuel-efficiency, Thermal stability
Anti-wear ~46%
Which region leads in Friction Modifiers Market?
Asia-Pacific leads with approximately 35.5% of global revenue, driven by Chinese and Indian automotive output, lubricant blending capacity, and industrial equipment maintenance spend. North America is the fastest-growing region on tightening fuel-economy rules and low-viscosity oil adoption.
Friction Modifiers Market Regional Market Share
Loading chart...
Friction Modifiers Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.4%
North America
0.24%
Europe
0.22%
Latin America
0.09%
Middle East & Africa
0.07%
Global
Asia-Pacific (China, Japan, India, South Korea, Southeast Asia)
North America (USA, Canada, Mexico)
Europe (Germany, UK, France, Italy)
Latin America (Brazil, Argentina, Mexico)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
Our analysis suggests regional share will shift only modestly through 2032; Asia-Pacific's advantage is structural, rooted in blending capacity rather than temporary pricing. The more decisive variable is specification stringency: North American and European OEM approvals increasingly gate premium volumes, so regional share understates where margin concentrates.
What is driving growth — and what is holding it back?
Fuel-economy and emissions regulation is the primary demand engine, reinforced by low-viscosity oil adoption and commercial-vehicle fleet expansion. Restraints are cost and technology driven: raw-material volatility compresses formulator margins, while electrification threatens long-run internal-combustion additive volumes.
The balance favors Growth. Regulatory drivers are legislated and near-term, while electrification risk is longer-dated and partly offset by hybrid and commercial-vehicle lubricant demand. Our analysis suggests the binding constraint is not demand but qualification capacity: OEM engine-test slots and specification cycles limit how fast new chemistry reaches volume.
Who are the leading vendors?
Competition is concentrated among integrated additive-package suppliers that combine chemistry portfolios with OEM engine-test validation and global blending support. Afton, Lubrizol, Infineum, BASF, and Croda anchor the premium tier, with ADEKA, Chevron, and specialty players serving regional and niche demand.
Vendor
Primary strength
Differentiation
Afton Chemical
Full additive packages
Broad OEM approvals
Lubrizol
Formulation depth
Bio-based and specialty chemistry
BASF SE
Integrated chemicals
Global supply reliability
Croda International
Organic chemistry
Ester and amide specialities
Infineum
Drivetrain and engine
Specification compliance
ADEKA
Organomolybdenum
High-load performance
The moat is specification lock-in rather than raw-material access. Once a modifier is qualified into an OEM oil formulation, switching costs rise sharply because requalification requires engine testing. This implies incumbents with test infrastructure will capture disproportionate share of premium, low-viscosity growth.
What do buyers and operators need to know? (Decision Support)
Selection hinges on three mission-critical criteria: base-oil compatibility, boundary-lubrication performance under the target oil's viscosity grade, and documented OEM or industry-spec compliance. Buyers should request engine-test evidence, not just bench friction data, because bench results poorly predict sequence-test outcomes in low-viscosity formulations.
Procurement risk concentrates in supply continuity and reformulation exposure. Single-sourcing an organomolybdenum modifier exposes blenders to molybdenum price swings, while organic alternatives reduce that exposure but may require requalification. Switching costs are material: requalification can consume months of test capacity and delay product launches.
Regulatory compliance is a growing gate. Formulators must track evolving emissions and fuel-economy rules across jurisdictions, plus chemical registration requirements that differ by region. Our analysis suggests buyers should build dual-chemistry qualified supply, pairing an organic primary with a secondary polymer or organomolybdenum option, to hedge both price and specification risk.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors steady, regulation-led growth at a mid-single-digit CAGR, with the 1.15 Billion (2023) to 1.68 Billion (2032) trajectory the most defensible planning base. Demand is not commodity-cyclical; it is tied to legislated fuel-economy outcomes, which gives visibility that most specialty chemicals lack. The strongest counter-argument is electrification: if BEV penetration accelerates faster than consensus in passenger vehicles, long-run engine-oil additive volumes would compress, though commercial vehicles and hybrids cushion the near term.
Our analysis suggests margin, not volume, is the decisive battleground. Vendors that combine organic chemistry with OEM engine-test validation will capture specification-led premium pricing, while undifferentiated suppliers face compression from raw-material volatility and import competition. Buyers should treat qualification capacity as the scarce resource and reserve test slots early.
The key evidence that would change this conclusion is a faster-than-expected shift in OEM oil specifications toward chemistries that reduce friction-modifier loading, or a sharp BEV inflection in commercial fleets. Absent those, the growth path holds.
Investors should prioritize additive suppliers with documented OEM approvals and organic-chemistry portfolios, not lowest-cost producers.
Operators should qualify a dual-chemistry supply base to hedge molybdenum price and specification risk.
Formulators should align R&D roadmaps with GF-7 and low-viscosity specifications to secure early qualification advantage.
Friction Modifiers Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Friction Modifiers Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.3% from 2020-2034
Segmentation
By Type
Organic
Organomolybdenum
Polymer
By Compound Class
Organic
Inorganic
By Application
Commercial Vehicle Lubricants
Passenger Vehicle Lubricants
Industrial Lubricants
Rail Lubricants
Aviation Lubricants
Power Generation Lubricants
By Base Oil Compatibility
Mineral
Synthetic
Bio-based
By Function
Anti-wear Performance
Fuel Efficiency Enhancement
Thermal Stability Improvement
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Friction Modifiers Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Friction Modifiers Market Executive Summary
2.1. Market Snapshot
3. Friction Modifiers Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Friction Modifiers Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Friction Modifiers Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. Organic
5.1.2. Organomolybdenum
5.1.3. Polymer
5.2. Analysis, Insights and Forecast - by Compound Class
5.2.1. Organic
5.2.2. Inorganic
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Commercial Vehicle Lubricants
5.3.2. Passenger Vehicle Lubricants
5.3.3. Industrial Lubricants
5.3.4. Rail Lubricants
5.3.5. Aviation Lubricants
5.3.6. Power Generation Lubricants
5.4. Analysis, Insights and Forecast - by Base Oil Compatibility
5.4.1. Mineral
5.4.2. Synthetic
5.4.3. Bio-based
5.5. Analysis, Insights and Forecast - by Function
5.5.1. Anti-wear Performance
5.5.2. Fuel Efficiency Enhancement
5.5.3. Thermal Stability Improvement
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Friction Modifiers Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. Organic
6.1.2. Organomolybdenum
6.1.3. Polymer
6.2. Analysis, Insights and Forecast - by Compound Class
6.2.1. Organic
6.2.2. Inorganic
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Commercial Vehicle Lubricants
6.3.2. Passenger Vehicle Lubricants
6.3.3. Industrial Lubricants
6.3.4. Rail Lubricants
6.3.5. Aviation Lubricants
6.3.6. Power Generation Lubricants
6.4. Analysis, Insights and Forecast - by Base Oil Compatibility
6.4.1. Mineral
6.4.2. Synthetic
6.4.3. Bio-based
6.5. Analysis, Insights and Forecast - by Function
6.5.1. Anti-wear Performance
6.5.2. Fuel Efficiency Enhancement
6.5.3. Thermal Stability Improvement
7. Friction Modifiers Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. Organic
7.1.2. Organomolybdenum
7.1.3. Polymer
7.2. Analysis, Insights and Forecast - by Compound Class
7.2.1. Organic
7.2.2. Inorganic
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Commercial Vehicle Lubricants
7.3.2. Passenger Vehicle Lubricants
7.3.3. Industrial Lubricants
7.3.4. Rail Lubricants
7.3.5. Aviation Lubricants
7.3.6. Power Generation Lubricants
7.4. Analysis, Insights and Forecast - by Base Oil Compatibility
7.4.1. Mineral
7.4.2. Synthetic
7.4.3. Bio-based
7.5. Analysis, Insights and Forecast - by Function
7.5.1. Anti-wear Performance
7.5.2. Fuel Efficiency Enhancement
7.5.3. Thermal Stability Improvement
8. Friction Modifiers Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. Organic
8.1.2. Organomolybdenum
8.1.3. Polymer
8.2. Analysis, Insights and Forecast - by Compound Class
8.2.1. Organic
8.2.2. Inorganic
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Commercial Vehicle Lubricants
8.3.2. Passenger Vehicle Lubricants
8.3.3. Industrial Lubricants
8.3.4. Rail Lubricants
8.3.5. Aviation Lubricants
8.3.6. Power Generation Lubricants
8.4. Analysis, Insights and Forecast - by Base Oil Compatibility
8.4.1. Mineral
8.4.2. Synthetic
8.4.3. Bio-based
8.5. Analysis, Insights and Forecast - by Function
8.5.1. Anti-wear Performance
8.5.2. Fuel Efficiency Enhancement
8.5.3. Thermal Stability Improvement
9. Friction Modifiers Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. Organic
9.1.2. Organomolybdenum
9.1.3. Polymer
9.2. Analysis, Insights and Forecast - by Compound Class
9.2.1. Organic
9.2.2. Inorganic
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Commercial Vehicle Lubricants
9.3.2. Passenger Vehicle Lubricants
9.3.3. Industrial Lubricants
9.3.4. Rail Lubricants
9.3.5. Aviation Lubricants
9.3.6. Power Generation Lubricants
9.4. Analysis, Insights and Forecast - by Base Oil Compatibility
9.4.1. Mineral
9.4.2. Synthetic
9.4.3. Bio-based
9.5. Analysis, Insights and Forecast - by Function
9.5.1. Anti-wear Performance
9.5.2. Fuel Efficiency Enhancement
9.5.3. Thermal Stability Improvement
10. Friction Modifiers Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. Organic
10.1.2. Organomolybdenum
10.1.3. Polymer
10.2. Analysis, Insights and Forecast - by Compound Class
10.2.1. Organic
10.2.2. Inorganic
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Commercial Vehicle Lubricants
10.3.2. Passenger Vehicle Lubricants
10.3.3. Industrial Lubricants
10.3.4. Rail Lubricants
10.3.5. Aviation Lubricants
10.3.6. Power Generation Lubricants
10.4. Analysis, Insights and Forecast - by Base Oil Compatibility
10.4.1. Mineral
10.4.2. Synthetic
10.4.3. Bio-based
10.5. Analysis, Insights and Forecast - by Function
Table 16: Europe Friction Modifiers Market Revenue Billion Forecast, by Type 2020 & 2034
Frequently Asked Questions
1. How big is the friction modifiers market?
The global friction modifiers market was valued at approximately 1.15 Billion in 2023 and is forecast to reach 1.68 Billion by 2032, growing at a 4.3% CAGR driven by fuel-efficient lubricant demand.
2. Which region dominates friction modifier demand?
Asia-Pacific leads with roughly 35.5% of global revenue, supported by automotive production and industrial expansion in China and India. North America is the fastest-growing region on stringent fuel-economy regulation.
3. What are the main types of friction modifiers?
The market divides into organic, organomolybdenum, and polymer friction modifiers, plus organic versus inorganic compound classes. Organic modifiers hold the largest share at approximately 56% due to base-oil compatibility and environmental profile.
4. Who are the leading friction modifier suppliers?
Leading suppliers include Afton Chemical, Lubrizol, BASF, Croda International, Infineum, ADEKA, and Chevron. Competition centers on additive-package breadth, OEM engine-test validation, and formulation support for lubricant blenders.
5. What is restraining friction modifier market growth?
Raw-material price volatility compresses formulator margins, while battery-electric vehicle adoption and potential combustion-engine bans threaten long-run engine-oil additive volumes. Technological obsolescence also forces continuous R&D reinvestment.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement to validate sizing and specification dynamics. We conducted in-depth interviews across the value chain with raw-material and chemical producers, specialized friction-modifier manufacturers, contract formulators and lubricant blenders, and global additive distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring both technical qualification and procurement economics are captured.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
40%
Procurement & Sourcing Directors
35%
Quality & Regulatory Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Chemical Producers
40%
Formulators & Lubricant Blenders
35%
Distributors & Traders
25%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade databases (UN Comtrade, USITC DataWeb, Eurostat), corporate annual filings and SEC 10-K disclosures, patent databases tracking friction-modifier chemistry, and recognized technical standards bodies including ASTM and SAE lubricant specification committees. These sources anchor import-export flows, capacity announcements, and specification timelines.
Demand Modeling & Market Sizing Triangulation
We triangulate simultaneously through a Top-Down model allocating macroeconomic automotive and industrial output to lubricant additive intensity, and a Bottom-Up model built from manufacturer capacity, product pricing, and end-use consumption by application. Divergences between the two are resolved through primary interview evidence and trade-flow cross-checks.


 Friction Modifiers Market