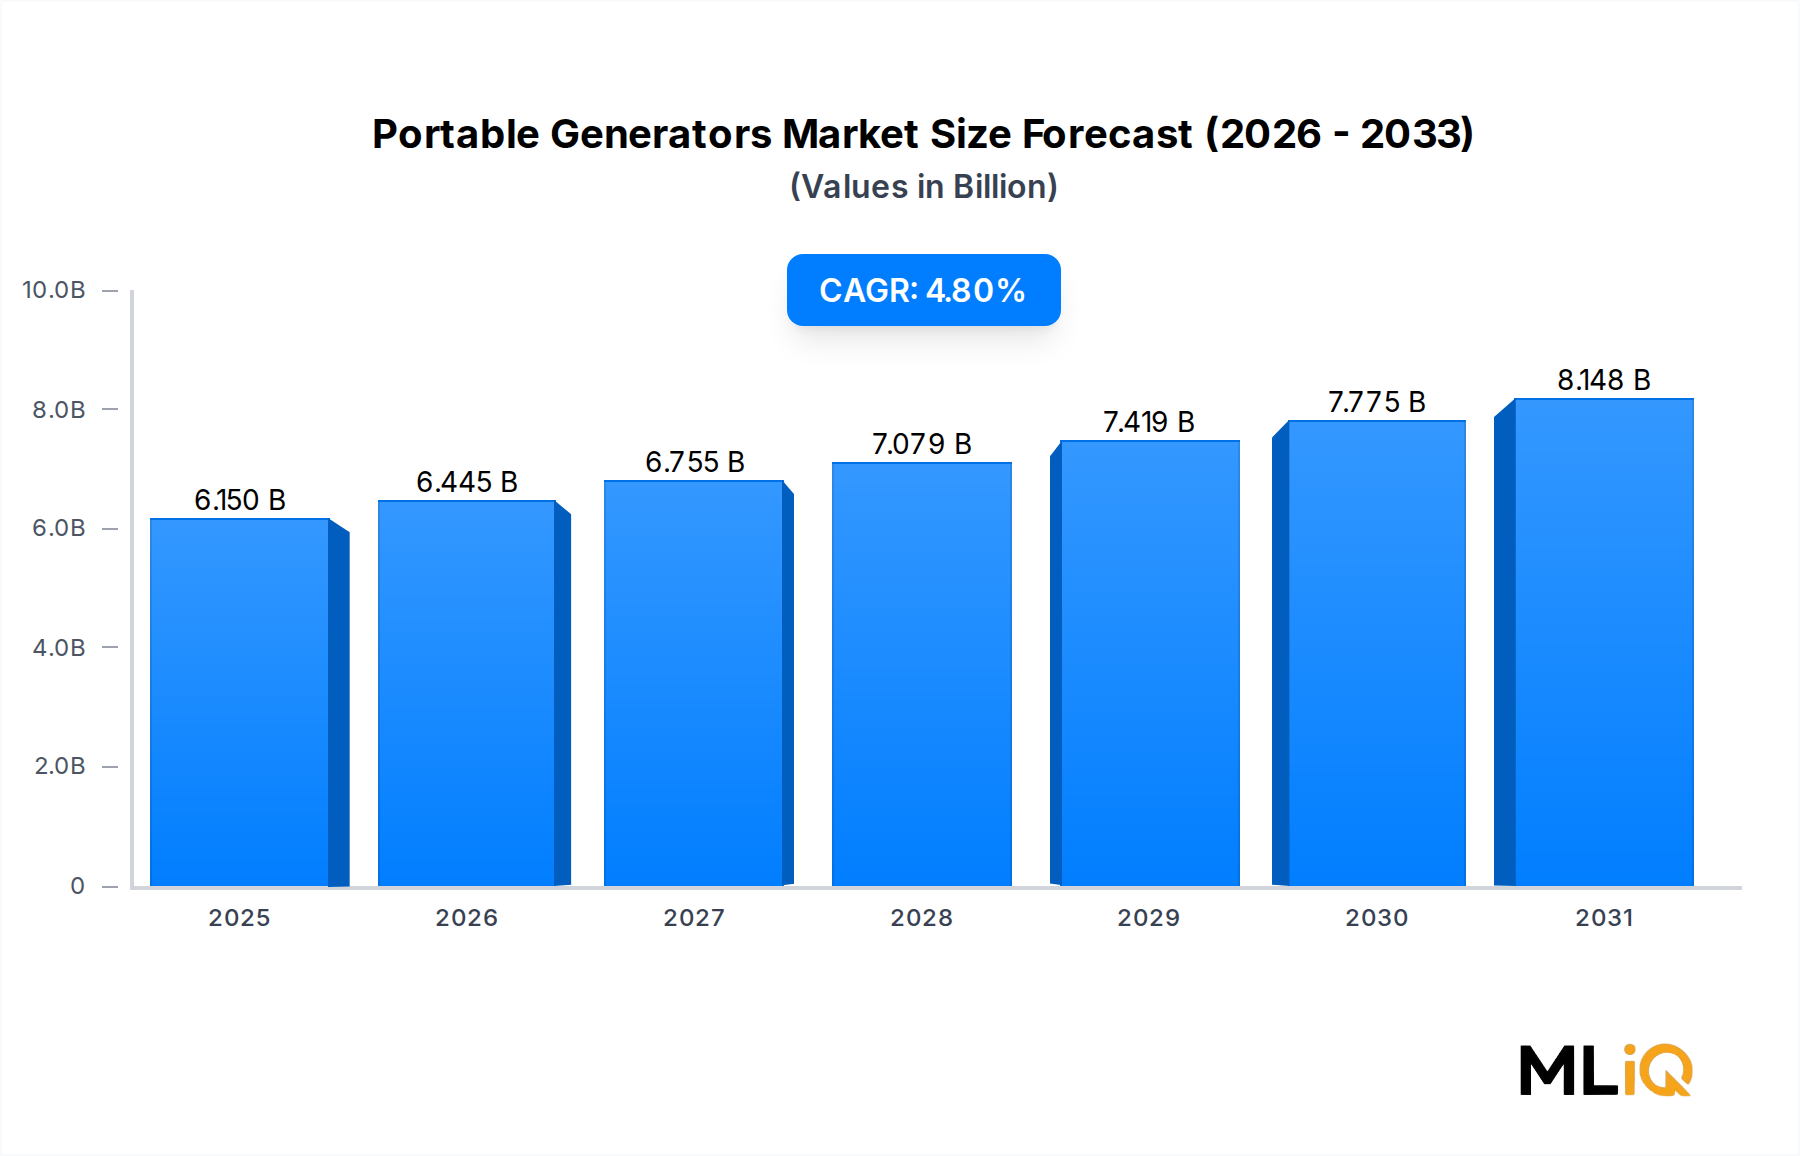
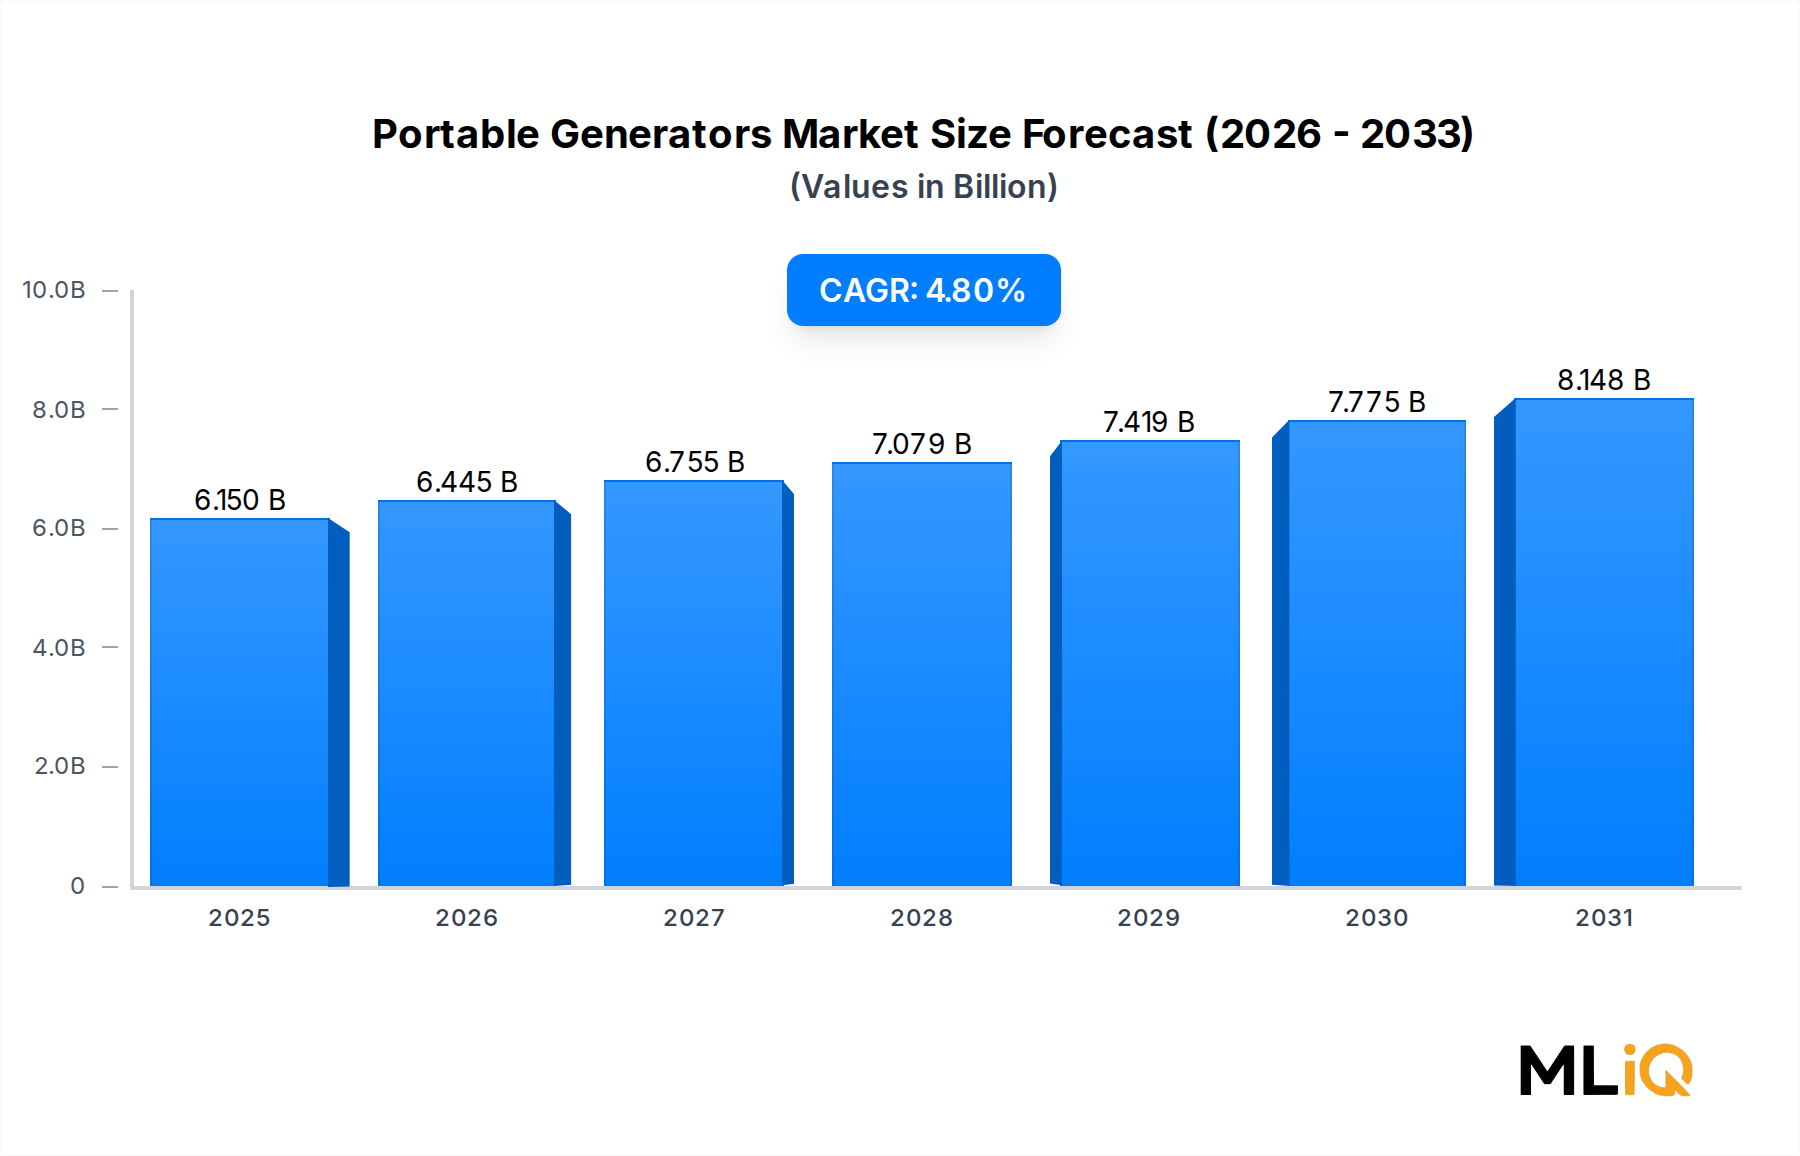
The global portable generators market is entering a structurally reinforced growth phase, underpinned by escalating grid instability, expanding off-grid construction activity, and a secular rise in disaster preparedness spending among residential and commercial end-users. Valued at USD 6.15 billion in the base year 2025, the market is projected to reach approximately USD 9.02 billion by 2033, expanding at a CAGR of 4.8% across the forecast period.
This trajectory is not incidental. Macro-level forces—including the intensification of weather-related power outages, accelerating electrification of remote infrastructure in emerging economies, and the surge in outdoor recreational and event industries—collectively sustain baseline demand above cyclical fluctuations. In parallel, regulatory pressure to reduce carbon emissions is bifurcating product demand: traditional gasoline and diesel units continue to dominate by volume, while hybrid and inverter-based configurations gain traction among premium-tier buyers.
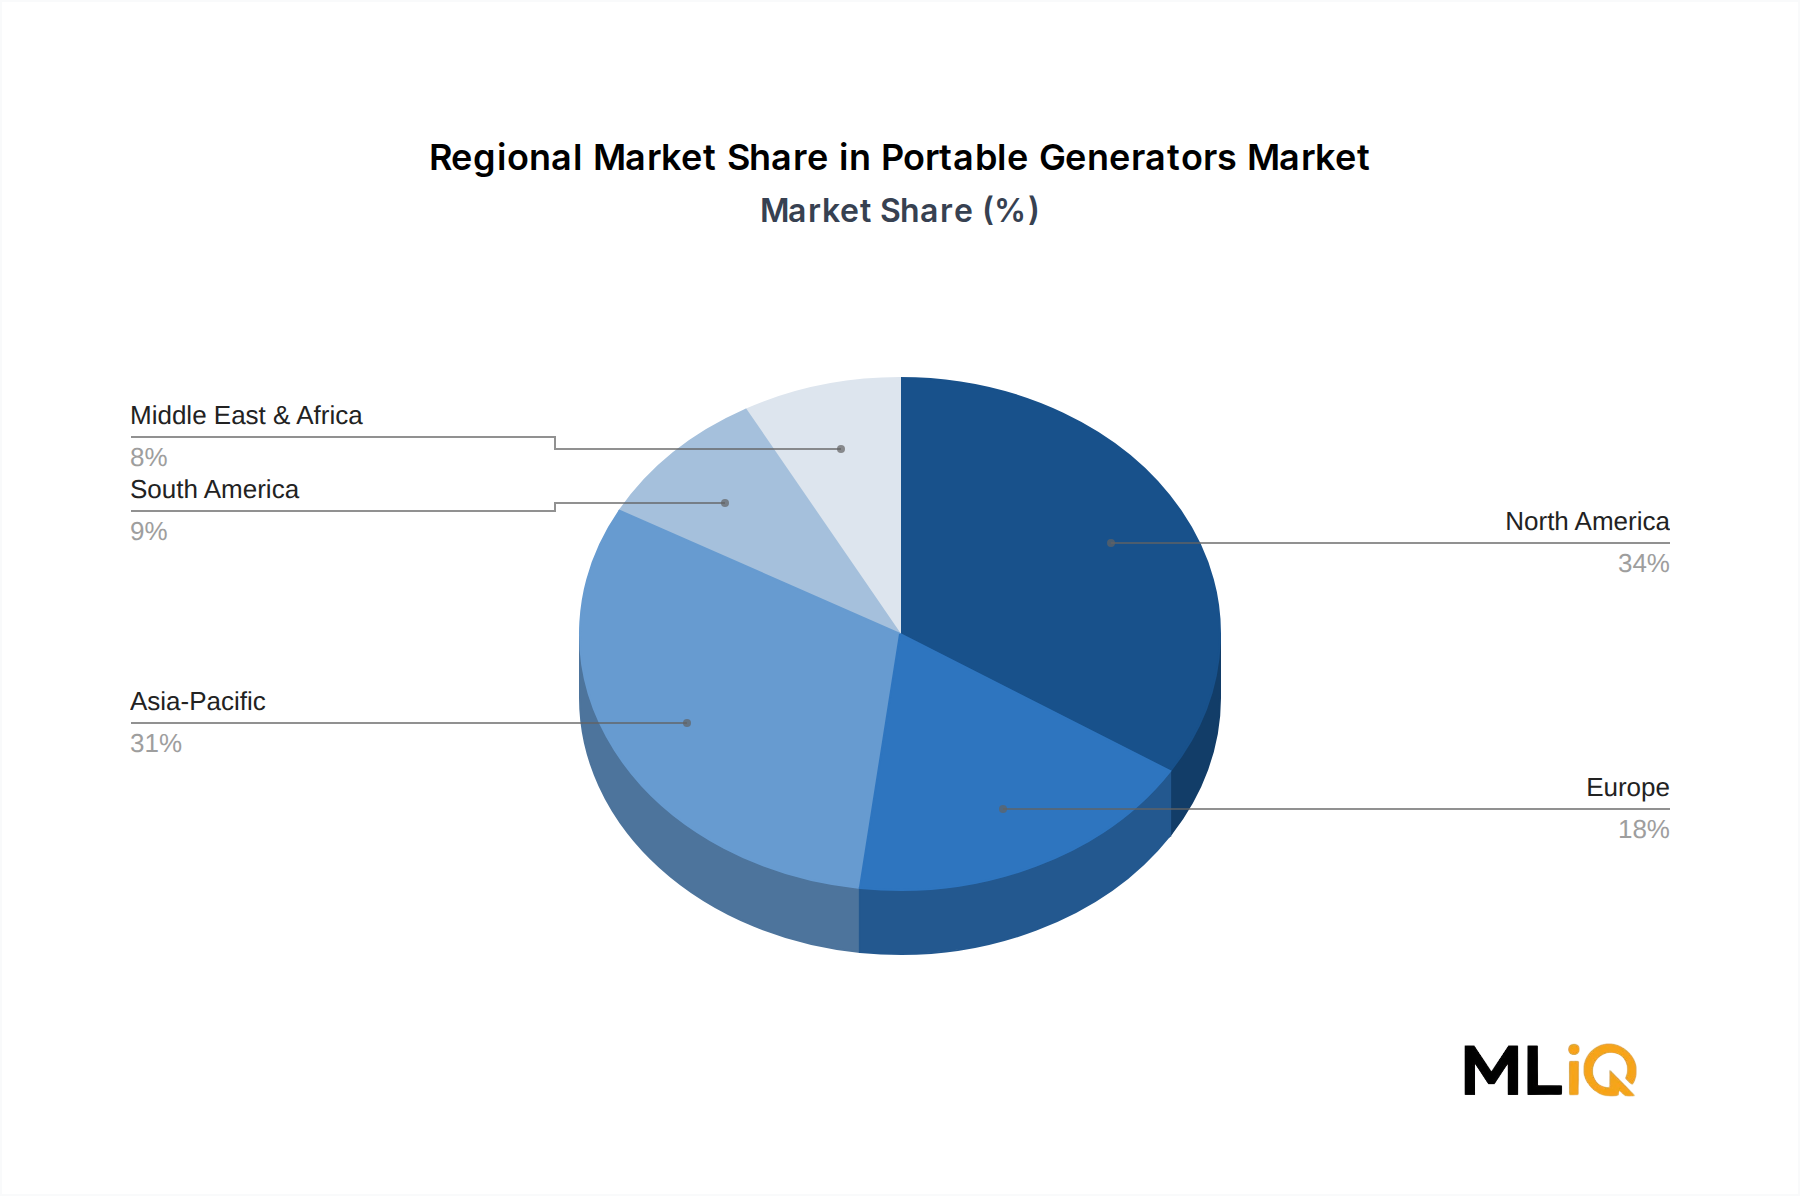
North America retains its commanding market position, driven by high household generator penetration rates, frequent extreme weather events, and a mature retail and e-commerce distribution infrastructure. Asia-Pacific, however, is emerging as the most dynamic growth corridor, fueled by rapid urbanization, frequent power shortages in developing nations such as India and across ASEAN, and accelerating construction expenditure in Southeast Asia.
From a competitive standpoint, the market exhibits a moderately consolidated structure. Generac Power Systems, Honda Motor Co., Ltd., Briggs & Stratton Corporation, and Kohler Co. collectively command a substantial revenue share, leveraging brand trust, extensive distribution networks, and technological innovation. Emerging players and regional manufacturers are intensifying competition in the sub-3kW and mid-range 3–10kW segments, particularly across Asia-Pacific and Africa.
Strategic investment themes include the integration of CO-Sense and automatic carbon monoxide shutdown technology—now mandated in several U.S. states—inverter-based quiet-operation models for residential use, and dual-fuel configurations that provide operational flexibility between gasoline and propane. These product innovations are reshaping purchase decisions and driving upward average selling price (ASP) migration across core segments.
In summary, the portable generators market presents a compelling, multi-dimensional investment and competitive landscape for stakeholders across manufacturing, distribution, and end-use verticals.