Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Physical Security Market Forecast & 6.5% CAGR
Physical Security Market
Physical Security Market Forecast & 6.5% CAGR
Physical Security Market by Component (System, Services), by Systems Type (Physical Access System, Video Surveillance System, Perimeter Intrusion and Detection, Physical Security Information Management, Others), by Service Type (Access Control as a Service, Video Surveillance as a Service, Remote Monitoring Services, Security Systems Integration Services, Others), by Enterprise Size (Large Enterprises, SMEs), by Industry Vertical (BFSI, Government, Retail, Transportation, Residential, IT and Telecom, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 9, 2026|Base Year : 2025|Pages : 285
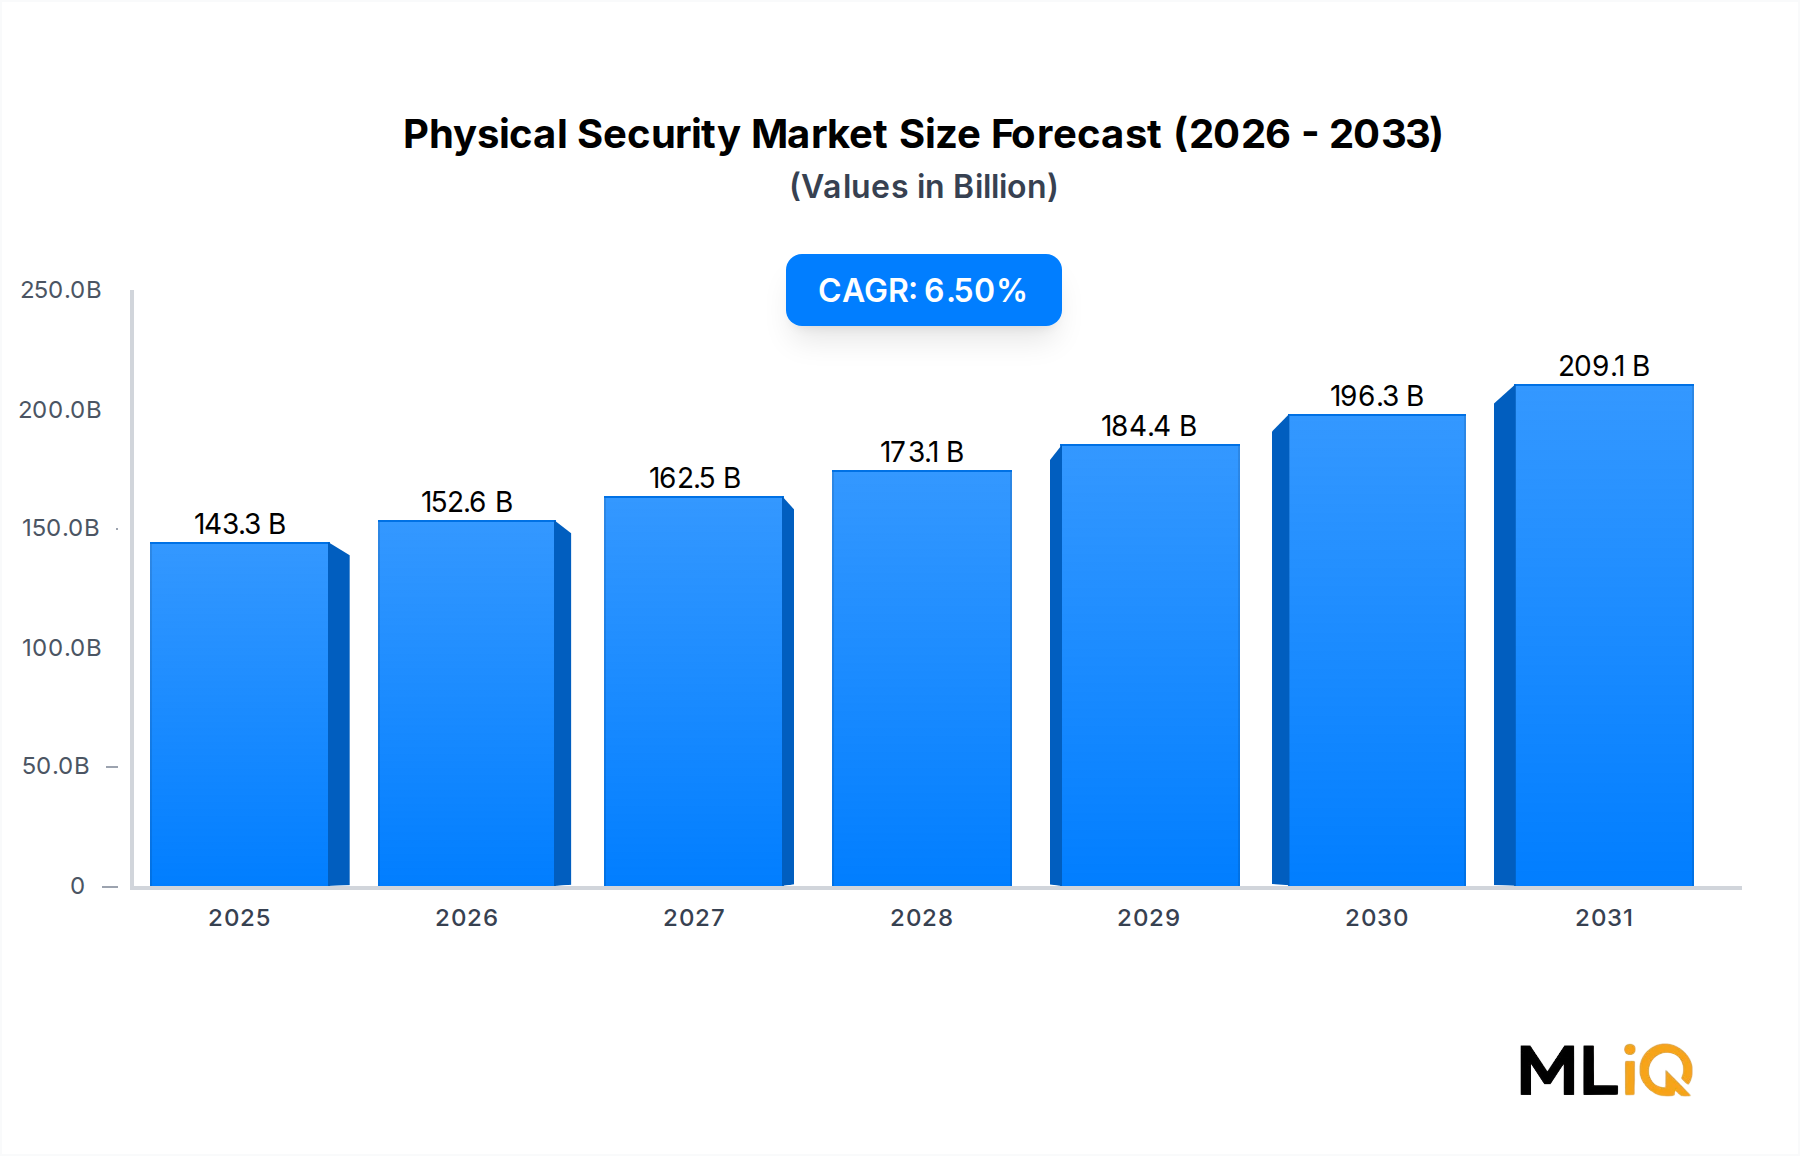
Physical Security Market revenue reached USD 143.31 billion in 2025. At the stated 6.5% CAGR, the market is projected to reach USD 252.6 billion by 2034. Demand is led by distributed enterprise operations, critical infrastructure investment, and risk managers who expect real-time visibility across doors, perimeters, and cameras. The Video Surveillance Market captures the biggest share of physical security budgets, although cloud-centric security services are growing from a smaller base. Commercial organizations view spending as insurance against fraud, workplace violence, and supply chain intrusion. Governments also contribute through building codes, anti-terrorism grants, and public transit safety mandates.
Physical Security Market Size (In Billion)
250.0B
200.0B
150.0B
100.0B
50.0B
0
143.3 B
2025
152.6 B
2026
162.5 B
2027
173.1 B
2028
184.4 B
2029
196.3 B
2030
209.1 B
2031
The dominant video surveillance segment is anchored by network camera upgrades and analytics. System installation continues to generate volume, while services such as remote monitoring and system integration expand recurring revenue. This pattern is visible in the Access Control as a Service Market, where mobile credentials reduce card issuance overhead and enable tenant self-service. The 2025-2034 growth outlook therefore depends less on unit camera growth and more on data handling capability, cyber-hardened edge devices, and cloud software subscriptions.
Segment Deep-Dive: Video Surveillance System Dominance in Physical Security Market
Video surveillance is estimated to generate around 40% of global Physical Security Market revenue. It is the dominant system type because video is the main source of forensic evidence, intrusion verification, and operational analytics. Cameras, recorders, video management software, and storage form a large hardware base that service providers can monetize with recurring subscriptions.
System and Services Split
Within the Component segment, System covers hardware and on-premise licenses; Services covers installation, connectivity, and monitoring. Video surveillance hardware is gradually commoditized, but Services vendors retain margin by designing networks, tuning AI models, and managing cloud storage. Enterprise buyers increasingly separate hardware procurement from integration, causing the Security Systems Integration Services Market to grow at a 7-8% annual rate. That is faster than hardware replacement cycles, which typically run 5 to 7 years.
Video Analytics and Software Value
The Video Surveillance Market is shifting from passive recording to proactive alerting. Edge-based analytics can identify person detection, crowd formation, and object removal at the camera. These features reduce bandwidth and storage needs, making AI-enabled cameras attractive for multi-site retailers and campuses. The same video data also informs the Physical Security Information Management Market, where operators aggregate alarms, sensors, and video into one queue.
Physical Access Integration
The Physical Access System Market remains an adjacent revenue pool. Door controllers, electronic locks, credential readers, and mobile-enabled readers are often purchased with video because access events require visual confirmation. In large enterprise rollouts, video surveillance serves as the evidence layer while PSIM serves as the decision layer. The long-term risk for the Physical Access System Market is that access control as a service removes upfront product sales and forces hardware vendors to compete on cloud subscription economics.
This segment is mature in North America and Europe but still expanding in Asia-Pacific. The fastest replacement cycles occur in BFSI, transportation, and government, where video evidence is tied to compliance reporting. Market share for the top five camera and VMS vendors remains above 50%, but lower-priced OEMs are gaining share in SME installations.
Primary Market Drivers & Growth Restraints in Physical Security Market
Drivers
Demand for safer public places drives camera installations in transit hubs, entertainment zones, and municipal buildings. Public infrastructure budgets in the United States and European Union increasingly fund video analytics and emergency communication systems. A further catalyst is cyber-physical convergence: as building networks extend to IP cameras, security teams purchase defense-in-depth products from vendors that provide secure device onboarding and encryption. The Video Surveillance Market also benefits from insurance discounts; commercial property insurers now require documented analytics-based monitoring, particularly in high-theft retail environments. The Perimeter Intrusion Detection Market is expanding around perimeters of data centers, substations, and airports because fence sensors offer low false alarm rates and can be layered with cameras.
Restraints
Legacy system integration is expensive, and skilled installation labor is scarce. Many site managers delay upgrades because migrating from analog closed-circuit television to IP-based analytics requires new cabling, network segmentation, and operator training. Privacy regulations restrict continuous recording and facial recognition, slowing project approval cycles. The Remote Monitoring Services Market faces the challenge of false alarm penalties in jurisdictions that require verified response; such rules increase operating costs for central stations. The Access Control as a Service Market reduces hardware capex but creates vendor lock-in and raises questions about long-term subscription cost in multi-year tenders.
Competitive advantage is moving toward open platforms, cloud subscription models, and AI-enabled monitoring. Key vendors include:
Genetec Inc.: Provides a unified Security Center platform for video, access control, and automatic license plate recognition; strong channel partner ecosystem.
PELCO Corporation: Focuses on video surveillance hardware and video management software used in transportation and critical infrastructure projects.
Johnson Controls: Offers integrated building management and security systems, including access control and video through its OpenBlue digital platform.
HONEYWELL INTERNATIONAL, INC.: Sells enterprise security systems, cybersecurity services, and building automation with a strong installed base position.
Cisco system Inc.: Provides Meraki cloud-managed cameras, network security, and IoT infrastructure, integrating physical security into IT networks.
Senstar Corporation: Specializes in perimeter intrusion detection, including buried cable sensors and radar systems.
BAE Systems plc: Supplies high-assurance command and control, cyber, and physical security solutions mainly for defense and government clients.
STANLEY CONVERGENT SECURITY SOLUTIONS, INC.: Provides commercial security monitoring, video remote monitoring, and electronic security services on a national account model.
Robert Bosch GmbH: Bosch Security and Safety Systems supplies video, intrusion detection, communication, and access control products worldwide.
ADT CORPORATION: Focuses on residential and small-business alarm monitoring, video doorbells, and professional installation.
Strategic Milestones & Recent Developments in Physical Security Market
January 2024: Genetec expanded cloud-hosted Security Center capabilities in Asia-Pacific, aligning SaaS delivery with data residency requirements.
April 2024: Bosch Security announced a new line of IP cameras with built-in AI acceleration, lowering network bandwidth for video analytics.
July 2024: Johnson Controls upgraded OpenBlue to unify video and access control workflows for multi-building campuses.
September 2024: Honeywell introduced a centralized security operations dashboard targeting airport and data center customers.
February 2025: ADT Corporation launched a commercial-grade mobile video monitoring package for multi-site retail chains.
May 2025: BAE Systems extended its security management platform to include AI-assisted perimeter analytics for critical national infrastructure.
Regional Market Analysis & Growth Corridors for Physical Security Market
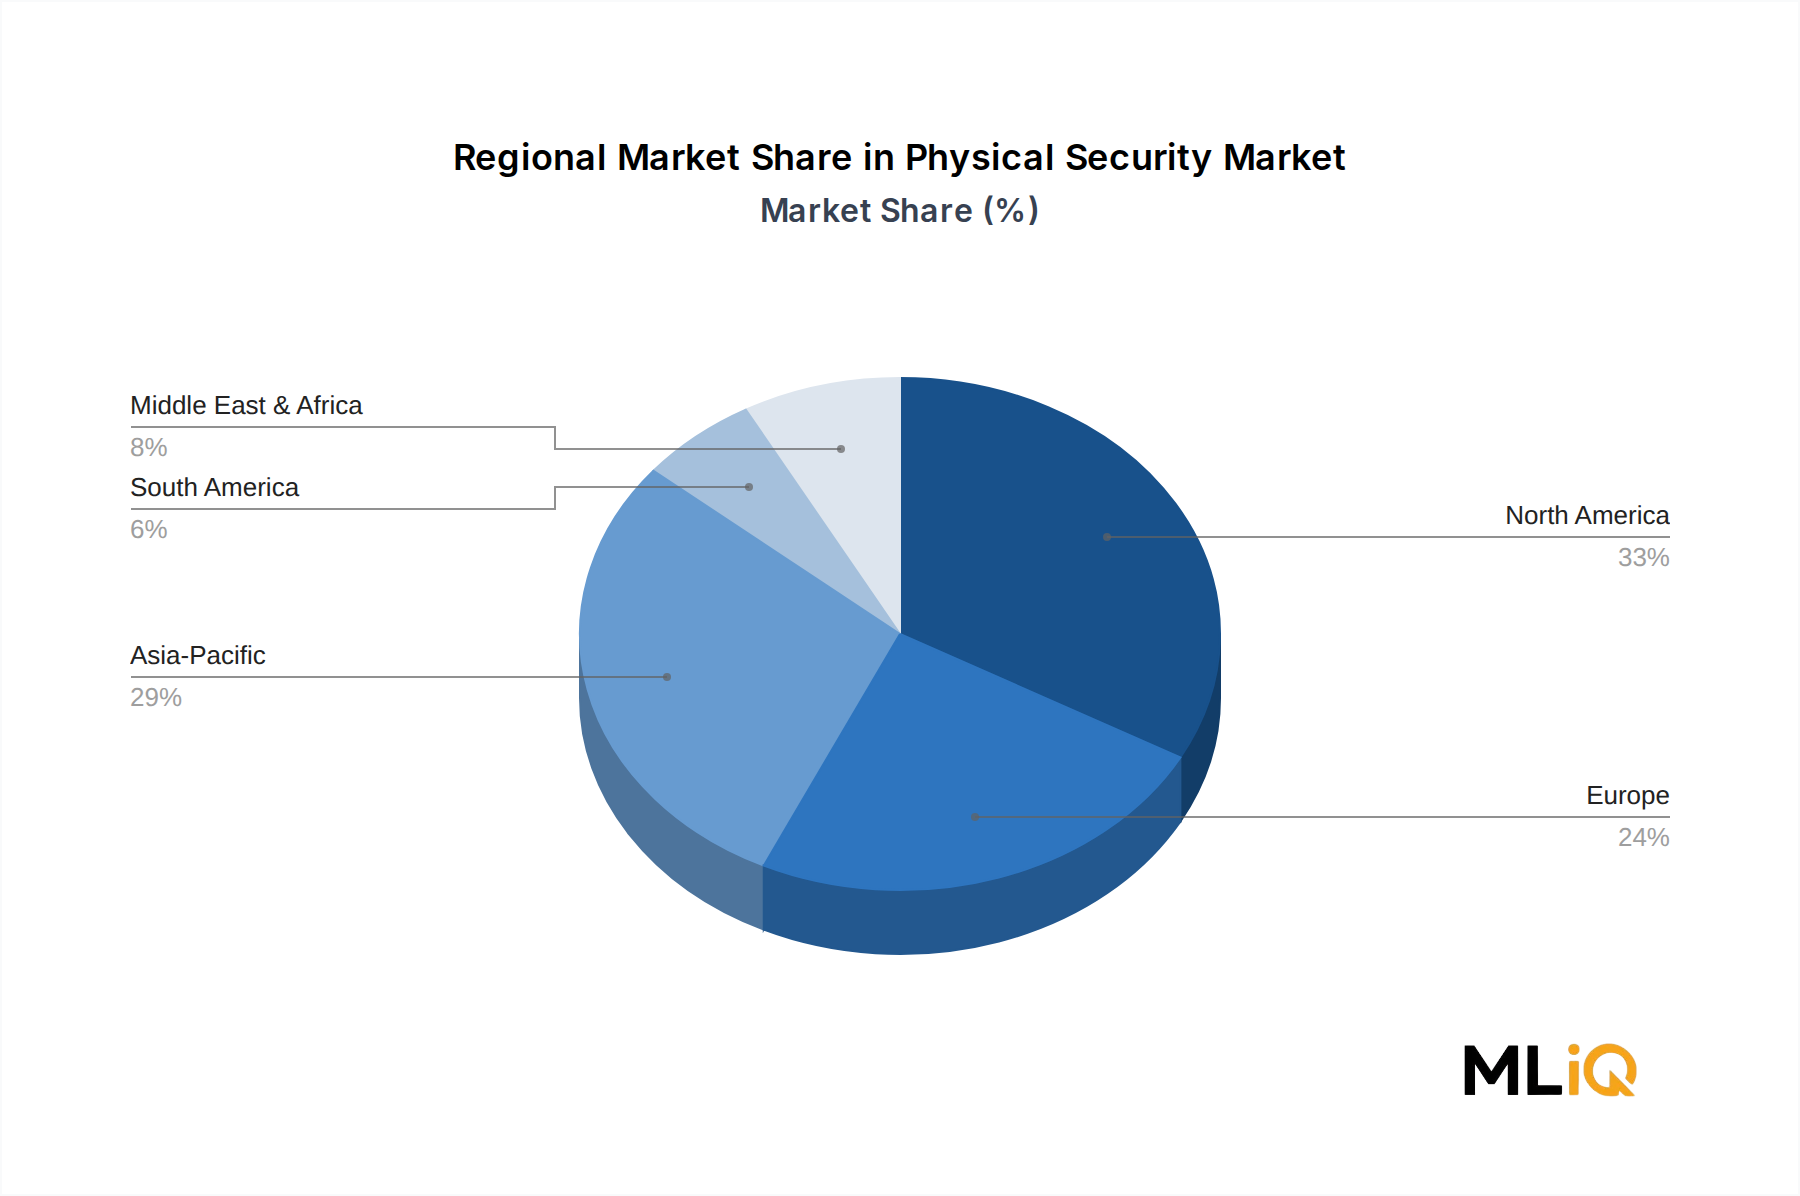
North America holds the largest regional share at roughly 33% of the 2025 global revenue. Mature cities are replacing legacy systems in data centers, hospitals, and transit networks; high labor costs favor analytics and centralized monitoring. North America’s CAGR is estimated at 5.9%, slower than the global average because penetration is high.
Europe accounts for about 24% of global revenue. GDPR requirements and country-specific data protection laws make on-premise and cloud video retention planning complex. The United Kingdom, Germany, and France invest heavily in public space video surveillance and critical infrastructure protection. European demand favors integration and privacy-conscious AI; growth is close to 5.2%.
Asia-Pacific is the fastest-growing region, with about 29% share and an estimated CAGR of 7.8%. China’s smart-city programs, India’s metro and industrial corridor construction, and ASEAN infrastructure contracts create concentrated demand. The Video Surveillance Market in this region benefits from domestic manufacturing scale and declining camera prices.
South America and the Middle East and Africa represent 6% and 8% of global revenue, respectively. LAMEA is price sensitive, with governments and large enterprises prioritizing banking and oil and gas site security. Perimeter Intrusion Detection Market demand in Africa is growing around oil and gas fencing and mining camps, while Brazil’s residential market accelerates through do-it-yourself cameras and subscription monitoring.
North America remains the most mature region; Asia-Pacific is the revenue growth corridor. The largest gains in Asia will be in cloud security services once regulatory rules for cross-border data become clearer.
Technology Innovation & R&D Trajectory in Physical Security Market
AI inference at the edge is the most consequential technology change. Cameras with dedicated neural processing units allow on-device person and vehicle detection, reducing false alarms and bandwidth cost. As more cameras become intelligent, the value of centralized video management shifts from recording to unified metadata search.
Cloud-native security platforms represent a second innovation. Large enterprises now trial video surveillance as a service and access control as a service, with hybrid deployment models that store video locally and send alerts to the cloud. R&D spending is directed at open APIs and cybersecurity certifications because customers insist on integration with identity and enterprise security stacks. The Physical Security Information Management Market, once a centralized console layer, is being reshaped by feature overlap with video management systems.
Subscription pricing and advanced data analytics are likely to dominate new contracts. Patent activity is increasing in facial recognition anonymisation, privacy-preserving detection, and cloud-edge workload orchestration. These developments reinforce the position of software-defined vendors and threaten hardware-only providers that lack a recurring revenue path.
Customer Segmentation & Buying Behavior in Physical Security Market
Enterprise size creates two distinct purchase behaviors. Large Enterprises tend to use formal RFPs, security systems integrators, and multi-year maintenance agreements. SMEs increasingly buy online, prefer self-install or partner-assisted cloud services, and choose flat monthly subscriptions.
Industry verticals influence feature priority. BFSI emphasizes compliance audit trails and centralized monitoring; Government institutions require secure supply chain and high assurance; Retail needs camera-based person counts and theft prevention; Transportation focuses on license plate recognition and baggage or crowd analytics. The Residential Security Market is heavily direct-to-consumer, with mobile apps as the primary interface and monthly monitoring as the core revenue stream.
Procurement has shifted finance criteria from capital expenditure to operating expenditure. Remote Monitoring Services Market contracts now bundle video analytics, cyber insurance support, and false alarm mitigation. Buyers whose key performance indicators include risk reduction and time-to-response will accept higher total cost of ownership if the service desk demonstrates measurable incident response improvement. Price elasticity is more pronounced in the hardware layer; integrators therefore add value through software configuration and workflow design.
Physical Security Market Segmentation
1. Component
1.1. System
1.2. Services
2. Systems Type
2.1. Physical Access System
2.2. Video Surveillance System
2.3. Perimeter Intrusion and Detection
2.4. Physical Security Information Management
2.5. Others
3. Service Type
3.1. Access Control as a Service
3.2. Video Surveillance as a Service
3.3. Remote Monitoring Services
3.4. Security Systems Integration Services
3.5. Others
4. Enterprise Size
4.1. Large Enterprises
4.2. SMEs
5. Industry Vertical
5.1. BFSI
5.2. Government
5.3. Retail
5.4. Transportation
5.5. Residential
5.6. IT and Telecom
5.7. Others
Physical Security Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Physical Security Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.5% from 2020-2034
Segmentation
By Component
System
Services
By Systems Type
Physical Access System
Video Surveillance System
Perimeter Intrusion and Detection
Physical Security Information Management
Others
By Service Type
Access Control as a Service
Video Surveillance as a Service
Remote Monitoring Services
Security Systems Integration Services
Others
By Enterprise Size
Large Enterprises
SMEs
By Industry Vertical
BFSI
Government
Retail
Transportation
Residential
IT and Telecom
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. System
5.1.2. Services
5.2. Market Analysis, Insights and Forecast - by Systems Type
5.2.1. Physical Access System
5.2.2. Video Surveillance System
5.2.3. Perimeter Intrusion and Detection
5.2.4. Physical Security Information Management
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Service Type
5.3.1. Access Control as a Service
5.3.2. Video Surveillance as a Service
5.3.3. Remote Monitoring Services
5.3.4. Security Systems Integration Services
5.3.5. Others
5.4. Market Analysis, Insights and Forecast - by Enterprise Size
5.4.1. Large Enterprises
5.4.2. SMEs
5.5. Market Analysis, Insights and Forecast - by Industry Vertical
5.5.1. BFSI
5.5.2. Government
5.5.3. Retail
5.5.4. Transportation
5.5.5. Residential
5.5.6. IT and Telecom
5.5.7. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. South America
5.6.3. Europe
5.6.4. Middle East & Africa
5.6.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. System
6.1.2. Services
6.2. Market Analysis, Insights and Forecast - by Systems Type
6.2.1. Physical Access System
6.2.2. Video Surveillance System
6.2.3. Perimeter Intrusion and Detection
6.2.4. Physical Security Information Management
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by Service Type
6.3.1. Access Control as a Service
6.3.2. Video Surveillance as a Service
6.3.3. Remote Monitoring Services
6.3.4. Security Systems Integration Services
6.3.5. Others
6.4. Market Analysis, Insights and Forecast - by Enterprise Size
6.4.1. Large Enterprises
6.4.2. SMEs
6.5. Market Analysis, Insights and Forecast - by Industry Vertical
6.5.1. BFSI
6.5.2. Government
6.5.3. Retail
6.5.4. Transportation
6.5.5. Residential
6.5.6. IT and Telecom
6.5.7. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. System
7.1.2. Services
7.2. Market Analysis, Insights and Forecast - by Systems Type
7.2.1. Physical Access System
7.2.2. Video Surveillance System
7.2.3. Perimeter Intrusion and Detection
7.2.4. Physical Security Information Management
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by Service Type
7.3.1. Access Control as a Service
7.3.2. Video Surveillance as a Service
7.3.3. Remote Monitoring Services
7.3.4. Security Systems Integration Services
7.3.5. Others
7.4. Market Analysis, Insights and Forecast - by Enterprise Size
7.4.1. Large Enterprises
7.4.2. SMEs
7.5. Market Analysis, Insights and Forecast - by Industry Vertical
7.5.1. BFSI
7.5.2. Government
7.5.3. Retail
7.5.4. Transportation
7.5.5. Residential
7.5.6. IT and Telecom
7.5.7. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. System
8.1.2. Services
8.2. Market Analysis, Insights and Forecast - by Systems Type
8.2.1. Physical Access System
8.2.2. Video Surveillance System
8.2.3. Perimeter Intrusion and Detection
8.2.4. Physical Security Information Management
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by Service Type
8.3.1. Access Control as a Service
8.3.2. Video Surveillance as a Service
8.3.3. Remote Monitoring Services
8.3.4. Security Systems Integration Services
8.3.5. Others
8.4. Market Analysis, Insights and Forecast - by Enterprise Size
8.4.1. Large Enterprises
8.4.2. SMEs
8.5. Market Analysis, Insights and Forecast - by Industry Vertical
8.5.1. BFSI
8.5.2. Government
8.5.3. Retail
8.5.4. Transportation
8.5.5. Residential
8.5.6. IT and Telecom
8.5.7. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. System
9.1.2. Services
9.2. Market Analysis, Insights and Forecast - by Systems Type
9.2.1. Physical Access System
9.2.2. Video Surveillance System
9.2.3. Perimeter Intrusion and Detection
9.2.4. Physical Security Information Management
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by Service Type
9.3.1. Access Control as a Service
9.3.2. Video Surveillance as a Service
9.3.3. Remote Monitoring Services
9.3.4. Security Systems Integration Services
9.3.5. Others
9.4. Market Analysis, Insights and Forecast - by Enterprise Size
9.4.1. Large Enterprises
9.4.2. SMEs
9.5. Market Analysis, Insights and Forecast - by Industry Vertical
9.5.1. BFSI
9.5.2. Government
9.5.3. Retail
9.5.4. Transportation
9.5.5. Residential
9.5.6. IT and Telecom
9.5.7. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. System
10.1.2. Services
10.2. Market Analysis, Insights and Forecast - by Systems Type
10.2.1. Physical Access System
10.2.2. Video Surveillance System
10.2.3. Perimeter Intrusion and Detection
10.2.4. Physical Security Information Management
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by Service Type
10.3.1. Access Control as a Service
10.3.2. Video Surveillance as a Service
10.3.3. Remote Monitoring Services
10.3.4. Security Systems Integration Services
10.3.5. Others
10.4. Market Analysis, Insights and Forecast - by Enterprise Size
10.4.1. Large Enterprises
10.4.2. SMEs
10.5. Market Analysis, Insights and Forecast - by Industry Vertical
10.5.1. BFSI
10.5.2. Government
10.5.3. Retail
10.5.4. Transportation
10.5.5. Residential
10.5.6. IT and Telecom
10.5.7. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Genetec Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. PELCO Corporation
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Johnson Controls
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. HONEYWELL INTERNATIONAL
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. INC.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Cisco system Inc.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Senstar Corporation
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. BAE Systems plc
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. STANLEY CONVERGENT SECURITY SOLUTIONS
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. INC.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Robert Bosch GmbH
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. ADT CORPORATION
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Physical Security Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Physical Security Market Revenue (billion), by Component 2026 & 2034
Figure 3: North America Physical Security Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Physical Security Market Revenue (billion), by Systems Type 2026 & 2034
Figure 5: North America Physical Security Market Revenue Share (%), by Systems Type 2026 & 2034
Figure 6: North America Physical Security Market Revenue (billion), by Service Type 2026 & 2034
Figure 7: North America Physical Security Market Revenue Share (%), by Service Type 2026 & 2034
Figure 8: North America Physical Security Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 9: North America Physical Security Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 10: North America Physical Security Market Revenue (billion), by Industry Vertical 2026 & 2034
Figure 11: North America Physical Security Market Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 12: North America Physical Security Market Revenue (billion), by Country 2026 & 2034
Figure 13: North America Physical Security Market Revenue Share (%), by Country 2026 & 2034
Figure 14: South America Physical Security Market Revenue (billion), by Component 2026 & 2034
Figure 15: South America Physical Security Market Revenue Share (%), by Component 2026 & 2034
Figure 16: South America Physical Security Market Revenue (billion), by Systems Type 2026 & 2034
Figure 17: South America Physical Security Market Revenue Share (%), by Systems Type 2026 & 2034
Figure 18: South America Physical Security Market Revenue (billion), by Service Type 2026 & 2034
Figure 19: South America Physical Security Market Revenue Share (%), by Service Type 2026 & 2034
Figure 20: South America Physical Security Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 21: South America Physical Security Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 22: South America Physical Security Market Revenue (billion), by Industry Vertical 2026 & 2034
Figure 23: South America Physical Security Market Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 24: South America Physical Security Market Revenue (billion), by Country 2026 & 2034
Figure 25: South America Physical Security Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Europe Physical Security Market Revenue (billion), by Component 2026 & 2034
Figure 27: Europe Physical Security Market Revenue Share (%), by Component 2026 & 2034
Figure 28: Europe Physical Security Market Revenue (billion), by Systems Type 2026 & 2034
Figure 29: Europe Physical Security Market Revenue Share (%), by Systems Type 2026 & 2034
Figure 30: Europe Physical Security Market Revenue (billion), by Service Type 2026 & 2034
Figure 31: Europe Physical Security Market Revenue Share (%), by Service Type 2026 & 2034
Figure 32: Europe Physical Security Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 33: Europe Physical Security Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 34: Europe Physical Security Market Revenue (billion), by Industry Vertical 2026 & 2034
Figure 35: Europe Physical Security Market Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 36: Europe Physical Security Market Revenue (billion), by Country 2026 & 2034
Figure 37: Europe Physical Security Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Middle East & Africa Physical Security Market Revenue (billion), by Component 2026 & 2034
Figure 39: Middle East & Africa Physical Security Market Revenue Share (%), by Component 2026 & 2034
Figure 40: Middle East & Africa Physical Security Market Revenue (billion), by Systems Type 2026 & 2034
Figure 41: Middle East & Africa Physical Security Market Revenue Share (%), by Systems Type 2026 & 2034
Figure 42: Middle East & Africa Physical Security Market Revenue (billion), by Service Type 2026 & 2034
Figure 43: Middle East & Africa Physical Security Market Revenue Share (%), by Service Type 2026 & 2034
Figure 44: Middle East & Africa Physical Security Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 45: Middle East & Africa Physical Security Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 46: Middle East & Africa Physical Security Market Revenue (billion), by Industry Vertical 2026 & 2034
Figure 47: Middle East & Africa Physical Security Market Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 48: Middle East & Africa Physical Security Market Revenue (billion), by Country 2026 & 2034
Figure 49: Middle East & Africa Physical Security Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Asia Pacific Physical Security Market Revenue (billion), by Component 2026 & 2034
Figure 51: Asia Pacific Physical Security Market Revenue Share (%), by Component 2026 & 2034
Figure 52: Asia Pacific Physical Security Market Revenue (billion), by Systems Type 2026 & 2034
Figure 53: Asia Pacific Physical Security Market Revenue Share (%), by Systems Type 2026 & 2034
Figure 54: Asia Pacific Physical Security Market Revenue (billion), by Service Type 2026 & 2034
Figure 55: Asia Pacific Physical Security Market Revenue Share (%), by Service Type 2026 & 2034
Figure 56: Asia Pacific Physical Security Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 57: Asia Pacific Physical Security Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 58: Asia Pacific Physical Security Market Revenue (billion), by Industry Vertical 2026 & 2034
Figure 59: Asia Pacific Physical Security Market Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 60: Asia Pacific Physical Security Market Revenue (billion), by Country 2026 & 2034
Figure 61: Asia Pacific Physical Security Market Revenue Share (%), by Country 2026 & 2034
Table 64: Rest of Asia Pacific Physical Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This methodology defines the estimates for the market scoped by Component, Systems Type, Service Type, Enterprise Size, Industry Vertical, and the five major regions described in the full report title covering 2026-2034. The entire study is updated to the date of purchase.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Security Operations Center Director
25%
Physical Security Manager
25%
IT Security and Network Architect
20%
Facility Management Leader
15%
Compliance and Risk Officer
15%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Video Surveillance Hardware OEMs
25%
Access Control and PSIM Software Vendors
20%
Security Systems Integration and Installation Firms
20%
Managed Security Service Providers
20%
Technology Distributors
15%
Primary Research
Primary research accounts for 70–80% of total research effort. We conducted interviews with physical security decision makers across four stakeholder groups: Security Operations Center Directors, Physical Security Technology Managers, Facilities and Risk Leaders, and IT Security Architects at enterprises using video surveillance, access control, and intruder detection systems.
A second primary research stream captured supply-side input from video surveillance camera OEMs, access control hardware and software vendors, Physical Security Information Management platform providers, security systems integrators, and managed security service providers. These interviews validated pricing trends, average contract values, and channel margins.
A 70/30 research split was maintained, with 70–80% primary and 20–30% secondary research.
Secondary Research & Industry Benchmarking
Secondary research contributes 20–30% and draws on standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook.
Both top-down and bottom-up methods are applied simultaneously and cross-validated with multi-level data triangulation. The top-down framework starts with reported segment revenue from technology vendors and distributor shipments. The bottom-up framework estimates demand using metrics such as the number of new commercial construction projects per region, installed base of access control readers, video camera penetration per 1,000 employees in BFSI, government, and retail, and average refresh cycles for intrusion detection systems.
The model covers the full title: Physical Security Market, by Component (System, Services), by Systems Type (Physical Access System, Video Surveillance System, Perimeter Intrusion and Detection, Physical Security Information Management, Others), by Service Type (Access Control as a Service, Video Surveillance as a Service, Remote Monitoring Services, Security Systems Integration Services, Others), by Enterprise Size (Large Enterprises, SMEs), by Industry Vertical (BFSI, Government, Retail, Transportation, Residential, IT and Telecom, Others), by Region, Forecast 2026-2034.
Vendor revenues are triangulated to avoid double counting between component and service revenue streams.
Data Accuracy & Quality Check
Final estimates are validated to a guaranteed data accuracy of 85–90%, determined by source consistency, interview sample coverage, and modeling variance checks. Any estimates outside that threshold are identified as assumptions.
All datasets are updated to the date of purchase, and report analytics are refreshed when new budget or regulatory proxies become available.
Frequently Asked Questions
1. What are the biggest barriers to entry in the Physical Security Market?
System integrator relationships and installed base are key moats. New entrants must match certifications such as UL 294 and partner with hardware manufacturers such as Bosch or Genetec, while access control and video software ecosystems make switching costly. The top five vendors control an estimated 35% of global revenue, which increases compliance and distribution hurdles.
2. How are AI analytics and cloud services disrupting traditional physical security vendors?
AI video analytics and video surveillance as a service are shifting value away from boxed hardware to software subscriptions. Surveillance cameras are becoming edge computing devices; by 2027 analysts expect over 55% of new video systems to include AI inference, which pressures margins and shortens refresh cycles.
3. Which product segments in physical security are growing fastest?
Access Control as a Service and video surveillance systems lead growth. The Access Control as a Service Market may expand at over 10% annually through 2034 because it converts capital-expense control panels and readers into recurring revenue. By comparison, legacy PSIM platforms grow near 4% as open VMS platforms absorb those functions.
4. How do privacy and government regulations affect the Physical Security Market?
GDPR limits retention of video and biometric data, while the U.S. SAFETY Act encourages anti-terrorism security purchases. Compliance demands such as EU EN 50132 force vendors to redesign storage and audit trails, adding 8-10% to project costs for large enterprise deployments.
5. Which end-user industries are creating the most demand for modern physical security systems?
BFSI, government, and transportation are the largest buyers, while residential demand is climbing through video doorbells. Banks are upgrading branch cameras and access control for remote monitoring; governments in North America and Asia-Pacific are spending on perimeter intrusion detection for critical infrastructure. Transportation sector security spending is growing at a 7% clip in Europe.
6. What recent product launches or M&A activity should physical security buyers track?
Honeywell, Johnson Controls, and Bosch continue to bundle analytics into access control suites, with recurring revenue strategies dominating 2024 announcements. Genetec expanded cloud Security Center availability; BAE Systems focused on high-security military sites. Expect more consolidation in access control as a service and remote monitoring subsegments.