Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Internet of Vehicle Market Hits USD 933.6B by 2033
Internet of Vehicle Market
Internet of Vehicle Market Hits USD 933.6B by 2033
Internet of Vehicle Market by Component (Hardware, Software, Service), by Technology (Bluetooth, Cellular, Wi-Fi, NFC, Others), by Communication Type (Vehicle-to-Vehicle, Vehicle-to-Infrastructure, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 239
Key Insights & Executive Summary: Internet of Vehicle Market
Internet of Vehicle Market Size (In Billion)
750.0B
600.0B
450.0B
300.0B
150.0B
0
248.4 B
2025
293.1 B
2026
345.8 B
2027
408.1 B
2028
481.5 B
2029
568.2 B
2030
670.5 B
2031
Market at a Glance
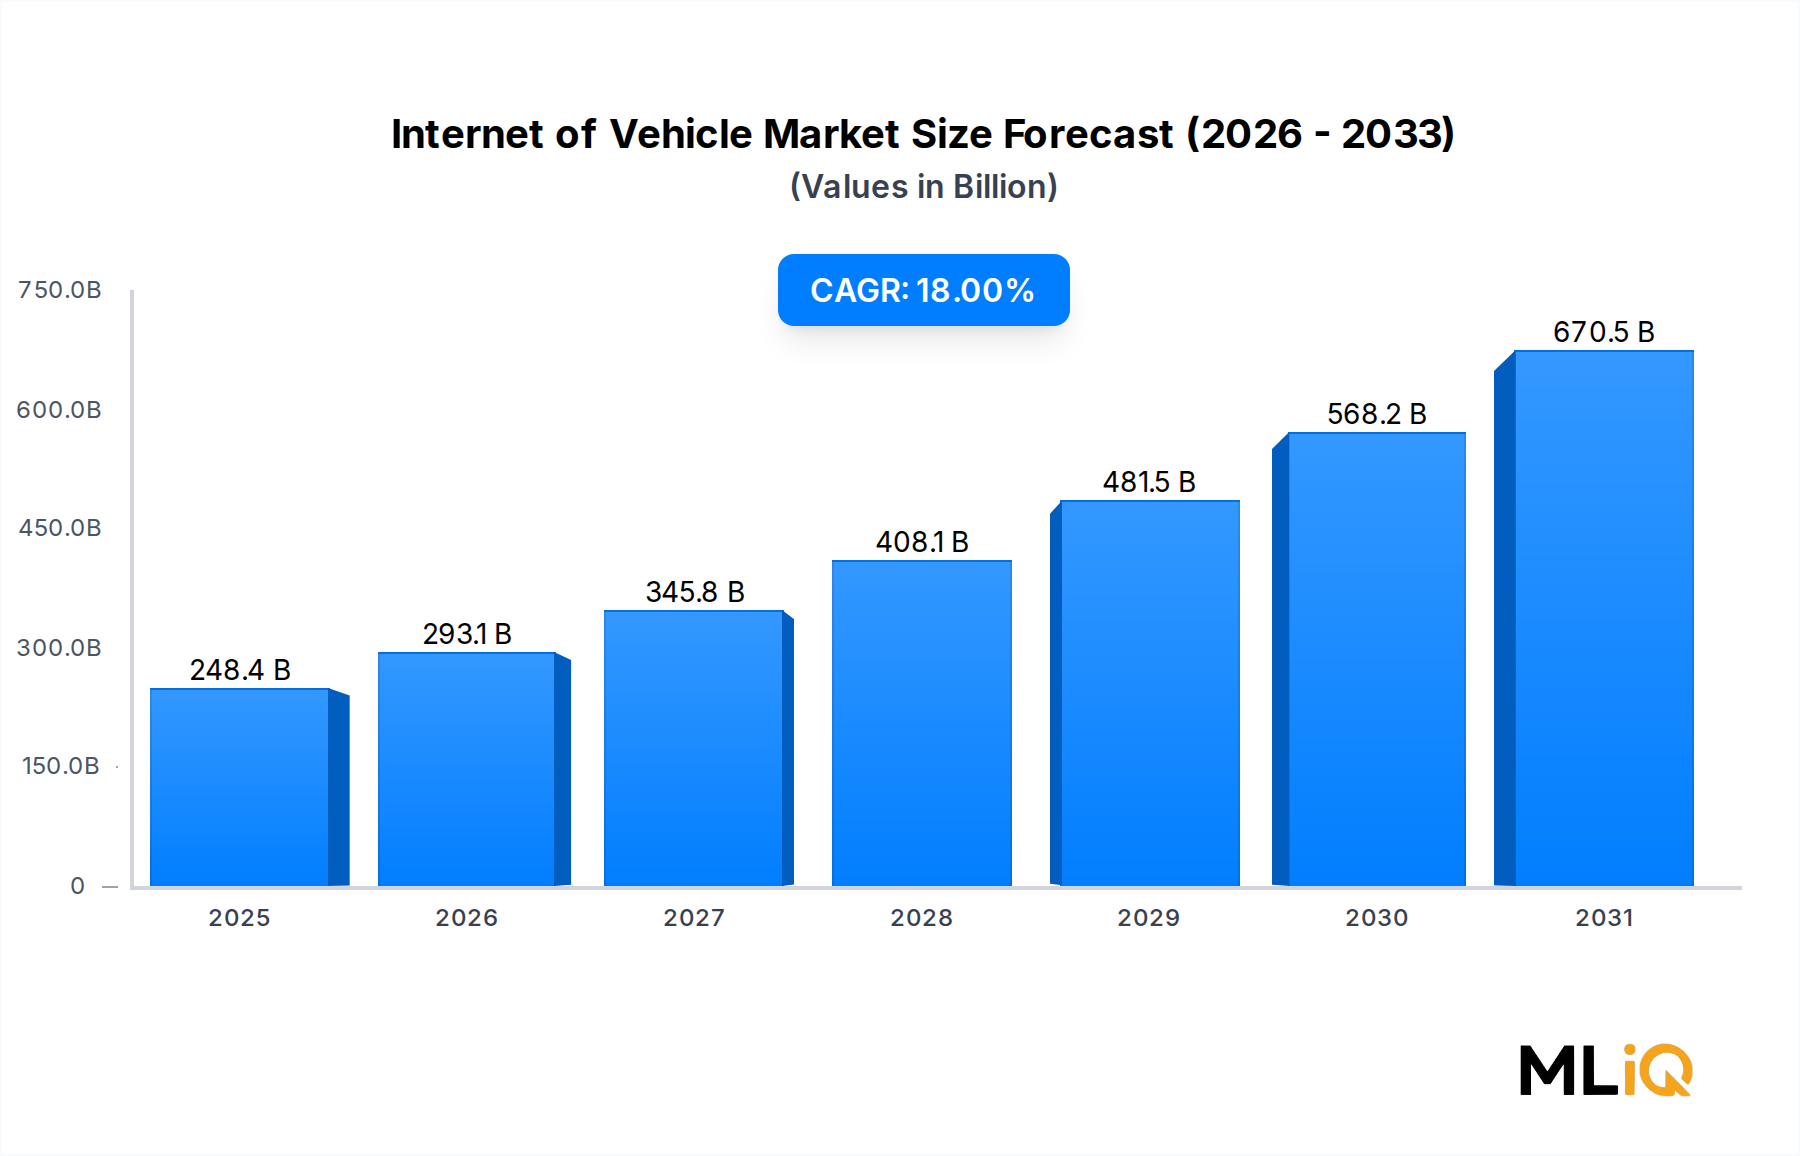
The Internet of Vehicle Market closed 2025 at USD 248,366.62 million and is forecast to reach USD 933,576 million by 2033, a 3.8x expansion at an 18.0% CAGR. Growth is no longer confined to premium passenger cars; commercial fleets, municipal buses and two-wheelers now drive unit volume.
Three structural findings define the period:
Hardware carries 52% of revenue, led by telematics control units, V2X radios and zonal domain controllers.
Software and services grow at 21.8% and 20.4% respectively, outpacing hardware at 16.2% as OEMs monetize over-the-air updates.
Cellular connectivity (4G LTE and 5G C-V2X) holds an estimated 58% of connectivity revenue.
Three forces set the 2025–2033 trajectory.
Regulatory deadlines. UNECE R155 and R156 cybersecurity and software-update rules apply to every new vehicle type approved in the EU, Japan and South Korea, forcing secure gateway hardware into mid-market trims.
Silicon cost deflation. Automotive-grade 5G modems and V2X chipsets have fallen roughly 30–35% in unit price since 2021, pulling connectivity below the premium tier.
Data monetization. Insurers, logistics operators and city authorities buy vehicle data directly, shifting the Automotive IoT Hardware Market from a one-time component sale into recurring revenue.
Two constraints temper the curve. Spectrum coordination for the Vehicle-to-Everything Communication Market remains incomplete outside China, the United States and parts of Europe, and automotive-grade chip lead times still average 26–38 weeks. Even so, the Smart Transportation Infrastructure Market's roadside-unit buildout and rising In-Car Connectivity Solutions Market attach rates support the 18.0% forecast, with the Connected Car Software Market acting as the margin engine for the next cycle.
Segment Deep-Dive: Hardware Component Dominance in Internet of Vehicle Market
Segment Analysis Matrix
Segment
CAGR (%)
Market Share (%)
Key Demand Driver
Hardware
16.2
52
Mandatory V2X and TCU fitment; rising silicon content per vehicle
Software
21.8
29
OTA update stacks, hypervisors and middleware licensing
Service
20.4
19
Connectivity data plans, fleet analytics, post-sale uptime contracts
Hardware is the largest revenue pool at 52% of the Internet of Vehicle Market, equivalent to roughly USD 129,150 million in 2025. It grows more slowly than software because unit prices fall as volumes scale, but it remains the segment every other layer depends on.
Sub-Segment Dynamics
Telematics control units (TCUs) are the highest-volume hardware item. Global fitment is approaching 90% on new light vehicles sold in the EU and North America, versus roughly 60% in South America.
V2X radios remain a smaller but policy-driven line item. Dual-mode (C-V2X plus IEEE 802.11p) modules add USD 60–120 to bill-of-materials cost and are being designed into platforms for 2027–2030 model years.
Zonal and domain controllers absorb multiple electronic control units into one enclosure, raising hardware value per car while compressing the supplier count.
Within the Automotive Semiconductor Market, automotive-qualified 5G modems, GNSS receivers and secure elements represent the fastest-moving input category. Suppliers that hold AEC-Q100 qualification and ISO 26262 documentation capture disproportionate share.
Margin Pressure
Hardware gross margins sit in the 28–34% band, and the Vehicle Telematics Market is already showing price erosion of 4–6% per year on commodity aftermarket devices. Three pressures dominate:
Tier-1 integrators face OEM annual price-down demands of 3–5% per program year.
Memory and modem content inflation offsets part of that deflation, keeping average selling prices flat rather than rising.
Software-heavy competitors bundle free connectivity to win the Fleet Management Systems Market contract, using service margin to subsidize hardware.
The practical consequence: hardware scale wins volume, but the Connected Car Software Market and service layer determine enterprise value. Vendors that own both capture 10–15 percentage points more gross margin than component-only suppliers.
Primary Market Drivers & Growth Restraints in Internet of Vehicle Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
UNECE R155/R156 cybersecurity and OTA compliance for all new vehicle types
High
Short term
Driver
5G and 5G-Advanced coverage expansion enabling low-latency C-V2X use cases
High
Medium term
Driver
Fleet telematics ROI: 10–20% fuel savings and 10–30% insurance discounts
High
Short term
Driver
Software-defined vehicle architecture raising semiconductor content per car
Medium
Long term
Restraint
Fragmented V2X spectrum allocation outside China, the United States and parts of the EU
High
Medium term
Restraint
26–38 week automotive chip lead times and 18–24 month qualification cycles
Medium
Short term
Restraint
Data privacy rules limiting cross-border vehicle data transfer
Medium
Long term
Restraint
Capital cost of retrofitting roadside units on existing corridors
Medium
Long term
The strongest single catalyst is compliance, not consumer demand. UNECE R155 and R156 turned the Automotive Cybersecurity Market from a discretionary upgrade into a type-approval condition, and OEMs now budget intrusion detection and secure provisioning in every platform.
Demand-side catalysts are equally quantifiable:
Commercial fleet operators report 10–20% fuel and route savings after deploying telematics, with payback inside 18 months.
Usage-based insurance programs reduce premiums by 10–30%, giving insurers a direct reason to buy OEM data feeds.
Municipal procurement for the Vehicle-to-Everything Communication Market adds signal-phase-and-timing and intersection-awareness use cases that reduce collision exposure at equipped junctions.
On the restraint side, spectrum fragmentation is the most expensive friction. Europe's coexistence debate between ITS-G5 and C-V2X delayed deployment by three to four years relative to China, where 5.9 GHz-class C-V2X pilots now cover dozens of cities. Chip lead times have normalized from 2021 peaks but still run 26–38 weeks, which forces OEMs to commit to connectivity silicon two model years ahead of production.
Competitive Ecosystem & Key Vendor Profiles: Internet of Vehicle Market
Vendor Benchmarking Matrix
Company Name
Core Strength
Target Audience
Market Position
NXP Semiconductors N.V.
Automotive MCUs, secure elements, V2X radios
OEMs, Tier-1 integrators
Leader
Intel Corporation
Compute platforms, Mobileye perception stack
OEMs, mobility platforms
Leader
Cisco Systems Inc.
Networking, edge routing, industrial IoT security
Cities, fleet operators
Challenger
Texas Instruments Inc.
Automotive analog, radar and power management
Tier-1 suppliers
Leader
Google Inc.
In-vehicle OS and maps, cloud vehicle data services
OEMs, consumers
Leader
Apple Inc.
In-car interface layer and digital key
OEMs, consumers
Challenger
IBM Corporation
Hybrid cloud, data governance, fleet analytics
Fleets, municipalities
Challenger
SAP
Enterprise data exchange, supply chain and fleet ERP
OEMs, logistics operators
Challenger
Ford Motor Company
Embedded connectivity and fleet telematics at scale
Fleet buyers, retail
Leader
Audi AG
Premium software-defined vehicle programs
Premium consumers
Niche
Vendor positioning below reflects disclosed 2023–2025 activity and product reach.
NXP Semiconductors N.V.: Holds a leading automotive portfolio spanning MCUs, secure elements and C-V2X radios, and agreed to acquire TTTech Auto for USD 625 million in January 2025 to add safety-critical middleware.
Intel Corporation: Combines foundry ambitions with the Mobileye perception stack and agreed in 2024 to acquire Silicon Mobility for electric-vehicle energy-management silicon.
Cisco Systems Inc.: Supplies edge routing, industrial networking and security infrastructure to municipal smart-corridor and depot connectivity projects rather than vehicle-side silicon.
Texas Instruments Inc.: Retains a strong position in automotive analog, radar and power management, backed by an USD 11 billion 300mm fab investment in Lehi, Utah announced in 2023.
Google Inc.: Embeds its automotive OS and maps into OEM platforms and monetizes vehicle data through cloud services, following a six-year Ford agreement signed in 2021.
Apple Inc.: Competes at the interface layer through smartphone projection and ultra-wideband digital key, without controlling the underlying vehicle network.
IBM Corporation: Targets the data governance layer, offering hybrid cloud and analytics for fleets and transport authorities that must manage vehicle data residency.
SAP: Extends enterprise resource planning into automotive supply chain and fleet data exchange, competing for the back-office integration budget.
Ford Motor Company: Operates one of the largest embedded-connectivity fleets and monetizes telematics directly through its commercial vehicle services business.
Audi AG: Uses premium software-defined vehicle programs as a proving ground for zonal architecture and over-the-air feature sales within the Volkswagen Group.
Strategic Milestones & Recent Developments in Internet of Vehicle Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Jan 2025
NXP Semiconductors
M&A
USD 625 million acquisition of TTTech Auto adds safety-critical middleware
Agreement to acquire Silicon Mobility for EV energy-management SoCs
Aug 2024
NHTSA
Regulation
Proposed C-V2X deployment rule for new light vehicles
Feb 2023
Texas Instruments
Investment
USD 11 billion 300mm fab in Lehi, Utah for long-run automotive capacity
Feb 2021
Ford / Google
Partnership
Six-year agreement embedding Google built-in and cloud data services
Mar 2023
Cisco
Partnership
Multi-year technology partnership with Mercedes-AMG PETRONAS F1
2024
SAP
Launch
Automotive cloud expansion for fleet and supply chain data exchange
Chronological detail on the highest-impact moves:
2021 — Ford and Google. The six-year agreement put Google's automotive OS and maps into Ford vehicles and moved vehicle data services into Google Cloud, establishing a template for OEM–hyperscaler deals.
February 2023 — Texas Instruments. The Lehi fab commitment targets 300mm analog and embedded capacity, a direct response to the 2020–2022 automotive chip shortage.
February 2024 — Intel and Silicon Mobility. The acquisition added electric-vehicle energy-management silicon, tightening Intel's grip on powertrain software-defined control.
June 2024 — Qualcomm and Autotalks. Closing the deal consolidated dual-mode V2X silicon supply and reduced the field of independent V2X chip vendors.
August 2024 — NHTSA. The proposed rule to accelerate C-V2X deployment signals a shift from voluntary to mandated vehicle connectivity in the United States.
January 2025 — NXP and TTTech Auto. The USD 625 million deal pushes a semiconductor vendor into safety-critical middleware, blurring the line between chip and software supplier.
The pattern across all six events is consolidation toward integrated chip-plus-software stacks, which compresses opportunities for single-layer vendors.
Regional Market Analysis & Growth Corridors for Internet of Vehicle Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation (USD million)
Primary Catalyst
Regulatory Stringency
Asia-Pacific
21.5
99,347.0
China C-V2X pilot cities; NEV penetration above 40%
High
North America
17.2
59,608.0
NHTSA V2X rulemaking; fleet telematics adoption
Medium-High
Europe
16.8
54,641.0
UNECE R155/R156; EU ITS Directive
High
South America
14.6
14,901.62
Brazil commercial fleet tracking and cargo-theft prevention
Medium
Middle East & Africa
15.4
19,869.0
GCC smart-city programs and fleet modernization
Low-Medium
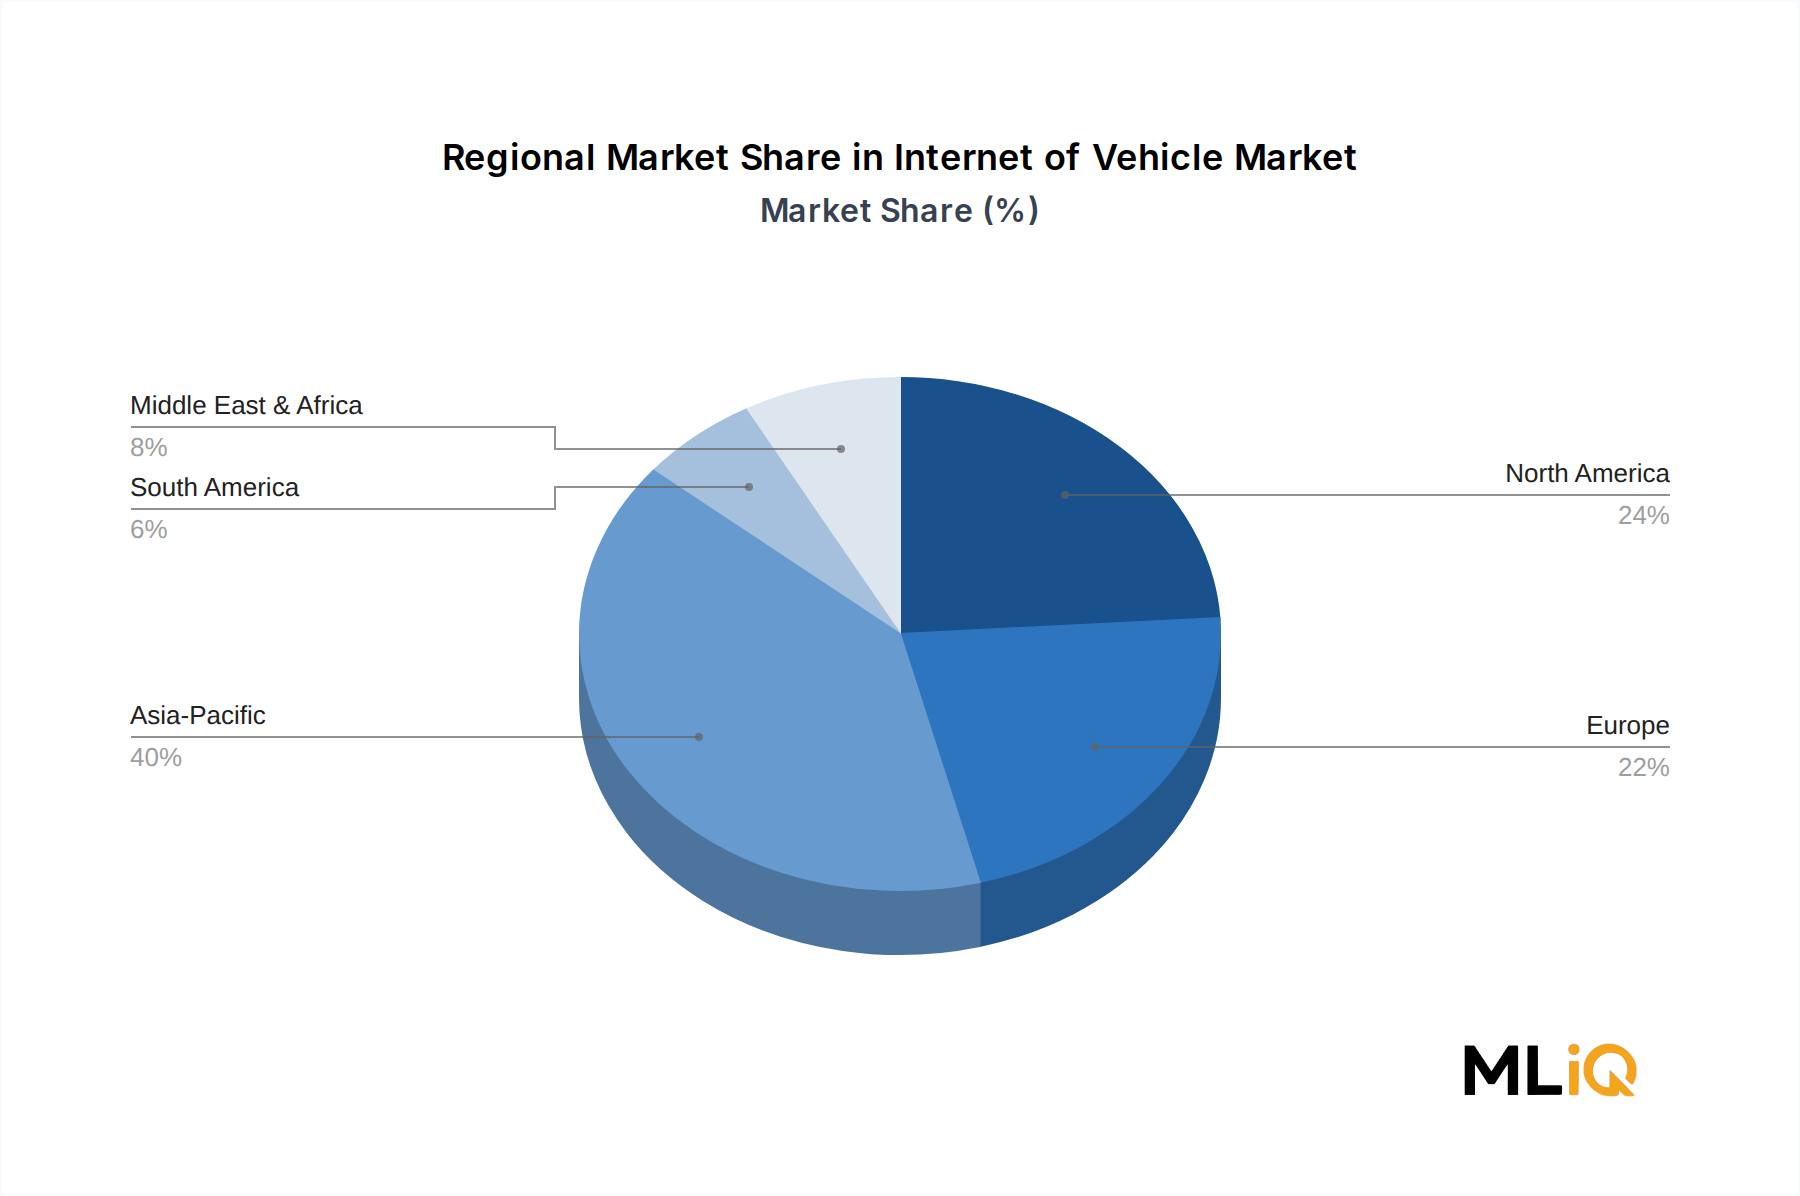
Asia-Pacific is the fastest-growing and largest region, at an estimated 21.5% CAGR and 40.0% of 2025 global revenue (USD 99,347 million). The growth engine is China, where new energy vehicles account for more than 40% of domestic passenger sales and C-V2X pilot cities have deployed equipped intersections at scale.
North America grows at 17.2% on a USD 59,608 million base. Maturity shows in high telematics attach rates, but the NHTSA proposed rule on C-V2X is the swing factor for 2027–2030 volume.
Europe grows at 16.8% from USD 54,641 million. Regulation, not consumer pull, drives the curve: UNECE R155/R156 compliance is mandatory for all new vehicle types, and the ITS Directive pushes member states toward cooperative corridor deployment.
South America grows at 14.6% from USD 14,901.62 million, with Brazil's cargo-theft problem making fleet tracking a hard financial necessity rather than a feature.
Middle East & Africa grows at 15.4% from USD 19,869 million, led by GCC smart-mobility programs where public procurement, not private demand, funds roadside and fleet deployments.
The strategic read: volume upside sits in Asia-Pacific, while Europe and North America deliver predictable, regulation-anchored revenue with higher software attach rates.
Supply Chain & Raw Material Dynamics: Internet of Vehicle Market
Upstream dependencies concentrate in four inputs: automotive-grade semiconductor wafers, radio-frequency front-end components, printed circuit board laminates and rare-earth magnets used in actuators and sensors.
Silicon and packaging. Automotive MCUs and SoCs are produced mainly at 28–65 nm nodes, with foundry and outsourced assembly capacity concentrated in Taiwan, South Korea and Malaysia. Qualification cycles of 18–24 months make supplier switching impractical inside a model cycle.
Power semiconductors. Silicon carbide and gallium nitride devices for onboard chargers and inverters remain the highest-volatility line item; SiC substrate pricing has declined roughly 20–25% since 2022 as capacity came online.
Passive and interconnect materials. Gold bonding wire and copper laminate prices rose sharply through 2022–2024, adding low-single-digit percentage cost to module bills of materials.
Battery and backup cells. Small lithium cells for emergency call and telematics backup add a compliance-dependent cost line, particularly in Europe.
Historical disruptions are instructive. The March 2021 fire at Renesas' Naka fab and the February 2021 Texas winter storm that idled NXP and Infineon facilities in Austin compounded into a shortage that removed an estimated USD 200 billion-plus of vehicle production revenue across 2021–2022. Current conditions differ: inventory correction through 2024–2025 has pushed lead times down from 52 weeks toward 26–38 weeks, but the structural exposure remains. A single leading-edge automotive node outage still propagates to global vehicle assembly within eight weeks.
Investment, M&A & Funding Activity in Internet of Vehicle Market
Capital is shifting from hardware bets toward software, middleware and data platforms.
Semiconductor consolidation. Qualcomm's Autotalks acquisition (closed 2024, estimated USD 350 million) and NXP's USD 625 million agreement for TTTech Auto (January 2025) set the price benchmarks for V2X and safety-critical middleware assets.
Automotive software and simulation. Applied Intuition's 2024 round valued the company at roughly USD 6 billion, reflecting demand for toolchains that validate connected and autonomous vehicle software.
Cheaper design tooling. Renesas' agreement to acquire Altium for approximately USD 5.9 billion in February 2024 signaled that semiconductor vendors want the electronics design software layer attached to their silicon.
Robotaxi and mobility platforms. Hyundai's USD 475 million investment in Motional in 2024 kept autonomous mobility capital flowing despite repeated timeline slippage.
Growth-stage connectivity software. Sonatus' USD 75 million Series B and comparable rounds show continued appetite for vehicle data infrastructure and OTA platforms.
Sub-segments attracting the most capital are over-the-air update infrastructure, V2X modem software, automotive cybersecurity and fleet data analytics. The recurring theme among acquirers is vertical integration: chip vendors buying software, OEMs buying data platforms, and hyperscalers buying vehicle-data contracts. Expect continued premium valuations for any asset that combines safety certification with a cloud data pipeline.
Investment Outlook & Consolidation Signals: Internet of Vehicle Market
The 2025–2033 window favors vendors that convert connectivity into recurring revenue rather than one-time fitment. Companies with certified security stacks, cloud data pipelines and fleet contracts should compound faster than component-only peers. The 18.0% CAGR to USD 933,576 million by 2033 is achievable without a step-change in consumer behavior, provided spectrum rules stabilize and semiconductor supply stays within current lead-time bands.
Internet of Vehicle Market Segmentation
1. Component
1.1. Hardware
1.2. Software
1.3. Service
2. Technology
2.1. Bluetooth
2.2. Cellular
2.3. Wi-Fi
2.4. NFC
2.5. Others
3. Communication Type
3.1. Vehicle-to-Vehicle
3.2. Vehicle-to-Infrastructure
3.3. Others
Internet of Vehicle Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Internet of Vehicle Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 18.00% from 2020-2034
Segmentation
By Component
Hardware
Software
Service
By Technology
Bluetooth
Cellular
Wi-Fi
NFC
Others
By Communication Type
Vehicle-to-Vehicle
Vehicle-to-Infrastructure
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Hardware
5.1.2. Software
5.1.3. Service
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. Bluetooth
5.2.2. Cellular
5.2.3. Wi-Fi
5.2.4. NFC
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Communication Type
5.3.1. Vehicle-to-Vehicle
5.3.2. Vehicle-to-Infrastructure
5.3.3. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Hardware
6.1.2. Software
6.1.3. Service
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. Bluetooth
6.2.2. Cellular
6.2.3. Wi-Fi
6.2.4. NFC
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by Communication Type
6.3.1. Vehicle-to-Vehicle
6.3.2. Vehicle-to-Infrastructure
6.3.3. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Hardware
7.1.2. Software
7.1.3. Service
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. Bluetooth
7.2.2. Cellular
7.2.3. Wi-Fi
7.2.4. NFC
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by Communication Type
7.3.1. Vehicle-to-Vehicle
7.3.2. Vehicle-to-Infrastructure
7.3.3. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Hardware
8.1.2. Software
8.1.3. Service
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. Bluetooth
8.2.2. Cellular
8.2.3. Wi-Fi
8.2.4. NFC
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by Communication Type
8.3.1. Vehicle-to-Vehicle
8.3.2. Vehicle-to-Infrastructure
8.3.3. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Hardware
9.1.2. Software
9.1.3. Service
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. Bluetooth
9.2.2. Cellular
9.2.3. Wi-Fi
9.2.4. NFC
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by Communication Type
9.3.1. Vehicle-to-Vehicle
9.3.2. Vehicle-to-Infrastructure
9.3.3. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Hardware
10.1.2. Software
10.1.3. Service
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. Bluetooth
10.2.2. Cellular
10.2.3. Wi-Fi
10.2.4. NFC
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by Communication Type
10.3.1. Vehicle-to-Vehicle
10.3.2. Vehicle-to-Infrastructure
10.3.3. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. INTEL CORPORATION
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. NXP SEMICONDUCTORS N.V.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. AUDI AG
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. CISCO SYSTEMS INC.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. APPLE INC.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. GOOGLE INC.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. IBM CORPORATION
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. TEXAS INSTRUMENTS INC.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. SAP
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. FORD MOTOR COMPANY
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Internet of Vehicle Market Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Internet of Vehicle Market Revenue (million), by Component 2026 & 2034
Figure 3: North America Internet of Vehicle Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Internet of Vehicle Market Revenue (million), by Technology 2026 & 2034
Figure 5: North America Internet of Vehicle Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Internet of Vehicle Market Revenue (million), by Communication Type 2026 & 2034
Figure 7: North America Internet of Vehicle Market Revenue Share (%), by Communication Type 2026 & 2034
Figure 8: North America Internet of Vehicle Market Revenue (million), by Country 2026 & 2034
Figure 9: North America Internet of Vehicle Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Internet of Vehicle Market Revenue (million), by Component 2026 & 2034
Figure 11: South America Internet of Vehicle Market Revenue Share (%), by Component 2026 & 2034
Figure 12: South America Internet of Vehicle Market Revenue (million), by Technology 2026 & 2034
Figure 13: South America Internet of Vehicle Market Revenue Share (%), by Technology 2026 & 2034
Figure 14: South America Internet of Vehicle Market Revenue (million), by Communication Type 2026 & 2034
Figure 15: South America Internet of Vehicle Market Revenue Share (%), by Communication Type 2026 & 2034
Figure 16: South America Internet of Vehicle Market Revenue (million), by Country 2026 & 2034
Figure 17: South America Internet of Vehicle Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Internet of Vehicle Market Revenue (million), by Component 2026 & 2034
Figure 19: Europe Internet of Vehicle Market Revenue Share (%), by Component 2026 & 2034
Figure 20: Europe Internet of Vehicle Market Revenue (million), by Technology 2026 & 2034
Figure 21: Europe Internet of Vehicle Market Revenue Share (%), by Technology 2026 & 2034
Figure 22: Europe Internet of Vehicle Market Revenue (million), by Communication Type 2026 & 2034
Figure 23: Europe Internet of Vehicle Market Revenue Share (%), by Communication Type 2026 & 2034
Figure 24: Europe Internet of Vehicle Market Revenue (million), by Country 2026 & 2034
Figure 25: Europe Internet of Vehicle Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Internet of Vehicle Market Revenue (million), by Component 2026 & 2034
Figure 27: Middle East & Africa Internet of Vehicle Market Revenue Share (%), by Component 2026 & 2034
Figure 28: Middle East & Africa Internet of Vehicle Market Revenue (million), by Technology 2026 & 2034
Figure 29: Middle East & Africa Internet of Vehicle Market Revenue Share (%), by Technology 2026 & 2034
Figure 30: Middle East & Africa Internet of Vehicle Market Revenue (million), by Communication Type 2026 & 2034
Figure 31: Middle East & Africa Internet of Vehicle Market Revenue Share (%), by Communication Type 2026 & 2034
Figure 32: Middle East & Africa Internet of Vehicle Market Revenue (million), by Country 2026 & 2034
Figure 33: Middle East & Africa Internet of Vehicle Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Internet of Vehicle Market Revenue (million), by Component 2026 & 2034
Figure 35: Asia Pacific Internet of Vehicle Market Revenue Share (%), by Component 2026 & 2034
Figure 36: Asia Pacific Internet of Vehicle Market Revenue (million), by Technology 2026 & 2034
Figure 37: Asia Pacific Internet of Vehicle Market Revenue Share (%), by Technology 2026 & 2034
Figure 38: Asia Pacific Internet of Vehicle Market Revenue (million), by Communication Type 2026 & 2034
Figure 39: Asia Pacific Internet of Vehicle Market Revenue Share (%), by Communication Type 2026 & 2034
Figure 40: Asia Pacific Internet of Vehicle Market Revenue (million), by Country 2026 & 2034
Figure 41: Asia Pacific Internet of Vehicle Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Internet of Vehicle Market Revenue million Forecast, by Component 2020 & 2034
Table 2: Internet of Vehicle Market Revenue million Forecast, by Technology 2020 & 2034
Table 3: Internet of Vehicle Market Revenue million Forecast, by Communication Type 2020 & 2034
Table 4: Internet of Vehicle Market Revenue million Forecast, by Region 2020 & 2034
Table 5: North America Internet of Vehicle Market Revenue million Forecast, by Component 2020 & 2034
Table 6: North America Internet of Vehicle Market Revenue million Forecast, by Technology 2020 & 2034
Table 7: North America Internet of Vehicle Market Revenue million Forecast, by Communication Type 2020 & 2034
Table 8: North America Internet of Vehicle Market Revenue million Forecast, by Country 2020 & 2034
Table 9: United States Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 10: Canada Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 11: Mexico Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 12: South America Internet of Vehicle Market Revenue million Forecast, by Component 2020 & 2034
Table 13: South America Internet of Vehicle Market Revenue million Forecast, by Technology 2020 & 2034
Table 14: South America Internet of Vehicle Market Revenue million Forecast, by Communication Type 2020 & 2034
Table 15: South America Internet of Vehicle Market Revenue million Forecast, by Country 2020 & 2034
Table 16: Brazil Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 17: Argentina Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 18: Rest of South America Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 19: Europe Internet of Vehicle Market Revenue million Forecast, by Component 2020 & 2034
Table 20: Europe Internet of Vehicle Market Revenue million Forecast, by Technology 2020 & 2034
Table 21: Europe Internet of Vehicle Market Revenue million Forecast, by Communication Type 2020 & 2034
Table 22: Europe Internet of Vehicle Market Revenue million Forecast, by Country 2020 & 2034
Table 23: United Kingdom Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Germany Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 25: France Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 26: Italy Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 27: Spain Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 28: Russia Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 29: Benelux Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 30: Nordics Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 31: Rest of Europe Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Internet of Vehicle Market Revenue million Forecast, by Component 2020 & 2034
Table 33: Middle East & Africa Internet of Vehicle Market Revenue million Forecast, by Technology 2020 & 2034
Table 34: Middle East & Africa Internet of Vehicle Market Revenue million Forecast, by Communication Type 2020 & 2034
Table 35: Middle East & Africa Internet of Vehicle Market Revenue million Forecast, by Country 2020 & 2034
Table 36: Turkey Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Israel Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 38: GCC Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 39: North Africa Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 40: South Africa Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 41: Rest of Middle East & Africa Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 42: Asia Pacific Internet of Vehicle Market Revenue million Forecast, by Component 2020 & 2034
Table 43: Asia Pacific Internet of Vehicle Market Revenue million Forecast, by Technology 2020 & 2034
Table 44: Asia Pacific Internet of Vehicle Market Revenue million Forecast, by Communication Type 2020 & 2034
Table 45: Asia Pacific Internet of Vehicle Market Revenue million Forecast, by Country 2020 & 2034
Table 46: China Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 47: India Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 48: Japan Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 49: South Korea Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 50: ASEAN Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 51: Oceania Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Internet of Vehicle Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounted for 72% of total effort and 70–80% of the data weight in this study; secondary research contributed the remaining 28%, within the firm's standard 20–30% band. All interviews were conducted by senior analysts using a structured questionnaire and cross-checked against disclosed filings.
Company types in the value chain (primary interview sample):
Automotive-grade system-on-chip (SoC) and telematics control unit (TCU) suppliers
Tier-1 automotive electronics integrators building V2X modules and zonal domain controllers
Commercial fleet telematics software and SaaS platform operators
OEM connected-vehicle program teams (passenger EV and commercial truck platforms)
Roadside unit (RSU) and smart mobility infrastructure deployers
Stakeholder designations interviewed:
Director of Connected Vehicle Architecture (OEM)
Head of Automotive Semiconductor Product Line
Telematics and Fleet Data Platform Product Manager
Automotive Cybersecurity and Compliance Lead (UNECE R155/R156 scope)
Interview mix: 38% OEM and Tier-1 program decision-makers, 27% semiconductor and module suppliers, 21% software/data platform vendors, 14% infrastructure and network operators. Regional split mirrored revenue weighting: Asia-Pacific 40%, North America 24%, Europe 22%, Middle East & Africa 8%, South America 6%.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Connected Vehicle Architecture
26%
Head of Automotive Semiconductor Product Line
22%
Telematics and Fleet Data Platform Product Manager
19%
Automotive Cybersecurity and Compliance Lead
17%
Vehicle Program Procurement Manager
16%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Tier-1 Automotive Electronics Integrators
28%
Automotive Semiconductor and Module Suppliers
24%
OEM Connected Vehicle Program Teams
20%
Telematics and Fleet Software Providers
16%
Network Operators and RSU Infrastructure Vendors
12%
Secondary Research & Industry Benchmarking
Secondary research supplied historical baselines, regulatory timelines and cross-validation of supplier share. Sources were restricted to audited filings, government publications, standards bodies and trade associations; no market research websites were used.
Benchmarking approach: regulatory effective dates, chipset qualification timelines and OEM production schedules were reconstructed into a unified deployment calendar before any sizing work began.
Every report is updated to the date of purchase, so regulatory and deal tables reflect the latest available disclosures.
Demand Modeling & Market Estimation
Top-down and bottom-up models were built simultaneously and reconciled through multi-level data triangulation at global, regional and segment level.
Bottom-up inputs (quantitative metrics): annual light-vehicle and commercial-vehicle production by region; telematics control unit fitment rate per region; average automotive semiconductor content value per vehicle (USD); active commercial fleet telematics subscriptions and average revenue per user; C-V2X roadside unit deployment counts on designated corridors.
Bottom-up construction: regional vehicle production was multiplied by segment-specific fitment rates and per-unit connectivity cost, then rolled up across hardware, software and service components.
Top-down construction: global connectivity and automotive electronics spending was allocated by region and technology using disclosed supplier revenue shares, then cross-checked against OEM telematics disclosure.
Triangulation: a third estimate was derived from operator connectivity contract values and chipset shipment volumes. Variance beyond ±7% between the three estimates triggered re-interviewing of the affected supply-chain tier.
Forecast logic: 2025–2033 projections apply segment-specific CAGRs, with hardware at 16.2%, software at 21.8% and services at 20.4%, producing a blended 18.0% CAGR and a 2033 valuation of USD 933,576 million.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90% at the global and regional aggregate level.
Every primary interview transcript was reviewed by a second analyst; conflicting figures were resolved by re-contact rather than averaging.
Segment shares were tested against supplier revenue concentration and adjusted where a single vendor exceeded 30% of a sub-segment.
Regulatory timelines were verified against official gazettes, not secondary summaries, and any rule still in proposal stage is labeled as such.
Quarterly refresh cycles reconcile actual vehicle production and chipset shipment data against forecast assumptions; reports are updated to the date of purchase.
Frequently Asked Questions
1. How much venture capital is flowing into connected-vehicle and V2X startups?
Automotive-mobility startups have attracted roughly USD 3.5–4.5 billion of venture funding annually since 2023, with the largest slices going to C-V2X modem software, over-the-air update infrastructure and automotive cybersecurity. Exit benchmarks are now well established: Qualcomm closed its Autotalks acquisition in 2024 at an estimated USD 350 million, and NXP agreed to buy TTTech Auto for USD 625 million in January 2025. Intel's 2022 carve-out IPO of Mobileye raised about USD 861 million, showing continued public-market appetite for vehicle perception and data platforms.
2. What regulations govern the Internet of Vehicle Market and how do they change compliance costs?
UNECE R155 and R156 have applied to all new vehicle types in the EU, Japan and South Korea since July 2024, requiring a certified cybersecurity management system and a software update management system. NHTSA issued a proposed rule in August 2024 to accelerate C-V2X deployment at 5.9 GHz on new light vehicles, while the FCC already reserved the lower 45 MHz of that band for C-V2X in 2020. Compliance adds an estimated USD 150–400 per vehicle in secure gateway hardware, hardware security module provisioning and audit costs.
3. What are the primary growth drivers of the Internet of Vehicle Market?
Three catalysts dominate: mandatory connectivity and cybersecurity compliance, 5G coverage expansion that enables low-latency vehicle-to-everything use cases, and fleet operators chasing measurable ROI. Telematics-based fuel and route optimization typically delivers 10–20% operating cost reduction for commercial fleets, and usage-based insurance programs can cut premiums by 10–30%. These economics underpin the 18.0% CAGR that lifts the market from USD 248,366.62 million in 2025 to USD 933,576 million by 2033.
4. Which segments and product types generate the most revenue?
Hardware is the largest component at roughly 52% of revenue, driven by telematics control units, V2X radios and zonal domain controllers. Software is the fastest-growing at about 21.8% CAGR, followed by services at 20.4%, both benefiting from over-the-air update platforms and data subscription models. By technology, cellular (4G LTE and 5G C-V2X) accounts for an estimated 58% of connectivity revenue, ahead of Wi-Fi, Bluetooth and NFC.
5. Which region is growing fastest and where are the emerging opportunities?
Asia-Pacific is the fastest-growing region at an estimated 21.5% CAGR and already represents 40.0% of global revenue, supported by China's C-V2X pilot-city program and new energy vehicle penetration above 40% of domestic sales. North America grows at 17.2% and Europe at 16.8%, both anchored by regulatory deadlines rather than volume expansion. The fastest incremental upside now sits in India's AIS-140 telematics mandate and GCC smart-mobility programs, where base-year valuations remain below USD 20,000 million.
6. What disruptive technologies could reshape the Internet of Vehicle Market?
Cellular V2X has effectively displaced DSRC and ITS-G5 in China and the United States, and 5G-Advanced with RedCap modules will lower the cost of always-connected vehicles. Edge AI inference inside domain controllers reduces cloud round-trip latency from hundreds of milliseconds to under 20 milliseconds for safety functions, while ultra-wideband digital key systems are replacing passive NFC entry. Automotive cybersecurity moves in parallel, with intrusion detection and secure element provisioning becoming standard line items in every vehicle bill of materials.