Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Analytical X-ray Instrumentation Market: 4.88% CAGR to 2033
Analytical X-ray Instrumentation Market
Analytical X-ray Instrumentation Market: 4.88% CAGR to 2033
Analytical X-ray Instrumentation Market by Type (Analog X-ray Systems, Digital X-ray Systems), by Application (General Radiography, Chest Imaging Applications, Chest Imaging Applications, Cardiovascular Imaging, Dental Applications, Cancer detection, Others), by Technology (Computed Radiography, Direct Radiography), by End Users (Hospitals, Diagnostic Centers, Dental Care Centers), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
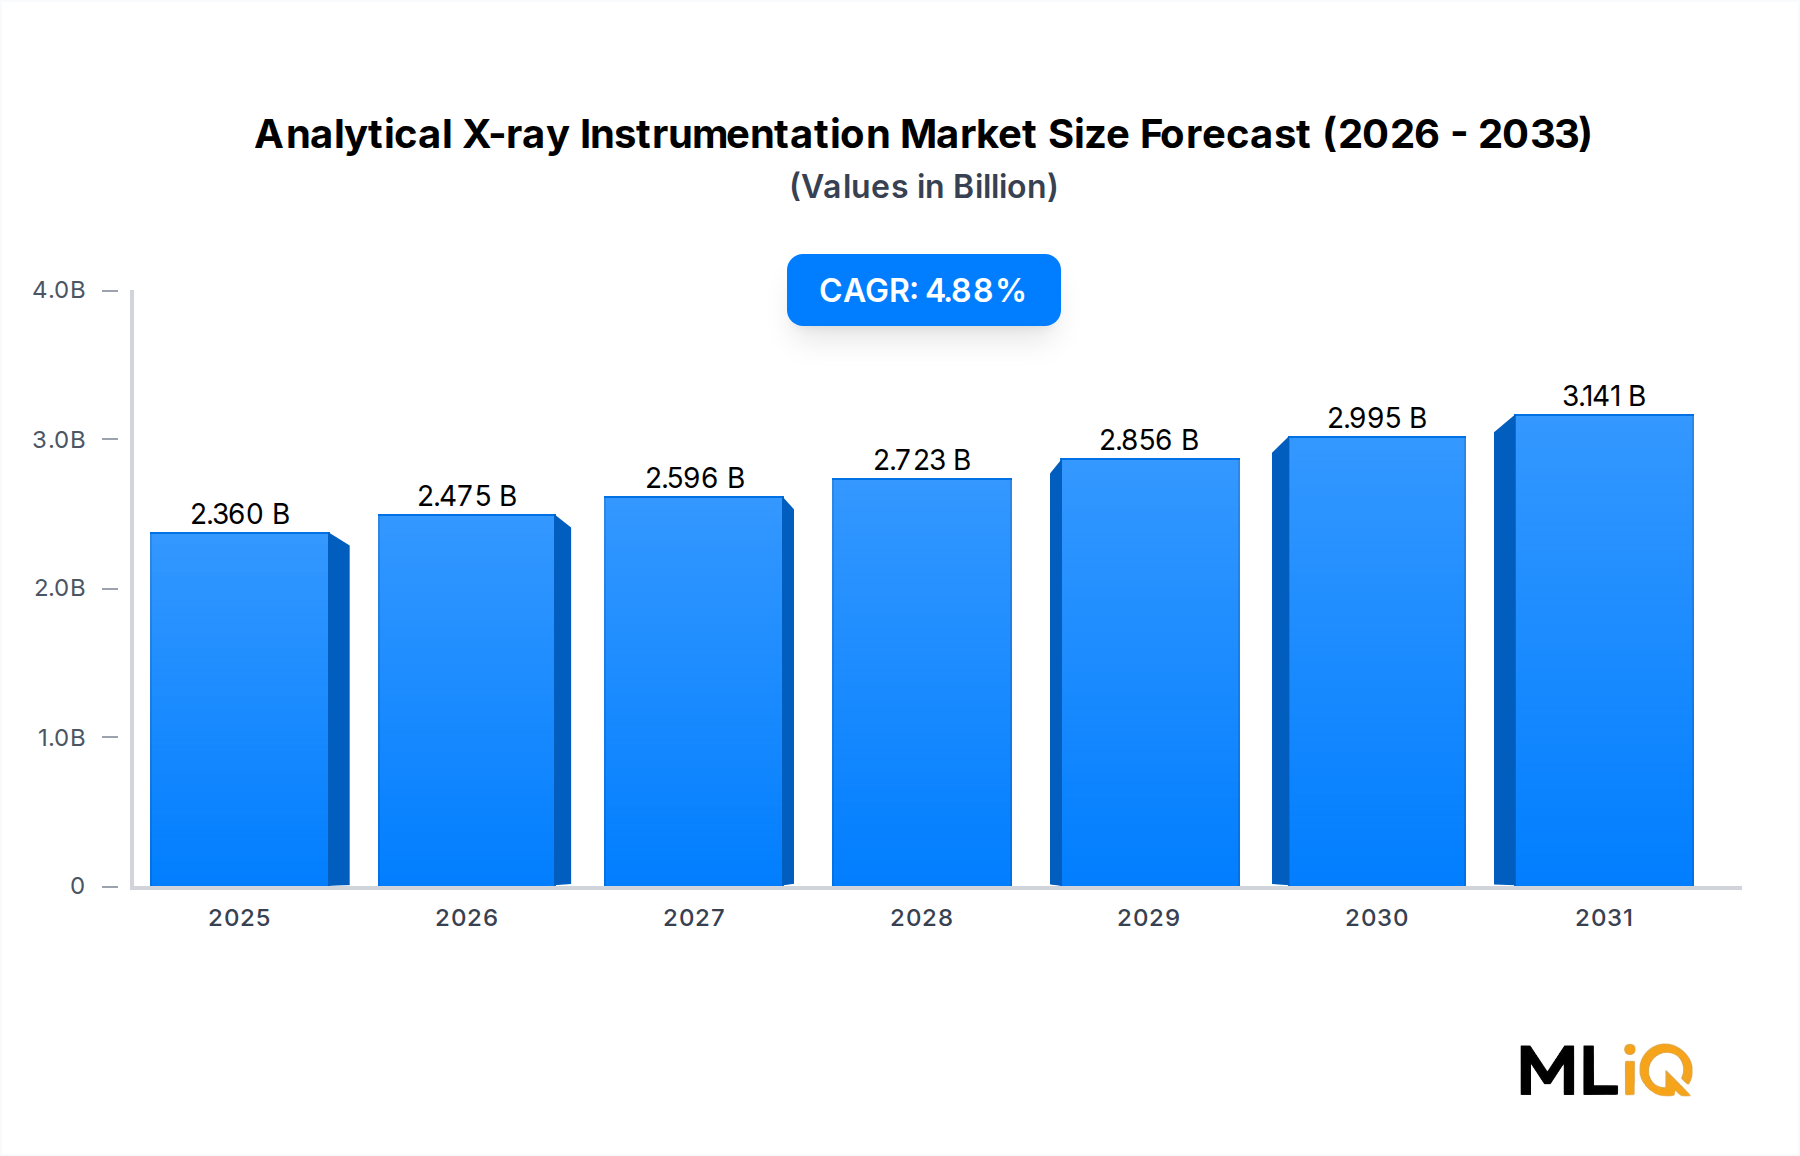
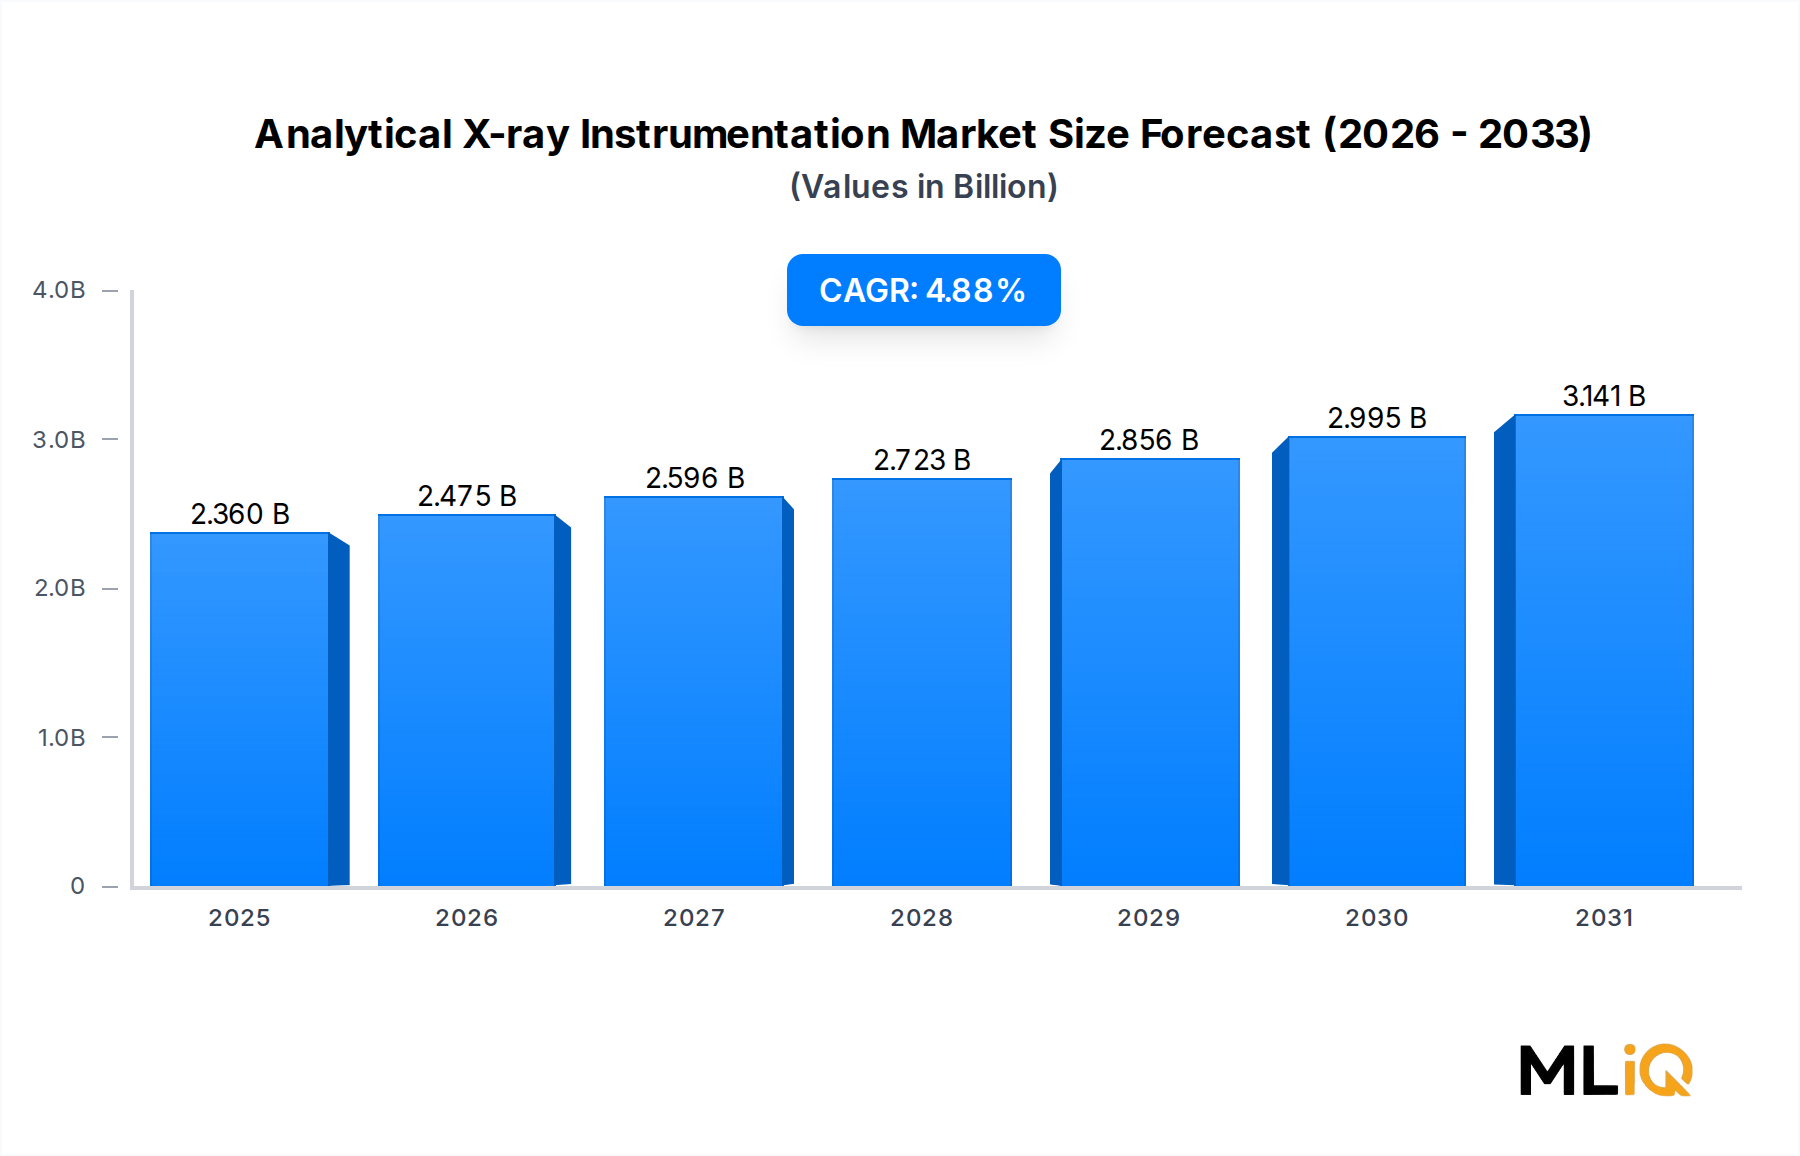
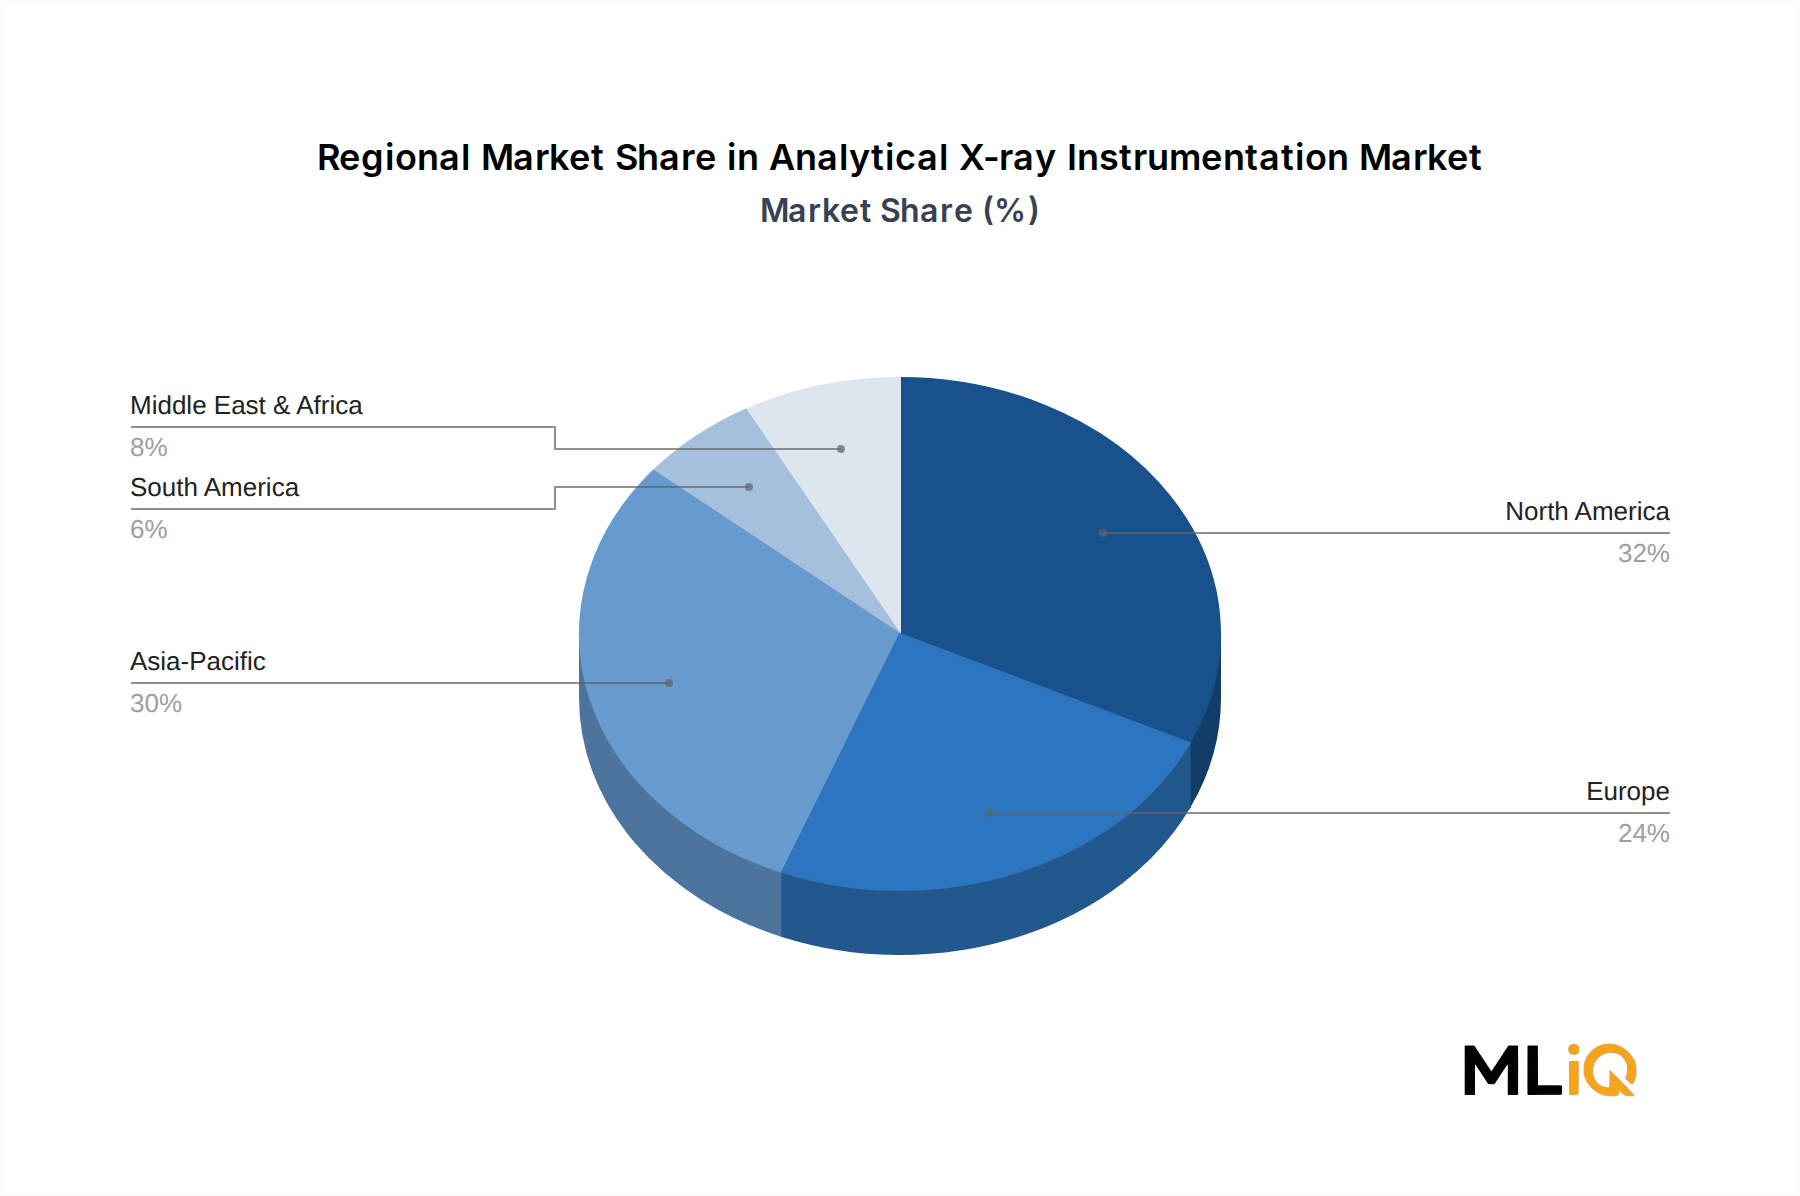
The global Analytical X-ray Instrumentation Market reached $2.36 billion in 2025 and is forecast to expand to $3.46 billion by 2033, registering a 4.88% CAGR. Growth is supported by hospital replacement cycles, the shift from analog to digital detectors, and rising demand for Diagnostic X-ray Market procedures in aging populations. North America holds the largest regional share at 32%, driven by high imaging volumes and favorable reimbursement.
Analytical X-ray Instrumentation Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.360 B
2025
2.475 B
2026
2.596 B
2027
2.723 B
2028
2.856 B
2029
2.995 B
2030
3.141 B
2031
Digital transformation: More than 70% of new radiology installations use digital panels, reducing film and chemical costs.
AI integration: AI-based image reconstruction is being adopted in 18% of new high-end systems, improving diagnostic confidence.
Cost pressure: Equipment prices for premium systems range from $150,000 to $500,000, limiting adoption in low-resource settings.
The Medical Imaging Equipment Market benefits from this X-ray instrumentation demand, as X-ray remains the most frequent imaging modality globally. However, supply-chain constraints for specialized semiconductors and X-ray tubes create lead times of 12–20 weeks. The market outlook remains positive but uneven across regions.
Segment Deep-Dive: Digital X-ray Systems Dominance in Analytical X-ray Instrumentation Market
Segment Analysis Matrix
Segment
CAGR (%)
Market Share (%)
Key Demand Driver
Digital X-ray Systems
5.4
68
Faster image acquisition, lower radiation dose
Analog X-ray Systems
1.2
24
Low-cost replacements in emerging markets
Direct Radiography
6.0
52
Workflow efficiency and PACS integration
Digital X-ray Systems Market is the largest revenue contributor, with $1.60 billion in 2025. The Analog X-ray Systems Market continues to decline in developed regions but remains relevant in price-sensitive markets. Within technology, the Direct Radiography Market is replacing the Computed Radiography Market, which grows at only 2.5% annually.
Sub-segment dynamics
General radiography accounts for 38% of digital system revenue, followed by chest imaging at 21%.
Dental Radiography Market is a high-margin niche, with 9% of total instrument sales but higher replacement frequency.
Cardiovascular imaging requires specialized detectors, commanding a 15–20% price premium.
Margin pressures
Intense competition among Thermo Fisher, Bruker, and Siemens Healthineers compresses gross margins to 35–42%.
Component costs for X-ray tubes and flat panels rose 8% in 2024, squeezing mid-tier vendors.
Service and maintenance contracts now represent 22% of total revenue, providing recurring income.
Aging population increases diagnostic imaging volume by 5% annually
High
Long term
Driver
Digital detector replacement cycles shorten to 6–8 years
High
Short term
Driver
AI-assisted diagnosis reduces read time by 25%
Medium
Short term
Restraint
High equipment cost limits adoption in emerging markets
High
Long term
Restraint
Regulatory approvals for new X-ray devices take 12–18 months
Medium
Long term
Restraint
Global shortage of helium-3 and rare earth materials
Medium
Short term
Key drivers include rising chronic disease prevalence and hospital capital spending. In the U.S., the Centers for Medicare & Medicaid Services (CMS) reimbursement for X-ray procedures supports steady demand. The Diagnostic X-ray Market is also boosted by point-of-care imaging in emergency departments, which grew 11% in 2024.
Restraints center on cost and regulation. A single digital radiography room costs between $200,000 and $400,000, deterring small clinics. The FDA’s 510(k) pathway adds 6–12 months to product launches. Additionally, tariffs on imported X-ray components increase prices by 4–7% in North America.
Thermo Fisher Scientific Inc.: Leverages its analytical portfolio to cross-sell X-ray systems into pharmaceutical and materials testing labs.
Bruker: Focuses on high-end X-ray diffraction, with 15% of revenue from service contracts.
Rigaku: Holds 22% share in semiconductor metrology X-ray tools and invests 9% of revenue in R&D.
Siemens Healthineers: Installed base of over 40,000 radiography systems, strong in Hospital X-ray Imaging Market.
GE Healthcare: Offers AI-based X-ray triage, targeting 20% reduction in report turnaround.
Canon Inc.: Supplies flat panel detectors to OEMs and direct radiography systems to dental clinics.
Carestream Health: Specializes in Dental Radiography Market with compact, low-dose units.
PANalytical B.V.: Serves industrial X-ray fluorescence and diffraction, with 12% market share in mining.
Koninklijke Philips N.V.: Integrates X-ray with cardiovascular ultrasound and informatics.
AMETEK: Provides X-ray detectors for security and industrial inspection, growing at 6.5% annually.
Strategic Milestones & Recent Developments in Analytical X-ray Instrumentation Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Q2 2024
Bruker
Launch
Released high-throughput X-ray diffractometer for battery research
Q4 2024
Siemens Healthineers
Partnership
Collaborated with AI firm for radiography triage software
Q1 2025
GE Healthcare
M&A
Acquired AI imaging startup to enhance X-ray analytics
Q2 2025
Rigaku
Launch
Introduced compact CT X-ray system for semiconductor inspection
Q3 2025
Canon Inc.
Partnership
Teamed with dental distributor to expand in Asia-Pacific
Q2 2024: Bruker launched a new X-ray diffractometer targeting lithium-ion battery quality control, addressing a $120 million materials analysis segment.
Q4 2024: Siemens Healthineers partnered with an AI vendor, aiming to cut radiologist reading time by 30%.
Q1 2025: GE Healthcare acquired an AI imaging startup for $85 million, strengthening its X-ray software stack.
Q2 2025: Rigaku introduced a compact CT system with 2 µm resolution for semiconductor fault detection.
Q3 2025: Canon Inc. expanded dental radiography distribution in India and Southeast Asia, targeting 15% annual growth.
Asia-Pacific is the fastest-growing region, driven by China’s $1.2 billion medical imaging equipment budget and India’s dental radiography expansion.
North America remains the most mature, with 68% of systems already digital; growth comes from replacements and AI upgrades.
Europe faces slower growth due to stringent EU MDR compliance costs, but Germany and France lead in direct radiography adoption.
LAMEA shows rising demand in Turkey and GCC countries, where private hospital chains invest in digital X-ray rooms.
Investment, M&A & Funding Activity in Analytical X-ray Instrumentation Market
M&A activity has accelerated. In 2024, $340 million in disclosed deals targeted X-ray detector and AI software companies. Private equity firms invested $110 million in dental radiography roll-ups across Europe and North America.
Venture capital: X-ray AI startups raised $95 million in 2024, with average round size of $12 million.
Strategic acquirers: Thermo Fisher, Bruker, and Siemens Healthineers completed 7 acquisitions since 2023.
High-growth sub-segments: photon-counting detectors and portable X-ray systems attracted 60% of total funding.
Partnerships: OEMs formed 14 distribution agreements with dental and veterinary imaging providers in 2025.
Technology Innovation & R&D Trajectory in Analytical X-ray Instrumentation Market
Three disruptive technologies are reshaping the market:
Photon-counting detectors: Offer 30% higher contrast at lower dose. Adoption expected in 15% of premium systems by 2028. Patent filings grew 22% annually since 2022.
AI-based reconstruction: Reduces image noise and scan time. R&D spending by top five vendors reached $480 million in 2024, with AI representing 18%.
CMOS flat panel X-ray Detector Market: Enables portable, low-power imaging. The X-ray Detector Market is projected to grow at 7.2% CAGR, challenging incumbent scintillator designs.
These technologies reinforce demand for the Medical Imaging Equipment Market but threaten analog and computed radiography vendors. Incumbents must invest in detector fabrication and software to maintain share. R&D intensity averages 8–10% of revenue among leading vendors, with patent expirations in 2027 creating opportunities for generic tube manufacturers.
Table 58: Rest of Asia Pacific Analytical X-ray Instrumentation Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% primary research via interviews with X-ray tube and detector OEMs, flat panel detector manufacturers, medical imaging software integrators, dental radiography distributors, and hospital radiology procurement consortia.
Interviewed 3–4 stakeholder titles: Chief Radiology Procurement Officer, Medical Imaging Director, X-ray Systems Product Manager, Clinical Engineering Manager, and Regulatory Affairs Specialist.
Data accuracy guaranteed at 85–90% through cross-validation of interview transcripts and survey responses.
Primary input covered installed base, replacement cycles, and purchasing criteria for Digital X-ray Systems Market and Analog X-ray Systems Market.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Radiology Procurement Officer
24%
Medical Imaging Director
22%
X-ray Systems Product Manager
20%
Clinical Engineering Manager
18%
Regulatory Affairs Specialist
16%
Industry Ecosystem Breakdown
Company Type
Representation (%)
X-ray tube and detector OEMs
28%
Flat panel detector manufacturers
22%
Medical imaging software integrators
18%
Dental radiography equipment distributors
17%
Hospital radiology procurement consortia
15%
Secondary Research & Industry Benchmarking
20–30% secondary research from Bloomberg, Factiva, Hoovers, and PitchBook for financial filings, M&A, and funding rounds.
Also referenced .gov databases (e.g., CMS reimbursement schedules), .org trade publications, and NEMA standards for X-ray equipment.
Every report is updated to the date of purchase, incorporating latest company announcements and regulatory changes.
Demand Modeling & Market Estimation
Simultaneous top-down and bottom-up methodologies validated via multi-level data triangulation.
Bottom-up metrics: annual X-ray exams per 1,000 population, installed base of digital radiography systems, average replacement cycle for X-ray detectors, hospital radiology capital expenditure per bed, and dental practice X-ray unit density per 10,000 population.
Top-down segmentation by Type (Analog X-ray Systems, Digital X-ray Systems), Application, Technology, and End Users.
Regional demand modeled for North America, Europe, Asia-Pacific, South America, and Middle East & Africa.
Data Accuracy & Quality Check
Triangulation across primary interviews, secondary databases, and trade association reports yields 85–90% estimated data accuracy.
Outlier detection and variance analysis performed on all quantitative inputs.
Final market sizes for Diagnostic X-ray Market and Medical Imaging Equipment Market cross-checked against public company revenues.
Quality assurance review by senior analysts before publication.
Frequently Asked Questions
1. How active is venture capital investment in the Analytical X-ray Instrumentation Market?
Venture capital investment reached $95 million in 2024 across 22 deals, with average round size of $12 million. Most funding targeted AI reconstruction and portable X-ray detector startups. Strategic investors like GE Healthcare and Siemens Healthineers participated in 6 of these rounds.
2. What disruptive technologies are reshaping the Analytical X-ray Instrumentation Market?
Photon-counting detectors, AI-based image reconstruction, and CMOS flat panel sensors are the primary disruptors. Photon-counting offers 30% higher contrast at lower dose and is expected in 15% of premium systems by 2028. AI reconstruction reduces radiologist reading time by 25% and is being adopted by major OEMs.
3. Who are the leading companies in the Analytical X-ray Instrumentation Market?
Thermo Fisher Scientific, Bruker, Rigaku, Siemens Healthineers, and GE Healthcare are the market leaders. The top five vendors collectively hold approximately 48% of global revenue. Siemens Healthineers has the largest installed base in Hospital X-ray Imaging Market with over 40,000 systems.
4. How are purchasing trends shifting in the Analytical X-ray Instrumentation Market?
Hospitals increasingly prefer Direct Radiography Market solutions over computed radiography, with 72% of new radiology purchases being direct digital systems. Buyers demand AI integration and lower dose features, driving premium pricing. Dental clinics are adopting compact digital units, boosting the Dental Radiography Market by 8% annually.
5. Which segments dominate the Analytical X-ray Instrumentation Market?
Digital X-ray Systems Market dominates with 68% revenue share, followed by Analog X-ray Systems Market at 24%. General radiography is the largest application at 38% of segment revenue. Chest imaging and dental applications are the fastest-growing sub-segments, each exceeding 6% CAGR.
6. What are the major supply-chain risks in the Analytical X-ray Instrumentation Market?
Supply-chain risks include helium-3 shortages, rare earth material dependencies, and semiconductor lead times of 12–20 weeks. Tariffs on imported X-ray tubes increased costs by 4–7% in North America in 2024. Regulatory delays for new devices add 12–18 months to product launches.