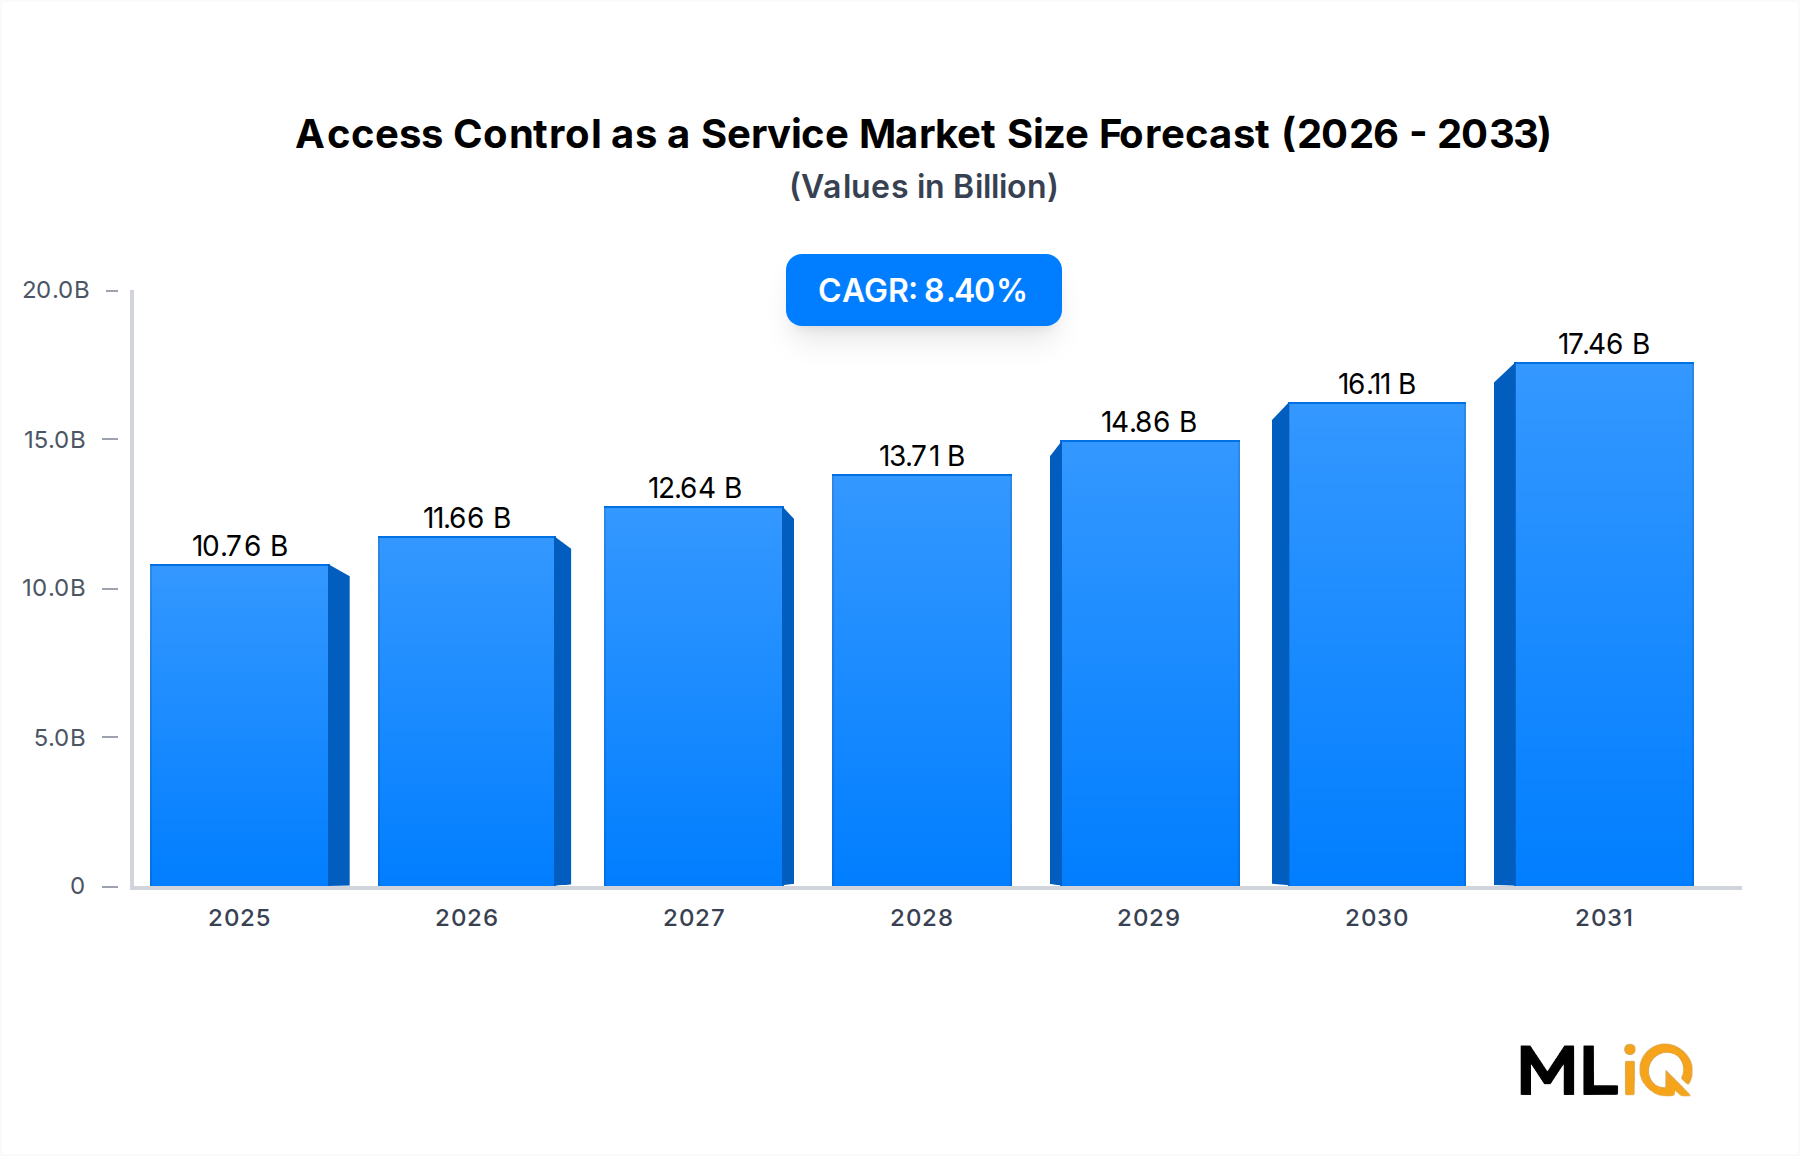
The global Access Control as a Service Market was valued at $10.76 billion in 2024 and is projected to expand at a compound annual growth rate of 8.4% through 2033, reflecting sustained institutional and commercial appetite for cloud-delivered, subscription-based security infrastructure. This trajectory positions the market as one of the fastest-maturing segments within enterprise security, outpacing legacy on-premises alternatives in both deployment velocity and total cost of ownership attractiveness.
Several macro-level forces are converging to sustain this momentum. First, the widespread acceleration of digital transformation programs across governments, healthcare systems, and financial institutions is compelling organizations to decommission siloed, hardware-bound access control systems in favor of centrally managed, remotely administered cloud platforms. Second, the normalization of hybrid and remote work models has created structural demand for identity-aware perimeter security that can dynamically manage entry points across geographically dispersed facilities without requiring on-site IT intervention. Third, heightened regulatory scrutiny around data privacy and physical security compliance — including GDPR in Europe, HIPAA in healthcare verticals, and FedRAMP standards in government procurement — is pushing organizations toward auditable, cloud-native access logging frameworks.
On the supply side, the competitive landscape is increasingly shaped by platform convergence, where vendors are bundling access control functionality with video analytics, visitor management, and identity lifecycle management tools. This convergence is eroding the boundaries between the Access Control as a Service Market and adjacent segments such as the Identity and Access Management Market and the Physical Security Market, creating upsell pathways that accelerate average revenue per user metrics.
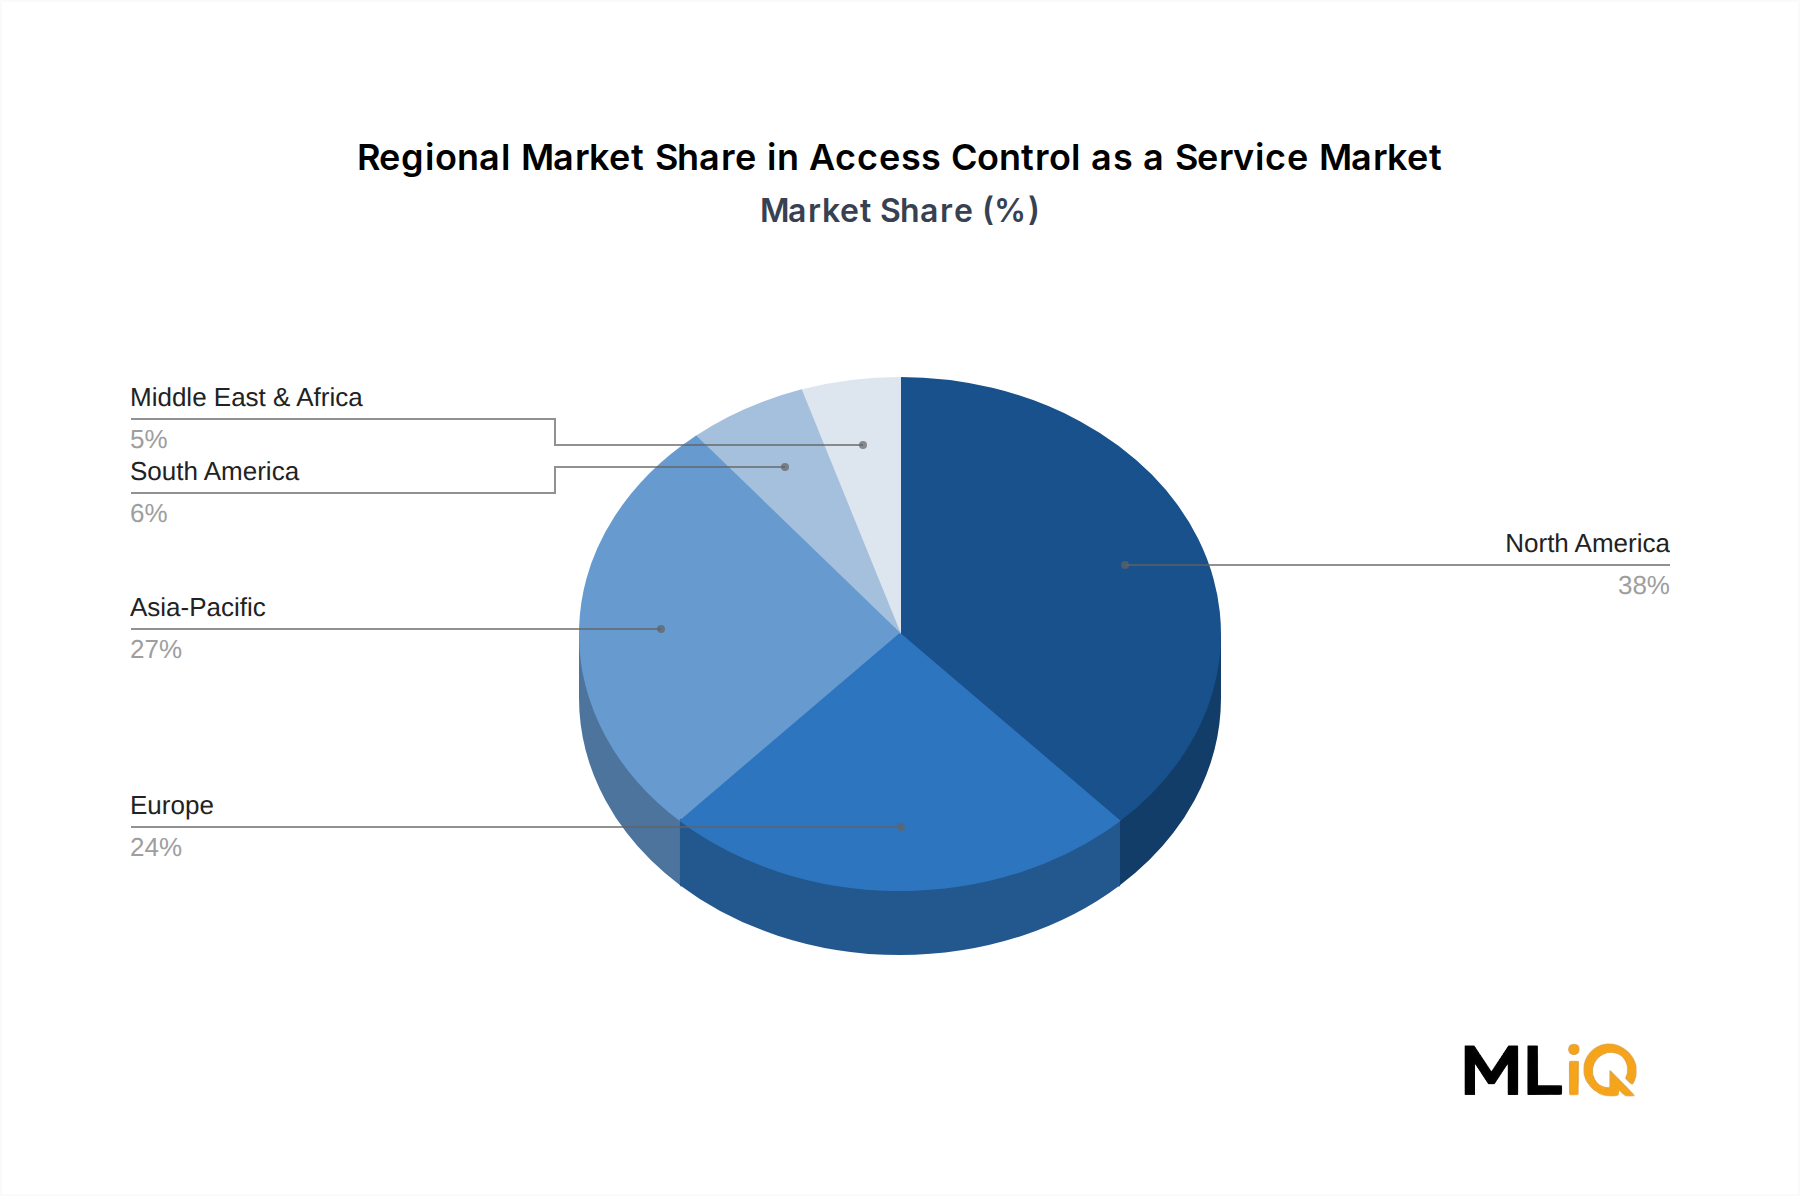
North America currently holds the largest revenue share, underpinned by high enterprise security spending and early cloud adoption. However, Asia Pacific is emerging as the fastest-growing region, driven by large-scale smart city investments and government-mandated digital infrastructure upgrades across China, India, and Southeast Asia.
Looking ahead to 2033, market participants that successfully integrate AI-driven anomaly detection, mobile credential management, and zero-trust architecture into their service stacks are expected to command disproportionate revenue share. The competitive moat is increasingly defined not by hardware breadth but by the depth of cloud-native integrations, API ecosystems, and analytics capabilities — reinforcing the structural shift from capital expenditure models to recurring, operationally expensed subscription arrangements across all major end-use verticals.