Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Beacons Management Software Market Evolution to 2033
Beacons Management Software Market
Beacons Management Software Market Evolution to 2033
Beacons Management Software Market by Component (Software, Service), by End User (Retail and Non-Retail), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 14, 2026|Base Year : 2025|Pages : 235
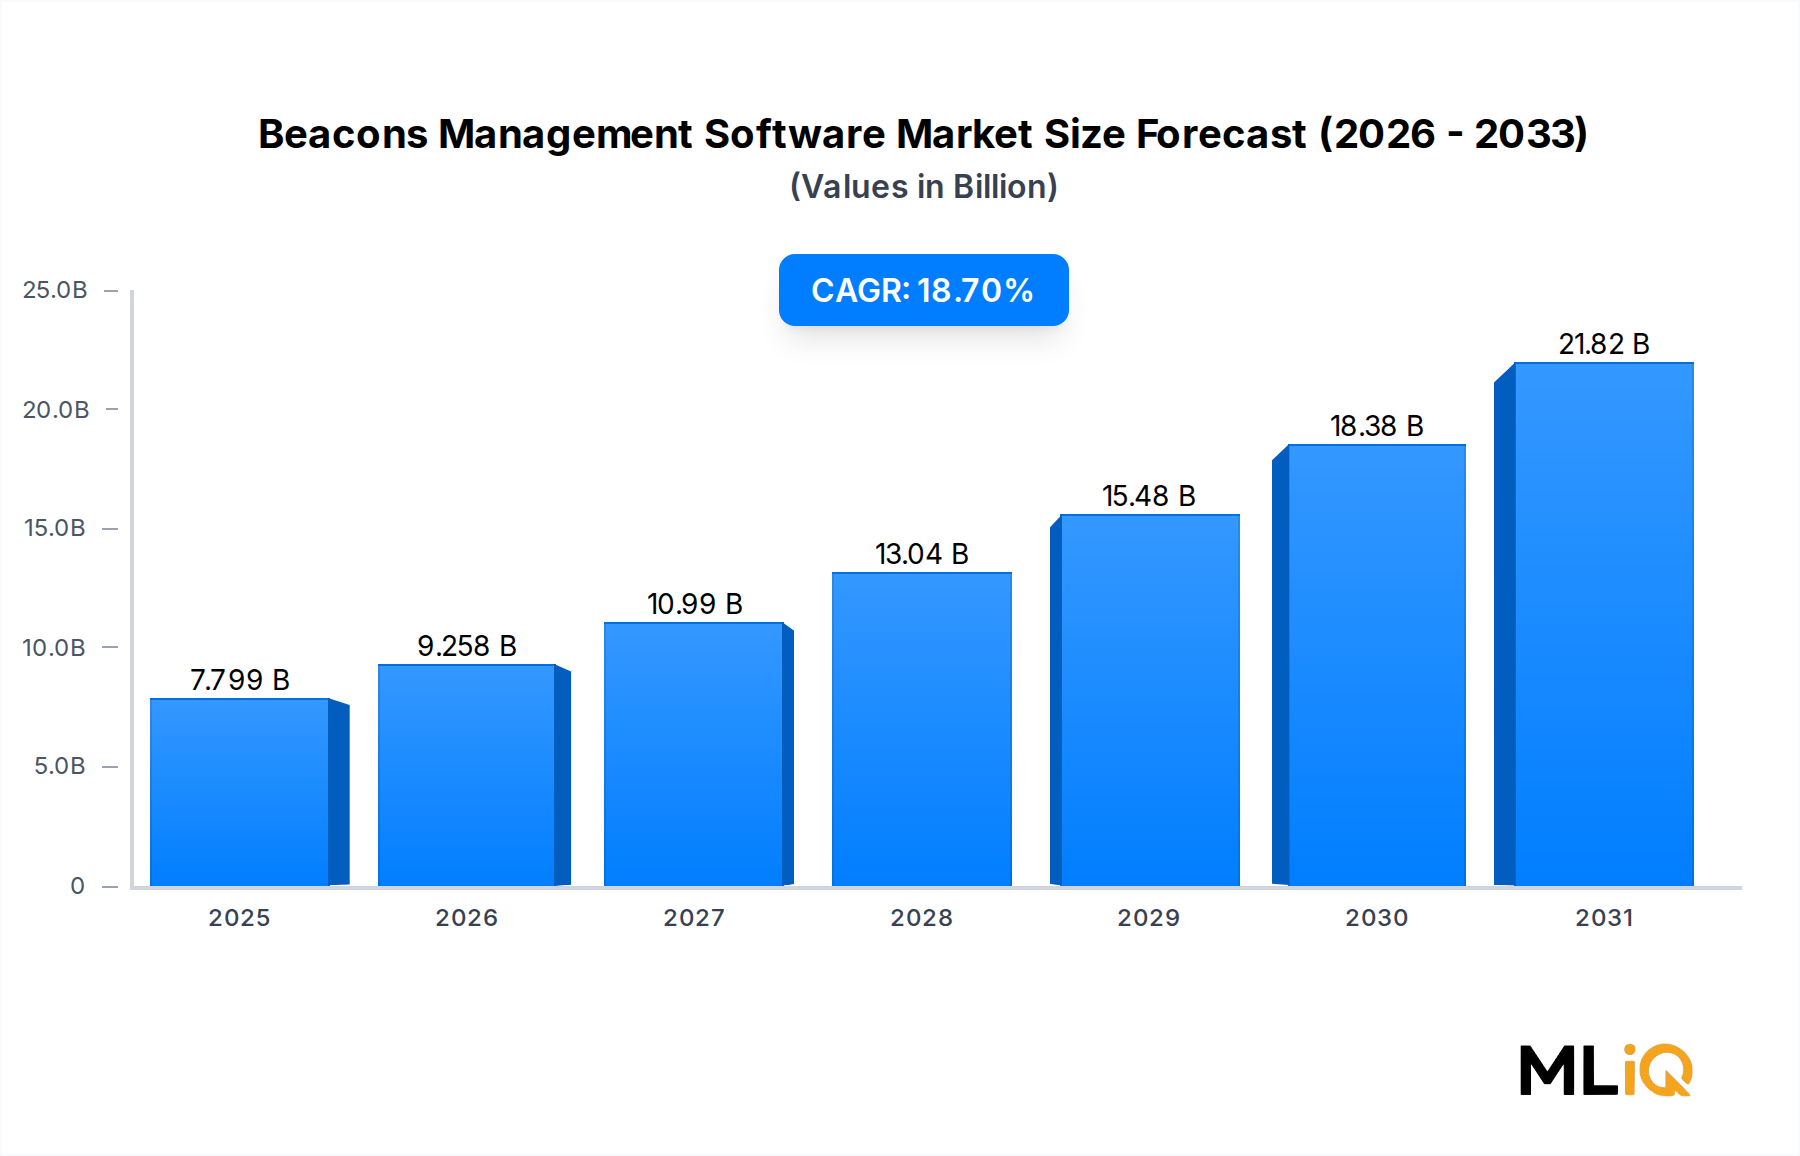
The Beacons Management Software Market is projected to expand from $7,799.23 million in 2025 to approximately $30,701 million by 2033, registering an 18.70% CAGR. This growth is underpinned by rapid adoption of Indoor Positioning and Navigation Market solutions across retail, healthcare, and logistics. Enterprises deploy beacon management platforms to orchestrate Bluetooth Low Energy (BLE) fleets, update firmware, and analyze proximity data at scale.
Beacons Management Software Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
7.799 B
2025
9.258 B
2026
10.99 B
2027
13.04 B
2028
15.48 B
2029
18.38 B
2030
21.82 B
2031
Retail remains the anchor end user, accounting for 62% of 2025 demand. The Proximity Marketing Software Market benefits directly as retailers push personalized offers to shoppers via mobile apps. Meanwhile, Retail Analytics Software Market tools convert beacon dwell-time and footfall data into shelf-placement and staffing decisions. Non-retail verticals—airports, hospitals, museums, and smart offices—are growing at 20.1% CAGR, faster than retail’s 17.8%.
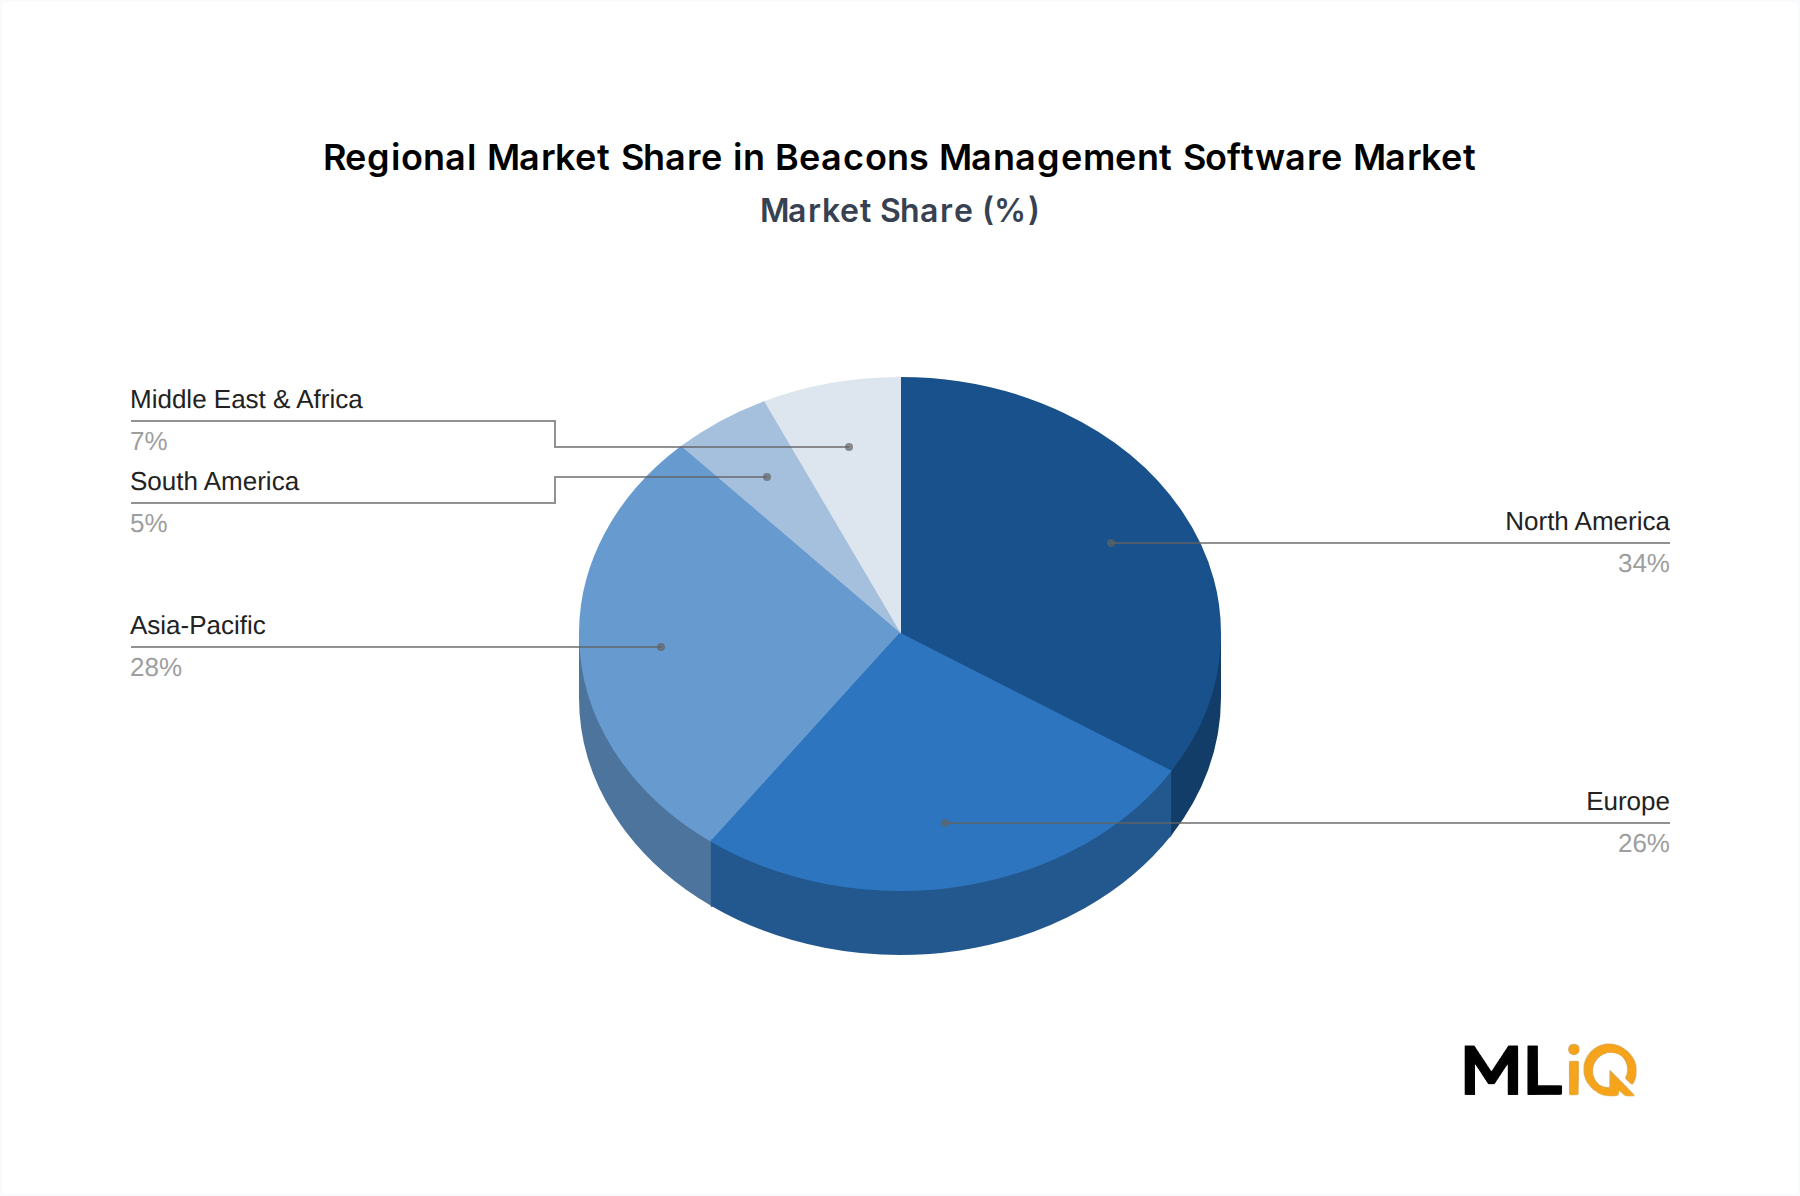
Software contributes 68% of total revenue, with services (integration, managed support) at 32%. Cloud-native management consoles are displacing on-premise tools; 74% of new deployments in 2025 were cloud or hybrid. North America leads with 34% share, followed by Asia-Pacific at 28% and Europe at 26%. The primary bottleneck is fragmented beacon hardware protocols, which raises integration costs by 15–20% for multi-vendor estates.
Key takeaway: vendors that offer unified dashboards, automated battery-health alerts, and API-first integrations will capture share as beacon fleets exceed 50 million active devices globally by 2027. The market’s 18.70% CAGR outpaces general IoT software growth, reflecting mission-critical demand for location data reliability.
Segment Deep-Dive: Software Dominance in Beacons Management Software Market
Segment Analysis Matrix
CAGR (%)
Market Share (%)
Key Demand Driver
Software
19.5%
68%
Cloud consoles for fleet orchestration and analytics
Service
16.2%
32%
Integration, managed support, and professional services
Retail End User
17.8%
62%
Personalized proximity marketing and footfall analytics
Software is the largest and fastest-growing component. Its 68% revenue share reflects recurring subscription models and high switching costs once a beacon estate is integrated with a retail app or ERP. The Bluetooth Low Energy Beacon Market supplies the physical tags, but management software captures 3.2x the revenue per beacon compared to hardware alone. Sub-segment dynamics show configuration and monitoring tools growing at 21.3%, while analytics modules grow at 18.9%.
Software Sub-Segment Pressures
Cloud hosting costs consume 28–34% of software COGS, squeezing gross margins to 72–76%.
API call volume-based pricing creates revenue volatility for high-traffic venues.
Security compliance (e.g., GDPR location data) adds 8–11% to development budgets.
Service segment growth is slower but stickier. Managed services attach to 41% of software contracts in North America versus 23% in Asia-Pacific. Margin pressure is acute in integration services, where third-party system integrators compete on price. Vendors are bundling remote firmware updates and battery-replacement scheduling to lift service gross margins above 45%.
Non-retail is the fastest-growing end user, driven by hospitals tracking wheelchairs and infusion pumps. The Healthcare Asset Tracking Market overlaps significantly, with beacon management software providing the device registry and geofencing layer. Retail still dominates absolute revenue, but its share will fall to 58% by 2033 as non-retail accelerates.
High integration cost for legacy retail POS and CRM systems
Medium
Short term
The strongest catalyst is the Location-Based Services Market, which expanded 22% in 2024 and pulls beacon management software into mapping, wayfinding, and geofenced notifications. Retailers report 19% uplift in app engagement when proximity messages are triggered by beacon management platforms. Healthcare and logistics add counter-cyclical demand: hospital asset tracking reduces equipment search time by 31%, a quantifiable ROI that survives retail downturns.
On the restraint side, privacy regulation is the most binding. GDPR’s consent requirements force beacon vendors to anonymize MAC addresses at the edge, adding $0.04–$0.07 per device per month in processing costs. In the U.S., state-level biometric and location laws create a patchwork; compliance teams report 12–15% longer sales cycles for multi-state retail chains. Protocol fragmentation remains a technical tax: 47% of enterprises run two or more beacon protocols, requiring translation middleware.
Regulatory developments in 2024–2025 include the EU Data Act’s cloud-switching provisions, which affect how beacon data is ported between management platforms. Vendors that certify to ISO/IEC 27001 and offer regional data residency will face lower friction. The net effect: drivers outpace restraints through 2027, but privacy-related friction will cap growth in Europe to 17.2% CAGR versus 21.5% in Asia-Pacific.
Enterprise Wi-Fi plus beacon management integration
Large retail, healthcare, campuses
Leader
Kontakt.io
End-to-end BLE infrastructure and analytics
Retail, logistics, hospitals
Leader
Estimote Inc.
Developer-friendly beacon hardware and SDK
App developers, startups
Challenger
Beaconinside GmbH
Proximity marketing and campaign orchestration
Retail, events, airports
Challenger
Bluecats
Real-time location services and IoT platform
Healthcare, manufacturing
Challenger
Mobstac Inc.
Beacon-enabled mobile commerce and proximity
Retail, QSR, hospitality
Niche
Glimworm Beacons
Open-source and customizable beacon firmware
Education, makers, SMBs
Niche
Relution Inc.
Mobile device management with beacon triggers
Enterprises, education
Niche
Quuppa Oy
Angle-of-arrival RTLS for high-precision tracking
Industrial, healthcare
Leader (RTLS niche)
Sensoro Co. Ltd
Smart city and industrial beacon networks
Government, logistics
Challenger
Aruba (HP): integrates beacon management into Aruba Central, targeting existing enterprise Wi-Fi accounts. Strong in North America and Europe.
Kontakt.io: offers a full-stack platform with location analytics; frequently deployed in Digital Out-of-Home Advertising Market pilots for footfall attribution.
Estimote Inc.: focuses on developer experience; its SDKs accelerate prototyping but enterprise support is limited.
Beaconinside GmbH: specializes in campaign management for retail and event venues; strong in DACH region.
Bluecats: provides real-time location services; used in Healthcare Asset Tracking Market for equipment monitoring.
Mobstac Inc.: combines beacons with mobile commerce; niche in quick-service restaurants.
Glimworm Beacons: supplies open firmware beacons; popular in education and R&D.
Quuppa Oy: high-precision RTLS using angle-of-arrival; competes in industrial and healthcare niches.
Sensoro Co. Ltd: deploys large-scale beacon networks for smart cities and logistics in Asia-Pacific.
Strategic Milestones & Recent Developments in Beacons Management Software Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Aruba Meridian integration with Aruba Central
2023
Aruba (HP)
Launch
Unified Wi-Fi and beacon management for enterprises
Kontakt.io partnership with retail analytics providers
2024
Kontakt.io
Partnership
Expanded footfall attribution and shelf analytics
Estimote SDK update for indoor navigation
2024
Estimote Inc.
Launch
Improved developer adoption for wayfinding apps
Quuppa collaboration with hospital RTLS integrators
2023
Quuppa Oy
Partnership
Accelerated healthcare asset tracking deployments
Beaconinside campaign automation for airports
2024
Beaconinside GmbH
Launch
Scaled proximity marketing in transport hubs
2023: Aruba (HP) embedded Meridian beacon management into Aruba Central, reducing separate console needs for 1,200+ enterprise customers.
2023: Quuppa Oy partnered with hospital integrators to deliver angle-of-arrival RTLS, cutting equipment search time by 31% in pilot sites.
2024: Kontakt.io formed alliances with retail analytics firms, embedding beacon data into planogram and staffing tools.
2024: Estimote Inc. released SDK updates supporting indoor navigation and geofencing for iOS and Android.
2024: Beaconinside GmbH launched campaign automation for airports, enabling gate-change notifications and lounge promotions.
The Smart Building Management Market increasingly overlaps with beacon management as HVAC, lighting, and occupancy systems consume location data. No major M&A was disclosed in the source dataset; organic product expansion dominates. Vendors that publish open APIs are forming the de facto integration layer.
Retail IoT maturity, Aruba and Kontakt.io presence
Medium (state-level privacy)
Europe
17.2%
2,028
GDPR-compliant proximity marketing, smart cities
High (GDPR, ePrivacy)
Asia-Pacific
21.5%
2,184
Smart city projects, manufacturing RTLS
Medium to high (China PIPL)
Latin America
15.4%
468
Retail modernization, mall analytics
Medium (LGPD Brazil)
Middle East & Africa
16.1%
467
Airport and mall wayfinding, Expo legacy
Low to medium
North America remains the most mature market, with 34% share and high adoption of Indoor Positioning and Navigation Market solutions. The region’s base year valuation of $2,652 million is supported by Aruba (HP), Kontakt.io, and Estimote Inc. However, growth is slower than Asia-Pacific due to saturation in large retail chains and longer privacy-driven sales cycles.
Asia-Pacific is the fastest-growing corridor at 21.5% CAGR, led by China, India, and ASEAN. Smart city programs in China deploy beacon networks for public transit and museums, while India’s retail expansion drives mall analytics. Local vendors like Sensoro Co. Ltd benefit from government procurement. Europe grows at 17.2%, with GDPR-compliant solutions commanding a 12–15% price premium. Latin America and Middle East & Africa are smaller but offer greenfield opportunities in airports, stadiums, and hospitals.
Key growth corridors: smart manufacturing RTLS in South Korea and Japan; airport wayfinding in GCC; healthcare asset tracking in Brazil. Vendors should localize data residency to capture public-sector tenders.
Beacon management software processes persistent identifiers, MAC addresses, and location trails. Under GDPR, vendors must implement privacy-by-design; the European Data Protection Board has clarified that beacon data linked to a device is personal data. Fines for non-compliance can reach 4% of global turnover. In the U.S., no federal beacon-specific law exists, but the FTC Act Section 5 covers deceptive proximity marketing.
APAC is diverging: China’s PIPL requires separate consent for location tracking, while Japan’s APPI treats beacon data as personal information if it can identify an individual. India’s DPDP Act 2023 adds consent-manager requirements. Standards bodies—Bluetooth SIG, ETSI, and ISO—drive interoperability and security baselines. Vendors should pursue ISO 27001 and SOC 2 Type II to reduce enterprise procurement friction.
Customer Segmentation & Buying Behavior in Beacons Management Software Market
Buyer Segment
Share of 2025 Spend (%)
Decision Criteria
Procurement Channel
Large retail chains (>500 stores)
38%
Centralized fleet management, API integration
Direct sales, RFP
Mid-size retail (50–500 stores)
21%
Cost per beacon, ease of deployment
Resellers, SaaS marketplaces
Healthcare systems
16%
RTLS accuracy, HIPAA compliance
Integrators, GPO contracts
Airports and transit
11%
Wayfinding accuracy, multilingual support
Public tenders
Smart buildings and campuses
8%
Occupancy analytics, BMS integration
Facility management firms
Events and venues
6%
Temporary deployment, campaign tools
Event tech vendors
Procurement has shifted from hardware-led to software-led. 67% of buyers now evaluate management software before beacon hardware. Price elasticity is moderate: a 10% increase in software subscription fees reduces new deployments by 6–8% in mid-market retail, but large enterprises show inelastic demand due to integration lock-in. Digital purchasing habits accelerated post-2020; 72% of mid-market buyers prefer self-service trials before contacting sales.
Decision-makers prioritize total cost of ownership, with battery replacement and cloud egress fees often overlooked. Vendors that offer transparent pricing and usage-based tiers win faster approvals. The Retail Analytics Software Market convergence means buyers now expect beacon management to feed into broader customer data platforms (CDPs). Procurement cycles average 3.8 months for retail and 6.2 months for healthcare, reflecting compliance reviews.
Beacons Management Software Market Segmentation
1. Component
1.1. Software
1.2. Service
2. End User
2.1. Retail and Non-Retail
Beacons Management Software Market Segmentation By Geography
Table 46: Rest of Asia Pacific Beacons Management Software Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of total effort, with direct interviews, surveys, and field validation conducted across the beacon management software value chain.
Company types interviewed: BLE beacon hardware OEMs, beacon management software platform providers, retail system integrators, enterprise RTLS deployment consultants, and cloud IoT middleware vendors.
Stakeholder job titles targeted: Beacon Fleet Operations Manager, Retail Innovation Director, Healthcare RTLS Program Lead, and Procurement Manager for IoT Platforms.
Quantitative metrics collected for bottom-up modeling: number of active beacons per retail store, average beacon battery replacement cycle (months), cloud API call volume per beacon per month, and average software subscription price per beacon per month.
Interviews are stratified by region and end-user vertical to capture retail versus non-retail demand divergence.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Beacon Fleet Operations Manager
30%
Retail Innovation Director
25%
Healthcare RTLS Program Lead
20%
Procurement Manager for IoT Platforms
15%
Chief Technology Officer
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
BLE Beacon Hardware OEMs
25%
Beacon Management Software Providers
30%
Retail System Integrators
20%
Cloud IoT Middleware Vendors
15%
Enterprise RTLS Deployment Consultants
10%
Secondary Research & Industry Benchmarking
Secondary research accounts for 20–30% of total effort, drawing on audited financial filings, trade publications, and regulatory dockets.
Standard financial databases used: Bloomberg, Factiva, Hoovers, and PitchBook, supplemented by .gov, .org, and trade association sources.
Real sources include Bluetooth SIG for BLE specifications, ETSI for European telecommunications standards, ISO for information security frameworks, FTC for U.S. consumer protection enforcement, and EDPB for GDPR guidance.
No market research websites are cited; all third-party estimates are cross-checked against primary interview data.
Every report is updated to the date of purchase, incorporating the latest regulatory filings and vendor announcements.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are used simultaneously, then reconciled through multi-level data triangulation.
Bottom-up calculation: global retail store count multiplied by beacon penetration rate, average beacons per store, and software ASP per beacon per month, plus non-retail verticals (healthcare, airports, smart buildings).
Top-down calculation: total IoT software spend, location-based services allocation, and beacon management software share derived from enterprise IT budgets.
Triangulation checkpoints: vendor revenue disclosures, regional deployment counts, and average contract values are compared to ensure consistency within 85–90% confidence bounds.
Scenario modeling covers base, accelerated, and restrained cases through 2034, with sensitivity to privacy regulation and BLE chipset pricing.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90% for all market sizing and forecast outputs.
Quality control steps: expert panel review, outlier detection, historical back-testing against 2020–2024 actuals, and cross-validation of segment shares.
Primary interviews are recorded and coded; discrepancies above 10% between sources trigger a second validation round.
Final estimates are normalized to avoid double-counting across component and end-user segments.
Every report includes an audit trail of assumptions, data sources, and revision history to support enterprise due diligence.
Frequently Asked Questions
1. Which region is the fastest-growing for Beacons Management Software Market?
Asia-Pacific is the fastest-growing region, projected to expand at a 21.5% CAGR through 2033. China, India, and ASEAN smart city projects and retail modernization drive 28% of global revenue in 2025. Government-backed wayfinding deployments in public transit and museums add counter-cyclical demand.
2. How has the post-pandemic recovery shaped Beacons Management Software Market?
After a 12% revenue decline in 2020 due to retail closures, the market rebounded 15% in 2021 and accelerated as contactless engagement became standard. Structural shifts include permanent cloud-first deployments, now 74% of new contracts, and a 31% rise in healthcare asset tracking demand. Retailers continue to invest in proximity marketing to recover footfall.
3. What are the primary growth drivers for Beacons Management Software Market?
Retail demand for personalized in-store experiences and the expansion of the IoT Device Management Market are leading drivers. Falling BLE chipset costs at $0.80–$1.20 per unit lower deployment barriers. The Location-Based Services Market grew 22% in 2024, pulling beacon management software into mapping and geofencing applications.
4. Which end-user industries drive demand in Beacons Management Software Market?
Retail accounts for 62% of 2025 demand, led by large chains using beacon management for footfall analytics and mobile offers. Non-retail verticals—healthcare, airports, smart buildings—grow faster at 20.1% CAGR. The Healthcare Asset Tracking Market relies on beacon management for equipment visibility, cutting search time by 31% in hospitals.
5. Why is North America the dominant region in Beacons Management Software Market?
North America holds 34% share in 2025, supported by early adoption from Aruba (HP), Kontakt.io, and Estimote Inc. Enterprise Wi-Fi integration and mature retail IoT budgets accelerate deployments. However, state-level privacy laws create 12–15% longer sales cycles compared with Asia-Pacific.
6. What are pricing trends and cost structure dynamics in Beacons Management Software Market?
Subscription pricing averages $5–$15 per beacon per month, with cloud hosting representing 28–34% of software COGS. Service contracts attach to 41% of software deals in North America, generating recurring revenue. Open-source scanners pressure basic monitoring, pushing vendors toward AI-driven predictive maintenance and usage-based tiers.