Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Autonomous Driving Technology Market 20.2% CAGR to 2033
Autonomous Driving Technology Market
Autonomous Driving Technology Market 20.2% CAGR to 2033
Autonomous Driving Technology Market by Level of Automation (Level 1, Level 2, Level 3, Level 4, Level 5), by Application (Civil, Defense, Transportation Logistics, Construction), by Propulsion Type (Semi-autonomous, Fully Autonomous), by Vehicle Type (Passenger Car, Commercial Vehicle), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
Autonomous Driving Technology Market Size (In Billion)
300.0B
200.0B
100.0B
0
86.30 B
2025
103.7 B
2026
124.7 B
2027
149.9 B
2028
180.1 B
2029
216.5 B
2030
260.3 B
2031
Market at a Glance
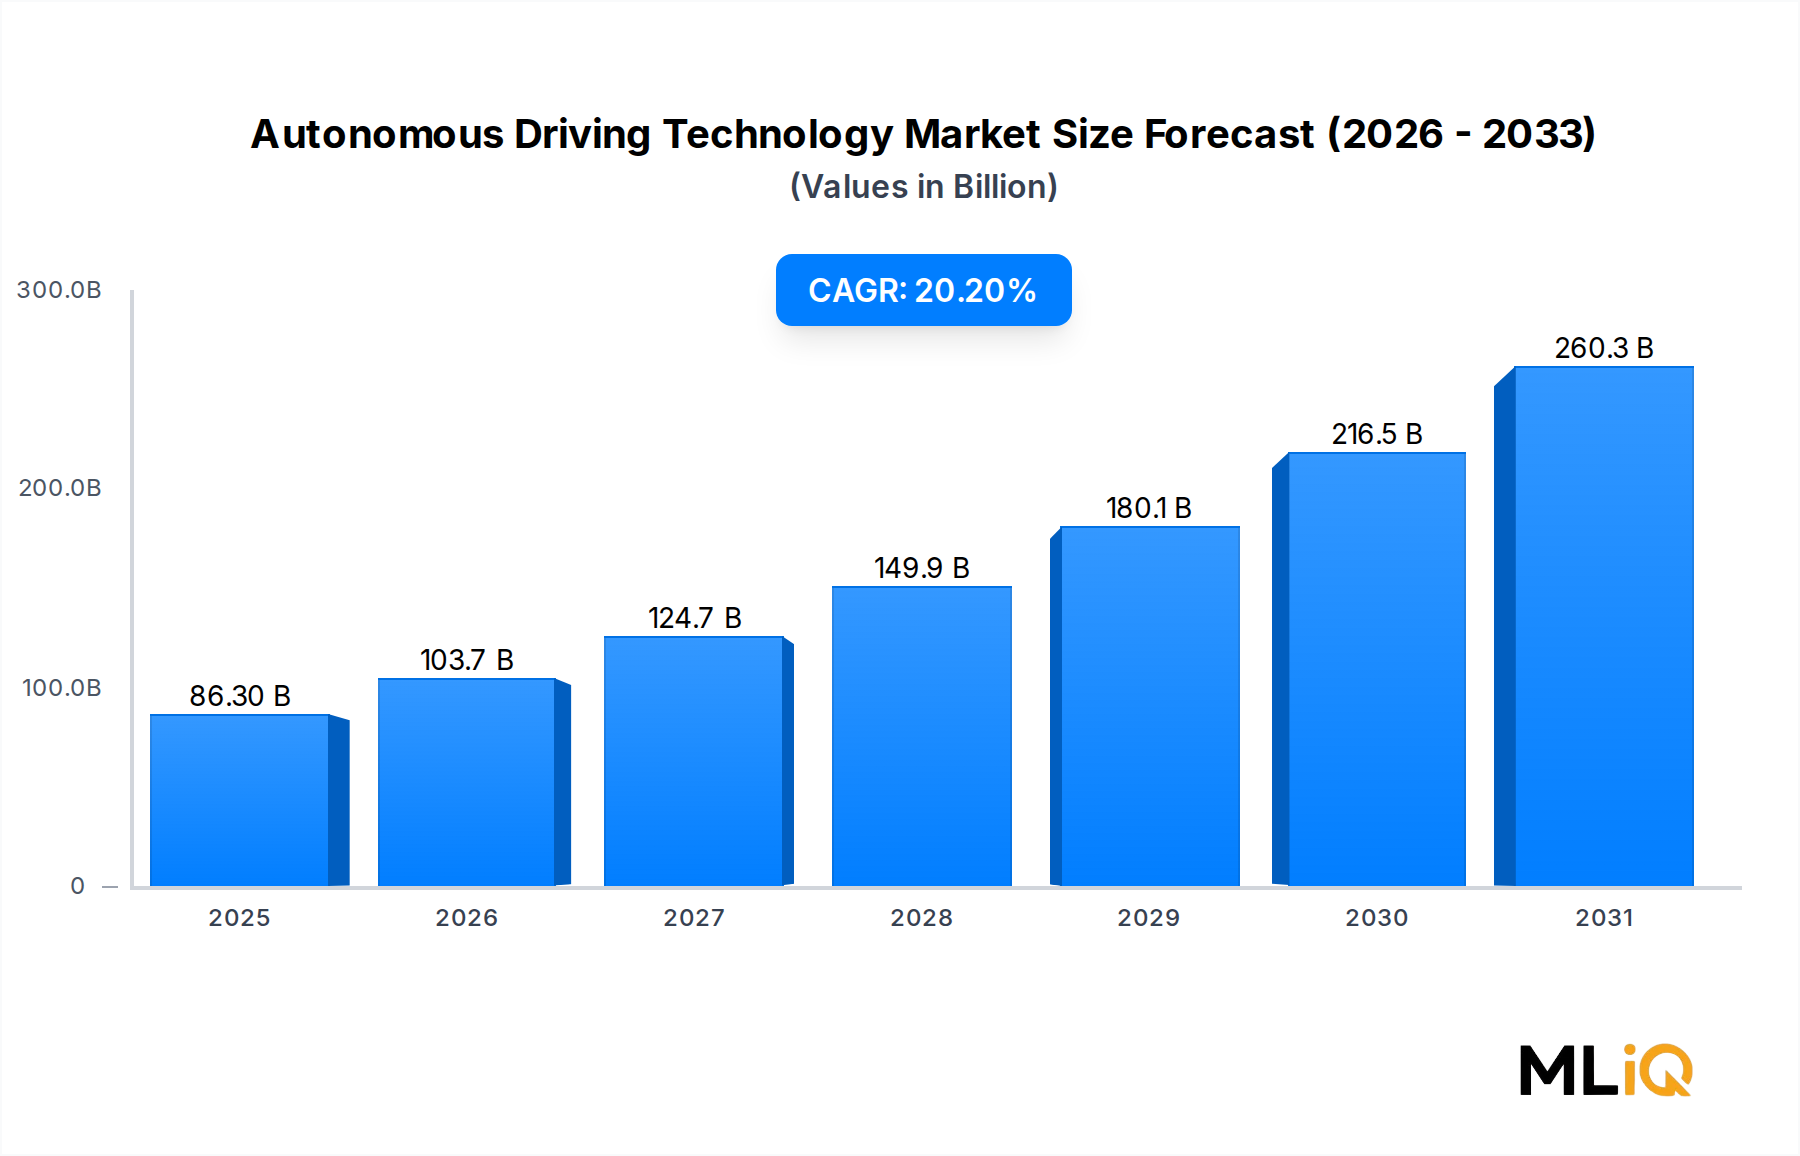
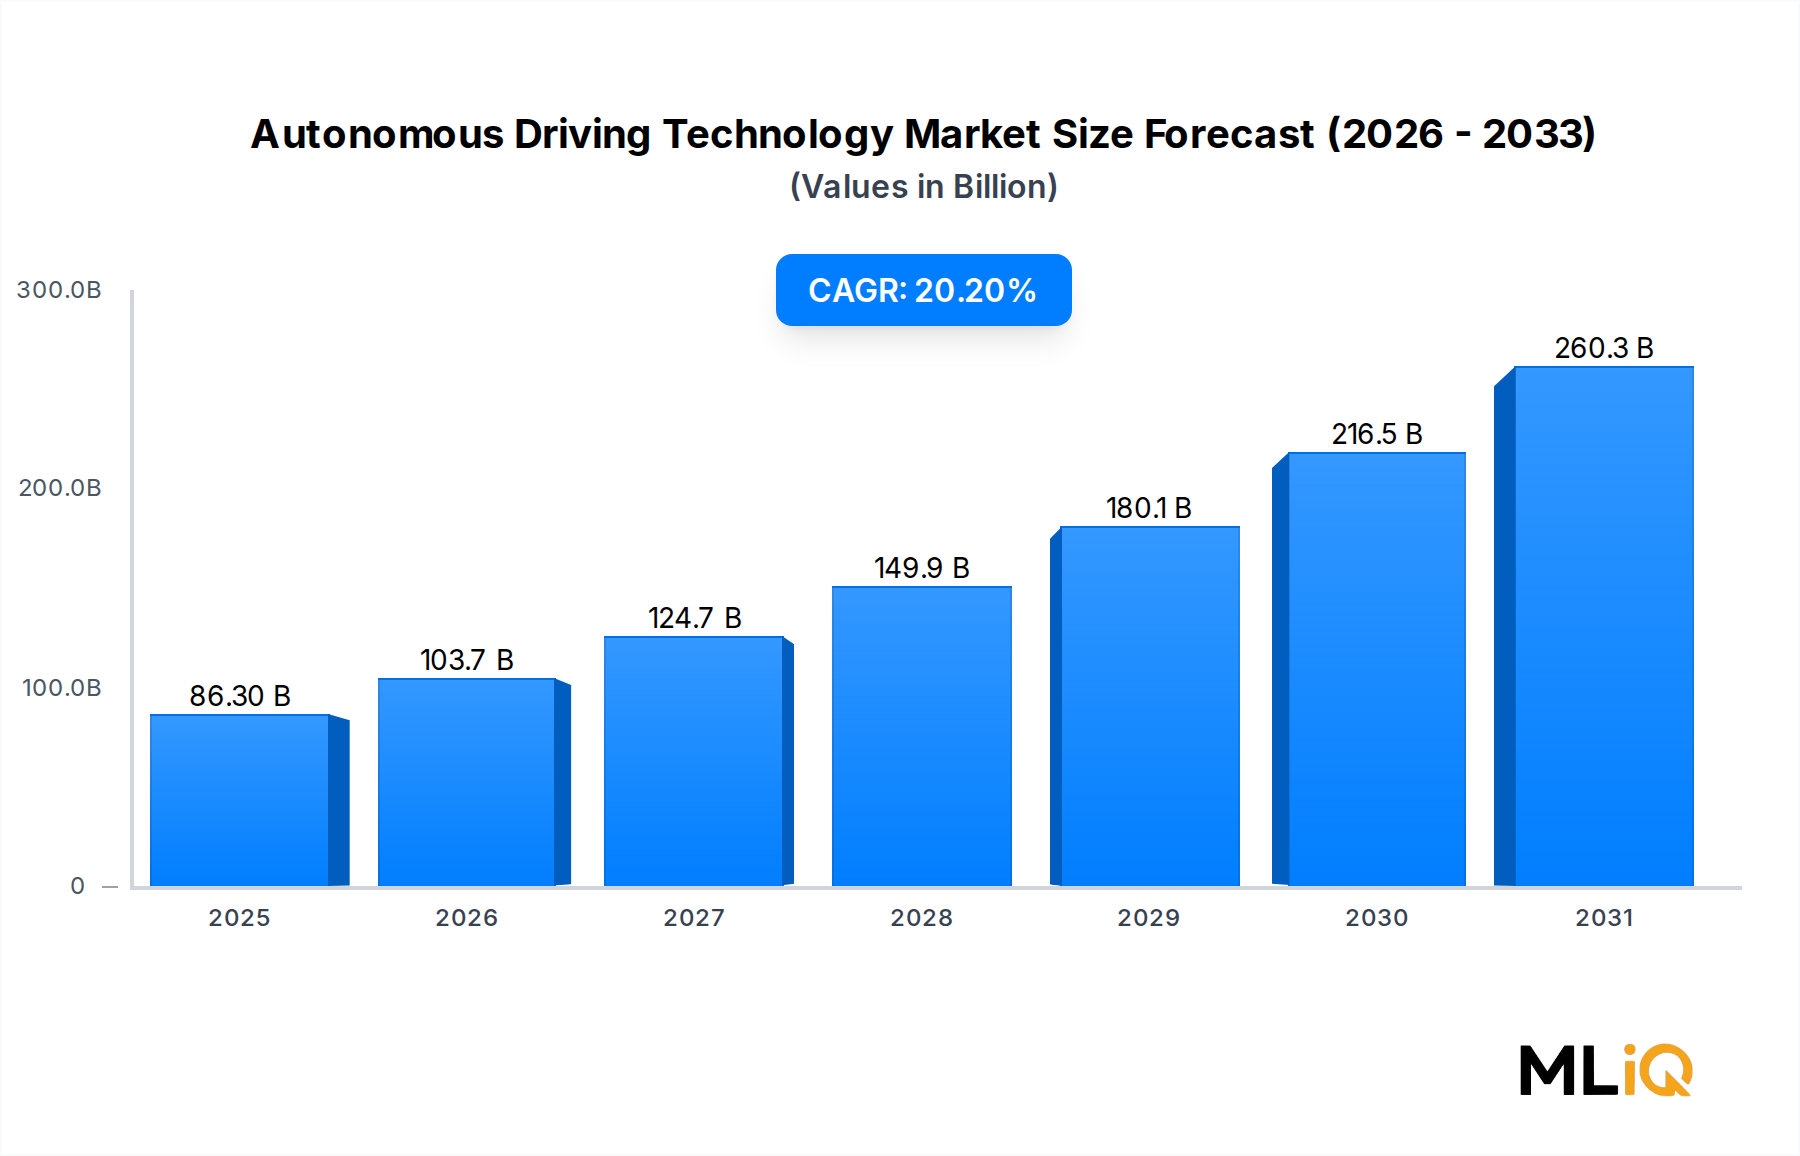
The Autonomous Driving Technology Market reaches $86.3 billion in 2025 and is set to expand to $376.1 billion by 2033, registering a 20.2% CAGR. Growth is driven by declining sensor costs, regulatory approvals for Level 3 systems, and rising consumer demand for advanced driver assistance. Asia-Pacific leads regional revenue, supported by China's aggressive smart vehicle mandates and Japan's robotaxi pilots. The Autonomous Vehicle Software Market attracts the highest venture funding, while the ADAS Sensor Market benefits from economies of scale in camera and radar production.
Automotive OEMs face a dual imperative: reduce hardware costs and monetize software. Tesla, Inc. and General Motors generate recurring revenue through over-the-air updates, with Tesla's Full Self-Driving package priced at $12,000 or $199 per month. BMW AG and Volkswagen AG embed Level 2 systems as standard on premium models, raising average selling prices by 4% to 6%. The LiDAR Market consolidates around solid-state designs, with unit prices falling from $10,000 in 2018 to under $1,000 in 2025.
Regulatory fragmentation remains a key variable. NHTSA's proposed framework for Level 3 deployment in the United States contrasts with the EU's UNECE R157 rules, which permit hands-off driving up to 60 km/h. China's Ministry of Industry and Information Technology approved Level 3 pilot zones in Beijing and Shanghai, accelerating local testing. These divergences force global platforms to maintain region-specific software stacks, increasing R&D spending by 12% to 18% annually for major automakers.
Key Strategic Takeaways
Level 2 systems generate 48% of 2025 revenue, but Level 4 will grow at a 35.6% CAGR through 2033.
Passenger cars hold 68% share by vehicle type; commercial vehicles grow faster in the Autonomous Trucking Market.
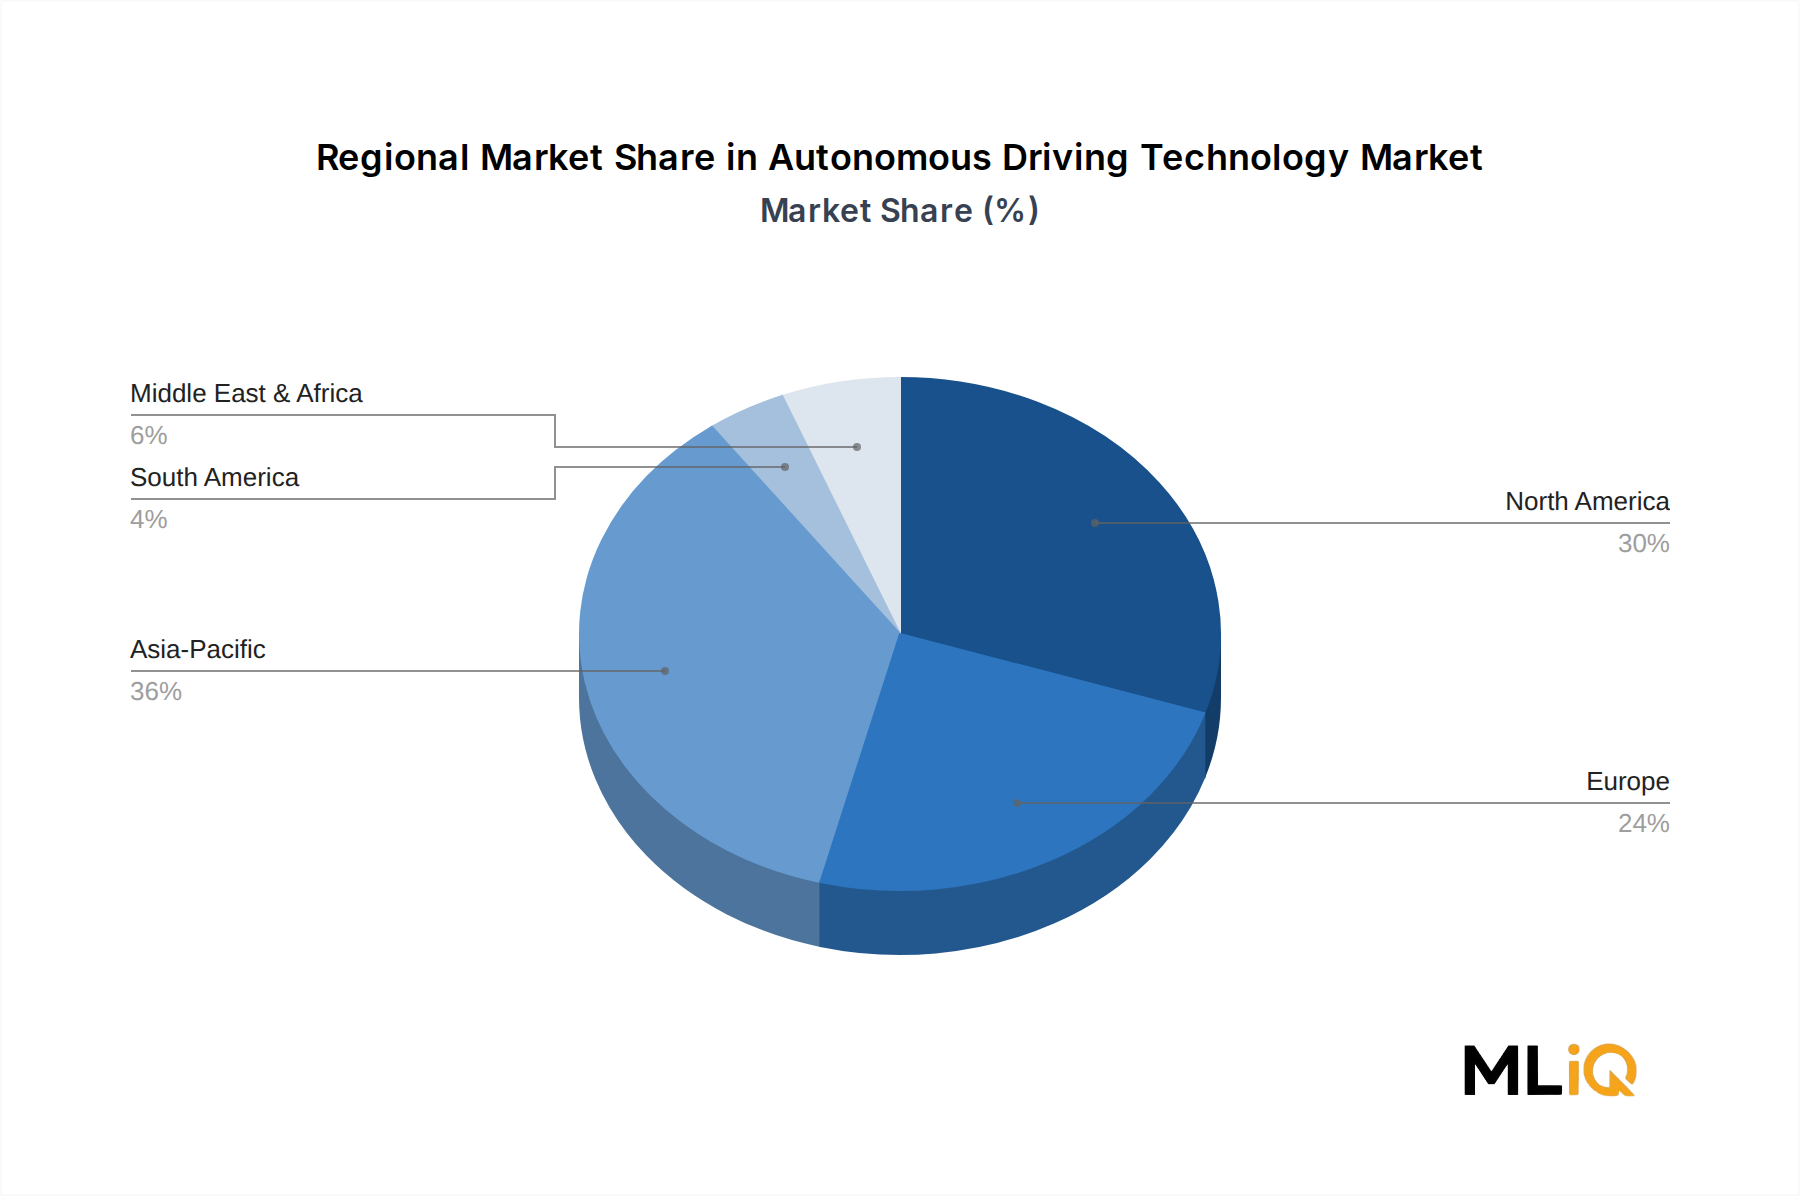
Asia-Pacific contributes 36% of global revenue, driven by China's EV and autonomous driving integration.
Automotive Semiconductor Market supply constraints eased in 2024, but advanced AI chips remain concentrated among NVIDIA, Qualcomm, and Mobileye.
High Definition Mapping Market requires continuous updates, creating recurring data revenue for HERE, TomTom, and Google.
Level 2 automation remains the revenue engine, with 48% of total market value in 2025. This segment includes adaptive cruise control, lane centering, and automatic emergency braking. Sub-segment dynamics show camera-plus-radar fusion dominating at 72% of Level 2 hardware shipments, while LiDAR remains limited to premium trims. Margin pressure is intense: Tier-1 suppliers face annual price reductions of 3% to 5% from OEMs, pushing consolidation among sensor makers.
Sub-Segment Dynamics by Application
The Civil application accounts for 61% of Level 2 demand, followed by Transportation Logistics at 24%. Defense and Construction adopt Level 2 for convoy and site management but represent smaller volumes. The Commercial Vehicle Autonomous Driving Market is nascent, with Level 2 platooning systems from AB Volvo and Daimler AG entering fleet trials. These systems reduce fuel consumption by 5% to 8% and improve driver retention.
Vehicle Type and Propulsion Type
Passenger cars represent 68% of 2025 revenue, while commercial vehicles show a higher growth rate of 24.3% CAGR due to logistics automation. Semi-autonomous propulsion dominates, accounting for 82% of units, as fully autonomous vehicles remain restricted to geofenced areas. The Robotaxi Market is projected to reach $45 billion by 2030, led by Waymo and Baidu Apollo.
Margin and Pricing Pressures
Hardware gross margins for Level 2 systems range from 18% to 25%, down from 30% in 2020. Software and over-the-air updates carry 60% to 75% margins, prompting OEMs to shift revenue models. General Motors' Super Cruise and Ford's BlueCruise offer subscription tiers at $25 to $45 per month. Connected Vehicle Market services, including real-time traffic and hazard alerts, add $8 to $12 per vehicle per month in data revenue.
Falling sensor and compute costs; LiDAR below $1,000
High
Short term
Driver
Regulatory approvals for Level 3 in EU, China, and US states
High
Short term
Driver
Consumer willingness to pay for ADAS features
Medium
Short term
Driver
Logistics automation demand for autonomous trucking
High
Long term
Restraint
High development costs and long validation cycles
High
Long term
Restraint
Cybersecurity and liability concerns
Medium
Short term
Restraint
Fragmented global regulations
High
Long term
Restraint
Limited charging and edge-compute infrastructure
Medium
Long term
Quantitative evaluation shows that every 10% reduction in LiDAR cost correlates with a 6% increase in Level 3 adoption in premium vehicles. Regulatory developments are decisive: Germany's StVG amendment allows Level 4 in defined operational areas, while California's DMV issued permits for driverless testing to 10 companies by 2024. These catalysts unlock insurance and liability frameworks.
On the restraint side, development costs for a full autonomous platform exceed $1 billion for an OEM, with validation requiring 10 billion simulated miles and 100 million real-world miles. Cybersecurity risks grow with vehicle connectivity; a single vulnerability could recall millions of units. The Automotive Semiconductor Market remains concentrated, with advanced nodes below 7nm dominated by TSMC. Any geopolitical disruption in Taiwan could halt production for 3 to 6 months.
Tesla, Inc.: Deploys vision-only Full Self-Driving with over 1.5 billion miles of fleet data. Its Robotaxi Market ambitions include a dedicated vehicle platform.
Volkswagen AG: Partners with Mobileye and Bosch for Level 2+ systems across 10 million vehicles annually. Invests $2.6 billion in Cariad software unit.
Toyota Motor Corporation: Focuses on safety-first autonomy with Guardian and Chauffeur systems. Holds over 4,000 patents in autonomous driving.
General Motors: Super Cruise covers 400,000 miles of compatible roads in North America. Plans to expand to 22 models by 2026.
BMW AG: First to receive Level 3 certification in Germany and Nevada. Offers Personal Pilot for $6,000 on 7 Series.
AB Volvo: Runs autonomous hub-to-hub freight with Aurora and Waabi. Targets $1 billion in autonomous trucking revenue by 2030.
Ford Motor Company: BlueCruise ranks second in hands-free miles in the US. Partners with Argo AI legacy talent for commercial autonomy.
Strategic Milestones & Recent Developments in Autonomous Driving Technology Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2024 Q1
Tesla, Inc.
Launch
FSD v12 end-to-end neural network deployed to 400,000 vehicles
2024 Q2
Daimler AG
Partnership
Autonomous trucking pilot with Torc Robotics in Texas
2024 Q3
Volkswagen AG
Partnership
Expanded Mobileye deal for Level 2+ across MEB platform
2024 Q4
General Motors
Launch
Super Cruise expanded to 750,000 miles of roads
2025 Q1
BMW AG
Certification
Level 3 Personal Pilot approved in Nevada and California
2024 Q1: Tesla, Inc. released FSD v12, replacing rule-based code with a single neural network, improving intervention rates by 30%.
2024 Q2: Daimler AG and Torc Robotics began Level 4 autonomous freight runs between Dallas and Houston, targeting 500,000 miles annually.
2024 Q3: Volkswagen AG deepened its Mobileye collaboration, planning to equip 8 million vehicles with Level 2+ by 2027.
2024 Q4: General Motors extended Super Cruise coverage to 750,000 miles, increasing subscription revenue by 18% year over year.
2025 Q1: BMW AG received regulatory approval for Level 3 in two US states, enabling hands-off driving up to 60 km/h.
These moves signal a shift from prototype testing to commercial deployment. The Autonomous Vehicle Software Market sees consolidation as OEMs acquire startups for talent and IP. Connected Vehicle Market standards, such as C-V2X, gain traction in China and Europe.
Asia-Pacific is the fastest-growing region with a 22.5% CAGR, driven by China's target of 50% of new vehicles having Level 2+ by 2025 and Japan's robotaxi trials in Tokyo. North America remains the most mature market for Level 3 and robotaxi services, with Waymo operating over 700 vehicles in San Francisco and Phoenix. Europe follows with stringent safety regulations, but the EU's General Safety Regulation mandates Level 2 features on all new vehicles from July 2024.
LAMEA shows potential in autonomous trucking and mining, where closed environments bypass regulatory hurdles. Brazil and South Africa deploy Level 2 for agricultural machinery. The Middle East focuses on smart city corridors in Dubai and Riyadh, with Level 4 shuttles planned for 2026. South America lags due to infrastructure gaps but offers growth in commercial vehicle autonomy for mining and ports.
Supply Chain & Raw Material Dynamics: Autonomous Driving Technology Market
Upstream dependencies include semiconductors, sensors, and rare earth materials. The Automotive Semiconductor Market relies on TSMC for 7nm and 5nm chips, with NVIDIA and Qualcomm designing autonomous driving platforms. A single advanced chip requires over 1,000 process steps and 12 to 16 weeks of fabrication. Supply disruptions from 2021 to 2023 caused OEMs to lose $210 billion in revenue, prompting buffer inventories.
LiDAR modules depend on gallium nitride and indium phosphide, with prices declining 12% annually since 2020. High Definition Mapping Market requires continuous data from fleet vehicles, creating recurring costs of $5 to $15 per vehicle per year. Camera and radar sensors rely on CMOS image sensors and 77 GHz radar chips, dominated by Sony, ON Semiconductor, and Infineon. Rare earth magnets for electric motors in autonomous EVs face price volatility; neodymium prices rose 45% in 2022 before stabilizing.
Supply chain risks include geopolitical tension over Taiwan, export controls on advanced chips, and single-source dependencies for LiDAR lasers. OEMs are diversifying with dual sourcing and regional assembly. AB Volvo and Daimler AG have qualified secondary suppliers for autonomous trucking compute. However, advanced AI chips remain constrained; NVIDIA's DRIVE Orin allocation is prioritized for 2026 model year launches.
Technology Innovation & R&D Trajectory in Autonomous Driving Technology Market
Three disruptive technologies reshape the market: end-to-end neural networks, 4D imaging radar, and vehicle-to-everything (V2X) communication. End-to-end systems, pioneered by Tesla, Inc., replace modular perception-planning stacks with a single neural network trained on 1.5 billion miles. Adoption timeline: 2025-2027 for consumer vehicles, reducing software development costs by 40%. Patents in end-to-end driving grew 65% year over year in 2024.
4D imaging radar provides 300-meter range and elevation data at $50 to $100 per unit, threatening LiDAR in Level 2 and Level 3. Automotive suppliers like Continental and Bosch plan mass production by 2026. The LiDAR Market responds with solid-state designs below $500, targeting Level 4 robotaxis. Connected Vehicle Market V2X deployments in China and Europe enable cooperative perception, improving safety by 25% in intersection scenarios.
R&D investment levels are high: Volkswagen AG allocates $2.6 billion annually to Cariad, while General Motors spends $1.5 billion on autonomous software. Patent trends show Toyota Motor Corporation leading with 4,000+ filings, followed by Ford and BMW. Emerging tech reinforces incumbents with data scale but threatens Tier-1 hardware suppliers reliant on legacy radar. The Autonomous Trucking Market will benefit from platooning V2X, while Robotaxi Market operators integrate 4D radar for cost reduction.
Autonomous Driving Technology Market Segmentation
1. Level of Automation
1.1. Level 1
1.2. Level 2
1.3. Level 3
1.4. Level 4
1.5. Level 5
2. Application
2.1. Civil
2.2. Defense
2.3. Transportation Logistics
2.4. Construction
3. Propulsion Type
3.1. Semi-autonomous
3.2. Fully Autonomous
4. Vehicle Type
4.1. Passenger Car
4.2. Commercial Vehicle
Autonomous Driving Technology Market Segmentation By Geography
Table 58: Rest of Asia Pacific Autonomous Driving Technology Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of all data in this report is derived from primary research, including structured interviews, expert calls, and paid surveys conducted with decision-makers across the autonomous driving value chain.
We interview 4–5 company types: autonomous driving compute platform designers (NVIDIA DRIVE, Qualcomm Snapdragon Ride); Tier-1 ADAS sensor integrators (Bosch, Continental, Aptiv); automotive-grade LiDAR and radar manufacturers (Luminar, Innoviz, Infineon); high-definition mapping and localization providers (HERE, TomTom, Google); and autonomous trucking fleet software vendors (Aurora, Torc Robotics, Waymo Via).
Stakeholder job titles include VP of Autonomous Driving Programs; ADAS Product Line Director; Chief Safety and Validation Officer; Procurement Director for Automotive Semiconductors; and Fleet Operations Director for Autonomous Trucking.
Every report is updated to the date of purchase, ensuring the latest quarterly filings and regulatory changes are reflected.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation across automation levels, applications, propulsion types, vehicle types, and regions.
Bottom-up quantitative metrics include: number of new vehicles equipped with Level 2+ systems per year; average sensor content per vehicle (camera, radar, LiDAR count); average selling price of LiDAR and 4D radar units; miles driven by robotaxi and autonomous trucking fleets; and annual R&D spend per OEM on autonomous driving software.
Top-down sizing uses global vehicle production forecasts, regulatory adoption timelines, and attach-rate curves for ADAS packages. Cross-checks against supplier order books and semiconductor shipment data reduce variance.
Data Accuracy & Quality Check
All estimates pass a multi-stage validation: source triangulation, historical back-testing, and expert review by senior analysts.
Guaranteed estimated data accuracy level of 85–90% for market sizes and CAGR projections.
Discrepancies above 10% trigger re-interview or alternate source verification. Final numbers are reconciled with public regulatory targets and OEM production plans.
Report updated to date of purchase; any post-publication material events are flagged in the client portal.
Frequently Asked Questions
1. How are consumer preferences shifting in the Autonomous Driving Technology Market?
Buyers increasingly pay for advanced driver assistance systems rather than full autonomy, with surveys showing 62% of new car buyers in the United States want Level 2 features. Tesla and General Motors report higher take rates for hands-on highway assist packages. Insurers also reward vehicles with automatic emergency braking, influencing purchase decisions.
2. What pricing trends are shaping the Autonomous Driving Technology Market?
Sensor and compute costs are falling; LiDAR units that cost $10,000 in 2018 now sell below $1,000 at volume. Software subscription prices range from $99 to $199 per month for premium autonomy packages. Overall vehicle sticker prices rise 3% to 7% when Level 2+ hardware is standard.
3. Which funding and investment trends define the Autonomous Driving Technology Market?
Venture capital and corporate investors deployed over $12 billion into autonomous driving startups in 2024, led by robotaxi and autonomous trucking firms. Waymo, Cruise, and Aurora secured large rounds, while automotive OEMs committed $5 billion to in-house software. SPAC activity cooled, shifting capital to strategic partnerships.
4. What are the main segments and applications in the Autonomous Driving Technology Market?
The market splits by automation level, application, propulsion type, and vehicle type. Passenger cars represent 68% of 2025 revenue, while commercial vehicles show faster growth in autonomous trucking. Defense and construction applications remain niche but adopt Level 4 systems for closed environments.
5. What is the current size and projected CAGR of the Autonomous Driving Technology Market through 2033?
The market is valued at $86.3 billion in 2025 and is projected to reach $376.1 billion by 2033, expanding at a 20.2% CAGR. Asia-Pacific contributes the largest regional share at 36%, followed by North America at 30%. Level 2 systems generate the largest revenue today, but Level 4 grows fastest.
6. Which end-user industries drive downstream demand in the Autonomous Driving Technology Market?
Automotive OEMs, logistics fleets, defense agencies, and construction equipment makers constitute primary end users. Transportation logistics accounts for 31% of commercial demand, with autonomous trucking pilots by AB Volvo and Daimler AG. Ride-hailing operators and public transit agencies also test robotaxi deployments.