Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Lecture Capture Solutions Market: 12.6% CAGR to 2033?
Lecture Capture Solutions Market
Lecture Capture Solutions Market: 12.6% CAGR to 2033?
Lecture Capture Solutions Market by Product (Software, Hardware), by End User (Academic, Corporate, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
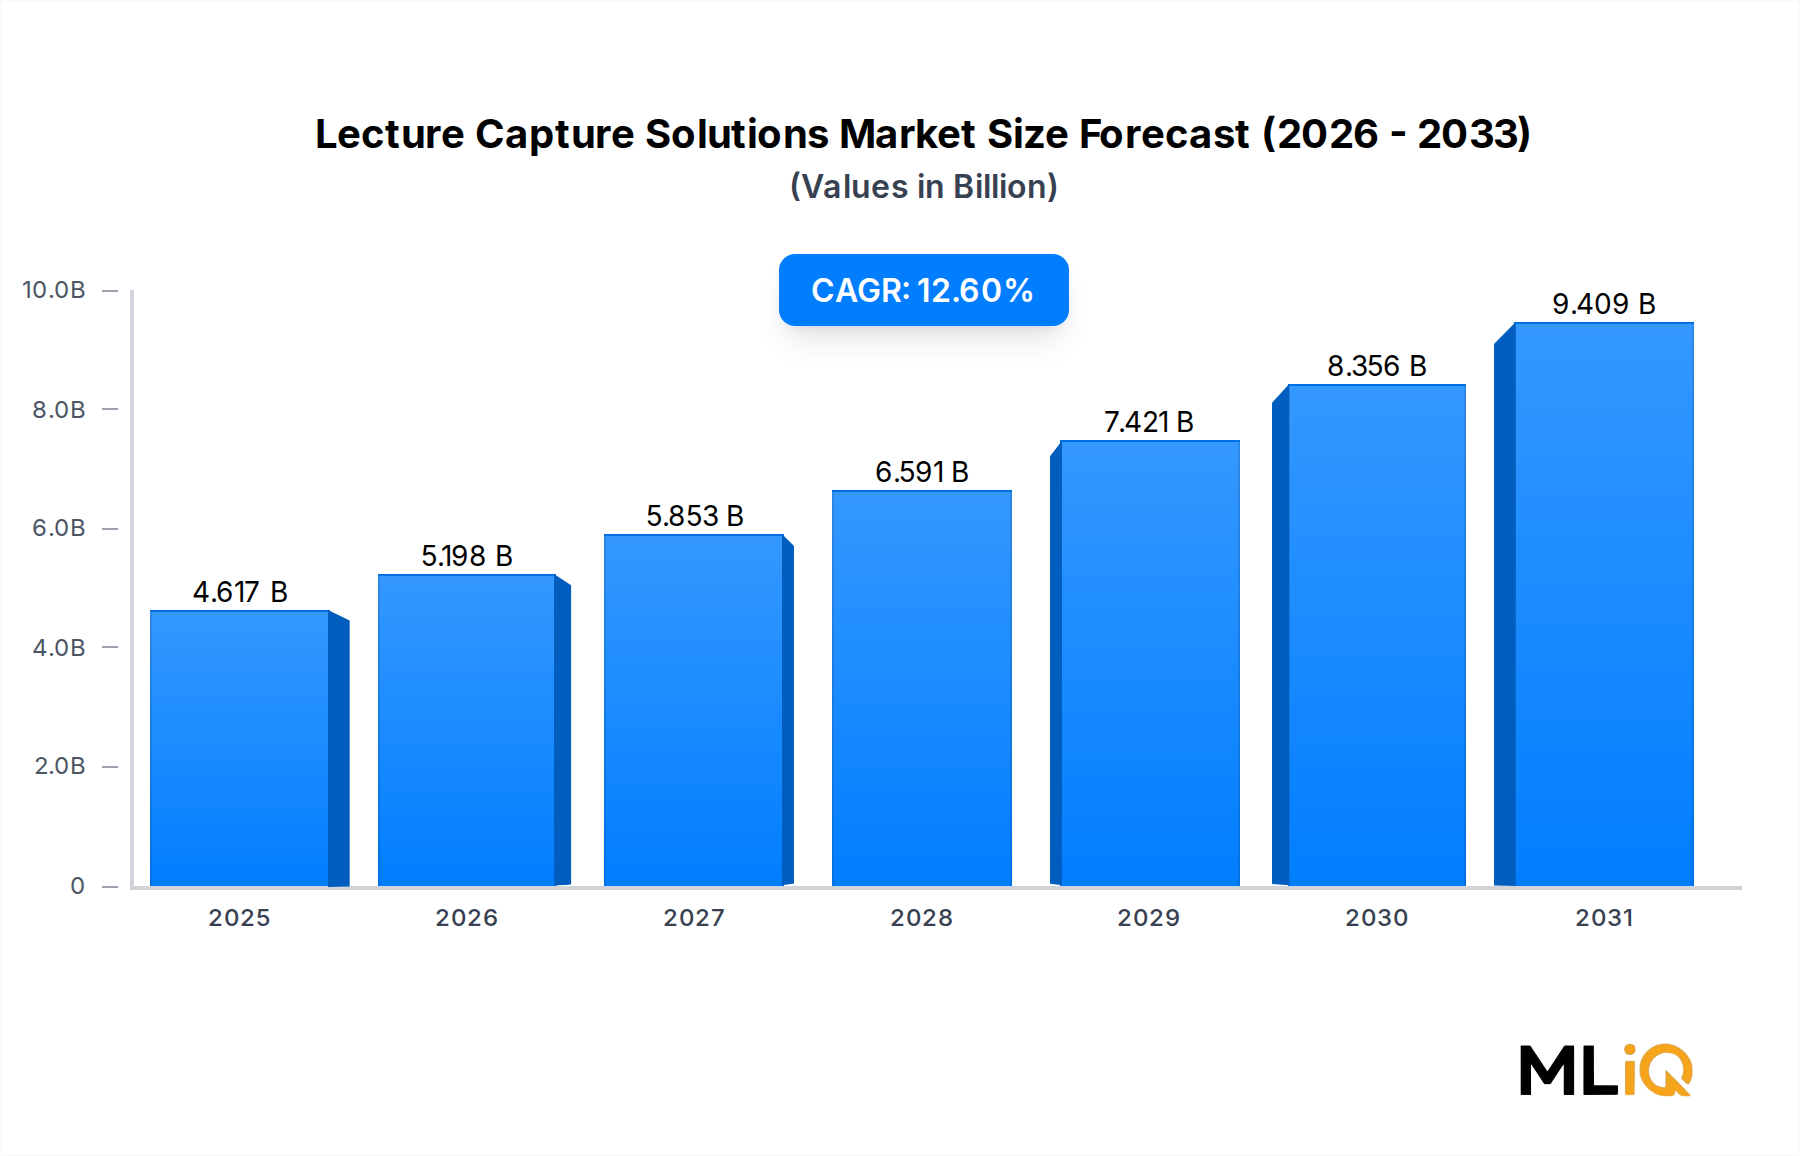
The Lecture Capture Solutions Market is undergoing a structural expansion, driven by the permanent shift to hybrid and HyFlex learning models. In 2024, the market stood at $4.1 billion and is forecast to reach $11.9 billion by 2033, representing a 12.6% CAGR. This growth is not linear; it is concentrated in software and cloud delivery, where the Lecture Capture Software Market alone accounts for 62% of product revenue. Academic institutions remain the largest buyer cohort at 48% of total demand, but corporate training is rising at 11.8% annually as enterprises digitize compliance and onboarding.
Lecture Capture Solutions Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
4.617 B
2025
5.198 B
2026
5.853 B
2027
6.591 B
2028
7.421 B
2029
8.356 B
2030
9.409 B
2031
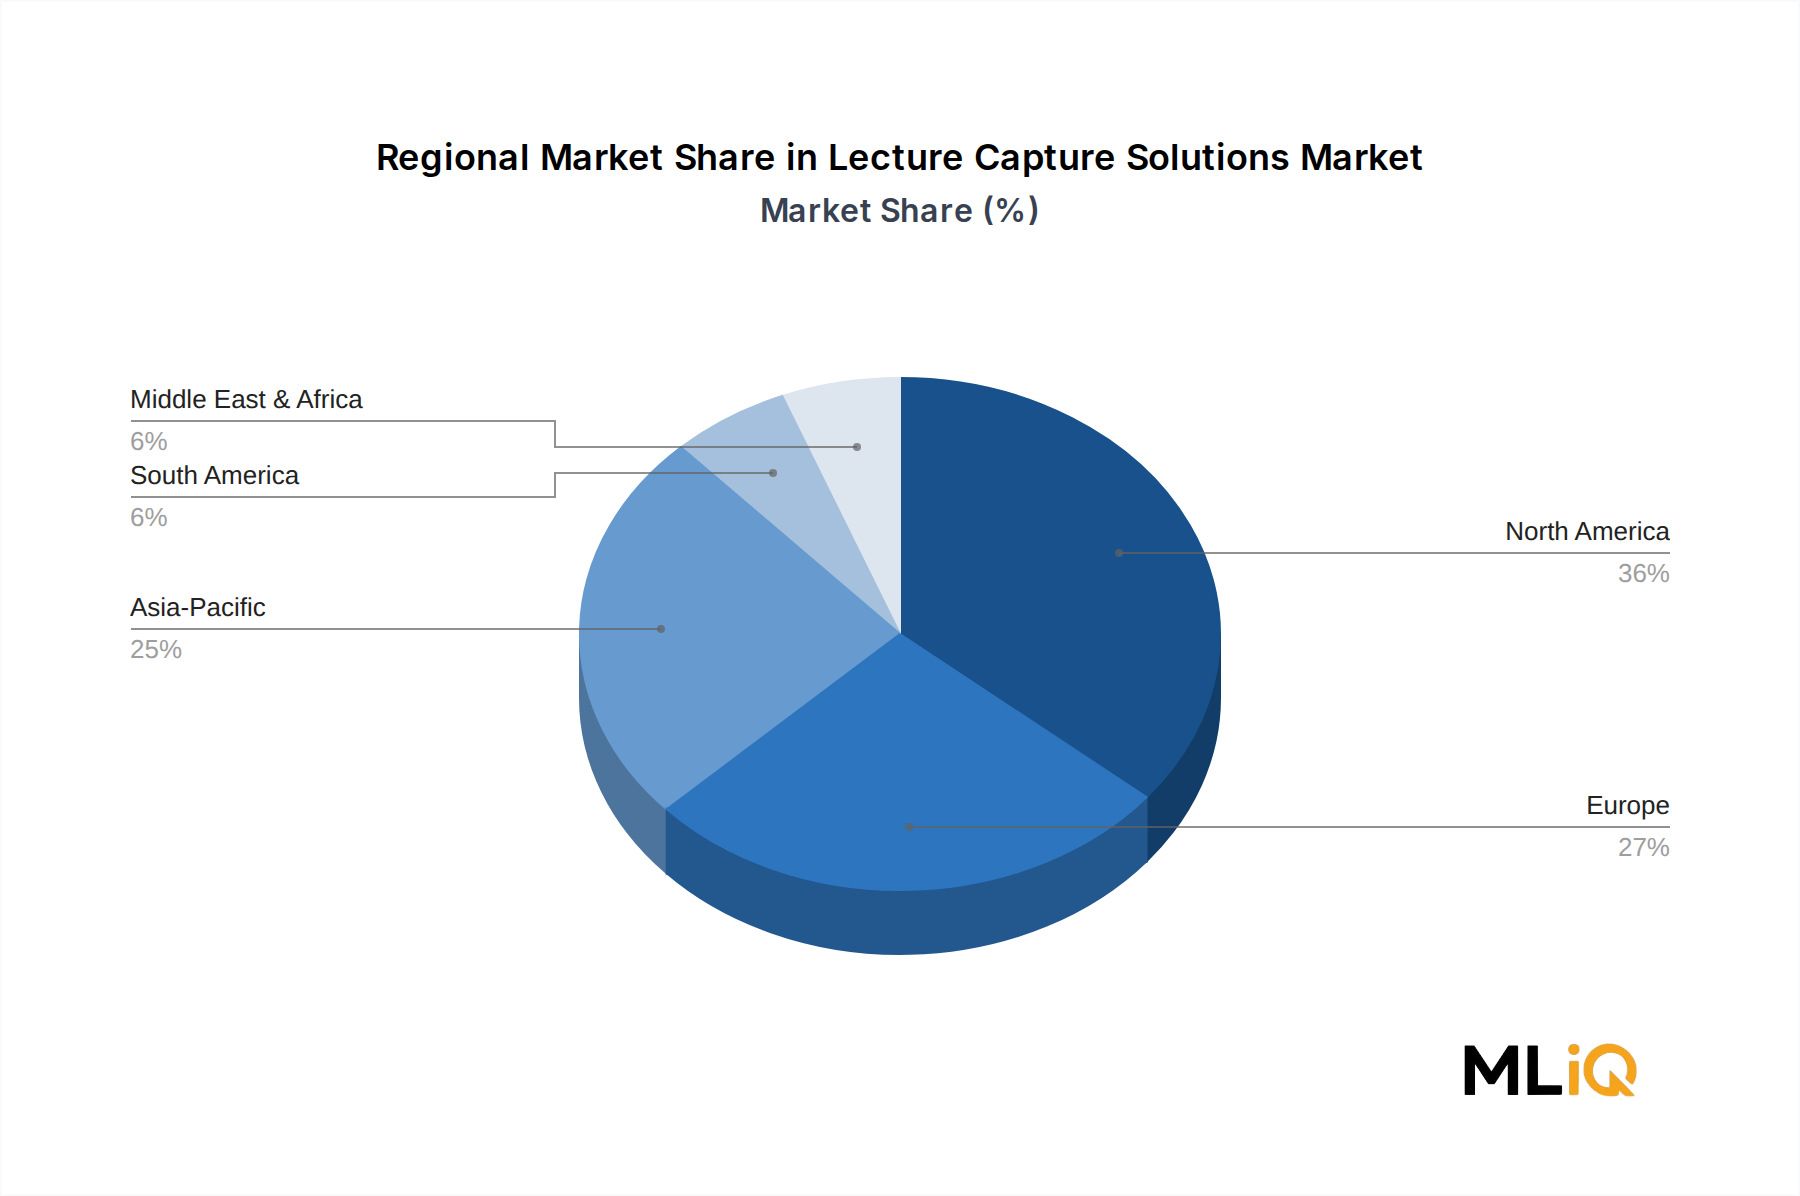
North America retains a 36% revenue share, supported by 4,000+ higher education institutions and federal distance education funding. Europe follows at 27%, propelled by the EU Digital Education Action Plan, while Asia-Pacific is the fastest-growing region at 15.2% CAGR. The Enterprise Video Platform Market is converging with lecture capture, as vendors like Kaltura and Panopto embed AI search, auto-captioning, and analytics into broader video ecosystems. This convergence expands the addressable market beyond classrooms into corporate and government training.
Three macro forces explain the momentum. First, the Higher Education Lecture Capture Market benefits from accreditation requirements for recorded instruction and accessibility mandates. Second, the Distance Learning Market has normalized asynchronous video consumption, with 78% of students now expecting on-demand lecture access. Third, AI-driven indexing reduces video review time by up to 40%, directly improving learning outcomes and operational efficiency.
However, growth is tempered by privacy regulation, integration complexity, and hardware refresh cycles. Vendors that offer open APIs, FERPA/GDPR-compliant cloud storage, and AI-powered search will capture disproportionate value. The next competitive battleground is not capture itself but intelligent retrieval and analytics across the entire video estate.
Segment Deep-Dive: Academic End-User Dominance in Lecture Capture Solutions Market
Segment Analysis Matrix
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Academic End-User
13.1%
48%
Hybrid and HyFlex course delivery mandates
Software Product
14.2%
62% of product revenue
AI transcription and automated indexing
Corporate End-User
11.8%
34%
Remote workforce training and compliance
The academic end-user segment is the revenue engine of the Lecture Capture Solutions Market, generating 48% of global demand in 2024. Universities and colleges are standardizing on capture platforms to support HyFlex instruction, where students attend either in person or remotely. This shift is not temporary; 68% of higher education institutions have made lecture capture a line item in their permanent IT budgets. The Higher Education Lecture Capture Market is also being reshaped by LMS integration—Canvas, Blackboard, and Moodle now require native video tools, pushing vendors toward API-first architectures.
Software vs. Hardware Dynamics
Software is the dominant product sub-segment, representing 62% of product revenue and growing at 14.2% CAGR. The Lecture Capture Software Market benefits from recurring subscription models, cloud scalability, and AI features such as automated transcription, speaker diarization, and searchable indexes. Margins for pure software vendors range from 70–80% gross, compared to 25–35% for hardware-centric offerings. The Lecture Capture Hardware Market, including cameras, capture appliances, and encoders, faces commoditization and longer refresh cycles. However, demand persists for 4K multi-camera systems and intelligent tracking cameras, especially in large lecture halls.
Cloud infrastructure is a critical enabler. The Cloud Video Storage Market is expanding in tandem with capture adoption, as institutions store petabytes of lecture video for compliance and review. Storage costs have fallen to $0.02–$0.05 per GB per month, but egress and transcoding fees remain margin pressures. The Corporate Training Lecture Capture Market is smaller at 34% share but offers higher average revenue per user due to compliance training, onboarding, and certification videos. Corporate buyers demand SSO, SCORM compliance, and analytics on learner engagement.
Margin Pressures and Strategic Implications
Hardware vendors face 15–20% annual price erosion on basic capture devices, forcing consolidation and a pivot to software bundles. Software vendors confront rising cloud costs and AI compute expenses, but they can offset these through tiered pricing and analytics add-ons. The key strategic takeaway is that end-user loyalty is tied to ecosystem integration, not capture quality alone. Vendors that offer seamless LMS, CRM, and HRIS connectors will sustain pricing power.
The most powerful driver is the institutionalization of hybrid learning. Over 4,000 U.S. colleges now offer HyFlex courses, and lecture capture is the primary tool for asynchronous access. This is reinforced by the AI Video Indexing Market, where automated speech-to-text and visual search cut review time by 40% and boost content reuse. Corporate demand adds another layer: global e-learning spend is projected to exceed $400 billion by 2028, with video accounting for 60% of that spend. The Distance Learning Market similarly normalizes on-demand video, creating a permanent baseline for capture solutions.
Bottlenecks and Compliance Costs
On the restraint side, hardware and integration costs remain a barrier for smaller institutions. A typical 50-room deployment can cost $500,000–$1.2 million, including cameras, encoders, wiring, and installation. Privacy regulation is a more persistent constraint. FERPA in the U.S. and GDPR in Europe require explicit consent, data residency, and deletion policies. Compliance adds 10–15% to vendor operating costs and slows sales cycles by 2–3 months. Cloud storage cost variability also pressures margins, especially for vendors that bundle unlimited storage.
Net Impact Assessment
Drivers outweigh restraints through 2033, but the margin structure will favor software and services. The Enterprise Video Platform Market is absorbing standalone capture tools, meaning vendors must either scale into platforms or specialize in vertical compliance. Restraints are manageable with modular pricing, hybrid cloud architectures, and automated compliance tooling. The strategic imperative is to convert capture data into searchable, analytics-rich learning objects.
Echo360: A leader in the Lecture Capture Software Market with strong LMS integrations and analytics. Its platform serves over 1,000 institutions and emphasizes student engagement data.
Panopto: Combines video capture with AI-powered search and accessibility features. It holds a significant share of the Higher Education Lecture Capture Market and expands into corporate learning.
Kaltura: Provides an open-source Enterprise Video Platform Market solution with modular capture, hosting, and analytics. Its flexibility appeals to large universities and media companies.
Cisco Systems: Leverages Webex and collaboration hardware to enter lecture capture, targeting corporate training and hybrid classrooms. Its strength is network integration and security.
Crestron Electronics: Dominates AV control and hardware, including intelligent cameras and room systems. It competes in the Lecture Capture Hardware Market through bundled room solutions.
Sonic Foundry: Offers Mediasite capture appliances and cloud services, with a niche focus on higher education and healthcare training. Its installed base provides recurring revenue.
Epiphan Systems: Specializes in live streaming and capture hardware, including 4K appliances. It serves enterprise and education customers needing reliable encoding.
HaiVision Systems: Focuses on video encoding and streaming for broadcast and education. Its low-latency solutions are used in distance learning and telepresence.
Strategic Milestones & Recent Developments in Lecture Capture Solutions Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2021
Kaltura
IPO
Raised $150M for cloud R&D
2021
Panopto
M&A
Acquired by K1 Investment Management
2022
Echo360
Launch
AI-powered transcription engine
2023
Cisco Systems
Partnership
Webex integration with Canvas LMS
2023
Crestron Electronics
Launch
1 Beyond intelligent camera systems
2024
Epiphan Systems
Launch
4K capture appliance for hybrid classrooms
2021 – Kaltura IPO: Raised approximately $150 million, accelerating cloud infrastructure and AI video indexing capabilities. This strengthened the Enterprise Video Platform Market and intensified competition with Panopto and Echo360.
2021 – Panopto acquired by K1 Investment Management: The deal consolidated Panopto’s position in the Higher Education Lecture Capture Market, providing capital for AI search and analytics expansion.
2022 – Echo360 launches AI transcription engine: Reduced manual captioning costs by 30% and improved accessibility compliance for universities.
2023 – Cisco partners with Canvas LMS: Embedded Webex capture directly into the LMS, targeting corporate and higher education hybrid classrooms.
2023 – Crestron launches 1 Beyond cameras: Introduced intelligent tracking cameras for large lecture halls, addressing the Lecture Capture Hardware Market demand for automated production.
2024 – Epiphan launches 4K capture appliance: Focused on reliable, high-resolution capture for hybrid classrooms, supporting the Cloud Video Storage Market with direct-to-cloud uploads.
North America remains the largest market at $1.48 billion in 2024, with 36% global share. Growth is driven by replacement cycles, AI upgrades, and federal distance education rules. The region’s maturity means slower unit growth but higher software attach rates. The Corporate Training Lecture Capture Market is expanding as U.S. enterprises adopt video for compliance and onboarding.
Europe: Regulation as a Catalyst
The European market is valued at $1.11 billion and grows at 12.4% CAGR. The EU Digital Education Action Plan and GDPR create a compliance-driven demand for secure, on-premise or EU-hosted capture solutions. The Higher Education Lecture Capture Market in Germany, France, and the UK is modernizing aging AV infrastructure.
Asia-Pacific: Fastest-Growing Corridor
Asia-Pacific is the fastest-growing region at 15.2% CAGR, reaching $1.03 billion in 2024. China and India are investing in smart classrooms and digital universities. The Distance Learning Market is expanding rapidly due to mobile-first consumption and government initiatives. Local vendors compete on price, but international platforms lead on AI features.
LAMEA: Mobile-First Leapfrog
LAMEA represents $0.49 billion and grows at 13.5% CAGR. Brazil, Mexico, and GCC countries are deploying cloud-based capture to bypass legacy hardware. Regulatory stringency is lower, but data sovereignty rules in some countries require local hosting. The region offers high growth with lower average revenue per user.
Hardware components dominate cross-border trade in this market, particularly cameras, encoders, and servers. The Video Encoding Chip Market is concentrated in Taiwan, South Korea, and the United States, with export controls affecting high-performance chips. Tariffs under Section 301 on Chinese-made AV equipment add 10–25% to U.S. import costs, pushing vendors to relocate assembly to Vietnam or Mexico. Non-tariff barriers include CE marking in Europe, FCC certification in the U.S., and China’s CCC requirements. These compliance costs add 5–8% to landed hardware prices. Software and cloud services are less affected by tariffs but face data localization rules that can require in-country data centers, increasing operating costs by 15–20% for global platforms.
Regulation is a defining force in the Lecture Capture Solutions Market. In the U.S., FERPA governs student education records, requiring vendors to implement access controls and audit trails. HIPAA applies when capture is used in medical training. The EU’s GDPR imposes consent, data minimization, and breach notification rules, with fines up to 4% of global revenue. The EU AI Act adds transparency requirements for automated transcription and indexing, likely increasing compliance costs by 10–15% for AI-heavy platforms. In Asia-Pacific, China’s PIPL mandates local storage of personal data, affecting the Enterprise Video Platform Market and forcing international vendors to partner with local cloud providers. Accessibility standards such as WCAG 2.2 and Section 508 require captions, transcripts, and keyboard navigation, which often become product differentiators. The Distance Learning Market benefits from these rules because they standardize video accessibility across borders. Overall, compliance is shifting from a cost center to a competitive moat for vendors that invest in privacy-by-design and universal design.
Lecture Capture Solutions Market Segmentation
1. Product
1.1. Software
1.2. Hardware
2. End User
2.1. Academic
2.2. Corporate
2.3. Others
Lecture Capture Solutions Market Segmentation By Geography
Table 46: Rest of Asia Pacific Lecture Capture Solutions Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of our data collection, ensuring granular validation of the Lecture Capture Solutions Market. We conduct structured interviews, surveys, and expert consultations with stakeholders across the value chain.
Company types interviewed (4–5 specific): lecture capture software platform developers; AV hardware OEMs (cameras, encoders, capture appliances); cloud video storage and CDN providers; AI video indexing algorithm vendors; and higher education AV systems integrators.
Stakeholder job titles (3–4 specific): University Chief Information Officer; Director of Academic Technology; Corporate Learning & Development Manager; AV Procurement Manager; and Cloud Solutions Architect.
Guaranteed data accuracy level: 85–90%, achieved through multi-level data triangulation and cross-validation of primary responses against secondary benchmarks.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
University Chief Information Officer
25%
Director of Academic Technology
25%
Corporate Learning & Development Manager
20%
AV Procurement Manager
20%
Cloud Solutions Architect
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Lecture Capture Software Developers
35%
AV Hardware OEMs
25%
Cloud Service Providers
15%
System Integrators
15%
Academic Institutions
10%
Secondary Research & Industry Benchmarking
Secondary research accounts for 20–30% of our methodology, focusing on financial filings, regulatory documents, and trade publications.
Every report is updated to the date of purchase, ensuring all market data, vendor developments, and regulatory changes reflect the latest available information.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are used simultaneously and validated via multi-level data triangulation. Bottom-up models build from institutional adoption and pricing; top-down models size from total education and training video spend.
Specific quantitative metrics in the bottom-up calculation (3–4): number of higher education institutions globally (approximately 45,000); average lecture capture software license cost per student ($8–$15 per year); classroom AV penetration rate (32% of tier-1 universities); and cloud storage cost per GB per year ($0.24–$0.60).
Demand modeling incorporates segment-level adoption curves for software, hardware, academic, corporate, and other end users, with regional calibration for North America, Europe, Asia-Pacific, South America, and Middle East & Africa.
Forecast period 2026–2034 extends the base year 2025, with CAGR projections validated against historical adoption patterns and technology replacement cycles.
Data Accuracy & Quality Check
All primary data is verified through multi-level triangulation, comparing interview responses with transaction data, pricing databases, and regulatory filings.
Guaranteed accuracy level of 85–90% is maintained through outlier detection, cross-source reconciliation, and expert panel review.
Quality control includes 100% response validation, duplicate elimination, and consistency checks across regional and segment-level estimates.
Final market sizing is reviewed by senior analysts and benchmarked against public company revenues, trade association reports, and government education statistics.
Report updates are guaranteed to the date of purchase, with version control and change logs for all revised figures.
Frequently Asked Questions
1. How high are barriers to entry in the Lecture Capture Solutions Market?
Barriers are moderate-to-high due to integration with LMS platforms, data privacy compliance, and high R&D for AI indexing. Established vendors like Echo360 and Panopto hold 40%+ combined share in higher education, creating network effects. New entrants face average customer acquisition costs exceeding $50,000 per university.
2. Which region dominates the Lecture Capture Solutions Market and why?
North America holds about 36% of global revenue, driven by 4,000+ higher education institutions and federal funding for hybrid learning. The U.S. Department of Education’s Title IV distance education rules accelerate adoption. High broadband penetration and established AV integrators further entrench its leadership.
3. What sustainability and ESG factors affect the Lecture Capture Solutions Market?
Cloud-based capture reduces campus travel and physical media, lowering carbon footprint by up to 30% compared to on-premise hardware. Vendors face pressure to use energy-efficient encoders and recyclable AV components. ESG reporting now influences 25% of enterprise procurement decisions for video platforms.
4. Which end-user industries drive demand in the Lecture Capture Solutions Market?
Academic institutions represent 48% of revenue, followed by corporate training at 34%, as remote workforce compliance requires searchable video libraries. Healthcare and government agencies are emerging end users with high security needs. Downstream demand correlates with e-learning spend, projected to reach $400 billion globally by 2028.
5. How does the regulatory environment impact the Lecture Capture Solutions Market?
FERPA in the U.S. and GDPR in Europe impose strict student data privacy and consent requirements, raising compliance costs by 10–15% for vendors. The EU AI Act adds transparency obligations for automated indexing and captioning. Non-compliance can result in fines up to 4% of global revenue.
6. What is the current size and projected CAGR of the Lecture Capture Solutions Market?
The market was valued at $4.1 billion in 2024 and is projected to reach $11.9 billion by 2033, growing at a 12.6% CAGR. Software captures 62% of product revenue, while academic end users account for 48% of total demand. Hybrid learning and AI video indexing are the primary growth accelerators.