Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Cloud Security Posture Management Market: 14.5% CAGR to 2033
Cloud Security Posture Management Market
Cloud Security Posture Management Market: 14.5% CAGR to 2033
Cloud Security Posture Management Market by Offering (Solution, Service), by Cloud Service Model (Infrastructure-as-a-Service (IaaS), by Platform-as-a-Service (PaaS), by Software-as-a-Service (IaaS), by Enterprise Size (Large Enterprises, SMEs), by Industry Vertical (BFSI, Government & Defense, Retail & E-commerce, Healthcare, IT & Telecom, Energy & Utilities, Manufacturing, Education, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 325
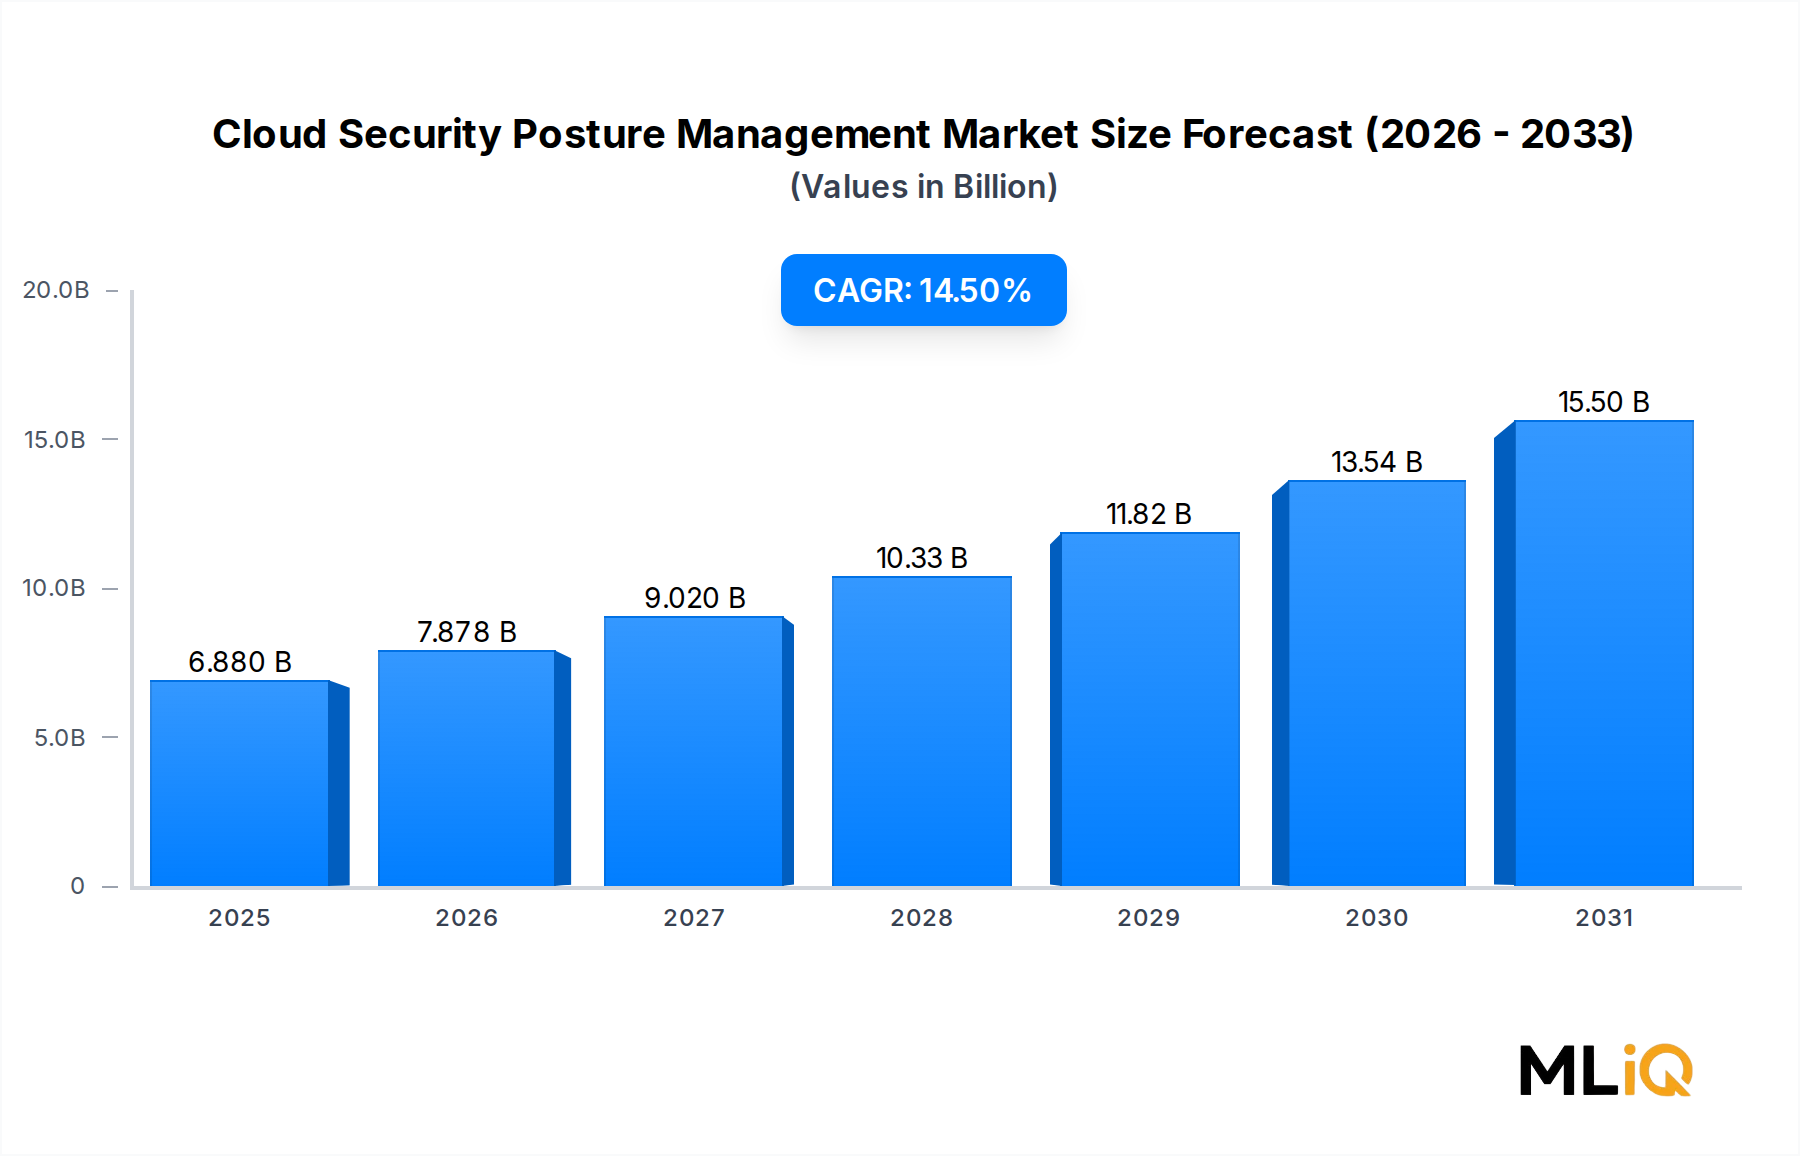
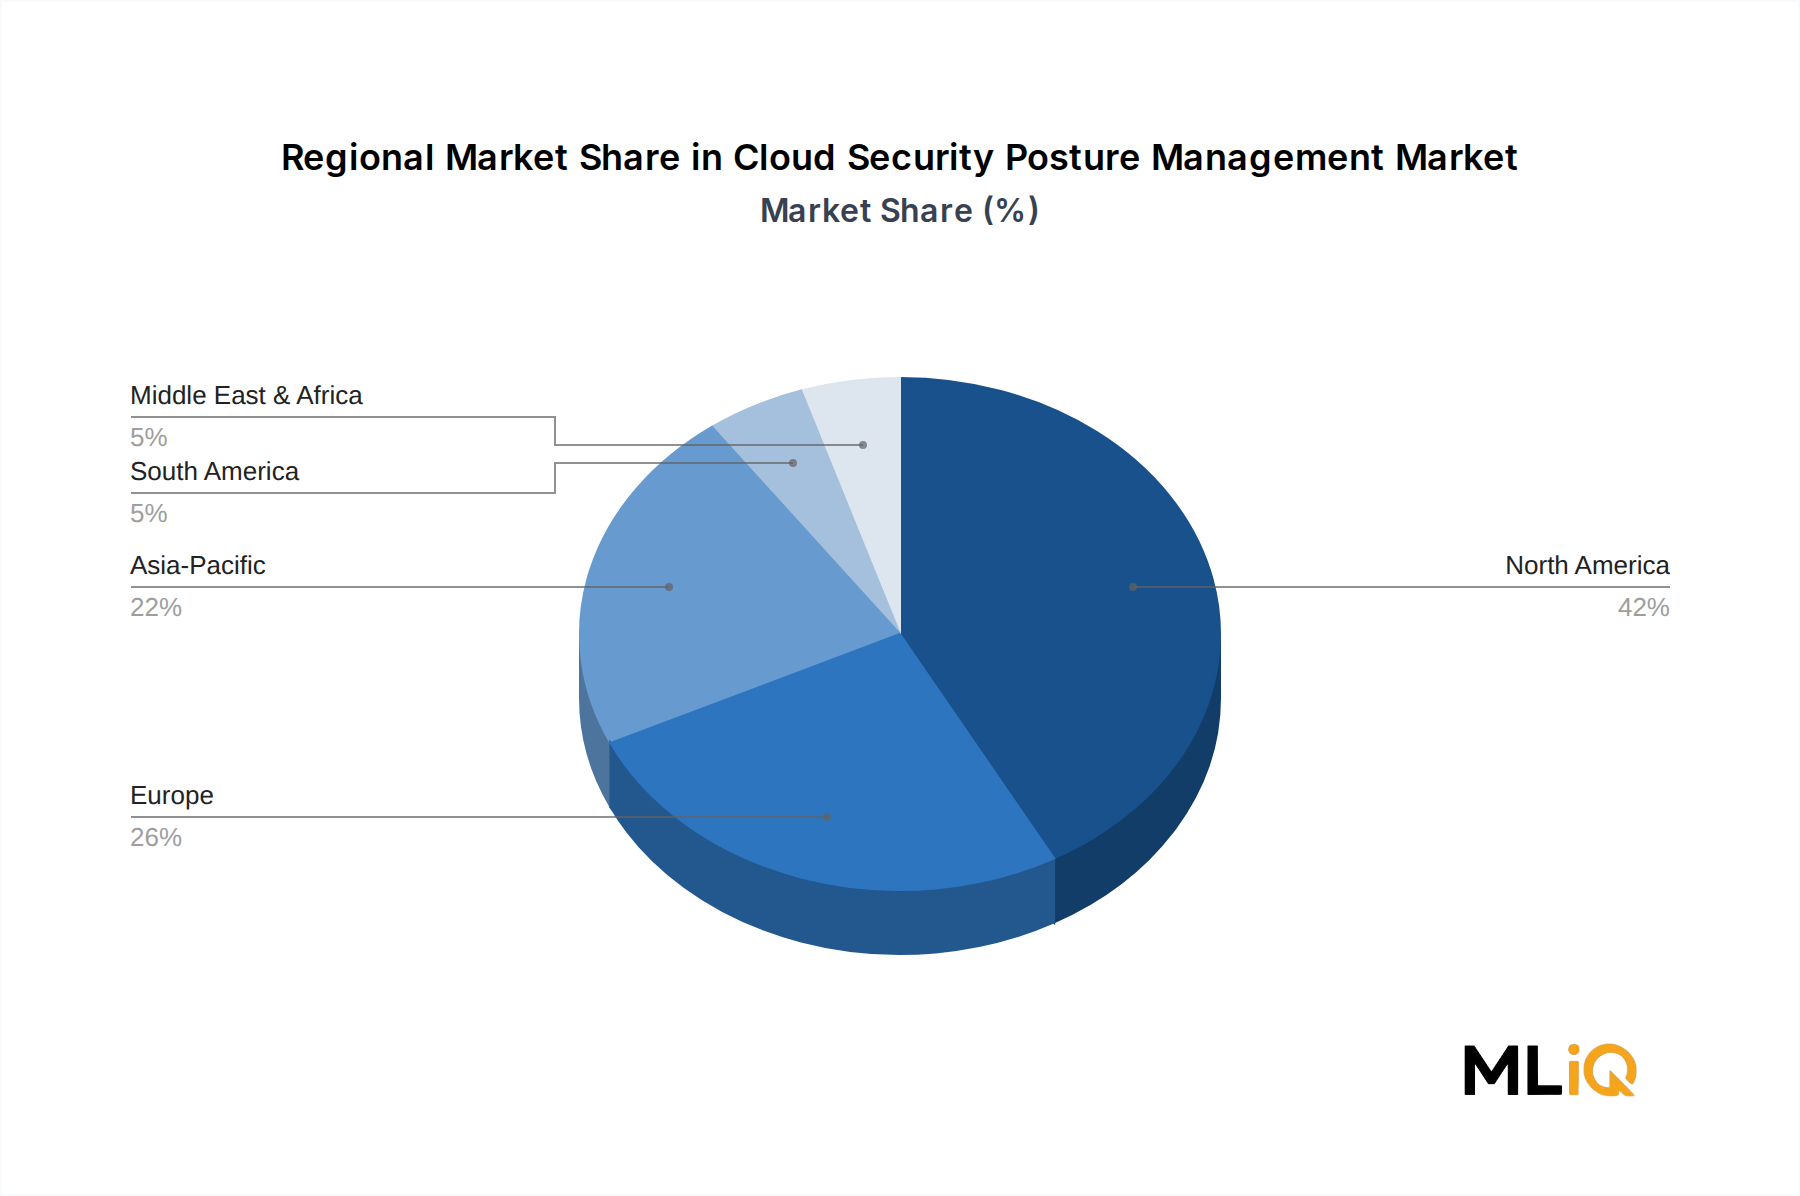
The Cloud Security Posture Management Market is poised for significant expansion, driven by escalating cloud adoption and stringent regulatory requirements. The market, valued at $6.88 billion in 2025, is projected to reach $20.3 billion by 2033, registering a CAGR of 14.5%. This growth is underpinned by the increasing complexity of multi-cloud environments and the rising frequency of cloud misconfigurations, which expose enterprises to data breaches and compliance penalties. North America currently dominates the market, accounting for 42% of global revenue, attributed to early cloud adoption and robust regulatory frameworks such as FedRAMP and CCPA. Europe follows closely, with 26% share, driven by GDPR enforcement and data sovereignty concerns. The Asia-Pacific region is expected to witness the fastest growth, propelled by rapid digital transformation and expanding cloud infrastructure investments. In terms of offerings, the Solution segment leads with 68% market share, as organizations prioritize continuous monitoring and automated remediation tools. The Cloud Security Posture Management Solutions Market is thus the primary revenue generator, while the CSPM Services Market provides essential support for deployment and management. Key trends include the integration of AI and machine learning for threat detection, the shift towards cloud-native application protection platforms, and the consolidation of security tools. However, challenges such as budget constraints and a shortage of skilled professionals may temper growth. Overall, the market presents lucrative opportunities for vendors that can deliver comprehensive, scalable, and compliant CSPM solutions.
Cloud Security Posture Management Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
6.880 B
2025
7.878 B
2026
9.020 B
2027
10.33 B
2028
11.82 B
2029
13.54 B
2030
15.50 B
2031
Segment Deep-Dive: Solution Dominance in Cloud Security Posture Management Market
Segment Analysis Matrix
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Solution
15.2%
68%
Need for continuous compliance monitoring
Service
12.8%
32%
Shortage of in-house cloud security expertise
The Solution segment is the dominant offering in the Cloud Security Posture Management Market, capturing 68% of global revenue in 2025. This segment encompasses software platforms that provide visibility, compliance monitoring, and threat detection across cloud environments. The sub-segment dynamics reveal that within Solutions, the IaaS Security Market is the largest, as infrastructure-as-a-service remains the most widely adopted cloud model. However, the SaaS Security Posture Management Market is growing rapidly, driven by the proliferation of SaaS applications in enterprises. The Cloud Security Posture Management Solutions Market benefits from high margins due to recurring subscription models, but faces pressure from intense competition and the need for continuous innovation.
Sub-Segment Dynamics
Cloud Service Model: IaaS accounts for 45% of solution revenue, followed by PaaS at 30% and SaaS at 25%. The IaaS Security Market is expected to maintain its lead, but SaaS is projected to grow at a 16.5% CAGR through 2033.
Enterprise Size: Large enterprises contribute 75% of solution revenue, while SMEs are increasingly adopting CSPM solutions, growing at a 15.8% CAGR as they migrate to the cloud.
Industry Vertical: BFSI leads with 25% share, followed by IT & Telecom and Government & Defense, each at 18%.
Margin Pressures
High R&D costs for AI-driven analytics and integration capabilities.
Pricing pressure from cloud-native providers embedding CSPM features into broader platforms.
Customer demand for flexible licensing models, including pay-as-you-go.
The Service segment, including consulting, integration, and managed services, is growing at a slower pace but remains critical for end-to-end security. The CSPM Services Market is driven by organizations lacking internal expertise, particularly SMEs. However, margin pressures in services are higher due to labor costs and customization demands. Overall, the Solution segment's dominance is expected to persist, with the Cloud Compliance Automation Market emerging as a key growth area within solutions.
Increasing frequency of cloud misconfigurations and breaches
High
Short term
Driver
Shift to multi-cloud and hybrid environments
Medium
Long term
Restraint
Budget constraints in SMEs
Medium
Short term
Restraint
Shortage of skilled cloud security professionals
High
Long term
Restraint
Complexity of integrating CSPM with existing tools
Medium
Short term
The market is propelled by the exponential growth in cloud adoption, with global cloud spending expected to exceed $1 trillion by 2026. This surge creates an urgent need for security posture management. Regulatory compliance is a major driver, as data protection laws impose hefty fines for non-compliance; for instance, GDPR fines reached €2.1 billion in 2023 alone. The Multi-Cloud Security Market is expanding as organizations use multiple cloud providers, increasing complexity and the need for unified visibility. Additionally, the rise in cloud misconfigurations, responsible for over 60% of cloud security incidents, fuels demand for CSPM tools. The Cloud Workload Protection Market is also benefiting, as CSPM integrates with workload security to provide holistic protection.
However, restraints impede faster growth. Budget limitations, especially among SMEs, restrict adoption of premium CSPM solutions. The cybersecurity workforce gap, with 3.5 million unfilled positions globally, hampers deployment and management. Integration challenges with existing security stacks can lead to longer sales cycles. Despite these restraints, the market is expected to grow robustly, with the Cloud Security Analytics Market gaining traction as organizations seek advanced analytics for threat detection and response.
Prisma Cloud platform with broad CSPM capabilities
Large enterprises, multi-cloud environments
Leader
CrowdStrike
Falcon Cloud Security with integrated threat intelligence
Enterprises, BFSI
Leader
Microsoft
Defender for Cloud, native integration with Azure
Microsoft-centric organizations
Leader
IBM
Security and Compliance Center, strong compliance automation
Regulated industries
Challenger
ZScaler
Zero trust exchange with CSPM module
Cloud-first enterprises
Challenger
Check Point
CloudGuard unified cloud security
Hybrid cloud environments
Challenger
Fortinet
FortiCNAPP, integrated with network security
SMB to large enterprises
Niche
Trend Micro
Cloud One, comprehensive cloud security
Diverse industries
Leader
Palo Alto Networks: Offers Prisma Cloud, a comprehensive CSPM solution with advanced threat detection and compliance capabilities. The company has strengthened its position through strategic acquisitions like Bridgecrew.
CrowdStrike: Falcon Cloud Security provides agentless CSPM and workload protection, leveraging its threat intelligence. CrowdStrike is a leader in the endpoint security market and is expanding into cloud security.
Microsoft: Defender for Cloud is natively integrated with Azure, providing CSPM for multi-cloud environments. Its vast customer base and continuous innovation make it a formidable player.
IBM: Security and Compliance Center offers robust compliance automation and is favored by regulated industries. IBM's focus on hybrid cloud and AI-driven security is a key differentiator.
ZScaler: Zscaler CSPM is part of its zero trust exchange, providing secure access and posture management. The company targets cloud-first enterprises seeking integrated security.
Check Point: CloudGuard provides unified cloud security across multi-cloud environments, with strong network security integration. Check Point is a challenger with a loyal customer base.
Fortinet: FortiCNAPP combines CSPM with cloud workload protection, leveraging Fortinet's network security expertise. It appeals to cost-conscious enterprises.
Trend Micro: Cloud One is a comprehensive platform with CSPM, workload security, and container security. Trend Micro is a leader in cloud security with a global presence.
The competitive landscape is intense, with vendors differentiating through integration, automation, and AI. The Cloud Infrastructure Entitlement Management Market is a key battleground, as vendors like Microsoft and Palo Alto Networks enhance least-privilege access controls.
Acquired CloudKnox Security for entitlement management
Sep 2022
CrowdStrike
M&A
Acquired Reposify to add external attack surface management
Mar 2023
Cisco
M&A
Acquired Valtix to boost cloud security posture
May 2024
Trend Micro
Launch
Launched enhanced Cloud One CSPM with AI-driven compliance
February 2021: Palo Alto Networks acquired Bridgecrew, a CSPM startup, for approximately $156 million. This move integrated infrastructure-as-code security into Prisma Cloud, strengthening its shift-left capabilities.
July 2021: Microsoft acquired CloudKnox Security, a cloud infrastructure entitlement management (CIEM) provider, to enhance multi-cloud least-privilege access in Defender for Cloud. The acquisition addressed the growing need for identity-centric security.
September 2022: CrowdStrike acquired Reposify, an external attack surface management (EASM) company, for a reported $50 million. This added external visibility to Falcon Cloud Security, complementing its agent-based protection.
March 2023: Cisco acquired Valtix, a cloud-native security platform, to integrate CSPM into its Security Cloud vision. The deal aimed to simplify multi-cloud security for enterprises.
May 2024: Trend Micro launched new CSPM features within Cloud One, including AI-powered compliance automation and enhanced risk assessment. This launch targeted organizations facing complex regulatory requirements.
These strategic moves highlight the trend of consolidation, as vendors seek to offer integrated platforms. The Cloud Security Posture Management Market is witnessing increased M&A activity, with a focus on AI, automation, and multi-cloud support.
North America is the most mature market, with 42% of global revenue, driven by the presence of major vendors and strict regulations. The United States alone accounts for 85% of North American revenue, with Canada and Mexico following. Europe is the second-largest market, with 26% share, where GDPR has made CSPM a compliance necessity. The region is also seeing increased demand for data sovereignty solutions, boosting local vendors. Asia-Pacific is the fastest-growing region, expected to register a 16.2% CAGR through 2033, fueled by rapid cloud adoption in China, India, and Southeast Asia. Government initiatives like India's Digital India and China's cloud computing development plan are key catalysts. LAMEA, while smaller, presents opportunities in the GCC countries and South Africa, where cloud adoption is rising.
Fastest-growing market: Asia-Pacific, driven by digital transformation and increasing cybersecurity awareness. The region's large SME base is a significant opportunity for CSPM vendors.
Most mature market: North America, where competition is intense and vendors focus on advanced features like AI and automation. The presence of major cloud providers (AWS, Microsoft, Google) fuels demand.
The Cloud Security Posture Management Market is witnessing a shift towards regional compliance requirements, with vendors localizing their solutions to meet specific regulations.
Supply Chain & Raw Material Dynamics: Cloud Security Posture Management Market
The CSPM market's supply chain is primarily digital, relying on cloud infrastructure, threat intelligence feeds, and software development. Upstream dependencies include cloud service providers (AWS, Microsoft Azure, Google Cloud) whose APIs and services are foundational. Any disruption in these platforms, such as major outages, can impact CSPM solution availability. For instance, the AWS outage in December 2021 affected numerous CSPM tools. Sourcing risks include dependency on third-party threat intelligence providers like Recorded Future and Mandiant, whose data feeds are critical for real-time detection. Price volatility in cloud compute and data egress costs directly affects CSPM vendors' operating expenses. The cost of cloud infrastructure has generally declined, but data transfer fees remain a pain point. Additionally, the open-source components used in CSPM platforms, such as Elasticsearch and Kubernetes, introduce security and maintenance risks. Historical disruptions, like the Log4j vulnerability in 2021, required urgent patching across supply chains. To mitigate risks, vendors are diversifying threat intelligence sources and adopting multi-cloud strategies. The Cloud Workload Protection Market is closely linked, as both rely on similar infrastructure. Overall, the supply chain is resilient but vulnerable to cloud provider policies and cybersecurity incidents.
Regulatory frameworks are a major driver for CSPM adoption. In North America, FedRAMP mandates cloud security assessments for federal agencies, while CCPA and CPRA impose data privacy requirements. The US Executive Order 14028 on Improving the Nation's Cybersecurity (2021) emphasizes zero trust and cloud security, accelerating CSPM adoption. In Europe, GDPR imposes fines up to 4% of global revenue for data breaches, making CSPM essential for compliance. The NIS2 Directive (2022) expands cybersecurity requirements to critical infrastructure. In Asia-Pacific, regulations vary: China's Cybersecurity Law and Data Security Law require data localization and security reviews; Japan's APPI and Australia's Privacy Act set data protection standards. Industry-specific standards like PCI DSS for payment card data and HIPAA for healthcare also drive CSPM demand. Recent policy changes include the EU Cyber Resilience Act (proposed 2022) and the US National Cybersecurity Strategy (2023), which emphasize software supply chain security. Compliance with these frameworks necessitates automated monitoring and reporting, a core CSPM function. The Cloud Compliance Automation Market is thus poised for growth, as organizations seek to streamline regulatory adherence. Vendors are embedding compliance templates for standards like ISO 27001, SOC 2, and NIST 800-53. However, the fragmented regulatory environment across geographies poses challenges for global CSPM deployments. Overall, the regulatory landscape is becoming more stringent, creating sustained demand for CSPM solutions.
Table 70: Rest of Asia Pacific Cloud Security Posture Management Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conduct 70-80% of our research through primary interviews with key stakeholders across the value chain.
Target respondents include: Chief Information Security Officers (CISOs), Cloud Security Architects, DevOps/Cloud Operations Managers, Compliance Officers, and IT Procurement Managers.
We interview representatives from CSPM platform developers, cloud infrastructure providers (IaaS), managed security service providers (MSSPs), cloud security consulting firms, and enterprise IT security teams.
Primary data is collected via structured questionnaires, in-depth interviews, and expert panels, ensuring granular insights into adoption patterns, pricing, and competitive dynamics.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Information Security Officer (CISO)
25%
Cloud Security Architect
25%
DevOps/Cloud Operations Manager
20%
Compliance Officer
15%
IT Procurement Manager
15%
Industry Ecosystem Breakdown
Company Type
Representation (%)
CSPM Platform Developers
30%
Cloud Infrastructure Providers
25%
Managed Security Service Providers (MSSPs)
20%
Cloud Security Consulting Firms
15%
Enterprise IT Security Teams
10%
Secondary Research & Industry Benchmarking
20-30% of research is derived from secondary sources, including company filings, annual reports, and regulatory documents.
We utilize financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook to validate revenue and market share.
We employ both top-down and bottom-up methodologies, validated through multi-level data triangulation.
Bottom-up estimation uses quantitative metrics such as number of cloud workloads per enterprise, average number of cloud accounts per organization, CSPM tool adoption rate, and average cost per cloud security incident.
Top-down analysis leverages global IT security spending and cloud adoption forecasts, cross-referenced with regional regulatory intensity.
Market sizing is segmented by offering, cloud service model, enterprise size, industry vertical, and region.
Data Accuracy & Quality Check
Our estimated data accuracy level is 85-90%, achieved through rigorous validation and cross-referencing.
Every report is updated to the date of purchase, ensuring the latest market developments are incorporated.
Data triangulation involves comparing primary interview findings with secondary data and historical trends.
Quality checks include outlier detection, sanity checks against industry benchmarks, and peer review by senior analysts.
Frequently Asked Questions
1. How do regulatory frameworks impact the Cloud Security Posture Management Market?
Regulatory frameworks such as GDPR, CCPA, and HIPAA mandate strict data protection and privacy, driving demand for CSPM solutions that ensure continuous compliance. For instance, GDPR fines reached €2.1 billion in 2023, compelling organizations to adopt automated posture management. The market benefits as enterprises seek tools to avoid penalties and demonstrate compliance.
2. What is the environmental impact of cloud security posture management solutions?
CSPM solutions are software-based, so their direct environmental footprint is minimal. However, they indirectly influence energy consumption by optimizing cloud resource usage. For example, by identifying unused or misconfigured resources, CSPM tools can reduce cloud waste, potentially lowering energy consumption by up to 15%. Vendors are also increasingly focusing on sustainable cloud practices.
3. How are consumer purchasing trends shifting in the Cloud Security Posture Management Market?
Consumers, primarily enterprises, are shifting towards integrated platforms that combine CSPM with workload protection and identity management. There is a growing preference for subscription-based pricing and pay-as-you-go models. For instance, 68% of organizations now prefer consolidated security suites over point solutions, driving vendors to expand their capabilities.
4. What are the key barriers to entry in the Cloud Security Posture Management Market?
High barriers include the need for advanced AI and machine learning capabilities, extensive R&D investment, and integration with major cloud providers. Building trust with enterprises and achieving compliance certifications like FedRAMP and SOC 2 also require significant time and resources. Established vendors like Palo Alto Networks and Microsoft dominate, making it challenging for new entrants.
5. Which pricing trends are shaping the Cloud Security Posture Management Market?
Pricing is increasingly based on the number of cloud workloads or accounts, with average annual costs ranging from $50,000 to $500,000 for large enterprises. Vendors are offering tiered pricing and bundled solutions to attract SMEs. The shift towards consumption-based models is expected to continue, with a CAGR of 14.5% in market value.
6. Why is post-pandemic recovery driving structural shifts in the Cloud Security Posture Management Market?
The pandemic accelerated cloud adoption, with remote work and digital transformation becoming permanent. This led to a 30% increase in cloud workloads, creating sustained demand for CSPM. Long-term structural shifts include the adoption of zero trust architectures and multi-cloud strategies, embedding CSPM as a core security requirement.