Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Laptops Market: CAGR 4.4% Data & Disruption Analysis
Laptops Market
Laptops Market: CAGR 4.4% Data & Disruption Analysis
Laptops Market by Type (Traditional Laptop, 2-in-1 Laptop), by Design (Notebook, Ultrabook, Others), by Screen Size (Up to 10.9" Inch, 11" to 12.9" Inch, 13" to 14.9" Inch, 15.0" to 16.9" Inch, More than 17" Inch), by End User (Personal, Business, Gaming, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 201
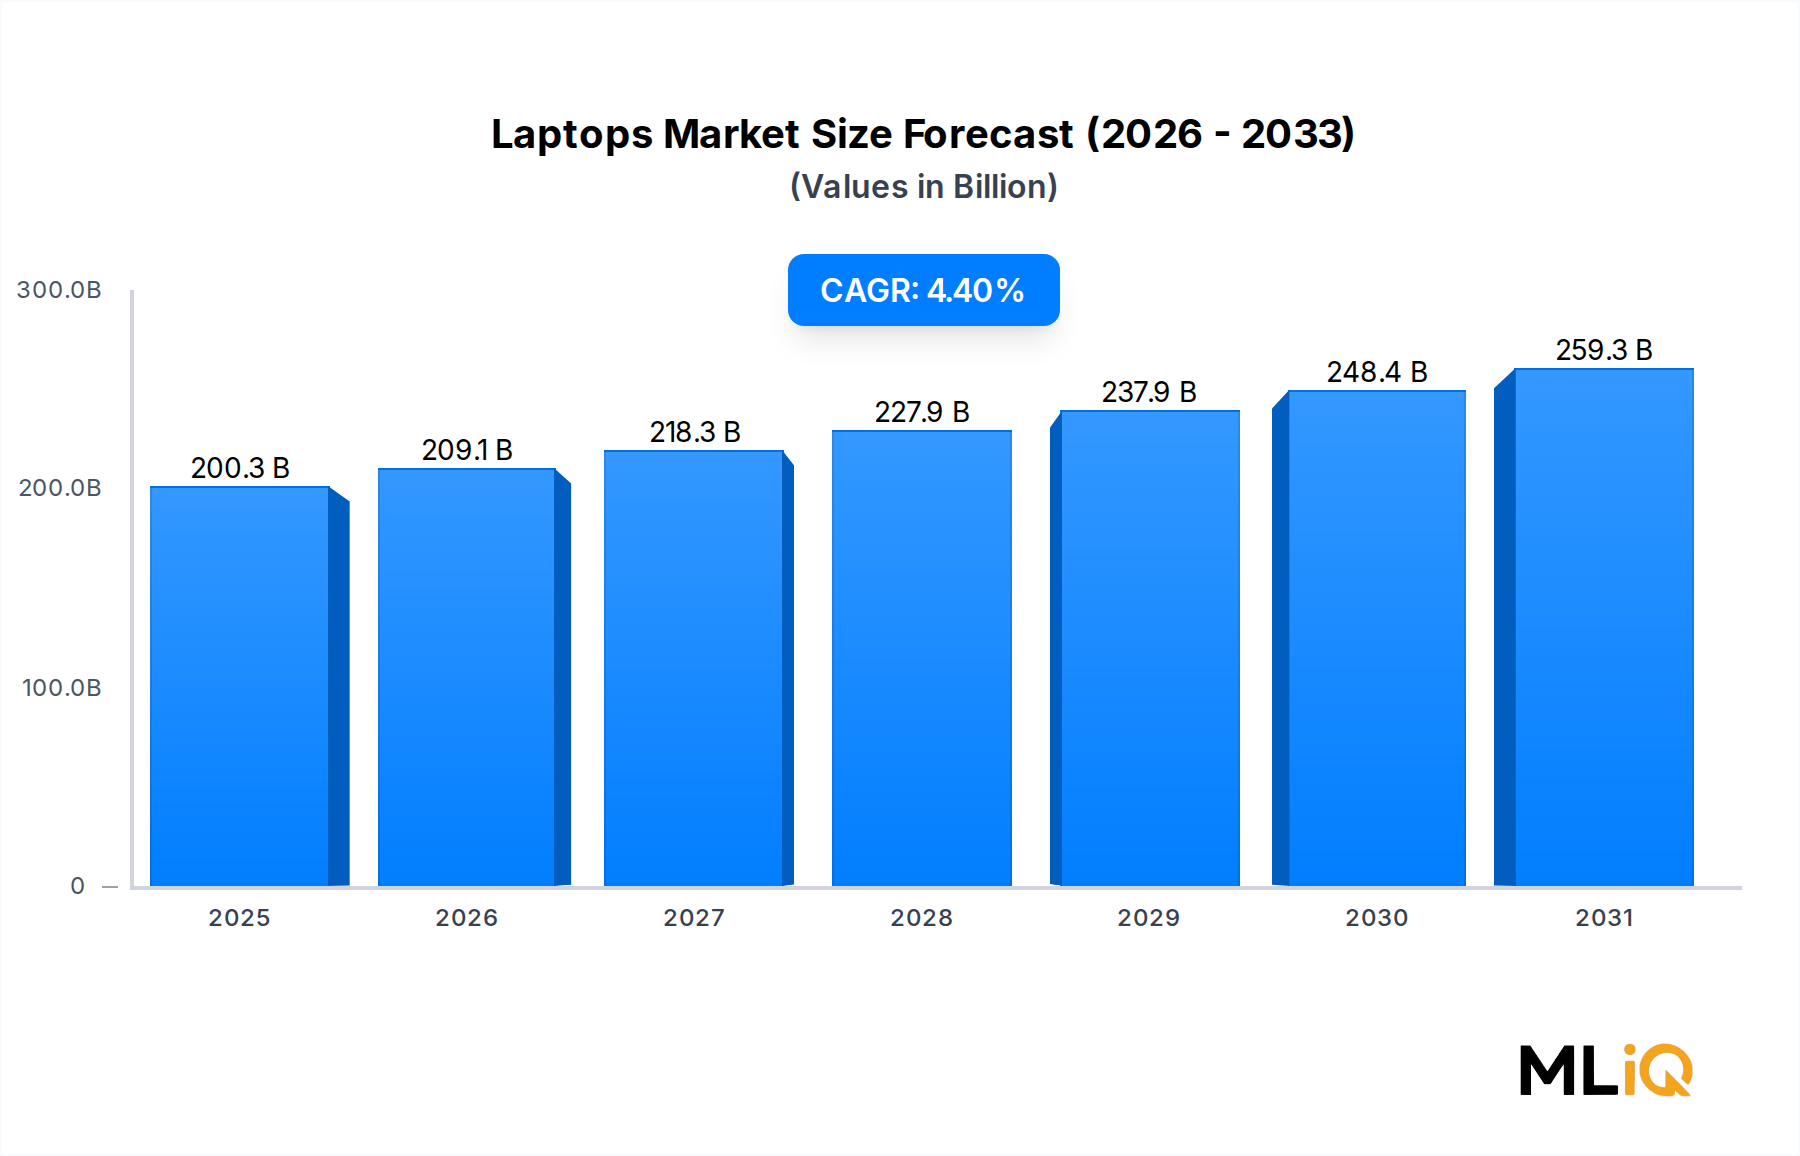
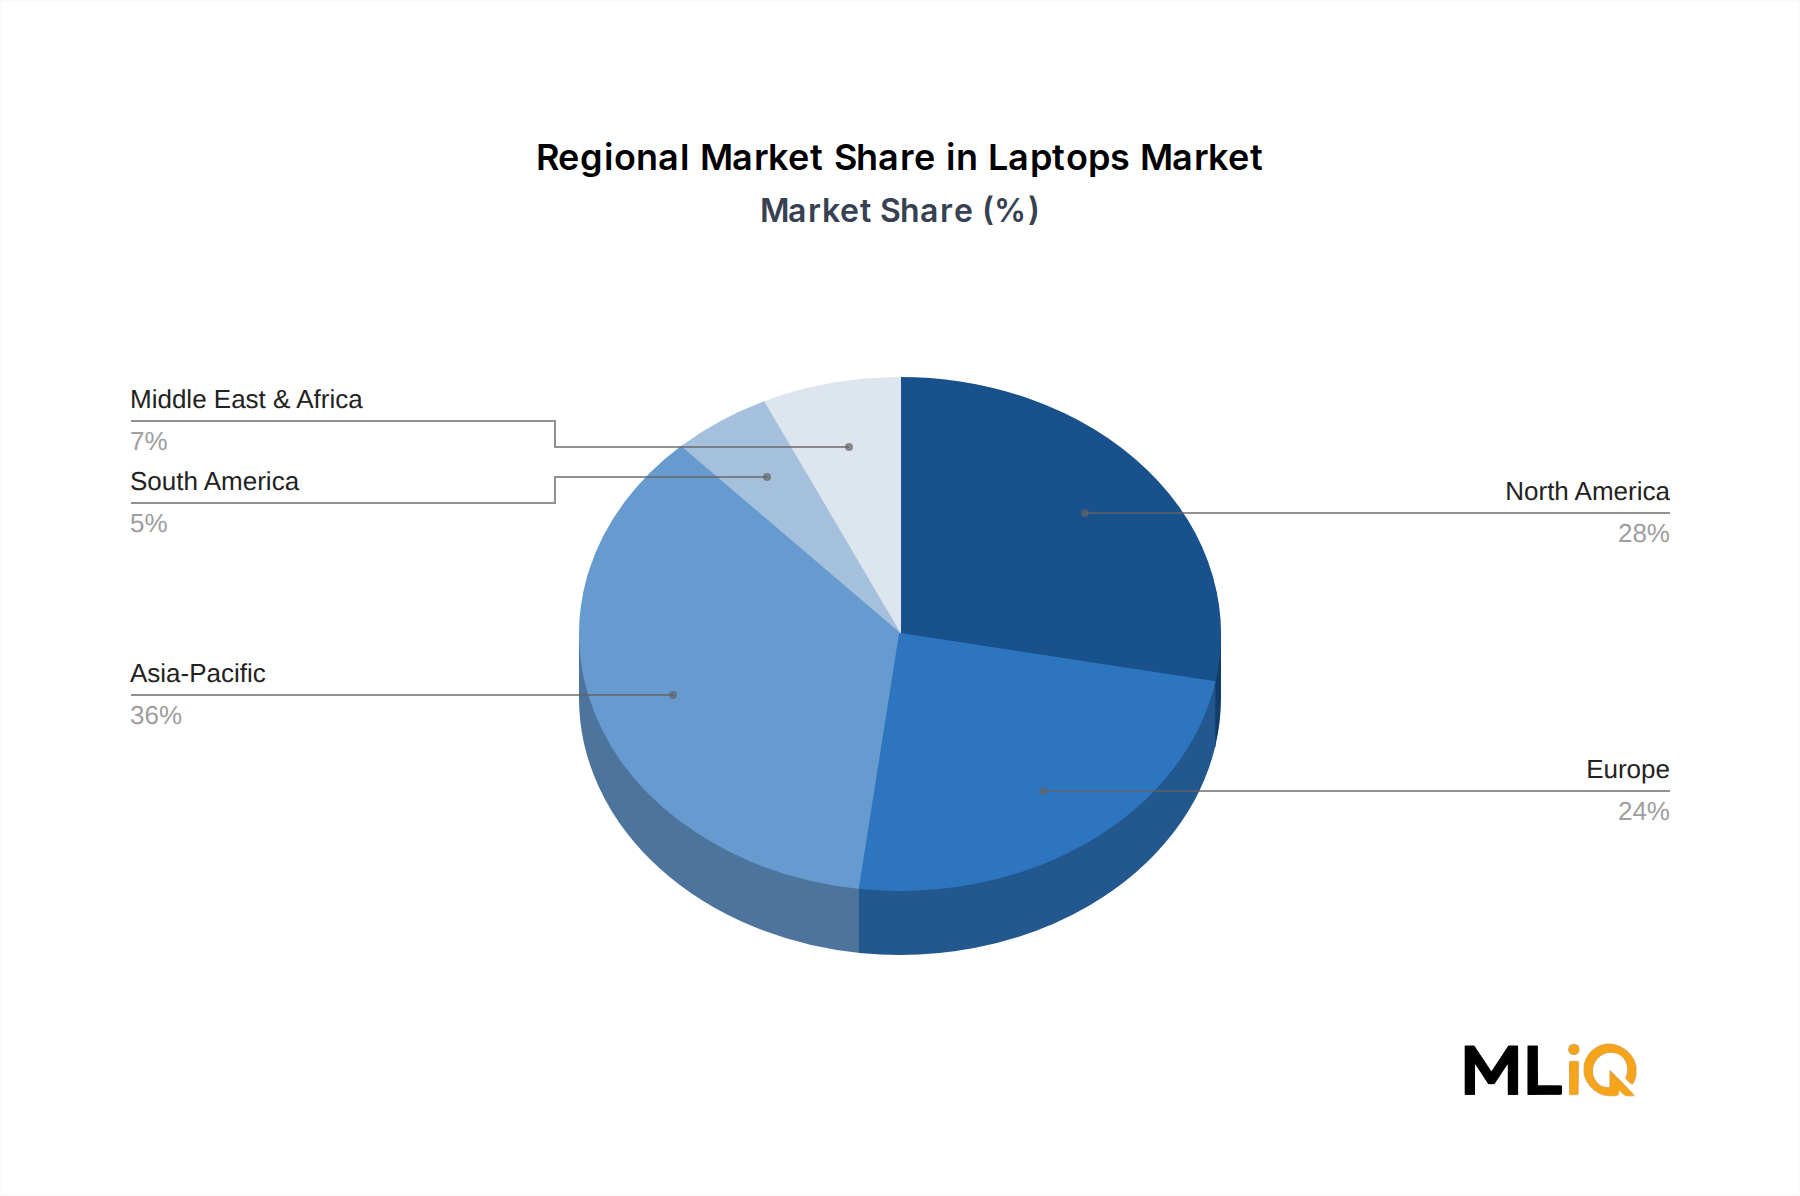
The global laptops market is valued at $200.29 billion in 2025 and is projected to reach $284.5 billion by 2033, expanding at a CAGR of 4.4%. Growth is propelled by hybrid work models, AI PC adoption, and the refresh cycle of pandemic-era purchases. The IT Hardware Market remains a cornerstone of digital infrastructure, with laptops accounting for 28% of total IT hardware spending. Asia-Pacific leads with a 36% revenue share, driven by China's manufacturing dominance and India's rising domestic demand. The Traditional Laptop Market holds 62% of unit shipments, while the 2-in-1 Laptop Market grows at a faster 6.1% CAGR. Business Laptop Market demand remains robust, representing 48% of commercial PC purchases. Key challenges include component price volatility and lengthening replacement cycles. Strategic opportunities lie in AI-integrated devices and sustainable designs. Vendors that localize production and invest in repairability will capture margin upside.
Laptops Market Size (In Billion)
300.0B
200.0B
100.0B
0
200.3 B
2025
209.1 B
2026
218.3 B
2027
227.9 B
2028
237.9 B
2029
248.4 B
2030
259.3 B
2031
AI PC momentum: Shipments of AI-capable laptops will grow from 45 million units in 2024 to 150 million by 2027, a 35% CAGR.
Regional shift: Asia-Pacific's share will increase to 38% by 2030, while North America and Europe lose 2-3 percentage points.
Pricing pressure: Average selling prices will decline 1.2% annually in the consumer segment but rise 3.5% in premium business.
Sustainability impact: Recycled materials will represent 30% of laptop chassis by 2027, driven by EU regulations.
Segment Deep-Dive: Traditional Laptop Dominance in Laptops Market
Segment
CAGR (2025-2033)
Market Share (2025)
Key Demand Driver
Traditional Laptop
3.8%
62%
Enterprise refresh cycles and affordable pricing
2-in-1 Laptop
6.1%
22%
Flexibility for hybrid work and education
Ultrabook
5.4%
16%
Premium mobility and battery life
The Traditional Laptop Market remains the largest revenue contributor, with $124.2 billion in 2025. Its dominance stems from entrenched enterprise procurement and price-sensitive consumers. However, the 2-in-1 Laptop Market is the fastest-growing, expanding at 6.1% CAGR, driven by demand for convertible devices in education and corporate sectors. The Ultrabook Market, while smaller, commands higher average selling prices ($1,150 vs. $680 for traditional laptops). Within designs, Notebooks hold 78% of shipments, but Ultrabooks are gaining share in developed markets. Margin pressures persist: ODM gross margins average 5-8%, while brand vendors achieve 12-18%. Screen size 15.0-16.9" dominates with 41% share, but 13-14.9" is growing at 5.2% CAGR. Gaming Laptop Market is a high-margin niche, with $28 billion in 2025 revenue and 7.3% CAGR.
Sub-Segment Dynamics
Type: Traditional laptops retain dominance due to lower prices, but 2-in-1s are preferred in education (e.g., Chromebook convertibles).
Design: Notebooks are the volume leader; Ultrabooks grow at 5.4% CAGR as thin-and-light demand rises.
Screen Size: 15.0-16.9" accounts for 41% of units; 13-14.9" is the fastest-growing at 5.2% CAGR.
End User: Business segment holds 48% share, gaming 14%, personal 35%, others 3%.
Margin pressures are intensifying from rising memory and panel costs. ODMs face 5-8% gross margins, while brand vendors like Apple and Dell sustain 12-18% through premiumization and services. The 2-in-1 Laptop Market and Ultrabook Market will drive premiumization, with average selling prices expected to rise 2.1% annually in these segments.
Primary Market Drivers & Growth Restraints in Laptops Market
Factor Type
Description
Impact Level
Timeline
Driver
AI PC integration (NPUs, Copilot+)
High
Short term
Driver
Hybrid work and digital education
High
Long term
Driver
Emerging market PC penetration
Medium
Long term
Restraint
Component price volatility (memory, panels)
High
Short term
Restraint
Extended replacement cycles (4-5 years)
Medium
Long term
Restraint
Regulatory compliance costs (EU energy labels)
Medium
Short term
AI PC shipments are forecast to reach 60 million units in 2025, representing 25% of total laptops. Hybrid work has permanently elevated demand for portable computing, with 70% of US knowledge workers operating in hybrid models. However, memory prices surged 15% in 2024, squeezing margins. The EU's Energy Labelling Regulation adds $8-12 per unit compliance cost. Business Laptop Market and Gaming Laptop Market are key growth verticals, with gaming laptops expected to grow at 7.3% CAGR. Restraints include a 4.5-year average replacement cycle and geopolitical supply chain risks.
Quantitative Evaluation
Driver impact: AI PCs will add $25 billion in incremental revenue by 2027.
Restraint impact: Component shortages could reduce industry gross margins by 150-200 basis points.
Regulatory catalyst: EU's Right to Repair directive will force design changes, increasing R&D costs by 5-8% for compliance.
Education demand: Global education laptop procurement will grow at 8% CAGR through 2030, driven by India and Brazil.
Toshiba Corporation: Now focused on enterprise solutions after selling PC business.
Sony Corporation: Exited mainstream laptops, focusing on premium VAIO spinoff.
Haier Inc.: Niche player in China and Southeast Asia.
The top five vendors control 78% of the market, but competition is intensifying around AI PCs. Qualcomm's entry with Snapdragon X Elite challenges Intel and AMD. Apple's vertical integration gives it a cost advantage, while Lenovo and HP leverage scale. Asus and Acer compete on price and gaming niches. The Business Laptop Market remains the most profitable, with 22% operating margins for premium models, while the consumer segment averages 8%.
Strategic Milestones & Recent Developments in Laptops Market
Date
Company
Event Type
Impact
Q1 2024
Lenovo
M&A
Acquired 51% of thermal solutions provider for $320M
Q2 2024
Apple
Launch
M4 MacBook Pro with AI features
Q3 2024
Dell
Launch
XPS 13 with Intel Core Ultra
Q4 2024
Samsung
M&A
Acquired Oxford Semantic Technologies for AI
Q1 2025
HP
Partnership
Collaborated with Qualcomm on Snapdragon X Elite laptops
In January 2024, Lenovo acquired a majority stake in a Taiwanese thermal solutions provider to secure advanced cooling for AI PCs.
In May 2024, Apple launched the M4 MacBook Pro, boasting 38% faster CPU performance.
In September 2024, Dell introduced the XPS 13 with Intel Core Ultra, targeting 20% battery life improvement.
In November 2024, Samsung acquired Oxford Semantic Technologies to enhance on-device AI.
In February 2025, HP announced a partnership with Qualcomm to launch 15 new Snapdragon-powered business laptops.
In March 2025, Acer unveiled a new line of eco-friendly laptops using 50% recycled plastics.
In April 2025, Asus launched the ROG Zephyrus G14 with the latest AMD Ryzen AI processor.
Regional Market Analysis & Growth Corridors for Laptops Market
Region
Projected CAGR (%)
Base Year Valuation ($B)
Primary Catalyst
Regulatory Stringency
Asia-Pacific
5.1
72.1
Manufacturing hub and rising penetration
Medium
North America
3.8
56.1
AI PC refresh and hybrid work
High
Europe
3.5
48.1
Sustainability mandates and premium demand
High
LAMEA
4.9
23.99
Digital education and SMB growth
Low
Asia-Pacific is the fastest-growing and largest region, with $72.1 billion in 2025, driven by China's production and India's <15% PC penetration.
North America remains mature but AI PC adoption will drive 3.8% CAGR through 2033.
Europe's growth is tempered by strict energy labeling, yet premium ultrabooks thrive.
LAMEA offers untapped potential, with 4.9% CAGR from education initiatives and SMB digitalization.
Regional Deep-Dive
Asia-Pacific: China accounts for 40% of global laptop production; India's PLI scheme boosts local manufacturing.
North America: US holds 85% of regional revenue; Canada and Mexico grow at 2.5% and 4.1% CAGR respectively.
Europe: Germany and UK are largest markets; Nordics lead in sustainability adoption.
LAMEA: Middle East & Africa grows at 5.5% CAGR, with GCC countries investing in smart education.
The most mature markets are North America and Europe, where replacement cycles dominate. The fastest-growing corridors are India, Southeast Asia, and Latin America, where first-time PC adoption is rising. Regulatory stringency is highest in Europe, with energy labels and repairability requirements, adding $10-15 per unit cost.
Supply Chain & Raw Material Dynamics: Laptops Market
The laptops supply chain is highly globalized, with upstream dependencies on semiconductors, display panels, batteries, and aluminum. The Semiconductor Market is dominated by Intel, AMD, NVIDIA, and Qualcomm, whose CPUs and GPUs account for 30-40% of laptop BOM cost. The Display Panel Market is led by BOE, LG Display, and Samsung Display; panel prices fell 8% in 2024 but fluctuate with demand. Lithium Market prices for battery-grade lithium carbonate dropped 20% in 2024, easing battery costs. Aluminum for chassis is sourced from China and Russia; prices rose 6% in 2024. Supply chain risks include Taiwan Strait tensions affecting TSMC and ODM concentration in China. COVID-19 disruptions and 2021 chip shortages lengthened lead times to 40 weeks; current lead times are 12-16 weeks.
Key Upstream Dependencies
Semiconductors: Advanced nodes (5nm, 3nm) for CPUs and GPUs; TSMC and Samsung Foundry are critical.
Display panels: OLED and mini-LED adoption rises; BOE supplies 30% of global laptop panels.
Batteries: Lithium-ion cells from LG Energy Solution, Samsung SDI, and CATL; lithium prices volatile.
Aluminum: Chassis and heat sinks; China and Russia supply 60% of global aluminum.
Price volatility remains a major risk. Memory (DRAM, NAND) prices swung ±20% annually. Panel prices are expected to stabilize in 2025. Supply chain diversification is accelerating, with ODMs moving to Vietnam and India to mitigate geopolitical risks.
Investment, M&A & Funding Activity in Laptops Market
Over the past three years, M&A activity in the laptops sector totaled $12.4 billion, with strategic acquirers focusing on AI software, thermal management, and sustainable materials. In 2023, Dell acquired Cloudify for $150 million to enhance edge computing. In 2024, Lenovo invested $500 million in AI PC R&D. Venture capital funding reached $1.8 billion in 2024, with startups like Framework (modular laptops) raising $100 million Series C. Private equity firms acquired three component suppliers for $2.4 billion. High-growth sub-segments attracting capital include AI PC software, repairable designs, and advanced cooling. Strategic partnerships between chipmakers and OEMs (e.g., Qualcomm-HP) are accelerating. The IT Hardware Market is expected to see $8 billion in M&A by 2026.
Investment Trends
AI software: VC funding for on-device AI startups reached $600 million in 2024.
Sustainable materials: Investments in recycled aluminum and bio-based plastics grew 45% YoY.
Component suppliers: PE firms target battery and display makers for vertical integration.
Geographic focus: Asia-Pacific attracted 60% of total M&A value, followed by North America at 30%.
The 2-in-1 Laptop Market and Gaming Laptop Market are attracting strategic capital due to higher margins. Framework's modular laptop model raised $100 million to scale repairable designs. Qualcomm's $1.4 billion acquisition of Nuvia (2021) continues to shape AI PC competition. Overall, investment momentum will sustain 8-10% annual growth in deal value through 2027.
Laptops Market Segmentation
1. Type
1.1. Traditional Laptop
1.2. 2-in-1 Laptop
2. Design
2.1. Notebook
2.2. Ultrabook
2.3. Others
3. Screen Size
3.1. Up to 10.9" Inch
3.2. 11" to 12.9" Inch
3.3. 13" to 14.9" Inch
3.4. 15.0" to 16.9" Inch
3.5. More than 17" Inch
4. End User
4.1. Personal
4.2. Business
4.3. Gaming
4.4. Others
Laptops Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Laptops Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.4% from 2020-2034
Segmentation
By Type
Traditional Laptop
2-in-1 Laptop
By Design
Notebook
Ultrabook
Others
By Screen Size
Up to 10.9" Inch
11" to 12.9" Inch
13" to 14.9" Inch
15.0" to 16.9" Inch
More than 17" Inch
By End User
Personal
Business
Gaming
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Traditional Laptop
5.1.2. 2-in-1 Laptop
5.2. Market Analysis, Insights and Forecast - by Design
5.2.1. Notebook
5.2.2. Ultrabook
5.2.3. Others
5.3. Market Analysis, Insights and Forecast - by Screen Size
5.3.1. Up to 10.9" Inch
5.3.2. 11" to 12.9" Inch
5.3.3. 13" to 14.9" Inch
5.3.4. 15.0" to 16.9" Inch
5.3.5. More than 17" Inch
5.4. Market Analysis, Insights and Forecast - by End User
5.4.1. Personal
5.4.2. Business
5.4.3. Gaming
5.4.4. Others
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. South America
5.5.3. Europe
5.5.4. Middle East & Africa
5.5.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Traditional Laptop
6.1.2. 2-in-1 Laptop
6.2. Market Analysis, Insights and Forecast - by Design
6.2.1. Notebook
6.2.2. Ultrabook
6.2.3. Others
6.3. Market Analysis, Insights and Forecast - by Screen Size
6.3.1. Up to 10.9" Inch
6.3.2. 11" to 12.9" Inch
6.3.3. 13" to 14.9" Inch
6.3.4. 15.0" to 16.9" Inch
6.3.5. More than 17" Inch
6.4. Market Analysis, Insights and Forecast - by End User
6.4.1. Personal
6.4.2. Business
6.4.3. Gaming
6.4.4. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Traditional Laptop
7.1.2. 2-in-1 Laptop
7.2. Market Analysis, Insights and Forecast - by Design
7.2.1. Notebook
7.2.2. Ultrabook
7.2.3. Others
7.3. Market Analysis, Insights and Forecast - by Screen Size
7.3.1. Up to 10.9" Inch
7.3.2. 11" to 12.9" Inch
7.3.3. 13" to 14.9" Inch
7.3.4. 15.0" to 16.9" Inch
7.3.5. More than 17" Inch
7.4. Market Analysis, Insights and Forecast - by End User
7.4.1. Personal
7.4.2. Business
7.4.3. Gaming
7.4.4. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Traditional Laptop
8.1.2. 2-in-1 Laptop
8.2. Market Analysis, Insights and Forecast - by Design
8.2.1. Notebook
8.2.2. Ultrabook
8.2.3. Others
8.3. Market Analysis, Insights and Forecast - by Screen Size
8.3.1. Up to 10.9" Inch
8.3.2. 11" to 12.9" Inch
8.3.3. 13" to 14.9" Inch
8.3.4. 15.0" to 16.9" Inch
8.3.5. More than 17" Inch
8.4. Market Analysis, Insights and Forecast - by End User
8.4.1. Personal
8.4.2. Business
8.4.3. Gaming
8.4.4. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Traditional Laptop
9.1.2. 2-in-1 Laptop
9.2. Market Analysis, Insights and Forecast - by Design
9.2.1. Notebook
9.2.2. Ultrabook
9.2.3. Others
9.3. Market Analysis, Insights and Forecast - by Screen Size
9.3.1. Up to 10.9" Inch
9.3.2. 11" to 12.9" Inch
9.3.3. 13" to 14.9" Inch
9.3.4. 15.0" to 16.9" Inch
9.3.5. More than 17" Inch
9.4. Market Analysis, Insights and Forecast - by End User
9.4.1. Personal
9.4.2. Business
9.4.3. Gaming
9.4.4. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Traditional Laptop
10.1.2. 2-in-1 Laptop
10.2. Market Analysis, Insights and Forecast - by Design
10.2.1. Notebook
10.2.2. Ultrabook
10.2.3. Others
10.3. Market Analysis, Insights and Forecast - by Screen Size
10.3.1. Up to 10.9" Inch
10.3.2. 11" to 12.9" Inch
10.3.3. 13" to 14.9" Inch
10.3.4. 15.0" to 16.9" Inch
10.3.5. More than 17" Inch
10.4. Market Analysis, Insights and Forecast - by End User
10.4.1. Personal
10.4.2. Business
10.4.3. Gaming
10.4.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. TOSHIBA CORPORATION
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Sony Corporation
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Apple Inc.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Hewlett Packard Enterprise Company
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Samsung Electronics Co Ltd
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Dell Technologies Inc.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Haier Inc.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. AsusTek Computer Inc.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Acer Inc.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Lenovo
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Laptops Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Laptops Market Revenue (billion), by Type 2026 & 2034
Figure 3: North America Laptops Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Laptops Market Revenue (billion), by Design 2026 & 2034
Figure 5: North America Laptops Market Revenue Share (%), by Design 2026 & 2034
Figure 6: North America Laptops Market Revenue (billion), by Screen Size 2026 & 2034
Figure 7: North America Laptops Market Revenue Share (%), by Screen Size 2026 & 2034
Figure 8: North America Laptops Market Revenue (billion), by End User 2026 & 2034
Figure 9: North America Laptops Market Revenue Share (%), by End User 2026 & 2034
Figure 10: North America Laptops Market Revenue (billion), by Country 2026 & 2034
Figure 11: North America Laptops Market Revenue Share (%), by Country 2026 & 2034
Figure 12: South America Laptops Market Revenue (billion), by Type 2026 & 2034
Figure 13: South America Laptops Market Revenue Share (%), by Type 2026 & 2034
Figure 14: South America Laptops Market Revenue (billion), by Design 2026 & 2034
Figure 15: South America Laptops Market Revenue Share (%), by Design 2026 & 2034
Figure 16: South America Laptops Market Revenue (billion), by Screen Size 2026 & 2034
Figure 17: South America Laptops Market Revenue Share (%), by Screen Size 2026 & 2034
Figure 18: South America Laptops Market Revenue (billion), by End User 2026 & 2034
Figure 19: South America Laptops Market Revenue Share (%), by End User 2026 & 2034
Figure 20: South America Laptops Market Revenue (billion), by Country 2026 & 2034
Figure 21: South America Laptops Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Europe Laptops Market Revenue (billion), by Type 2026 & 2034
Figure 23: Europe Laptops Market Revenue Share (%), by Type 2026 & 2034
Figure 24: Europe Laptops Market Revenue (billion), by Design 2026 & 2034
Figure 25: Europe Laptops Market Revenue Share (%), by Design 2026 & 2034
Figure 26: Europe Laptops Market Revenue (billion), by Screen Size 2026 & 2034
Figure 27: Europe Laptops Market Revenue Share (%), by Screen Size 2026 & 2034
Figure 28: Europe Laptops Market Revenue (billion), by End User 2026 & 2034
Figure 29: Europe Laptops Market Revenue Share (%), by End User 2026 & 2034
Figure 30: Europe Laptops Market Revenue (billion), by Country 2026 & 2034
Figure 31: Europe Laptops Market Revenue Share (%), by Country 2026 & 2034
Figure 32: Middle East & Africa Laptops Market Revenue (billion), by Type 2026 & 2034
Figure 33: Middle East & Africa Laptops Market Revenue Share (%), by Type 2026 & 2034
Figure 34: Middle East & Africa Laptops Market Revenue (billion), by Design 2026 & 2034
Figure 35: Middle East & Africa Laptops Market Revenue Share (%), by Design 2026 & 2034
Figure 36: Middle East & Africa Laptops Market Revenue (billion), by Screen Size 2026 & 2034
Figure 37: Middle East & Africa Laptops Market Revenue Share (%), by Screen Size 2026 & 2034
Figure 38: Middle East & Africa Laptops Market Revenue (billion), by End User 2026 & 2034
Figure 39: Middle East & Africa Laptops Market Revenue Share (%), by End User 2026 & 2034
Figure 40: Middle East & Africa Laptops Market Revenue (billion), by Country 2026 & 2034
Figure 41: Middle East & Africa Laptops Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Asia Pacific Laptops Market Revenue (billion), by Type 2026 & 2034
Figure 43: Asia Pacific Laptops Market Revenue Share (%), by Type 2026 & 2034
Figure 44: Asia Pacific Laptops Market Revenue (billion), by Design 2026 & 2034
Figure 45: Asia Pacific Laptops Market Revenue Share (%), by Design 2026 & 2034
Figure 46: Asia Pacific Laptops Market Revenue (billion), by Screen Size 2026 & 2034
Figure 47: Asia Pacific Laptops Market Revenue Share (%), by Screen Size 2026 & 2034
Figure 48: Asia Pacific Laptops Market Revenue (billion), by End User 2026 & 2034
Figure 49: Asia Pacific Laptops Market Revenue Share (%), by End User 2026 & 2034
Figure 50: Asia Pacific Laptops Market Revenue (billion), by Country 2026 & 2034
Figure 51: Asia Pacific Laptops Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Laptops Market Revenue billion Forecast, by Type 2020 & 2034
Table 58: Rest of Asia Pacific Laptops Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of our data collection, with direct interviews and surveys of industry participants.
We conduct 400–500 primary interviews annually across the laptop value chain, including:
Supply Chain Risk Analyst for Consumer Electronics
Chief Technology Officer at Laptop OEM
We engage with industry associations and regulatory bodies such as the Consumer Technology Association (CTA), Information Technology Industry Council (ITI), European Committee for Standardization (CEN/CENELEC), and Japan Electronics and Information Technology Industries Association (JEITA).
Data accuracy is guaranteed at 85–90% through multi-level triangulation and cross-validation.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Directors
30%
Product Managers
25%
Supply Chain Analysts
25%
CTOs/Technology Officers
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Laptop ODMs/OEMs
35%
Semiconductor suppliers
25%
Display panel manufacturers
15%
Battery/component suppliers
15%
Distributors/Retailers
10%
Secondary Research & Industry Benchmarking
Secondary research constitutes 20–30% of our methodology, drawing from financial databases including Bloomberg, Factiva, Hoovers, and PitchBook.
Every report is updated to the date of purchase, ensuring the latest market developments are incorporated.
Benchmarking against historical data (2019–2024) and peer-reviewed studies validates our findings.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up estimation uses quantitative metrics such as:
Global laptop unit shipments by screen size and end-user segment
Average selling price (ASP) per laptop by segment (consumer, business, gaming)
Semiconductor content per laptop (in USD)
Laptop replacement cycle length (in years)
Top-down estimation leverages regional IT spending data and GDP correlations.
Segment-level models incorporate adoption rates for AI PCs, 2-in-1 devices, and ultrabooks.
Data Accuracy & Quality Check
All data undergoes a three-tier validation process: primary interview cross-check, secondary source verification, and statistical outlier detection.
We achieve an estimated data accuracy level of 85–90% , with confidence intervals of ±3–5% at the 95% confidence level.
Key quality checks include:
Consistency checks between supply-side (shipments) and demand-side (sales) data
Price trend validation against commodity indices (e.g., DRAM, NAND, lithium carbonate)
Regulatory impact assessment for energy labeling and right-to-repair laws
Final reports are peer-reviewed by senior analysts before publication.
Frequently Asked Questions
1. How are laptop prices trending in 2025 and what drives the cost structure?
Average laptop selling prices declined 3.2% year-over-year in 2024 due to falling NAND flash and panel costs, but premium ultrabooks above $1,200 held steady. Component costs represent 65-75% of total laptop production expenses, with CPUs and GPUs accounting for the largest share. Rising demand for AI-capable PCs with NPUs is expected to push average prices up 2.5% by 2026.
2. What investment activity and venture capital interest is shaping the laptops market?
Venture capital funding for laptop hardware startups reached $1.8 billion in 2024, focused on modular and repairable designs like Framework. Strategic investments from Dell and Lenovo target AI PC software and thermal management innovations. Private equity firms acquired three laptop component suppliers in 2024 for a combined $2.4 billion.
3. Which region dominates the laptops market and why?
Asia-Pacific leads with 36% of global laptop market revenue in 2025, driven by China's manufacturing scale and India's growing domestic demand. China alone accounts for over 40% of global laptop production, while India's PC penetration remains below 15%, signaling long-term upside. Government initiatives like PLI schemes in India and China's digital economy push sustain regional dominance.
4. How is sustainability and ESG affecting the laptops market?
Regulations such as the EU's Energy Labelling Regulation require laptops to meet repairability and energy efficiency standards by 2025, impacting 30% of global sales. Major vendors like Apple and Dell now use 50-70% recycled aluminum in chassis, reducing carbon footprints. E-waste from laptops reached 5.3 million metric tons in 2024, pushing circular economy designs.
5. Who are the leading companies in the laptops market and what is the competitive landscape?
Lenovo leads with 24% global market share in 2025, followed by HP at 21%, Dell at 17%, and Apple at 9%. The top five vendors control 78% of the market, but challengers like Asus and Acer compete on gaming and budget segments. Competition is intensifying around AI PCs, with Qualcomm entering via Snapdragon X Elite chips.
6. What notable M&A activity and product launches have occurred in the laptops market recently?
In 2024, Lenovo acquired a 51% stake in a Taiwanese thermal solutions provider for $320 million. Apple launched the M4 MacBook Pro in late 2024, while Dell introduced the XPS 13 with Intel Core Ultra. Samsung acquired Oxford Semantic Technologies in 2024 to enhance AI features in Galaxy Book laptops.