Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Energy Security Market CAGR 10.5% Forecast to 2033
Energy Security Market
Energy Security Market CAGR 10.5% Forecast to 2033
Energy Security Market by Component (Solution, Service), by Technology (Physical Security, Network Security), by Power Plant (Thermal and hydro, Nuclear, Oil and gas, Renewable Energy), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 283
Key Insights & Executive Summary: Energy Security Market
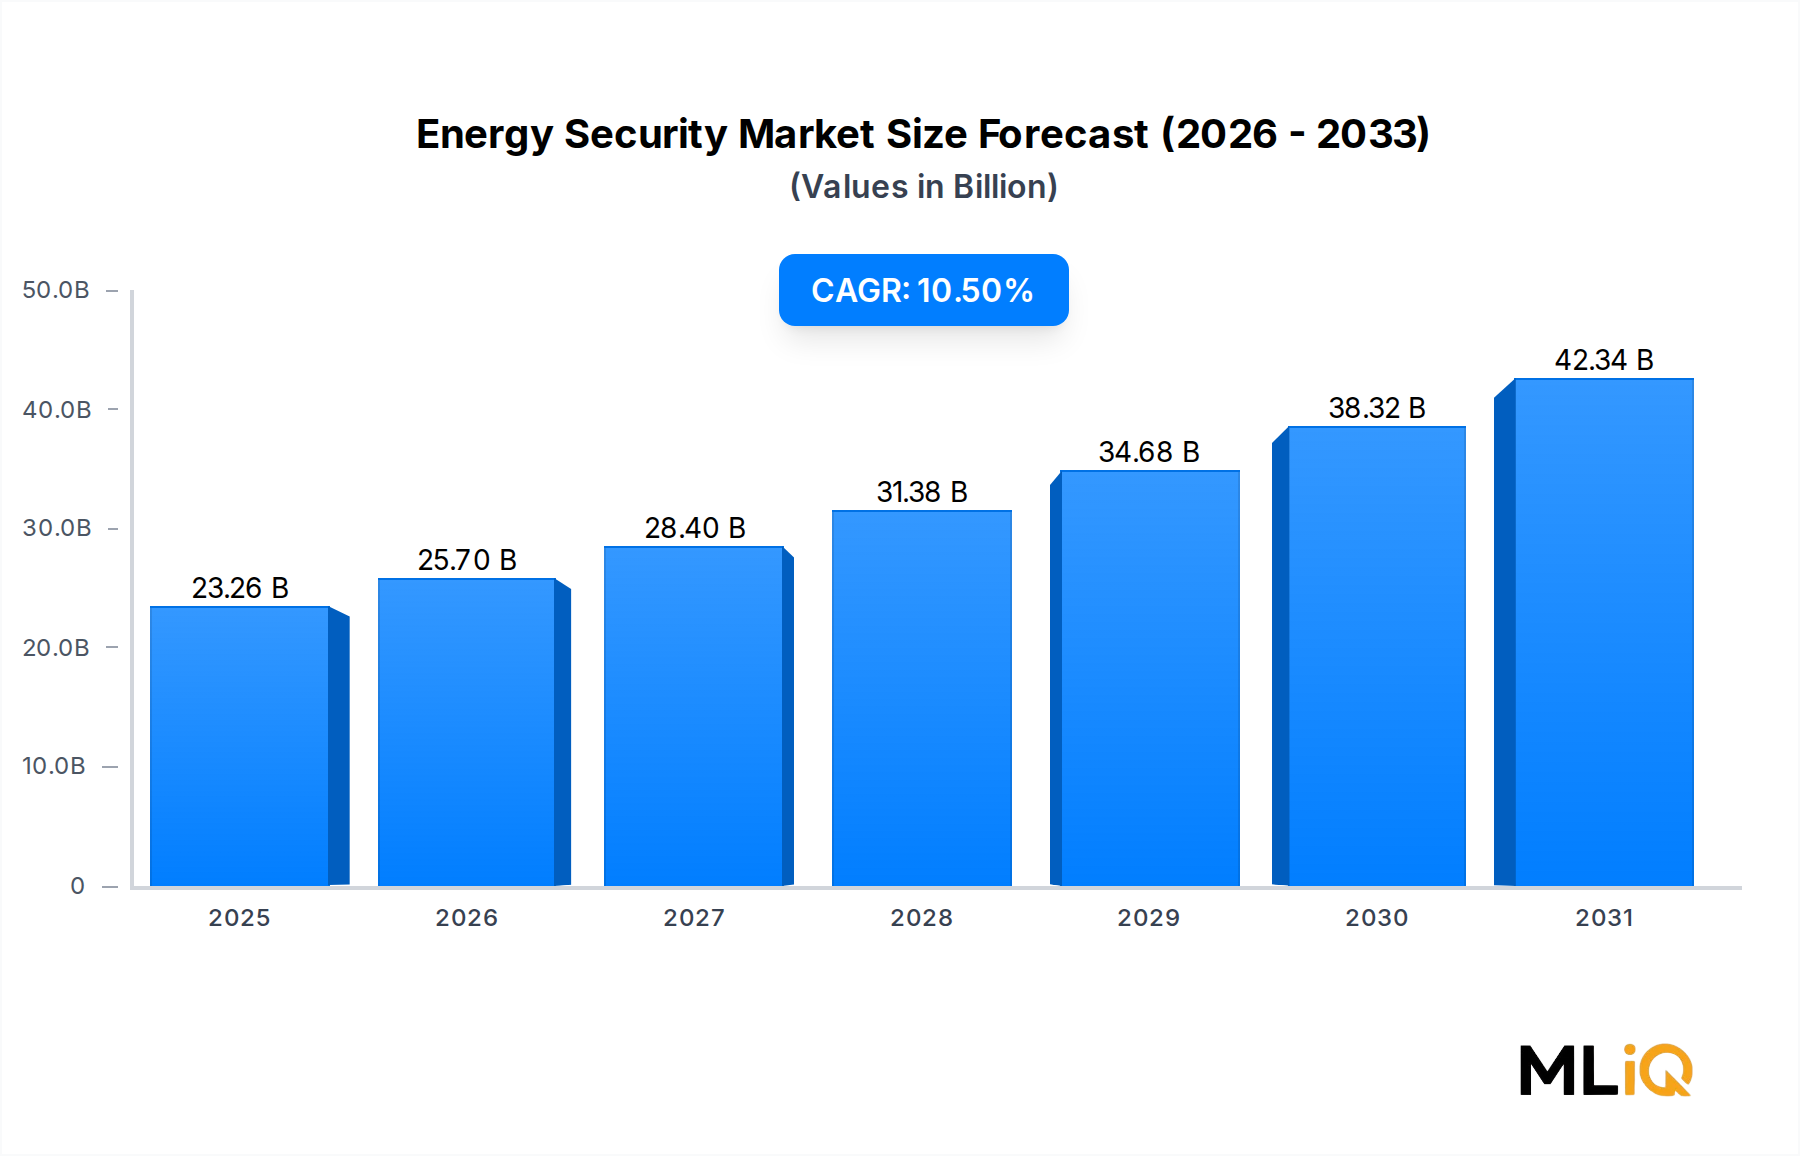
The Energy Security Market is valued at USD 23.26 billion in 2025 and is projected to reach USD 51.70 billion by 2033, expanding at a 10.5% CAGR. Growth is driven by grid digitization, stricter cyber-physical protection rules, and state-linked attacks on power assets. The Critical Infrastructure Protection Market is growing faster than general industrial security because utilities must defend both perimeter assets and operational technology networks.
Energy Security Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
23.26 B
2025
25.70 B
2026
28.40 B
2027
31.38 B
2028
34.68 B
2029
38.32 B
2030
42.34 B
2031
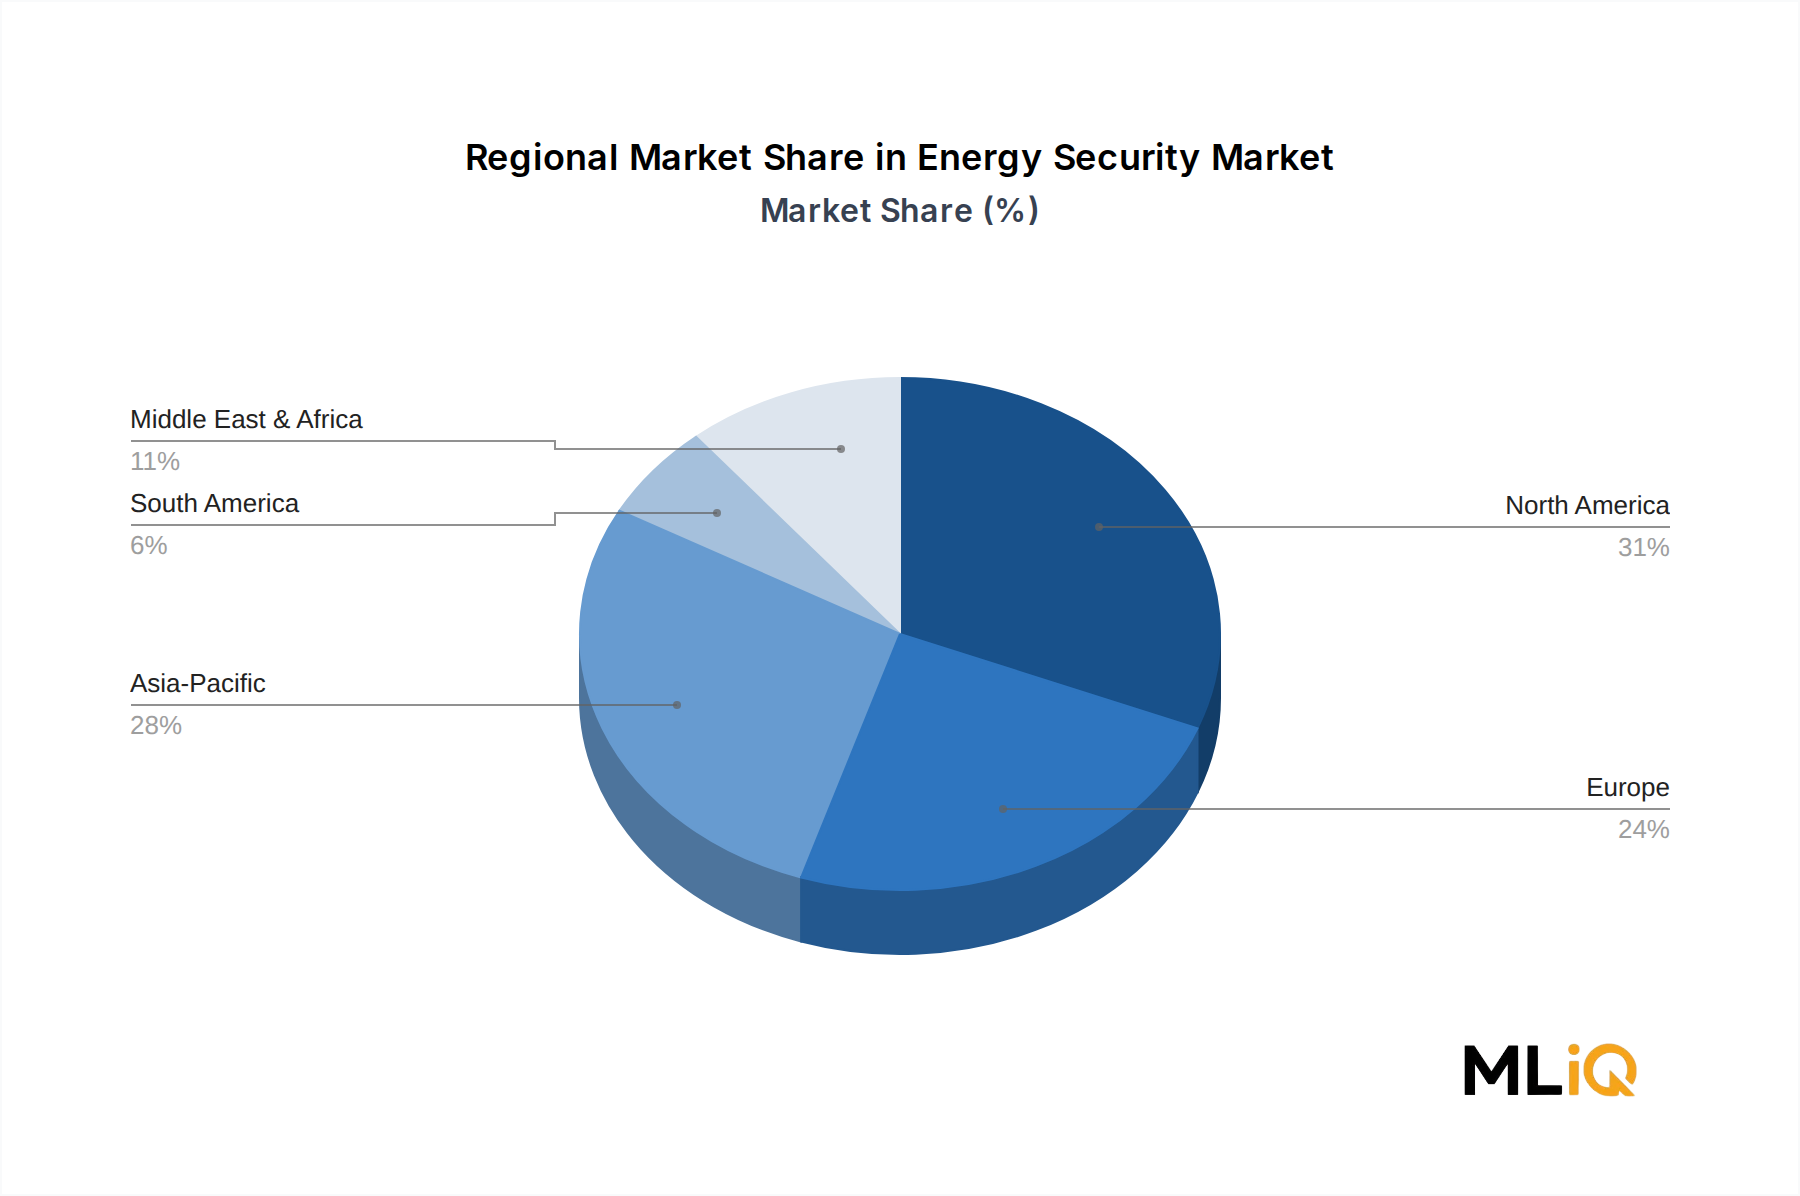
North America remains the largest region at USD 7.21 billion in 2025, supported by NERC CIP audits and grid modernization programs.
Asia-Pacific is the fastest-growing region at 12.4% CAGR, led by China State Grid, India's distribution reforms, and ASEAN transmission upgrades.
Solution component holds 58% revenue share; Service is growing faster at 11.4% CAGR as utilities outsource security operations.
Network Security outpaces physical hardware with a 12.1% CAGR versus 9.6% for perimeter-focused systems.
Market momentum is also tied to energy transition spending. Renewable capacity additions require remote monitoring, inverter security, and distributed grid protection, pulling new demand into the Energy Security Market. At the same time, nuclear operators and oil and gas firms are upgrading legacy control rooms to meet regulatory audits. The result is a market that is no longer only about cameras and fences; it is increasingly about continuous monitoring, identity control, and incident response across IT and OT.
Key constraints include long utility procurement cycles, limited OT security talent, and interoperability issues with installed SCADA systems. These factors slow deal closures but also raise contract values because vendors must integrate with existing infrastructure. Between 2025 and 2033, the most successful vendors will combine hardware, software, and managed services rather than sell standalone products.
Segment Deep-Dive: Solution Component Dominance in Energy Security Market
The Solution component dominates the Energy Security Market with an estimated 58% revenue share in 2025. It includes physical security systems, network security platforms, analytics, and control system protection. Service is smaller at 42% but expands faster because utilities lack internal OT security staff and rely on managed detection and response contracts.
Segment
CAGR (%)
Market Share (%)
Key Demand Driver
Solution (Component)
10.8
58
Integrated cyber-physical platforms for grid and plant control
Perimeter intrusion detection at substations and plants
Renewable Energy Security Market (Power Plant)
13.4
18
Distributed solar and wind asset protection
Solution Sub-Segment Dynamics
Network Security Market is the fastest-growing technology sub-segment, reaching 12.1% CAGR, as utilities deploy firewalls, anomaly detection, and secure remote access for field devices.
Physical Security Market remains the largest technology category by revenue, but growth is slower at 9.6% because camera and access control hardware is mature and increasingly commoditized.
Nuclear Power Plant Security Market carries higher entry barriers due to IAEA safeguards, national regulator inspections, and redundant command-and-control requirements.
Renewable Energy Security Market grows at 13.4% CAGR because solar farms, wind assets, and battery storage sites need remote cyber monitoring and perimeter protection with fewer on-site staff.
Margin Pressures
Hardware margins are under pressure from Chinese camera suppliers, open-source video management software, and competitive bidding in price-sensitive regions. Software and service margins remain stronger, often 35–45% gross margin for managed SOC contracts. Vendors face rising R&D costs for AI-based threat detection and compliance modules, which favors larger firms with installed bases. Small vendors can compete in niche consulting and integration but struggle to scale across multiple regulatory regimes.
Sub-segment demand also varies by power plant type. Thermal and hydro plants prioritize perimeter and access control, nuclear sites demand redundant cyber-physical security, and oil and gas facilities require explosion-proof cameras and pipeline monitoring. This fragmentation prevents a single product from serving all buyers, supporting the shift toward platform-based solutions.
Primary Market Drivers & Growth Restraints in Energy Security Market
Regulatory pressure and attack frequency are the strongest drivers. NERC CIP in North America, the EU NIS2 Directive, and IAEA nuclear security guidance set mandatory controls for critical assets. At the same time, ransomware incidents against utilities have increased, pushing boards to approve security budgets even when electricity demand growth is flat.
Factor Type
Description
Impact Level
Timeline
Driver
Regulatory mandates (NERC CIP, NIS2, IAEA)
High
Short term
Driver
Rising cyberattacks on the Grid Security Market
High
Short term
Driver
Energy transition and renewable expansion
High
Long term
Driver
Oil and Gas Security Market demand for LNG and pipeline monitoring
High
Medium term
Restraint
High integration cost with legacy OT systems
High
Short term
Restraint
Shortage of certified OT security engineers
Medium
Long term
Restraint
Budget competition within utility IT and operations
Medium
Short term
Restraint
Vendor lock-in and interoperability issues
Medium
Long term
Quantitative Evaluation
The average utility security budget rose from 4.1% of IT spend in 2022 to 6.3% in 2025, with cyber-physical projects taking the largest incremental share.
A single NERC CIP audit can cost USD 250,000–USD 600,000 in documentation, testing, and external validation, creating recurring demand for compliance services.
The Grid Security Market benefits from mandates to protect high-voltage substations, where a one-day outage can cost regional economies USD 10–20 million.
Oil and Gas Security Market growth is tied to LNG terminal expansions and pipeline monitoring, with security spending rising 8.9% annually across midstream assets.
Restraints do not eliminate demand; they shift spending toward vendors that can reduce integration risk. Utilities prefer suppliers with proven interoperability with Siemens, ABB, and Honeywell control systems. This preference slows new entrants but strengthens incumbents that can bundle hardware, software, and compliance expertise.
Competitive Ecosystem & Key Vendor Profiles: Energy Security Market
The vendor base combines diversified industrial firms, defense contractors, and specialized security technology providers. Competition is strongest in the Industrial Cybersecurity Market, where IT security vendors, OT specialists, and automation incumbents compete for utility budgets. Honeywell, Siemens, ABB, and Thales lead large-scale programs, while Teledyne FLIR and AEGIS Security & Investigations serve narrower physical security and investigation niches.
Company Name
Core Strength
Target Audience
Market Position
Honeywell International Inc.
Integrated OT security and process control
Utilities, oil and gas, nuclear
Leader
Siemens AG
Grid automation, SCADA, and digital twin security
Transmission and distribution utilities
Leader
ABB Ltd.
Substation automation and protection relays
Electric utilities, industrial plants
Leader
Thales
Data security, encryption, and identity
Government, critical infrastructure
Leader
BAE Systems plc
Defense-grade cyber and intelligence
National grids, defense agencies
Challenger
Lockheed Martin Corporation
Cyber range, mission-critical defense
Government, nuclear operators
Challenger
Elbit Systems Ltd.
Surveillance and perimeter defense
Border, energy, critical sites
Challenger
Teledyne FLIR LLC
Thermal imaging and perimeter detection
Substations, renewable sites
Niche
AEGIS Security & Investigations
Security consulting and investigations
Private utilities, corporate campuses
Niche
Hexagon AB
Geospatial and asset monitoring
Infrastructure operators
Challenger
Honeywell International Inc.: Combines process control knowledge with OT cybersecurity, making it a default shortlist vendor for large utilities and refineries.
Siemens AG: Leverages its grid automation installed base to sell security as part of digital substation and SCADA upgrades.
ABB Ltd.: Strong in substation protection and remote monitoring, especially where IEC 61850 deployments require security integration.
Thales: Uses encryption, identity, and data security capabilities to serve government and critical infrastructure buyers.
BAE Systems plc: Positions defense-grade cyber monitoring for national grid and nuclear programs with high assurance requirements.
Lockheed Martin Corporation: Provides cyber training ranges and mission-critical defense expertise for government-linked energy assets.
Elbit Systems Ltd.: Supplies surveillance, sensors, and command-and-control for perimeter-heavy energy and border sites.
Teledyne FLIR LLC: Focuses on thermal cameras and intrusion detection for substations, solar farms, and remote assets.
AEGIS Security & Investigations: Delivers consulting, threat assessment, and investigations for private utility and corporate clients.
Hexagon AB: Applies geospatial and asset monitoring software to map and protect distributed infrastructure.
Strategic Milestones & Recent Developments in Energy Security Market
Strategic activity is concentrated in cybersecurity portfolio expansion, grid monitoring launches, and partnerships that combine OT knowledge with cloud analytics.
Date
Company
Event Type
Impact
Q4 2024
Thales
M&A
Completed Imperva acquisition, strengthening data and application security for utility IT/OT convergence
Q1 2025
Honeywell International Inc.
Launch
Updated OT cybersecurity dashboard for power generation and oil and gas
Q1 2025
Siemens AG
Partnership
Expanded grid software alliances with utility automation integrators
Q2 2025
ABB Ltd.
Launch
Cloud-based substation security monitoring for transmission operators
Q2 2025
Teledyne FLIR LLC
Launch
Thermal perimeter cameras for renewable energy sites
Q3 2025
Lockheed Martin Corporation
Partnership
Co-developed cyber range for grid defense training
Q4 2024: Thales closed the Imperva acquisition, adding application and data security to its critical infrastructure portfolio and increasing competitive pressure on pure-play OT vendors.
Q1 2025: Honeywell released an updated OT security dashboard that consolidates alerts from substations, turbines, and pipeline controls, targeting utilities with mixed legacy assets.
Q1 2025: Siemens expanded alliances with automation integrators to embed security into digital substation projects, shortening deployment time for NERC CIP compliance.
Q2 2025: ABB introduced cloud-based monitoring for substation protection relays, allowing operators to detect configuration changes and unauthorized access remotely.
Q2 2025: Teledyne FLIR launched thermal perimeter cameras designed for solar and wind sites, addressing remote asset protection with lower staffing requirements.
Q3 2025: Lockheed Martin partnered to build a cyber range for grid defense training, helping utilities simulate attacks on SCADA and OT networks.
Regional Market Analysis & Growth Corridors for Energy Security Market
Regional demand varies by regulatory stringency, grid age, and energy mix. North America leads in revenue, Europe follows with strict cyber rules, and Asia-Pacific grows fastest due to new capacity and grid expansion.
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
9.8
USD 7.21 billion
NERC CIP audits, aging grid replacement
High
Europe
10.2
USD 5.58 billion
NIS2 Directive, cross-border grid coupling
High
Asia-Pacific
12.4
USD 6.51 billion
China State Grid, India distribution reforms, ASEAN transmission
Medium to high
South America
10.9
USD 1.40 billion
Brazil hydro and transmission upgrades, Argentina gas infrastructure
Medium
Middle East & Africa
11.6
USD 2.56 billion
GCC nuclear new-build, LNG terminals, smart city grids
Medium
Fastest-Growing vs. Most Mature Markets
Asia-Pacific is the fastest-growing region at 12.4% CAGR, driven by China's State Grid investment and India's push to secure 500 GW of renewable capacity by 2030.
North America is the most mature market at USD 7.21 billion, with replacement demand for substation security and mandatory CIP compliance cycles.
Europe grows at 10.2% CAGR, supported by NIS2, the European Grid Initiative, and cross-border electricity trade that requires common security standards.
Middle East & Africa is a high-value corridor for nuclear and LNG projects, with Turkey, Israel, and GCC states investing in perimeter and cyber defense.
South America remains smaller at USD 1.40 billion, but Brazil's hydro and transmission auctions create steady demand for remote monitoring and access control.
Export, Cross-Border Trade & Tariff Impact on Energy Security Market
Cross-border trade in energy security equipment and services follows three main corridors: North America-to-Europe for high-assurance cyber technology, China-to-Asia-Pacific for cameras and network hardware, and Israel-to-global for surveillance and perimeter systems. Tariffs and export controls have become a material cost factor.
The United States and European Union have tightened export controls on advanced semiconductors and network security equipment, adding 10–15% to procurement costs for some utility projects.
China remains the largest exporter of surveillance cameras, access control hardware, and optical components, but national security reviews in the United States and India limit adoption at critical sites.
The US-Mexico-Canada Agreement supports cross-border grid security services, while the EU's single market allows security hardware to move freely if it meets CE and NIS2 requirements.
Middle East importers rely on US, European, and Israeli vendors for nuclear and LNG security, with tariff exemptions common under defense and critical infrastructure programs.
Non-tariff barriers matter more than tariffs in this market. Certification requirements, data localization rules, and government procurement preferences can delay entry by 12–24 months. Vendors that localize assembly and data processing reduce political risk and improve win rates in Asia-Pacific and the GCC. The net impact of trade policy is higher prices and slower cross-border shipment growth, but not a decline in total demand, because regulatory mandates force utilities to buy compliant systems regardless of origin.
Supply Chain & Raw Material Dynamics: Energy Security Market
Upstream dependencies shape cost and delivery timelines. Energy security systems rely on semiconductors, rare earth magnets, lithium batteries, copper wiring, and hardened steel enclosures. The Semiconductor Sensor Market is central because thermal cameras, gas detectors, and vibration sensors require specialized chips.
Input
Supply Risk
Price Trend (2025)
Dependency
Semiconductor sensors
Medium
Stable after 2023 shortage
Taiwan, South Korea, US fabs
Rare earth magnets
High
Up 8–14% YoY
China-dominated processing
Lithium-ion batteries
Medium
Down 6% YoY
Australia, Chile, China
Copper wiring
Low to medium
Up 12% YoY
Chile, Peru, DRC
Hardened steel enclosures
Low
Flat to up 3%
Regional steel mills
The Semiconductor Sensor Market improved from 52-week lead times in 2022 to 18–24 weeks in 2025, but advanced image sensors and secure microcontrollers still face allocation constraints.
Rare earth magnets used in cameras, motors, and access control systems remain exposed to Chinese export quotas, with prices rising 8–14% year over year.
Lithium battery prices fell 6% in 2025, easing cost pressure on remote substation monitoring and backup power for security devices.
Copper prices increased 12% due to grid investment and electrification demand, raising cabling costs for perimeter and substation security projects.
Vendor dependencies are concentrated: many physical security OEMs rely on a small group of image sensor suppliers, while OT security vendors depend on Intel and AMD embedded processors.
Utilities are responding by dual-sourcing sensors, requiring 10–15% buffer inventory for critical components, and designing modular systems that accept multiple chip sets. These measures raise working capital but reduce outage risk. Supply chain resilience is now a procurement criterion, not just a cost issue. Vendors that can document alternate sourcing and secure firmware provenance gain an advantage in regulated tenders.
Energy Security Market Segmentation
1. Component
1.1. Solution
1.2. Service
2. Technology
2.1. Physical Security
2.2. Network Security
3. Power Plant
3.1. Thermal and hydro
3.2. Nuclear
3.3. Oil and gas
3.4. Renewable Energy
Energy Security Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Energy Security Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.5% from 2020-2034
Segmentation
By Component
Solution
Service
By Technology
Physical Security
Network Security
By Power Plant
Thermal and hydro
Nuclear
Oil and gas
Renewable Energy
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Solution
5.1.2. Service
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. Physical Security
5.2.2. Network Security
5.3. Market Analysis, Insights and Forecast - by Power Plant
5.3.1. Thermal and hydro
5.3.2. Nuclear
5.3.3. Oil and gas
5.3.4. Renewable Energy
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Solution
6.1.2. Service
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. Physical Security
6.2.2. Network Security
6.3. Market Analysis, Insights and Forecast - by Power Plant
6.3.1. Thermal and hydro
6.3.2. Nuclear
6.3.3. Oil and gas
6.3.4. Renewable Energy
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Solution
7.1.2. Service
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. Physical Security
7.2.2. Network Security
7.3. Market Analysis, Insights and Forecast - by Power Plant
7.3.1. Thermal and hydro
7.3.2. Nuclear
7.3.3. Oil and gas
7.3.4. Renewable Energy
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Solution
8.1.2. Service
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. Physical Security
8.2.2. Network Security
8.3. Market Analysis, Insights and Forecast - by Power Plant
8.3.1. Thermal and hydro
8.3.2. Nuclear
8.3.3. Oil and gas
8.3.4. Renewable Energy
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Solution
9.1.2. Service
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. Physical Security
9.2.2. Network Security
9.3. Market Analysis, Insights and Forecast - by Power Plant
9.3.1. Thermal and hydro
9.3.2. Nuclear
9.3.3. Oil and gas
9.3.4. Renewable Energy
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Solution
10.1.2. Service
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. Physical Security
10.2.2. Network Security
10.3. Market Analysis, Insights and Forecast - by Power Plant
10.3.1. Thermal and hydro
10.3.2. Nuclear
10.3.3. Oil and gas
10.3.4. Renewable Energy
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Honeywell International Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. hexagon ab
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Thales
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. BAE Systems plc
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Siemens AG
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Elbit Systems Ltd.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Teledyne FLIR LLC
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. ABB Ltd.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. AEGIS Security & Investigations
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Lockheed Martin Corporation
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Energy Security Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Energy Security Market Revenue (billion), by Component 2026 & 2034
Figure 3: North America Energy Security Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Energy Security Market Revenue (billion), by Technology 2026 & 2034
Figure 5: North America Energy Security Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Energy Security Market Revenue (billion), by Power Plant 2026 & 2034
Figure 7: North America Energy Security Market Revenue Share (%), by Power Plant 2026 & 2034
Figure 8: North America Energy Security Market Revenue (billion), by Country 2026 & 2034
Figure 9: North America Energy Security Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Energy Security Market Revenue (billion), by Component 2026 & 2034
Figure 11: South America Energy Security Market Revenue Share (%), by Component 2026 & 2034
Figure 12: South America Energy Security Market Revenue (billion), by Technology 2026 & 2034
Figure 13: South America Energy Security Market Revenue Share (%), by Technology 2026 & 2034
Figure 14: South America Energy Security Market Revenue (billion), by Power Plant 2026 & 2034
Figure 15: South America Energy Security Market Revenue Share (%), by Power Plant 2026 & 2034
Figure 16: South America Energy Security Market Revenue (billion), by Country 2026 & 2034
Figure 17: South America Energy Security Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Energy Security Market Revenue (billion), by Component 2026 & 2034
Figure 19: Europe Energy Security Market Revenue Share (%), by Component 2026 & 2034
Figure 20: Europe Energy Security Market Revenue (billion), by Technology 2026 & 2034
Figure 21: Europe Energy Security Market Revenue Share (%), by Technology 2026 & 2034
Figure 22: Europe Energy Security Market Revenue (billion), by Power Plant 2026 & 2034
Figure 23: Europe Energy Security Market Revenue Share (%), by Power Plant 2026 & 2034
Figure 24: Europe Energy Security Market Revenue (billion), by Country 2026 & 2034
Figure 25: Europe Energy Security Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Energy Security Market Revenue (billion), by Component 2026 & 2034
Figure 27: Middle East & Africa Energy Security Market Revenue Share (%), by Component 2026 & 2034
Figure 28: Middle East & Africa Energy Security Market Revenue (billion), by Technology 2026 & 2034
Figure 29: Middle East & Africa Energy Security Market Revenue Share (%), by Technology 2026 & 2034
Figure 30: Middle East & Africa Energy Security Market Revenue (billion), by Power Plant 2026 & 2034
Figure 31: Middle East & Africa Energy Security Market Revenue Share (%), by Power Plant 2026 & 2034
Figure 32: Middle East & Africa Energy Security Market Revenue (billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Energy Security Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Energy Security Market Revenue (billion), by Component 2026 & 2034
Figure 35: Asia Pacific Energy Security Market Revenue Share (%), by Component 2026 & 2034
Figure 36: Asia Pacific Energy Security Market Revenue (billion), by Technology 2026 & 2034
Figure 37: Asia Pacific Energy Security Market Revenue Share (%), by Technology 2026 & 2034
Figure 38: Asia Pacific Energy Security Market Revenue (billion), by Power Plant 2026 & 2034
Figure 39: Asia Pacific Energy Security Market Revenue Share (%), by Power Plant 2026 & 2034
Figure 40: Asia Pacific Energy Security Market Revenue (billion), by Country 2026 & 2034
Figure 41: Asia Pacific Energy Security Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Energy Security Market Revenue billion Forecast, by Component 2020 & 2034
Table 2: Energy Security Market Revenue billion Forecast, by Technology 2020 & 2034
Table 3: Energy Security Market Revenue billion Forecast, by Power Plant 2020 & 2034
Table 4: Energy Security Market Revenue billion Forecast, by Region 2020 & 2034
Table 5: North America Energy Security Market Revenue billion Forecast, by Component 2020 & 2034
Table 6: North America Energy Security Market Revenue billion Forecast, by Technology 2020 & 2034
Table 7: North America Energy Security Market Revenue billion Forecast, by Power Plant 2020 & 2034
Table 8: North America Energy Security Market Revenue billion Forecast, by Country 2020 & 2034
Table 9: United States Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 10: Canada Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: South America Energy Security Market Revenue billion Forecast, by Component 2020 & 2034
Table 13: South America Energy Security Market Revenue billion Forecast, by Technology 2020 & 2034
Table 14: South America Energy Security Market Revenue billion Forecast, by Power Plant 2020 & 2034
Table 15: South America Energy Security Market Revenue billion Forecast, by Country 2020 & 2034
Table 16: Brazil Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: Argentina Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Rest of South America Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 19: Europe Energy Security Market Revenue billion Forecast, by Component 2020 & 2034
Table 20: Europe Energy Security Market Revenue billion Forecast, by Technology 2020 & 2034
Table 21: Europe Energy Security Market Revenue billion Forecast, by Power Plant 2020 & 2034
Table 22: Europe Energy Security Market Revenue billion Forecast, by Country 2020 & 2034
Table 23: United Kingdom Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Germany Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 25: France Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 26: Italy Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Spain Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Russia Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: Benelux Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: Nordics Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Europe Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Energy Security Market Revenue billion Forecast, by Component 2020 & 2034
Table 33: Middle East & Africa Energy Security Market Revenue billion Forecast, by Technology 2020 & 2034
Table 34: Middle East & Africa Energy Security Market Revenue billion Forecast, by Power Plant 2020 & 2034
Table 35: Middle East & Africa Energy Security Market Revenue billion Forecast, by Country 2020 & 2034
Table 36: Turkey Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: Israel Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: GCC Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: North Africa Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: South Africa Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 41: Rest of Middle East & Africa Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: Asia Pacific Energy Security Market Revenue billion Forecast, by Component 2020 & 2034
Table 43: Asia Pacific Energy Security Market Revenue billion Forecast, by Technology 2020 & 2034
Table 44: Asia Pacific Energy Security Market Revenue billion Forecast, by Power Plant 2020 & 2034
Table 45: Asia Pacific Energy Security Market Revenue billion Forecast, by Country 2020 & 2034
Table 46: China Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 47: India Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 48: Japan Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 49: South Korea Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 50: ASEAN Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 51: Oceania Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Energy Security Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We allocate 70–80% of research effort to primary research and 20–30% to secondary research, ensuring direct validation from market participants.
Primary interviews target SCADA/ICS cybersecurity software vendors for substation automation, physical security camera and access control OEMs for thermal, hydro, and nuclear plants, grid automation sensor and remote terminal unit (RTU) manufacturers, EPC firms specializing in nuclear and LNG security integration, and managed security service providers operating utility security operations centers (SOCs).
We interview Utility Chief Information Security Officers (CISOs), Grid Modernization Program Directors, Nuclear Plant Security Managers, and Oil and Gas OT Security Leads to capture procurement criteria, deployment timelines, and budget authority.
Interview programs cover North America, Europe, Asia-Pacific, South America, and Middle East & Africa, with quotas by power plant type and technology segment.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Utility Chief Information Security Officer (CISO)
30%
Grid Modernization Program Director
25%
Nuclear Plant Security Manager
20%
Oil and Gas OT Security Lead
15%
Energy Regulator Compliance Analyst
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
SCADA/ICS cybersecurity software vendors
28%
Physical security and access control OEMs
22%
Grid automation sensor and RTU manufacturers
18%
EPC and nuclear plant security integrators
17%
Utility SOC and managed security service providers
15%
Secondary Research & Industry Benchmarking
Secondary sources include Bloomberg, Factiva, Hoovers, and PitchBook, alongside regulatory filings, utility capital plans, and national energy statistics.
We do not use market research websites as primary inputs; all third-party data is traced to original regulatory, utility, or vendor disclosures.
Every report is updated to the date of purchase, with revised forecasts if regulatory or tariff conditions change.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation across segment, region, and company-level inputs.
Bottom-up models calculate market size using number of substations above 100 kV per region, installed nuclear reactor units by country, average cybersecurity spend per MW of installed generation capacity, and replacement cycle of legacy RTUs and protection relays (years).
Top-down models reconcile global energy security spending against utility IT/OT budgets, regulatory audit volumes, and vendor revenue disclosures.
Segment models separate Component (Solution, Service), Technology (Physical Security, Network Security), and Power Plant (Thermal and hydro, Nuclear, Oil and gas, Renewable Energy).
Regional models apply country-level grid investment, outage cost, and compliance intensity factors to allocate demand across North America, South America, Europe, Middle East & Africa, and Asia Pacific.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, supported by cross-validation of primary interview data against financial filings and regulatory records.
Multi-level triangulation compares bottom-up demand estimates with top-down budget envelopes and independent trade statistics.
Outlier detection removes anomalous responses, and every market size figure is pressure-tested against historical growth and installed-base constraints.
Final forecasts are reviewed by senior analysts for consistency with NERC CIP, NIS2, IAEA, and national energy security requirements before publication.
Frequently Asked Questions
1. How high are barriers to entry in the Energy Security Market?
Barriers are high because utilities require NERC CIP and IEC 62443 compliance, multi-year certification, and proof of interoperability with legacy SCADA. Incumbents such as Siemens and Honeywell hold installed-base advantages across 60%+ of large generation assets. New entrants face 18–24 month utility procurement cycles and mandatory reference deployments.
2. What end-user industries drive downstream demand in the Energy Security Market?
Electric utilities, nuclear operators, oil and gas majors, and renewable asset managers account for the largest share. Thermal and hydro plants represent about 34% of power plant security spending, while nuclear adds 22% due to stricter IAEA and national regulator requirements. Oil and gas midstream and LNG terminals drive demand for perimeter and OT network monitoring.
3. How are purchasing trends shifting in the Energy Security Market?
Buyers are moving from standalone physical security hardware to integrated cyber-physical platforms with managed services. Subscription and outcome-based contracts grew from 19% of new awards in 2022 to an estimated 31% in 2025. Utilities increasingly require vendor SOC integration and 24/7 incident response rather than one-time product sales.
4. What is the current market size and CAGR projection for the Energy Security Market?
The Energy Security Market is valued at USD 23.26 billion in 2025 and is projected to reach USD 51.70 billion by 2033, expanding at a 10.5% CAGR. Growth is led by the Solution component, which holds roughly 58% revenue share. Network Security is the fastest-growing technology sub-segment at a 12.1% CAGR.
5. How do regulations shape the Energy Security Market?
Mandates such as NERC CIP in North America, the EU NIS2 Directive, and IAEA nuclear security guidance set minimum security controls and audit requirements. Compliance costs can add 7–12% to utility security budgets, but they also create recurring demand for monitoring, reporting, and certification services. Non-compliance penalties for critical infrastructure operators can exceed USD 1 million per day in severe cases.
6. Which region is fastest-growing and where are emerging opportunities?
Asia-Pacific is the fastest-growing region, with a projected 12.4% CAGR, driven by grid expansion in China, India, and ASEAN. Emerging opportunities include renewable energy security in India, nuclear new-build security in Turkey and the GCC, and cross-border grid protection in the Nordics and Benelux. North America remains the largest market at USD 7.21 billion in 2025.