Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
How Japan Big Data Market Reaches $2B by 2033
Japan Big Data Market
How Japan Big Data Market Reaches $2B by 2033
Japan Big Data Market by Component (Hardware, Software, Service), by Deployment Mode (On Premise, Cloud), by Enterprise Size (SMEs, Large Enterprise), by Business Function (Marketing and Sales, Finance, Human Resources, Operations), by Industry Vertical (BFSI, Government and Defense, Healthcare and Life Sciences, Manufacturing, Retail and Consumer Goods, Media and Entertainment, Telecommunications and IT, Transportation and Logistics, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 0
Key Insights & Executive Summary: Japan Big Data Market
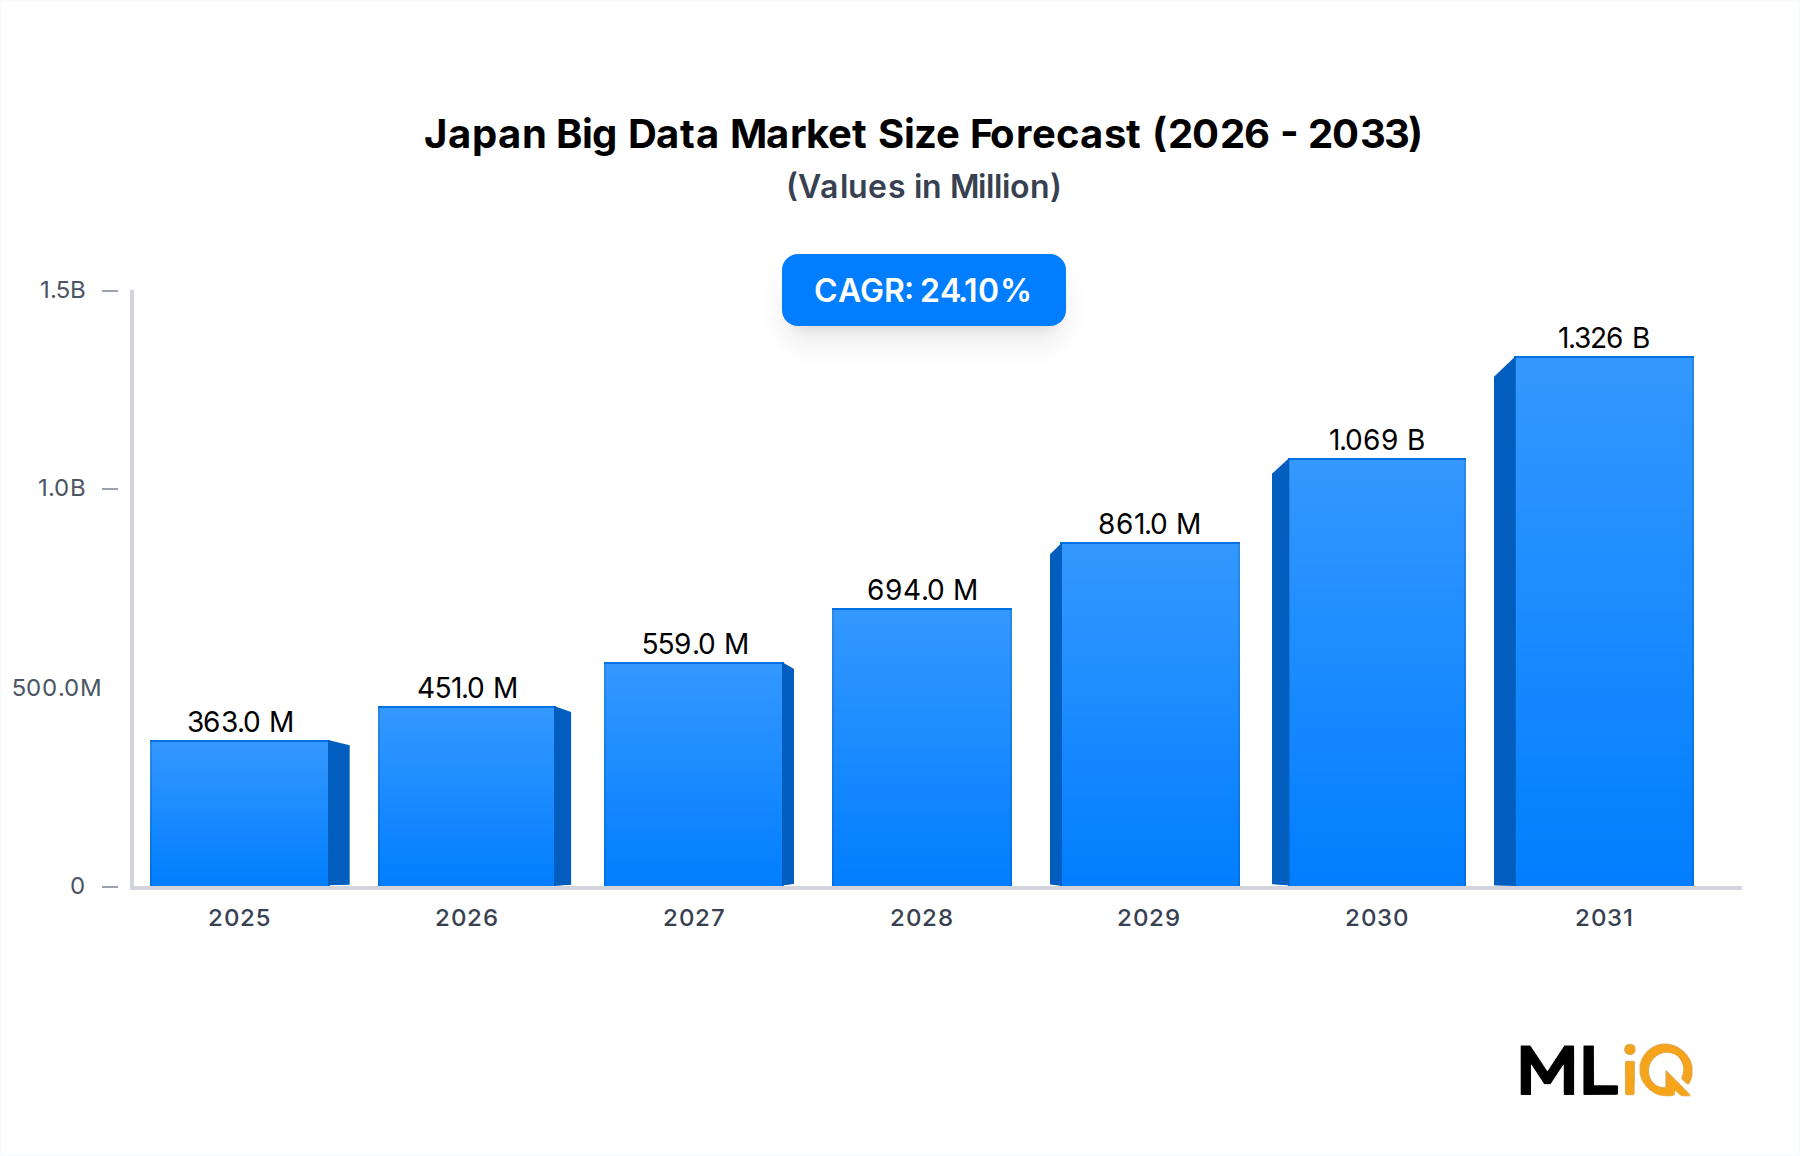
The Japan Big Data Market is valued at $292.7 million in 2024 and is projected to reach $2,042.7 million by 2033, expanding at a 24.09% CAGR. This growth is underpinned by enterprise digitization, cloud migration, and regulatory-driven data governance. Japan ICT Market spending on AI and analytics is rising as manufacturers, banks, and retailers seek operational efficiency.
Japan Big Data Market Size (In Million)
1.5B
1.0B
500.0M
0
363.0 M
2025
451.0 M
2026
559.0 M
2027
694.0 M
2028
861.0 M
2029
1.069 B
2030
1.326 B
2031
Cloud adoption is the fastest structural shift. The Japan Cloud Big Data Infrastructure Market is growing as hyperscalers open local regions and enterprises retire on-premise Hadoop clusters. Data warehouse modernization is equally critical: the Japan Data Warehousing Market is moving from legacy appliances to lakehouse architectures, enabling real-time analytics for BFSI and retail.
BFSI and manufacturing account for over 45% of big data software spend.
Software dominates with 52% revenue share, followed by services at 31% and hardware at 17%.
Tokyo, Osaka, and Fukuoka are primary data center corridors.
Key headwinds include a shortage of data engineers, high electricity costs for data centers, and strict cross-border data transfer rules under APPI. Still, Japan's Digital Agency and METI's semiconductor strategy support long-term investment. The market remains concentrated among global platform vendors and domestic SIs, with niche opportunities in industry-specific analytics. Japan Data Warehousing Market adoption is expected to accelerate as lakehouse platforms reduce total cost of ownership by 22-30% versus legacy systems.
Segment Deep-Dive: Software Dominance in Japan Big Data Market
Segment Analysis Matrix
CAGR (%)
Market Share (%)
Key Demand Driver
Software
26.5
52
Real-time analytics, AI model deployment
Services
22.1
31
Data integration, governance, managed analytics
Hardware
18.4
17
Server, storage, and network refresh
The Japan Big Data Analytics Software Market is the largest and fastest-growing component. It includes data integration, visualization, predictive analytics, and AI platforms. Demand is driven by BFSI fraud detection, manufacturing quality control, and retail personalization.
Sub-segment dynamics
Data integration and quality tools grow at 25.8% CAGR as enterprises consolidate silos.
Visualization and BI remain mature, growing at 17.9%, with replacement demand from legacy tools.
AI and machine learning platforms within the software segment grow at 31.2%, the highest sub-segment.
The Japan Big Data Services Market is expanding through managed services and consulting. System integrators such as Hitachi, IBM, and Teradata provide APPI-compliant data governance. Cloud services are increasingly bundled with platform subscriptions.
The Japan BFSI Big Data Market is a leading vertical, with megabanks spending on risk analytics and anti-money laundering. Insurance firms use telematics and claims analytics. Margin pressure is high due to price competition from cloud-native vendors and open-source alternatives. Hardware refresh cycles are lengthening, but AI training workloads drive GPU-accelerated server demand.
Cloud deployment is cannibalizing on-premise licenses. The Japan Cloud Big Data Infrastructure Market grows at 28.4% CAGR, while on-premise grows at 11.2%. Large enterprises prefer hybrid models for sensitive data. SMEs lag in adoption due to skills and budget constraints, but government subsidies are narrowing the gap. The Japan Big Data Services Market will benefit from multi-cloud orchestration and FinOps demand.
Primary Market Drivers & Growth Restraints in Japan Big Data Market
Factor Type
Description
Impact Level
Timeline
Driver
Government Digital Transformation (Digital Agency)
High
Long term
Driver
Cloud region expansion by AWS, Azure, Oracle
High
Short term
Driver
APPI compliance and data governance mandates
High
Long term
Driver
Japan AI and Machine Learning Market growth
High
Short term
Restraint
Data engineer shortage
High
Long term
Restraint
High data center energy costs
Medium
Short term
Restraint
Cross-border data transfer restrictions
Medium
Long term
Restraint
Legacy system integration complexity
High
Short term
Japan's Digital Agency mandates cloud-first infrastructure, boosting demand for scalable analytics. The Japan AI and Machine Learning Market expands at 29.7% CAGR, pulling big data platforms into model training and inference workflows. APPI amendments require consent management and audit trails, increasing software spend.
The Japan Healthcare Big Data Market is a high-growth vertical, with hospitals adopting electronic health records and real-world evidence platforms. BFSI remains the largest vertical at 29% share. Telecommunications and IT follow at 21%.
Restraints include a shortage of 9,000+ data engineers in Japan, according to industry estimates. Data center power costs are among the highest in Asia, pressuring cloud margins. Cross-border data rules limit global analytics consolidation. Legacy integration adds 15-20% to project costs. These factors moderate growth but do not reverse the upward trajectory.
Competitive Ecosystem & Key Vendor Profiles: Japan Big Data Market
Company Name
Core Strength
Target Audience
Market Position
IBM Corporation
watsonx, hybrid cloud
Large enterprise, BFSI
Leader
Oracle Corporation
Autonomous Data Warehouse, OCI
BFSI, telecom
Leader
Dell Corporation
Server, storage, data lake infrastructure
Manufacturing, retail
Leader
HPE
HPE GreenLake, edge-to-cloud
Government, healthcare
Challenger
Hitachi Data System
Lumada, industrial IoT analytics
Manufacturing, transport
Leader
Teradata
VantageCloud, data warehouse
BFSI, retail
Challenger
QBurst
Data engineering, AI consulting
SMEs, media
Niche
Finatext Ltd.
Financial data APIs, analytics
Fintech, BFSI
Niche
Rikkeisoft
Offshore development, data platforms
SMEs, IT services
Niche
ThinkPalm Technologies
Data analytics, IoT integration
Manufacturing, logistics
Niche
IBM Corporation: Expands watsonx with Japanese language models and APPI governance modules for regulated industries.
Oracle Corporation: Operates Japan East and Osaka cloud regions, bundling Autonomous Data Warehouse for BFSI clients.
Dell Corporation: Supplies PowerScale and PowerEdge systems to Japanese data centers, targeting AI training workloads.
HPE: Drives GreenLake consumption models for government and healthcare analytics.
Hitachi Data System: Integrates Lumada with manufacturing execution systems, serving automotive and electronics firms.
Teradata: Migrates legacy Teradata warehouses to VantageCloud on AWS and Azure in Japan.
QBurst: Provides data engineering and AI consulting for Japanese SMEs and media companies.
Finatext Ltd.: Offers financial data APIs and analytics to Japanese fintech and banking clients.
Rikkeisoft: Delivers offshore data platform development for Japanese SMEs and IT service providers.
ThinkPalm Technologies: Builds IoT and data analytics solutions for Japanese manufacturing and logistics.
Strategic Milestones & Recent Developments in Japan Big Data Market
Date
Company
Event Type
Impact
2024
IBM
Launch
Expanded watsonx capabilities in Japan with APPI compliance
2024
Oracle
Launch
Opened second cloud region in Japan to support data residency
2023
Hitachi Data System
Partnership
Lumada alliance with Japanese manufacturers for factory analytics
2023
Teradata
Partnership
VantageCloud availability on AWS Japan and Azure Japan
2023
Dell Corporation
Launch
PowerScale updates for AI and big data workloads
2023
HPE
Partnership
GreenLake expansion with Japanese system integrators
2024
Finatext Ltd.
Partnership
Financial data analytics collaboration with regional banks
2024
Rikkeisoft
Launch
Japan office for offshore data engineering services
2024: IBM deepened watsonx integration with Japanese language models, targeting BFSI and healthcare.
2024: Oracle expanded Japan cloud regions, enabling data residency for regulated industries.
2023: Hitachi Data System partnered with automotive manufacturers to deploy Lumada for quality analytics.
2023: Teradata made VantageCloud available on major Japanese clouds, easing migration.
2024: Finatext Ltd. collaborated with regional banks on open banking data analytics.
Regional Market Analysis & Growth Corridors for Japan Big Data Market
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
21.5
$1,420M
AI/cloud maturity
Medium
Europe
20.8
$980M
GDPR-driven governance
High
Asia-Pacific
26.3
$1,650M
Digital transformation, manufacturing
Medium-High
LAMEA
19.4
$410M
Telecom and BFSI modernization
Medium
Asia-Pacific is the fastest-growing region, led by China, Japan, and India. Japan contributes 18% of APAC big data revenue. North America remains the most mature market, with high adoption in BFSI and healthcare. Europe follows with strict data protection rules. LAMEA grows from a smaller base, with GCC countries investing in smart city analytics.
Fastest-growing: Asia-Pacific at 26.3% CAGR, driven by Japan and China's AI investments.
Most mature: North America, where cloud penetration exceeds 70% among large enterprises.
Japan focus: The Japan Healthcare Big Data Market is expected to grow at 27.8% CAGR through 2033.
Regulatory divergence: APPI, GDPR, and PIPL create compliance complexity for cross-border analytics.
Supply Chain & Raw Material Dynamics: Japan Big Data Market
Component
Key Suppliers
Price Trend
Risk Level
GPUs and AI accelerators
Nvidia, AMD, Intel
Rising 15-20% YoY
High
Server CPUs
Intel, AMD
Stable to rising
Medium
DRAM and NAND
Samsung, SK hynix, Micron
Volatile, up 10-25%
High
Storage arrays
Dell, HPE, Hitachi
Stable
Low
Network switches
Cisco, Arista, Huawei
Stable
Medium
Data center power
TEPCO, Kansai Electric
Rising 8-12%
High
The Japan Big Data Hardware Market depends on imported semiconductors and memory. Japan imports over 80% of advanced logic and memory chips, exposing local data center buildouts to global supply shocks. The 2021-2023 chip shortage delayed server deliveries by 12-20 weeks. GPU prices remain elevated due to AI demand, with Nvidia H100 and A100 lead times extending beyond 26 weeks in 2024.
Historical disruptions include the 2011 earthquake, 2020 pandemic, and 2024 Noto earthquake, which affected component logistics. Japan's semiconductor strategy aims to onshore advanced manufacturing through TSMC Kumamoto and Rapidus. Until then, price volatility in DRAM and NAND will pressure hardware margins. Data center electricity costs are rising, with Tokyo power prices up 10% in 2024.
Export, Cross-Border Trade & Tariff Impact on Japan Big Data Market
Trade Corridor
Flow Type
Volume Share
Tariff/Barrier
Japan to United States
Software, services, cloud
28%
Low tariff, data privacy rules
Japan to Europe
Analytics services, hardware
18%
GDPR adequacy, low tariff
Japan to China
Components, analytics software
12%
Export controls on advanced chips
Taiwan/South Korea to Japan
Semiconductors, memory
25%
Low tariff, supply dependency
ASEAN to Japan
IT services, data processing
10%
CPTPP preferences
Japan is a net importer of big data hardware and a net exporter of analytics services and embedded software. Cross-border data flows are governed by APPI, which requires equivalent protection for transfers to third countries. The US-Japan Digital Trade Agreement and CPTPP facilitate data flows, but China's export controls on advanced semiconductors limit hardware supply.
Tariff impacts are modest for software, but non-tariff barriers include data localization requirements in healthcare and government. Japan's export controls on semiconductor manufacturing equipment, implemented in 2023, affect trade with China. Cross-border shipment volumes for servers and storage grew 7% in 2024, while cloud service exports grew 19%. Geopolitical tensions may add 5-8% to supply chain costs for critical components.
Japan Big Data Market Segmentation
1. Component
1.1. Hardware
1.2. Software
1.3. Service
2. Deployment Mode
2.1. On Premise
2.2. Cloud
3. Enterprise Size
3.1. SMEs
3.2. Large Enterprise
4. Business Function
4.1. Marketing and Sales
4.2. Finance
4.3. Human Resources
4.4. Operations
5. Industry Vertical
5.1. BFSI
5.2. Government and Defense
5.3. Healthcare and Life Sciences
5.4. Manufacturing
5.5. Retail and Consumer Goods
5.6. Media and Entertainment
5.7. Telecommunications and IT
5.8. Transportation and Logistics
5.9. Others
Japan Big Data Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Japan Big Data Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 24.09% from 2020-2034
Segmentation
By Component
Hardware
Software
Service
By Deployment Mode
On Premise
Cloud
By Enterprise Size
SMEs
Large Enterprise
By Business Function
Marketing and Sales
Finance
Human Resources
Operations
By Industry Vertical
BFSI
Government and Defense
Healthcare and Life Sciences
Manufacturing
Retail and Consumer Goods
Media and Entertainment
Telecommunications and IT
Transportation and Logistics
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Hardware
5.1.2. Software
5.1.3. Service
5.2. Market Analysis, Insights and Forecast - by Deployment Mode
5.2.1. On Premise
5.2.2. Cloud
5.3. Market Analysis, Insights and Forecast - by Enterprise Size
5.3.1. SMEs
5.3.2. Large Enterprise
5.4. Market Analysis, Insights and Forecast - by Business Function
5.4.1. Marketing and Sales
5.4.2. Finance
5.4.3. Human Resources
5.4.4. Operations
5.5. Market Analysis, Insights and Forecast - by Industry Vertical
5.5.1. BFSI
5.5.2. Government and Defense
5.5.3. Healthcare and Life Sciences
5.5.4. Manufacturing
5.5.5. Retail and Consumer Goods
5.5.6. Media and Entertainment
5.5.7. Telecommunications and IT
5.5.8. Transportation and Logistics
5.5.9. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. South America
5.6.3. Europe
5.6.4. Middle East & Africa
5.6.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Hardware
6.1.2. Software
6.1.3. Service
6.2. Market Analysis, Insights and Forecast - by Deployment Mode
6.2.1. On Premise
6.2.2. Cloud
6.3. Market Analysis, Insights and Forecast - by Enterprise Size
6.3.1. SMEs
6.3.2. Large Enterprise
6.4. Market Analysis, Insights and Forecast - by Business Function
6.4.1. Marketing and Sales
6.4.2. Finance
6.4.3. Human Resources
6.4.4. Operations
6.5. Market Analysis, Insights and Forecast - by Industry Vertical
6.5.1. BFSI
6.5.2. Government and Defense
6.5.3. Healthcare and Life Sciences
6.5.4. Manufacturing
6.5.5. Retail and Consumer Goods
6.5.6. Media and Entertainment
6.5.7. Telecommunications and IT
6.5.8. Transportation and Logistics
6.5.9. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Hardware
7.1.2. Software
7.1.3. Service
7.2. Market Analysis, Insights and Forecast - by Deployment Mode
7.2.1. On Premise
7.2.2. Cloud
7.3. Market Analysis, Insights and Forecast - by Enterprise Size
7.3.1. SMEs
7.3.2. Large Enterprise
7.4. Market Analysis, Insights and Forecast - by Business Function
7.4.1. Marketing and Sales
7.4.2. Finance
7.4.3. Human Resources
7.4.4. Operations
7.5. Market Analysis, Insights and Forecast - by Industry Vertical
7.5.1. BFSI
7.5.2. Government and Defense
7.5.3. Healthcare and Life Sciences
7.5.4. Manufacturing
7.5.5. Retail and Consumer Goods
7.5.6. Media and Entertainment
7.5.7. Telecommunications and IT
7.5.8. Transportation and Logistics
7.5.9. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Hardware
8.1.2. Software
8.1.3. Service
8.2. Market Analysis, Insights and Forecast - by Deployment Mode
8.2.1. On Premise
8.2.2. Cloud
8.3. Market Analysis, Insights and Forecast - by Enterprise Size
8.3.1. SMEs
8.3.2. Large Enterprise
8.4. Market Analysis, Insights and Forecast - by Business Function
8.4.1. Marketing and Sales
8.4.2. Finance
8.4.3. Human Resources
8.4.4. Operations
8.5. Market Analysis, Insights and Forecast - by Industry Vertical
8.5.1. BFSI
8.5.2. Government and Defense
8.5.3. Healthcare and Life Sciences
8.5.4. Manufacturing
8.5.5. Retail and Consumer Goods
8.5.6. Media and Entertainment
8.5.7. Telecommunications and IT
8.5.8. Transportation and Logistics
8.5.9. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Hardware
9.1.2. Software
9.1.3. Service
9.2. Market Analysis, Insights and Forecast - by Deployment Mode
9.2.1. On Premise
9.2.2. Cloud
9.3. Market Analysis, Insights and Forecast - by Enterprise Size
9.3.1. SMEs
9.3.2. Large Enterprise
9.4. Market Analysis, Insights and Forecast - by Business Function
9.4.1. Marketing and Sales
9.4.2. Finance
9.4.3. Human Resources
9.4.4. Operations
9.5. Market Analysis, Insights and Forecast - by Industry Vertical
9.5.1. BFSI
9.5.2. Government and Defense
9.5.3. Healthcare and Life Sciences
9.5.4. Manufacturing
9.5.5. Retail and Consumer Goods
9.5.6. Media and Entertainment
9.5.7. Telecommunications and IT
9.5.8. Transportation and Logistics
9.5.9. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Hardware
10.1.2. Software
10.1.3. Service
10.2. Market Analysis, Insights and Forecast - by Deployment Mode
10.2.1. On Premise
10.2.2. Cloud
10.3. Market Analysis, Insights and Forecast - by Enterprise Size
10.3.1. SMEs
10.3.2. Large Enterprise
10.4. Market Analysis, Insights and Forecast - by Business Function
10.4.1. Marketing and Sales
10.4.2. Finance
10.4.3. Human Resources
10.4.4. Operations
10.5. Market Analysis, Insights and Forecast - by Industry Vertical
10.5.1. BFSI
10.5.2. Government and Defense
10.5.3. Healthcare and Life Sciences
10.5.4. Manufacturing
10.5.5. Retail and Consumer Goods
10.5.6. Media and Entertainment
10.5.7. Telecommunications and IT
10.5.8. Transportation and Logistics
10.5.9. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. QBurst
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Dell Corporation
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. IBM Corporation
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Finatext Ltd.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Oracle Corporation
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Rikkeisoft
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. HPE
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Hitachi Data System
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Teradata
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. ThinkPalm Technologies
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Japan Big Data Market Revenue Breakdown (million, %) by Product 2026 & 2034
Figure 2: Japan Big Data Market Value Share (%), by Component 2026 & 2034
Figure 3: Japan Big Data Market Value Share (%), by Deployment Mode 2026 & 2034
Figure 4: Japan Big Data Market Value Share (%), by Enterprise Size 2026 & 2034
Figure 5: Japan Big Data Market Value Share (%), by Business Function 2026 & 2034
Figure 6: Japan Big Data Market Value Share (%), by Industry Vertical 2026 & 2034
Figure 7: Japan Big Data Market Share (%) by Company 2026
List of Tables
Table 1: Japan Big Data Market Revenue million Forecast, by Component 2020 & 2034
Table 2: Japan Big Data Market Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 3: Japan Big Data Market Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 4: Japan Big Data Market Revenue million Forecast, by Business Function 2020 & 2034
Table 5: Japan Big Data Market Revenue million Forecast, by Industry Vertical 2020 & 2034
Table 6: Japan Big Data Market Revenue million Forecast, by Region 2020 & 2034
Table 7: North America Japan Big Data Market Revenue million Forecast, by Component 2020 & 2034
Table 8: North America Japan Big Data Market Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 9: North America Japan Big Data Market Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 10: North America Japan Big Data Market Revenue million Forecast, by Business Function 2020 & 2034
Table 11: North America Japan Big Data Market Revenue million Forecast, by Industry Vertical 2020 & 2034
Table 12: North America Japan Big Data Market Revenue million Forecast, by Country 2020 & 2034
Table 13: United States Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 14: Canada Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 15: Mexico Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 16: South America Japan Big Data Market Revenue million Forecast, by Component 2020 & 2034
Table 17: South America Japan Big Data Market Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 18: South America Japan Big Data Market Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 19: South America Japan Big Data Market Revenue million Forecast, by Business Function 2020 & 2034
Table 20: South America Japan Big Data Market Revenue million Forecast, by Industry Vertical 2020 & 2034
Table 21: South America Japan Big Data Market Revenue million Forecast, by Country 2020 & 2034
Table 22: Brazil Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 23: Argentina Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Rest of South America Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 25: Europe Japan Big Data Market Revenue million Forecast, by Component 2020 & 2034
Table 26: Europe Japan Big Data Market Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 27: Europe Japan Big Data Market Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 28: Europe Japan Big Data Market Revenue million Forecast, by Business Function 2020 & 2034
Table 29: Europe Japan Big Data Market Revenue million Forecast, by Industry Vertical 2020 & 2034
Table 30: Europe Japan Big Data Market Revenue million Forecast, by Country 2020 & 2034
Table 31: United Kingdom Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Germany Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 33: France Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 34: Italy Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 35: Spain Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 36: Russia Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Benelux Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 38: Nordics Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 39: Rest of Europe Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 40: Middle East & Africa Japan Big Data Market Revenue million Forecast, by Component 2020 & 2034
Table 41: Middle East & Africa Japan Big Data Market Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 42: Middle East & Africa Japan Big Data Market Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 43: Middle East & Africa Japan Big Data Market Revenue million Forecast, by Business Function 2020 & 2034
Table 44: Middle East & Africa Japan Big Data Market Revenue million Forecast, by Industry Vertical 2020 & 2034
Table 45: Middle East & Africa Japan Big Data Market Revenue million Forecast, by Country 2020 & 2034
Table 46: Turkey Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 47: Israel Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 48: GCC Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 49: North Africa Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 50: South Africa Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 51: Rest of Middle East & Africa Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 52: Asia Pacific Japan Big Data Market Revenue million Forecast, by Component 2020 & 2034
Table 53: Asia Pacific Japan Big Data Market Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 54: Asia Pacific Japan Big Data Market Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 55: Asia Pacific Japan Big Data Market Revenue million Forecast, by Business Function 2020 & 2034
Table 56: Asia Pacific Japan Big Data Market Revenue million Forecast, by Industry Vertical 2020 & 2034
Table 57: Asia Pacific Japan Big Data Market Revenue million Forecast, by Country 2020 & 2034
Table 58: China Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 59: India Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 60: Japan Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 61: South Korea Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 62: ASEAN Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 63: Oceania Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Table 64: Rest of Asia Pacific Japan Big Data Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% primary research; 20–30% secondary research. Primary interviews target the Japan big data value chain, including Japanese enterprise software integrators and data platform SIs, cloud hyperscaler data platform engineering teams, big data analytics ISVs and AI model vendors, server/storage/network OEMs, and IT consulting and APPI data governance advisory firms.
Stakeholder roles interviewed: Chief Data Officer / Head of Data Strategy, Director of Data Platform Engineering, Procurement Manager for Data Center Infrastructure, Head of Digital Transformation, and APPI Compliance and Data Governance Lead.
Quantitative metrics for bottom-up sizing: number of Japanese enterprises with >1 PB data storage, average cloud data warehouse spend per large enterprise, server shipment volumes to Japanese data centers, and data scientist headcount growth.
Every report is updated to the date of purchase.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Data Officer / Head of Data Strategy
25%
Director of Data Platform Engineering
25%
Procurement Manager, Data Center Infrastructure
20%
Head of Digital Transformation
15%
APPI Compliance and Data Governance Lead
15%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Japanese enterprise software integrators and data platform SIs
30%
Cloud hyperscaler data platform engineering teams
20%
Big data analytics ISVs and AI model vendors
20%
Server, storage, and network OEMs
15%
IT consulting and APPI data governance advisory firms
15%
Secondary Research & Industry Benchmarking
20–30% secondary research using Bloomberg, Factiva, Hoovers, and PitchBook for financial filings, deal data, and vendor benchmarks.
Trade associations include JEITA and IPA for ICT spending and data governance benchmarks.
Cross-validation with vendor earnings calls, cloud region announcements, and semiconductor supply chain reports.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are used simultaneously. Top-down uses Japan ICT spend and big data allocation; bottom-up builds from enterprise data platform deployments and average contract values.
Multi-level data triangulation reconciles vendor revenue, segment shares, and regional demand.
Guaranteed estimated data accuracy level of 85–90%.
Demand models incorporate APPI compliance costs, cloud migration rates, and AI workload growth.
Data Accuracy & Quality Check
70/30 research split ensures primary validation of secondary estimates.
Triangulation across at least three independent data sources per segment.
85–90% accuracy verified through back-testing against historical Japan big data spend.
Reports are updated to the date of purchase.
Frequently Asked Questions
1. How are disruptive technologies and emerging substitutes reshaping the Japan Big Data Market?
Cloud-native lakehouses and generative AI are displacing legacy on-premise data warehouses. The Japan Cloud Big Data Infrastructure Market grows at 28.4% CAGR, while on-premise grows at 11.2%. Open-source substitutes such as Apache Iceberg and Spark reduce vendor lock-in for Japanese enterprises.
2. What raw material sourcing and supply chain considerations affect the Japan Big Data Market?
Hardware depends on imported GPUs, DRAM, and NAND, with Japan importing over 80% of advanced chips. Nvidia H100 lead times exceeded 26 weeks in 2024, and DRAM prices rose 10-25%. Data center power costs in Tokyo increased 10% in 2024, pressuring operating margins.
3. How do export-import dynamics and international trade flows influence the Japan Big Data Market?
Japan is a net importer of servers and memory, sourcing 25% of semiconductors from Taiwan and South Korea. It exports analytics services and embedded software, with the US-Japan Digital Trade Agreement and CPTPP easing data flows. China's export controls on advanced chips added 5-8% to component costs.
4. Which sustainability, ESG, and environmental impact factors matter most in the Japan Big Data Market?
Data center electricity consumption and cooling water use are primary ESG concerns. Japanese operators face Tokyo's 2030 renewable energy targets, and carbon reporting under the Financial Services Agency's ESG rules affects vendor selection. Efficient AI accelerators can reduce energy per inference by 30-40%.
5. What is the current market size, valuation, and CAGR projection for the Japan Big Data Market through 2033?
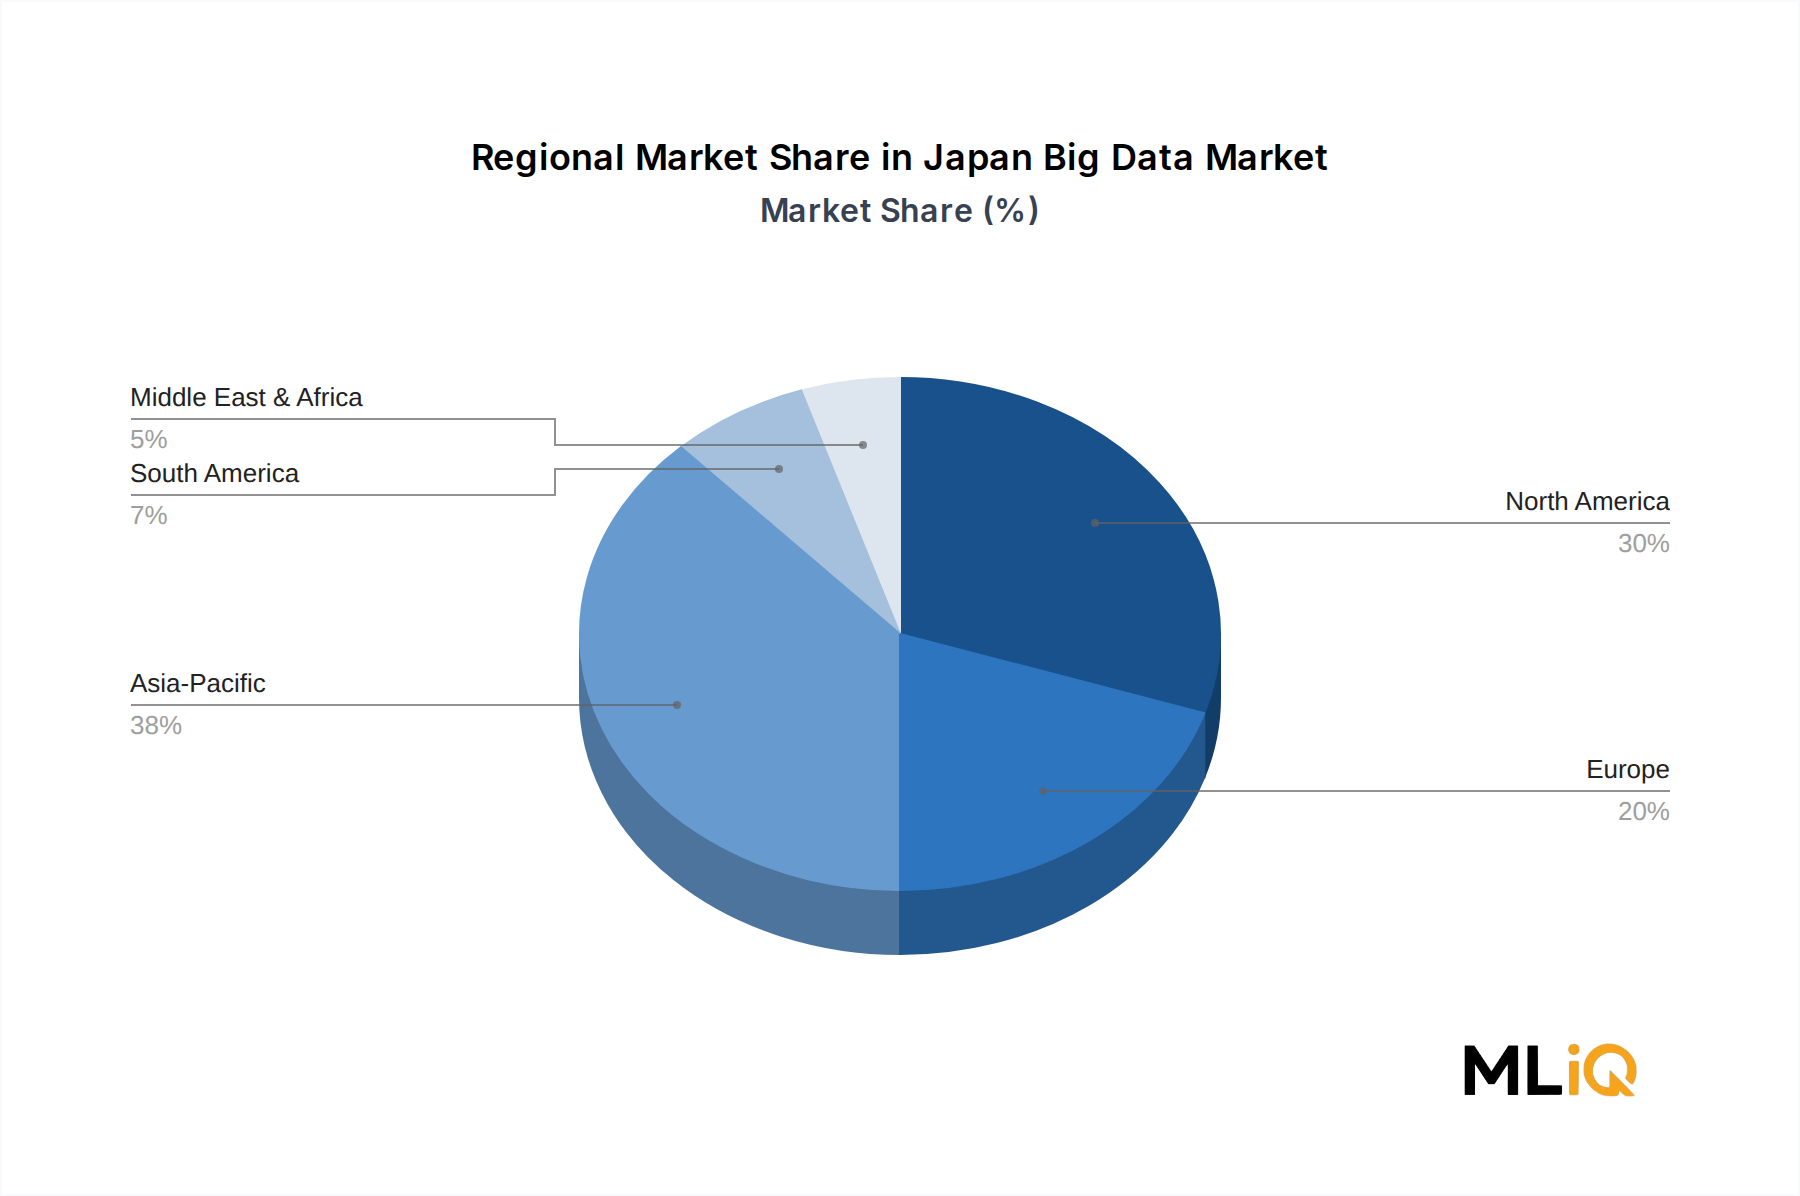
The Japan Big Data Market is valued at $292.7 million in 2024 and is forecast to reach $2,042.7 million by 2033, expanding at 24.09% CAGR. Software dominates with 52% share, followed by services at 31% and hardware at 17%. Asia-Pacific accounts for 38% of global regional revenue.
6. Who is investing in the Japan Big Data Market, and what funding rounds or venture capital activity is notable?
Corporate venture arms of Hitachi, IBM, and Oracle fund Japanese AI and data startups. Finatext Ltd. and Rikkeisoft have raised strategic funding for financial data APIs and offshore engineering. Venture capital into Japanese big data and AI startups exceeded $1.2 billion in 2023, with BFSI and healthcare as top sectors.