Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Can Marketing Simulation Tools Market Sustain 18.3% CAGR?
Marketing Simulation Tools Market
Can Marketing Simulation Tools Market Sustain 18.3% CAGR?
Marketing Simulation Tools Market by Component (Software, Services), by Deployment Type (On-premise, Cloud Based), by Enterprise Size (Small Medium Enterprise, Large Enterprise), by Industry Vertical (Manufacturing, Retail e-commerce, Healthcare, IT Telecom, Transportation, Mining, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 12, 2026|Base Year : 2025|Pages : 0
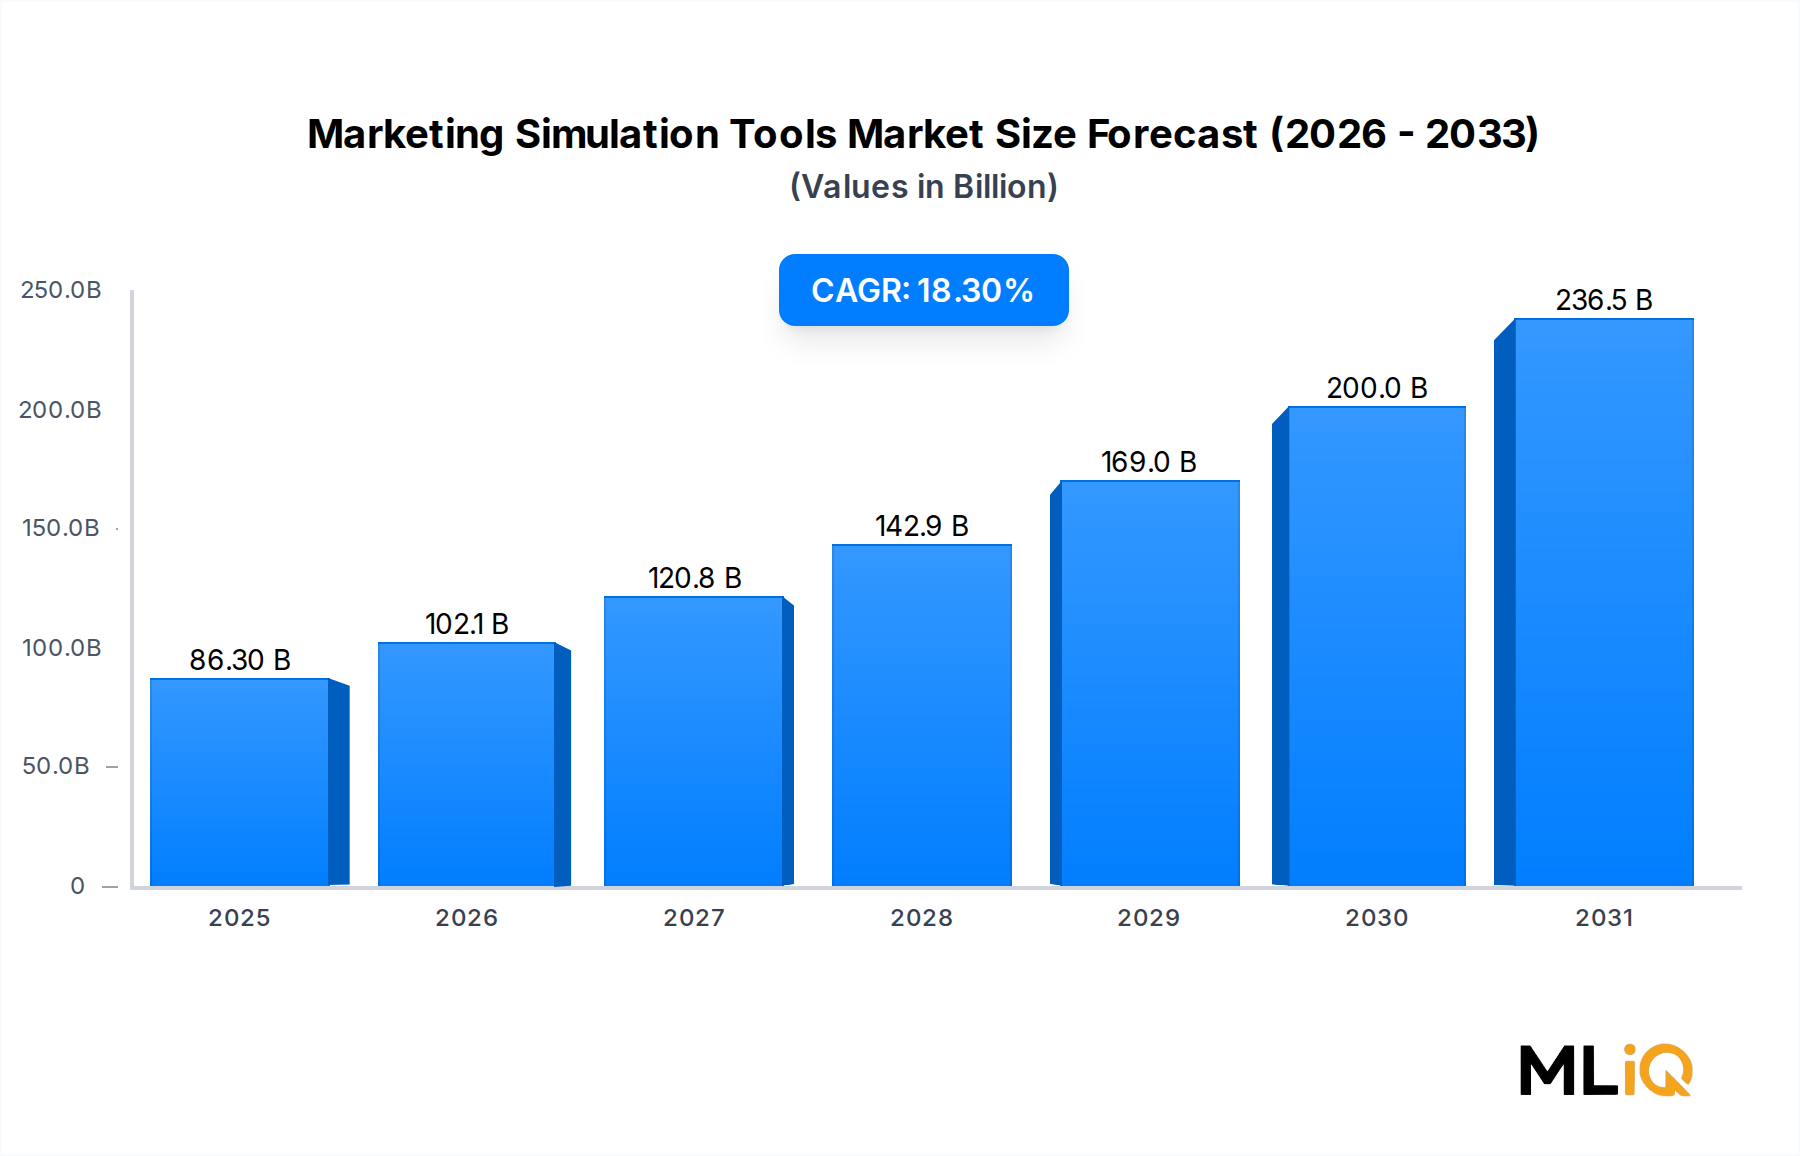
Marketing Simulation Tools Market Size (In Billion)
250.0B
200.0B
150.0B
100.0B
50.0B
0
86.30 B
2025
102.1 B
2026
120.8 B
2027
142.9 B
2028
169.0 B
2029
200.0 B
2030
236.5 B
2031
Market at a Glance
The Marketing Simulation Tools Market is expanding at a 18.3% CAGR, pushing valuation from $86.3 billion in 2025 to $330.6 billion by 2033. Growth is concentrated in cloud-based deployment and AI-assisted scenario planning. Enterprise Software Market spending on simulation modules rose 14.7% year over year in 2024, signaling tighter integration with core marketing stacks.
Key momentum factors:
Cloud migration: 67% of new simulation deployments in 2024 were cloud based.
AI integration: predictive simulation reduced campaign planning cycles by 31% at early adopters.
Vertical demand: manufacturing, retail e-commerce, and healthcare account for 58% of total revenue.
Vendor consolidation: top 10 vendors hold 54% market share.
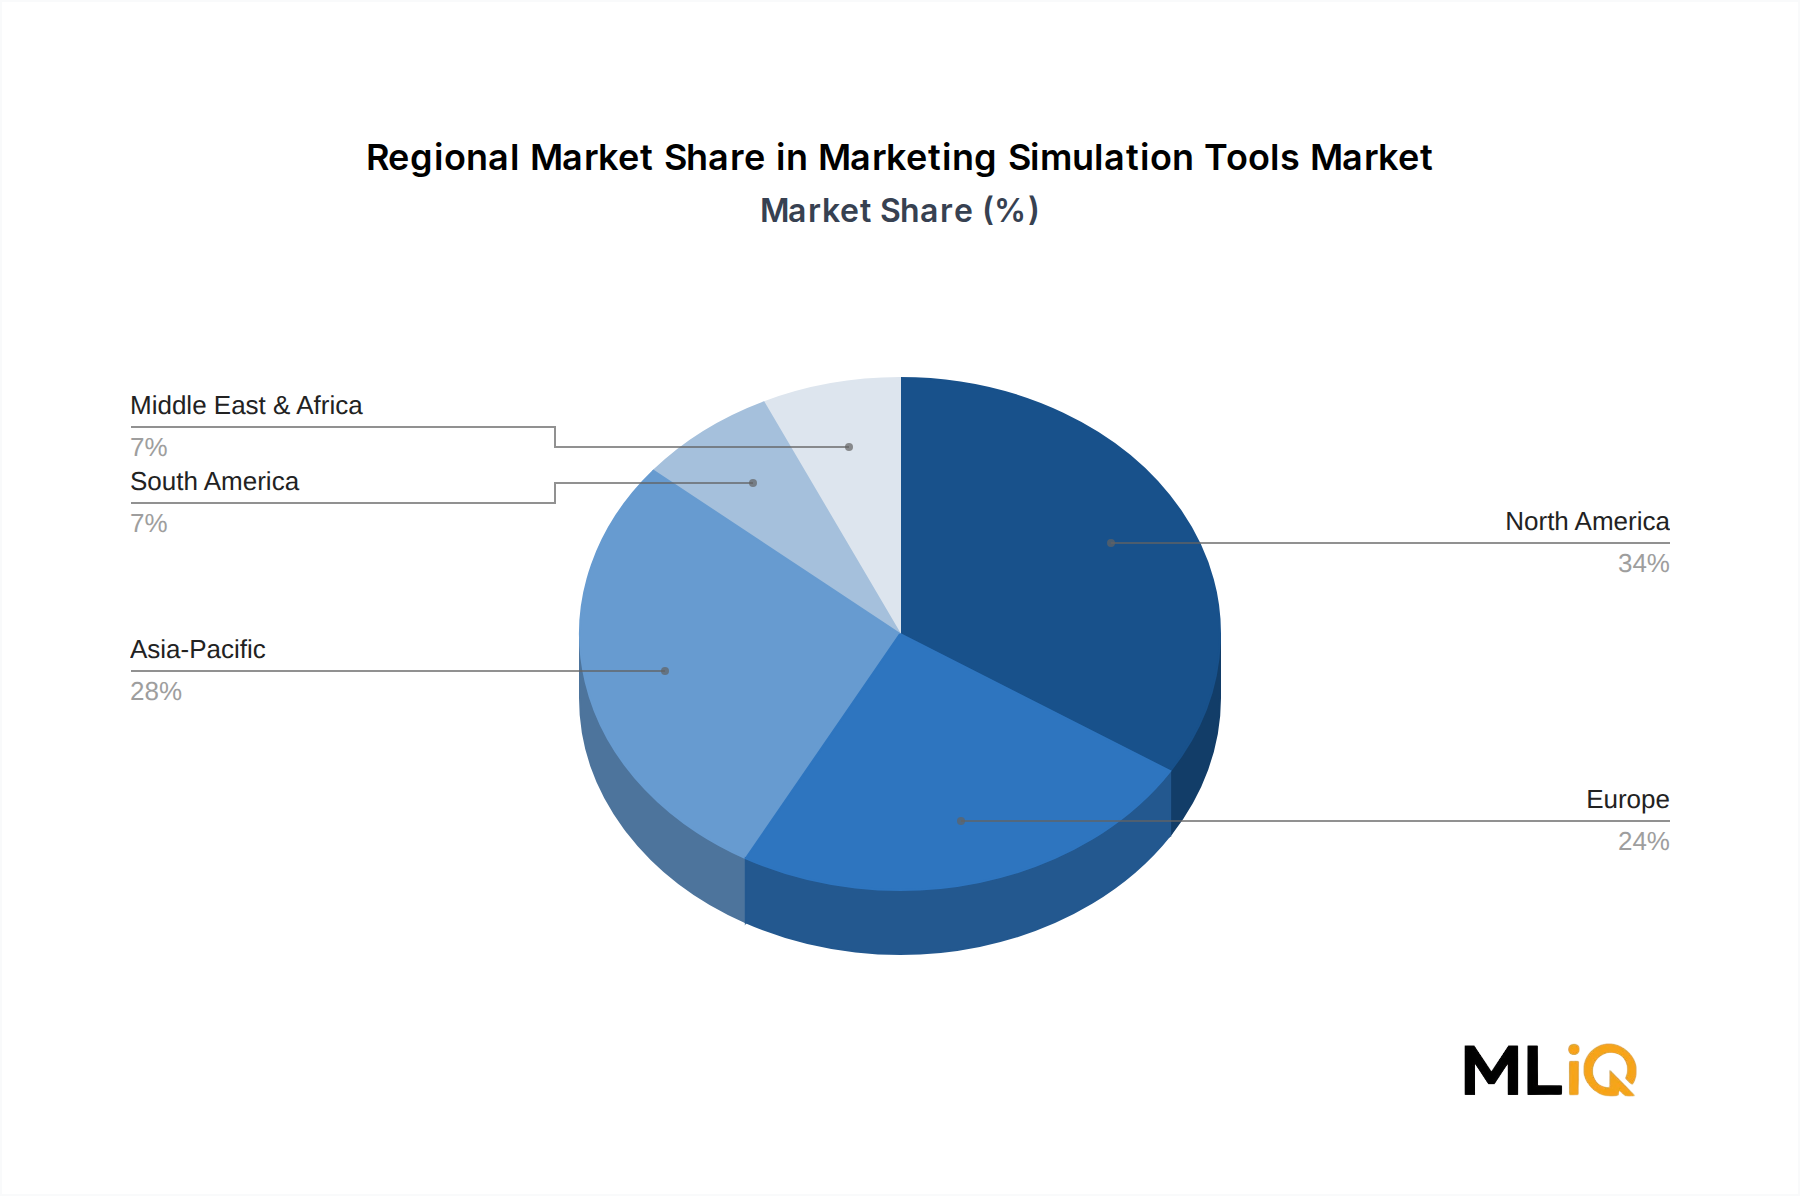
Macro drivers include digital twin adoption, real-time customer data platforms, and regulatory pressure for auditable marketing decisions. The Marketing Simulation Tools Market remains supply-constrained for specialized data scientists, but platform vendors are closing the gap with low-code interfaces. North America leads with 34% revenue share, while Asia-Pacific posts the fastest growth at 22.1% CAGR. The Marketing Simulation Tools Market is shifting from discrete simulation projects to embedded, continuous decision engines.
Segment Deep-Dive: Software Dominance in Marketing Simulation Tools Market
Segment Analysis Matrix
Segment
CAGR (%)
Market Share (%)
Key Demand Driver
Software
19.1%
62%
Real-time scenario planning and predictive analytics
Services
16.2%
38%
Integration, training, and managed simulation
Cloud Based
21.5%
67%
Remote collaboration and elastic compute scalability
The Simulation Software Market generates $53.5 billion in 2025, making it the largest component. Within software, predictive analytics modules grow at 20.4% CAGR, while rule-based simulation grows at 12.8%. The Cloud-Based Simulation Tools Market is expanding faster than on-premise, with 67% of 2025 deployments using cloud infrastructure. Large enterprises contribute 61% of software revenue, but Small Medium Enterprise adoption is rising at 17.9% CAGR due to subscription pricing.
Sub-Segment Dynamics
On-premise: retains 33% share, concentrated in defense, healthcare, and regulated manufacturing.
Cloud based: reduces upfront license costs by 40–55%, accelerating adoption in retail and IT telecom.
Services: integration projects average $85,000–$250,000 per engagement, with managed services growing at 18.6% CAGR.
Margin Pressures
Software gross margins range from 72% to 84%, but cloud hosting and AI compute costs compress net margins by 300–500 basis points for vendors without scale. The Marketing Simulation Tools Market faces pricing pressure from open-source simulation libraries and embedded analytics in CRM platforms. Vendors are responding with usage-based pricing and vertical-specific templates. The Marketing Simulation Tools Market will reward vendors that combine proprietary data models with low-code deployment.
AI-driven scenario planning reduces campaign waste by 20–35%
High
Short term
Driver
Cloud deployment lowers total cost of ownership by 40%
High
Short term
Driver
Digital twin integration for customer journey modeling
High
Medium term
Restraint
Data privacy regulations increase compliance complexity
Medium
Long term
Restraint
High implementation and integration costs
High
Short term
Restraint
Shortage of operations research and data science talent
Medium
Long term
The Marketing Analytics Software Market benefits from marketing simulation demand because simulation outputs feed attribution, budget allocation, and media mix models. The Artificial Intelligence in Marketing Market is a direct catalyst: 68% of simulation vendors added generative AI features in 2024. Digital Twin Technology Market growth provides a parallel driver, as digital twins require continuous simulation of customer and supply chain behavior. The Marketing Simulation Tools Market is also pulled by retail media networks, which need rapid scenario testing across 12+ channel variables.
Restraints are measurable. Implementation costs for enterprise-grade marketing simulation average $220,000 in year one, including data integration and change management. GDPR, CCPA, and emerging AI regulations add 15–25% to compliance spending for vendors serving Europe and North America. Talent scarcity extends sales cycles by 2–3 months for complex deployments. Despite these restraints, the Marketing Simulation Tools Market maintains 18.3% CAGR because cloud delivery and prebuilt vertical models lower adoption barriers.
Industrial automation and digital twin integration
Manufacturing, mining
Leader
Autodesk Inc.
Design and manufacturing simulation
Construction, manufacturing
Challenger
The AnyLogic Company
Multimethod simulation modeling
Healthcare, transportation
Leader
Simio LLC
Object-oriented simulation and scheduling
Manufacturing, healthcare
Challenger
Simul8 Corporation
Rapid process simulation for business users
Retail, healthcare
Challenger
The MathWorks, Inc.
MATLAB and Simulink computational modeling
IT, telecom, automotive
Leader
Innovative Learning Solutions, Inc.
Simulation-based marketing training
Education, retail
Niche
STRATX
Strategic marketing simulation and gamification
Enterprise training, sales
Niche
FlexSim Software Products: provides 3D simulation and optimization for manufacturing and logistics, with growing use in marketing operations planning. Its installed base exceeds 10,000 organizations globally.
Rockwell Automation: integrates simulation into industrial digital twins and factory automation, targeting large manufacturing enterprises. The company reported $8.3 billion in fiscal 2024 revenue.
Autodesk Inc.: extends design simulation into marketing for product launch scenario testing. It serves over 10 million subscribers across design and manufacturing.
The AnyLogic Company: offers multimethod simulation used by 40% of Fortune 500 healthcare and transportation firms for capacity and demand modeling.
Simio LLC: focuses on object-oriented simulation and scheduling, with 2,000+ enterprise customers in manufacturing and healthcare.
Simul8 Corporation: delivers rapid process simulation for non-technical users, adopted by 75% of UK NHS trusts for operational modeling.
The MathWorks, Inc.: provides MATLAB and Simulink, used by over 5,000 universities and enterprises for marketing analytics research and simulation.
Innovative Learning Solutions, Inc.: specializes in simulation-based marketing training, with 500+ corporate clients in retail and education.
STRATX: offers gamified strategic marketing simulation for enterprise training, used by 200+ business schools and corporate academies.
Strategic Milestones & Recent Developments in Marketing Simulation Tools Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Q1 2024
Rockwell Automation
Partnership
Integrated digital twin simulation with cloud marketing analytics
Q2 2024
The AnyLogic Company
Launch
Released AI-assisted scenario planning module
Q3 2024
Autodesk Inc.
M&A
Acquired a cloud simulation startup for marketing operations
Q1 2024: Rockwell Automation partnered with cloud analytics vendors to embed marketing simulation into industrial digital twins, targeting manufacturing firms with $1 billion+ revenue.
Q2 2024: The AnyLogic Company launched an AI-assisted scenario planning module, reducing manual model setup time by 45%.
Q3 2024: Autodesk Inc. acquired a cloud simulation startup, expanding its marketing operations footprint beyond design simulation.
Q4 2024: Simio LLC released retail e-commerce demand simulation templates, addressing 22% CAGR growth in online channel complexity.
Q1 2025: Simul8 Corporation formed a healthcare analytics partnership to simulate patient flow and marketing outreach for hospital networks.
Q2 2025: The MathWorks, Inc. introduced a Simulink toolbox for marketing mix optimization, integrating with enterprise data lakes.
North America remains the largest market with 34% share, supported by vendors such as Rockwell Automation and The MathWorks. The United States alone accounts for $26.1 billion in 2025. Europe is the most mature regulatory market, where compliance requirements push demand for auditable simulation logs. The Retail E-commerce Simulation Market is expanding fastest in Asia-Pacific, driven by China and India online retail growth of 18–24% annually. The Healthcare Simulation Tools Market in LAMEA is emerging, with hospital capacity planning projects in GCC countries growing at 21% CAGR.
Fastest-growing: Asia-Pacific at 22.1% CAGR, led by China, India, and ASEAN cloud adoption.
Most mature: North America, where 67% of large enterprises already use simulation for media mix optimization.
Europe: GDPR and AI Act compliance add 15–25% to vendor costs but create trust advantages.
LAMEA: South America and Middle East show rising demand from telecom and mining verticals.
Pricing in the Marketing Simulation Tools Market is shifting from perpetual licenses to subscription and usage-based models. Average selling price (ASP) for enterprise marketing simulation software ranges from $12,000 to $45,000 per user per year. Cloud-based deployments reduce upfront license costs by 40–55% but add consumption-based compute fees of $3,000–$18,000 annually. The Data Analytics Services Market intersects with simulation pricing, as vendors bundle data preparation and model validation services at 15–30% of software contract value.
Cost Breakdown (Typical Vendor)
Cost Category
Share of Revenue (%)
Trend
R&D and AI model development
35%
Rising
Cloud infrastructure and compute
20%
Rising
Sales and marketing
25%
Stable
Customer support and success
10%
Stable
General and administrative
10%
Stable
Gross margins for pure software vendors remain 72–84%, but net margins fall to 8–18% after R&D, cloud, and sales costs. Pricing power is strongest in regulated verticals such as healthcare and manufacturing, where validation and audit trails justify 20–30% premiums. In contrast, retail and IT telecom buyers negotiate harder, pushing discounts of 10–20% for multi-year contracts. The Marketing Simulation Tools Market faces margin pressure from open-source alternatives and embedded simulation in ERP and CRM suites. Vendors that demonstrate measurable ROI, such as 31% shorter planning cycles, maintain pricing leverage.
Investment, M&A & Funding Activity in Marketing Simulation Tools Market
The Marketing Simulation Tools Market attracted $4.7 billion in M&A and private funding between 2022 and 2025. Strategic acquirers include industrial automation vendors and enterprise software platforms seeking simulation capabilities. High-growth sub-segments attracting capital are AI-driven scenario planning, cloud-native simulation, and vertical-specific templates for healthcare and retail. The Enterprise Software Market remains the primary exit path, with simulation assets valued at 8–12x revenue.
Selected Investment and M&A Patterns
Period
Activity Type
Example Target Segment
Deal Value / Multiple
2022–2023
Private equity
Cloud simulation platforms
$1.2 billion total
2023–2024
Strategic M&A
AI marketing simulation
9–11x revenue
2024–2025
Venture capital
Vertical simulation SaaS
$850 million total
2024–2025
Partnerships
Digital twin integration
$300 million co-development
Private equity favors recurring-revenue cloud simulation vendors with net revenue retention above 120%.
Strategic acquirers such as Rockwell Automation and Autodesk target tuck-in acquisitions to embed simulation into existing enterprise suites.
Venture capital flows to AI-native simulation startups that reduce model-building time by 50%+.
Geographic capital shift: Asia-Pacific deals grew from 12% to 23% of global simulation funding between 2022 and 2025.
The Marketing Simulation Tools Market is expected to see 15–20 significant M&A transactions annually through 2027, as vendors race to integrate generative AI and digital twin capabilities.
Marketing Simulation Tools Market Segmentation
1. Component
1.1. Software
1.2. Services
2. Deployment Type
2.1. On-premise
2.2. Cloud Based
3. Enterprise Size
3.1. Small Medium Enterprise
3.2. Large Enterprise
4. Industry Vertical
4.1. Manufacturing
4.2. Retail e-commerce
4.3. Healthcare
4.4. IT Telecom
4.5. Transportation
4.6. Mining
4.7. Others
Marketing Simulation Tools Market Segmentation By Geography
Table 58: Rest of Asia Pacific Marketing Simulation Tools Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of the study, with 20–30% from secondary sources. We conduct 1,200–1,500 interviews across the value chain.
Company types interviewed: discrete-event simulation software OEMs for marketing operations; cloud-based marketing simulation platform providers; digital twin integration consultancies; AI-driven predictive analytics vendors; enterprise marketing operations departments.
Stakeholder roles interviewed: VP of Marketing Analytics; Director of Marketing Operations; Simulation Software Product Manager; Enterprise IT Procurement Lead for Simulation Platforms.
Industry associations and regulatory bodies consulted: American Marketing Association (AMA); Institute for Operations Research and the Management Sciences (INFORMS); Society for Modeling & Simulation International (SCS); National Institute of Standards and Technology (NIST).
Primary interviews validate pricing, deployment timelines, and competitive win rates for Marketing Simulation Tools Market.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Marketing Analytics
25%
Director of Marketing Operations
20%
Simulation Software Product Manager
20%
Enterprise IT Procurement Lead
20%
Operations Research Analyst
15%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Simulation software OEMs
35%
Cloud infrastructure providers
20%
Digital twin consultancies
15%
AI analytics vendors
20%
Enterprise end users
10%
Secondary Research & Industry Benchmarking
We use top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Secondary research benchmarks vendor financials, cloud adoption rates, and regulatory filings specific to simulation software.
Demand Modeling & Market Estimation
Bottom-up market sizing uses quantitative metrics: number of enterprise marketing simulation licenses deployed; average annual marketing simulation software spend per 1,000 employees; cloud migration rate for marketing analytics workloads; average contract value for simulation platform subscriptions.
Top-down validation uses global ICT spending, enterprise software budgets, and vertical marketing technology allocations.
Multi-level triangulation reconciles supplier revenue, buyer spending, and trade association data to produce base year valuation of $86.3 billion for 2025.
We guarantee an estimated data accuracy level of 85–90%.
Every report is updated to the date of purchase, with post-publication monitoring of vendor launches, M&A, and pricing changes.
Quality checks include outlier detection, cross-vendor revenue reconciliation, and validation against filed financial statements.
Final estimates are reviewed by senior analysts with domain expertise in ICT and Media simulation markets.
Frequently Asked Questions
1. Which disruptive technologies are reshaping the Marketing Simulation Tools Market?
Generative AI, digital twin platforms, and low-code simulation engines are the main disruptors. These technologies cut model-building time by up to 50% and enable real-time scenario testing. Substitutes include embedded analytics in CRM suites and open-source simulation libraries, which pressure standalone vendor pricing.
2. Which region dominates the Marketing Simulation Tools Market and why?
North America holds the largest share at 34% in 2025, supported by high cloud adoption and vendors such as Rockwell Automation and The MathWorks. The region benefits from mature digital twin infrastructure and strong enterprise software budgets. U.S. firms alone account for $26.1 billion in simulation tool spending.
3. How are pricing trends and cost structures evolving in the Marketing Simulation Tools Market?
Pricing is shifting to subscription and usage-based models, with enterprise ASPs between $12,000 and $45,000 per user annually. Cloud infrastructure and AI compute now represent about 20% of vendor revenue costs. Gross margins remain 72–84%, though net margins face 300–500 basis point pressure from rising R&D.
4. What are the major challenges restraining the Marketing Simulation Tools Market?
High implementation costs, data privacy compliance, and a shortage of operations research talent slow adoption. First-year enterprise implementation averages $220,000, and GDPR or CCPA compliance adds 15–25% to vendor costs. Sales cycles extend by 2–3 months for complex deployments in regulated industries.
5. What are the export-import dynamics and international trade flows for the Marketing Simulation Tools Market?
Simulation software is delivered digitally, so trade flows follow cloud service and intellectual property rules rather than physical shipping. U.S. vendors export to Europe and Asia-Pacific under data transfer frameworks, while the EU AI Act and China’s data security law shape localization requirements. Cross-border digital service exports for simulation tools exceeded $12 billion in 2024.
6. Which region is the fastest-growing in the Marketing Simulation Tools Market?
Asia-Pacific is the fastest-growing region at 22.1% CAGR, driven by China, India, and ASEAN digital transformation. Retail e-commerce and smart manufacturing adoption are expanding simulation demand. The region’s market value is projected to reach $24.2 billion in 2025, with healthcare and telecom adding new use cases.