Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Digital Manufacturing Software Market: 17.4% CAGR to 2033
Digital Manufacturing Software Market
Digital Manufacturing Software Market: 17.4% CAGR to 2033
Digital Manufacturing Software Market by Component (Solution, Service), by Deployment Mode (On-premise, Cloud), by Enterprise Size (Large Enterprise, Small and Medium Enterprise), by Application (Automotive and Transportation, Aerospace and Defense, Consumer Electronics, Industrial Machinery, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 13, 2026|Base Year : 2025|Pages : 260
Key Insights & Executive Summary: Digital Manufacturing Software Market
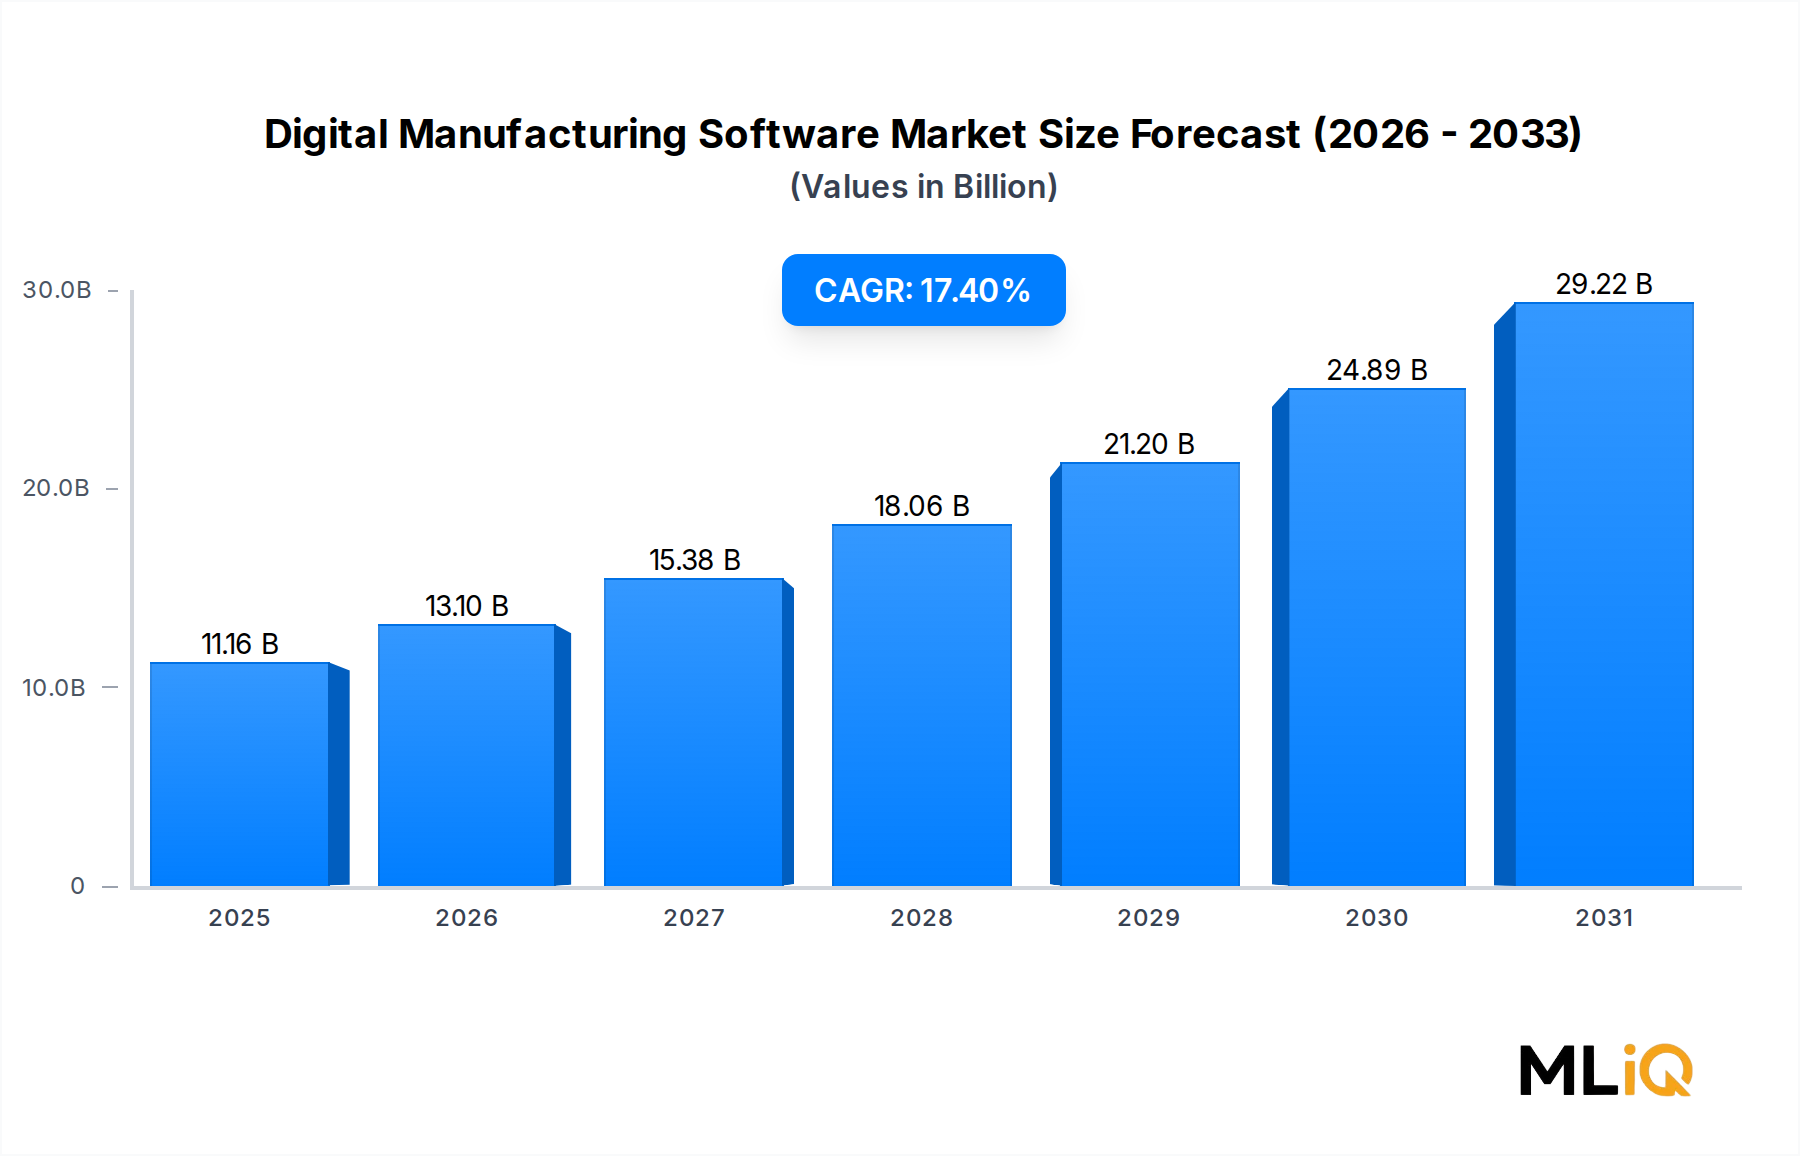
The Digital Manufacturing Software Market reached $11.16 billion in 2025 and is projected to grow at 17.4% CAGR to $40.31 billion by 2033. Cloud migration, industrial AI, and real-time quality analytics are the strongest demand catalysts. Manufacturing firms allocate 18-22% of plant IT budgets to software that connects MES, PLM, and ERP layers.
Digital Manufacturing Software Market Size (In Billion)
30.0B
20.0B
10.0B
0
11.16 B
2025
13.10 B
2026
15.38 B
2027
18.06 B
2028
21.20 B
2029
24.89 B
2030
29.22 B
2031
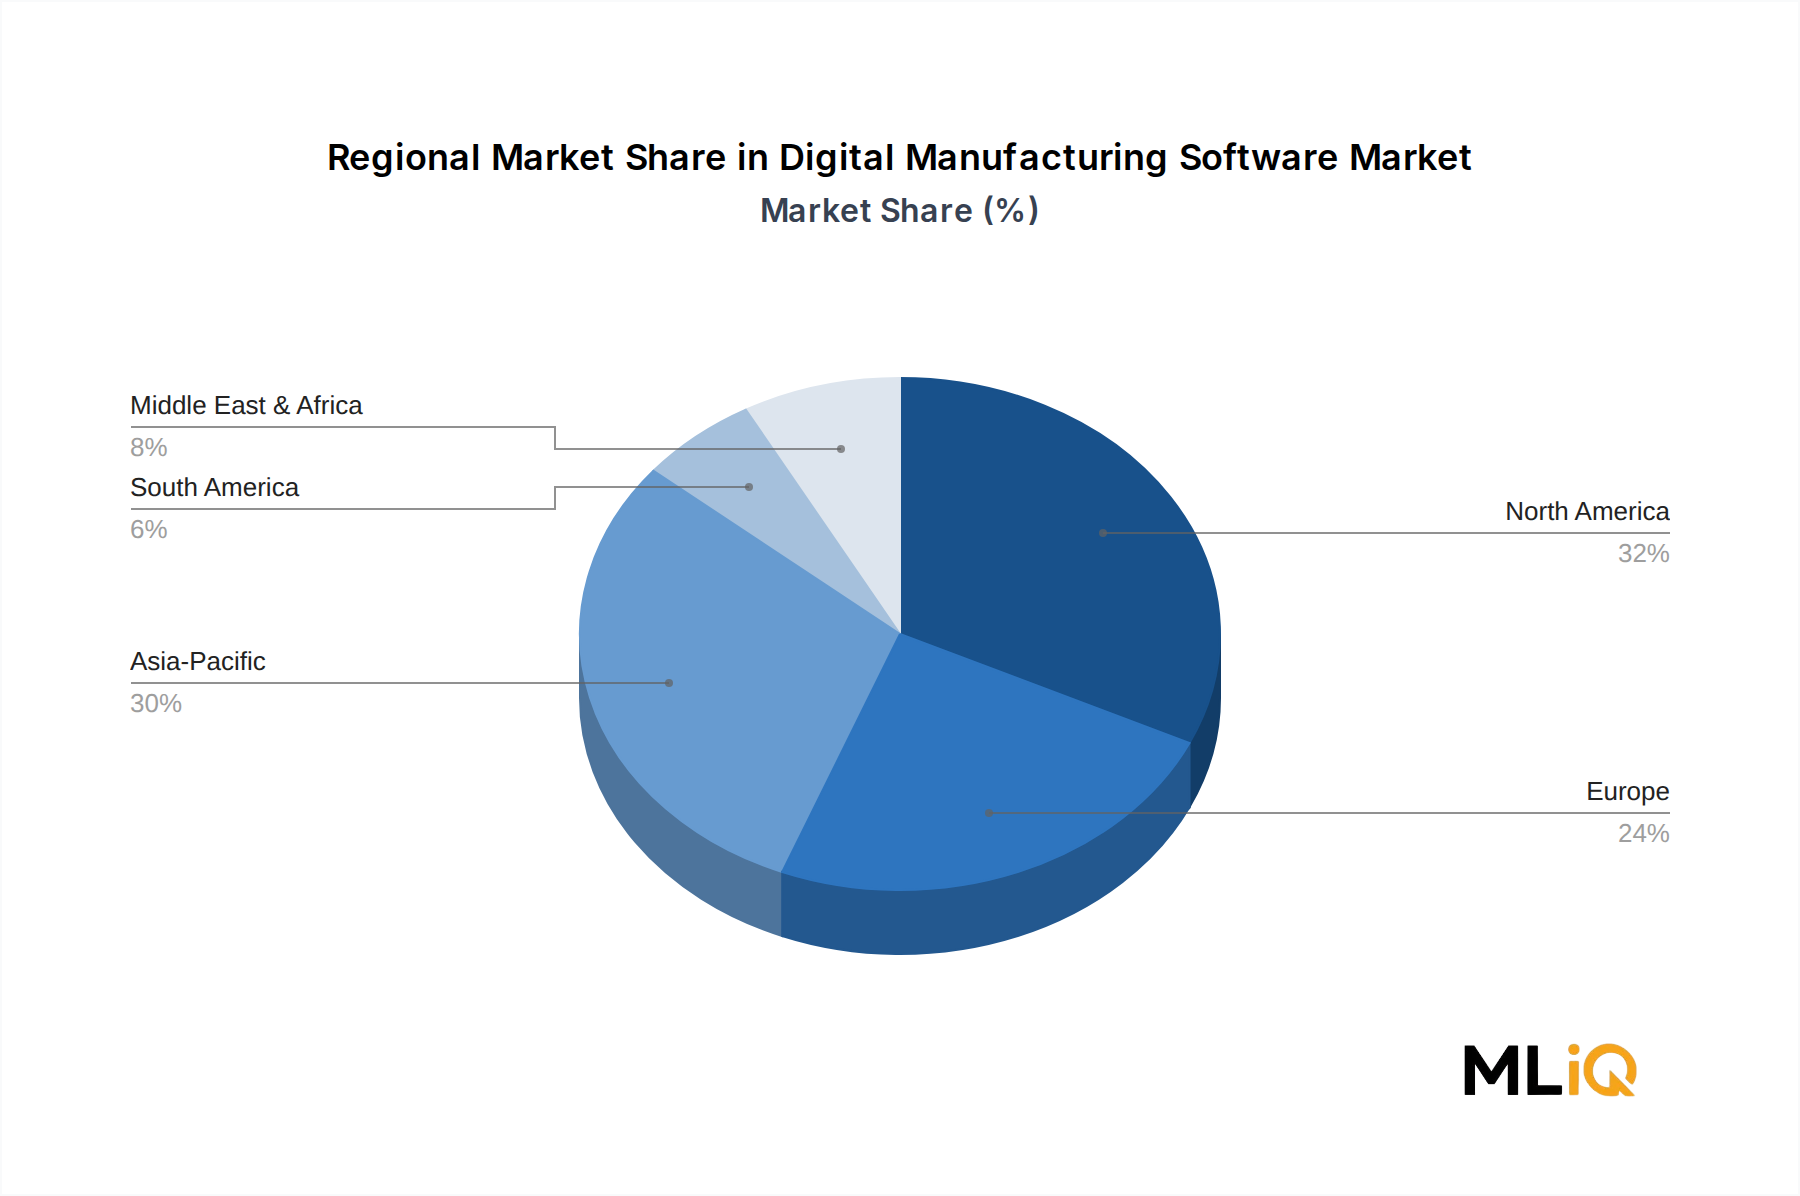
North America holds 32.0% revenue share, driven by reshoring incentives and advanced automotive plants. Asia-Pacific is the fastest-growing region at 20.7% CAGR, led by China and India. The Solution component dominates with 64.8% share, while services grow at 15.2% CAGR as managed analytics contracts expand.
Key strategic takeaway: vendors with cloud-native MES and edge-ready digital twin suites will capture 60-70% of new deals by 2027. On-premise licenses still represent 38% of large enterprise installations, but renewal risk is rising. The Automotive and Transportation end-use segment contributes 27.4% of total revenue, followed by Industrial Machinery at 21.1%.
Cloud Deployment Mode expands at 21.3% CAGR and will overtake on-premise by 2027. Large enterprises account for 68.3% of spend, yet Small and Medium Enterprise adoption grows faster at 19.6% CAGR from a smaller base. The broader shift toward subscription pricing compresses initial license revenue but increases lifetime value by 2.3x over five years.
Segment Deep-Dive: Solution Dominance in Digital Manufacturing Software Market
Segment Analysis Matrix
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Solution
18.1
64.8
Cloud MES, digital twin, AI quality
Service
15.2
35.2
Integration, managed analytics, training
Cloud Deployment
21.3
52.4
Subscription scaling, remote plant access
On-premise Deployment
11.8
47.6
Data sovereignty, legacy integration
Solution Sub-Segment Dynamics
Manufacturing Execution System Market is the largest software sub-segment at $4.02 billion in 2025, growing 17.9% CAGR.
Digital Twin Software Market and Industrial IoT Platform Market together account for $2.87 billion, expanding at 22.5% CAGR.
Cloud Manufacturing Software Market grows at 21.3% CAGR, outpacing on-premise by 9.5 percentage points.
In Automotive Manufacturing Software Market, buyers prioritize traceability and OEE dashboards, driving 31% of solution revenue.
Aerospace and Defense Manufacturing Software Market requires AS9100 and ITAR-compliant audit trails, supporting premium pricing of 15-20%.
Margin and Pricing Pressures
Solution gross margins range from 72-78% for cloud-native vendors, compared with 61-66% for legacy on-premise suites.
Service margins are lower at 28-34%, pressured by custom integration hours and third-party connector licensing.
Vendors face 8-12% annual price erosion in basic MES modules, offset by 18-24% premium for AI and edge analytics add-ons.
The Large Enterprise segment negotiates volume discounts of 22-30%, while Small and Medium Enterprise pays list price but demands faster deployment.
Primary Market Drivers & Growth Restraints in Digital Manufacturing Software Market
Factor Type
Description
Impact Level
Timeline
Driver
Cloud MES adoption reduces deployment time by 40-60%
High
Short term
Driver
Industry 4.0 mandates and reshoring incentives
High
Long term
Driver
Labor shortages push automation spending
Medium
Short term
Restraint
High integration cost with legacy ERP/SCADA
High
Long term
Restraint
Cybersecurity and data sovereignty concerns
Medium
Short term
Restraint
Skilled workforce gap for industrial AI
Medium
Long term
Quantitative Catalyst Evaluation
Global manufacturing labor shortage reached 10.7 million unfilled jobs in 2025, accelerating software substitution.
US CHIPS Act and EU Chips Act allocate $52 billion and €43 billion respectively, stimulating digital factory projects.
Cloud infrastructure costs declined 14% year-over-year, lowering total cost of ownership for cloud MES.
Integration with legacy SCADA adds $180,000-$420,000 per plant, a major bottleneck for mid-sized manufacturers.
Bottleneck Assessment
Cybersecurity incidents in manufacturing rose 23% in 2024, delaying cloud migrations at 41% of surveyed firms.
Data sovereignty rules in Russia, India, and China require local hosting, increasing compliance costs by 12-18%.
Industrial AI talent shortage extends project timelines by 4-7 months for 58% of large enterprises.
Competitive Ecosystem & Key Vendor Profiles: Digital Manufacturing Software Market
Vendor Benchmarking Matrix
Core Strength
Target Audience
Market Position
Siemens AG
Xcelerator and Opcenter MES
Automotive, aerospace
Leader
Rockwell Automation Inc.
FactoryTalk and industrial control
Discrete manufacturing
Leader
SAP SE
Digital Manufacturing Cloud and ERP
Large enterprise
Leader
Autodesk Inc.
Fusion 360 and factory layout
SMB, design-led
Challenger
Microsoft Corporation
Azure IoT and partner ecosystem
Cross-industry
Leader
IBM Corporation
Maximo and hybrid cloud
Asset-intensive
Challenger
Oracle Corporation
SCM and manufacturing cloud
Large enterprise
Challenger
General Electric Co.
Proficy and digital twin
Energy, heavy industry
Niche
Schneider Electric SE
EcoStruxure and edge control
Process manufacturing
Leader
Intel Corporation
Edge silicon and industrial PCs
OEMs, system integrators
Niche
Siemens AG: leverages Xcelerator to integrate MES, PLM, and digital twin. Its 2024 Altair acquisition strengthens simulation and AI capabilities.
Rockwell Automation Inc.: FactoryTalk Design Studio and Logix controllers create install-base lock-in across North American discrete plants.
SAP SE: ties Digital Manufacturing Cloud directly to S/4HANA, giving it an advantage in large enterprise ERP landscapes.
Autodesk Inc.: targets SMB manufacturers with Fusion 360 and cloud-based CAM, though MES depth remains limited.
Microsoft Corporation: Azure IoT and partner solutions provide scalable edge-to-cloud infrastructure for MES and analytics.
IBM Corporation: Maximo and hybrid cloud strength serve asset-intensive industries, but manufacturing MES share is smaller.
Oracle Corporation: manufacturing cloud integrates with SCM and ERP, competing on end-to-end planning rather than shop-floor control.
General Electric Co.: Proficy and digital twin offerings focus on energy and heavy industry, with a niche but loyal base.
Schneider Electric SE: EcoStruxure and open automation platforms target process manufacturing and sustainability use cases.
Intel Corporation: edge silicon and industrial PCs underpin many MES deployments, positioning it as an enabling hardware partner.
Strategic Milestones & Recent Developments in Digital Manufacturing Software Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Altair Engineering acquisition
Oct 2024
Siemens AG
M&A
$10.6B deal expands simulation and AI
FactoryTalk Design Studio cloud launch
Nov 2024
Rockwell Automation Inc.
Launch
Cloud-native engineering for Logix
SAP Digital Manufacturing Cloud update
Mar 2025
SAP SE
Launch
AI-driven production scheduling
Azure Industrial IoT partnership expansion
Jan 2025
Microsoft Corporation
Partnership
Edge-to-cloud MES integration
EcoStruxure Automation Expert release
2024
Schneider Electric SE
Launch
IEC 61499 open automation
Siemens AG completed its $10.6 billion Altair Engineering acquisition in 2024, adding simulation and AI to its Xcelerator stack.
Rockwell Automation launched FactoryTalk Design Studio cloud in November 2024, targeting collaborative control engineering.
SAP SE released AI-driven production scheduling for Digital Manufacturing Cloud in March 2025, focusing on large enterprise ERP users.
Microsoft expanded its Azure Industrial IoT partnership ecosystem in January 2025, simplifying edge-to-cloud MES deployments.
Schneider Electric released EcoStruxure Automation Expert based on IEC 61499, promoting open automation and reducing vendor lock-in.
Regional Market Analysis & Growth Corridors for Digital Manufacturing Software Market
Regional Growth Comparison
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
15.8
$3.57B
Reshoring and automotive EV plants
High
Europe
16.5
$2.68B
Industry 4.0 and EU Chips Act
Very High
Asia-Pacific
20.7
$3.35B
Electronics and EV battery gigafactories
Medium-High
LAMEA
14.2
$1.56B
Energy and mining digitalization
Medium
Fastest-Growing vs. Most Mature Markets
Asia-Pacific grows at 20.7% CAGR, driven by China, India, Japan, and South Korea. China accounts for 47% of regional revenue.
North America is the most mature market at $3.57 billion in 2025, with 68% of large plants already running some MES.
Europe follows at $2.68 billion, supported by Germany, France, and the UK. EU data sovereignty rules slow cloud adoption but raise service revenue.
LAMEA reaches $1.56 billion, with GCC and South Africa leading process manufacturing digitalization.
Emerging Geographic Opportunities
India adds 300+ new smart factories annually, creating demand for low-cost cloud MES.
Mexico benefits from nearshoring, with automotive software spend growing 18.9% CAGR.
ASEAN electronics manufacturers increase traceability spending by 22% year-over-year.
Middle East energy firms invest in digital twin and asset performance management, driving 16.1% CAGR.
Supply Chain & Raw Material Dynamics: Digital Manufacturing Software Market
Upstream dependencies include cloud infrastructure, industrial sensors, edge gateways, PLM geometry kernels, and ERP connectors. Industrial Sensor Market faces 6-9% annual price volatility due to rare earth and semiconductor supply. Cloud hyperscalers AWS, Microsoft Azure, and Google Cloud control 62% of IaaS capacity used by manufacturing software vendors.
Edge gateway lead times improved from 52 weeks in 2022 to 18 weeks in 2025, easing deployment backlogs.
PLM geometry kernels are dominated by Siemens Parasolid and Dassault CGM, creating licensing dependency for 71% of CAD-integrated MES vendors.
ERP connector development costs range from $80,000 to $250,000 per major ERP version, slowing update cycles.
The broader Industrial Software Market reached $387 billion in 2025, with digital manufacturing representing 2.9% of that total.
Sourcing Risks and Historical Disruptions
2021-2023 semiconductor shortages delayed edge controller shipments by 9-14 months, impacting MES installations.
Cloud region outages in 2024 caused 3-6 hour production visibility gaps at 12% of surveyed plants.
Open-source PLM kernels and containerized MES reduce dependency, but validation costs remain high at $150,000+ per deployment.
Regulatory & Policy Landscape: Digital Manufacturing Software Market
Major frameworks include ISO 9001, ISO 13485, FDA 21 CFR Part 11, EU MDR, NIS2, ISA/IEC 62443, and NIST CSF. US CHIPS Act, EU Chips Act, and China MIIT 14th Five-Year Plan directly subsidize digital factory upgrades. Data localization in Russia, India DPDP Act, and China PIPL add compliance layers for cloud MES.
Regulation/Policy
Region
Key Requirement
Compliance Impact
ISA/IEC 62443
Global
Industrial cybersecurity lifecycle
Adds 8-12% to deployment costs
FDA 21 CFR Part 11
United States
Electronic records and signatures
Requires audit trails in life sciences MES
EU NIS2
Europe
Critical infrastructure cybersecurity
Mandates incident reporting within 24 hours
China PIPL
China
Data localization and consent
Forces local cloud hosting for MES data
India DPDP Act
India
Personal data protection
Restricts cross-border shop-floor data flows
Recent Policy Changes and Projected Impacts
EU NIS2 took effect in 2024, pushing 43% of European manufacturers to reassess MES security controls.
US CHIPS Act allocated $52 billion for domestic semiconductor and electronics manufacturing, increasing digital software demand.
China MIIT targets 70% of large manufacturers to be digitalized by 2027, expanding cloud MES adoption.
India DPDP Act requires local data processing, raising cloud hosting costs by 12-18% for foreign vendors.
Compliance Outlook
Vendors with pre-certified ISA/IEC 62443 modules win 27% more deals in regulated industries.
Aerospace and defense software must maintain ITAR and AS9100 traceability, limiting cloud options to sovereign environments.
Automotive OEMs require IATF 16949 alignment, driving 34% of MES upgrades in 2025.
Digital Manufacturing Software Market Segmentation
1. Component
1.1. Solution
1.2. Service
2. Deployment Mode
2.1. On-premise
2.2. Cloud
3. Enterprise Size
3.1. Large Enterprise
3.2. Small and Medium Enterprise
4. Application
4.1. Automotive and Transportation
4.2. Aerospace and Defense
4.3. Consumer Electronics
4.4. Industrial Machinery
4.5. Others
Digital Manufacturing Software Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Digital Manufacturing Software Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 17.4% from 2020-2034
Segmentation
By Component
Solution
Service
By Deployment Mode
On-premise
Cloud
By Enterprise Size
Large Enterprise
Small and Medium Enterprise
By Application
Automotive and Transportation
Aerospace and Defense
Consumer Electronics
Industrial Machinery
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Solution
5.1.2. Service
5.2. Market Analysis, Insights and Forecast - by Deployment Mode
5.2.1. On-premise
5.2.2. Cloud
5.3. Market Analysis, Insights and Forecast - by Enterprise Size
5.3.1. Large Enterprise
5.3.2. Small and Medium Enterprise
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Automotive and Transportation
5.4.2. Aerospace and Defense
5.4.3. Consumer Electronics
5.4.4. Industrial Machinery
5.4.5. Others
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. South America
5.5.3. Europe
5.5.4. Middle East & Africa
5.5.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Solution
6.1.2. Service
6.2. Market Analysis, Insights and Forecast - by Deployment Mode
6.2.1. On-premise
6.2.2. Cloud
6.3. Market Analysis, Insights and Forecast - by Enterprise Size
6.3.1. Large Enterprise
6.3.2. Small and Medium Enterprise
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Automotive and Transportation
6.4.2. Aerospace and Defense
6.4.3. Consumer Electronics
6.4.4. Industrial Machinery
6.4.5. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Solution
7.1.2. Service
7.2. Market Analysis, Insights and Forecast - by Deployment Mode
7.2.1. On-premise
7.2.2. Cloud
7.3. Market Analysis, Insights and Forecast - by Enterprise Size
7.3.1. Large Enterprise
7.3.2. Small and Medium Enterprise
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Automotive and Transportation
7.4.2. Aerospace and Defense
7.4.3. Consumer Electronics
7.4.4. Industrial Machinery
7.4.5. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Solution
8.1.2. Service
8.2. Market Analysis, Insights and Forecast - by Deployment Mode
8.2.1. On-premise
8.2.2. Cloud
8.3. Market Analysis, Insights and Forecast - by Enterprise Size
8.3.1. Large Enterprise
8.3.2. Small and Medium Enterprise
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Automotive and Transportation
8.4.2. Aerospace and Defense
8.4.3. Consumer Electronics
8.4.4. Industrial Machinery
8.4.5. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Solution
9.1.2. Service
9.2. Market Analysis, Insights and Forecast - by Deployment Mode
9.2.1. On-premise
9.2.2. Cloud
9.3. Market Analysis, Insights and Forecast - by Enterprise Size
9.3.1. Large Enterprise
9.3.2. Small and Medium Enterprise
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Automotive and Transportation
9.4.2. Aerospace and Defense
9.4.3. Consumer Electronics
9.4.4. Industrial Machinery
9.4.5. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Solution
10.1.2. Service
10.2. Market Analysis, Insights and Forecast - by Deployment Mode
10.2.1. On-premise
10.2.2. Cloud
10.3. Market Analysis, Insights and Forecast - by Enterprise Size
10.3.1. Large Enterprise
10.3.2. Small and Medium Enterprise
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Automotive and Transportation
10.4.2. Aerospace and Defense
10.4.3. Consumer Electronics
10.4.4. Industrial Machinery
10.4.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Autodesk Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Rockwell Automation Inc.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. IBM Corporation
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Intel Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. SAP SE
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Oracle Corporation
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. General Electric Co.
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Microsoft Corporation
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Siemens AG
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Schneider Electric SE
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Digital Manufacturing Software Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Digital Manufacturing Software Market Revenue (billion), by Component 2026 & 2034
Figure 3: North America Digital Manufacturing Software Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Digital Manufacturing Software Market Revenue (billion), by Deployment Mode 2026 & 2034
Figure 5: North America Digital Manufacturing Software Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 6: North America Digital Manufacturing Software Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 7: North America Digital Manufacturing Software Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 8: North America Digital Manufacturing Software Market Revenue (billion), by Application 2026 & 2034
Figure 9: North America Digital Manufacturing Software Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Digital Manufacturing Software Market Revenue (billion), by Country 2026 & 2034
Figure 11: North America Digital Manufacturing Software Market Revenue Share (%), by Country 2026 & 2034
Figure 12: South America Digital Manufacturing Software Market Revenue (billion), by Component 2026 & 2034
Figure 13: South America Digital Manufacturing Software Market Revenue Share (%), by Component 2026 & 2034
Figure 14: South America Digital Manufacturing Software Market Revenue (billion), by Deployment Mode 2026 & 2034
Figure 15: South America Digital Manufacturing Software Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 16: South America Digital Manufacturing Software Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 17: South America Digital Manufacturing Software Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 18: South America Digital Manufacturing Software Market Revenue (billion), by Application 2026 & 2034
Figure 19: South America Digital Manufacturing Software Market Revenue Share (%), by Application 2026 & 2034
Figure 20: South America Digital Manufacturing Software Market Revenue (billion), by Country 2026 & 2034
Figure 21: South America Digital Manufacturing Software Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Europe Digital Manufacturing Software Market Revenue (billion), by Component 2026 & 2034
Figure 23: Europe Digital Manufacturing Software Market Revenue Share (%), by Component 2026 & 2034
Figure 24: Europe Digital Manufacturing Software Market Revenue (billion), by Deployment Mode 2026 & 2034
Figure 25: Europe Digital Manufacturing Software Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 26: Europe Digital Manufacturing Software Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 27: Europe Digital Manufacturing Software Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 28: Europe Digital Manufacturing Software Market Revenue (billion), by Application 2026 & 2034
Figure 29: Europe Digital Manufacturing Software Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Europe Digital Manufacturing Software Market Revenue (billion), by Country 2026 & 2034
Figure 31: Europe Digital Manufacturing Software Market Revenue Share (%), by Country 2026 & 2034
Figure 32: Middle East & Africa Digital Manufacturing Software Market Revenue (billion), by Component 2026 & 2034
Figure 33: Middle East & Africa Digital Manufacturing Software Market Revenue Share (%), by Component 2026 & 2034
Figure 34: Middle East & Africa Digital Manufacturing Software Market Revenue (billion), by Deployment Mode 2026 & 2034
Figure 35: Middle East & Africa Digital Manufacturing Software Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 36: Middle East & Africa Digital Manufacturing Software Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 37: Middle East & Africa Digital Manufacturing Software Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 38: Middle East & Africa Digital Manufacturing Software Market Revenue (billion), by Application 2026 & 2034
Figure 39: Middle East & Africa Digital Manufacturing Software Market Revenue Share (%), by Application 2026 & 2034
Figure 40: Middle East & Africa Digital Manufacturing Software Market Revenue (billion), by Country 2026 & 2034
Figure 41: Middle East & Africa Digital Manufacturing Software Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Asia Pacific Digital Manufacturing Software Market Revenue (billion), by Component 2026 & 2034
Figure 43: Asia Pacific Digital Manufacturing Software Market Revenue Share (%), by Component 2026 & 2034
Figure 44: Asia Pacific Digital Manufacturing Software Market Revenue (billion), by Deployment Mode 2026 & 2034
Figure 45: Asia Pacific Digital Manufacturing Software Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 46: Asia Pacific Digital Manufacturing Software Market Revenue (billion), by Enterprise Size 2026 & 2034
Figure 47: Asia Pacific Digital Manufacturing Software Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 48: Asia Pacific Digital Manufacturing Software Market Revenue (billion), by Application 2026 & 2034
Figure 49: Asia Pacific Digital Manufacturing Software Market Revenue Share (%), by Application 2026 & 2034
Figure 50: Asia Pacific Digital Manufacturing Software Market Revenue (billion), by Country 2026 & 2034
Figure 51: Asia Pacific Digital Manufacturing Software Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Digital Manufacturing Software Market Revenue billion Forecast, by Component 2020 & 2034
Table 2: Digital Manufacturing Software Market Revenue billion Forecast, by Deployment Mode 2020 & 2034
Table 3: Digital Manufacturing Software Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 4: Digital Manufacturing Software Market Revenue billion Forecast, by Application 2020 & 2034
Table 5: Digital Manufacturing Software Market Revenue billion Forecast, by Region 2020 & 2034
Table 6: North America Digital Manufacturing Software Market Revenue billion Forecast, by Component 2020 & 2034
Table 7: North America Digital Manufacturing Software Market Revenue billion Forecast, by Deployment Mode 2020 & 2034
Table 8: North America Digital Manufacturing Software Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 9: North America Digital Manufacturing Software Market Revenue billion Forecast, by Application 2020 & 2034
Table 10: North America Digital Manufacturing Software Market Revenue billion Forecast, by Country 2020 & 2034
Table 11: United States Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: Canada Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 14: South America Digital Manufacturing Software Market Revenue billion Forecast, by Component 2020 & 2034
Table 15: South America Digital Manufacturing Software Market Revenue billion Forecast, by Deployment Mode 2020 & 2034
Table 16: South America Digital Manufacturing Software Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 17: South America Digital Manufacturing Software Market Revenue billion Forecast, by Application 2020 & 2034
Table 18: South America Digital Manufacturing Software Market Revenue billion Forecast, by Country 2020 & 2034
Table 19: Brazil Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 20: Argentina Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 21: Rest of South America Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 22: Europe Digital Manufacturing Software Market Revenue billion Forecast, by Component 2020 & 2034
Table 23: Europe Digital Manufacturing Software Market Revenue billion Forecast, by Deployment Mode 2020 & 2034
Table 24: Europe Digital Manufacturing Software Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 25: Europe Digital Manufacturing Software Market Revenue billion Forecast, by Application 2020 & 2034
Table 26: Europe Digital Manufacturing Software Market Revenue billion Forecast, by Country 2020 & 2034
Table 27: United Kingdom Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: Germany Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: France Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: Italy Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Spain Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Russia Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 33: Benelux Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 34: Nordics Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 35: Rest of Europe Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 36: Middle East & Africa Digital Manufacturing Software Market Revenue billion Forecast, by Component 2020 & 2034
Table 37: Middle East & Africa Digital Manufacturing Software Market Revenue billion Forecast, by Deployment Mode 2020 & 2034
Table 38: Middle East & Africa Digital Manufacturing Software Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 39: Middle East & Africa Digital Manufacturing Software Market Revenue billion Forecast, by Application 2020 & 2034
Table 40: Middle East & Africa Digital Manufacturing Software Market Revenue billion Forecast, by Country 2020 & 2034
Table 41: Turkey Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 42: Israel Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 43: GCC Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 44: North Africa Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 45: South Africa Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 46: Rest of Middle East & Africa Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 47: Asia Pacific Digital Manufacturing Software Market Revenue billion Forecast, by Component 2020 & 2034
Table 48: Asia Pacific Digital Manufacturing Software Market Revenue billion Forecast, by Deployment Mode 2020 & 2034
Table 49: Asia Pacific Digital Manufacturing Software Market Revenue billion Forecast, by Enterprise Size 2020 & 2034
Table 50: Asia Pacific Digital Manufacturing Software Market Revenue billion Forecast, by Application 2020 & 2034
Table 51: Asia Pacific Digital Manufacturing Software Market Revenue billion Forecast, by Country 2020 & 2034
Table 52: China Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 53: India Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 54: Japan Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 55: South Korea Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 56: ASEAN Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 57: Oceania Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 58: Rest of Asia Pacific Digital Manufacturing Software Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of data inputs come from primary research, with 20–30% from secondary sources, ensuring real-time validation of the Digital Manufacturing Software Market.
We interview 4–5 specific company types: Cloud MES platform product managers, industrial automation OEM strategy leads, enterprise software systems integrators, edge sensor and gateway suppliers, and discrete manufacturing plant IT directors.
Stakeholder job titles include VP of Manufacturing IT, Plant Operations Director, Industrial IoT Solutions Architect, Procurement Manager for Industrial Software, and Regulatory Compliance Lead.
Industry associations and regulatory bodies referenced: MESA International, International Society of Automation (ISA), National Institute of Standards and Technology (NIST), and Object Management Group (OMG).
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Manufacturing IT
28%
Plant Operations Director
24%
Industrial IoT Solutions Architect
20%
Procurement Manager, Industrial Software
16%
Regulatory Compliance Lead
12%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Cloud MES Platform Vendors
34%
Industrial Automation OEMs
24%
Enterprise Software Integrators
18%
Edge Hardware & Sensor Providers
14%
Manufacturing Analytics Consultancies
10%
Secondary Research & Industry Benchmarking
20–30% of data is sourced from secondary research, including financial filings, trade publications, and regulatory databases.
Top-down and bottom-up methodologies are used simultaneously, validated via multi-level data triangulation.
Bottom-up quantitative metrics include: number of discrete manufacturing plants globally, average annual software spend per plant by enterprise size, cloud MES seat penetration per 1,000 production workers, and average replacement cycle for on-premise MES licenses.
Segment splits for Component, Deployment Mode, Enterprise Size, and Application are triangulated against vendor revenue disclosures and regional manufacturing capex data.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90%.
Every report is updated to the date of purchase.
Cross-validation with at least three independent sources per data point, plus outlier detection and time-series smoothing.
Final numbers are reviewed by senior analysts and compared with historical forecast accuracy within a 5% margin.
Frequently Asked Questions
1. How are disruptive technologies and emerging substitutes reshaping the Digital Manufacturing Software Market?
AI-driven quality inspection and digital twins are replacing standalone statistical process control tools. By 2025, 34% of new MES deployments include embedded AI vision, up from 12% in 2022. Siemens and Rockwell Automation now bundle digital twin simulation into core MES licenses.
2. What are the primary growth drivers and demand catalysts for digital manufacturing software?
Cloud MES adoption, Industry 4.0 mandates, and labor shortages drive demand. The market reached $11.16 billion in 2025 and grows at 17.4% CAGR. Automotive and aerospace plants account for 41% of total software spend.
3. Which region is the fastest-growing for digital manufacturing software, and where are emerging opportunities?
Asia-Pacific is the fastest-growing region at 20.7% CAGR, with China and India adding 1,200+ smart factories annually. Southeast Asia and Mexico offer emerging opportunities as nearshoring expands. North America remains the largest market at $3.57 billion in 2025.
4. How are purchasing behaviors and consumer trends shifting in digital manufacturing software?
Buyers are moving from perpetual licenses to subscription and consumption-based pricing. 62% of new contracts in 2025 are cloud-first, up from 44% in 2022. Procurement teams prioritize interoperability with existing ERP and SCADA systems.
5. What export-import dynamics and international trade flows affect digital manufacturing software?
Software is delivered digitally, but hardware dependencies create trade exposure. US export controls on advanced semiconductors and EU data localization rules affect edge deployments. Cross-border data flow restrictions in Russia and India add compliance costs.
6. Who are the notable recent developments, M&A, or product launches in digital manufacturing software?
Siemens AG announced its $10.6 billion acquisition of Altair Engineering in October 2024 to strengthen simulation. Rockwell Automation launched FactoryTalk Design Studio cloud in November 2024. SAP SE updated its Digital Manufacturing Cloud with AI scheduling in March 2025.